
 Global Lithium Ion Cell and Battery Pack Market | 2026-2036
Global Lithium Ion Cell and Battery Pack Market Size, Share, and Industry Trends Forecast 2026-2036
Global Lithium Ion Cell and Battery Pack Market Outlook
The EU Battery Regulation is broadening compliance obligations for carbon footprint disclosure and recycled content quotas. CATL leverages its integrated mining-to-cell pipeline to preempt traceability mandates. LG Energy Solution anchors its European expansion through Northvolt's supplier network, while BYD sustains cost leadership through in-house cathode production.
Lithium ion cells and battery packs are electrochemical energy storage devices comprising anode and cathode materials separated by electrolyte-soaked polymer membranes, typically operating at nominal voltages between 3.2V and 3.7V depending on cathode chemistry. Their primary purpose is to deliver rechargeable, high-specific-energy power for portable electronics, electric drivetrains, and grid-scale storage installations. Lithium iron phosphate formulations now dominate utility-scale energy storage systems due to superior thermal stability and extended cycle life exceeding 6,000 cycles. Solid-state technology represents the fastest-growing development track, with dual-carbon architectures gaining traction in premium consumer electronics where form factor constraints limit conventional pouch designs.
China's MIIT enforces GB standards for cell safety and energy density benchmarks that determine new energy vehicle subsidy eligibility. The EU's CE marking and ECHA REACH compliance requirements restrict hazardous substance thresholds in imported battery packs. Japan's METI coordinates national solid-state battery consortia targeting commercial manufacturing readiness. Stakeholders must monitor how divergent recycling mandates across these jurisdictions reshape supply chain localization strategies and technology licensing terms.
Market Dynamics
Cell chemistry standardization around lithium iron phosphate formulations is compressing R&D cycles and forcing cathode material suppliers to retool production lines or exit the market entirely.
Growth Catalysts
- Fleet electrification mandates:California's Advanced Clean Trucks regulation and the EU's CO2 standards for heavy-duty vehicles are binding procurement timelines for commercial vehicle operators.
- GB standards compliance:China's MIIT energy density benchmarks determine subsidy eligibility and are accelerating adoption of high-nickel cathode formulations in domestic battery production.
- Grid-scale storage deployment:Utility procurement of four-hour duration battery systems is displacing peaker gas plants in ERCOT and CAISO interconnection queues.
Market Restraints
- Lithium carbonate price volatility:Spot market swings in Chilean and Australian spodumene concentrate contracts are compressing cell manufacturer margins and delaying project financing.
- Cathode precursor concentration:Nickel sulfate refining capacity clusters in Indonesia's Morowali Industrial Park, creating single-point-of-failure exposure for European cell producers.
- Solid-state manufacturing yield gaps:Ceramic electrolyte sintering defects are limiting production economics below commercial viability thresholds.
Strategic Opportunities
- Second-life battery applications:Stationary storage repurposing of degraded automotive packs is opening new revenue streams for vehicle OEMs in Germany and Japan.
- India's PLI scheme:Production-linked incentives for advanced chemistry cell manufacturing are attracting cathode active material investments into Gujarat and Tamil Nadu.
- Direct recycling methods:Hydrometallurgical recovery of lithium and cobalt from black mass is converging with pyrometallurgical routes to reduce energy intensity versus virgin mining.
Industry Challenges
- Electrolyte formulation expertise:Fluorinated additive synthesis requires specialized chemists that battery startups struggle to recruit from established chemical conglomerates.
- UN 38.3 certification timelines:Transportation safety testing for new cell formats adds six to nine months to product launch schedules.
- Gigafactory construction capital intensity:Dry electrode coating equipment and cleanroom infrastructure require committed offtake agreements to secure project financing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Lithium Ion Cell and Battery Pack Market |
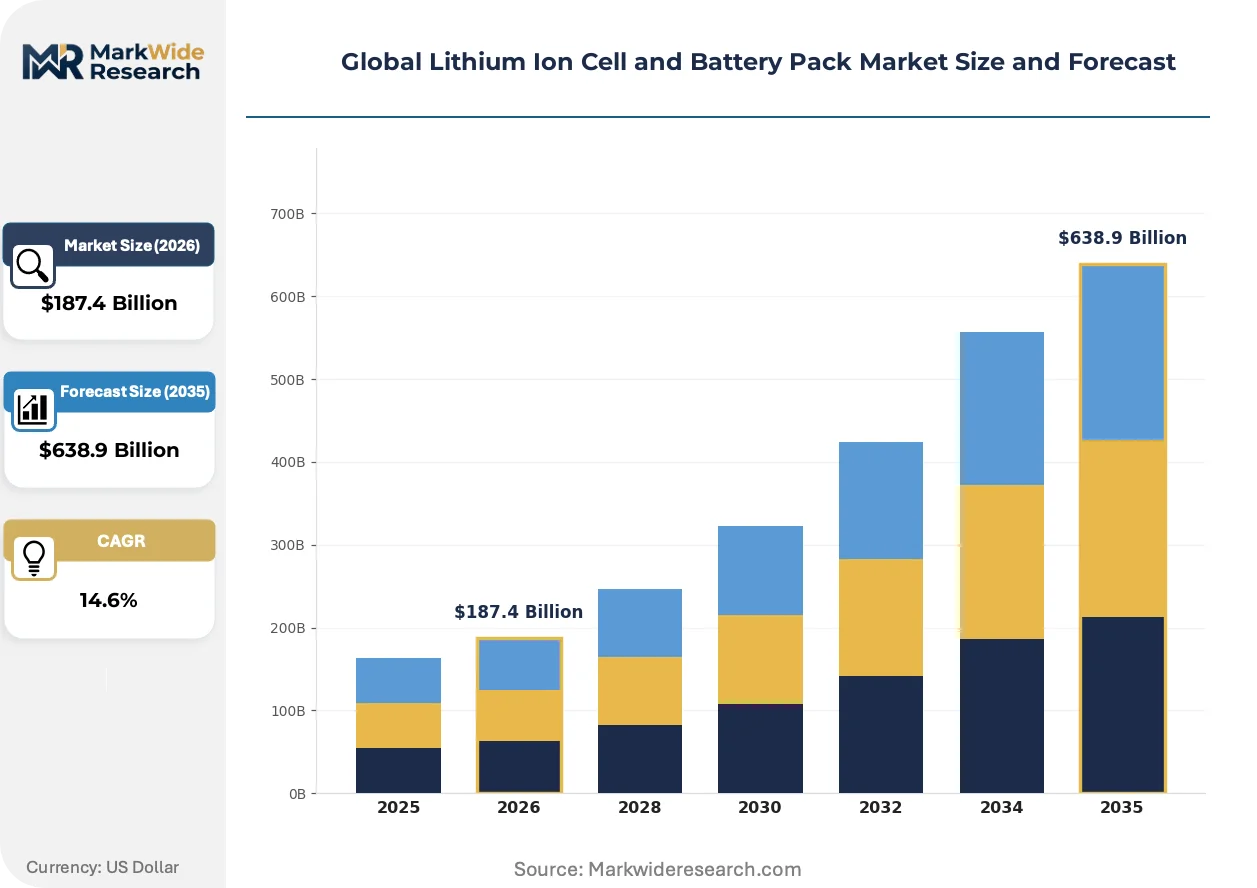
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $638.9 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium Polymer, Lithium Cobalt Oxide, Lithium Iron Phosphate, Lithium Manganese Oxide Application: Consumer Electronics, Electric Vehicles, Energy Storage Systems, Medical Devices End User: OEMs, Retailers, Utilities, Research Institutions Technology: Fast Charging, Dual-Carbon, Solid-State, Energy Density Improvement |
| Companies Covered | CATL, LG Energy Solution, Panasonic Energy, BYD, Samsung SDI, SK On, Northvolt, CALB Group, EVE Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Lithium Ion Cell and Battery Pack Market Strategic Shifts
Electrode architecture innovations and regulatory disclosure requirements are compressing technology cycles and forcing supply chain transparency investments that reshape competitive differentiation.
Solid-state electrolyte technology is consolidating research priorities across the industry. Polymer-ceramic composite separators promise energy density gains above 400 Wh/kg. Automotive OEMs in South Korea and Japan are accelerating validation programs for 2027 platform integration. This convergence is compressing venture funding for liquid electrolyte startups and redirecting talent toward inorganic solid electrolyte development.
The EU Battery Regulation's carbon footprint disclosure rules are mandating supply chain traceability from mining to module assembly. Industrial consequence includes binding recycled content quotas reaching 6% for lithium and nickel by 2031. Premium electric vehicle segments in Germany and the Netherlands face earliest compliance deadlines, prompting cathode producers to secure European black mass processing partnerships.
Long-term service contracts are displacing spot procurement for utility-scale storage. Independent power producers in Texas and California are bundling twenty-year performance guarantees with battery supply agreements. This shift concentrates buyer power among integrated developers and squeezes standalone cell suppliers into subordinate vendor roles. The restructuring is most visible in ERCOT's growing share of build-transfer-operate project structures.
Global Lithium Ion Cell and Battery Pack Market Segmentation
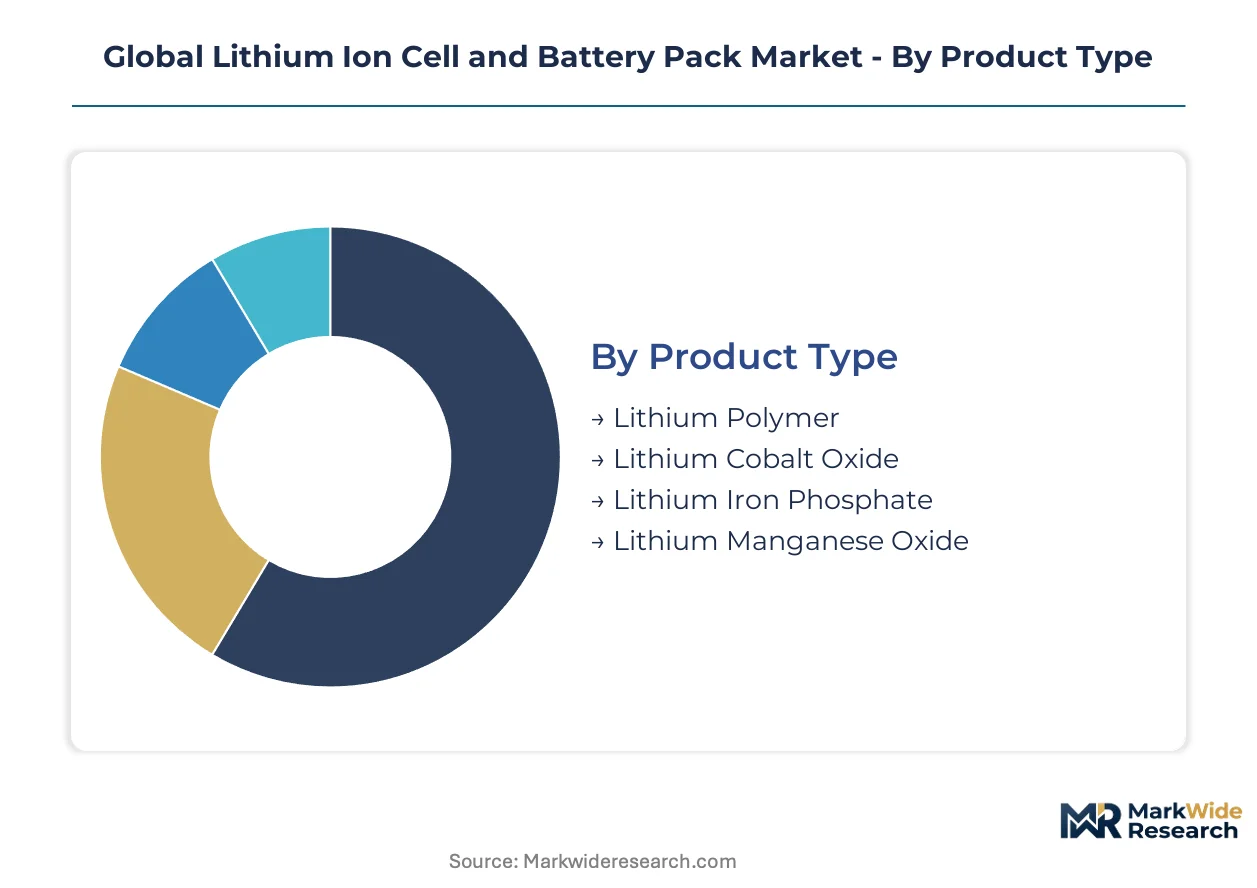
Cell chemistry and application requirements fragment procurement specifications across automotive, grid storage, and consumer electronics verticals. Divergent thermal management needs and cycle life expectations force manufacturers to maintain parallel production lines with limited component interchangeability.
Product Type:
Supply concentration in cathode precursor refining shapes cost structures and availability timelines for each chemistry family.
- Lithium Iron Phosphate:Iron-based cathode formulations deliver superior thermal stability with nominal voltages near 3.2V. Utility-scale battery installations in Texas and California concentrate procurement volumes for four-hour duration systems. China's CATL and BYD dominate cell production through integrated phosphate mining operations.
- Lithium Cobalt Oxide:High-energy-density cells utilizing layered oxide cathodes achieve specific energies above 250 Wh/kg. Premium smartphone and laptop manufacturers in South Korea and Japan specify these formulations despite cobalt supply exposure from the DRC. Samsung SDI and LG Energy Solution anchor production capacity around Nanjing and Ochang facilities.
- Lithium Polymer:Pouch-format cells with gel electrolyte enable flexible form factors for wearable devices. Apple's supply chain specifications drive volume concentration among Foxconn assembly partners.
- Lithium Manganese Oxide:Spinel-structure cathodes offer cost-competitive alternatives for power tools and e-bikes. Milwaukee Tool and Bosch specify these cells for cordless equipment lines.
Lithium iron phosphate absorbs the bulk of installed capacity; lithium cobalt oxide is expanding most quickly in premium consumer applications.
Application:
End-use specifications diverge sharply on cycle life, discharge rate, and safety certification requirements.
- Electric Vehicles:Automotive battery packs integrate thermal management systems and battery management electronics for 1,000+ cycle lifespans. Tesla's Gigafactory Nevada and CATL's Thuringia complex concentrate European and North American supply. NHTSA crash safety protocols and UN 38.3 transportation rules extend certification timelines.
- Energy Storage Systems:Containerized battery installations displace peaker gas plants in ERCOT and CAISO interconnection queues. Fluence and Wartsila bundle twenty-year performance guarantees with hardware supply. FERC Order 841 enables wholesale market participation for battery assets.
- Consumer Electronics:Smartphone and laptop OEMs prioritize energy density over cycle life for sub-500-cycle applications. Foxconn and Pegatron assembly volumes concentrate procurement timing around September product launches.
- Medical Devices:Implantable and portable diagnostic equipment requires IEC 60601 compliance and extended shelf stability. Medtronic and Abbott specify cells with ten-year minimum calendar life for cardiac rhythm management devices.
Electric vehicles command the largest share of cell output; energy storage systems are climbing the fastest as grid decarbonization accelerates.
End User:
Procurement scale and technical sophistication stratify buyer power across the value chain.
- OEMs:Automotive and electronics manufacturers specify cell formats and performance envelopes through multi-year supply agreements. Volkswagen's PowerCo and GM's Ultium Cells pursue captive production to secure volume commitments.
- Utilities:Duke Energy and NextEra Energy issue RFPs for grid-connected storage with guaranteed availability clauses. Procurement teams prioritize bankability of supplier balance sheets over unit cost minimization.
- Retailers:Amazon and Home Depot distribute replacement batteries and power tool packs with private-label sourcing from domestic assemblers.
- Research Institutions:National laboratories and university consortia pilot pre-commercial chemistries at kilowatt-hour scale. ARPA-E funding supports solid-state and dual-carbon architecture validation.
OEMs absorb the bulk of installed capacity; utilities are expanding procurement most quickly through independent power producer partnerships.
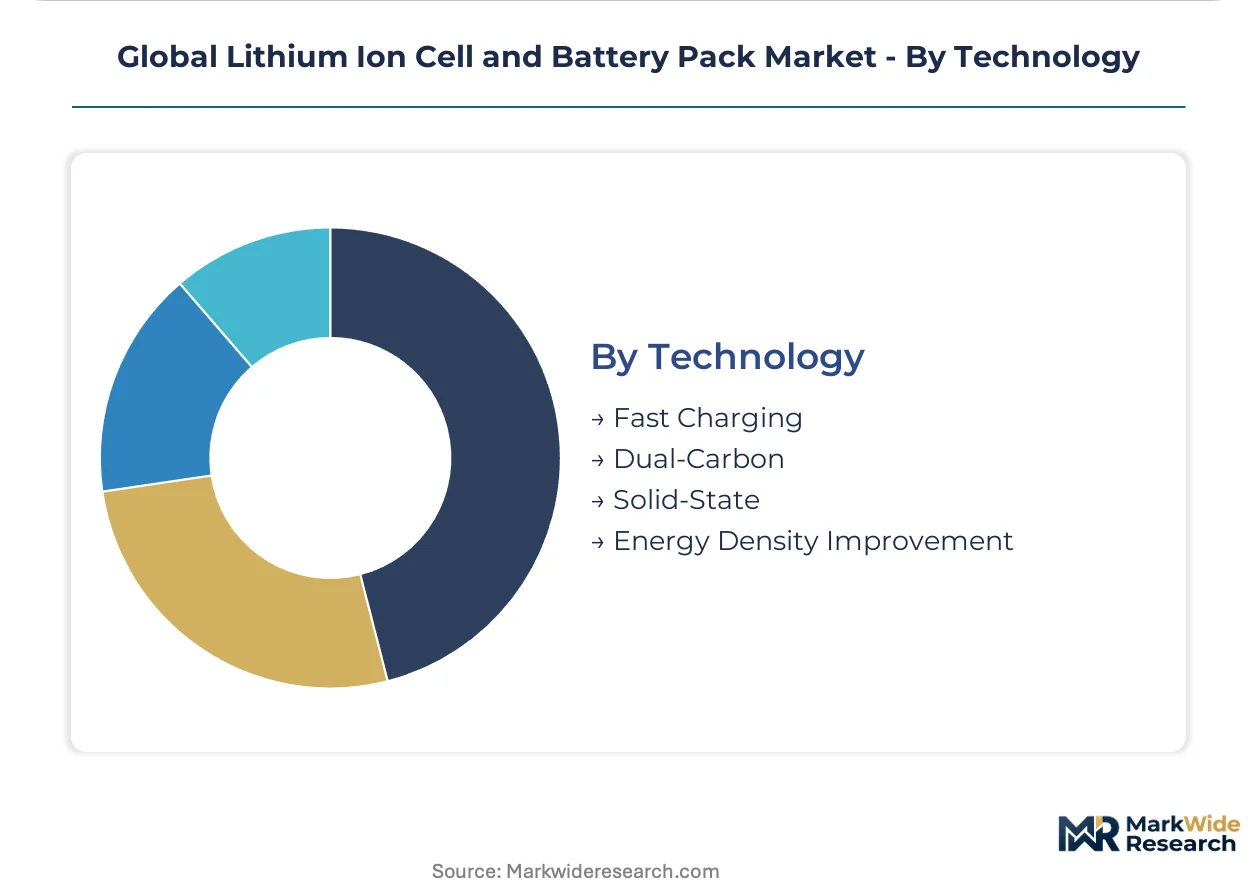
Technology:
R&D investment intensity and manufacturing readiness separate near-term deployable solutions from developmental architectures.
- Solid-State:Ceramic and sulfide electrolyte cells promise energy densities exceeding 400 Wh/kg with inherent thermal stability. Toyota and QuantumScape target automotive platform integration following extended validation cycles. Japan's METI coordinates national consortia for manufacturing readiness.
- Fast Charging:Silicon-anode and advanced electrolyte additive formulations enable 10-80% state-of-charge cycles in under 15 minutes. StoreDot and CATL deploy pilot lines for premium electric vehicle segments.
- Dual-Carbon:Symmetric electrode designs utilizing carbonaceous materials for both anode and cathode simplify recycling streams. KIST and Japanese trading houses pilot production for consumer electronics applications.
- Energy Density Improvement:High-nickel NMC 811 and lithium-rich layered oxide research targets 300 Wh/kg cell-level targets. China's MIIT energy density benchmarks accelerate domestic cathode formulation adoption.
Fast charging absorbs the bulk of near-term R&D deployment; solid-state is gaining share fastest as automotive validation timelines compress.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electric vehicle procurement concentrates in three manufacturing clusters. China's Fujian and Jiangsu provinces, Germany's Saxony-Thuringia corridor, and the US Southwest absorb the majority of cell output as fleet electrification mandates tighten.
China
CATL and BYD drive domestic procurement through integrated mining-to-cell pipelines. MIIT's GB standards enforce energy density benchmarks that determine new energy vehicle subsidy eligibility. Fujian's Ningde operations anchor the world's largest lithium iron phosphate cell manufacturing base.
Germany
Volkswagen's PowerCo and Tesla's Gigafactory Berlin concentrate automotive battery demand. The EU Battery Regulation mandates carbon footprint disclosure and recycled content quotas reaching 6% for lithium by 2031. Thuringia's Grünheide complex hosts cathode precursor processing partnerships with Northvolt's supplier network.
United States
Tesla's Gigafactory Nevada and GM's Ultium Cells anchor North American cell manufacturing. The Inflation Reduction Act's domestic content requirements reshape procurement toward North American mineral sourcing. Texas's ERCOT interconnection queues displace peaker gas plants with four-hour duration battery systems from Fluence and Wartsila.
South Korea
LG Energy Solution and Samsung SDI supply premium consumer electronics and automotive segments. The country's national solid-state battery consortia coordinate manufacturing readiness targets. Ochang's cathode material facilities supply Nanjing and European assembly operations.
India
Reliance Industries and Ola Electric accelerate domestic cell procurement under the PLI scheme for advanced chemistry manufacturing. The Ministry of Heavy Industries' production-linked incentives attract cathode active material investments into Gujarat and Tamil Nadu. Tamil Nadu's Sriperumbudur cluster hosts emerging lithium-ion assembly partnerships with Korean technology licensors.
Global Lithium Ion Cell and Battery Pack Market Competitive Environment
East Asian producers anchor the volume tier; European specialists hold emerging positions in sustainable chemistry. The market structure concentrates around six integrated cell manufacturers with captive cathode supply. Three strategic archetypes dominate: mining-to-cell integrators, automotive-captive producers, and technology licensors. Capacity expansion and strategic partnerships represent the dominant competitive moves as firms secure mineral offtake and regional assembly presence.
Within the integrated tier, CATL and BYD represent mining-to-cell archetypes with upstream phosphate and lithium control. LG Energy Solution occupies a position bridging Korean technology licensing with European expansion through supplier network anchoring. These three exemplify how geographic origin and corporate structure shape competitive positioning without requiring speculative claims about proprietary technologies or customer relationships.
| Leading Market Players |
|---|
| CATL |
| LG Energy Solution |
| Panasonic Energy |
| BYD |
| Samsung SDI |
| SK On |
| Northvolt |
| CALB Group |
| EVE Energy |
| Others |
Value Chain & Pricing Dynamics
Sovereign-backed producers in China's Fujian and Jiangsu provinces anchor upstream lithium and phosphate refining, compressing procurement timelines for downstream cell manufacturers while enforcing pricing discipline through captive mineral control. This ownership pattern binds pricing power to state-coordinated capacity expansion, forcing independent European and North American assemblers to absorb premium feedstock costs or pursue long-term offtake commitments with Indonesian nickel sulfate refiners.
Pricing Analysis
Short lead-time premiums dominate contract negotiations, with automotive OEMs paying 15-20% markups for six-month delivery windows versus standard twelve-month schedules. Three-tier pricing structure across premium, standard, and economy levels separates CATL's high-nickel NMC cells from BYD's iron phosphate offerings and second-tier Chinese producers' commodity pouch formats. Cost compression in standard-tier cylindrical cells is intensifying because Indonesian nickel refining bottlenecks are extending cathode precursor lead times. Fleet operators and utility procurement teams exhibit highest price sensitivity, while medical device OEMs prioritize IEC 60601 certification tiers over unit economics.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Long Beach, and Singapore buffer inventory for just-in-time cathode precursor delivery to European and North American gigafactories. Lithium carbonate draws from Chilean Atacama brine operations and Australian spodumene concentrators, while nickel sulfate feeds from Indonesia's Morowali Industrial Park and cobalt hydroxide from the DRC's Copperbelt. Single-source vulnerability concentrates in Indonesian nickel refining, where Chinese ownership of processing assets creates geopolitical exposure for Korean and Japanese cell producers. Distribution runs through hub-and-spoke patterns anchored by CATL's Ningde complex and LG Energy Solution's Nanjing operations, with secondary spokes radiating to Tesla's Nevada and Berlin assembly points.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Battery Regulation's carbon footprint disclosure mandates and recycled content quotas erect compliance moats that favor incumbents with integrated mining-to-cell traceability systems, raising capital barriers for speculative entrants lacking black mass processing partnerships.
For Market Incumbents: Extend backward integration into Indonesian nickel sulfate refining or Australian spodumene concentrators to preempt cathode precursor bottlenecks. Secure European black mass processing partnerships before recycled content quotas tighten. Capacity addition in Thuringia and Nevada insulates against tariff exposure from Chinese-origin cell imports.
For New Entrants and Emerging Players: Utility procurement officers represent the most penetrable channel partner type, as independent power producers in ERCOT and CAISO seek alternative suppliers to Fluence-Wartsila duopoly. Second-life battery repurposing for stationary storage offers white-space entry with lower certification burdens than automotive qualification. Direct recycling technology licensing from Korean research institutes accelerates go-to-market without gigafactory capital intensity.
For Investors and Strategic Acquirers: Distressed-cycle entries favor solid-state electrolyte specialists with Toyota or QuantumScape validation partnerships in Japan and South Korea. Long-term viability over the next decade hinges on ceramic separator manufacturing yield convergence above commercial thresholds. The signal to watch is automotive OEM platform integration announcements for 2027-2028 model year commitments.
| Strategic Initiative | Industry Significance |
|---|---|
| Cathode Precursor Backward Integration | Indonesian nickel sulfate refining partnerships with Tsingshan secure feedstock against Morowali concentration risk. |
| Solid-State Battery Validation | Toyota's platform integration programs compress venture funding timelines for liquid electrolyte competitors. |
| European Black Mass Processing | Northvolt supplier network partnerships preempt EU Battery Regulation recycled content quota enforcement. |
| Utility-Scale Storage Performance Guarantees | Twenty-year availability clauses with Duke Energy and NextEra concentrate buyer power among integrated developers. |
| Fast-Charging Silicon Anode Deployment | StoreDot pilot lines for premium electric vehicle segments differentiate against CATL's commodity iron phosphate dominance. |
Study Parameters
Trade databases, customs filings, and SEC 10-K disclosures formed the secondary backbone, supplemented by MIIT GB standard documentation and EU Battery Regulation implementation guidance. Primary interviews with cathode material procurement directors, gigafactory operations managers, utility storage planners, and automotive platform engineers validated supply chain concentration assumptions. Bottom-up cell production capacity tallies across Fujian, Jiangsu, Thuringia, and Nevada facilities were cross-referenced against top-down electric vehicle production forecasts from vehicle registration databases.
Bottom-up modeling of cathode active material demand by chemistry family was reconciled with top-down electric vehicle and grid storage deployment trajectories across the projection horizon. Segmentation dimensions included cell chemistry, application vertical, end-user procurement scale, and technology readiness tier. CAGRs were derived from installed capacity build-out schedules and fleet electrification mandate compliance timelines. Forecast inputs incorporated lithium carbonate spot price volatility bands and solid-state manufacturing yield improvement curves.
Several conditions sit outside the modeled scope, including unannounced geopolitical trade restrictions, breakthrough solid-state electrolyte formulations, and abrupt subsidy regime suspensions in China or India. Forecasts reflect documented assumptions about mineral offtake contract renewals and cathode precursor refining capacity expansion. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Germany SLI Battery Market
Lithium-ion Battery
India Electric Vehicle Battery Anode Market
Lithium-ion Battery
Lithium-Ion UPS System Market
Lithium-ion Battery
Global Next Generation Batteries Market
Lithium-ion Battery
Lithium Ion Capacitor Market
Lithium-ion Battery
Solid State Battery Market
Lithium-ion Battery
Asia-Pacific Lithium-Ion Battery Market
Lithium-ion Battery
Lithium-Ion Battery Cathode Material Market
Lithium-ion Battery
Global Lithium Mining Market
Lithium-ion Battery
United Kingdom Lithium-Ion Battery for Electric Vehicle Market
Lithium-ion Battery
Nanobolt Lithium Tungsten Batteries Market
Lithium-ion Battery
UAV Lithium Battery Market
Lithium-ion Battery
Solid Electrolyte for Lithium Ion Battery Market
Lithium-ion Battery
Europe NMC Battery Pack Market
Lithium-ion Battery
Ultra Low Temperature Lithium Battery Market
Lithium-ion Battery
Lithium Iodide Market