
 Lithium and Lithium Ion Battery Electrolytes Market | 2026-2036
Lithium and Lithium Ion Battery Electrolytes Market Size, Share, and Industry Trends Forecast 2026-2036
Lithium and Lithium Ion Battery Electrolytes Market Outlook
Solid-state electrolyte research is reshaping how battery manufacturers design thermal management architectures for next-generation cells. Shenzhen Capchem Technology leverages its integrated fluorinated additive production to anchor supply contracts with domestic cell makers. Mitsubishi Chemical Corporation sustains its position through proprietary lithium bis(fluorosulfonyl)imide salt purification that meets aerospace-grade specifications. BASF SE differentiates by operating dual-stream capacity for both conventional carbonate liquids and pilot sulfide-ceramic solid electrolyte lines.
Lithium and lithium ion battery electrolytes comprise lithium salts dissolved in organic carbonate solvents, typically lithium hexafluorophosphate in ethylene carbonate and dimethyl carbonate blends, with functional additives forming stable solid-electrolyte interphase layers on graphite anodes. These formulations enable lithium-ion shuttling between electrodes at operating voltages of 3.0–4.5 V, serving as the ionic transport medium that determines cycle life, rate capability, and safety thresholds in rechargeable cells. Liquid electrolytes still occupy the dominant revenue position due to mature manufacturing infrastructure and compatibility with existing winding and stacking equipment. Solid electrolytes are attracting capital allocation fastest as automotive OEMs demand simplified pack architectures without separate thermal runaway barriers. Gel and polymer electrolytes specialize in thin-form wearable device applications where mechanical flexibility outweighs energy density priorities.
The US EPA and FAA are tightening testing protocols for electrolyte flammability in aviation-bound battery shipments, while China's SAMR enforces GB/T 36276 compliance for grid-storage cell components. REACH registration requirements in Europe constrain solvent import pathways for non-EU blenders. Stakeholders must monitor how solid-state pilot lines alter salt precursor demand and whether regional carbon border adjustments reshape solvent sourcing economics.
Market Dynamics
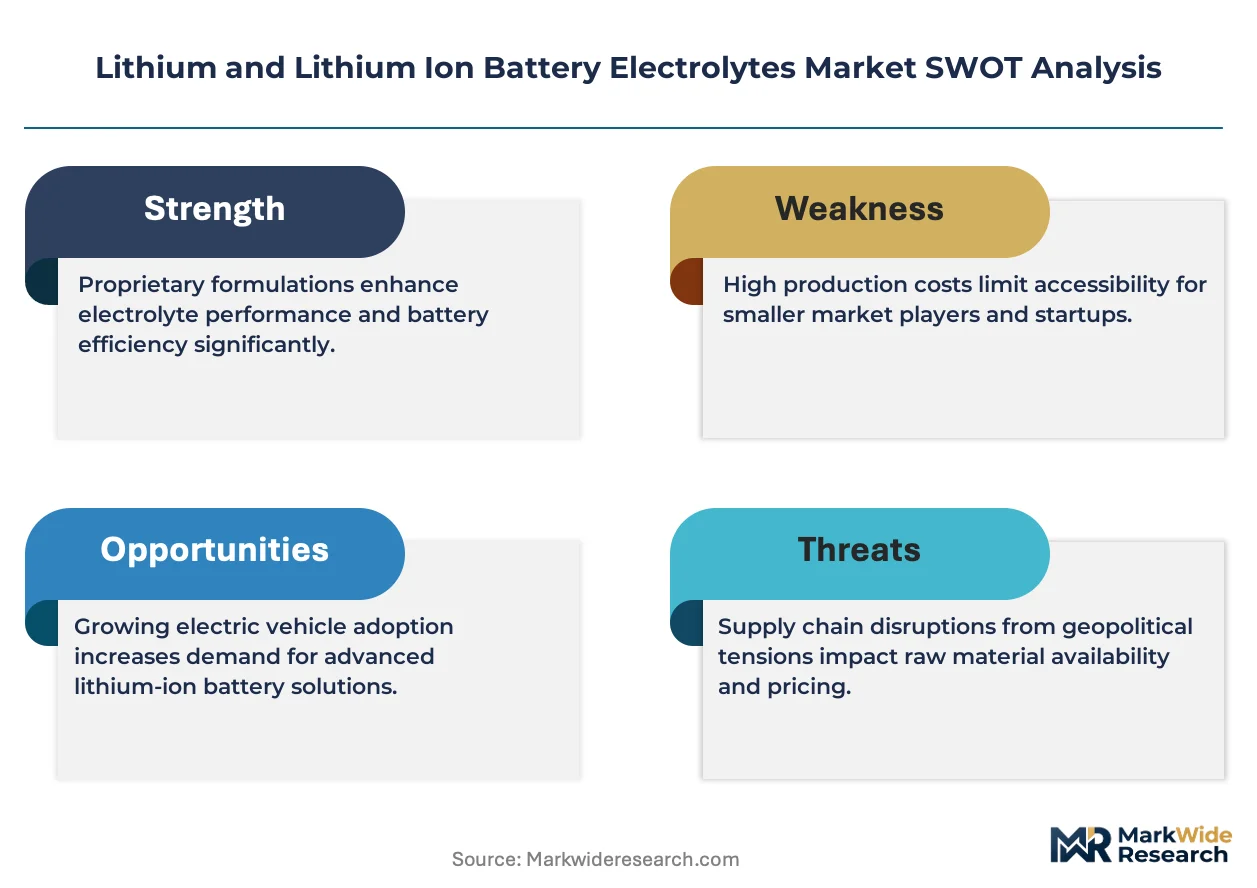
Automotive OEMs are consolidating electrolyte procurement around high-voltage formulations compatible with nickel-rich cathodes, compressing supplier qualification timelines from thirty-six months to eighteen months. This demand compression is forcing blenders to reconfigure solvent purification lines and salt precursor sourcing before solid-state architectures reach pilot scale.
Growth Catalysts
- Electric vehicle platform voltage escalation:800 V architectures require electrolyte additives that suppress oxidation at potentials above 4.3 V. Cell makers in South Korea's Ulsan corridor are locking multi-year supply agreements for fluorinated co-solvents.
- China's SAMR battery safety mandates:GB/T 36276 compliance for grid-storage cells mandates thermal runaway propagation testing that only high-purity lithium salt formulations can reliably pass. Domestic blenders are retrofitting distillation towers to meet these thresholds.
- Aviation battery certification pathways:The FAA's tightened flammability testing for lithium-ion shipments aboard cargo aircraft is creating qualified supplier lists that favor electrolyte producers with in-house flame-retardant additive synthesis.
Market Restraints
- Lithium hexafluorophosphate supply concentration:Over seventy percent of purified salt capacity sits in China's Jiangsu and Shandong provinces, exposing non-Chinese cell makers to export license volatility and freight cost spikes.
- Fluorinated solvent cost structure:Hexafluoropropylene carbonate and fluorinated ether precursors trade at three to five times conventional carbonate prices, compressing margins for high-voltage formulations.
- Solid-state substitution timeline:Sulfide-ceramic and oxide-garnet electrolytes in pilot production at automotive OEMs threaten to displace liquid electrolyte volumes in premium vehicle segments by the early 2030s.
Strategic Opportunities
- India's PLI scheme for advanced chemistry cells:The twenty-five billion rupee production-linked incentive program is attracting electrolyte blenders to Gujarat and Tamil Nadu industrial corridors before local cell capacity ramps.
- Marine and aviation energy storage:Offshore vessel electrification and electric vertical take-off aircraft are creating demand for electrolyte formulations with enhanced low-temperature conductivity and reduced vapor pressure.
- Recycling-integrated salt recovery:Pyrometallurgical and direct recycling flowsheets are enabling lithium salt reclamation from production scrap and end-of-life cells, reducing virgin precursor dependence.
Industry Challenges
- Electrolyte-formulation chemist scarcity:The intersection of electrochemistry, organic synthesis, and battery safety engineering commands salaries that mid-cap blenders struggle to match against pharmaceutical and semiconductor competitors.
- Dual-certification timeline compression:Simultaneous qualification for automotive OEMs and energy-storage integrators requires parallel testing protocols that strain analytical laboratory capacity and extend cash conversion cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lithium and Lithium Ion Battery Electrolytes Market |
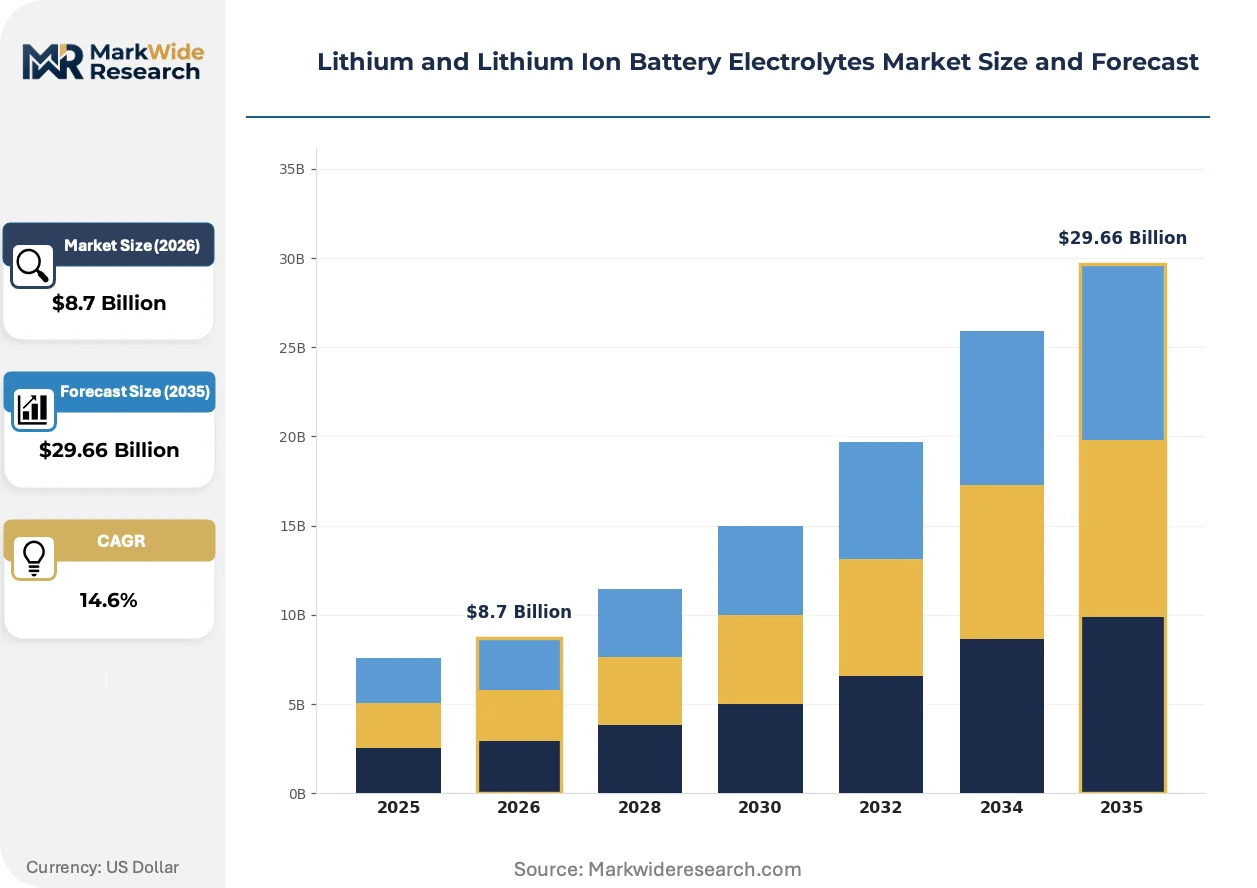
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $29.66 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Electrolytes, Solid Electrolytes, Gel Electrolytes, Polymer Electrolytes End User: Consumer Electronics, Electric Vehicles, Renewable Energy Storage, Industrial Applications Distribution Channel: Direct Sales, Online Retail, Distributors, OEMs Application: Power Tools, Wearable Devices, Grid Storage, Medical Devices |
| Companies Covered | Shenzhen Capchem Technology Co., Ltd., Guangzhou Tinci Materials Technology Co., Mitsubishi Chemical Corporation, Soulbrain MI, BASF SE, UBE Corporation, Shanshan Technology, Dongwha Electrolyte, Panax Etec Co Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lithium and Lithium Ion Battery Electrolytes Market Strategic Shifts
Electrolyte chemistry is bifurcating between incremental liquid-formulation refinement and disruptive solid-state architectures, with capital allocation increasingly favoring technologies that simplify pack-level thermal management. This divergence is reshaping supplier R&D portfolios and equipment procurement strategies.
Sulfide-based solid electrolytes, particularly lithium thiophosphate glasses and argyrodite compounds, are rendering obsolete the separate thermal barrier layers and venting systems required in conventional liquid-electrolyte packs. Automotive OEMs in Germany and Japan are accelerating pilot line investments for sulfide-ceramic cells targeting 2027 platform launches. The structural consequence is a compression in demand for flame-retardant liquid additives and compression pads, redirecting supplier technical service resources toward solid-electrolyte interface engineering.
REACH registration requirements for cyclic carbonate solvents and lithium salt precursors are constraining import pathways for non-European blenders seeking to supply European cell manufacturing. ECHA's 2024 update to substance evaluation criteria now requires chronic aquatic toxicity data for novel fluorinated additives, extending registration timelines by twelve to eighteen months. European energy-storage integrators are responding by consolidating supplier lists around registrants with complete dossiers, excluding smaller Asian blenders from grid-storage tenders.
Cell makers are unbundling electrolyte formulation from cathode procurement, reversing the bundled cathode-electrolyte supply contracts that dominated the 2015-2022 period. Tier-one automotive OEMs in the United States and South Korea are now issuing separate RFQs for electrolyte blends, enabling direct qualification of additive specialists and solvent purifiers. This disintermediation is most visible in the North American battery corridor spanning Michigan, Ohio, and Tennessee, where new cell plants are signing direct supply agreements with Mitsubishi Chemical and Ube Industries rather than relying on cathode producer intermediaries.
Lithium and Lithium Ion Battery Electrolytes Market Segmentation
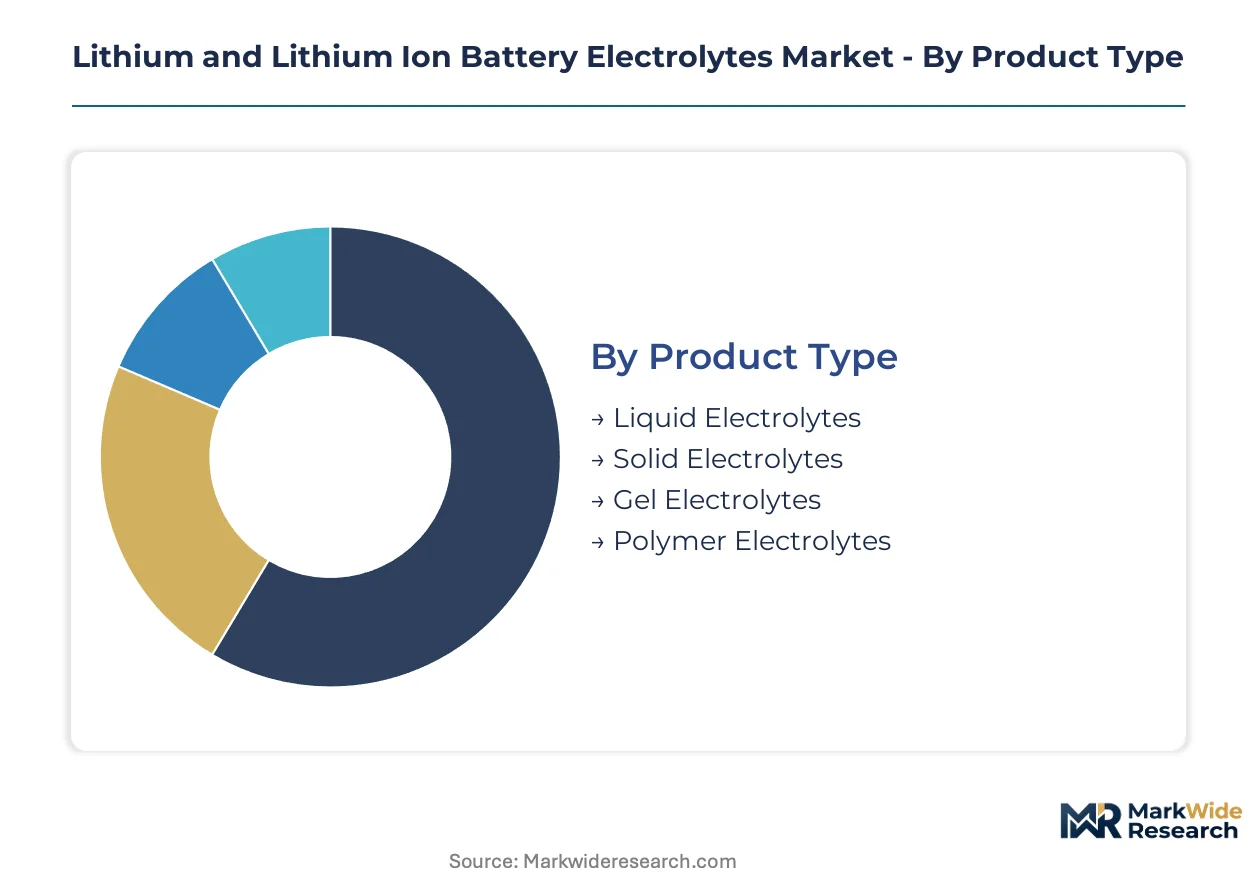
Electrolyte procurement cycles vary dramatically across cell chemistry types, with liquid formulations commanding annual contract renegotiations while solid-state development partnerships span multi-year horizons. Understanding these temporal patterns reveals where supplier capacity investments face the tightest return windows.
Product Type:
Liquid electrolytes turn inventory fastest with quarterly adjustment cycles to cathode chemistry shifts, whereas solid electrolyte supply agreements lock in five-to-seven-year development timelines.
- Liquid Electrolytes:These lithium hexafluorophosphate solutions in carbonate solvent blends remain the workhorse for cylindrical and prismatic cell production. Demand concentrates in South Korea's Ulsan industrial complex where cell makers are qualifying high-voltage formulations for nickel-rich cathodes ahead of platform voltage escalation.
- Solid Electrolytes:Sulfide-ceramic and oxide-garnet compositions eliminate thermal runaway barriers but require dry-room manufacturing infrastructure. Automotive OEMs in Germany and Japan are anchoring pilot line investments here as pack architecture simplification becomes the priority design criterion.
- Gel Electrolytes:Polymer matrices swollen with liquid electrolyte occupy niche medical and wearable applications where mechanical compliance matters more than energy density.
- Polymer Electrolytes:Dry polymer electrolyte films serve thin-form factor devices with limited rate capability requirements.
Liquid electrolytes anchor the volume base while solid electrolytes gain share at the steepest rate.
End User:
Cost tier stratification separates premium automotive specifications from commoditized consumer electronics grades, with certification burden driving margin dispersion.
- Electric Vehicles:Cell makers demand electrolyte lots qualified to automotive OEM test matrices spanning thermal abuse, overcharge, and vibration protocols. China's SAMR GB/T 36276 compliance is becoming a non-negotiable entry ticket for grid-storage adjacent vehicle-to-grid applications.
- Consumer Electronics:High-volume cylindrical cell production for power banks and laptops tolerates wider specification bands in exchange for price elasticity. Procurement concentrates in Guangdong province contract manufacturers serving global electronics brands.
- Renewable Energy Storage:Grid-scale integrators prioritize calendar life and impedance stability over rate capability, favoring electrolyte formulations with optimized solid-electrolyte interphase formation.
- Industrial Applications:Forklift and stationary backup power systems operate in temperature extremes that demand electrolyte additives for low-temperature conductivity preservation.
Consumer electronics anchors the volume base while electric vehicles command the steepest expansion trajectory in absolute dollar terms.
Distribution Channel:
Customer type determines contract structure complexity, with OEM direct relationships demanding the deepest technical service embedding.
- OEMs:Tier-one automotive and energy-storage integrators issue multi-year sole-source contracts with attached formulation development obligations. Mitsubishi Chemical and Ube Industries have established direct supply positions with North American cell plants in Michigan and Tennessee.
- Distributors:Regional chemical distributors serve mid-cap cell makers and specialty battery assemblers with stocked solvent blends and salt precursors.
- Direct Sales:Large-volume cell producers bypass intermediaries for lithium salt procurement, negotiating directly with Jiangsu and Shandong province refiners.
- Online Retail:Laboratory-scale electrolyte formulations and additive samples move through specialized chemical supply platforms serving R&D organizations.
OEM direct sales anchors the revenue base while distributor relationships are expanding most quickly in India's Gujarat and Tamil Nadu corridors ahead of PLI scheme cell capacity ramp.
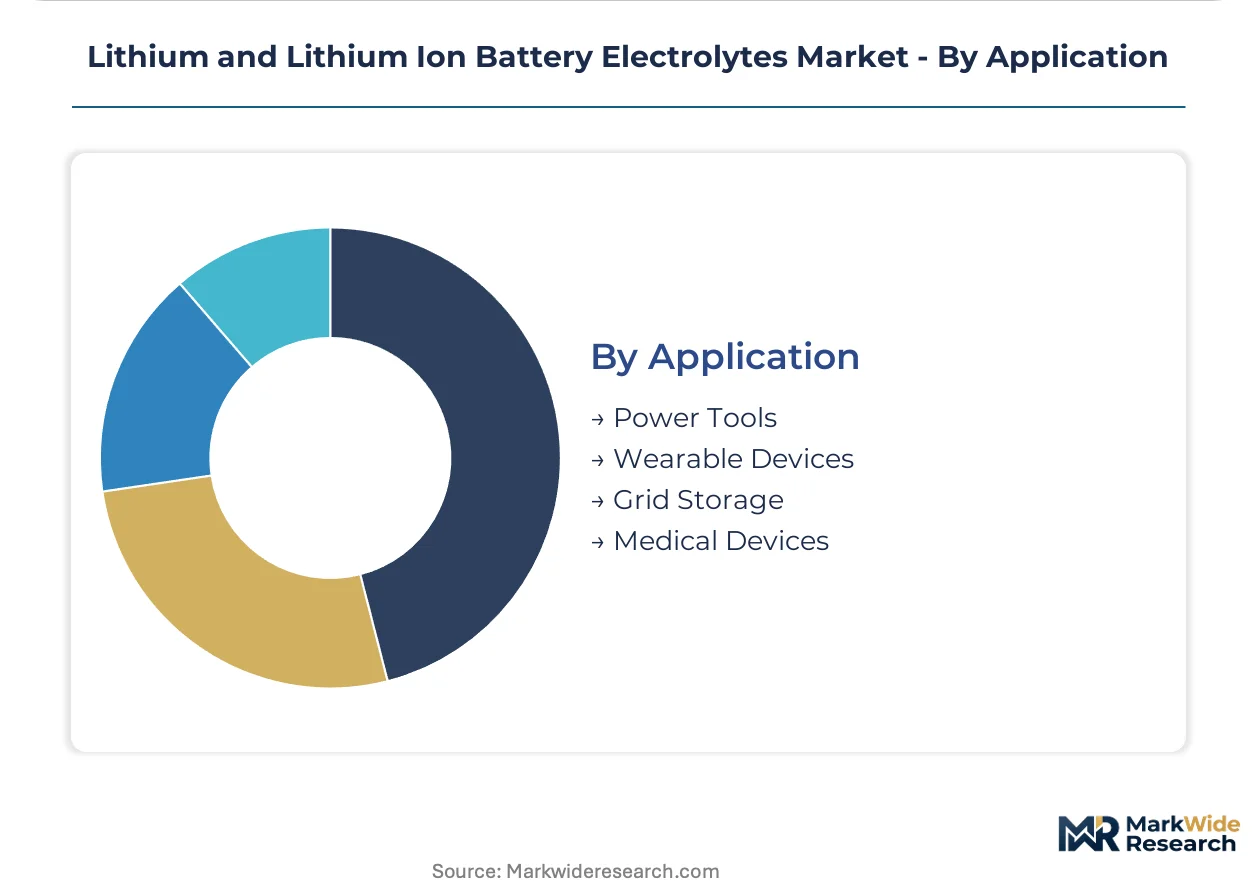
Application:
Maturity differentiation separates established power tool segments from nascent medical device certifications with multi-year approval timelines.
- Grid Storage:Utility-scale battery installations require electrolyte formulations validated to twenty-year calendar life projections with minimal impedance growth. China's State Grid procurement specifications are tightening purity thresholds for lithium salts and solvent blends.
- Power Tools:High-rate cylindrical cells for professional construction equipment demand electrolyte additives that suppress gas generation during fast-charge cycling.
- Wearable Devices:Ultra-thin pouch cells prioritize mechanical flexibility and vapor pressure reduction over energy density metrics.
- Medical Devices:Implantable and portable diagnostic equipment requires electrolyte lots qualified to ISO 13485 traceability standards with extended biocompatibility documentation.
Power tools anchors the established volume base while grid storage applications are climbing the fastest as renewable penetration targets drive procurement acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Jiangsu and Shandong provinces export purified lithium hexafluorophosphate salts to cell makers in South Korea's Ulsan corridor and Japan's Kansai chemical cluster, forming the dominant trade-flow backbone of the electrolyte supply network.
China
Domestic cell makers are scaling orders for high-voltage formulations as nickel-rich cathode chemistry shifts accelerate. SAMR's evolving GB standards on battery safety tighten purity thresholds for lithium salts and solvent blends, forcing retrofit investments in distillation infrastructure. Production concentrates in Jiangsu and Shandong provinces where over seventy percent of global purified salt capacity operates.
South Korea
Automotive OEMs are consolidating electrolyte procurement around 800 V-compatible formulations, compressing supplier qualification timelines. The MFDS maintains chemical substance registration requirements for electrolyte components used in medical device batteries. The Ulsan industrial complex anchors cell production where multi-year supply agreements for fluorinated co-solvents are being locked.
Japan
Automotive OEMs are accelerating pilot line investments for sulfide-ceramic solid electrolytes targeting 2027 platform launches. METI supports domestic supply chain resilience initiatives for critical battery materials. The Kansai chemical cluster sustains advanced lithium salt purification operations meeting aerospace-grade specifications.
United States
Tier-one automotive OEMs are issuing separate RFQs for electrolyte blends, disintermediating cathode producer intermediaries. The EPA and FAA tighten testing protocols for electrolyte flammability in aviation-bound battery shipments. The North American battery corridor spanning Michigan, Ohio, and Tennessee is signing direct supply agreements with established Asian blenders.
Germany
Automotive OEMs are prioritizing pack architecture simplification through solid-state electrolyte adoption. ECHA's REACH registration requirements constrain import pathways for non-European blenders, with 2024 updates extending registration timelines for novel fluorinated additives. Production investments concentrate in the industrial regions supplying cell manufacturing for premium vehicle segments.
Lithium and Lithium Ion Battery Electrolytes Market Competitive Environment
Channel-controlling players compete with product-specialist players across a market structure where salt precursor purification and additive synthesis capabilities determine tier placement. The vendor base clusters around three strategic archetypes: integrated chemical conglomerates with captive salt production, specialized electrolyte blenders with formulation IP, and regional solvent purifiers serving mid-cap cell makers. Dominant competitive moves include backward integration into lithium salt refining and geographic expansion through direct supply agreements with new cell plants in North America and India.
Among Asian chemical conglomerates, Shenzhen Capchem Technology Co., Ltd. and Mitsubishi Chemical Corporation exemplify the integrated archetype combining salt production with formulation development. Guangzhou Tinci Materials Technology Co. occupies a specialist position within China's domestic supply base. These three entities anchor the competitive structure by representing distinct geographic and capability configurations: Shenzhen-based integrated production, Japanese aerospace-grade purification, and Guangzhou-centered domestic formulation supply.
| Leading Market Players |
|---|
| Shenzhen Capchem Technology Co., Ltd. |
| Guangzhou Tinci Materials Technology Co. |
| Mitsubishi Chemical Corporation |
| Soulbrain MI |
| BASF SE |
| UBE Corporation |
| Shanshan Technology |
| Dongwha Electrolyte |
| Panax Etec Co Ltd |
| Others |
Value Chain & Pricing Dynamics
Jiangsu province's concentrated lithium hexafluorophosphate refining capacity shapes pricing power for downstream blenders across East Asia, with export license volatility in China's Shandong corridor feeding directly into contract indexation clauses for South Korean and Japanese cell makers.
Pricing Analysis
Cost-plus contracts indexed to lithium carbonate and fluorinated precursor spot markets dominate electrolyte procurement, with automotive OEMs locking eighteen-month price bands against raw material volatility. Price differentiation separates aerospace-grade salt purification from standard battery-grade formulations, while volume scale determines co-solvent discounts. Cost compression in high-voltage additive tiers is intensifying because fluorinated ether precursors trade at multiples of conventional carbonates. Consumer electronics cell makers exhibit highest price sensitivity, whereas aviation-qualified suppliers command premium stability.
Supply Chain Analysis
Export control regimes on fluorinated chemical precursors and advanced lithium salt purification technology constrain flows from China's Jiangsu and Shandong provinces to non-domestic blenders. The supply chain draws from lithium carbonate feedstock in South American salares, hexafluorophosphate refining in East Asia, and fluorinated co-solvent synthesis in specialized chemical clusters. Single-source vulnerability concentrates in purified salt capacity, with over seventy percent operating in two Chinese provinces. Distribution runs through direct supply agreements with tier-one automotive OEMs and regional distributors serving mid-cap cell makers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Solid-state electrolyte substitution threatens liquid formulation incumbents, requiring defensive positioning before sulfide-ceramic pilot lines reach commercial scale.
For Market Incumbents: Pre-empt solid-state displacement by anchoring long-term supply agreements with 800 V automotive platforms before qualification windows narrow further. Backward integration into fluorinated additive synthesis defends margin position against precursor cost spikes, while dual-stream capacity for liquid and pilot solid-electrolyte lines preserves optionality.
For New Entrants and Emerging Players: India's Gujarat and Tamil Nadu industrial corridors offer underpenetrated entry points ahead of PLI scheme cell capacity ramp, with electrolyte blending equipment transferable from established chemical processing industries. Marine and aviation energy storage segments tolerate longer qualification timelines, enabling formulation specialization without immediate automotive certification burden.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors additive synthesis specialists with captive fluorinated chemistry capabilities over commodity salt refiners. Long-term viability hinges on interface engineering competence for solid-electrolyte architectures. Monitor automotive OEM solid-state pilot line announcements as inflection indicator for liquid electrolyte demand trajectory.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluorinated Additives | Captive supply of hexafluoropropylene carbonate precursors insulates margin from volatile spot pricing. |
| Dual-Stream Capacity Investment | Parallel liquid and sulfide-ceramic solid electrolyte lines preserve customer optionality across technology cycles. |
| Long-Term Supply Agreement | Eighteen-month automotive OEM contracts with price indexation reduce exposure to lithium salt volatility. |
| Geographic Expansion to India | Gujarat and Tamil Nadu positioning ahead of PLI scheme cell capacity ramp secures first-mover supply relationships. |
| Aviation Certification Investment | FAA-qualified flame-retardant additive synthesis opens qualified supplier lists for cargo aircraft battery shipments. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across electrolyte blenders, lithium salt refiners, automotive OEM procurement teams, and cell maker R&D directors. Secondary validation drew from SAMR GB standard filings, ECHA REACH registration databases, customs trade flows for carbonate solvents, and SEC disclosures from listed chemical conglomerates. Bottom-up cell production forecasts were triangulated against top-down electrolyte consumption intensity metrics.
Calibration against historical capacity utilization rates and cathode chemistry transition timelines anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include electrolyte formulation type, end-use application, and regional production cluster. CAGRs were derived from volume-demand elasticity curves and pricing trajectory assumptions, with fluorinated additive penetration rates and solid-state substitution timelines serving as key forecast inputs.
Practitioners should monitor solid-state pilot line commercialization announcements and export license volatility in China's salt refining corridors for early signals. Forecasts reflect assumptions on cathode voltage escalation timelines and regulatory purity threshold evolution. Material shifts in automotive OEM platform architecture or REACH registration timeline extensions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Taiwan Lithium-Ion Battery Market
Lithium-ion Battery
North America Lithium-Ion Battery Market
Lithium-ion Battery
North America Lithium-Ion Battery for Electric Vehicle Market
Lithium-ion Battery
Europe Lithium-Ion Battery for Electric Vehicle Market
Lithium-ion Battery
Lithium-Ion Battery Packs Market
Lithium-ion Battery
Lithium-Ion Stationary Battery Market
Lithium-ion Battery
Industrial Lithium-Ion Batteries Market
Lithium-ion Battery
Lithium Battery Pack Market
Lithium-ion Battery
Lithium Battery in Myanmar Market
Lithium-ion Battery
Japan Lithium-Ion Battery Market
Lithium-ion Battery
China SLI Battery Market
Lithium-ion Battery
Automotive Lithium-Ion Battery Cell Market
Lithium-ion Battery
France Lithium-Ion Battery for Electric Vehicle Market
Lithium-ion Battery
Italy Electric Vehicles Battery Anode Market
Lithium-ion Battery
Europe Solid State Battery Market
Lithium-ion Battery
LAMEA Solid State Battery Market