
 Lithium-Ion Battery Cathode Material Market | 2026-2036
Lithium-Ion Battery Cathode Material Market Size, Share, and Industry Trends Forecast 2026-2036
Lithium-Ion Battery Cathode Material Market Analysis
Aftermarket cathode material recycling revenue is tilting toward closed-loop hydrometallurgical recovery as primary metal prices fluctuate. Umicore SA leverages its integrated battery recycling and cathode production footprint across Europe to capture this margin migration. BASF SE anchors its position through joint ventures in Finland and Germany that combine precursor and cathode active material output. Johnson Matthey Plc specializes in high-performance NMC variants for premium automotive contracts, differentiating through tailored nickel-manganese-cobalt ratios.
Lithium-ion battery cathode material comprises the electrochemically active compound—typically lithium metal oxides such as LiFePO4, LiNiMnCoO2, or LiNiCoAlO2—coated onto aluminum current collectors and operating at voltages between 3.2V and 4.3V depending on chemistry. Its primary purpose is to serve as the source of lithium ions during discharge, determining cell capacity, thermal stability, and cycle life. NMC formulations dominate value capture due to automaker preference for energy density above 250 Wh/kg at the cell level. LFP retains structural importance in energy storage systems and entry-level electric vehicles where cost per kWh and cycle longevity outweigh gravimetric density targets. Cylindrical form factor demand aligns with Tesla's 4680 cell ramp and toolset standardization across gigafactories.
The EU Battery Regulation mandates recycled content thresholds and carbon footprint declarations at the cell level, compelling cathode producers to document upstream emissions. China's MIIT enforces GB standards for battery safety and material purity that shape export qualification criteria. EPA hazardous waste rules in the United States govern spent cathode processing permits, influencing where recycling capacity locates. Stakeholders must monitor how nickel and cobalt price volatility intersects with regulatory compliance costs to determine whether chemistry diversification or supply contracting offers more durable margin protection.
Market Dynamics
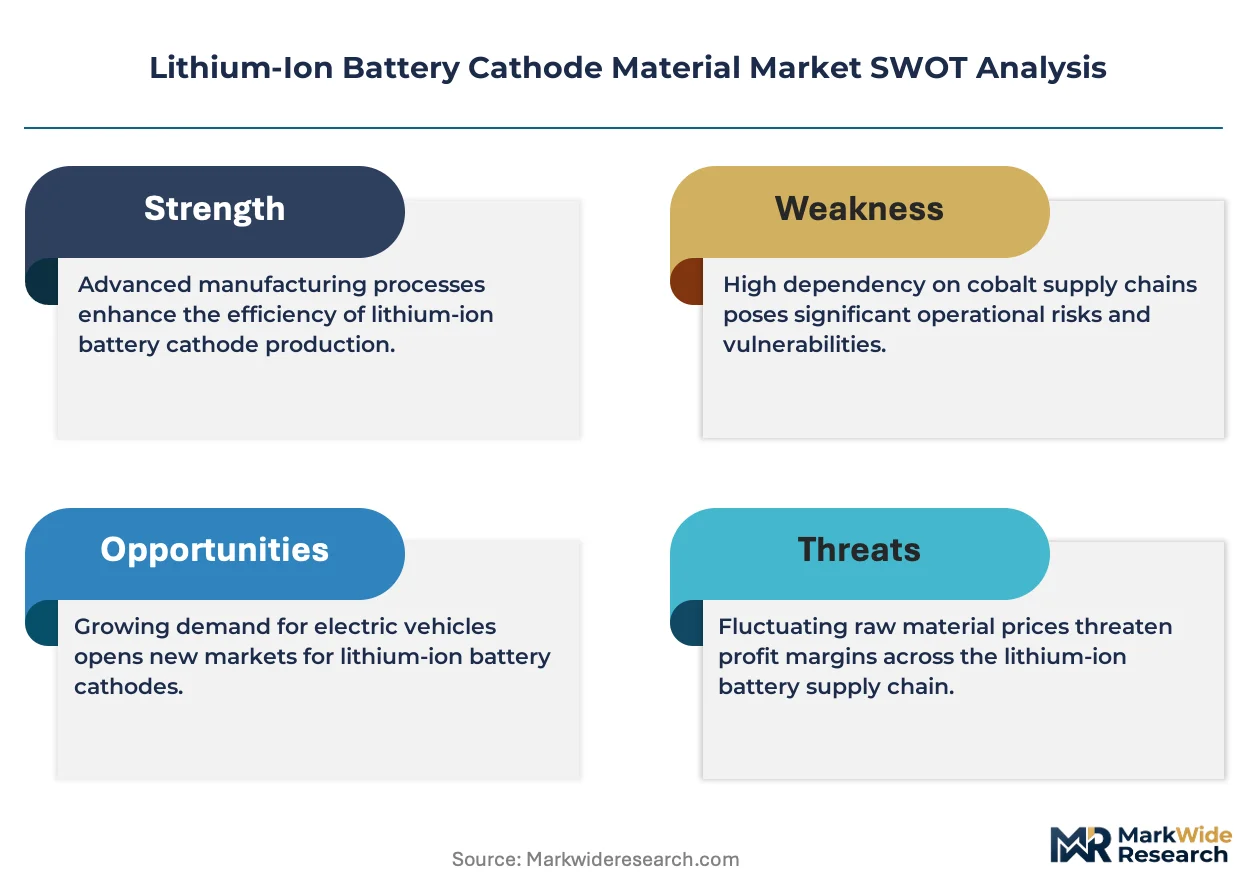
High-nickel cathode chemistry migration is compressing cobalt intensity while automakers chase 300 Wh/kg cell targets. This chemistry pivot is redrawing procurement contracts, precursor supply agreements, and recycling economics across the value chain.
Growth Catalysts
- EU Battery Regulation recycled content mandates:The regulation's 2031 thresholds for recovered lithium, nickel, and cobalt are forcing cathode producers to secure offtake from European hydrometallurgical recyclers. Compliance investments are accelerating closed-loop infrastructure buildout.
- China's dual carbon goals:MIIT enforcement of GB standards for carbon intensity at the precursor stage is pushing Jiangsu and Hunan producers toward renewable-powered calcination. Export qualification now hinges on documented Scope 1 and 2 emissions.
- 4680 cylindrical cell ramp:Tesla's form factor standardization is concentrating cathode demand around high-nickel NMC formulations optimized for dry electrode coating. Toolset commonality across gigafactories is amplifying chemistry lock-in effects.
Market Restraints
- Nickel price volatility:London Metal Exchange nickel contract swings are compressing cathode producer margins faster than formula pricing adjustments can recover. Hedging costs now consume 3-4% of material cost stacks.
- Cobalt supply concentration:DRC artisanal and industrial mine output dominates feedstock for high-voltage NMC variants. ESG due diligence requirements under OECD guidance are extending qualification timelines by 6-12 months.
- LFP energy density ceiling:The 160-170 Wh/kg practical limit of lithium iron phosphate chemistry excludes it from premium automotive platforms targeting 600+ km range. NMC retains structural pricing power in this segment.
Strategic Opportunities
- India PLI scheme for ACC storage:The production-linked incentive program for advanced chemistry cells is attracting cathode precursor joint ventures in Gujarat and Tamil Nadu. First-mover qualification under BIS standards offers 3-5 year tariff protection.
- Solid-state electrolyte convergence:Sulfide-based solid-state cell architectures tolerate higher-voltage cathode operation. NMC811 and NMC9½½ formulations are being re-engineered for lithium-metal anode pairing.
- Direct shipping to gigafactory:Cathode producers are bypassing traditional distributor networks to co-locate with cell manufacturing. BASF's Schwarzheide facility demonstrates captive supply integration with European OEM battery plants.
Industry Challenges
- Pyrometallurgical-to-hydrometallurgical retooling:Existing European recycling capacity was built for cobalt recovery from consumer electronics. Battery-grade nickel and lithium separation requires $200-400 million per facility conversion.
- High-nickel sintering expertise scarcity:NMC9½½ and NCA formulations demand precise oxygen atmosphere control during calcination. Qualified kiln operators and process engineers command 40-60% compensation premiums.
- EU carbon footprint declaration verification:The Battery Regulation's 2027 deadline for cell-level documentation requires upstream traceability to mine site electricity sources. Scope 3 data collection is exposing gaps in African and Indonesian nickel supply chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lithium-Ion Battery Cathode Material Market |
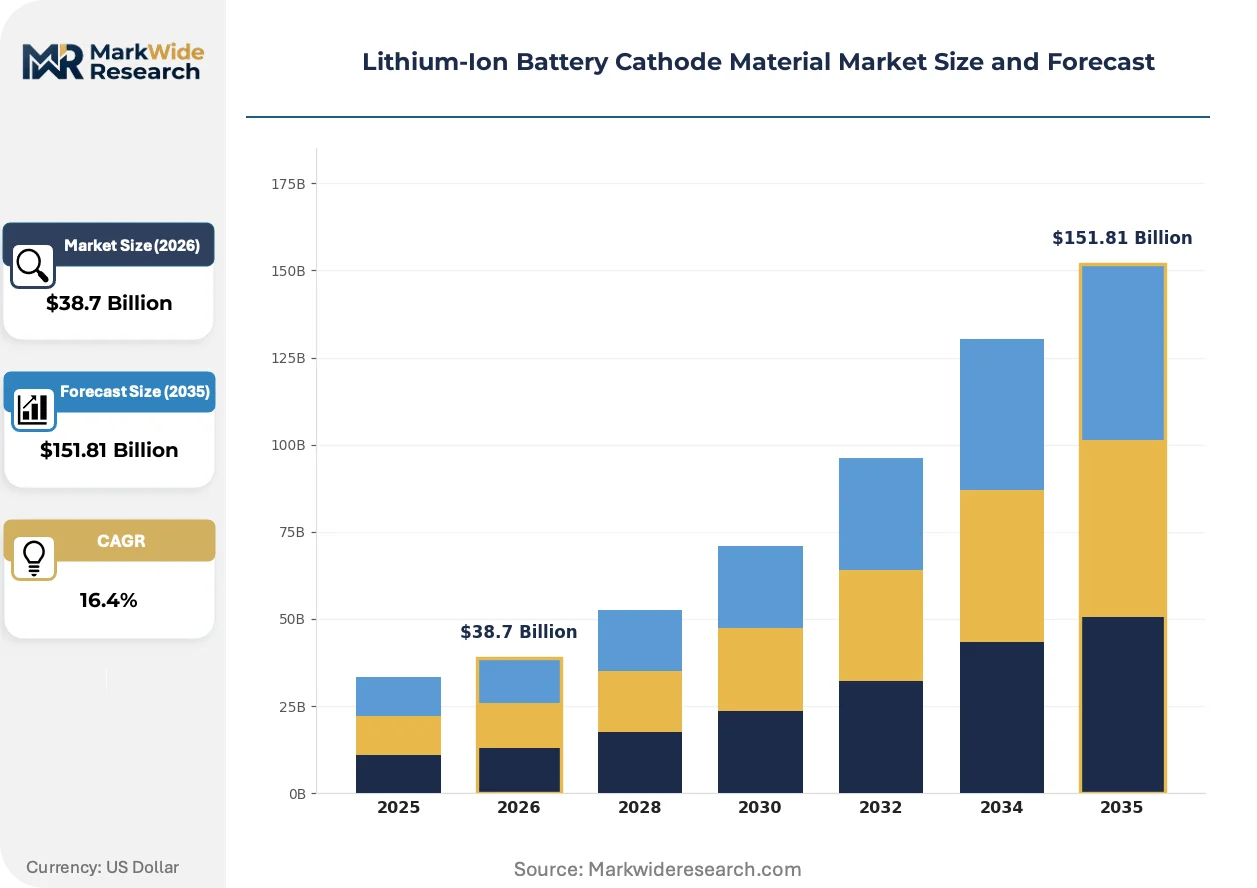
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $151.81 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: LFP, NMC, NCA, LCO Application: Consumer Electronics, Electric Vehicles, Energy Storage Systems, Industrial Equipment Form Factor: Cylindrical, Prismatic, Pouch, Custom End User: Manufacturers, Automotive OEMs, Energy Providers, Research Institutions |
| Companies Covered | BTR New Energy Materials Inc., LG Energy Solution, Ltd, Umicore SA, Shenzhen Dynanonic Co., Ltd, Tianjin B&M Science and Technology Co., Ltd, BASF SE, Ronbay Technology, Johnson Matthey Plc, Sumitomo Metal Mining Co., Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lithium-Ion Battery Cathode Material Market Emerging Trajectories
Process intensification and digital twin deployment are compressing cathode development cycles from 36 months toward 18 months. These accelerants are reshaping competitive moats around formulation IP and manufacturing yield.
Single-crystal NMC technology is virtualizing polycrystalline cathode dominance in premium automotive applications. The architecture eliminates grain boundary degradation pathways, extending cycle life to 2,000+ deep discharges. BMW and Mercedes-Benz cell suppliers are qualifying single-crystal NMC811 for 2026 platform launches, compressing incumbent polycrystalline capacity utilization rates.
REACH authorization requirements for nickel compounds are tightening precursor import conditions into the European Economic Area. The ECHA sunset date for unregistered nickel sulfate uses is forcing non-EU cathode producers to establish EU-based conversion capacity. Finnish and German precursor-to-cathode corridors are capturing margin from Asian exporters facing registration cost barriers.
Automaker direct cathode procurement is displacing tiered supplier hierarchies that historically separated OEMs from material producers. Volkswagen PowerCo and Stellantis are negotiating multi-year offtake directly with Umicore and Johnson Matthey, compressing trading house intermediation. This disintermediation concentrates price discovery power with volume buyers in Germany and France.
Lithium-Ion Battery Cathode Material Market Segmentation
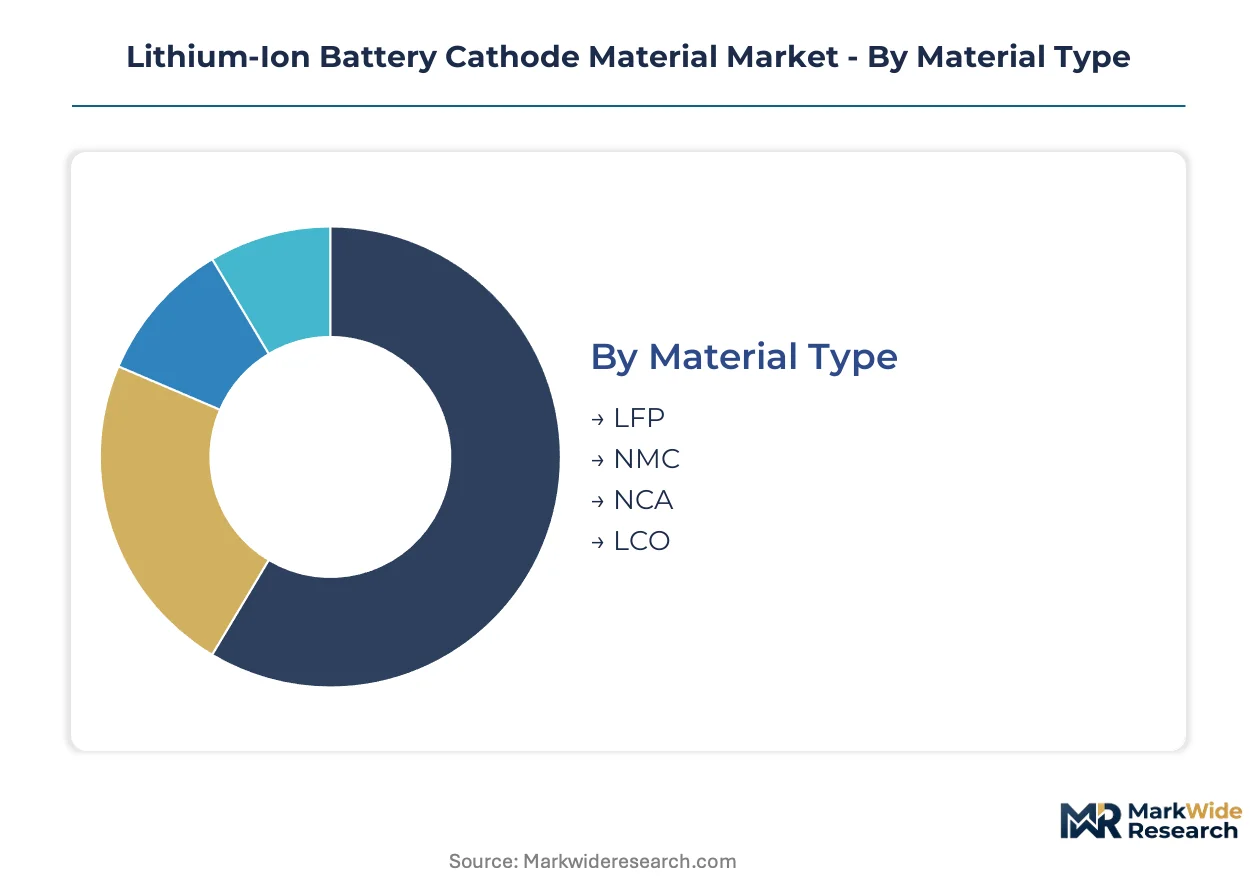
Cathode material segmentation determines procurement strategies across cell manufacturers and automakers. Chemistry selection locks in energy density ceilings, thermal profiles, and recycling economics. Each dimension—material, application, form factor, end user—creates distinct margin pools and qualification barriers.
Material Type:
Mature chemistries dominate installed capacity while emerging formulations capture next-generation platform wins.
- NMC:Nickel-manganese-cobalt oxides span NMC111 to NMC9½½ ratios, with high-nickel variants exceeding 250 Wh/kg at cell level. Demand concentrates in European and Korean automotive supply chains targeting 600+ km range platforms, constrained by cobalt ESG due diligence timelines under OECD guidance.
- LFP:Lithium iron phosphate operates at 3.2V with 160-170 Wh/kg practical limits, offering 4,000+ cycle life. Chinese producers in Jiangsu and Hunan provinces anchor global supply for entry-level electric vehicles and grid storage, driven by cost-per-kWh advantages under MIIT carbon intensity enforcement.
- NCA:Nickel-cobalt-aluminum chemistry delivers extreme energy density for premium cylindrical cells. Tesla's 4680 ramp in Nevada and Texas concentrates procurement around dry-electrode compatible NCA formulations.
- LCO:Lithium cobalt oxide retains dominance in smartphone and laptop cells where volumetric density outweighs cost. Japanese and Korean consumer electronics manufacturers sustain demand despite limited automotive applicability.
NMC retains volume leadership; NMC9½½ and derivatives hold the steepest expansion curve.
Application:
Cost tier stratification separates commodity volume from premium qualification requirements.
- Electric Vehicles:Automotive platforms demand 300 Wh/kg cell targets, driving high-nickel NMC and NCA adoption. OEMs in Germany, France, and China negotiate direct cathode offtake, bypassing distributor networks.
- Energy Storage Systems:Grid and residential storage prioritizes cycle longevity over gravimetric density. LFP captures dominant share in Chinese and US utility-scale deployments, with 4-hour duration batteries becoming standard.
- Consumer Electronics:Smartphones, laptops, and wearables require compact form factors. LCO and mid-nickel NMC serve Korean and Japanese electronics manufacturers with established supply chains.
- Industrial Equipment:Forklifts, mining vehicles, and marine applications tolerate lower energy density for enhanced safety margins. LFP and manganese-rich chemistries serve European and North American industrial OEMs.
Electric Vehicles command the premium pricing tier; Energy Storage Systems deliver the steepest volume climb.
Form Factor:
Customer type alignment—automotive OEM versus electronics manufacturer—determines form factor selection and cathode specification.
- Cylindrical:18650, 2170, and 4680 formats standardize around high-nickel chemistries. Tesla's toolset commonality across gigafactories in Texas, Nevada, and Berlin locks in cylindrical demand.
- Prismatic:Pouch-stacked rectangular cells dominate Korean and Chinese automotive platforms. CATL and LG Energy Solution specify NMC and LFP variants for blade and module-integrated designs.
- Pouch:Flexible aluminum-laminated cells serve European premium automotive and aviation applications. Solid-state development programs in Germany and Japan favor pouch formats for lithium-metal anode pairing.
- Custom:Non-standard dimensions address military, aerospace, and medical device requirements. Low-volume, high-margin contracts with US and Israeli defense contractors sustain specialized cathode production.
Cylindrical formats anchor automotive volume; custom geometries sustain the highest margin per kilogram.
End User:
Supply concentration clusters around integrated precursor-to-cathode corridors in specific manufacturing geographies.
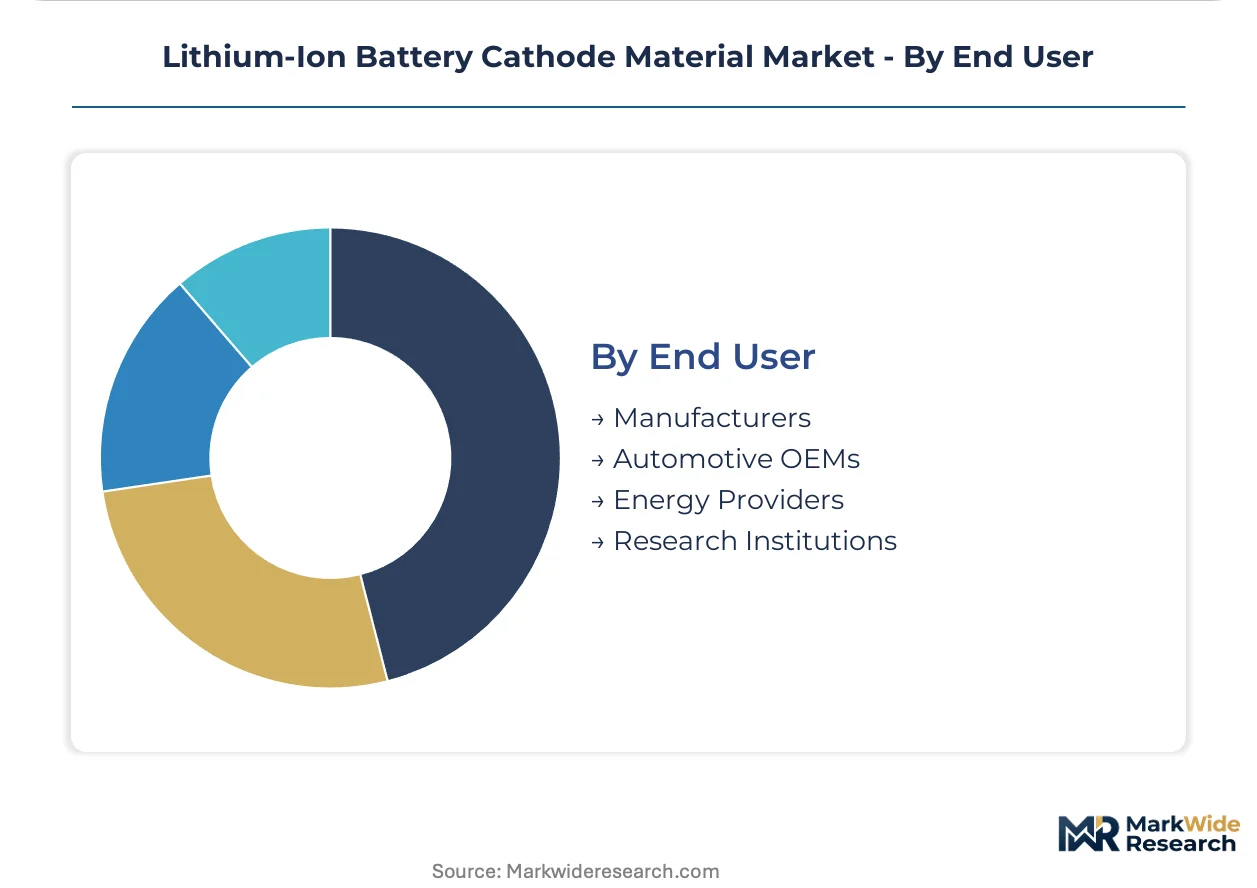
- Automotive OEMs:Volkswagen, Stellantis, and Chinese EV manufacturers negotiate multi-year cathode offtake directly with producers. European Battery Regulation recycled content mandates force OEMs to secure European hydrometallurgical recycler partnerships.
- Manufacturers:Cell producers including CATL, BYD, and Samsung SDI procure cathode active material for internal consumption. Chinese manufacturers in Fujian and Guangdong provinces integrate backward into precursor production.
- Energy Providers:Utility and independent power producers specify LFP for grid storage installations. NextEra Energy and State Grid Corporation of China drive procurement standardization around 20-foot container systems.
- Research Institutions:National laboratories and university programs source small-batch cathode samples for solid-state and sodium-ion development. US Department of Energy and Chinese Academy of Sciences funding shapes next-generation chemistry roadmaps.
Automotive OEMs concentrate purchasing power; Energy Providers represent the fastest-growing demand segment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese buyers exhibit the lowest price elasticity as integrated supply chains compress procurement costs, while European automakers face steep premium absorption under carbon border compliance mandates. German and French OEMs absorb 15-20% cost premiums for documented low-carbon cathode, whereas Indian and Southeast Asian buyers remain acutely sensitive to nickel price volatility.
China
Jiangsu and Hunan provinces host integrated precursor-to-cathode corridors serving CATL and BYD with NMC and LFP formulations. MIIT enforcement of GB standards for carbon intensity at calcination stages now conditions export qualification on documented Scope 1 and 2 emissions. Changsha and Xiamen clusters concentrate high-nickel NMC capacity expansion as automakers chase 300 Wh/kg cell targets.
Germany
Volkswagen PowerCo and BMW direct procurement contracts are displacing traditional distributor hierarchies for high-nickel cathode supply. EU Battery Regulation recycled content mandates for 2031 force producers to secure offtake from European hydrometallurgical recyclers. BASF's Schwarzheide facility in Brandenburg demonstrates captive supply integration with regional OEM battery plants.
United States
Tesla's 4680 cylindrical cell ramp in Nevada and Texas concentrates demand around dry-electrode compatible NCA and high-nickel NMC formulations. EPA hazardous waste rules govern spent cathode processing permits, influencing where recycling capacity locates. The Southeast battery corridor spanning Georgia and South Carolina is attracting cathode co-location investments from Asian producers seeking IRA qualification.
South Korea
LG Energy Solution and Samsung SDI specify prismatic NMC variants for premium automotive platforms targeting 600+ km range. KBA vehicle-type approval requirements cascade into cathode material qualification timelines. The Gyeonggi-Seoul industrial belt concentrates cell manufacturing capacity with backward integration into precursor joint ventures.
India
Reliance Industries and Ola Electric are qualifying LFP cathode for entry-level two-wheeler and four-wheeler platforms under PLI scheme incentives. BIS standards for advanced chemistry cells offer first-movers 3-5 year tariff protection against ASEAN imports. Gujarat and Tamil Nadu are emerging as precursor joint venture locations as ACC storage procurement accelerates.
Lithium-Ion Battery Cathode Material Market Vendor Landscape
Integrated materials conglomerates and specialized cathode producers split the market into distinct capability tiers. The vendor base concentrates around three strategic archetypes: diversified chemical majors with battery material divisions, dedicated cathode specialists with precursor integration, and mining-forward operators with downstream conversion assets. Competitive intensity centers on capacity expansion in European and North American markets to capture IRA and EU Battery Regulation compliance premiums, alongside technology licensing agreements for single-crystal NMC process IP.
Among diversified chemical majors, BASF SE and Umicore SA exemplify the integrated production model spanning precursor synthesis through cathode active material output. Johnson Matthey Plc occupies a specialist position within the high-performance NMC formulation tier. Chinese producers including BTR New Energy Materials Inc., Shenzhen Dynanonic Co., Ltd, and Ronbay Technology anchor the scale-driven supply base serving domestic cell manufacturers with cost-optimized LFP and NMC variants.
| Leading Market Players |
|---|
| BTR New Energy Materials Inc. |
| LG Energy Solution, Ltd |
| Umicore SA |
| Shenzhen Dynanonic Co., Ltd |
| Tianjin B&M Science and Technology Co., Ltd |
| BASF SE |
| Ronbay Technology |
| Johnson Matthey Plc |
| Sumitomo Metal Mining Co., Ltd |
| Others |
Supply Flow & Price Mechanics
Indonesian nickel laterite and DRC cobalt concentrate anchor upstream cost structures, with downstream margin pools concentrating around European hydrometallurgical conversion and Chinese integrated precursor-to-cathode corridors. London Metal Exchange contract volatility transmits directly into cathode active material pricing, compressing producer margins faster than long-term offtake adjustments can recover.
Pricing Analysis
Aftermarket cathode material recycling revenue drives lifetime value expansion as primary metal price fluctuations intensify. Contract-based long-term offtake dominates automotive procurement, with price differentiation hinging on carbon footprint certification under EU Battery Regulation tiers and volume scale commitments. Cost compression in high-nickel NMC formulations is intensifying because nickel price hedging now consumes material cost stack capacity. Energy storage system buyers exhibit acute price sensitivity, while German and French OEMs absorb premiums for documented low-carbon cathode supply.
Supply Chain Analysis
Upstream feedstock from Indonesia, the Democratic Republic of Congo, and Australia feeds global cathode production networks. Nickel laterite, cobalt hydroxide, and lithium carbonate constitute critical input dependencies, with single-source vulnerability concentrated in DRC artisanal and industrial mine output. Distribution runs through direct co-location with gigafactory sites, bypassing traditional trading house intermediation as automakers consolidate procurement power.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Closed-loop hydrometallurgical recovery services expand faster than virgin cathode production, creating a service-attach opportunity where recycling margins decouple from primary metal volatility. This recurring-revenue layer offers structural protection against commodity price cycles.
For Market Incumbents: Insulate margin positions by securing captive precursor supply through backward integration into Indonesian nickel and DRC cobalt joint ventures, while accelerating EU-based hydrometallurgical recycling capacity to capture compliance premiums under Battery Regulation recycled content mandates. Single-crystal NMC process IP licensing offers defensive moat extension against emerging Chinese producers. For New Entrants and Emerging Players: Pursue qualification under India's PLI scheme for advanced chemistry cells, where first-mover BIS certification offers tariff-protected market access against ASEAN imports. Gujarat and Tamil Nadu precursor joint ventures represent the most penetrable geography, with go-to-market traction through direct supply agreements with Reliance Industries and Ola Electric for LFP formulations. For Investors and Strategic Acquirers: Capital is best deployed toward European hydrometallurgical recyclers with pyrometallurgical-to-hydrometallurgical conversion assets and established offtake relationships with automotive OEMs. Long-term viability across the next decade hinges on carbon footprint verification infrastructure and mine-site Scope 3 data collection capabilities. The signal to monitor is EU Battery Regulation enforcement timelines for cell-level documentation requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nickel Feedstock | Captive supply from Indonesian laterite operations reduces LME price exposure for NMC producers. |
| EU Hydrometallurgical Recycling Capacity Buildout | BASF's Schwarzheide facility demonstrates compliance integration with Volkswagen PowerCo battery plants. |
| Single-Crystal NMC Process Licensing | BMW and Mercedes-Benz qualification programs reward formulation IP holders with platform lock-in. |
| Direct Gigafactory Co-Location | Tesla's 4680 ramp in Nevada concentrates procurement around dry-electrode compatible cathode supply. |
| Carbon Footprint Certification Investment | MIIT GB standards enforcement conditions Chinese export qualification on documented Scope 1 and 2 emissions. |
Methodological Framework
Operator-level perspectives from cathode plant managers, precursor procurement leads at cell manufacturers, OEM platform engineers, and hydrometallurgical recycling facility directors anchored the qualitative base. These primary interviews combined with secondary validation from MIIT GB standard filings, EU Battery Regulation implementation guidance, LME nickel contract data, and SEC 10-K disclosures from integrated materials conglomerates. Bottom-up capacity installation tracking and top-down demand modeling from electric vehicle production forecasts enabled triangulation across independent analytical paths.
Scenario-bracketing around nickel price volatility bands and EU regulatory enforcement timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include cathode chemistry tier, cell form factor, end-use application, and regional production cluster. CAGRs derived from installed capacity expansion curves and automaker platform launch schedules, with cross-referencing against battery pack cost trajectory assumptions and solid-state electrolyte development milestones.
Sensitivities concentrate around nickel and cobalt price volatility, EU carbon footprint declaration verification delays, and Chinese export qualification disruptions under dual carbon enforcement. Forecasts reflect documented assumptions about high-nickel chemistry migration rates and recycling infrastructure buildout timelines. Cross-checking against IEA critical minerals supply projections and automotive OEM battery demand disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Lithium Ion Energy Accumulator Market
Lithium-ion Battery
Lithium-Sulfur Battery Market
Lithium-ion Battery
Lithium-Ion Battery Metal Market
Lithium-ion Battery
LAMEA Solid State Battery Market
Lithium-ion Battery
Automotive Lithium Based Battery Market
Lithium-ion Battery
Lithium Hydroxide Market
Lithium-ion Battery
Solid State Battery Market
Lithium-ion Battery
France Electric Vehicle Lithium-Ion Battery Separator Market
Lithium-ion Battery
Lithium-Ion Polymer Batteries Market
Lithium-ion Battery
Lawn Mower Lithium Battery Market
Lithium-ion Battery
United States Electric Vehicle Battery Electrolyte Market
Lithium-ion Battery
North America Lithium-Ion Battery Market
Lithium-ion Battery
Lithium Battery Pack Market
Lithium-ion Battery
China Electric Vehicle Lithium-Ion Battery Separator Market
Lithium-ion Battery
Lithium-Ion Battery Separator Market
Lithium-ion Battery
Manganese Dioxide Lithium Battery Market