
 LAMEA Solid State Battery Market | 2026-2036
LAMEA Solid State Battery Market Size, Share, and Industry Trends Forecast 2026-2036
LAMEA Solid State Battery Market Insights
Brazil's emerging battery materials corridor is narrowing the supply chain distance between raw lithium processing and cell assembly. Toyota Motor Corporation leverages its solid-state R&D heritage to anchor pilot production discussions with São Paulo-based automotive partners. Samsung SDI Co., Ltd. competes through advanced ceramic electrolyte know-how, while Blue Solutions sustains its niche in solid polymer systems for specialized mobility applications.
A solid-state battery replaces flammable liquid electrolytes with ion-conductive solids such as sulfide glasses, oxide ceramics, or polymer composites, achieving energy densities above 300 Wh/kg while eliminating thermal runaway risks in high-duty cycling. The technology serves electric vehicles, grid storage, and aerospace platforms where safety margins and volumetric efficiency carry premium value. Ceramic batteries dominate current LAMEA procurement conversations due to their compatibility with existing lithium-ion manufacturing tooling, while thin-film architectures specialize in micro-power applications for defense electronics and medical sensors. Solid polymer batteries occupy the mid-range, attracting energy providers seeking modular storage with simplified thermal management.
Brazil's national energy regulator and the Argentine Secretariat of Energy shape market access through storage procurement quotas tied to renewable auction rounds, while Chile's environmental impact assessment framework governs lithium extraction permits that feed upstream material supply. The EU-LAMEA Green Alliance technical standards increasingly influence product certification requirements for batteries exported to European automotive OEMs. Stakeholders must track how national development bank financing terms evolve for domestic cell manufacturing versus imported pack assembly.
Market Dynamics
Ceramic electrolyte compatibility with existing lithium-ion tooling is compressing time-to-market for LAMEA manufacturers facing procurement deadlines from Brazil's renewable auction quotas.
Growth Catalysts
- Brazil's storage procurement quotas:ANEEL's auction mandates require grid-scale battery pairing with renewable projects, pulling solid-state cell demand into the industrial southeast.
- Chilean lithium extraction permits:The environmental impact assessment framework governs upstream material supply, anchoring regional cathode precursor production near Atacama extraction sites.
- Ceramic electrolyte tooling compatibility:Oxide formulations slot into existing electrode coating lines, slashing retooling capex versus sulfide glass alternatives.
Market Restraints
- Argentine lithium carbonate volatility:Secretariat of Energy export licensing delays create feedstock uncertainty for Brazilian cathode plants.
- Sulfide electrolyte moisture sensitivity:Production requires sub-ppm humidity environments, constraining viable manufacturing geographies to coastal industrial zones with desiccant infrastructure.
- EU-LAMEA Green Alliance certification lag:European automotive OEMs impose testing timelines that outpace regional lab capacity, delaying pack qualification.
Strategic Opportunities
- Argentina's underdeveloped cell assembly base:Proximity to lithium brine operations invites backward integration into electrode production for export to Brazilian pack integrators.
- Defense electronics thin-film demand:Solid-state micro-batteries for aerospace platforms leverage regional cobalt-free cathode research from São Paulo institutes.
- Chilean national development bank financing:CORFO's domestic manufacturing credit lines favor solid-state ventures over imported pack assembly, reshaping capital access.
Industry Challenges
- Solid-state interface engineering talent scarcity:Ceramic-electrode contact optimization requires specialists concentrated in Asian and European research hubs, forcing LAMEA firms into premium expatriate hiring.
- Multi-layer stack lamination yield:Dry electrode bonding for sulfide cells demands precision equipment with 18-month lead times, compressing pilot production schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LAMEA Solid State Battery Market |
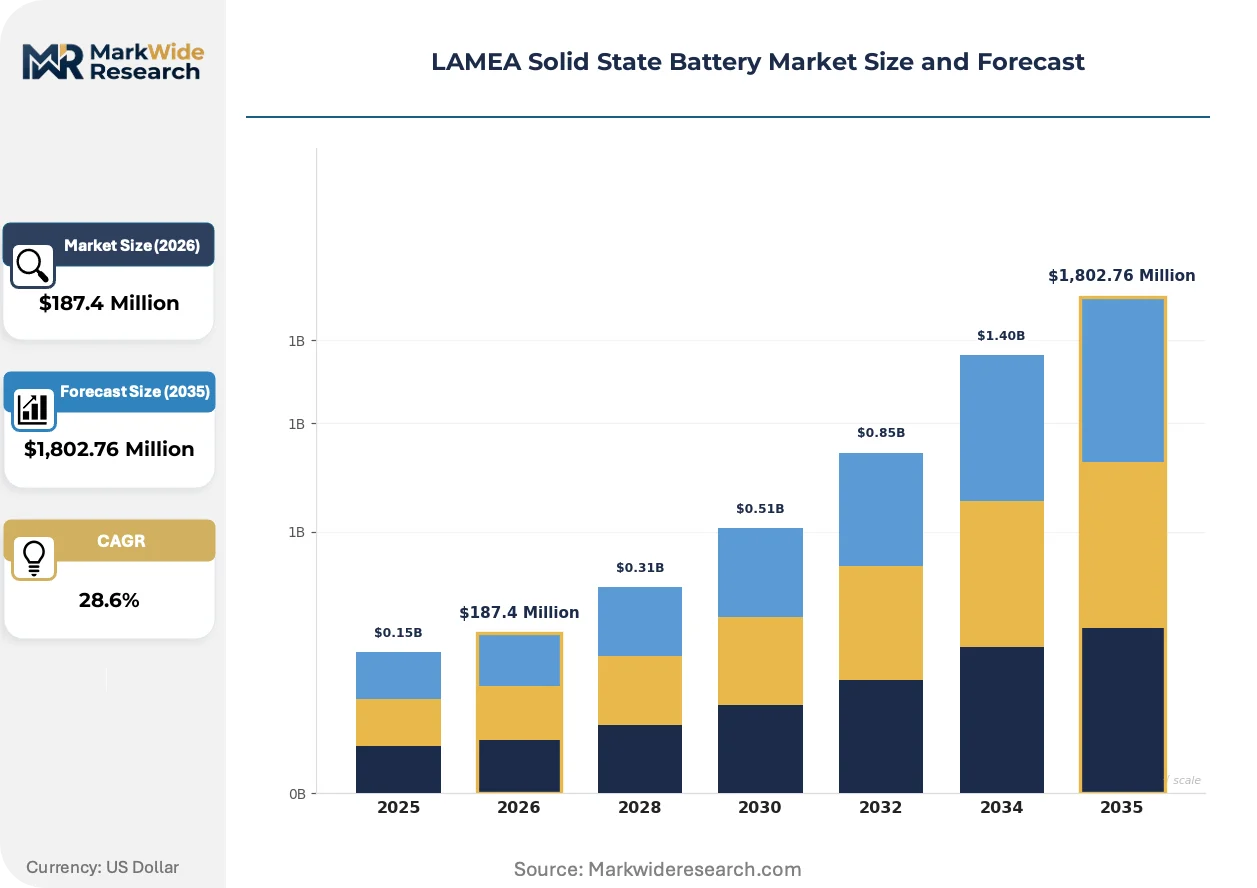
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $1,802.76 Million |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thin-Film Battery, Solid Polymer Battery, Lithium-Sulfur Battery, Ceramic Battery Application: Electric Vehicles, Consumer Electronics, Renewable Energy Storage, Aerospace End User: Automotive OEMs, Electronics Manufacturers, Energy Providers, Defense Contractors Technology: Solid Electrolyte, Li-Ion Technology, High-Temperature Electrolyte, Advanced Coating |
| Companies Covered | Solid Power, Inc., QuantumScape Corporation, Samsung SDI Co., Ltd., LG Energy Solution Ltd., Toyota Motor Corporation, Robert Bosch GmbH, Ilika plc, ProLogium Technology Co., Ltd., Blue Solutions, Others |
| Regions Covered | LAMEA: Brazil, Mexico, Argentina, Saudi Arabia, UAE, South Africa, Nigeria, Egypt, Rest of LAMEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LAMEA Solid State Battery Market Trends and Innovations
Process digitization and regulatory alignment with European automotive standards are compressing development cycles for regional solid-state ventures.
Oxide ceramic electrolyte slurry coating is digitizing quality control workflows through in-line impedance spectroscopy, enabling real-time defect detection during electrode stacking. Brazilian automotive OEMs pilot this at São Paulo pilot lines, trimming qualification timelines from 24 months toward 14-month targets. The compression is digitizing competitive entry barriers, favoring capital-rich incumbents over venture-stage challengers.
ANEEL's grid interconnection standards now mandate thermal runaway propagation testing that mirrors EU battery passport requirements, forcing pack architects toward solid-state architectures by default. Industrial developers in Minas Gerais report redesign costs for liquid-electrolyte alternatives now exceed solid-state premium differentials. The policy convergence is digitizing procurement specifications across Brazil's renewable auction rounds.
Automotive OEMs now specify cell-level traceability from lithium extraction through pack assembly, displacing spot-market cathode purchasing. Tier-one suppliers in São Paulo's ABC region consolidate around long-term offtake agreements with Argentine brine operators, locking in five-year supply visibility. This specification tightening is digitizing contract structures most visibly in Brazil's electric bus procurement corridors.
LAMEA Solid State Battery Market Segmentation
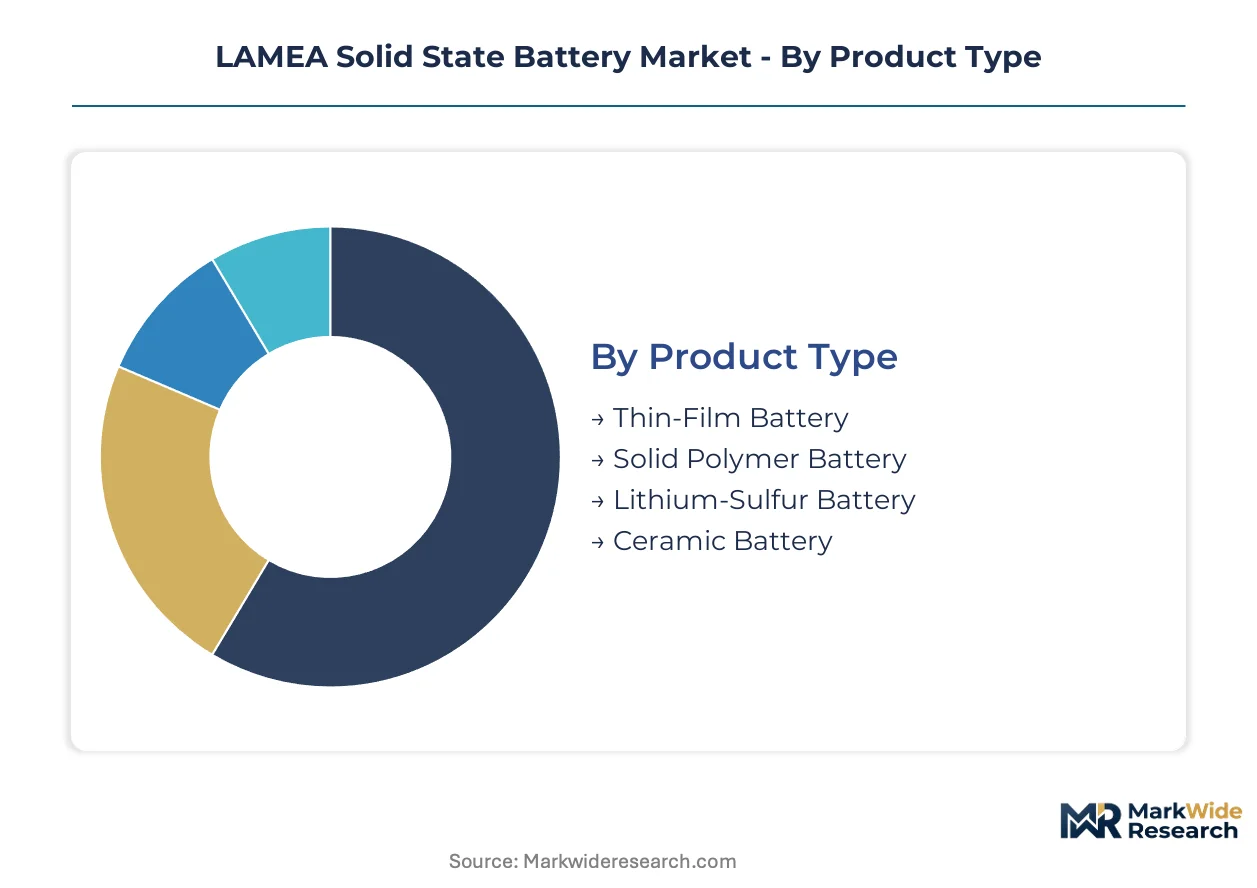
Solid-state battery procurement in LAMEA fragments across four distinct dimensions. Each segmentation axis reveals divergent technical requirements, certification timelines, and supplier qualification hurdles that reshape competitive entry points.
Product Type:
After-sales service intensity varies sharply across solid-state chemistries, with ceramic and sulfide systems demanding specialized diagnostic infrastructure that thin-film architectures bypass entirely.
- Ceramic Battery:Oxide electrolyte formulations leverage existing lithium-ion electrode coating lines, trimming retooling capital for Brazilian automotive OEMs in São Paulo's ABC region. Grid-scale developers in Minas Gerais prioritize ceramic cells for ANEEL-mandated thermal runaway propagation testing, where oxide stability eliminates liquid-electrolyte redesign costs.
- Thin-Film Battery:Micro-power architectures deposit electrolyte layers via physical vapor deposition, achieving sub-millimeter form factors for aerospace sensor payloads. Defense electronics procurement in Brazil's industrial southeast concentrates here, driven by cobalt-free cathode research from São Paulo institutes that eliminates supply chain exposure to Argentine lithium carbonate volatility.
- Solid Polymer Battery:Polyethylene-oxide based electrolytes operate at ambient temperatures with simplified thermal management, attracting energy providers seeking modular storage for distributed renewable integration.
- Lithium-Sulfur Battery:Sulfur cathode chemistry paired with solid electrolytes pushes theoretical energy densities toward 500 Wh/kg, though polysulfide shuttle effects constrain cycle life in early LAMEA deployments.
Ceramic batteries hold the largest share; momentum sits with thin-film architectures for defense and aerospace qualification pipelines.
Application:
Volume concentration and margin structure diverge across end-use sectors, with electric vehicles capturing procurement scale and aerospace commanding qualification premiums.
- Electric Vehicles:Brazilian automotive OEMs anchor pilot production discussions for solid-state cell integration, with ANEEL's renewable auction quotas indirectly pulling battery demand through grid-scale storage co-location strategies. Toyota Motor Corporation leverages its sulfide glass heritage in São Paulo partnership talks.
- Renewable Energy Storage:Grid-scale developers face ANEEL mandates requiring battery pairing with wind and solar auction winners, compressing supplier qualification timelines toward 14-month targets.
- Consumer Electronics:Wearable and portable device manufacturers prioritize thin-film solid-state cells for volumetric efficiency, though LAMEA demand lags Asian manufacturing hubs.
- Aerospace:Satellite and unmanned platform specifications demand the highest safety margins, with solid-state architectures eliminating thermal runaway risks that liquid electrolytes cannot satisfy at altitude.
Electric vehicles command the dominant procurement volume; renewable energy storage is climbing the fastest as auction mandates tighten.
End User:
Customer type determines contract structure, with automotive OEMs demanding cell-level traceability and energy providers accepting pack-level procurement.
- Automotive OEMs:Brazilian manufacturers now specify lithium extraction-to-assembly traceability, displacing spot-market cathode purchasing in favor of five-year Argentine brine offtake agreements.
- Energy Providers:Grid developers in Brazil's industrial southeast consolidate procurement around solid-state packs for ANEEL-compliant interconnection, prioritizing ceramic electrolyte compatibility over energy density maximization.
- Electronics Manufacturers:Consumer device assemblers source thin-film cells for premium product lines, though regional production capacity remains concentrated in Asian supply bases.
- Defense Contractors:Aerospace and military specifications leverage São Paulo institute research on cobalt-free cathodes, with procurement isolated from commercial lithium carbonate price swings.
Automotive OEMs dominate contract value; defense contractors represent the steepest expansion trajectory as sovereign capability programs accelerate.
Technology:
Manufacturing maturity and equipment lead times fragment the supplier base, with solid electrolyte deposition requiring precision infrastructure that advanced coating techniques circumvent.
- Solid Electrolyte:Sulfide glass and oxide ceramic formulations demand sub-ppm humidity environments, constraining viable production geographies to coastal Brazilian industrial zones with desiccant infrastructure.
- Advanced Coating:Slurry-based oxide electrolyte application digitizes quality control through in-line impedance spectroscopy, enabling real-time defect detection that trims qualification timelines.
- Li-Ion Technology:Solid-state architectures that retain conventional lithium-ion electrode materials ease supplier transition, leveraging existing cathode precursor supply from Argentine brine operations.
- High-Temperature Electrolyte:Phosphate-based systems operating above 80°C target grid storage applications where thermal management infrastructure is pre-installed.
Solid electrolyte technology anchors current production; advanced coating methods are gaining share fastest as digitization compresses development cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ANEEL's storage procurement quotas anchor Brazil's market dominance, with the national energy regulator mandating battery pairing for renewable auction winners. Chilean lithium extraction permits and Argentine brine operations feed upstream material supply across the region.
Brazil
Grid-scale developers in Minas Gerais and São Paulo's ABC region drive ceramic battery procurement for ANEEL-compliant interconnection standards. The national energy regulator mandates thermal runaway propagation testing that favors solid-state architectures over liquid-electrolyte redesigns. Automotive OEMs in São Paulo pilot production discussions with sulfide glass heritage partners, compressing supplier qualification timelines toward 14-month targets.
Chile
CORFO's domestic manufacturing credit lines reshape capital access for solid-state ventures versus imported pack assembly. The environmental impact assessment framework governs lithium extraction permits anchoring regional cathode precursor production near Atacama brine operations. Grid developers concentrate procurement around ceramic electrolyte compatibility for renewable auction compliance.
Argentina
Proximity to lithium brine operations invites backward integration into electrode production for export to Brazilian pack integrators. The Secretariat of Energy export licensing creates feedstock uncertainty that five-year offtake agreements increasingly displace. Mendoza-based cathode plants face volatility from carbonate price swings.
Mexico
Nearshoring automotive supply chains pull pilot production discussions for solid-state cell integration with North American OEMs. The national development bank financing terms favor domestic cell manufacturing over imported pack assembly for grid-scale storage. Industrial developers in Nuevo León explore ceramic electrolyte tooling compatibility for compressed time-to-market.
LAMEA Solid State Battery Market Competitive Landscape
Asian conglomerates and European specialists split the market between scale-driven ceramic production and niche thin-film architectures. The vendor base concentrates around three strategic archetypes: automotive heritage players leveraging R&D depth, battery-focused manufacturers with electrode coating expertise, and materials science specialists occupying solid polymer segments. Competitive moves center on strategic partnerships with regional automotive OEMs and capacity expansion near lithium extraction sites.
Within the automotive heritage tier, Toyota Motor Corporation exemplifies sulfide glass R&D leverage in São Paulo partnership discussions. Samsung SDI Co., Ltd. occupies a position among Korean manufacturers with advanced ceramic electrolyte capabilities. Blue Solutions anchors the solid polymer specialist archetype for specialized mobility applications. These three represent distinct competitive vectors: heritage-driven pilot production, coating technology scale, and polymer system niche defense.
| Leading Market Players |
|---|
| Solid Power, Inc. |
| QuantumScape Corporation |
| Samsung SDI Co., Ltd. |
| LG Energy Solution Ltd. |
| Toyota Motor Corporation |
| Robert Bosch GmbH |
| Ilika plc |
| ProLogium Technology Co., Ltd. |
| Blue Solutions |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in Argentine lithium carbonate refining compresses cathode precursor margins for Brazilian cell manufacturers, forcing oxide ceramic electrolyte buyers toward long-term offtake contracts that lock in volume visibility at the expense of pricing flexibility. ANEEL's renewable auction quotas accelerate procurement timelines, amplifying supplier pricing power in São Paulo's industrial corridor.
Pricing Analysis
Brazil-to-Argentina price spreads for cathode precursors exceed those for finished cells, incentivizing backward integration into electrode production. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade and volume scale, with ANEEL-compliant thermal runaway testing commanding tier-one premiums. Pricing pressure stems from sulfide electrolyte moisture sensitivity and the capital intensity of sub-ppm humidity infrastructure. Energy providers exhibit highest price sensitivity, prioritizing ceramic electrolyte compatibility over energy density maximization.
Supply Chain Analysis
Tariff exposure between Argentina and Brazil dominates supply chain risk calculus for cathode precursor flows. Raw material dependencies center on Chilean lithium brine, Argentine carbonate refining, and Korean electrolyte precursor imports. Single-source vulnerability concentrates in Atacama extraction permits governed by CORFO's environmental framework. Distribution runs through São Paulo-based pack integrators serving ANEEL-mandated grid developers in Minas Gerais.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The LAMEA solid-state battery market is approaching a platform-economics inflection where ANEEL's grid interconnection standards and EU-LAMEA Green Alliance certification convergence create interoperability lock-in for early movers. The ceramic electrolyte tooling compatibility advantage is consolidating procurement specifications around a narrow technical baseline.
For Market Incumbents:Pre-empt sulfide glass specialist entrants by securing exclusive electrode coating partnerships with São Paulo automotive OEMs before qualification timelines compress further. Anchor capacity expansion in coastal Brazilian industrial zones with existing desiccant infrastructure, neutralizing the moisture sensitivity barrier that constrains rival geographies. Cement ANEEL relationship management as the priority lever against Korean ceramic electrolyte competitors.
For New Entrants and Emerging Players:Establish a beachhead in Argentina's underdeveloped cell assembly base, exploiting proximity to lithium brine operations for backward integration into cathode precursor production. Target defense electronics thin-film procurement, where São Paulo institute cobalt-free cathode research eliminates feedstock exposure to Argentine carbonate volatility. Lead with solid polymer systems for modular energy storage, bypassing the ceramic electrolyte equipment lead time bottleneck.
For Investors and Strategic Acquirers:Recurring-revenue conversion is highest among energy providers locked into ANEEL-mandated long-term service agreements for grid-scale storage. Over the projection horizon, acquisition targets should screen for ceramic electrolyte slurry coating digitization capabilities and existing Brazilian automotive OEM qualification relationships. Watch CORFO domestic manufacturing credit line allocation shifts as the inflection signal for capital access tiering.
| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Electrolyte Capacity Buildout | ANEEL-compliant thermal runaway testing eliminates liquid-electrolyte redesign costs for grid developers. |
| Backward Integration into Cathode Production | Argentine brine proximity secures feedstock visibility against Secretariat of Energy export licensing delays. |
| Defense Electronics Thin-Film Partnership | São Paulo institute cobalt-free research isolates procurement from lithium carbonate price swings. |
| Sub-ppm Humidity Infrastructure Investment | Coastal Brazilian zones with desiccant capability constrain viable sulfide glass manufacturing geographies. |
| EU-LAMEA Green Alliance Certification Alignment | European automotive OEM testing timelines reshape regional lab capacity investment priorities. |
Research Methodology
A standing panel of battery cell manufacturing executives, ANEEL regulatory affairs specialists, Argentine brine operation managers, and São Paulo automotive OEM platform engineers provided ongoing calibration across the analysis window. Primary interview findings were cross-referenced against secondary validation from CORFO financing disclosure records, ANEEL auction procurement databases, SEC filings from listed battery manufacturers, and Chilean environmental impact assessment frameworks. Bottom-up cell production capacity estimates were triangulated with top-down renewable auction storage mandate trajectories.
Scenario-bracketing framed volume and value outputs across the modeling period, with low-case assumptions modeling Argentine export licensing delays and high-case assumptions incorporating accelerated CORFO domestic manufacturing credit deployment. Segmentation dimensions modeled included electrolyte chemistry type, application sector, end-user contract structure, and regional production cluster regulatory framework. CAGRs were derived from installed base replacement cycles and auction mandate compliance deadlines, with electrolyte tooling lead times and qualification timeline compression serving as industry-specific forecast inputs.
Stress conditions across Argentine lithium carbonate export licensing volatility, Brazilian real currency fluctuation, and sulfide electrolyte moisture sensitivity equipment availability were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about ANEEL mandate enforcement consistency and EU-LAMEA Green Alliance certification timeline convergence. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Next-Generation Lithium Batteries Market
Lithium-ion Battery
Global Pin Type Lithium-Based Battery Market
Lithium-ion Battery
China Electric Vehicle Lithium-Ion Battery Separator Market
Lithium-ion Battery
Lithium Battery Wet Separator Market
Lithium-ion Battery
South America Electric Vehicle Battery Materials Market
Lithium-ion Battery
India Electric Vehicle Battery Materials Market
Lithium-ion Battery
Dual Carbon Battery Market
Lithium-ion Battery
United States Battery Cell Market
Lithium-ion Battery
Lithium Sulfur Dioxide Battery Market
Lithium-ion Battery
Global Lithium-Ion Battery Energy Storage System Market
Lithium-ion Battery
Thin Film Battery Market
Lithium-ion Battery
Global Lithium Mining Market
Lithium-ion Battery
EV SOLID State Battery Market
Lithium-ion Battery
Global Next Generation Batteries Market
Lithium-ion Battery
Bangladesh Lithium-Ion Battery Market
Lithium-ion Battery
Automotive Lithium-Ion Battery Cell Market