
 EV All-Solid-State Battery Market | 2026-2036
EV All-Solid-State Battery Market Size, Share, and Industry Trends Forecast 2026-2036
EV All-Solid-State Battery Market Insights
Japan is reconfiguring the competitive map for solid-state battery manufacturing through Toyota Motor Corporation's sustained investment in sulfide electrolyte production at its Teiho plant. QuantumScape Corporation leverages its proprietary ceramic separator architecture to anchor development timelines in the United States. Samsung SDI Co., Ltd. competes through aggressive Korean government-backed pilot line construction near Gumi.
An EV all-solid-state battery replaces flammable liquid electrolytes with ion-conducting solid materials such as sulfide, oxide, or halide compounds, achieving energy densities above 400 Wh/kg while eliminating thermal runaway risks in high-voltage automotive packs. Sulfide-based electrolytes currently dominate laboratory-scale development due to their room-temperature ionic conductivity rivaling liquid counterparts, though solid polymer formulations occupy nearer-term commercialization paths for lower-temperature applications. Pouch cell formats lead automotive prototyping programs, while thin-film architectures specialize in aerospace auxiliary power units where volume constraints override cost sensitivity.
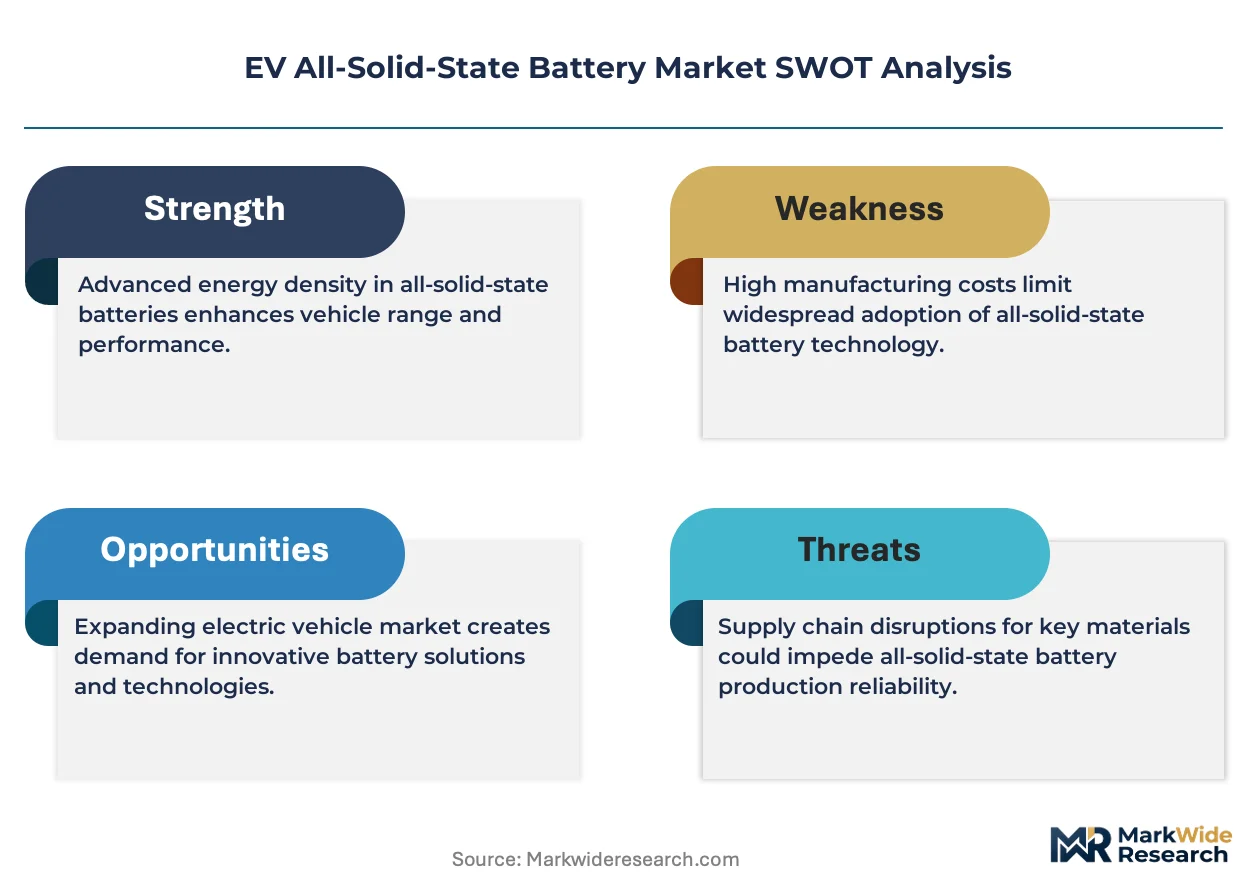
The US Department of Energy's Battery Manufacturing and Recycling Grants, Japan's METI Green Innovation Fund, and South Korea's K-Battery Development Strategy collectively shape demand by conditioning capital access on domestic content thresholds and energy density milestones. REACH compliance in Europe restricts sulfide electrolyte precursor chemistries, forcing reformulation investments for any market entry. Stakeholders must monitor which regulatory jurisdiction first certifies automotive-grade solid-state packs for mass production, as that approval will redirect supply chain investments and patent licensing flows across competing technology camps.
Market Dynamics
Automotive OEMs are consolidating pilot production partnerships around sulfide electrolyte architectures, forcing cathode suppliers and separator developers to co-locate manufacturing capacity near vehicle assembly hubs to meet qualification timelines.
Growth Catalysts
- Japan's METI Green Innovation Fund:Direct capital injection into domestic pilot lines accelerates sulfide electrolyte scale-up for 2028 vehicle integration targets.
- Energy density mandates:Automotive OEMs require 400+ Wh/kg pack specifications that only solid-state architectures can satisfy within current physics constraints.
- South Korea's K-Battery Development Strategy:Government-backed clustering near Gumi creates dedicated supply ecosystems for ceramic separator and halide precursor production.
Market Restraints
- Lithium metal anode cost volatility:Thin-film deposition yields below 60% at pilot scale inflate unit economics versus liquid lithium-ion benchmarks.
- REACH compliance friction:ECHA restrictions on phosphorous sulfide precursors force European entrants into costly reformulation cycles before market access.
- Technical limitation:Dendrite penetration through ceramic separators at fast-charge rates above 2C remains unresolved across all major electrolyte families.
Strategic Opportunities
- Underpenetrated aerospace auxiliary power:Thin-film solid-state cells command 5-10x automotive pricing due to volume-agnostic performance requirements.
- US IRA domestic content thresholds:Battery Manufacturing and Recycling Grants condition funding on North American electrolyte synthesis, creating first-mover advantages for localized sulfide production.
- Technology convergence:Silicon nanowire anodes paired with halide electrolytes enable 500 Wh/kg laboratory demonstrations that attract defense procurement interest.
Industry Challenges
- Materials science talent scarcity:Ion conductor synthesis expertise concentrates in Japanese and Korean national laboratories, constraining Western hiring pipelines.
- Automotive certification timelines:UN ECE R100 revision cycles for solid-state thermal propagation testing extend validation programs by 18-24 months versus liquid cell equivalents.
- IP licensing complexity:Overlapping patent estates covering oxide-garnet and sulfide-Li6PS5Cl compositions create royalty stacking risks for commercial entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | EV All-Solid-State Battery Market |
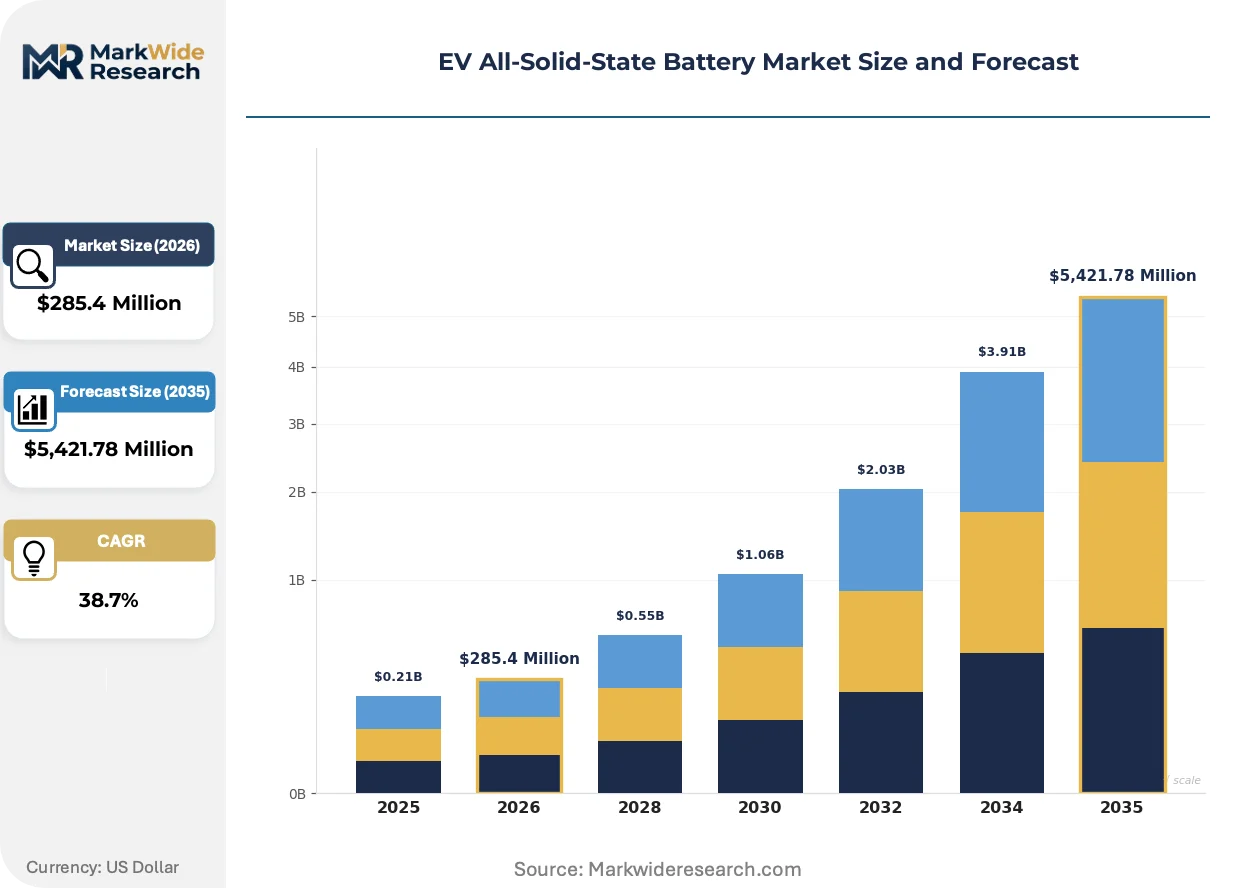
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $5,421.78 Million |
| CAGR (2026 – 2036) | 38.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thin-Film Batteries, 3D Batteries, Coin Cells, Pouch Cells Technology: Lithium Metal, Sulfur-Based, Solid Polymer, Inorganic Solid Electrolytes End User: Automotive Manufacturers, Aerospace Industries, Consumer Electronics, Energy Storage Systems Installation: Onboard Systems, Stationary Applications, Portable Devices, Industrial Equipment |
| Companies Covered | Solid Power, Inc., QuantumScape Corporation, Toyota Motor Corporation, ProLogium Technology Co., Ltd., Factorial Energy, Blue Solutions, Samsung SDI Co., Ltd., CATL, Ilika plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
EV All-Solid-State Battery Market Trends and Innovations
Electrolyte manufacturing is bifurcating into high-temperature sintering for oxide ceramics versus ambient-pressure compaction for sulfide glasses, with equipment suppliers retooling deposition lines to serve both process families.
Halide electrolyte formulations are virtualizing the competitive landscape for next-generation cells. These materials combine oxidative stability above 4V with mechanical compliance that oxide ceramics cannot match. Korean cathode suppliers are retrofitting coating lines for halide interface layers ahead of 2026 qualification deadlines. This chemistry is virtualizing the pathway to cobalt-free cathode integration by eliminating liquid electrolyte decomposition at high voltages.
REACH authorization requirements for sulfide precursors are forcing European material suppliers into joint development agreements with Asian electrolyte producers. The industrial consequence is a technology licensing flow from Japan and Korea toward German chemical conglomerates seeking compliant formulations. Battery cell manufacturers with European assembly plants are accelerating halide electrolyte programs to bypass sulfide regulatory exposure entirely.
Fleet procurement managers are consolidating supplier relationships around vertically integrated solid-state producers capable of delivering certified packs rather than raw cells. This behavior compresses the value chain by 1-2 intermediary tiers. The shift is most visible in German commercial vehicle electrification programs, where OEMs now require electrolyte-to-pack traceability for warranty coverage.
EV All-Solid-State Battery Market Segmentation
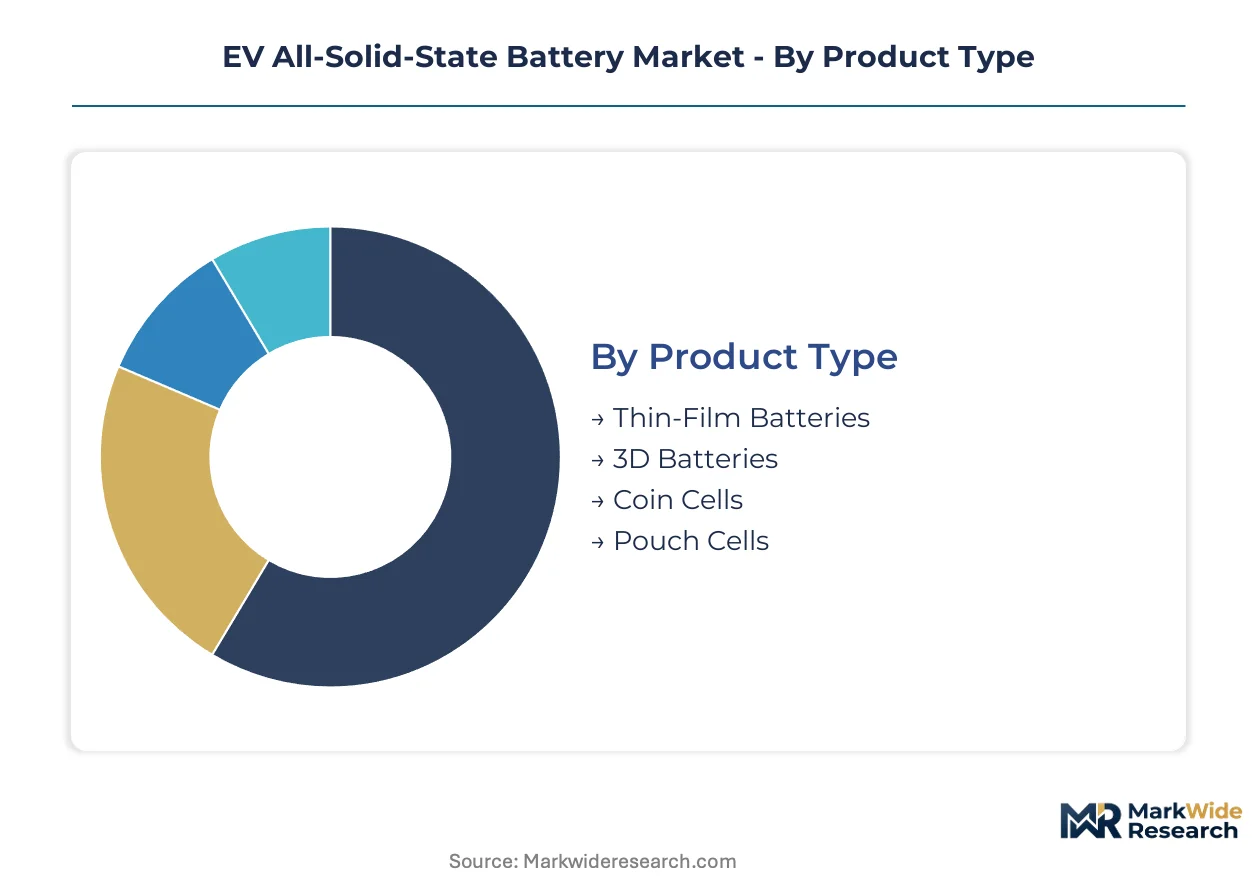
Segmentation in the EV all-solid-state battery market reveals distinct technical requirements across cell architectures, with after-sales service intensity varying dramatically between aerospace auxiliary power units and automotive traction packs. Understanding these structural differences enables suppliers to align warranty coverage, replacement protocols, and field engineering resources with each segment's failure modes and operational criticality.
Product Type:
After-sales service intensity peaks with pouch cell formats due to their direct integration into vehicle battery management systems requiring predictive maintenance algorithms and thermal monitoring infrastructure.
- Pouch Cells:Laminated aluminum-polymer housings enable flexible form factors that conform to vehicle chassis cavities. Automotive manufacturers in South Korea and Japan dominate procurement for 800V platform integration, driven by UN ECE R100 thermal propagation testing requirements that mandate cell-level traceability and replacement protocols.
- Thin-Film Batteries:Vacuum-deposited ceramic electrolytes achieve sub-millimeter thickness for aerospace auxiliary power applications. Demand concentrates with satellite and drone manufacturers where volume constraints override cost sensitivity, though limited cycle life necessitates frequent replacement schedules and specialized refurbishment services.
- 3D Batteries:Architectured electrodes with vertically aligned channels reduce ion diffusion path lengths. Solid-state startups in California and Massachusetts pilot these designs for defense procurement programs.
- Coin Cells:Standardized CR2032-compatible form factors serve as reference electrodes and diagnostic tools. Laboratory equipment suppliers in Germany and Switzerland constitute the primary demand base.
Pouch cells hold the largest share; momentum sits with thin-film architectures in aerospace applications.
Technology:
Cost tier stratification separates laboratory-scale sulfide development from near-commercial solid polymer systems, with capital intensity determining which electrolyte families attract automotive OEM partnerships versus niche electronics applications.
- Sulfide-Based:Li6PS5Cl and argyrodite compositions achieve room-temperature ionic conductivity exceeding 10 mS/cm. Toyota Motor Corporation's Teiho plant and Samsung SDI's Gumi pilot lines anchor production scaling in Japan and South Korea, constrained by moisture sensitivity that demands dry room infrastructure and specialized handling protocols.
- Lithium Metal:Anode architectures paired with ceramic or glassy electrolytes enable 400+ Wh/kg energy density. QuantumScape Corporation's proprietary separator technology dominates US development timelines, though dendrite penetration at fast-charge rates above 2C remains unresolved.
- Solid Polymer:Polyethylene oxide and polyacrylonitrile matrices operate at elevated temperatures with simpler manufacturing. European suppliers favor these formulations to bypass REACH restrictions on sulfide precursors.
- Inorganic Solid Electrolytes:Oxide-garnet LLZO and halide Li3YCl6 compositions balance oxidative stability with mechanical compliance. Korean cathode suppliers retrofit coating lines for halide interface layers ahead of qualification deadlines.
Sulfide-based systems command the deepest OEM partnerships; solid polymer offers the shortest path to commercial volume.
End User:
Application-specific performance requirements create divergent procurement patterns, with automotive qualification timelines stretching 18-24 months longer than consumer electronics acceptance criteria.
- Automotive Manufacturers:Battery electric vehicle platforms require 150+ kWh packs with 10-minute fast-charge capability. METI subsidies in Japan and K-Battery Development Strategy funding in South Korea condition capital access on domestic content thresholds and energy density milestones.
- Aerospace Industries:Auxiliary power units and satellite systems prioritize specific energy over cost. Thin-film solid-state cells command 5-10x automotive pricing due to volume-agnostic performance requirements and radiation hardness specifications.
- Consumer Electronics:Wearable devices and medical implants demand millimeter-scale form factors. Japanese component suppliers lead miniaturization efforts for hearing aids and continuous glucose monitors.
- Energy Storage Systems:Grid-scale installations require 20+ year operational life with minimal degradation. US Department of Energy grants target domestic electrolyte synthesis for utility-scale deployment.
Automotive manufacturers absorb the majority of pilot production capacity; aerospace applications generate the highest unit margins.
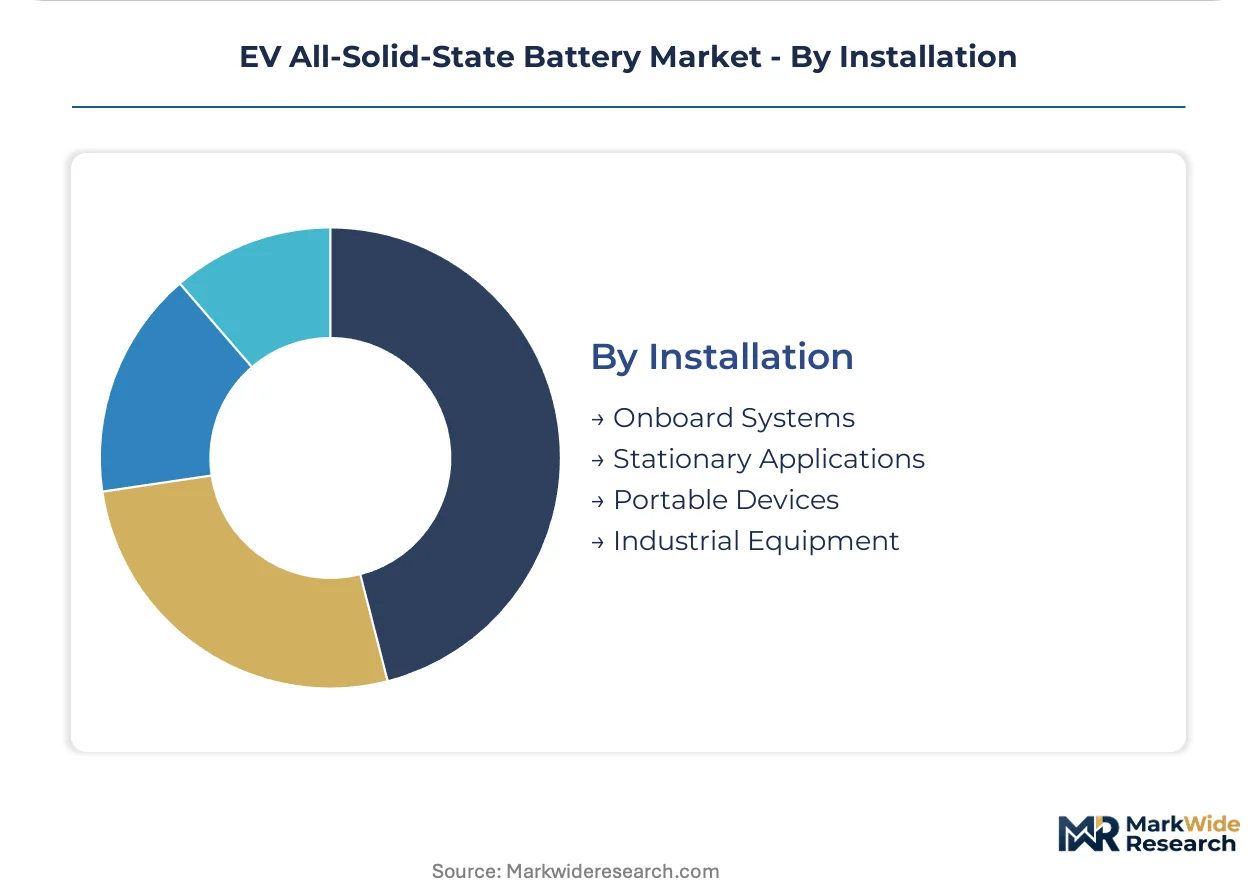
Installation:
Customer type differentiation separates fleet operators requiring electrolyte-to-pack traceability from portable device manufacturers focused on standardized cell interchangeability.
- Onboard Systems:Vehicle-integrated battery packs demand crashworthiness certification and thermal runaway containment. German commercial vehicle electrification programs now mandate full supply chain traceability for warranty coverage.
- Stationary Applications:Grid-connected storage and backup power systems prioritize calendar life over power density. Installations in California and Texas target IRA domestic content bonuses for North American cell assembly.
- Portable Devices:Field-replaceable units require standardized interfaces and simplified logistics. Medical device manufacturers in Switzerland and Minnesota specify solid-state alternatives to eliminate liquid electrolyte leakage risks.
- Industrial Equipment:Forklifts, mining vehicles, and port automation systems operate in extreme temperature environments. Solid-state architectures eliminate fire suppression system requirements in underground applications.
Onboard systems represent the dominant addressable market; stationary applications are climbing fastest as grid storage procurement accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan consumes solid-state batteries through automotive qualification pipelines, while South Korea deploys them via government-backed manufacturing clusters, and the United States channels demand through IRA-conditioned domestic content incentives.
United States
Automotive OEMs and aerospace contractors drive procurement through Department of Energy Battery Manufacturing and Recycling Grants. IRA domestic content thresholds condition federal funding on North American electrolyte synthesis. QuantumScape Corporation anchors development timelines in California, where ceramic separator pilot production targets defense and commercial vehicle integration.
Japan
Toyota Motor Corporation sustains the deepest sulfide electrolyte investment for 2028 vehicle integration targets. METI Green Innovation Fund capital injections accelerate pilot line scale-up at domestic plants. Teiho manufacturing complex near Toyota City concentrates moisture-sensitive sulfide glass production infrastructure.
South Korea
Samsung SDI and domestic cathode suppliers cluster near Gumi under K-Battery Development Strategy funding. Government-backed incentives condition capital access on energy density milestones and local content thresholds. Korean suppliers retrofit coating lines for halide interface layers ahead of qualification deadlines.
Germany
Commercial vehicle electrification programs mandate electrolyte-to-pack traceability for warranty coverage. REACH authorization requirements force material suppliers into joint development agreements with Asian producers. German chemical conglomerates seek compliant sulfide formulations through technology licensing from Japanese and Korean partners.
EV All-Solid-State Battery Market Competitive Landscape
Capability concentration sits with sulfide electrolyte specialists holding national laboratory partnerships; scale advantage sits with diversified battery manufacturers with existing cathode supply relationships. The structure remains bifurcated between vertically integrated automotive OEMs and independent cell developers seeking qualification partnerships. Two archetypes dominate: government-backed Asian conglomerates with pilot line infrastructure, and venture-funded Western specialists with ceramic separator IP. Competitive moves center on strategic partnerships for automotive qualification timelines and geographic licensing to bypass regulatory friction.
Within the government-backed tier, Toyota Motor Corporation and Samsung SDI Co., Ltd. exemplify state-coordinated scale strategies. QuantumScape Corporation occupies a position among venture-funded Western developers prioritizing ceramic separator architectures. These three entities represent divergent pathways to automotive certification: Japanese sulfide scale-up, Korean halide diversification, and US ceramic specialization.
| Leading Market Players |
|---|
| Solid Power, Inc. |
| QuantumScape Corporation |
| Toyota Motor Corporation |
| ProLogium Technology Co., Ltd. |
| Factorial Energy |
| Blue Solutions |
| Samsung SDI Co., Ltd. |
| CATL |
| Ilika plc |
| Others |
Pricing and Supply Chain Analysis
Moisture-sensitive sulfide precursor dependency concentrates pricing power among Japanese and Korean electrolyte producers, compressing tier spreads for automotive buyers while inflating premiums for REACH-compliant European formulations. This single-source vulnerability forces German chemical conglomerates into technology licensing arrangements that reshape both cost structures and geographic sourcing patterns.
Pricing Analysis
Automotive-grade solid-state cells in South Korea and Japan trade at substantial premiums to European equivalents due to dry room infrastructure costs and sulfide handling protocols. Pricing stratifies across automotive traction, aerospace auxiliary, and laboratory reference tiers, with certification grade and volume scale as primary differentiation drivers. Cost compression in the sulfide electrolyte tier is intensifying as pilot line yields improve and lithium metal anode deposition efficiency advances. Fleet procurement managers demonstrate highest price sensitivity, while satellite manufacturers accept 5-10x multiples for radiation-hardened thin-film architectures.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculations for ceramic separator precursor sourcing. Electrolyte synthesis concentrates in Japan, South Korea, and the United States, with sulfide glass production anchored in moisture-controlled facilities near Toyota City and Gumi. Raw material dependencies center on lithium metal foil, phosphorous sulfide precursors, and rare-earth halide salts. Distribution runs through vertically integrated OEM supply agreements rather than spot markets, with cathode suppliers retrofitting coating lines to co-locate with pilot production hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive solid-state battery procurement is consolidating around platform-standardized pack architectures, with interoperability between cell formats and battery management systems emerging as the decisive ecosystem battleground.
For Market Incumbents: Build captive sulfide electrolyte production capacity as the primary moat against emerging halide electrolyte challengers. Toyota Motor Corporation and Samsung SDI Co., Ltd. should accelerate backward integration into lithium metal anode deposition to offset yield volatility below 60% at pilot scale. Securing UN ECE R100 revision cycle pre-qualification creates channel control advantages that independent cell developers cannot replicate. For New Entrants and Emerging Players: Mid-market stationary storage applications in Texas and California represent the most penetrable entry point for halide electrolyte specialists seeking to bypass automotive certification timelines. Defense procurement programs for silicon nanowire anode architectures offer alternative qualification pathways with less stringent volume requirements. A go-to-market angle anchored on IRA domestic content threshold compliance enables access to Department of Energy Battery Manufacturing and Recycling Grants without competing directly for automotive platform slots. For Investors and Strategic Acquirers: First automotive-grade solid-state pack certification by NHTSA or Japan's Ministry of Land, Infrastructure, Transport and Tourism reshapes the acquisition landscape toward qualified producers with traceable supply chains. Long-term viability centers on electrolyte-to-pack vertical integration rather than component specialization. Acquisition targets should demonstrate pilot line operational status with named OEM partnerships. The signal to watch is regulatory approval timeline acceleration for sulfide versus halide electrolyte families.| Strategic Initiative | Industry Significance |
|---|---|
| Pilot Line Scale-Up | Domestic sulfide electrolyte production secures METI and K-Battery Strategy funding access. |
| Ceramic Separator IP Licensing | Proprietary separator architectures anchor US development timelines against Asian sulfide scale. |
| Halide Electrolyte Diversification | Oxidative stability above 4V enables cobalt-free cathode integration for Korean suppliers. |
| Automotive Platform Partnership | 800V integration mandates compress supplier tiers and consolidate procurement relationships. |
| REACH Compliance Reformulation | Joint development agreements with Asian producers unlock European market access for German chemical conglomerates. |
Research Methodology
Operator-level perspectives from solid-state battery pilot line engineers, automotive OEM platform integration leads, cathode supplier coating line managers, and electrolyte synthesis R&D directors anchored the qualitative base. These primary insights combined with secondary validation from SEC filings of listed battery developers, METI Green Innovation Fund disbursement records, US Department of Energy grant award databases, and UN ECE working party technical documentation. Bottom-up cell architecture demand modeling and top-down automotive electrification spending projections provided triangulation discipline.
Scenario-bracketing around sulfide yield improvement trajectories, halide electrolyte commercialization timelines, and regulatory certification sequence uncertainties shaped the analytical framework. Segmentation dimensions modeled include cell format, electrolyte chemistry family, end-use application intensity, and regional production cluster across the analysis window. CAGRs derived from electrolyte cost curve projections and automotive platform adoption curves, with specific inputs from lithium metal anode deposition efficiency trends and dry room capital cost deflation assumptions.
Practitioners should monitor pilot line yield breakthroughs, regulatory certification sequence announcements, and sulfide precursor trade flow disruptions for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Lithium Battery Pack Market
Lithium-ion Battery
Italy Electric Vehicle Battery Materials Market
Lithium-ion Battery
Cathode Material of Power Lithium Battery Market
Lithium-ion Battery
Lithium Sulfur Dioxide Battery Market
Lithium-ion Battery
Lithium-Ion Forklift Battery Market
Lithium-ion Battery
Nanobolt Lithium Tungsten Batteries Market
Lithium-ion Battery
Lithium-Ion Battery Packs Market
Lithium-ion Battery
Sodium-Ion Battery Market
Lithium-ion Battery
Dual Carbon Battery Market
Lithium-ion Battery
Power Lithium Battery Market
Lithium-ion Battery
Silicon Anode Lithium-Ion Battery Market
Lithium-ion Battery
Lithium-Ion Battery Cathode Material Market
Lithium-ion Battery
Bangladesh Lithium-Ion Battery Market
Lithium-ion Battery
Graphene Battery Technology Market
Lithium-ion Battery
South America Electric Vehicle Battery Electrolyte Market
Lithium-ion Battery
Liquid Lithium Ion Battery Market