
 Next-Generation Lithium Batteries Market | 2026-2036
Next-Generation Lithium Batteries Market Size, Share, and Industry Trends Forecast 2026-2036
Next-Generation Lithium Batteries Market Insights
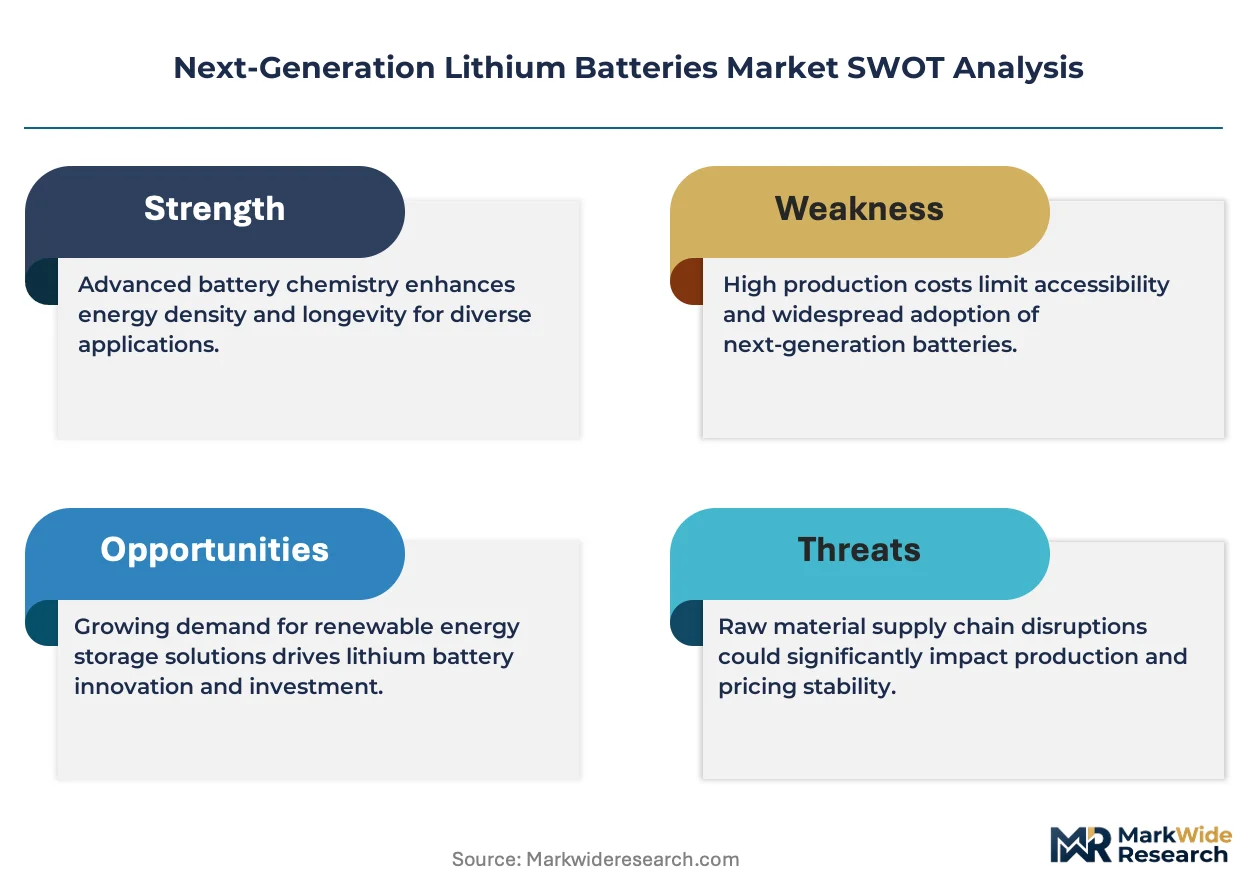
China's Jiangsu and Fujian provinces is fragmenting as CATL extends its vertical reach into lithium refining and cathode precursor production. Panasonic sustains its technology leadership through heavy R&D allocation toward silicon-anode integration. Samsung SDI competes by anchoring its European customer base with localized cell assembly in Hungary.
Next-generation lithium batteries encompass electrochemical storage devices that exceed conventional lithium-ion energy density thresholds through solid-state electrolytes, silicon-dominant anodes, or lithium-metal architectures, typically achieving above 300 Wh/kg at the cell level for automotive traction applications. Solid-state technology leads investment flows due to its promise of eliminating thermal runaway, while lithium-sulfur chemistries occupy niche aerospace and defense applications where gravimetric density outweighs cycle life constraints. Energy storage systems represent the fastest-growing end-user segment as grid operators seek longer-duration assets, though electric vehicles still dominate absolute cell offtake volumes.
The EU Battery Regulation mandates recycled content quotas and supply chain due diligence, compelling producers to reconfigure material flows. China's MIIT enforces GB standards on cell safety and energy density that filter export eligibility. The US IRA ties tax credits to North American assembly and critical mineral sourcing thresholds. Stakeholders must weigh regulatory compliance costs against access to subsidized demand pools when siting capacity and qualifying suppliers.
Market Dynamics
Automotive OEMs are forcing cathode and electrolyte suppliers to co-locate near European and North American cell plants, fragmenting the China-centric supply architecture that dominated the past decade.
Growth Catalysts
- EU Battery Regulation:Recycled content mandates and carbon footprint disclosure rules are compelling producers to reconfigure material flows toward certified green supply chains.
- Solid-state electrolytes:Elimination of thermal runaway risk is unlocking higher energy density ceilings for premium electric vehicle platforms.
- South Korean cathode clusters:Concentrated precursor and active material capacity in Gyeonggi and North Chungcheong provinces is shortening logistics loops for European cell makers.
Market Restraints
- Lithium carbonate volatility:Spot price swings exceeding 400% in 24-month windows are compressing margin visibility for cell producers locked into fixed automotive contracts.
- Single-source sulfide electrolytes:Japanese and Korean chemical firms control 90% of ceramic electrolyte precursor supply, creating chokepoint risk.
- Dendrite suppression:Lithium-metal anodes remain limited by uncontrollable filament growth during fast-charge cycles above 1C rates.
Strategic Opportunities
- India's PLI scheme:Cell manufacturing incentives targeting 50 GWh domestic capacity by 2030 are attracting cathode precursor joint ventures.
- Grid-scale energy storage:Four-hour and longer duration battery procurements by ISO New England and CAISO are opening silicon-anode applications beyond mobility.
- US IRA domestic content bonuses:Critical mineral and North American assembly thresholds are redirecting lithium hydroxide refining investments toward Quebec and Nevada.
Industry Challenges
- Solid-state dry electrode coating:Equipment capable of solvent-free cathode production at gigafactory scale remains limited to pilot-line throughput.
- UN 38.3 certification timelines:New chemistries face 18-24 month testing windows for air transport approval, delaying aerospace customer onboarding.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Next-Generation Lithium Batteries Market |
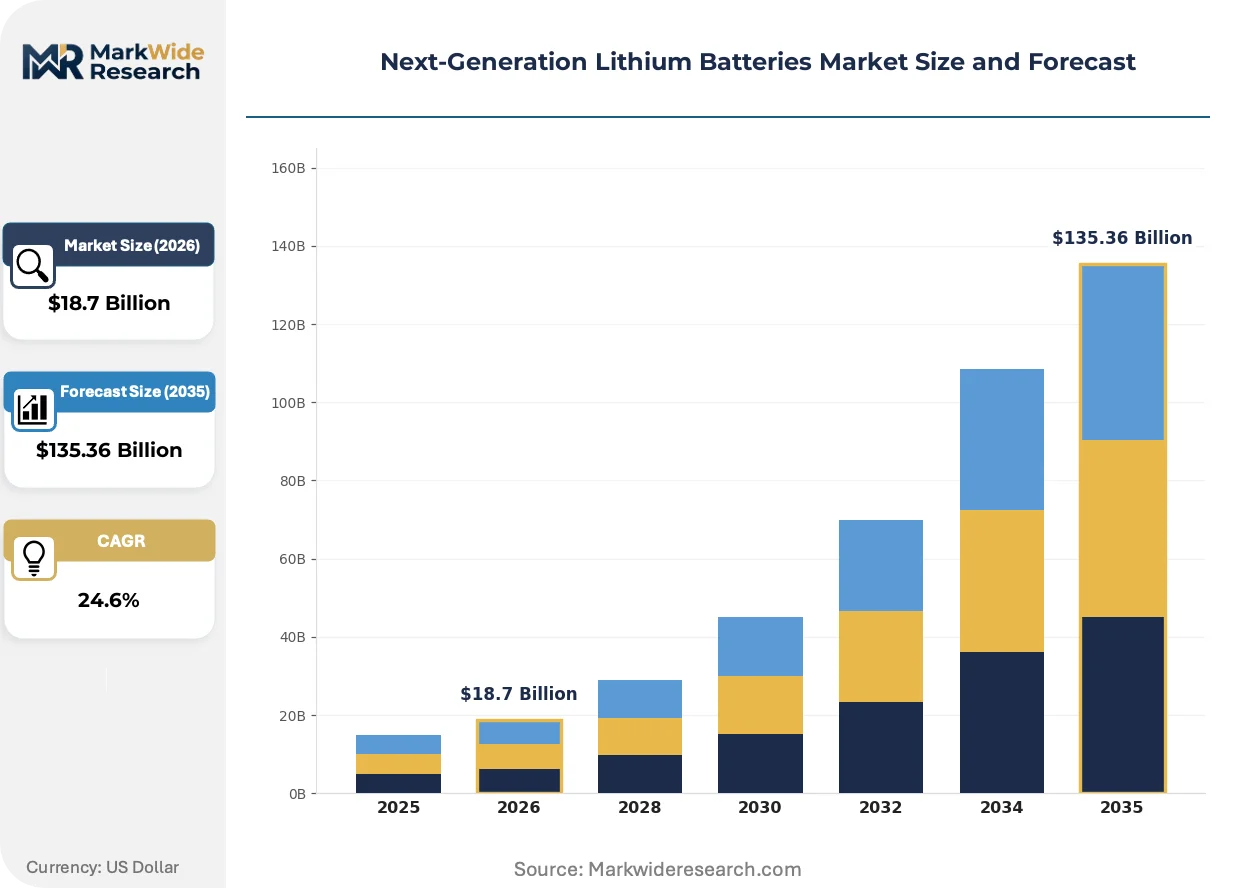
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $135.36 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LFP, NMC, NCA, Li-S End User: Electric Vehicles, Consumer Electronics, Energy Storage Systems, Industrial Equipment Technology: Solid-State, Liquid Electrolyte, Lithium-Ion, Flexible Batteries Application: Grid Storage, Automotive, Aerospace, Portable Electronics |
| Companies Covered | CATL, Panasonic, Samsung SDI, LG Chem, BYD, Sony, Tianjin Lishen, Hefei Guoxuan, Umicore, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Next-Generation Lithium Batteries Market Trends and Innovations
Electrode architectures and cell formats are diverging sharply between automotive traction and stationary storage applications, ending the era of interchangeable commodity cells.
Silicon-dominant anodes are migrating from cylindrical 2170 formats into prismatic and blade-style cells for automotive platforms. Korean cell makers are qualifying 15-20% silicon oxide blends for 2026 vehicle programs. This migration from graphite is compressing cobalt content requirements while demanding novel binder chemistries to accommodate 300% volume expansion during lithiation.
China's MIIT GB standards on cell safety and energy density are filtering export eligibility for domestic producers. Non-compliant manufacturers lose access to overseas markets regardless of price competitiveness. European importers are responding by demanding third-party GB certification documentation before contract execution.
Fleet operators and energy traders are consolidating procurement through long-term offtake agreements rather than spot purchases. Direct contracting between renewable developers and cell producers is displacing distributor intermediaries in utility-scale storage. This pattern is most visible in ERCOT and CAISO territories where merchant storage assets require decade-long revenue certainty.
Next-Generation Lithium Batteries Market Segmentation
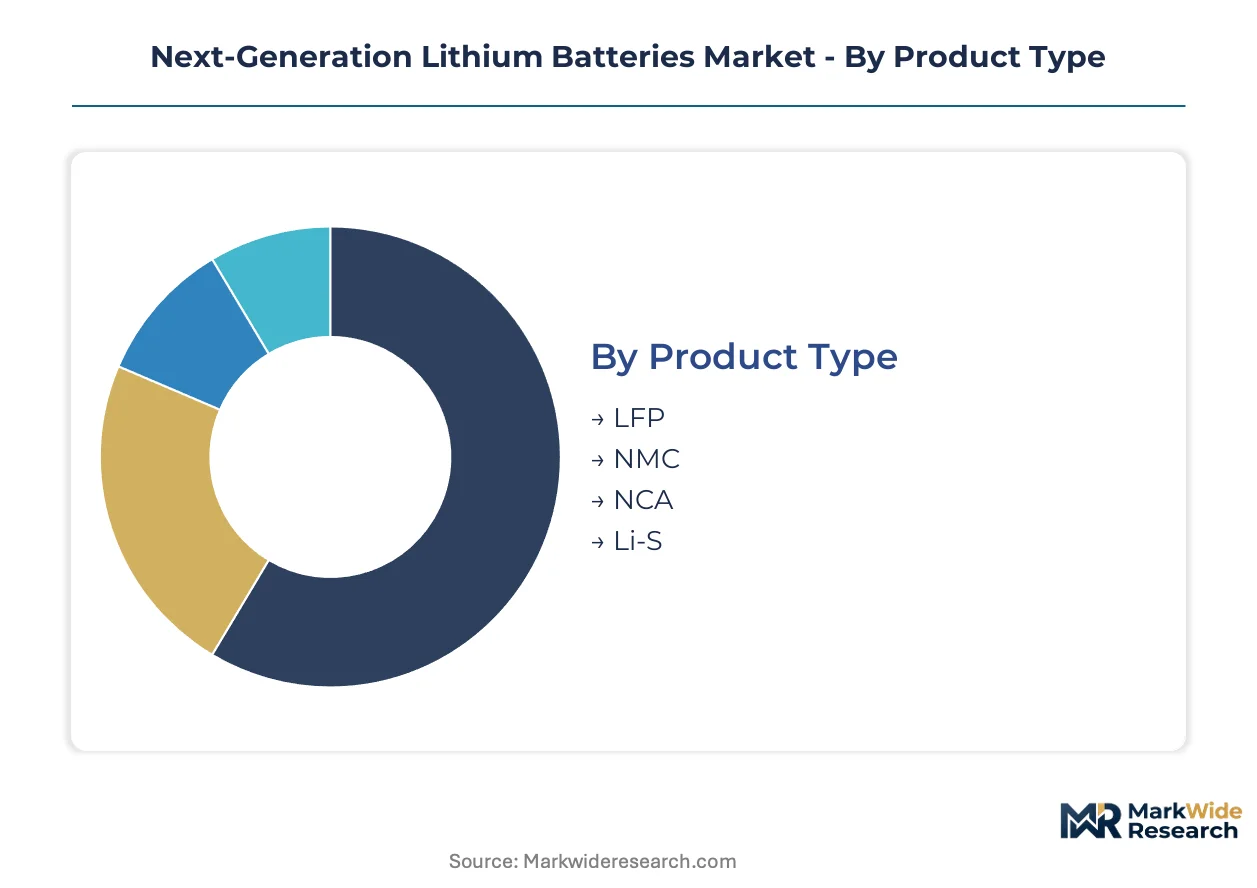
Next-generation lithium batteries fragment across electrochemical architectures, end-use requirements, and manufacturing maturity. Each segmentation dimension carries distinct margin profiles, certification pathways, and supply chain dependencies that dictate procurement strategy.
Product Type:
Mature cathode chemistries dominate installed capacity, while emerging formulations target energy density ceilings.
- LFP:Lithium iron phosphate cells deliver thermal stability and cycle life exceeding 4,000 cycles at the cost of lower energy density. Chinese producers in Hubei and Sichuan provinces supply the bulk of stationary storage installations across ERCOT and CAISO territories, driven by lithium carbonate price volatility that favors iron-based cathodes.
- NMC:Nickel-manganese-cobalt layered oxides achieve 250-300 Wh/kg cell-level density through elevated nickel content. Korean cathode clusters in Gyeonggi province feed European automotive cell plants, constrained by EU Battery Regulation recycled content mandates that complicate cobalt sourcing.
- NCA:Nickel-cobalt-aluminum cathodes maximize volumetric energy density for premium electric vehicle platforms.
- Li-S:Lithium-sulfur chemistries promise theoretical densities above 500 Wh/kg but remain limited by polysulfide shuttle degradation.
NMC handles the majority of throughput; Li-S is the fastest mover on share.
End User:
Volume concentration varies sharply between mobility-centric and stationary applications.
- Electric Vehicles:Automotive OEMs specify cell formats and thermal management systems that lock suppliers into decade-long qualification cycles. German gigafactory corridors in Saxony and Thuringia anchor European demand, with IRA domestic content bonuses redirecting some hydroxide refining toward Nevada and Quebec.
- Energy Storage Systems:Four-hour and longer duration procurements by ISO New England and CAISO are opening silicon-anode applications. Grid operators demand 20-year cycle warranties that favor LFP chemistries with proven degradation curves.
- Consumer Electronics:Smartphone and laptop manufacturers prioritize volumetric energy density and fast-charge capability over cycle life.
- Industrial Equipment:Forklift and material handling fleets in North American distribution centers are converting from lead-acid to lithium-ion traction batteries.
Electric Vehicles handles the majority of throughput; Energy Storage Systems is expanding most quickly.
Technology:
Manufacturing readiness separates near-term deployable platforms from laboratory-scale architectures.
- Solid-State:Ceramic and sulfide electrolytes eliminate flammable liquid components, enabling lithium-metal anodes with projected 400+ Wh/kg density. Japanese and Korean chemical firms control 90% of sulfide precursor supply, creating chokepoint risk for European cell makers.
- Liquid Electrolyte:Conventional carbonate-based electrolytes with graphite or silicon-blend anodes retain cost advantages and established supply chains. Chinese MIIT GB standards filter export eligibility, forcing non-compliant manufacturers to retool or abandon overseas markets.
- Lithium-Ion:Traditional intercalation chemistries with liquid electrolytes dominate current manufacturing capacity.
- Flexible Batteries:Thin-film and printed cell architectures target wearable and medical device applications requiring mechanical compliance.
Liquid Electrolyte handles the majority of throughput; Solid-State is climbing the fastest.
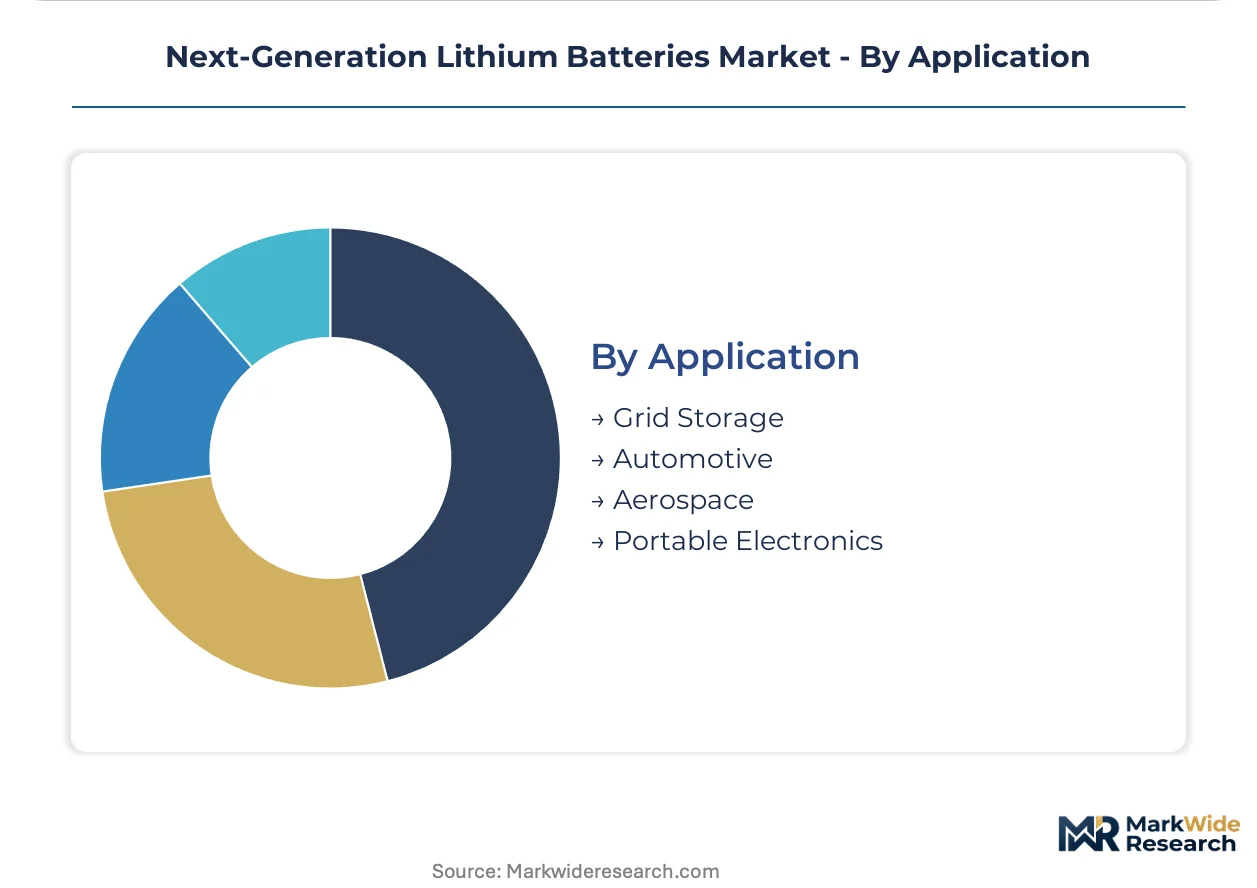
Application:
Performance requirements diverge between stationary assets and mobile platforms.
- Automotive:Traction batteries must survive vibration, thermal cycling, and crash scenarios while delivering 150-300 kW discharge rates. South Korean cell makers are qualifying 15-20% silicon oxide anode blends for 2026 vehicle programs, compressing cobalt content while demanding novel binder chemistries.
- Grid Storage:Utility-scale installations prioritize capital cost per MWh and calendar life over gravimetric density. India's PLI scheme targeting 50 GWh domestic capacity by 2030 is attracting cathode precursor joint ventures for this segment.
- Aerospace:Satellites and electric aircraft demand maximum energy density with minimal mass penalty, accepting shorter cycle life.
- Portable Electronics:Smartphones and laptops require form-factor flexibility and rapid charge acceptance.
Automotive handles the majority of throughput; Grid Storage is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT's GB standards on cell safety and energy density are filtering export eligibility, compelling producers across China, South Korea, and Germany to reconfigure qualification protocols for overseas market access.
China
Jiangsu and Fujian provinces host the dominant cathode precursor and cell manufacturing clusters, with CATL extending backward integration into lithium refining. MIIT enforces GB standards that filter export eligibility, forcing non-compliant manufacturers to retool or abandon overseas markets. Hubei and Sichuan provinces supply the bulk of LFP cells for stationary storage installations.
South Korea
Gyeonggi and North Chungcheong provinces concentrate cathode active material capacity, shortening logistics loops for European cell makers. The MFDS oversees industrial chemical safety compliance for electrolyte formulations. Samsung SDI anchors its European customer base with localized cell assembly in Hungary, bypassing EU import tariffs.
Germany
Saxony and Thuringia anchor the European gigafactory corridor, with automotive OEMs demanding co-located cathode and electrolyte suppliers. The EU Battery Regulation mandates recycled content quotas and carbon footprint disclosure, compelling producers to reconfigure material flows. KBA certification requirements govern cell safety for domestic vehicle integration.
United States
Nevada and Quebec are attracting lithium hydroxide refining investments to satisfy IRA domestic content bonuses for critical mineral sourcing. FERC regulates grid interconnection standards for utility-scale storage deployments. ERCOT and CAISO territories drive four-hour and longer duration battery procurements, opening silicon-anode applications.
India
Maharashtra and Gujarat are emerging as cell manufacturing hubs under the PLI scheme targeting 50 GWh domestic capacity by 2030. The CEA sets technical standards for grid-connected storage systems. Tamil Nadu and Karnataka are attracting cathode precursor joint ventures for grid-scale energy storage segments.
Next-Generation Lithium Batteries Market Competitive Landscape
Vertically integrated conglomerates and specialized cell manufacturers split the market between scale-driven cost optimization and technology-focused performance differentiation. The vendor base concentrates around three strategic archetypes: diversified chemical conglomerates with captive material supply, pure-play battery specialists with automotive qualification depth, and diversified industrials with cross-sector energy storage exposure. Dominant competitive moves include backward integration into lithium refining and cathode precursor production, plus geographic expansion through localized cell assembly in target demand markets.
Among Asia-Pacific-based producers, CATL, Panasonic, and Samsung SDI occupy positions that exemplify the three archetypal strategies. CATL represents the vertically integrated conglomerate model with upstream control over refining and precursor production. Panasonic anchors the technology-specialist tier through sustained R&D allocation toward advanced anode integration. Samsung SDI exemplifies the regional-expansion approach with European manufacturing presence.
| Leading Market Players |
|---|
| CATL |
| Panasonic |
| Samsung SDI |
| LG Chem |
| BYD |
| Sony |
| Tianjin Lishen |
| Hefei Guoxuan |
| Umicore |
| Others |
Pricing and Supply Chain Analysis
The Shanghai-Rotterdam maritime corridor carries sulfide electrolyte precursors and cathode active materials whose freight cost volatility feeds directly into European cell producers' margin structures, amplifying price spreads between Asia-sourced and locally qualified supply tiers.
Pricing Analysis
Geographic price spreads between South Korean cathode supply and European domestic alternatives exceed transport-cost differentials alone, reflecting GB certification premiums and IRA domestic content bonuses. Contract-based long-term offtake agreements dominate automotive procurement, while spot purchases persist in stationary storage. Price differentiation rests on certification grade and volume scale, with EU Battery Regulation compliance commanding premiums. Cost compression in standard-grade LFP cells is intensifying because Chinese overcapacity spills into export markets. Utility-scale developers exhibit highest price sensitivity; premium EV platforms show lowest.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates strategic planning for cathode precursor procurement. Supply concentrates in China, South Korea, and Japan, with Japanese and Korean chemical firms controlling ceramic electrolyte precursor production. The chain draws from lithium hydroxide, nickel sulfate, and sulfide electrolyte inputs. Single-source vulnerability in sulfide electrolytes creates chokepoint risk for solid-state cell makers. Distribution runs through direct OEM contracts and long-term offtake agreements with renewable developers, displacing distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment through EU Battery Regulation certification and IRA domestic content qualification creates structural barriers that compound with each qualification cycle.
For Market Incumbents: Build regulatory moats by securing EU Battery Regulation carbon footprint certification and GB standards compliance ahead of export eligibility deadlines. Expand captive lithium hydroxide refining in Quebec and Nevada to capture IRA domestic content bonuses. Deepen backward integration into cathode precursor production to offset sulfide electrolyte single-source vulnerability from Japanese and Korean chemical suppliers.
For New Entrants and Emerging Players: Pursue India's PLI scheme cell manufacturing incentives targeting grid-scale energy storage, where qualification cycles remain shorter than automotive traction applications. Target silicon-anode binder chemistry specialization as automotive OEMs qualify 15-20% silicon oxide blends. Establish joint ventures with Tamil Nadu and Karnataka cathode precursor producers to secure raw material offtake.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors solid-state electrolyte specialists with sulfide precursor supply relationships or dry electrode coating equipment capabilities. Long-term viability hinges on navigating the transition from liquid electrolyte dominance toward ceramic and sulfide architectures without stranded conventional capacity. Watch for UN 38.3 certification timeline compression as an inflection signal for aerospace and defense lithium-sulfur adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lithium Refining | Captures IRA domestic content bonuses for Nevada and Quebec hydroxide production. |
| Solid-State Electrolyte Scale-Up | Eliminates thermal runaway risk for premium European EV platforms. |
| GB Standards Certification Investment | Secures China export eligibility under MIIT enforcement. |
| Silicon-Anode Binder Chemistry Development | Addresses 300% volume expansion in Korean cell makers' 2026 vehicle programs. |
| Long-Term Supply Agreement with Grid Operators | Locks in ERCOT and CAISO four-hour duration procurement demand. |
Research Methodology
Cross-validation between cell producer procurement executives and cathode active material supplier technical directors anchors the qualitative findings. Primary interviews with OEM platform engineers, utility storage procurement officers, sulfide electrolyte chemical specialists, and EU regulatory compliance consultants combine with secondary validation from MIIT GB standard filings, EU Battery Regulation delegated acts, SEC 10-K supply chain disclosures, and FERC interconnection queue data. Bottom-up cell production capacity builds and top-down automotive demand projections triangulate market sizing.
Calibration against historical capacity utilization rates and announced gigafactory ramp schedules shapes the projection framework. Segmentation dimensions span electrochemical architecture, end-use application, technology readiness tier, and regional regulatory cluster. CAGRs derive from fitted growth curves applied to qualified capacity announcements and automotive platform launch timelines. Forecast inputs include solid-state electrolyte yield improvement trajectories and silicon-anode cycle life degradation models.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese state-backed producers or sulfide electrolyte supply cartels would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Consumer Lithium-Ion Battery Market
Lithium-ion Battery
Thin Film Lithium-Ion Battery Market
Lithium-ion Battery
Lithium-Ion Battery Rechargeable Hearing Aids Market
Lithium-ion Battery
Lithium Cobalt Oxide Market
Lithium-ion Battery
High Temperature Lithium Battery Market
Lithium-ion Battery
Automotive Lithium Ion Battery Market
Lithium-ion Battery
Pouch Lithium-Ion Batteries Market
Lithium-ion Battery
Lithium Battery in Myanmar Market
Lithium-ion Battery
Next Generation Advanced Battery Market
Lithium-ion Battery
Global Nanowire Battery Market
Lithium-ion Battery
Li Metal Battery Market
Lithium-ion Battery
Nanotechnology Enabled Battery Market
Lithium-ion Battery
France Electric Vehicle Battery Electrolyte Market
Lithium-ion Battery
EV All-Solid-State Battery Market
Lithium-ion Battery
Anode Material for Sodium-Ion Battery Market
Lithium-ion Battery
Southeast Asia Lithium-Ion Battery Market