
 Graphene Battery Technology Market | 2026-2036
Graphene Battery Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Graphene Battery Technology Market Insights
China is rewriting the competitive map for graphene battery manufacturing through massive electrode material foundries and state-backed pilot lines. Samsung SDI leverages its Korean cathode supply chain to sustain high-purity graphene dispersion for automotive cells. Nanotech Energy dominates the U.S. West Coast with proprietary organic electrolyte formulations that reduce flammability risks in flexible battery architectures.
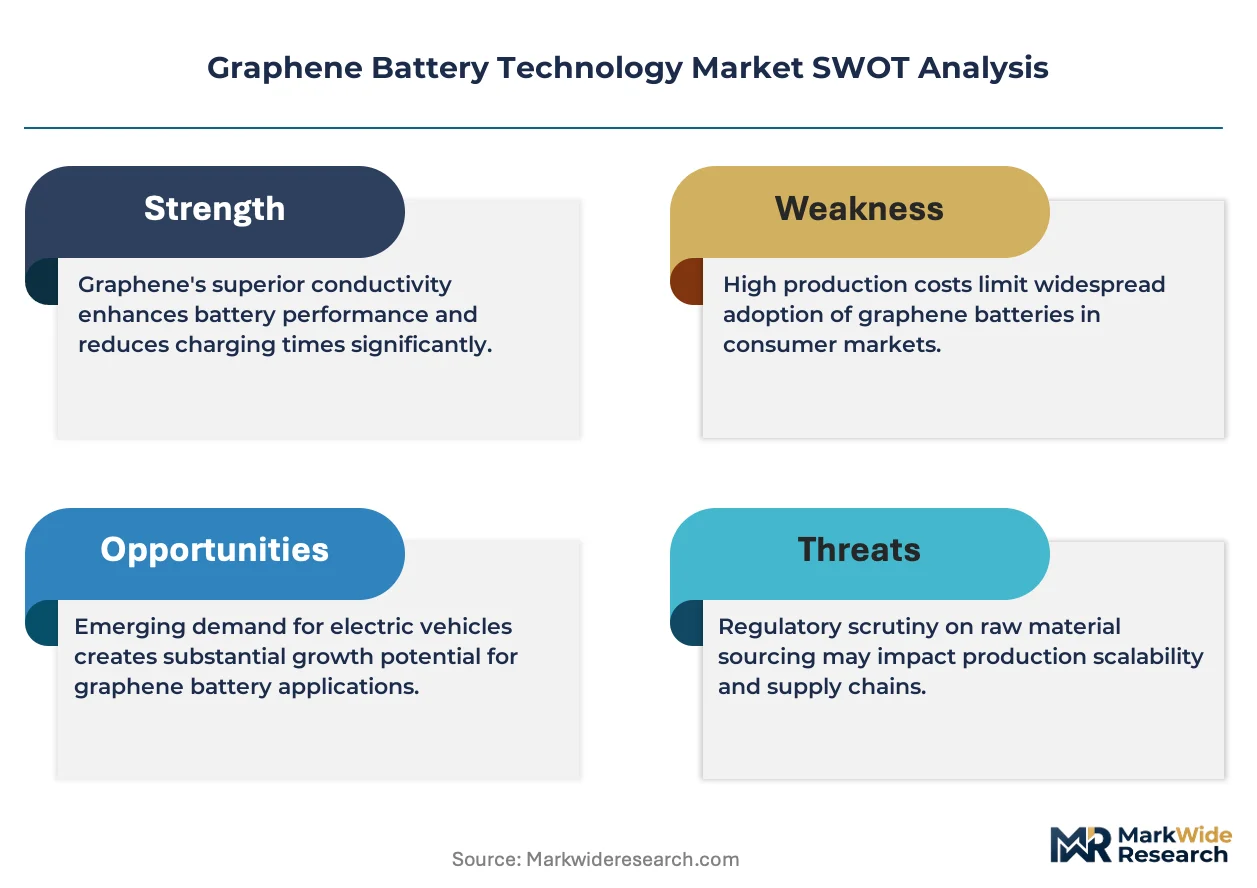
Graphene battery technology integrates single-atom-thick carbon lattices into conventional or solid-state cell designs to achieve conductivity above 10,000 S/m and charge rates five to ten times faster than graphite anodes, primarily serving applications where weight reduction and cycle durability outweigh lithium-ion cost advantages. Solid-state batteries command the steepest R&D allocation because their ceramic-graphene composite electrolytes promise simultaneous energy density gains and thermal runaway suppression. Electric vehicles anchor the largest end-user revenue pool, though wearable tech segments generate superior margins per watt-hour due to premium pricing for ultrathin form factors.
China's MIIT enforces GB standards for battery energy density and recycling traceability that filter out low-grade graphene suppliers from automotive qualification lists. The EU's REACH and RoHS frameworks restrict hazardous precursor chemicals in European-manufactured cells, pushing Grabat Graphenano Energy and Cabot Corporation toward aqueous synthesis routes. Stakeholders must track how evolving solid-state patent thickets and national critical-mineral security policies reshape licensing costs and anode material sourcing geography.
Market Dynamics
Automotive certification mandates from China's MIIT and South Korea's MFDS are compressing qualification timelines for graphene-enhanced cells, forcing electrode suppliers to accelerate purity validation while OEMs consolidate procurement around pre-certified material streams.
Growth Catalysts
- MIIT Energy Density Benchmarks:China's revised GB standards for automotive cells mandate minimum thresholds that only graphene-doped anodes reliably achieve, filtering supplier pools toward high-purity dispersion specialists.
- Solid-State Ceramic Electrolyte Convergence:Aerospace contractors in Germany and the United States are drawing R&D investment toward thermal-stable graphene-ceramic composites for satellite and drone power systems.
- Flexible Wearable Form Factors:Ultrathin graphene cells enable medical patch and fitness band architectures where lithium-ion thickness constraints exclude conventional designs.
Market Restraints
- High-Purity Graphite Feedstock Volatility:Battery-grade flake graphite from Mozambique and Madagascar faces export licensing delays that propagate through graphene oxide precursor costs.
- East Asian Cathode Concentration:Over 70% of graphene dispersion capacity clusters in South Korean and Chinese electrode foundries, creating single-source vulnerability for European and North American cell assemblers.
- Scalable Defect-Free Synthesis Limits:Chemical vapor deposition yields for single-layer graphene remain below industrial thresholds, constraining anode coating uniformity at automotive scale.
Strategic Opportunities
- Indian PLI Scheme for Advanced Chemistry Cells:Production-linked incentives for domestic battery manufacturing create localized graphene electrode demand outside East Asian supply chains.
- EU Battery Regulation Traceability Mandates:Digital passport requirements for carbon footprint disclosure favor graphene suppliers with aqueous synthesis routes that bypass REACH-restricted precursors.
- AI-Accelerated Materials Discovery:Machine learning platforms for electrolyte formulation are compressing R&D cycles for solid-state graphene cell architectures.
Industry Challenges
- Interfacial Engineering Talent Scarcity:The specialized skill set for graphene-electrolyte interface optimization remains concentrated in academic clusters, constraining manufacturing scale-up.
- Automotive Qualification Timeline Compression:OEMs demand 18-month cell validation cycles that conflict with graphene anode aging studies requiring 24-plus months of cycle-life data.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Graphene Battery Technology Market |
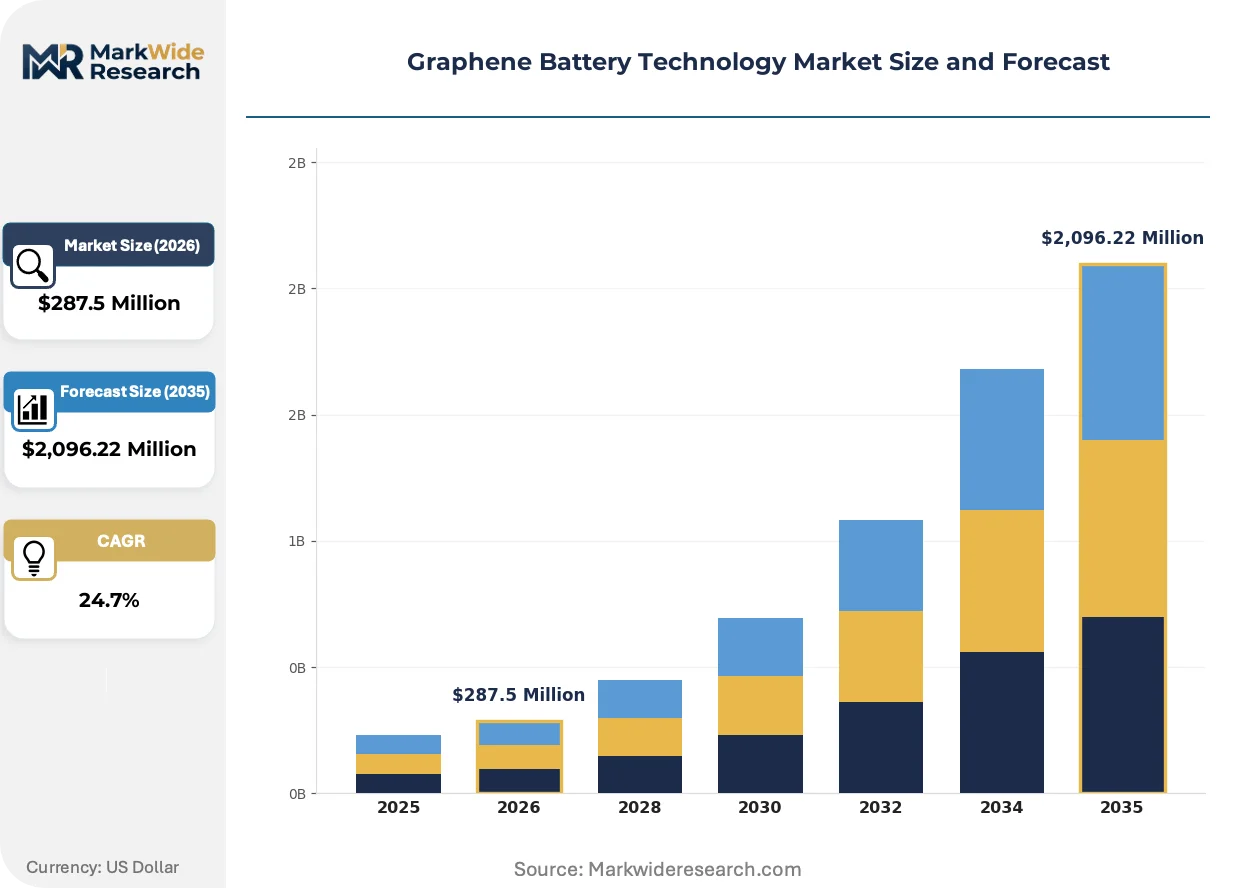
| Market Size in 2026 | $287.5 Million |
| Market Size in 2035 | $2,096.22 Million |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Batteries, Solid-State Batteries, Supercapacitors, Hybrid Batteries End User: Consumer Electronics, Automotive OEMs, Renewable Energy, Aerospace Technology: Energy Storage, Fast Charging, Lightweight Applications, Thermal Management Application: Electric Vehicles, Portable Devices, Grid Storage, Wearable Tech |
| Companies Covered | Nanotech Energy, Huawei Technologies Co., Ltd., Samsung SDI, Cabot Corporation, Log 9 Materials Scientific Private Limited, Grabat Graphenano Energy, XG Sciences, Inc., Global Graphene Group, Nanotek Instruments, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Graphene Battery Technology Market Trends and Innovations
Research frontiers are converging on solid-state architectures where graphene functions as both conductive scaffold and mechanical buffer, while regulatory frameworks harden around carbon accounting and material traceability that reshape competitive positioning.
Silicon-graphene composite anodes are collapsing the energy density penalty that previously constrained silicon expansion in automotive cells. Cell developers at German research clusters and U.S. national laboratories are integrating these materials into prototype 4680 formats. The structural consequence is compressing cobalt content requirements while extending cycle life targets beyond 1,500 charge events.
REACH authorization processes for N-methyl-2-pyrrolidone solvents are tightening precursor chemical access across European manufacturing zones. ECHA's sunset date evaluations for reproductive toxicants are forcing Grabat Graphenano Energy and Cabot Corporation toward water-based exfoliation routes. Aqueous synthesis adopters in Spain and Germany are securing preferred supplier status with automotive OEMs subject to CSRD supply chain disclosure rules.
Buyer consolidation among Chinese electric vehicle manufacturers is compressing supplier negotiation leverage for graphene electrode vendors. BYD and CATL procurement teams are mandating multi-year fixed-price contracts that transfer flake graphite volatility risk upstream. The pattern is most visible in Shenzhen and Ningbo battery industrial parks where tier-one cell assemblers now require foundry-equity stakes from material partners.
Graphene Battery Technology Market Segmentation
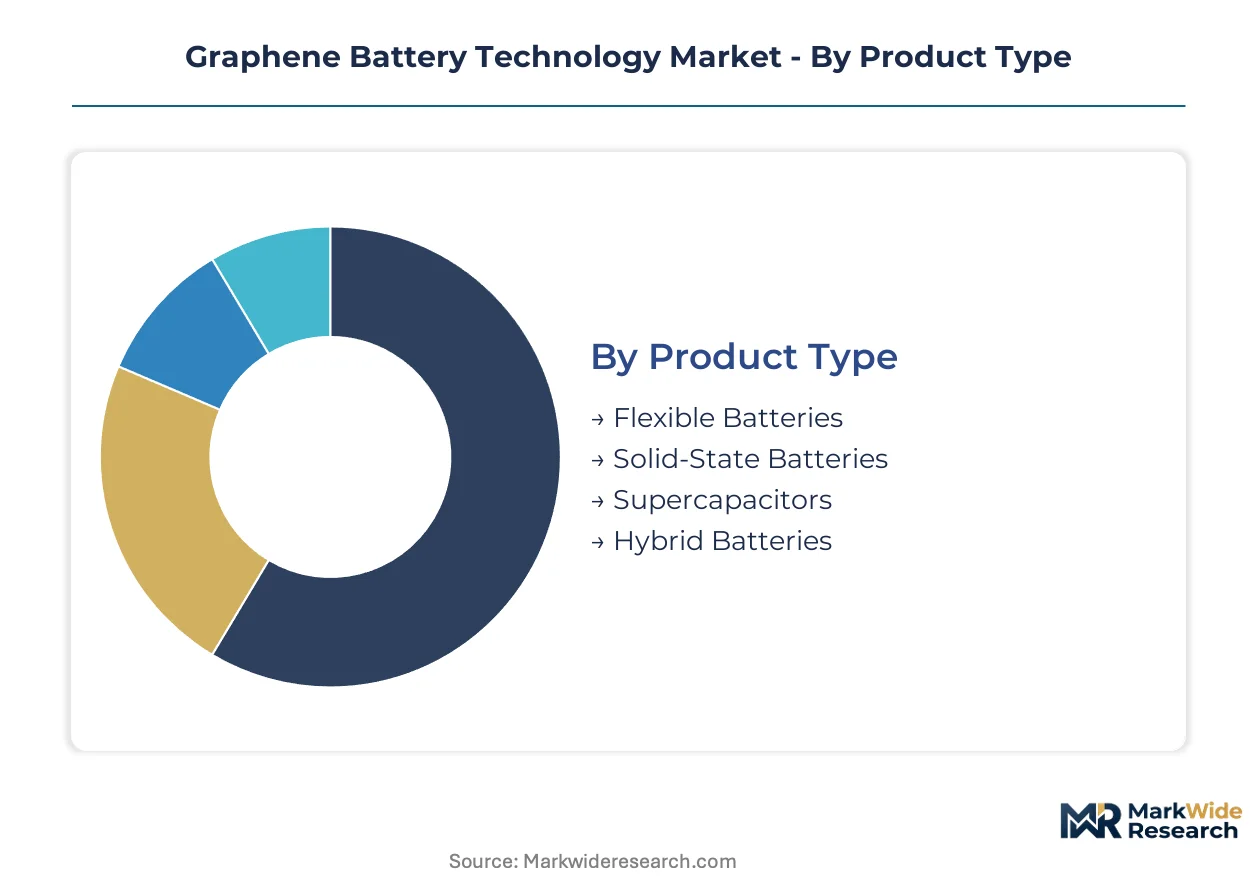
Segmentation in graphene battery technology separates architectures by electrochemical design, end-use performance thresholds, and integration complexity. Each dimension carries distinct purity requirements, qualification timelines, and margin structures that reshape supplier positioning.
Product Type:
Cost tier determines graphene layer count, substrate material, and manufacturing yield, with premium architectures commanding specialized synthesis equipment and cleanroom protocols.
- Solid-State Batteries:Ceramic-graphene composite electrolytes eliminate liquid flammability risks while enabling energy density above conventional lithium-ion. Aerospace contractors in Germany and the United States are consolidating procurement around these thermal-stable architectures for satellite power systems.
- Flexible Batteries:Ultrathin graphene anodes deposited on polymer substrates enable bend radii below 5mm for wearable form factors. Medical patch manufacturers and fitness band assemblers in Shenzhen and Seoul are scaling orders as MIIT and MFDS certification pathways mature for skin-contact power systems.
- Supercapacitors:High-surface-area graphene electrodes deliver charge rates exceeding 10,000 cycles with minimal degradation.
- Hybrid Batteries:Dual-architecture cells combining graphene anodes with conventional cathodes bridge cost-performance gaps.
Solid-state batteries command the established base. The steepest expansion runs through flexible batteries.
End User:
Application context dictates qualification stringency, with mobility and medical segments imposing the most demanding cycle-life and safety documentation.
- Automotive OEMs:4680-format cylindrical cells with silicon-graphene composite anodes are collapsing cobalt dependencies while extending cycle targets beyond 1,500 events. BYD and CATL procurement teams in China are mandating multi-year fixed-price contracts that transfer flake graphite volatility risk upstream to electrode foundries.
- Consumer Electronics:Smartphone and laptop manufacturers prioritize charge rate over absolute energy density. Korean and Chinese battery industrial parks are scaling graphene-doped fast-charge cells for flagship device launches.
- Renewable Energy:Grid-scale installations require decade-plus cycle warranties that strain current graphene anode aging data availability.
- Aerospace:Satellite and drone power systems demand thermal runaway suppression across temperature extremes from launch vibration to orbital thermal cycling.
Automotive OEMs anchor the revenue base. Aerospace is climbing the fastest as solid-state qualification timelines compress.
Technology:
Functional specialization separates segments by which performance vector graphene enhances—conductivity, kinetics, mass reduction, or thermal stability.
- Fast Charging:Graphene's electron mobility above 10,000 S/m enables charge rates five to ten times faster than graphite anodes. Electric vehicle manufacturers in China are deploying these cells in premium sedan lines where 10-minute charge targets are non-negotiable.
- Thermal Management:Single-atom-thick carbon lattices function as heat spreaders, suppressing localized hot spots during high-rate discharge. Aerospace battery pack designers in Germany are integrating graphene-ceramic composites for satellite power systems.
- Energy Storage:Maximizing watt-hour density through graphene-enabled cathode loading.
- Lightweight Applications:Mass reduction for aviation and portable defense systems where gram-level savings compound.
Energy storage commands the established base. Fast charging is gaining share fastest as automotive OEMs compress charge window specifications.
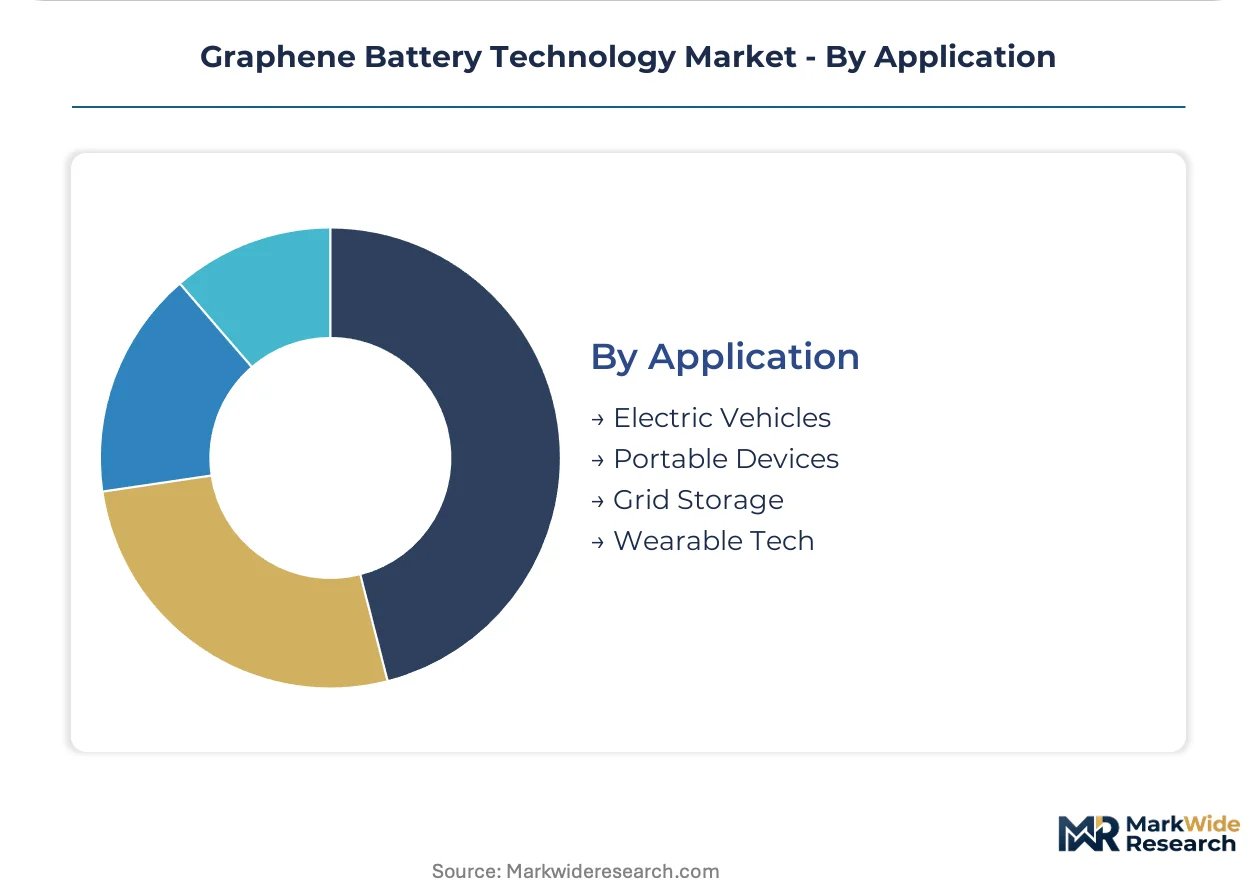
Application:
Integration environment shapes form factor constraints, from cylindrical automotive packs to ultrathin wearable laminates.
- Electric Vehicles:Prismatic and cylindrical cells with graphene-enhanced anodes are penetrating premium sedan and SUV lines where energy density benchmarks filter out conventional graphite. NMPA and MIIT certification mandates are compressing supplier qualification timelines toward 18-month cycles.
- Wearable Tech:Medical patches and fitness bands require sub-millimeter thickness that excludes conventional lithium-ion. Nanotech Energy's organic electrolyte formulations on the U.S. West Coast are reducing flammability risks in these skin-adjacent architectures.
- Portable Devices:Smartphone and tablet power cells balance charge rate with volumetric constraints.
- Grid Storage:Utility-scale installations prioritize capital cost per megawatt-hour over premium graphene performance.
Electric vehicles anchor the established base. Wearable tech is expanding most quickly as medical device certification pathways mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electrode foundry capacity clusters in East Asian industrial corridors, with Chinese and South Korean cathode supply chains absorbing over seventy percent of global graphene dispersion output. European and North American cell assemblers face single-source vulnerability as certification mandates compress qualification timelines.
China
BYD and CATL procurement teams in Shenzhen and Ningbo are mandating multi-year fixed-price contracts that transfer flake graphite volatility risk upstream to electrode foundries. MIIT enforces revised GB standards for automotive cell energy density that filter supplier pools toward high-purity dispersion specialists. Battery industrial parks in Shenzhen and Ningbo now require foundry-equity stakes from material partners.
South Korea
Samsung SDI leverages domestic cathode supply chains to sustain high-purity graphene dispersion for automotive cells targeting premium sedan lines. MFDS certification mandates compress supplier qualification timelines toward eighteen-month cycles. Electrode foundries in the Seoul Capital Area are scaling fast-charge cell output for flagship consumer electronics launches.
Germany
Solid-state battery research clusters in Bavaria and Baden-Württemberg are drawing concentrated demand from aerospace contractors seeking thermal-stable power systems for satellite applications. ECHA REACH authorization processes for N-methyl-2-pyrrolidone solvents are forcing aqueous synthesis adoption among domestic suppliers. Research consortia in Stuttgart and Munich are integrating silicon-graphene composite anodes into prototype 4680 formats.
United States
Nanotech Energy dominates the West Coast with proprietary organic electrolyte formulations that reduce flammability risks in flexible battery architectures for medical patches and fitness bands. FAA and Department of Defense procurement specifications for drone power systems are accelerating thermal management requirements. National laboratories in California and Massachusetts are compressing R&D cycles for solid-state graphene cell architectures through machine learning platforms.
India
Production-linked incentive schemes for advanced chemistry cell manufacturing are creating localized graphene electrode demand outside East Asian supply chains. BIS standards for battery energy density and recycling traceability are filtering qualification lists toward high-purity suppliers. Industrial corridors in Gujarat and Tamil Nadu are attracting electrode foundry investments as domestic electric vehicle assembly scales.
Graphene Battery Technology Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in electrode materials and dispersion chemistry. The vendor base separates into three functional layers: automotive cell assemblers with captive foundry relationships, independent electrode material suppliers, and graphene precursor specialists. Competitive dynamics revolve around foundry-equity requirements from Chinese OEMs and aqueous synthesis patent positioning for European regulatory compliance. Technology licensing and backward integration into flake graphite sourcing represent the dominant competitive moves.
Among East Asian battery conglomerates, Samsung SDI exemplifies the integrated platform archetype with domestic cathode supply chain control. Nanotech Energy occupies a position within the specialty electrolyte tier on the U.S. West Coast. Grabat Graphenano Energy represents the European aqueous synthesis pivot as REACH restrictions tighten precursor chemical access.
| Leading Market Players |
|---|
| Nanotech Energy |
| Huawei Technologies Co., Ltd. |
| Samsung SDI |
| Cabot Corporation |
| Log 9 Materials Scientific Private Limited |
| Grabat Graphenano Energy |
| XG Sciences, Inc. |
| Global Graphene Group |
| Nanotek Instruments, Inc. |
| Others |
Pricing and Supply Chain Analysis
Shenzhen and Ningbo battery industrial parks concentrate electrode foundry capacity that transfers flake graphite volatility risk upstream through multi-year fixed-price contracts mandated by BYD and CATL procurement teams. This geographic concentration compresses margin buffers for dispersion specialists while amplifying pricing power for automotive OEMs with captive material streams.
Pricing Analysis
China's MIIT GB standards dictate the pricing tier structure across the graphene battery market, separating automotive-qualified suppliers from industrial-grade vendors. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale, with MIIT-compliant automotive cells commanding substantial premiums over consumer electronics variants. Cost compression in standard-tier electrodes is intensifying because Chinese OEMs demand multi-year fixed-price commitments that lock in margins during flake graphite export licensing delays. Automotive OEMs exhibit the least price sensitivity due to non-negotiable energy density mandates, while grid storage developers remain most price-sensitive as they prioritize capital cost per megawatt-hour over premium graphene performance.
Supply Chain Analysis
Battery-grade flake graphite feedstock from Mozambique and Madagascar anchors upstream material flows, with graphene oxide precursor synthesis drawing from these African sources and secondary Chinese spherical graphite processing hubs. The supply chain rests on high-purity cathode materials from South Korean foundries, ceramic electrolyte substrates from German research clusters, and organic electrolyte formulations from U.S. West Coast specialists. Single-source vulnerability concentrates in East Asian electrode dispersion capacity, where over seventy percent of global output clusters in Chinese and South Korean industrial corridors. Distribution runs through tier-one cell assembler procurement networks that increasingly require foundry-equity stakes from material partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Graphene battery technology sits at a platform-economics inflection where solid-state patent thickets and automotive qualification ecosystems are creating winner-take-most dynamics. Interoperability between MIIT certification pathways and EU Battery Regulation traceability mandates is consolidating supplier pools around dual-compliant material platforms.
For Market Incumbents: Harden defensive positions by securing captive flake graphite sourcing through backward integration into Mozambican and Malagasy mining concessions, insulating margin structures from export licensing volatility. Accelerate aqueous synthesis patent filings to preempt REACH restriction compliance costs that threaten European market access. Samsung SDI and Nanotech Energy demonstrate the protective value of domestic cathode supply chain control and proprietary electrolyte formulations respectively.
For New Entrants and Emerging Players: Build out white-space positions in Indian PLI scheme corridors where production-linked incentives for advanced chemistry cells create localized electrode demand outside East Asian supply chain chokepoints. Target medical patch and fitness band architectures in wearable tech segments where ultrathin form factors command premium margins per watt-hour and certification pathways remain less consolidated than automotive tiers. Establish go-to-market partnerships with Shenzhen-based medical device assemblers seeking skin-contact power systems with reduced flammability profiles.
For Investors and Strategic Acquirers: Long-term, this sits as a materials-platform play because solid-state ceramic-graphene composite electrolytes promise simultaneous energy density gains and thermal runaway suppression that will reshape aerospace and automotive power system procurement. Acquisition targets should emphasize aqueous synthesis specialists with REACH-compliant precursor routes and established MIIT qualification relationships. Watch for inflection signals in 4680-format silicon-graphene composite anode adoption rates at German research clusters and U.S. national laboratories, as these prototypes indicate commercial scalability thresholds.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Flake Graphite Sourcing | Mozambican and Malagasy mining concessions insulate electrode foundries from export licensing delays that propagate through precursor costs. |
| Aqueous Synthesis Patent Positioning | REACH-compliant water-based exfoliation routes secure preferred supplier status with European automotive OEMs subject to CSRD disclosure rules. |
| MIIT Qualification Acceleration | GB standards compliance filters supplier pools toward high-purity dispersion specialists with automotive certification pathways. |
| Solid-State R&D Consortium Participation | German and U.S. research clusters draw aerospace procurement for thermal-stable graphene-ceramic composite satellite power systems. |
| Indian PLI Scheme Manufacturing Localization | Gujarat and Tamil Nadu industrial corridors attract electrode foundry investments as domestic electric vehicle assembly scales outside East Asian supply chains. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with electrode foundry managers, automotive OEM procurement leads, aerospace battery pack designers, and regulatory affairs specialists at graphene precursor suppliers. Secondary validation drew from MIIT GB standard filings, ECHA REACH authorization databases, Indian BIS certification records, and customs trade data tracking flake graphite import flows. Bottom-up capacity assessments at Shenzhen, Ningbo, and Seoul Capital Area industrial parks were triangulated against top-down demand projections from electric vehicle production databases and medical device shipment records.
Calibration against historical qualification timeline compression patterns informed growth trajectory modeling across the projection horizon. Segmentation dimensions included electrochemical architecture, end-use performance threshold, and integration complexity, with additional granularity around automotive certification tier and aqueous synthesis route adoption. CAGRs were derived from slope analysis of patent filing velocity, foundry investment announcements, and OEM procurement contract structures. Industry-specific forecast inputs incorporated solid-state ceramic electrolyte R&D expenditure patterns and silicon-graphene composite anode prototype progression at German research clusters.
The forecast holds incumbent behavior within observed patterns; aggressive moves by vertically integrated Chinese battery conglomerates or state-backed Indian electrode foundries would shift outcomes beyond modeled ranges. Cross-checking against aerospace contractor thermal management specification updates and FAA drone power system procurement guidelines is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Li-Sulfur Battery Market
Lithium-ion Battery
Lithium-Sulfur Battery Market
Lithium-ion Battery
Lithium Iron Phosphate (LiFePO4) Battery Market
Lithium-ion Battery
Lithium Solid-State Battery Market
Lithium-ion Battery
Europe NMC Battery Pack Market
Lithium-ion Battery
Lithium Polymer Battery Market
Lithium-ion Battery
Lithium Battery Components Market
Lithium-ion Battery
Automotive 48V Lithium Battery Market
Lithium-ion Battery
Bangladesh Lithium-Ion Battery Market
Lithium-ion Battery
EV SOLID State Battery Market
Lithium-ion Battery
Next Generation Advanced Battery Market
Lithium-ion Battery
Lithium-Ion Battery Anode Market
Lithium-ion Battery
Germany Electric Vehicle Battery Materials Market
Lithium-ion Battery
Graphite Anode for LIB Market
Lithium-ion Battery
China SLI Battery Market
Lithium-ion Battery
Silicon Anode Lithium-Ion Battery Market