
 Battery Swap-Ready Pack Systems for Urban Fleets Market | 2026-2036
Battery Swap-Ready Pack Systems for Urban Fleets Market Size, Share, and Industry Trends Forecast 2026-2036
Battery Swap-Ready Pack Systems for Urban Fleets Market Insights
Aftermarket service revenue is rewriting competitive economics across the battery swap ecosystem. Gogoro leverages its vertically integrated network of GoStations to control recurring energy-subscription flows in Taiwan's dense urban corridors. CATL anchors high-volume manufacturing of standardized chassis-integrated modules, sustaining cost leadership through captive cell production. NIO differentiates via its Power Swap architecture, competing on user experience in China's premium ride-hailing segment.
Battery swap-ready pack systems for urban fleets comprise modular electrochemical energy storage units engineered for mechanical decoupling and automated exchange, typically featuring CAN bus communication protocols, liquid thermal management circuits, and standardized mechanical latching interfaces compatible with robotic swap stations; their primary purpose is eliminating vehicle downtime during charging for high-utilization commercial fleets operating on fixed routes or dispatch schedules. Modular Packs lead current deployment due to their compatibility across multiple vehicle platforms, while Smart Packs represent the fastest-growing category as fleet operators demand real-time state-of-health telemetry and predictive degradation analytics. Lithium-Ion technology dominates installed capacity, though Sodium-Ion chemistry is gaining structural traction for last-mile delivery applications where energy density requirements are moderate and cost sensitivity is acute.
China's SAMR enforces GB standards for battery dimensional interchangeability and electrical safety protocols, directly conditioning which pack architectures achieve market access. India's CEA and BIS jointly regulate energy storage system certification for commercial vehicle applications, creating compliance thresholds that shape supplier selection by municipal transit operators. The EU's F-Gas Regulation and impending battery passport requirements under the EU Green Deal will extend material traceability obligations to swap-ready pack producers serving European microtransit fleets. Stakeholders must monitor which regulatory jurisdictions first mandate open-architecture swap standards, as this determination will lock in design commitments for the next generation of platform-agnostic pack systems.
Market Dynamics
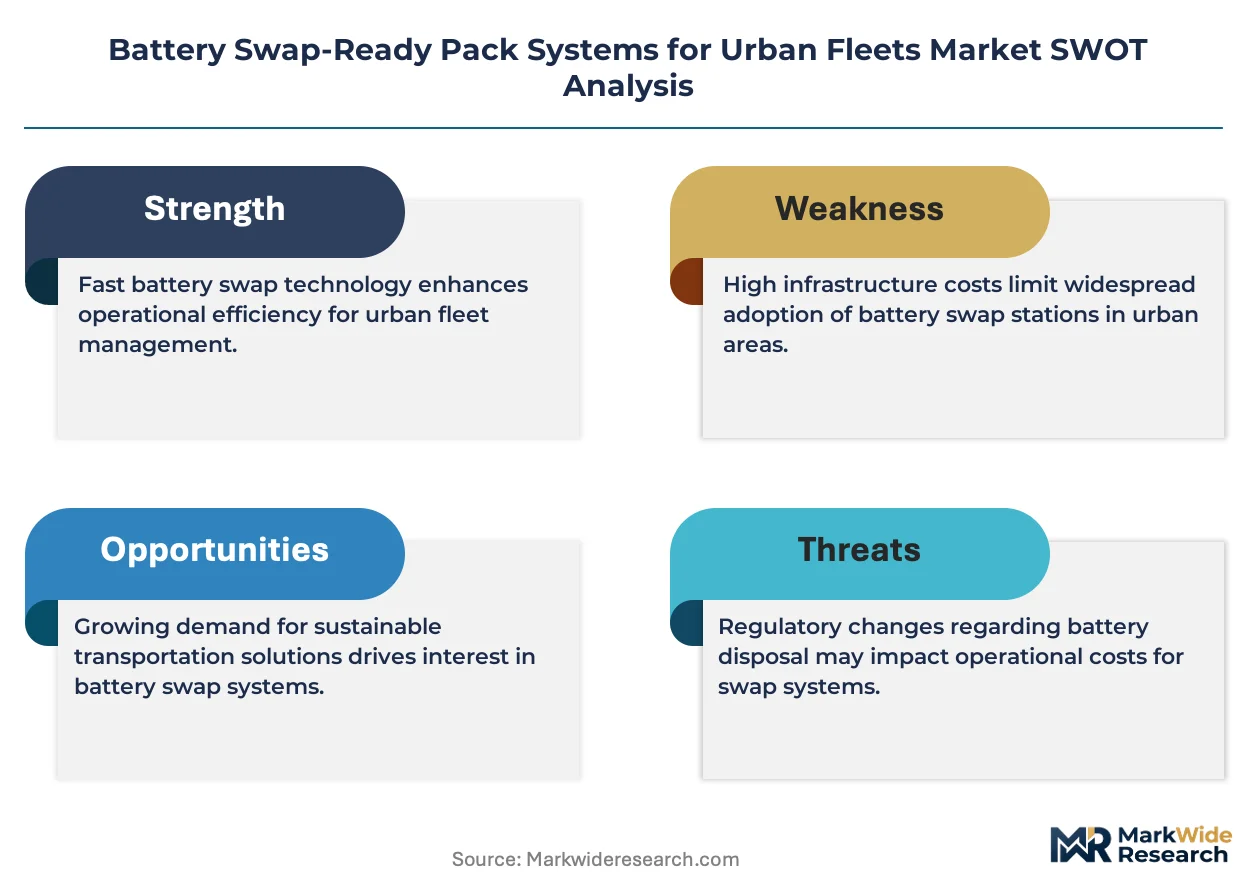
Standardization pressure from China's GB standards for dimensional interchangeability is forcing pack architecture redesigns across supplier ecosystems, compressing time-to-market for modular systems targeting municipal bus depots and ride-hailing fleets.
Growth Catalysts
- Dual carbon policy mandates:China's MEE enforcement of carbon intensity targets for commercial transport fleets is accelerating depot electrification timelines and swap-ready procurement specifications.
- Dense urban corridor utilization:India's urban logistics operators face acute downtime constraints on two-wheeler delivery fleets, creating structural pull for sub-three-minute swap protocols.
- CAN bus protocol maturation:Standardized battery management system communication architectures are reducing integration friction between pack suppliers and vehicle OEMs.
Market Restraints
- Lithium carbonate price volatility:Raw material input swings compress pack assembler margins and deter long-term fleet contracting.
- Cell supply concentration:Manufacturing of high-nickel cylindrical formats concentrates in East Asian production corridors, creating single-source vulnerability for European system integrators.
- Mechanical latch standardization gaps:Absence of unified robotic interface specifications forces redundant engineering across swap station deployments.
Strategic Opportunities
- Sodium-ion chemistry integration:Moderate energy density packs for last-mile cargo applications unlock cost structures below lithium-ion parity.
- EU battery passport alignment:Material traceability mandates under the EU Green Deal create first-mover advantage for swap-ready producers with embedded digital twin architectures.
- Microtransit fleet conversion:European municipal operators are piloting swap-enabled electric minibuses for on-demand service zones.
Industry Challenges
- Thermal management engineering scarcity:Liquid cooling circuit design for high-C-rate swap packs requires specialized simulation talent concentrated at automotive tier-one suppliers.
- Swap station capex intensity:Robotic handling systems and battery inventory buffers demand upfront capital deployment that strains municipal procurement cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Battery Swap-Ready Pack Systems for Urban Fleets Market |
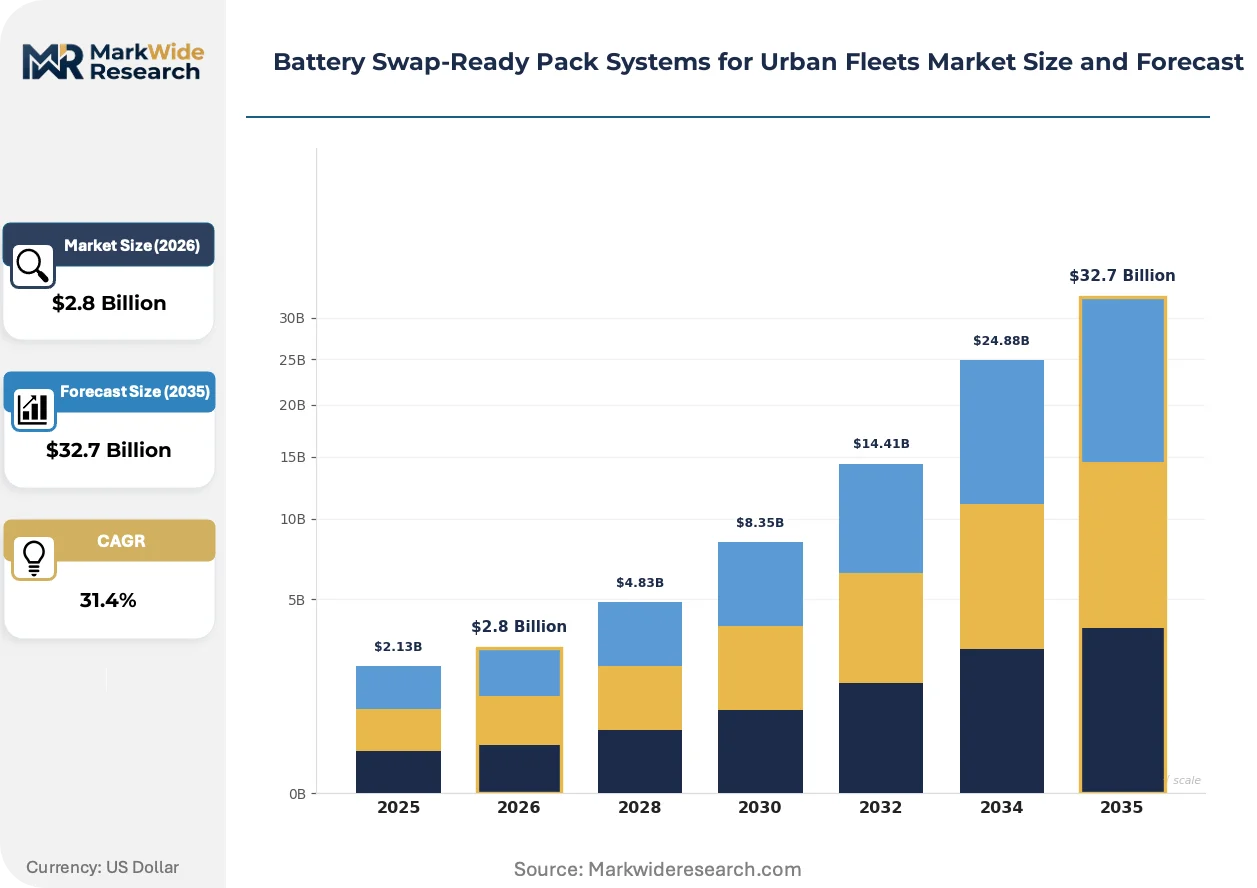
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $32.7 Billion |
| CAGR (2026 – 2036) | 31.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular Packs, Integrated Modules, Portable Units, Fixed Installations, Smart Packs Technology: Lithium-Ion, Solid-State, Nickel-Metal Hydride, Lead-Acid, Sodium-Ion Application: Ride-Hailing Vehicles, Last-Mile Delivery, Public E-Buses, Cargo Scooters, Microtransit Services End User: Municipal Transit Operators, Private Logistic Firms, Delivery Startups, Sharing Platform Companies |
| Companies Covered | NIO, Gogoro, CATL, Ample, SUN Mobility, Battery Smart, Ola Electric, Bounce Infinity, Swobbee, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Battery Swap-Ready Pack Systems for Urban Fleets Market Trends and Innovations
Real-time telemetry integration is compressing the information gap between pack health and fleet dispatch decisions, enabling predictive swap scheduling rather than reactive range anxiety management.
Smart battery management systems with embedded edge computing are digitizing state-of-health inference directly at the pack level. Transit operators in Shenzhen and Hangzhou are deploying these systems across bus depots to optimize swap queue sequencing. This digitizing of degradation analytics is reducing unnecessary battery rotations and extending cycle life.
The EU's F-Gas Regulation is phasing down hydrofluorocarbon-based thermal management fluids in commercial vehicle applications. Pack suppliers serving European microtransit fleets are accelerating transition to CO2-based cooling circuits. This regulatory compression is favoring suppliers with existing low-GWP refrigeration expertise.
Fleet procurement departments are unbundling energy service contracts from hardware acquisition, separating pack ownership from vehicle ownership. Leasing consortia in India's urban corridors are capturing this shift by offering battery-as-a-service models to delivery aggregators. This reconfiguration is visible most acutely in Bengaluru and Hyderabad where two-wheeler fleet density supports station network economics.
Battery Swap-Ready Pack Systems for Urban Fleets Market Segmentation
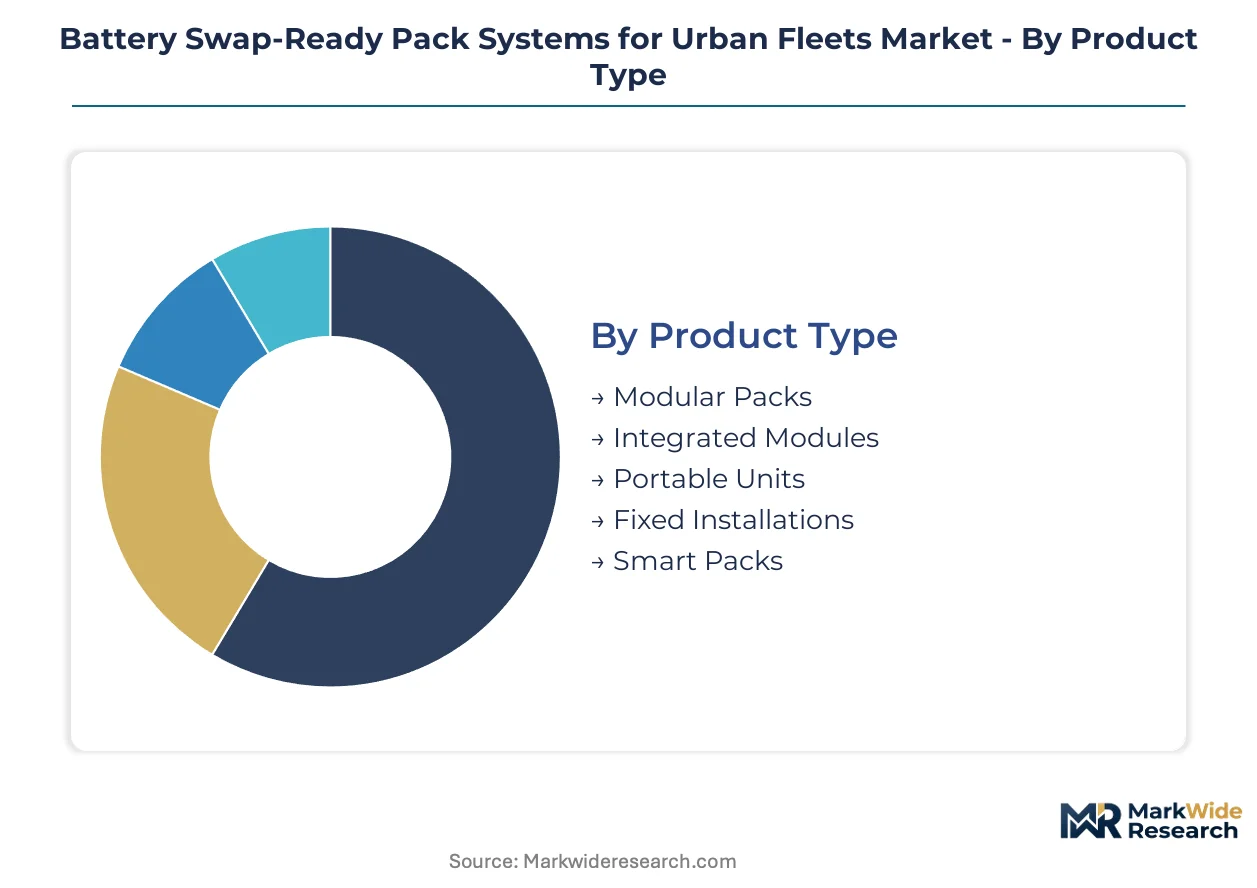
Segmentation in battery swap-ready pack systems reveals how technical specifications, chemistry choices, and fleet operational models intersect to determine procurement priorities. Urban fleet operators select pack architectures based on route predictability, vehicle platform diversity, and swap station network density.
Product Type:
Urban corridors impose divergent mechanical requirements on swap architectures depending on fleet heterogeneity and depot automation levels.
- Modular Packs:Standardized electrochemical units with CAN bus communication and mechanical latching interfaces designed for cross-platform compatibility. Shenzhen's municipal bus depots favor these for mixed OEM fleets where robotic swap stations must accommodate multiple vehicle widths. GB standards compliance accelerates procurement for China's ride-hailing consolidation.
- Smart Packs:Edge-computing-enabled battery management systems with embedded state-of-health telemetry and predictive degradation analytics. Bengaluru's delivery aggregators deploy these across two-wheeler fleets to optimize swap queue sequencing and extend cycle life through data-driven dispatch.
- Integrated Modules:Chassis-embedded packs with liquid thermal management circuits engineered for single-platform dedication.
- Portable Units:Manual-lift battery formats targeting microtransit operators with limited robotic infrastructure.
- Fixed Installations:Stationary buffer storage systems at swap depots for grid stabilization and peak demand management.
The dominant share belongs to Modular Packs, while Smart Packs are expanding most quickly as fleet telemetry demands intensify.
Technology:
Chemistry selection tracks energy density requirements against raw material cost exposure and thermal management complexity.
- Lithium-Ion:High-nickel cylindrical and prismatic formats dominating installed capacity across high-utilization fleets. CATL's captive cell production secures cost leadership for China's premium ride-hailing segment where energy density prioritizes range extension.
- Sodium-Ion:Moderate energy density chemistry gaining structural traction where cost sensitivity outweighs gravimetric performance constraints. India's last-mile cargo scooter operators pilot these for sub-parity pack economics on fixed urban routes with predictable daily mileage.
- Solid-State:Next-generation ceramic electrolyte architectures targeting premium microtransit applications.
- Nickel-Metal Hydride:Legacy chemistry retained in select municipal retrofit programs.
- Lead-Acid:Phased-out format limited to transitional fleet conversions in price-constrained procurement environments.
Lithium-Ion retains volume leadership, though Sodium-Ion is climbing the fastest as procurement departments unbundle energy service contracts from hardware acquisition.
Application:
Route predictability and duty cycle intensity determine swap protocol design and station network economics.
- Public E-Buses:High-capacity depot-based swap systems with overnight charging buffers and robotic handling for 300+ kWh packs. Hangzhou's municipal transit authority deploys these across fixed-route networks where downtime elimination justifies capex-intensive infrastructure.
- Last-Mile Delivery:Sub-three-minute swap protocols for two-wheeler and three-wheeler cargo fleets operating on dense urban corridors. Hyderabad's logistics aggregators leverage SUN Mobility's station density to sustain continuous dispatch schedules without range anxiety penalties.
- Ride-Hailing Vehicles:Premium sedan and SUV formats with user experience-optimized swap architectures.
- Cargo Scooters:Lightweight commercial two-wheelers with standardized pack footprints for cross-fleet compatibility.
- Microtransit Services:On-demand electric minibuses requiring flexible swap scheduling for variable route patterns.
Public E-Buses command the largest committed capacity, while Last-Mile Delivery is gaining share fastest as e-commerce logistics electrifies.
End User:
Procurement sophistication and contracting horizon length differentiate customer segments across the ecosystem.
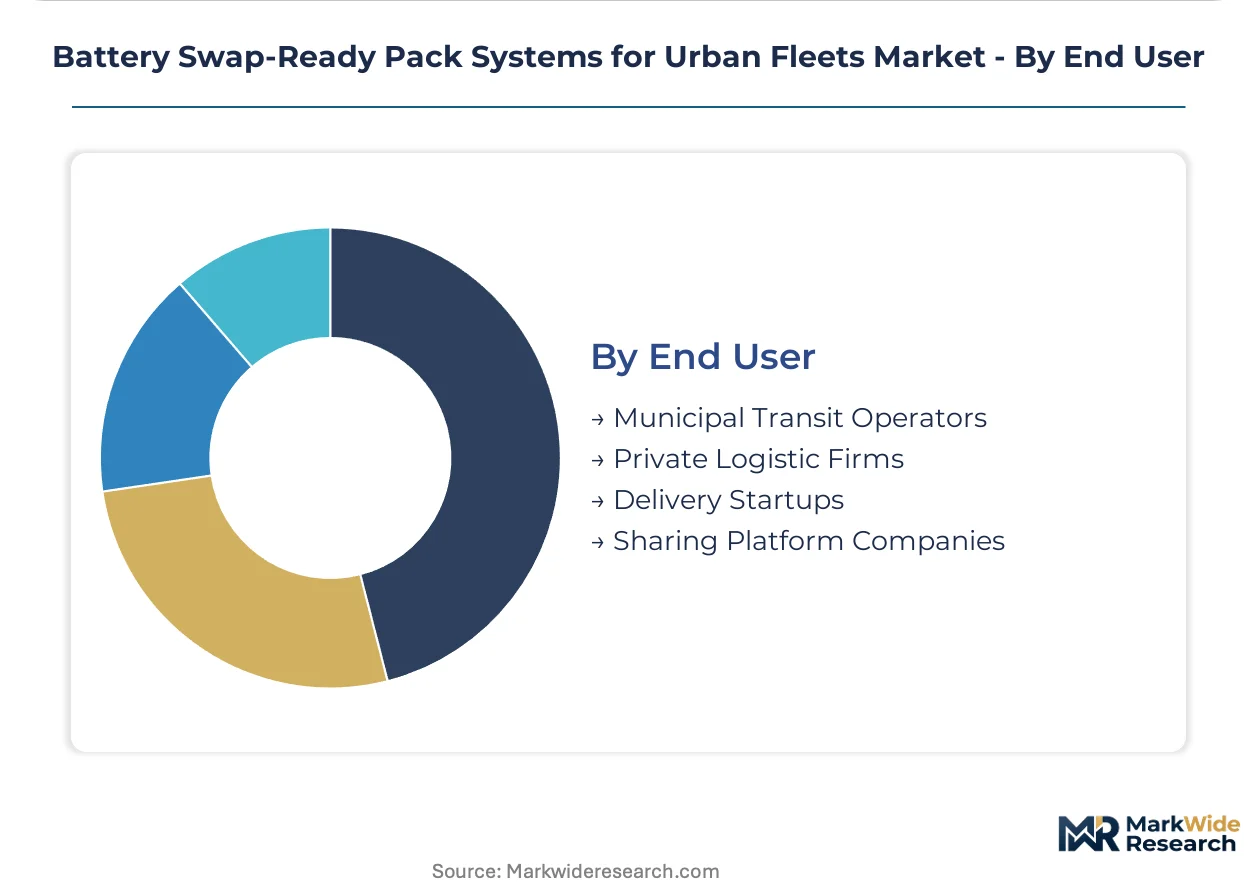
- Municipal Transit Operators:Long-cycle tendering processes with stringent GB standards compliance and multi-year service level agreements. Shenzhen and Hangzhou authorities bundle swap infrastructure with bus fleet procurement, locking in supplier relationships through depot electrification mandates.
- Private Logistic Firms:Asset-heavy operators with dedicated route networks and captive swap station deployment. Taiwan's Gogoro Network captures these through vertically integrated GoStation ownership and recurring energy-subscription revenue streams.
- Delivery Startups:Venture-funded aggregators prioritizing capital-light battery-as-a-service models.
- Sharing Platform Companies:Multi-modal mobility providers seeking cross-vehicle swap compatibility.
Municipal Transit Operators anchor committed demand, while Private Logistic Firms are scaling fastest through unbundled energy service contracting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across procurement contexts. Municipal transit authorities in China absorb premium capex for robotic depot infrastructure, while Indian delivery aggregators prioritize sub-parity pack economics on thin margins. European microtransit operators face intermediate sensitivity where EU Green Deal compliance costs filter through to contracting structures.
China
Dual carbon mandates from MEE compress electrification timelines for municipal bus fleets. SAMR-enforced GB standards for dimensional interchangeability lock in modular pack architectures for depot procurement. Shenzhen and Hangzhou transit authorities bundle swap infrastructure with fleet tenders, consolidating supplier relationships through multi-year service agreements.
India
Last-mile logistics operators face acute downtime constraints on two-wheeler delivery fleets. CEA and BIS jointly regulate energy storage certification, creating compliance thresholds that shape supplier selection. Bengaluru and Hyderabad host dense station networks where SUN Mobility and Ola Electric sustain continuous dispatch schedules through battery-as-a-service contracting.
Germany
Automotive tier-one suppliers concentrate thermal management engineering talent for liquid-cooled high-C-rate packs. KBA type-approval processes extend to swap-ready architectures under evolving commercial vehicle safety frameworks. Stuttgart and Munich industrial clusters pilot CO2-based cooling circuits ahead of F-Gas Regulation phase-down deadlines.
Taiwan
Vertically integrated network operators capture recurring energy-subscription revenue in dense urban corridors. METI-aligned standards facilitate cross-strait component flows for pack assembly. Taipei anchors GoStation network density where Gogoro controls hardware-software integration across two-wheeler fleet dispatch.
United States
Venture-funded mobility startups pilot modular swap protocols for last-mile cargo applications. NHTSA safety guidelines for commercial EV battery systems condition market access for imported pack architectures. California and Texas logistics corridors test robotic handling systems for three-wheeler delivery electrification.
Battery Swap-Ready Pack Systems for Urban Fleets Market Competitive Landscape
Vertically integrated network operators and captive cell manufacturers split the market along ownership-structure lines. The vendor base concentrates around three strategic archetypes: energy-service platforms controlling station infrastructure, automotive-tier suppliers with thermal management depth, and cell producers extending downstream into pack integration. Dominant competitive moves include backward integration into cell production and geographic licensing of swap station operating systems.
Within the network-operator archetype, Gogoro and SUN Mobility exemplify vertically integrated platform control. NIO occupies a position in premium ride-hailing segments through user-experience-optimized architectures. CATL anchors the manufacturing-intensive tier through captive supply of standardized chassis-integrated modules.
| Leading Market Players |
|---|
| NIO |
| Gogoro |
| CATL |
| Ample |
| SUN Mobility |
| Battery Smart |
| Ola Electric |
| Bounce Infinity |
| Swobbee |
| Others |
Pricing and Supply Chain Analysis
Single-source dependency on East Asian cylindrical cell production compresses pricing tier spreads while forcing European system integrators into premium positioning for liquid-cooled swap packs. Lithium carbonate volatility feeds directly into pack assembler margins, conditioning whether fleet operators absorb cost pass-through or shift procurement toward sodium-ion alternatives.
Pricing Analysis
Aftermarket service revenue from battery-as-a-service subscriptions drives lifetime value capture beyond hardware margins. Three-tier pricing structure across premium, standard, and economy levels separates NIO's user-experience-optimized architectures from CATL's volume-scale chassis modules and Indian leasing consortia's sub-parity sodium-ion offerings. Pricing pressure stems from raw material input swings that deter long-term fleet contracting. Municipal transit authorities in China exhibit lowest price sensitivity, absorbing robotic depot infrastructure premiums, while Indian delivery aggregators operate on thin margins that prioritize sub-parity pack economics.
Supply Chain Analysis
Export-control restrictions on semiconductor manufacturing equipment and advanced battery materials limit technology transfer flows between East Asian production corridors and emerging assembly hubs. Cell manufacturing concentrates in China, South Korea, and Japan, with pack integration drawing from automotive tier-one suppliers in Germany and Taiwan. Raw material dependencies span lithium carbonate, high-nickel cathode precursors, and liquid cooling circuit components. Single-source vulnerability concentrates in cylindrical format cell supply. Distribution runs through OEM-direct contracting for municipal fleets and vertically integrated network operators for two-wheeler logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The battery swap-ready pack market sits in early-cycle expansion as dual carbon mandates and depot electrification timelines compress adoption curves across municipal transit procurement.
For Market Incumbents: Insulate recurring revenue streams by deepening captive cell production and locking multi-year service level agreements with Shenzhen and Hangzhou transit authorities. Sodium-ion chemistry integration and unbundled energy service contracting represent emerging threats from low-cost entrants; defend through GB standards compliance investment and thermal management engineering depth that latecomers cannot replicate. For New Entrants and Emerging Players: Establish a beachhead in European microtransit fleet conversion, where F-Gas Regulation phase-downs and battery passport requirements create compliance thresholds favoring new CO2-based cooling architectures. India's last-mile cargo scooter segment offers penetrable white-space with moderate energy density requirements and battery-as-a-service procurement models. Go-to-market execution should anchor on digital twin architectures that embed material traceability ahead of EU Green Deal mandates. For Investors and Strategic Acquirers: The market sits at a platform-consolidation phase that favors vertically integrated network operators with station infrastructure control and recurring subscription revenue. Long-term viability over the next decade hinges on swap station network density achieving minimum efficient scale in urban corridors. Acquisition targets should display captive cell supply or robotic handling system integration. The signal to watch is which regulatory jurisdictions first mandate open-architecture swap standards, as this determination will lock in design commitments and supplier positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cell Production | CATL's captive cylindrical format supply secures cost leadership against pack assemblers dependent on spot market procurement. |
| Swap Station Network Density Expansion | Gogoro's GoStation ownership in Taipei creates defensive moats through recurring energy-subscription revenue capture. |
| Digital Twin Architecture Development | EU battery passport alignment favors producers with embedded material traceability systems ahead of compliance deadlines. |
| Sodium-Ion Chemistry Scale-Up | Indian logistics operators pilot sub-parity pack economics on fixed urban routes with predictable daily mileage constraints. |
| GB Standards Compliance Certification | SAMR-enforced dimensional interchangeability locks modular architectures into China's municipal bus depot procurement. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of trade customs data, SEC filings from battery and automotive suppliers, GB standards documentation, and EU regulatory filings. Primary interviews engaged fleet procurement managers at municipal transit authorities, thermal engineering leads at automotive tier-one suppliers, swap station network operators, and CEA certification specialists. Secondary validation drew from SAMR enforcement notices, BIS energy storage directives, and F-Gas Regulation implementation guidance. Bottom-up pack shipment estimates triangulate against top-down fleet electrification procurement forecasts.
Forecast inputs include vehicle platform standardization trajectories, swap station capex deployment cycles, and chemistry migration curves from lithium-ion to sodium-ion. Segmentation dimensions span product type, technology chemistry, application duty cycle, and end-user contracting sophistication across the projection horizon. CAGRs derive from installed base growth rates and replacement cycle timing. Industry-specific inputs incorporate GB standards adoption timelines and dual carbon policy enforcement intensity from MEE.
Stress conditions across lithium carbonate price bands, swap station utilization rates, and regulatory standardization timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding fleet electrification mandates and station network economics. Material shifts in cell supply concentration or open-architecture swap standard mandates would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Battery Infrastructure
South America Electric Vehicle Battery Manufacturing Equipment Market
Battery Infrastructure
Global Battery Technology Market
Battery Infrastructure
Global Automotive 48 Volt Battery System Market
Battery Infrastructure
France Electric Vehicle Battery Manufacturing Equipment Market
Battery Infrastructure
Substation Battery Market
Battery Infrastructure
New Energy Battery Structural Parts Market
Battery Infrastructure
United Kingdom Electric Vehicle Battery Separator Market
Battery Infrastructure
China Electric Vehicle Battery Electrolyte Market
Battery Infrastructure
Electric Vehicle Battery Swapping Market
Battery Infrastructure
France Electric Vehicle Battery Materials Market
Battery Infrastructure
Advance Battery Technologies Market
Battery Infrastructure
Lithium-Ion Battery Housing Cases Market
Battery Infrastructure
China Battery Manufacturing Equipment Market
Battery Infrastructure
China Electric Vehicle Battery Manufacturing Equipment Market
Battery Infrastructure
North America Electric Vehicle Battery Electrolyte Market
Battery Infrastructure
Middle East and Africa Electric Vehicle Battery Separator Market