
 North America Electric Vehicle Battery Manufacturing Equipment Market | 2026-2036
North America Electric Vehicle Battery Manufacturing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
North America Electric Vehicle Battery Manufacturing Equipment Market Insights
Contract equipment buyers from battery cell startups is collapsing as vertically integrated OEMs internalize production lines. Tesla Inc. dominates in-house equipment specification across its Nevada and Texas facilities. Panasonic Energy of North America anchors Japanese-American joint venture tooling standards at its Kansas operation. Siemens AG competes through digital twin integration for line commissioning and yield optimization.
North America electric vehicle battery manufacturing equipment encompasses machinery for electrode coating, cell stacking, electrolyte filling, formation cycling, and module assembly, typically operating at micron-level precision and cleanroom conditions to prevent contamination. This equipment serves the industrial purpose of converting raw cathode and anode materials into finished battery packs ready for vehicle integration. Assembly Equipment leads capital expenditure as gigafactories scale cylindrical and prismatic cell formats, while Testing Systems captures expanding margin pools from formation and aging protocols required for solid-state validation. Solid-State technology represents the fastest-growing equipment segment, though Lithium-Ion tooling sustains near-term volume dominance across the application base.
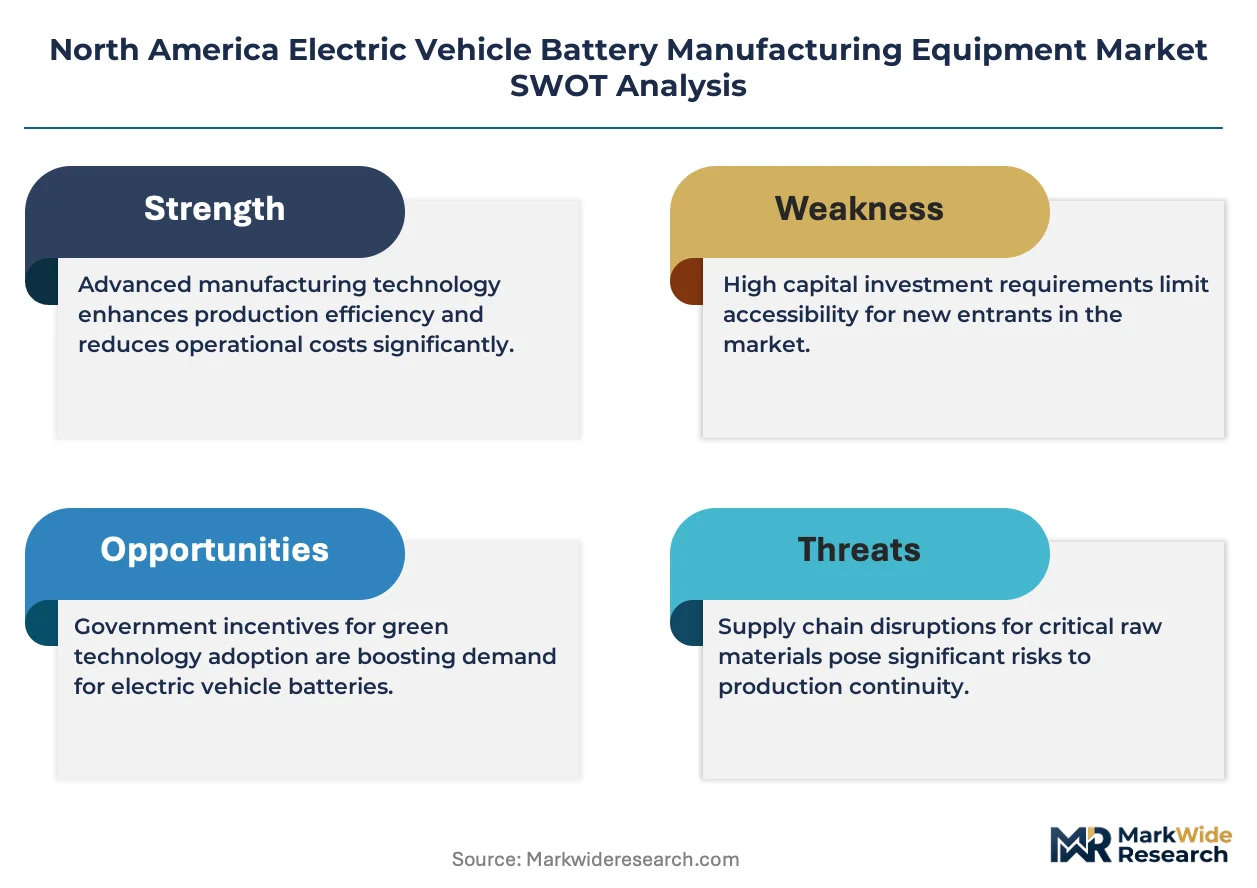
The U.S. Inflation Reduction Act and Canada's Strategic Innovation Fund together shape demand through production tax credits tied to North American content thresholds. NHTSA battery safety standards and EPA industrial emissions rules further constrain equipment design, forcing suppliers to certify thermal management and solvent recovery systems. Stakeholders must monitor how proposed EPA updates to hazardous air pollutant rules for electrode manufacturing alter cleanroom ventilation specifications and capital requirements.
Market Dynamics
The U.S. Inflation Reduction Act's domestic content thresholds are redirecting capital flows toward Michigan, Tennessee, and Ontario gigafactory clusters, compressing equipment procurement timelines and favoring regional suppliers with proven cleanroom certification.
Growth Catalysts
- Production Tax Credits:The U.S. IRA and Canada's Strategic Innovation Fund tie incentives to North American content thresholds, compelling battery cell OEMs to localize electrode coating and formation cycling equipment procurement.
- Solid-State Pilot Lines:Solid-state cell validation protocols are expanding demand for specialized formation and aging systems operating at dry-room conditions below -40°C dewpoint.
- Great Lakes Corridor Concentration:Battery cell production capacity expansion across Michigan and Ontario is concentrating equipment buyer pools, enabling supplier economies of scale in micron-precision assembly systems.
Market Restraints
- High-Purity Solvent Supply:N-methyl-2-pyrrolidone and other electrode coating solvents face concentrated Asian supply chains, exposing equipment operators to input cost volatility and forced substitution trials.
- Cleanroom Infrastructure Bottlenecks:EPA hazardous air pollutant rules for electrode manufacturing constrain ventilation system design, extending facility commissioning timelines and inflating capital requirements for solvent recovery integration.
- Technical Talent Scarcity:The shallow pool of technicians qualified in lithium-ion cell failure mode analysis restricts operational scaling at new gigafactory sites across the U.S. Midwest.
Strategic Opportunities
- Second-Life Battery Disassembly:End-of-life electric vehicle pack processing creates demand for automated module dismantling and cell sorting equipment, an application segment with minimal incumbent supplier presence.
- Digital Twin Commissioning:Virtual line validation before physical installation reduces yield ramp time, opening service revenue pools for equipment vendors with Siemens AG-class simulation capabilities.
- Mexican Nearshoring:Labor cost differentials and USMCA content rules are drawing electrode slitting and tab welding equipment inquiries to Baja California and Querétaro industrial zones.
Industry Challenges
- Cleanroom Certification Backlogs:ISO 14644-1 Class 7 and Class 8 validation for electrode coating bays faces inspector capacity constraints, delaying production start dates at greenfield facilities.
- Multiformat Line Reconfiguration:Cylindrical 4680, prismatic blade, and pouch cell format transitions force equipment buyers to specify modular stacking and welding stations with uncertain payback periods.
- Integration Complexity:Legacy MES systems at automotive OEM battery plants resist seamless data handoff to new formation cycling equipment, requiring costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Electric Vehicle Battery Manufacturing Equipment Market |
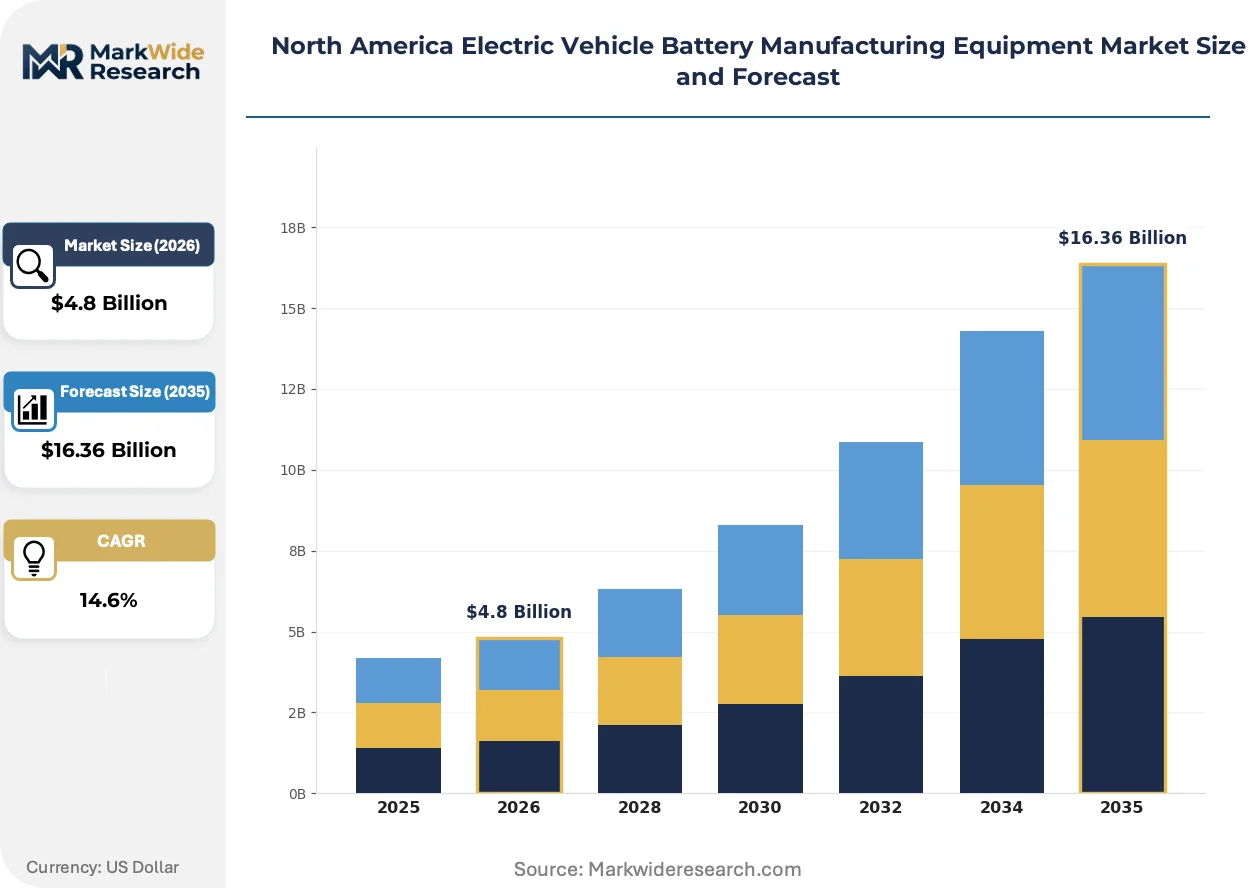
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $16.36 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Assembly Equipment, Testing Systems, Manufacturing Tools, Material Handling Equipment Technology: Lithium-Ion, Solid-State, Nickel-Metal Hydride, Lead-Acid Application: Electric Passenger Vehicles, Electric Buses, Electric Trucks, Hybrid Vehicles End User: OEMs, Battery Manufacturers, Component Suppliers, Research Institutions |
| Companies Covered | A123 Systems, Dürr AG, Hitachi High-Tech Corporation, Manz AG, Nordson Corporation, Panasonic Energy of North America, Siemens AG, Tesla Inc., Wuxi Lead Intelligent Equipment, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Electric Vehicle Battery Manufacturing Equipment Market Trends and Innovations
Equipment specification priorities are pivoting from throughput maximization toward yield assurance and format flexibility, as cell chemistry transitions and regulatory traceability requirements reshape capital allocation.
Dry electrode coating is displacing traditional solvent-based slurry processes in pilot line deployments. Tesla Inc. and Panasonic Energy of North America are validating binder-free calendering systems at their Nevada and Kansas facilities. This technology is displacing conventional coating dryers and solvent recovery infrastructure, compressing equipment footprints and eliminating thermal drying energy loads.
The U.S. EPA's proposed updates to hazardous air pollutant standards for electrode manufacturing are tightening volatile organic compound capture requirements. Equipment suppliers must now certify thermal oxidizer integration and real-time emission monitoring as standard line components. Formation cycling system vendors face the steepest compliance redesign burden, as aging protocols generate the highest solvent vapor concentrations.
Cell OEMs are consolidating equipment procurement under single-source line integrators rather than bidding individual process stations separately. Tier 1 automotive battery buyers now demand turnkey electrode-to-module accountability, displacing the fragmented vendor management models that dominated early gigafactory builds. This pattern is most visible in Tennessee and Ontario, where SK On and LG Energy Solution have awarded full-line contracts to Korean and German equipment consortia.
North America Electric Vehicle Battery Manufacturing Equipment Market Segmentation
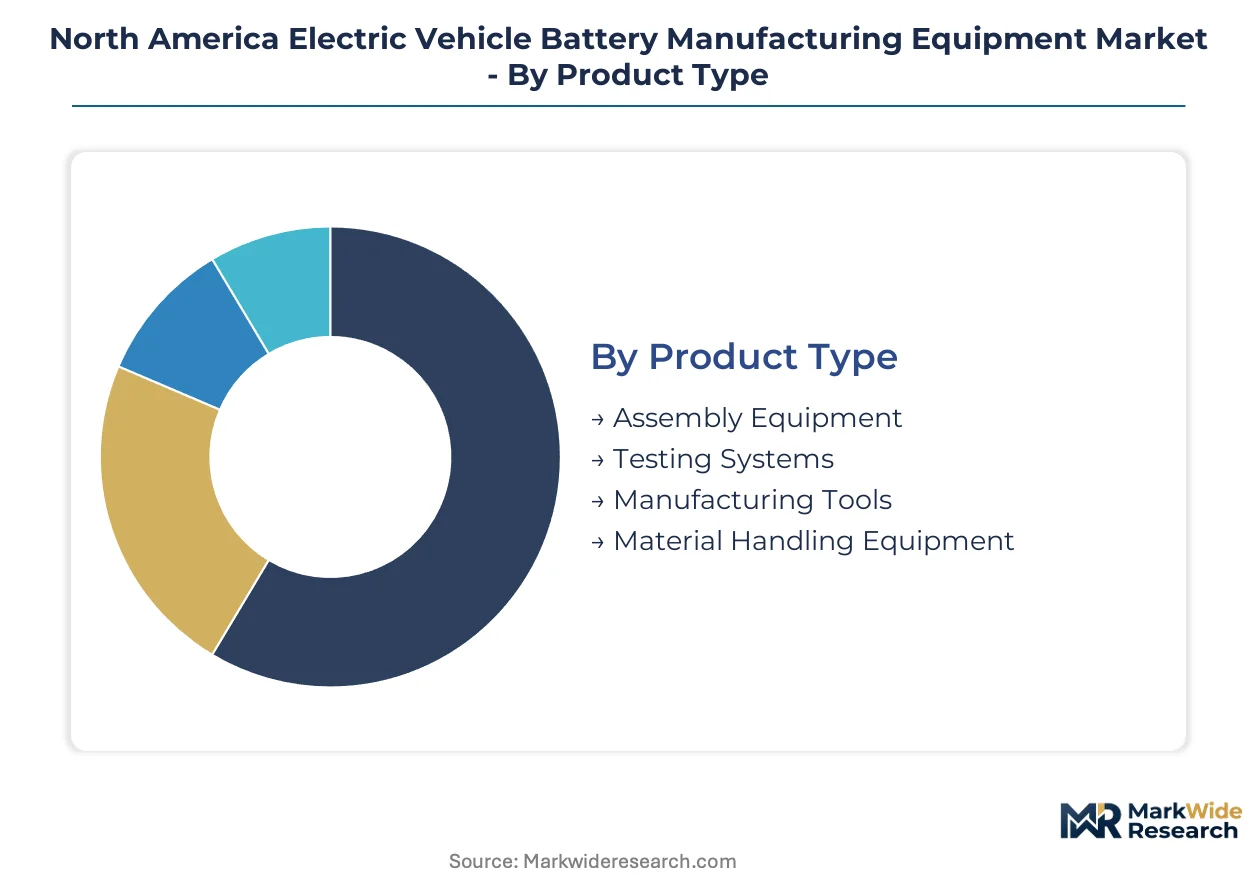
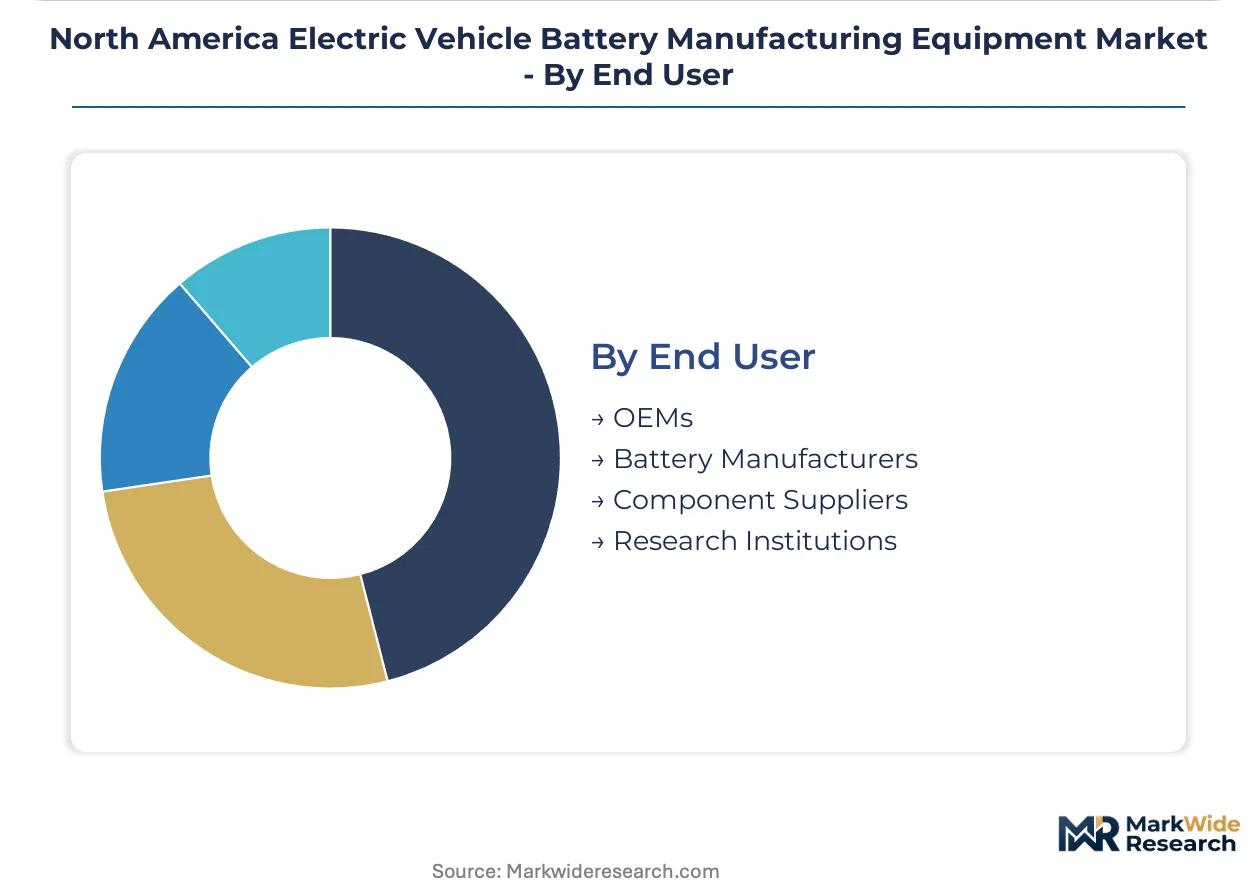
Equipment specification diverges sharply across buyer types in this market. Cell chemistry transitions and gigafactory scale-up patterns create distinct procurement channels that reshape supplier positioning.
Product Type:
Channel mix splits between turnkey line integrators serving OEMs and specialized component vendors supplying battery manufacturers.
- Assembly Equipment:Micron-precision stacking, welding, and module integration systems operate at ISO 14644-1 Class 7 cleanroom standards. Michigan and Ontario gigafactories concentrate demand for cylindrical and prismatic format lines as SK On and LG Energy Solution scale capacity.
- Testing Systems:Formation cycling and aging protocols validate cell electrochemical performance across temperature and voltage ranges. Solid-state pilot lines in Nevada and Kansas are expanding dry-room formation equipment orders below -40°C dewpoint specifications.
- Manufacturing Tools:Electrode slitting dies and calendering rollers require carbide-grade precision for cathode and anode thickness control.
- Material Handling Equipment:Automated guided vehicles and vacuum conveyors manage inter-bay logistics under cleanroom contamination protocols.
By volume, Assembly Equipment leads. By growth pace, Testing Systems is climbing the fastest.
Technology:
Cost tier stratification separates mature chemistry tooling from next-generation pilot line investments.
- Lithium-Ion:Established solvent-based coating and formation infrastructure dominates current capital allocation across Tennessee and Michigan production sites. Near-term volume concentration sustains equipment supplier margins despite chemistry transition risks.
- Solid-State:Dry electrode coating and sulfide electrolyte handling systems operate under specialized moisture-free conditions. U.S. IRA production tax credits are accelerating pilot line deployments in Nevada and Kansas as Tesla and Panasonic validate binder-free processes.
- Nickel-Metal Hydride:Legacy hybrid vehicle battery tooling maintains replacement demand from established Toyota and Honda supply chains.
- Lead-Acid:Minimal equipment crossover with EV applications; limited to auxiliary power system manufacturing.
Lithium-Ion retains volume leadership. Solid-State commands the steepest expansion trajectory.
Application:
Customer type concentration varies by vehicle class duty cycle and battery pack architecture requirements.
- Electric Passenger Vehicles:High-volume cylindrical and prismatic cell formats drive automated line specifications. The U.S. Great Lakes corridor concentrates procurement as Ford, General Motors, and Stellantis localize cell supply.
- Electric Trucks:Heavy-duty pack assembly requires modular welding stations handling larger form factors and thermal management integration.
- Electric Buses:Transit authority procurement cycles create lumpy demand for high-capacity pouch cell module equipment.
- Hybrid Vehicles:Smaller-scale NiMH and Li-Ion pack lines serve power-split transmission integration requirements.
Electric Passenger Vehicles dominate unit volume. Electric Trucks is gaining share fastest on commercial fleet electrification timelines.
End User:
Supply concentration tilts toward vertically integrated OEMs consolidating procurement under single-source integrators.
- OEMs:Tesla, Ford, and General Motors internalize equipment specification and line commissioning through captive engineering teams. The U.S. IRA domestic content thresholds compel direct procurement relationships with German and Korean equipment consortia.
- Battery Manufacturers:SK On, LG Energy Solution, and Panasonic Energy of North America anchor Japanese-American and Korean-German joint venture tooling standards.
- Component Suppliers:Electrode and separator producers purchase specialized coating and slitting equipment for Tier 2 supply positions.
- Research Institutions:Argonne National Laboratory and university pilot lines drive small-batch formation and characterization equipment demand.
OEMs command the largest procurement volumes. Battery Manufacturers show the fastest contract expansion on dedicated gigafactory investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Vancouver's deepwater container terminals anchor Canadian battery equipment imports, while Union Pacific and BNSF rail corridors stitch together the U.S. Great Lakes manufacturing belt.
United States
Michigan's Detroit-Hamtramck corridor and Tennessee's Chattanooga-Knoxville axis concentrate cylindrical cell assembly line orders from Ford and General Motors. The U.S. Inflation Reduction Act's domestic content thresholds compel electrode coating equipment procurement from regional suppliers with NHTSA-certified thermal management systems. Nevada's Tahoe-Reno Industrial Center hosts Tesla's dry electrode pilot validation.
Canada
Ontario's Windsor-Toronto corridor anchors LG Energy Solution and Stellantis joint venture gigafactory construction, driving demand for prismatic cell stacking equipment. Canada's Strategic Innovation Fund production tax credits match U.S. IRA incentives, redirecting Korean and German equipment vendor sales offices to Oakville and Markham. The St. Lawrence Seaway facilitates heavy formation cycling system delivery to Quebec's emerging battery research cluster.
Mexico
Baja California's Tijuana-Mexicali manufacturing zone attracts electrode slitting and tab welding equipment inquiries driven by USMCA regional value content rules. Querétaro's aerospace-industrial infrastructure repurposes for battery module assembly, with OEMs exploiting labor cost differentials against U.S. Great Lakes operations. The Port of Lázaro Cárdenas offers Pacific Rim equipment import alternatives to congested Long Beach routes.
North America Electric Vehicle Battery Manufacturing Equipment Market Competitive Landscape
Concentration sits with diversified industrial conglomerates and captive OEM engineering divisions rather than pure-play equipment vendors. The supplier base stratifies between turnkey line integrators commanding full-vehicle-program accountability and specialized component vendors serving Tier 2 electrode and separator producers. Two archetypes dominate: German-Japanese precision engineering houses and vertically integrated automotive OEMs with captive equipment specification teams. Competitive moves center on consortia formation for full-line contracts and digital twin capability acquisition to compress commissioning timelines.
Among German-based industrial groups, Dürr AG and Siemens AG exemplify the turnkey integrator archetype, anchoring electrode-to-module line accountability for Korean battery manufacturers in Tennessee and Ontario. Tesla Inc. and Panasonic Energy of North America occupy the captive OEM position, internalizing equipment specification through Nevada and Kansas engineering centers. Hitachi High-Tech Corporation represents the Japanese precision automation tradition, while Manz AG and Nordson Corporation sit within the specialized process equipment tier serving coating and dispensing applications.
| Leading Market Players |
|---|
| A123 Systems |
| Dürr AG |
| Hitachi High-Tech Corporation |
| Manz AG |
| Nordson Corporation |
| Panasonic Energy of North America |
| Siemens AG |
| Tesla Inc. |
| Wuxi Lead Intelligent Equipment |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake contracts between Korean battery manufacturers and German equipment consortia lock in both electrode coating line access and five-year price visibility across Tennessee and Ontario gigafactory builds. These arrangements transfer volume risk to equipment vendors while insulating cell producers from N-methyl-2-pyrrolidone solvent cost spikes.
Pricing Analysis
Volume-discount tiering separates turnkey line integrators from specialized component vendors. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 14644-1 cleanroom certification grade and after-sales service bundling. Pricing pressure stems from OEM consolidation under single-source integrators. Tier 2 electrode producers show highest price sensitivity; captive OEM engineering teams show lowest.
Supply Chain Analysis
N-methyl-2-pyrrolidone solvent supply from China, Japan, and South Korea creates single-source vulnerability for electrode coating equipment operators. Carbide-grade calendering rollers and precision stacking heads draw from German and Japanese machining centers. Tariff exposure on Chinese rare-earth magnets for servo motors concentrates in formation cycling systems. Distribution runs through Union Pacific and BNSF rail corridors to Michigan and Tennessee clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward vertically integrated OEMs as Tesla, Ford, and General Motors consolidate equipment procurement under single-source line integrators, fragmenting the vendor base and compressing margins for standalone equipment suppliers.
For Market Incumbents: Consolidate digital twin capabilities through acquisition of simulation software specialists to defend against Siemens AG-class commissioning advantages. Deepen backward integration into precision machining for calendering rollers to offset carbide supply risk from Japanese sources. Prioritize cleanroom certification investment as EPA hazardous air pollutant rules tighten. For New Entrants and Emerging Players: Differentiate on dry electrode coating equipment for solid-state pilot lines, where Tesla and Panasonic validation protocols create first-mover certification barriers. Target Mexican nearshoring inquiries in Baja California and Querétaro as USMCA content rules redirect tab welding and slitting equipment procurement. Lead with rapid line reconfiguration capabilities for multiformat cylindrical-to-prismatic transitions. For Investors and Strategic Acquirers: Capital is best deployed toward specialized formation cycling vendors with -40°C dewpoint dry-room expertise as solid-state chemistry transitions accelerate. Long-term viability hinges on equipment suppliers capturing recurring service revenue from digital twin commissioning rather than one-time line sales. Watch for EPA finalization of electrode manufacturing emission standards as inflection indicator for thermal oxidizer integration mandates.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Commissioning Capability | Siemens AG and Dürr AG compress yield ramp time through virtual line validation before physical installation. |
| Dry Electrode Coating Process Validation | Tesla and Panasonic Energy of North America eliminate solvent recovery infrastructure through binder-free calendering systems. |
| Mexican Nearshoring Footprint | USMCA regional value content rules draw electrode slitting equipment inquiries to Baja California industrial zones. |
| Solid-State Formation Cycling Specialization | Pilot lines in Nevada and Kansas expand orders for dry-room equipment below -40°C dewpoint specifications. |
| Single-Source Line Integration | SK On and LG Energy Solution award full-line contracts to Korean-German equipment consortia in Tennessee and Ontario. |
Research Methodology
A standing panel of gigafactory project directors, OEM battery platform engineers, Tier 1 equipment procurement managers, and EPA regulatory compliance officers provided ongoing calibration against primary fieldwork. Secondary validation drew from NHTSA battery safety filings, EPA hazardous air pollutant rulemaking dockets, SEC 10-K equipment vendor disclosures, and customs import records for precision machining components. Bottom-up equipment shipment tracking and top-down gigafactory capital expenditure triangulation anchored volume estimates.
Consistency checks against external benchmarks validated projections across the analysis window. Segmentation modeling spanned product type, cell chemistry technology, vehicle application, and end-user procurement archetype. CAGRs derived from equipment vendor backlog analysis and OEM capacity announcement timelines. Forecast inputs incorporated U.S. IRA domestic content threshold phase-ins and Canadian Strategic Innovation Fund matching credit schedules.
Material uncertainties — EPA finalization timelines for electrode manufacturing emission standards, N-methyl-2-pyrrolidone supply chain disruptions, and solid-state chemistry validation failures — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory stability and chemistry transition pace. Practitioners should keep alternative scenarios live as cleanroom certification inspector capacity constraints and multiformat line reconfiguration economics evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Battery Infrastructure
Italy Electric Vehicle Battery Separator Market
Battery Infrastructure
France Electric Vehicle Battery Materials Market
Battery Infrastructure
Lithium-Ion Battery Filling Machine Market
Battery Infrastructure
China Electric Vehicle Battery Electrolyte Market
Battery Infrastructure
United States Electric Vehicle Battery Separator Market
Battery Infrastructure
Global Automotive 48 Volt Battery System Market
Battery Infrastructure
Battery Tray Market
Battery Infrastructure
Battery Enclosure Market
Battery Infrastructure
Carbon Battery Bank Market
Battery Infrastructure
Canada Electric Vehicle Battery Separator Market
Battery Infrastructure
Asia Pacific Electric Vehicle Battery Separator Market
Battery Infrastructure
France Electric Vehicle Battery Manufacturing Equipment Market
Battery Infrastructure
Substation Battery Market
Battery Infrastructure
Germany Electric Vehicle Battery Manufacturing Equipment Market
Battery Infrastructure
Electric Vehicle Battery Swapping Market
Battery Infrastructure
North America Electric Vehicle Battery Separator Market