
 Advance Battery Technologies Market | 2026-2036
Advance Battery Technologies Market Size, Share, and Industry Trends Forecast 2026-2036
Advance Battery Technologies Market Analysis
The capability gap between gigafactory-scale producers and laboratory-stage solid-state developers is bifurcating competitive dynamics across the advance battery sector. Contemporary Amperex Technology Co., Limited leverages integrated cathode material refining and cell assembly to sustain cost leadership in lithium-ion volumes. LG Energy Solution anchors its position through high-nickel chemistry specialization for premium automotive contracts. QuantumScape competes in the solid-state layer, where manufacturing yield challenges still constrain commercial timelines.
Advance battery technologies encompass electrochemical energy storage systems engineered with energy densities exceeding 250 Wh/kg for lithium-ion variants, utilizing layered oxide cathodes and graphite or silicon-composite anodes to deliver reversible electrochemical reactions for portable, vehicular, and stationary power applications. Solid-state configurations replace flammable liquid electrolytes with ceramic or sulfide ionic conductors to enhance thermal stability and enable lithium-metal anodes. Among product type segments, electric vehicles command the dominant margin pool as OEMs negotiate long-term offtake agreements, while grid storage extends the fastest growth trajectory driven by utility-scale renewable pairing requirements. Consumer electronics represents a mature demand tier where cell commoditization limits pricing power.
The US IRA domestic content thresholds and EU Green Deal carbon border adjustments are redirecting capital toward regional cell manufacturing, compelling producers to localize supply chains or forfeit subsidy access. China's MIIT battery passport requirements and SAMR safety standards are raising compliance barriers for imported cells while favoring domestic champions. Japan's METI funding for solid-state R&D and South Korea's MFDS industrial safety protocols add further jurisdictional complexity to global deployment strategies. Stakeholders must monitor how regulatory fragmentation across these regimes reshapes technology licensing decisions and joint venture structures.
Market Dynamics
The advance battery sector is experiencing a fundamental restructuring as subsidy eligibility rules under the US IRA and EU Green Deal force producers to decouple from China-centric supply chains and rebuild capacity across three continents simultaneously.
Growth Catalysts
- IRA Domestic Content Thresholds:US electric vehicle OEMs are accelerating offtake negotiations with regional cell producers to secure tax credit eligibility, redirecting capital toward North American gigafactory construction.
- Solid-State Electrolyte Maturation:Sulfide and oxide ceramic conductors are approaching manufacturing yields sufficient for automotive qualification, unlocking energy densities above 400 Wh/kg for premium EV platforms.
- Grid-Scale Renewable Pairing Mandates:Utility procurement requirements in Germany, Australia, and California are mandating four-hour battery storage as a condition for solar and wind interconnection approvals.
Market Restraints
- Cathode Material Concentration:Over 80% of refined lithium, cobalt, and nickel processing capacity resides in China, creating single-point vulnerability for non-Chinese cell producers.
- Solid-State Manufacturing Yield Deficits:Ceramic electrolyte sintering and lithium-metal anode deposition remain below commercial viability thresholds, constraining scale-up timelines.
- EU Carbon Border Adjustment Mechanism:Import tariffs on embodied carbon are penalizing cells produced with coal-heavy Chinese electricity, eroding cost advantages of incumbent suppliers.
Strategic Opportunities
- India Production-Linked Incentive Scheme:Cell and component manufacturing subsidies are attracting first-mover investments to serve domestic two-wheeler and three-wheeler electrification.
- Aviation Electrification:Regional aircraft and urban air mobility platforms are specifying 300+ Wh/kg pack requirements that favor silicon-anode and solid-state chemistries over conventional lithium-ion.
- Second-Life Stationary Storage:Retired EV packs with 70-80% remaining capacity are being repurposed for grid buffering, creating circular revenue streams independent of raw material supply.
Industry Challenges
- Electrochemical Engineering Talent Scarcity:Cell design, thermal management, and formation protocol expertise is concentrated among a small cohort of specialists, constraining workforce scaling.
- Gigafactory Capital Intensity:Each 30 GWh facility requires $3-5 billion in equipment and construction spend, with payback periods extending beyond typical private equity horizons.
- UN 38.3 and UL 9540A Certification Timelines:Safety testing protocols for new chemistries add 12-18 months to product launch schedules, compressing competitive windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Advance Battery Technologies Market |
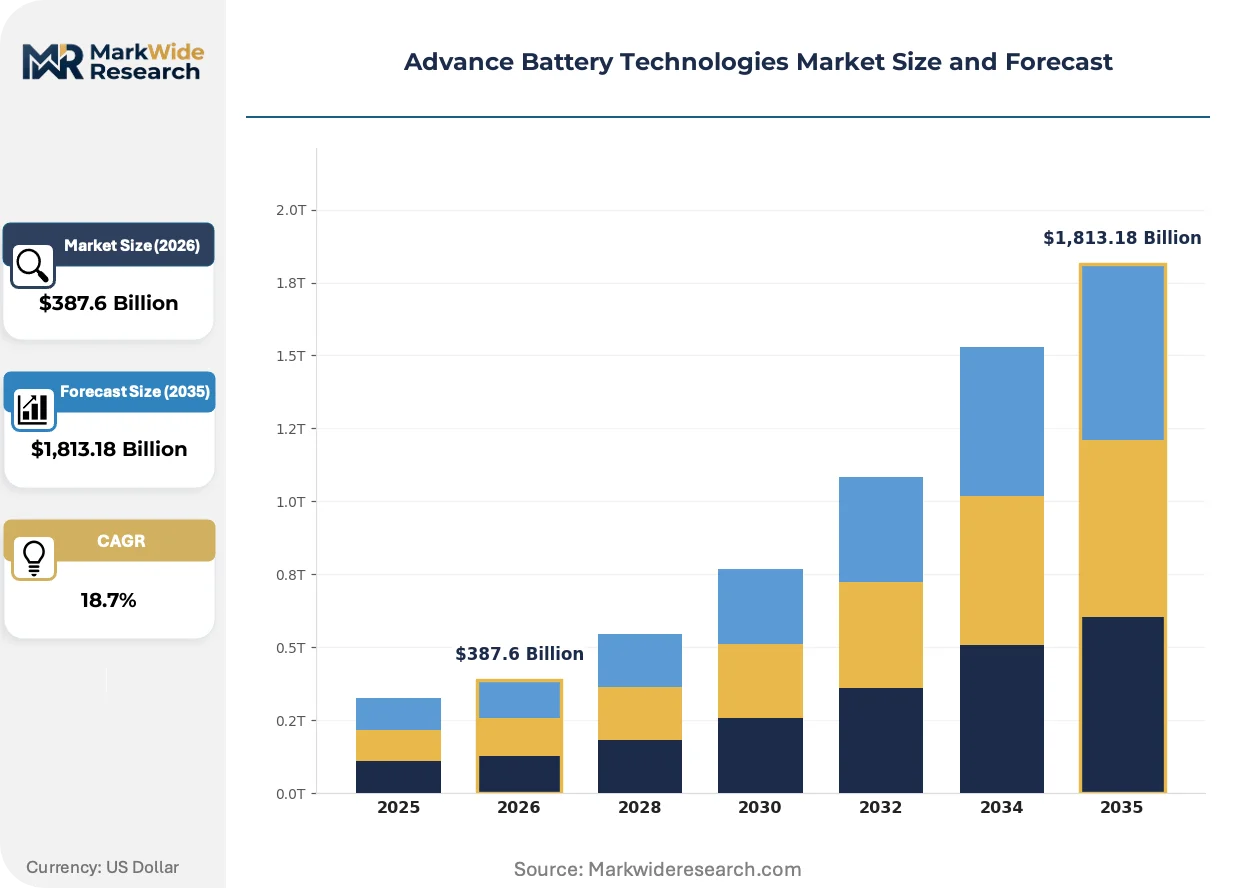
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $1,813.18 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Lithium-Ion, Sodium-Ion, Solid-State, Flow Battery Product Type: Consumer Electronics, Electric Vehicles, Grid Storage, Industrial Use End User: Automotive, Aerospace, Renewable Energy, Telecommunications Application: Energy Storage, Power Tools, Medical Devices, Electric Bicycles |
| Companies Covered | Contemporary Amperex Technology Co., Limited, LG Energy Solution, Panasonic Holdings Corporation, Samsung SDI, BYD Company Limited, SK On, GS Yuasa Corporation, Tesla, Inc., QuantumScape, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Advance Battery Technologies Market Emerging Trajectories
Electrode architecture innovations and regulatory pressure on supply chain provenance are forcing simultaneous advances in material science and manufacturing process control across the battery value chain.
Solid-state battery development is bifurcating competitive positioning between incumbent lithium-ion producers optimizing liquid-electrolyte cost curves and venture-backed developers pursuing ceramic-conductor architectures. Automotive OEMs are splitting procurement budgets between near-term high-nickel cylindrical cells and long-term solid-state pilot programs. This technology divergence is compressing R&D timelines for conventional platforms while extending qualification periods for next-generation formats.
The EU Green Deal carbon border adjustments are reshaping sourcing decisions by imposing embodied-carbon tariffs on imported cells and components. European cell producers are securing renewable power purchase agreements and localizing cathode refining to maintain price competitiveness. Premium automotive segments are absorbing compliance costs through pack-level pricing, while mass-market EV platforms are delaying European launches until regional supply chains mature.
Long-term offtake contracting is displacing spot-market procurement as the dominant volume allocation mechanism. Tier-one automotive OEMs are negotiating five-to-ten-year supply agreements with minimum volume guarantees and price escalation clauses tied to raw material indices. This shift is most visible in Germany and South Korea, where battery producers are committing dedicated production lines to single customers in exchange offtake certainty and co-investment in capacity expansion.
Advance Battery Technologies Market Segmentation
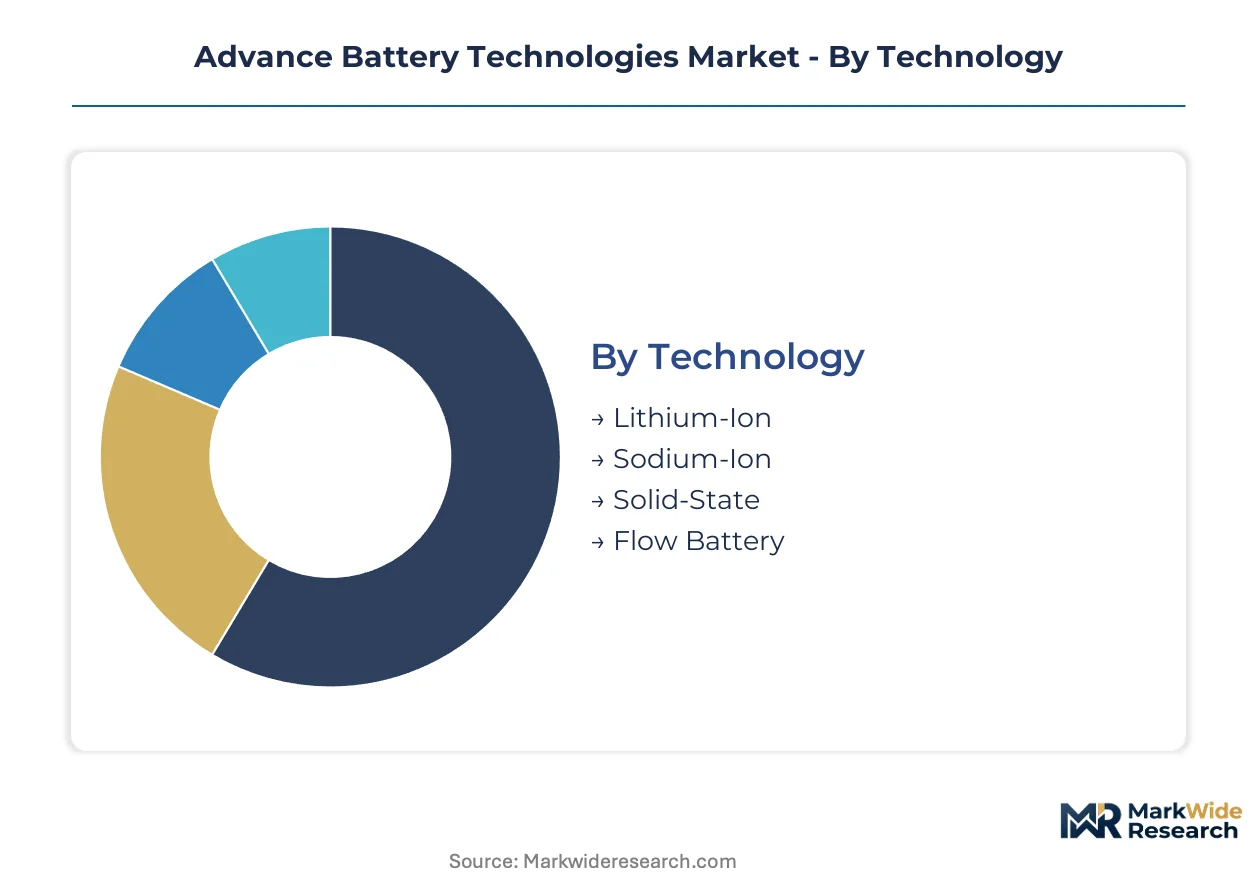
Segmentation in the advance battery sector exposes where incumbent technologies face displacement pressure from next-generation chemistries. Procurement patterns diverge sharply across end-use applications, with automotive and grid storage commanding fundamentally different performance specifications and cost tolerance thresholds.
Technology:
Solid-state and sodium-ion architectures pose the most acute substitution threat to conventional lithium-ion dominance, particularly in applications where energy density or raw material cost sensitivity reshapes procurement calculus.
- Lithium-Ion:Layered oxide cathodes paired with graphite or silicon-composite anodes deliver reversible electrochemical reactions at energy densities exceeding 250 Wh/kg. Automotive OEMs in Germany and South Korea negotiate long-term offtake agreements for high-nickel cylindrical formats, though cathode material concentration in China creates single-point vulnerability for non-Chinese cell producers.
- Solid-State:Ceramic or sulfide ionic conductors replace flammable liquid electrolytes to enable lithium-metal anodes and thermal stability improvements. Sulfide and oxide ceramic conductors are approaching manufacturing yields sufficient for automotive qualification in Japan, where METI funding accelerates R&D timelines toward premium EV platform integration.
- Sodium-Ion:Prussian white cathodes and hard carbon anodes leverage abundant raw materials to bypass lithium supply constraints. India's PLI scheme attracts first-mover investments for two-wheeler and three-wheeler electrification where energy density requirements remain modest.
- Flow Battery:Vanadium or zinc-bromide redox couples stored in external electrolyte tanks enable independent scaling of power and capacity. Utility procurement mandates in California and Germany specify four-hour storage duration for solar and wind interconnection approvals.
Lithium-ion retains volume leadership; solid-state holds the steepest expansion curve.
Product Type:
Margin structures stratify across product types according to pack-level pricing power and commoditization pressure, with electric vehicles capturing premium positioning while consumer electronics faces cell commoditization.
- Electric Vehicles:High-nickel chemistry specialization for premium automotive contracts anchors producer positioning. US IRA domestic content thresholds redirect capital toward North American gigafactory construction as OEMs accelerate offtake negotiations to secure tax credit eligibility.
- Grid Storage:Utility-scale renewable pairing requirements extend the fastest growth trajectory. Germany, Australia, and California mandate four-hour battery storage as a condition for solar and wind interconnection approvals.
- Consumer Electronics:Cylindrical and pouch formats for smartphones, laptops, and wearables represent mature demand tiers where cell commoditization limits pricing power and manufacturer differentiation.
- Industrial Use:Forklift motive power, backup systems, and material handling equipment specify robust cycle life and thermal tolerance over energy density optimization.
Electric vehicles command the dominant margin pool; grid storage is climbing the fastest.
End User:
Customer concentration varies dramatically across end user categories, with automotive consolidating procurement through tier-one OEMs while renewable energy fragments across utility and independent power producer accounts.
- Automotive:Tier-one OEMs negotiate five-to-ten-year supply agreements with minimum volume guarantees and price escalation clauses tied to raw material indices. South Korean battery producers commit dedicated production lines to single customers in exchange for offtake certainty.
- Renewable Energy:Utility and IPP procurement of utility-scale battery storage pairs with solar and wind generation assets. EU Green Deal carbon border adjustments penalize cells produced with coal-heavy Chinese electricity, eroding cost advantages of incumbent suppliers.
- Aerospace:Regional aircraft and urban air mobility platforms specify 300+ Wh/kg pack requirements that favor silicon-anode and solid-state chemistries. Aviation electrification creates specification pull beyond conventional lithium-ion capabilities.
- Telecommunications:Base station backup power and remote infrastructure specify long calendar life and wide temperature operation over energy density.
Automotive dominates procurement concentration; renewable energy is gaining share fastest.
Application:
Application-level segmentation reveals where battery performance requirements diverge from commodity specifications toward specialized electrochemical engineering.
- Energy Storage:Stationary systems for grid buffering and renewable integration specify cycle life, round-trip efficiency, and safety certification over gravimetric energy density. Retired EV packs with 70-80% remaining capacity create circular revenue streams through second-life repurposing.
- Power Tools:Cordless professional equipment demands high discharge rates and mechanical durability under vibration and impact loads.
- Medical Devices:Implantable and portable diagnostic equipment requires biocompatibility, hermetic sealing, and predictable degradation curves under FDA and EMA regulatory pathways.
- Electric Bicycles:Two-wheeler electrification in India and Southeast Asia specifies cost-optimized cell formats with moderate energy density and simplified battery management systems.
Energy storage retains volume leadership; electric bicycles hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies, with price-sensitive emerging markets prioritizing cost-optimized sodium-ion cells while premium automotive segments in developed economies absorb solid-state premiums.
China
Domestic EV manufacturers drive procurement of high-nickel cylindrical formats at scale. MIIT battery passport requirements and SAMR safety standards raise compliance barriers for imported cells. Ningde in Fujian Province anchors cathode material refining and cell assembly clusters serving both domestic OEMs and export markets.
United States
IRA domestic content thresholds redirect automotive OEM procurement toward regional gigafactory construction. FERC interconnection rules and state-level renewable storage mandates accelerate utility-scale battery procurement. Nevada and Texas host expanding cell manufacturing campuses tied to offtake agreements with Detroit and California-based automakers.
Germany
Premium automotive OEMs negotiate five-to-ten-year supply agreements with minimum volume guarantees. EU Green Deal carbon border adjustments penalize cells produced with coal-heavy electricity. Saxony and Thuringia concentrate cell assembly and cathode precursor production facilities serving Volkswagen and BMW supply chains.
Japan
Solid-state R&D programs target automotive qualification timelines for premium EV platforms. METI funding accelerates sulfide and oxide ceramic conductor development toward manufacturing viability. Kyoto and Osaka prefectures host materials science clusters advancing lithium-metal anode deposition techniques.
South Korea
High-nickel chemistry specialization anchors producer positioning for premium automotive contracts. MFDS industrial safety protocols add jurisdictional complexity to cell export strategies. Gyeonggi-do and Chungcheong provinces concentrate electrode coating and formation facilities serving Hyundai-Kia supply chains.
Advance Battery Technologies Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the advance battery sector. The market structure concentrates volume among integrated lithium-ion producers with captive cathode refining, while solid-state developers occupy a separate competitive layer constrained by manufacturing yield challenges. Three archetypes dominate: integrated gigafactory operators optimizing liquid-electrolyte cost curves, high-nickel chemistry specialists serving premium automotive contracts, and venture-backed solid-state developers pursuing ceramic-conductor architectures. Capacity expansion and strategic partnerships represent the dominant competitive moves, with producers securing long-term offtake agreements in exchange for co-investment in regional manufacturing.
Within the integrated gigafactory tier, Contemporary Amperex Technology Co., Limited and BYD Company Limited represent Chinese producers with backward integration into cathode material refining. LG Energy Solution and Samsung SDI exemplify South Korean specialists in high-nickel cylindrical formats. QuantumScape occupies a position within the solid-state developer archetype, where manufacturing yield constraints still separate laboratory performance from commercial scale.
| Leading Market Players |
|---|
| Contemporary Amperex Technology Co., Limited |
| LG Energy Solution |
| Panasonic Holdings Corporation |
| Samsung SDI |
| BYD Company Limited |
| SK On |
| GS Yuasa Corporation |
| Tesla, Inc. |
| QuantumScape |
| Others |
Supply Flow & Price Mechanics
Sodium-ion cell chemistry displacing lithium-ion in India's two-wheeler segment simultaneously redraws raw material procurement maps and compresses pack-level pricing floors, as cathode active material costs diverge from lithium carbonate spot volatility.
Pricing Analysis
After-sales revenue from second-life stationary storage repurposing and extended performance warranties now drives lifetime value capture for cell producers. Contract-based long-term offtake agreements dominate volume allocation, with price differentiation resting on cathode chemistry grade and UL 9540A certification tier. Cost compression in standard-format cylindrical cells is intensifying because Chinese producers are absorbing EU carbon border adjustment penalties to maintain export share. Mass-market automotive OEMs exhibit highest price sensitivity, while premium EV platforms absorb solid-state premiums.
Supply Chain Analysis
Inventory lead times for lithium hexafluorophosphate electrolyte salts and high-purity spherical graphite now stretch 16-24 weeks, constraining cell formation scheduling flexibility. Cathode precursor refining concentrates in China, South Korea, and Japan; anode material processing draws from China and Japan. Single-source vulnerability in refined cobalt sulfate from the Democratic Republic of Congo creates geopolitical exposure. Distribution runs through gigafactory-direct contracts with automotive OEMs and utility-scale EPC contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Battery passport interoperability and cross-OEM pack standardization are creating platform-economics inflection, as charging infrastructure and second-life repurposing networks reward modular, swappable designs over proprietary formats.
For Market Incumbents: Fortify cathode material refining positions through backward integration into lithium hydroxide conversion, defending against sodium-ion substitution in cost-sensitive segments. Secure IRA-compliant North American cell assembly capacity before domestic content thresholds tighten. Solid-state manufacturing yield deficits represent the priority R&D lever for premium positioning. For New Entrants and Emerging Players: Aviation electrification service-layer gaps expose under-served demand for 300+ Wh/kg pack qualification support and airworthiness certification consulting. Target regional aircraft and urban air mobility platforms where incumbent lithium-ion producers lack specialized engineering bandwidth. Go-to-market through airframe OEM engineering partnerships rather than commodity cell supply. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed solid-state electrolyte developers holding automotive qualification partnerships but requiring manufacturing scale capital. Long-term viability hinges on sulfide ceramic conductor yield convergence within a decade. Watch for METI funding allocation shifts as inflection signal for Japanese solid-state commercialization timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Automotive OEMs lock five-to-ten-year offtake with volume guarantees tied to nickel price indices. |
| Backward Integration | Cell producers acquire cathode precursor refining to secure IRA domestic content eligibility. |
| Technology Licensing | Solid-state developers license ceramic conductor IP to Asian gigafactory operators for pilot production. |
| Joint Venture | European producers partner with renewable power developers to secure carbon-neutral electricity for EU Green Deal compliance. |
| Capacity Buildout | Indian PLI scheme attracts first-mover sodium-ion investments for two-wheeler electrification demand. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with cell engineering directors, cathode material procurement leads, automotive platform battery specialists, utility-scale storage project developers, and solid-state R&D program managers. Secondary validation drew from MIIT battery passport filings, US IRA domestic content guidance documents, EU Green Deal carbon border adjustment implementing acts, and FERC interconnection queue data. Bottom-up cell shipment aggregation and top-down EV production forecast reconciliation enabled triangulation across modeling approaches.
Across the analysis window, volume and value outputs reflect segmentation by technology chemistry, product type tier, end-use application, and regional regulatory cluster. CAGRs were derived from installed capacity buildout trajectories and content-per-vehicle evolution. Forecast inputs incorporated lithium carbonate price volatility scenarios and solid-state manufacturing yield improvement curves.
Forecasts assume regulatory continuity in US IRA domestic content rules and EU Green Deal carbon border adjustments; material policy shifts would require re-modeling. Technology substitution timelines and raw material supply disruptions represent specific revision risks. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Battery Infrastructure
Automotive Battery Plate Market
Battery Infrastructure
Battery Production Machine Market
Battery Infrastructure
North America Electric Vehicle Battery Manufacturing Equipment Market
Battery Infrastructure
Battery Tray Market
Battery Infrastructure
Automatic Battery Manufacturing Equipment Market
Battery Infrastructure
South America Electric Vehicle Battery Separator Market
Battery Infrastructure
Italy Electric Vehicle Battery Separator Market
Battery Infrastructure
Middle East and Africa Electric Vehicle Battery Separator Market
Battery Infrastructure
ASEAN Countries Electric Vehicle Battery Separator Market
Battery Infrastructure
Europe Electric Vehicle Battery Separator Market
Battery Infrastructure
Lithium-Ion Battery Filling Machine Market
Battery Infrastructure
Battery Maintenance Service Market
Battery Infrastructure
Battery Enclosure Market
Battery Infrastructure
China Electric Vehicle Battery Electrolyte Market
Battery Infrastructure
Global Automotive 48 Volt Battery System Market
Battery Infrastructure
North America Electric Vehicle Battery Separator Market