
 China Electric Vehicle Battery Manufacturing Equipment Market | 2026-2036
China Electric Vehicle Battery Manufacturing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
China Electric Vehicle Battery Manufacturing Equipment Market Insights
GB/T certification for battery manufacturing equipment is bifurcating the competitive landscape into qualified system integrators and second-tier component vendors. Wuxi Lead Intelligent Equipment Co Ltd leverages its vertical integration across coating and winding systems to sustain pricing power in domestic tenders. Shenzhen Yinghe Technology anchors its position through specialization in laser welding and assembly automation for prismatic cells. Schuler AG competes by extending its European press expertise into Chinese joint ventures for electrode calendering.
China electric vehicle battery manufacturing equipment encompasses the machinery, control systems, and process automation required to produce lithium-ion and next-generation solid-state cells at scale, with line speeds now exceeding 200 ppm for cylindrical formats and dry electrode coating emerging as a disruptive process alternative. The primary purpose is to enable mass production of cells meeting strict energy density, cycle life, and safety specifications for automotive and energy storage applications. Electrode Coating Machines dominate capital expenditure allocation due to their direct impact on cell performance and yield, while Testing Equipment represents the fastest-expanding margin pool as in-line defect detection and formation cycling become mandatory for quality assurance. Battery Cell Equipment maintains structural importance as the integration layer where stacking, winding, and tab welding determine throughput consistency.
MIIT equipment qualification standards and GB/T safety protocols shape vendor eligibility for state-backed NEV supply chain investments, while SAMR enforcement of metrology calibration rules raises compliance costs for imported toolsets. MEE environmental audits on solvent recovery and NMP emissions from coating lines are forcing equipment retrofits and greenfield designs with closed-loop recycling. Stakeholders must monitor how Beijing's evolving equipment localization mandates and solid-state pilot line subsidies reshape supplier qualification criteria and capital allocation timelines.
Market Dynamics
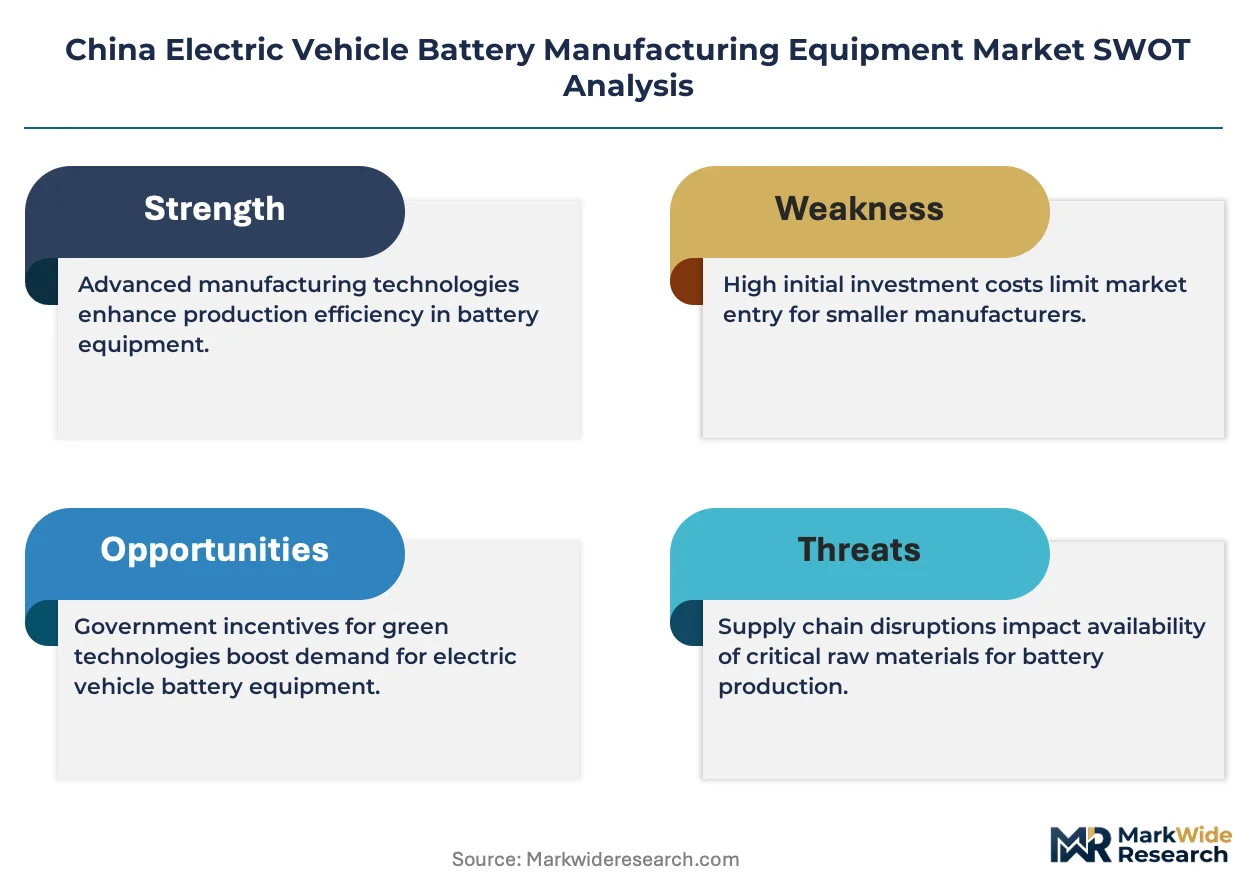
GB/T certification requirements and MIIT equipment qualification standards are concentrating procurement authority among state-approved system integrators, squeezing second-tier vendors from state-backed NEV supply chain tenders.
Growth Catalysts
- Dual Carbon Goals:Beijing's 2030 carbon peak mandate accelerates gigafactory buildouts in Jiangsu and Guangdong provinces, forcing equipment procurement cycles to compress.
- NEV Mandates:Domestic OEM procurement quotas for locally sourced battery manufacturing equipment create captive demand for certified coating and formation testing systems.
- Dry Electrode Coating:Solvent-free electrode manufacturing eliminates NMP recovery infrastructure, reducing line capex and environmental compliance burdens for greenfield plants.
Market Restraints
- Import Toolset Calibration Costs:SAMR metrology enforcement raises compliance expenses for European and Japanese precision measurement equipment, extending qualification timelines.
- Lithium Supply Concentration:Raw material processing bottlenecks in Qinghai and Sichuan provinces transmit volatility into electrode coating machine order backlogs.
- Technical Limitation in Solid-State:Sulfide electrolyte handling requirements exceed current dry room specifications, delaying pilot line equipment standardization.
Strategic Opportunities
- Fujian Province Buildouts:CATL's Ningde headquarters expansion creates secondary demand clusters for laser welding and assembly automation vendors outside traditional Jiangsu-Guangdong axes.
- Energy Storage Applications:Grid-scale battery procurement from State Grid Corporation opens parallel equipment demand for formation testing systems with extended cycle protocols.
- MEE Closed-Loop Subsidies:Environmental audit incentives for solvent recovery retrofits create aftermarket service contracts for existing coating line upgrades.
Industry Challenges
- Control Systems Integration:Legacy SCADA architectures from 2015-2018 equipment vintages conflict with new MIIT cybersecurity protocols for industrial data transmission.
- Specialized Technician Scarcity:Dry electrode process expertise resides with limited personnel from pilot programs, constraining commissioning velocity for commercial line deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Electric Vehicle Battery Manufacturing Equipment Market |
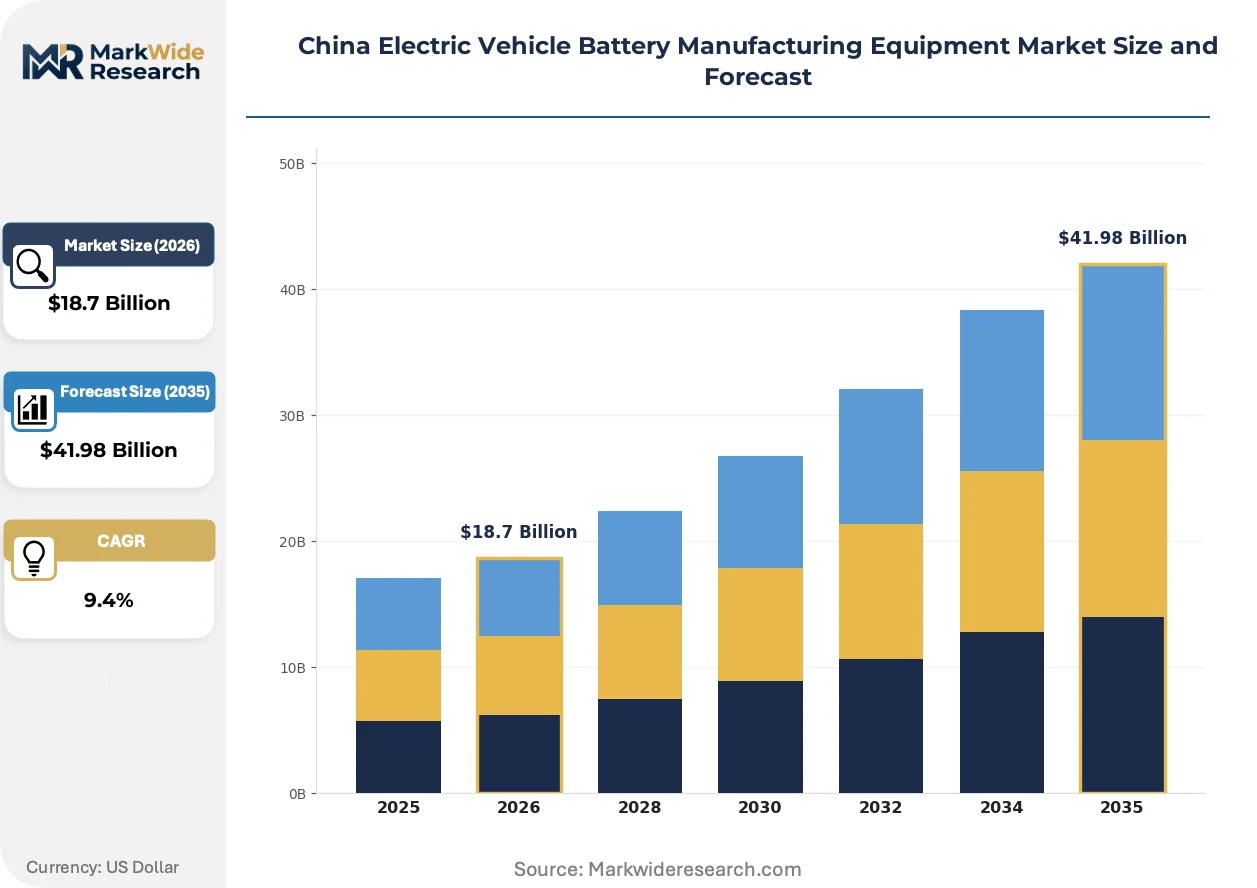
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrolyte Filling Machines, Electrode Coating Machines, Battery Cell Equipment, Testing Equipment Technology: Lithium-ion, Solid-state, Nickel-cadmium, Lithium Iron Phosphate Application: Automotive, Energy Storage, Consumer Electronics, Industrial End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Research Institutions |
| Companies Covered | Xiamen Lith Machine Limited, Wuxi Lead Intelligent Equipment Co Ltd, Schuler AG, Hitachi Ltd, Xiamen Tmax Battery Equipments Limited, Manz AG, Hitachi High-Tech, Shenzhen Yinghe Technology, Nanjing Tiansu Automation Equipment, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Electric Vehicle Battery Manufacturing Equipment Market Trends and Innovations
Dry electrode coating is decomposing traditional solvent-based manufacturing economics while regulatory pressure on NMP emissions accelerates process substitution timelines across Chinese gigafactory investments.
Dry electrode coating eliminates solvent recovery infrastructure and reduces drying oven energy consumption by removing NMP-based slurry preparation. BYD and CATL are piloting this technology for cylindrical cell lines in 2025-2026 commissioning windows. The process is decomposing incumbent coating machine vendor revenue models tied to solvent handling system sales and recurring NMP recovery maintenance contracts.
MIIT equipment qualification standards now mandate in-line defect detection and formation cycling data traceability for state-backed NEV supply chain investments. This regulatory tightening disqualifies non-certified vendors from tender participation and raises software validation burdens for imported testing equipment. High-speed stacking and winding systems face the steepest compliance redesign requirements as cell throughput specifications exceed 200 ppm.
Buyers are consolidating procurement authority under dedicated equipment engineering divisions within CATL, BYD, and Gotion High-Tech, displacing distributed plant-level purchasing. Centralized technical specification teams now dictate coating machine and formation testing requirements across multiple gigafactory sites. This concentration is most visible in Jiangsu province where Wuxi-based procurement hubs coordinate equipment selection for dispersed manufacturing footprints.
China Electric Vehicle Battery Manufacturing Equipment Market Segmentation
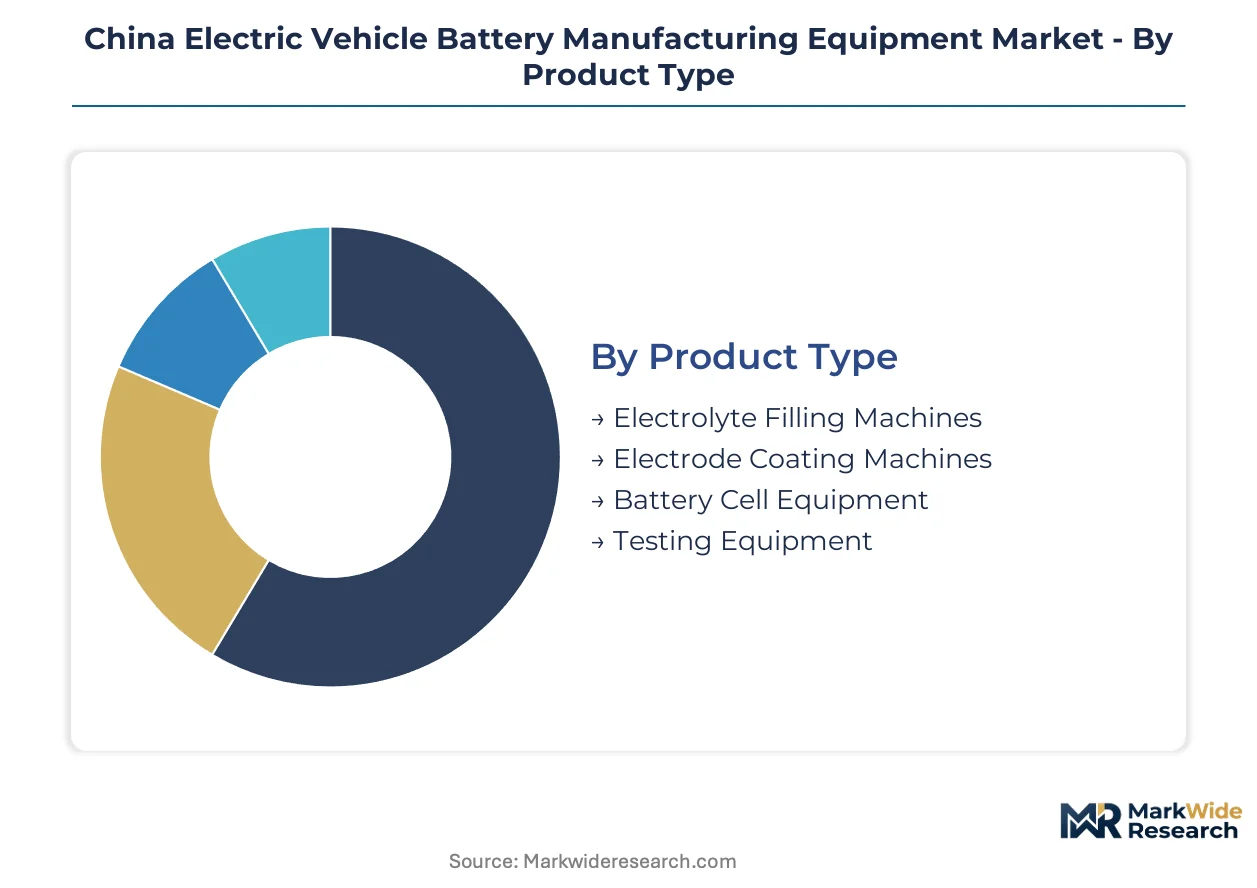
Equipment segmentation in China's battery manufacturing landscape reveals how capital allocation priorities shift between process stages and customer archetypes. MIIT qualification standards and GB/T certification requirements create divergent margin profiles across product categories, while technology roadmaps from CATL and BYD reshape application-level demand patterns.
Product Type:
Margin pools concentrate heavily in precision coating and in-line quality assurance systems where technical barriers protect pricing power.
- Electrode Coating Machines:These systems apply active material slurries to copper and aluminum foils with thickness tolerances below 2 micrometers, directly determining cell energy density and yield rates. Jiangsu province gigafactories in Changzhou and Wuxi drive procurement volume as CATL and BYD expand cylindrical and prismatic cell capacity under Beijing's dual carbon mandates. The dominant share belongs to Electrode Coating Machines, while Testing Equipment is closing the gap fastest.
- Testing Equipment:Formation cycling systems and in-line defect detection platforms verify cell performance across voltage, impedance, and thermal stability parameters. Guangdong procurement hubs in Shenzhen and Dongguan prioritize this category as MIIT data traceability requirements harden for state-backed NEV investments.
- Electrolyte Filling Machines:Precision dosing systems inject liquid electrolyte into cell housings under vacuum conditions, with Wuxi Lead Intelligent Equipment dominating domestic tender participation.
- Battery Cell Equipment:Stacking, winding, and tab welding modules integrate into continuous production lines where throughput specifications now exceed 200 ppm for cylindrical formats.
Capital expenditure tilts toward coating and testing as yield assurance becomes non-negotiable for automotive qualification.
Technology:
Process chemistry determines equipment architecture requirements and dry room specifications across Chinese manufacturing footprints.
- Lithium-ion:Conventional liquid electrolyte cells dominate installed capacity, with solvent-based coating lines requiring NMP recovery infrastructure and MEE environmental compliance audits. Fujian province CATL headquarters and Jiangsu gigafactories anchor equipment demand.
- Solid-state:Sulfide and oxide electrolyte formats demand ultra-low humidity environments below -60°C dew point, with pilot line equipment standardization delayed by materials handling constraints. The dominant technology remains Lithium-ion, though Solid-state is expanding most quickly in pilot investments.
- Lithium Iron Phosphate:LFP chemistry favors prismatic cell formats with simpler thermal management requirements, driving procurement of stacking equipment over winding systems.
- Nickel-cadmium:Legacy chemistry persists in industrial backup power applications with minimal equipment refresh demand.
Equipment vendors must architect platforms accommodating both incumbent liquid electrolyte dominance and solid-state pilot transitions.
Application:
End-use specifications fragment equipment requirements between automotive cycle life demands and grid-scale formation protocols.
- Automotive:Passenger vehicle battery packs demand cells exceeding 300 Wh/kg energy density with 1,000+ cycle lifespans, concentrating precision coating investment in Jiangsu and Guangdong OEM supply chains. The dominant application is Automotive, while Energy Storage is gaining share fastest.
- Energy Storage:Grid-scale systems from State Grid Corporation prioritize extended cycle protocols and safety certification, opening parallel demand for formation testing equipment with slower charge-discharge specifications.
- Consumer Electronics:Cylindrical cell formats for power tools and portable devices sustain mid-volume equipment demand with less stringent automotive qualification burdens.
- Industrial:Forklift and stationary backup applications tolerate lower energy density cells with reduced coating precision requirements.
Application diversification forces equipment platforms to span high-precision automotive and cost-optimized storage configurations.
End User:
Procurement authority centralization under dedicated engineering divisions reshapes vendor engagement models across customer tiers.
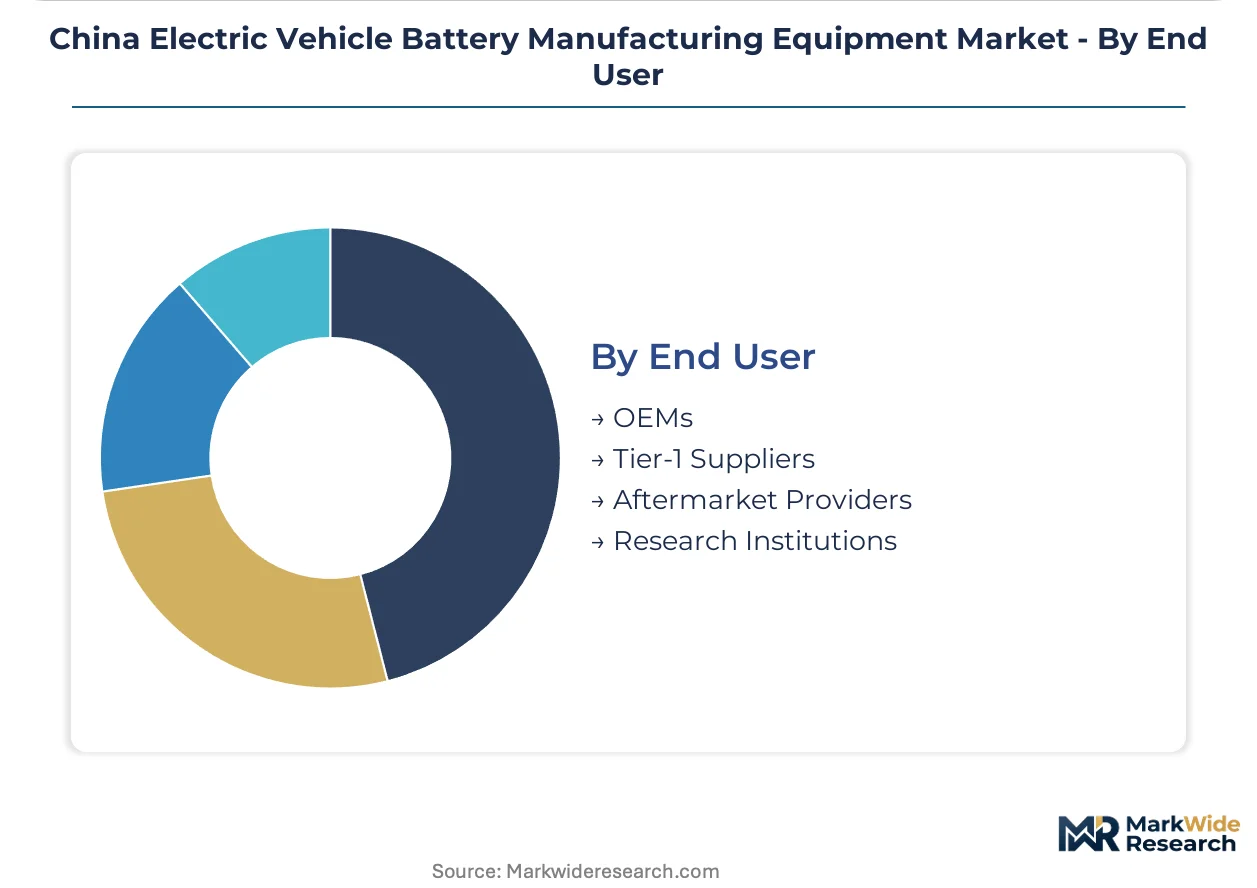
- OEMs:BYD, CATL, and Gotion High-Tech maintain captive equipment specification teams that dictate technical requirements across dispersed gigafactory footprints, consolidating tender participation for qualified system integrators. The dominant end user category is OEMs, while Tier-1 Suppliers are climbing fastest as outsourcing expands.
- Tier-1 Suppliers:Cell module integrators and pack assemblers procure secondary equipment for welding and assembly automation, particularly in Guangdong supplier clusters.
- Research Institutions:Chinese Academy of Sciences and university pilot lines drive small-volume demand for flexible coating and testing platforms with rapid reconfiguration capabilities.
- Aftermarket Providers:Cell replacement and refurbishment operations sustain limited equipment demand for disassembly and diagnostic systems.
Vendor strategies must navigate centralized OEM procurement alongside emerging Tier-1 supplier outsourcing channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment procurement authority concentrates under centralized engineering divisions at domestic OEMs, with geographic clustering following gigafactory placement decisions rather than traditional industrial distribution patterns.
Jiangsu Province
CATL and BYD cylindrical cell expansions in Changzhou and Wuxi drive coating machine demand with line speed specifications exceeding 200 ppm. MIIT equipment qualification standards mandate GB/T certification for all state-backed tender participation. Wuxi-based procurement hubs coordinate technical specifications across dispersed manufacturing footprints, consolidating vendor selection authority.
Guangdong Province
Shenzhen and Dongguan clusters prioritize formation testing equipment as MIIT data traceability requirements harden for NEV investments. SAMR metrology enforcement raises compliance costs for imported precision measurement toolsets. BYD's Shenzhen headquarters anchors laser welding and assembly automation procurement for prismatic cell lines.
Fujian Province
CATL's Ningde headquarters expansion creates secondary demand clusters outside traditional Jiangsu-Guangdong axes. MEE environmental audits on solvent recovery infrastructure force coating line retrofits with closed-loop recycling designs. Local equipment vendors capture aftermarket service contracts for existing NMP recovery system upgrades.
Sichuan Province
Qinghai-Sichuan lithium processing bottlenecks transmit raw material volatility into electrode coating machine order backlogs. Dual carbon goals accelerate western China gigafactory placement to access cleaner hydropower grids. Chengdu-Chongqing corridor attracts greenfield investments with lower environmental compliance burdens for dry electrode pilot lines.
Beijing-Tianjin-Hebei
State Grid Corporation grid-scale battery procurement opens parallel equipment demand for formation testing with extended cycle protocols. Solid-state pilot line subsidies from Beijing reshape supplier qualification criteria for sulfide electrolyte handling systems. Research institutions in the capital region drive small-volume demand for flexible coating platforms with rapid reconfiguration capabilities.
China Electric Vehicle Battery Manufacturing Equipment Market Competitive Landscape
Player mix skews toward domestic system integrators with MIIT certification and European precision equipment specialists operating through joint venture structures. The competitive landscape bifurcates between qualified vendors eligible for state-backed NEV tenders and second-tier component suppliers excluded from centralized procurement. Two strategic archetypes dominate: vertically integrated coating-to-winding specialists and precision measurement equipment providers adapting to SAMR calibration requirements. Competitive moves center on backward integration into control systems and geographic expansion through Fujian province secondary clusters.
Among domestic equipment fabricators, Wuxi Lead Intelligent Equipment Co Ltd and Shenzhen Yinghe Technology exemplify the certified system integrator archetype with established positions in state tender participation. Schuler AG represents the European precision engineering presence adapting press expertise to Chinese joint venture structures. These three anchors illustrate how vendor qualification criteria concentrate procurement authority among entities meeting GB/T certification and MIIT equipment standards.
| Leading Market Players |
|---|
| Xiamen Lith Machine Limited |
| Wuxi Lead Intelligent Equipment Co Ltd |
| Schuler AG |
| Hitachi Ltd |
| Xiamen Tmax Battery Equipments Limited |
| Manz AG |
| Hitachi High-Tech |
| Shenzhen Yinghe Technology |
| Nanjing Tiansu Automation Equipment |
| Others |
Pricing and Supply Chain Analysis
Dry electrode coating substitution for solvent-based processes simultaneously shifts procurement geography toward western China and collapses legacy pricing premiums tied to NMP recovery infrastructure. Equipment vendors with captive coating-to-winding integration capture margin expansion as line economics restructure around eliminated solvent handling costs.
Pricing Analysis
Cost-plus contracts with lithium carbonate indexation dominate electrode coating machine procurement, transferring raw material volatility directly to OEM buyers. Pricing stratifies across MIIT-certified system integrators, qualified component vendors, and non-certified second-tier suppliers. Cost compression in formation testing equipment intensifies as centralized procurement teams at BYD and CATL standardize specifications across multiple gigafactory sites. Tier-1 suppliers exhibit highest price sensitivity due to constrained module assembly margins, while captive OEM equipment engineering divisions prioritize qualification compliance over unit cost.
Supply Chain Analysis
Strategic stockpiling of precision motion control components and laser welding heads supersedes just-in-time preferences as SAMR calibration timelines extend for imported metrology equipment. Supply concentrates in Germany for press systems, Japan for precision measurement toolsets, and China for coating and winding integration. The ecosystem draws from lithium hydroxide processing in Qinghai, copper foil rolling in Jiangsu, and ceramic separator production in Guangdong. Single-source vulnerability in high-speed stacking modules creates bottleneck exposure. Distribution runs through centralized procurement hubs in Wuxi and Shenzhen coordinating dispersed manufacturing footprints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-moat defensive story where MIIT equipment qualification standards create switching costs that lock qualified vendors into state-backed NEV supply chain tenders.
For Market Incumbents: Shield certified positions by deepening backward integration into control systems software and expanding service contracts for existing coating line retrofits. Dry electrode pilot scaling threatens solvent-based equipment incumbency. Prioritize commissioning velocity capabilities to capture compressed procurement cycles under dual carbon mandates. For New Entrants and Emerging Players: Anchor in Fujian province secondary clusters around CATL's Ningde headquarters expansion, where geographic diversification creates tender participation windows outside entrenched Jiangsu-Guangdong vendor relationships. Energy storage formation testing with extended cycle protocols offers the most penetrable application segment. Pursue joint venture structures with European precision engineering specialists to bypass SAMR calibration barriers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed coating machine specialists holding MIIT certification but lacking control systems integration depth. Five-to-ten year viability hinges on solid-state pilot line equipment standardization timelines. Watch sulfide electrolyte handling system breakthroughs as the inflection signal for equipment architecture transitions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Control Systems | MIIT cybersecurity protocols for industrial data transmission favor vendors with in-house SCADA architectures. |
| Dry Electrode Process Scale-Up | Elimination of NMP recovery infrastructure reduces greenfield line capex and environmental compliance burdens. |
| Fujian Province Geographic Expansion | CATL's Ningde headquarters expansion creates secondary demand clusters outside traditional procurement axes. |
| Energy Storage Application Diversification | State Grid Corporation procurement opens parallel equipment demand with extended cycle protocol specifications. |
| MIIT Certification Investment | GB/T standards bifurcate competitive landscape into qualified system integrators and excluded second-tier vendors. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with equipment procurement directors at CATL and BYD, formation testing engineering leads, coating machine vendor sales executives, and MEE environmental audit specialists. Secondary validation drew from MIIT equipment qualification databases, SAMR metrology enforcement notices, customs trade data on precision component imports, and SEC filings of listed equipment fabricators. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators for the NEV supply chain.
Across the analysis window, forecasts incorporate product type segmentation by electrode coating machines, testing equipment, electrolyte filling systems, and cell assembly modules; technology segmentation spanning lithium-ion, solid-state, and LFP chemistries; and end-user segmentation across OEMs, Tier-1 suppliers, and research institutions. CAGRs derive from equipment procurement cycle analysis, gigafactory capacity buildout pipelines, and regulatory mandate implementation timelines. Specific inputs include dry electrode pilot line commissioning schedules and solid-state sulfide handling system standardization progress.
Decision-makers should treat outputs as directional under assumptions of sustained dual carbon policy enforcement and lithium supply chain stability; material deviation would warrant model refresh. Revision becomes warranted when solid-state pilot line equipment standardization crosses commercial viability thresholds or MEE environmental audit intensity shifts substantially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Battery Infrastructure
Lithium-Ion Battery Housing Cases Market
Battery Infrastructure
Carbon Battery Bank Market
Battery Infrastructure
Italy Electric Vehicle Battery Separator Market
Battery Infrastructure
Battery-As-A-Service Market
Battery Infrastructure
Solar Containers Market
Battery Infrastructure
North America Electric Vehicle Battery Manufacturing Equipment Market
Battery Infrastructure
Battery Lug Market
Battery Infrastructure
China Battery Manufacturing Equipment Market
Battery Infrastructure
Battery Maintenance Service Market
Battery Infrastructure
Global Automotive 48 Volt Battery System Market
Battery Infrastructure
ASEAN Countries Electric Vehicle Battery Manufacturing Equipment Market
Battery Infrastructure
France Electric Vehicle Battery Separator Market
Battery Infrastructure
Battery Enclosure Market
Battery Infrastructure
Battery Swap-Ready Pack Systems for Urban Fleets Market
Battery Infrastructure
South America Electric Vehicle Battery Separator Market
Battery Infrastructure
Battery Tray Market