
 Global Automotive 48 Volt Battery System Market | 2026-2036
Global Automotive 48 Volt Battery System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive 48 Volt Battery System Market Analysis
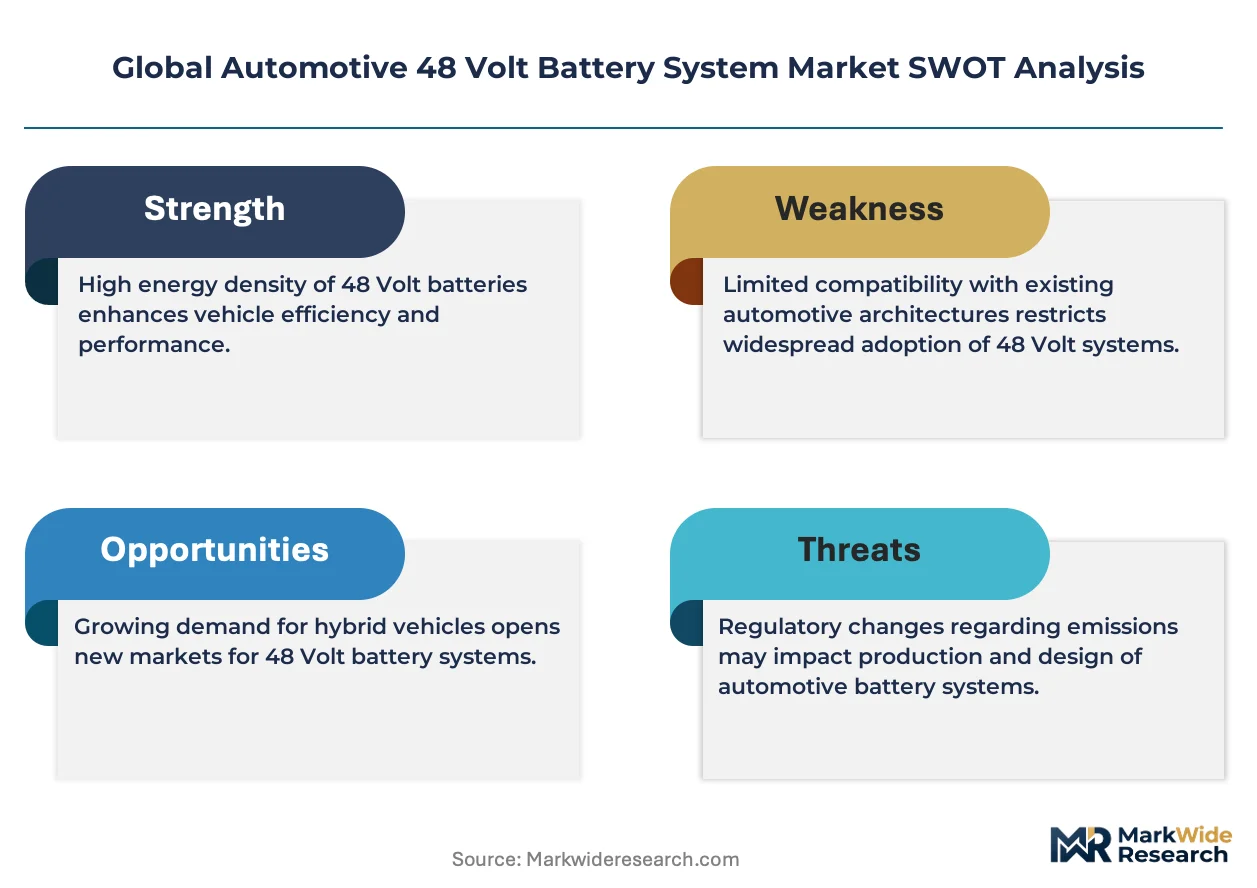
ISO 26262 functional safety certification is unwinding competitive access across the 48V battery supply chain, raising capital barriers for new entrants. Robert Bosch GmbH leverages captive semiconductor and cell-pack integration to sustain full-system dominance. Continental AG anchors its position through dedicated 48V inverter-motor-battery module production in Germany. Valeo SA competes on thermal management integration, bundling battery cooling with its electrification portfolio.
Automotive 48 volt battery systems combine lithium-ion or lead-acid cell packs with DC-DC converters and battery management electronics, operating at 48 volts to enable mild-hybrid power assist without full high-voltage architecture costs. The technology primarily serves start-stop enhancement, torque-fill during acceleration, and regenerative energy recovery in internal-combustion vehicles transitioning toward electrification. Lithium-ion chemistry leads product type segmentation due to superior cycle life and power density for repeated charge-discharge events. Passenger vehicles dominate end-user demand as OEMs deploy 48V systems across C-segment and above to meet tightening CO2 thresholds without full hybrid cost premiums. Regenerative braking technology captures the fastest growth trajectory within the technology segment, driven by its direct fuel economy contribution and software-defined recuperation strategies.
The EPA tailpipe standards, EU Green Deal vehicle CO2 mandates, and China's MIIT new energy vehicle credit system collectively shape 48V system penetration rates and technical specifications across their respective jurisdictions. NHTSA safety protocols and ECE R100 variant standards further govern battery enclosure integrity and electrical isolation requirements for road certification. Stakeholders must monitor how regulatory stringency divergence between the EPA and EU frameworks influences platform engineering decisions and regional production allocation.
Market Dynamics
Europe's F-Gas Regulation and CO2 fleet mandates are forcing powertrain electrification at the 48V tier, compressing engineering timelines and concentrating procurement decisions among German, Chinese, and American OEM assembly plants.
Growth Catalysts
- EU Green Deal vehicle CO2 mandates:OEMs deploy 48V mild-hybrid architectures across C-segment and above platforms to avoid fleet-average penalties without absorbing full hybrid cost premiums.
- Regenerative braking software:Advanced recuperation algorithms maximize energy recovery during deceleration events, delivering measurable fuel economy gains that satisfy EPA tailpipe certification thresholds.
- German OEM assembly concentration:Volkswagen, BMW, and Mercedes-Benz retooling at Wolfsburg, Munich, and Stuttgart plants creates localized demand spikes for integrated 48V module supply.
Market Restraints
- Lithium carbonate price volatility:Cell pack input costs fluctuate with South American and Australian mining output, squeezing margin predictability for system integrators.
- ISO 26262 functional safety certification:The ASIL-D compliance timeline extends 18-24 months, freezing competitive access for capital-constrained entrants lacking captive semiconductor fabrication.
- High-voltage hybrid substitution:Toyota and Honda full hybrid systems at 200V+ architectures threaten 48V relevance in markets where consumer willingness-to-pay supports electrification premiums.
Strategic Opportunities
- Indian passenger vehicle electrification:Maruti Suzuki and Tata Motors platform refreshes introduce 48V mild-hybrid options to meet BIS efficiency norms without full powertrain redesign.
- MIIT new energy vehicle credit system:China's point-based manufacturer incentives reward 48V deployment as a compliance bridge technology during the transition to pure battery electric platforms.
- Battery-thermal management convergence:Valeo and Mahle bundle cooling circuits with 48V packs, creating integrated subsystem offerings that command premium positioning against standalone component suppliers.
Industry Challenges
- Functional safety engineering talent scarcity:ASIL-certified firmware developers and battery management system architects command compensation premiums that inflate R&D overhead for mid-tier suppliers.
- Legacy 12V electrical architecture integration:DC-DC converter design must maintain backward compatibility with existing body electronics, wiring harnesses, and diagnostic protocols across multi-generational vehicle platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive 48 Volt Battery System Market |
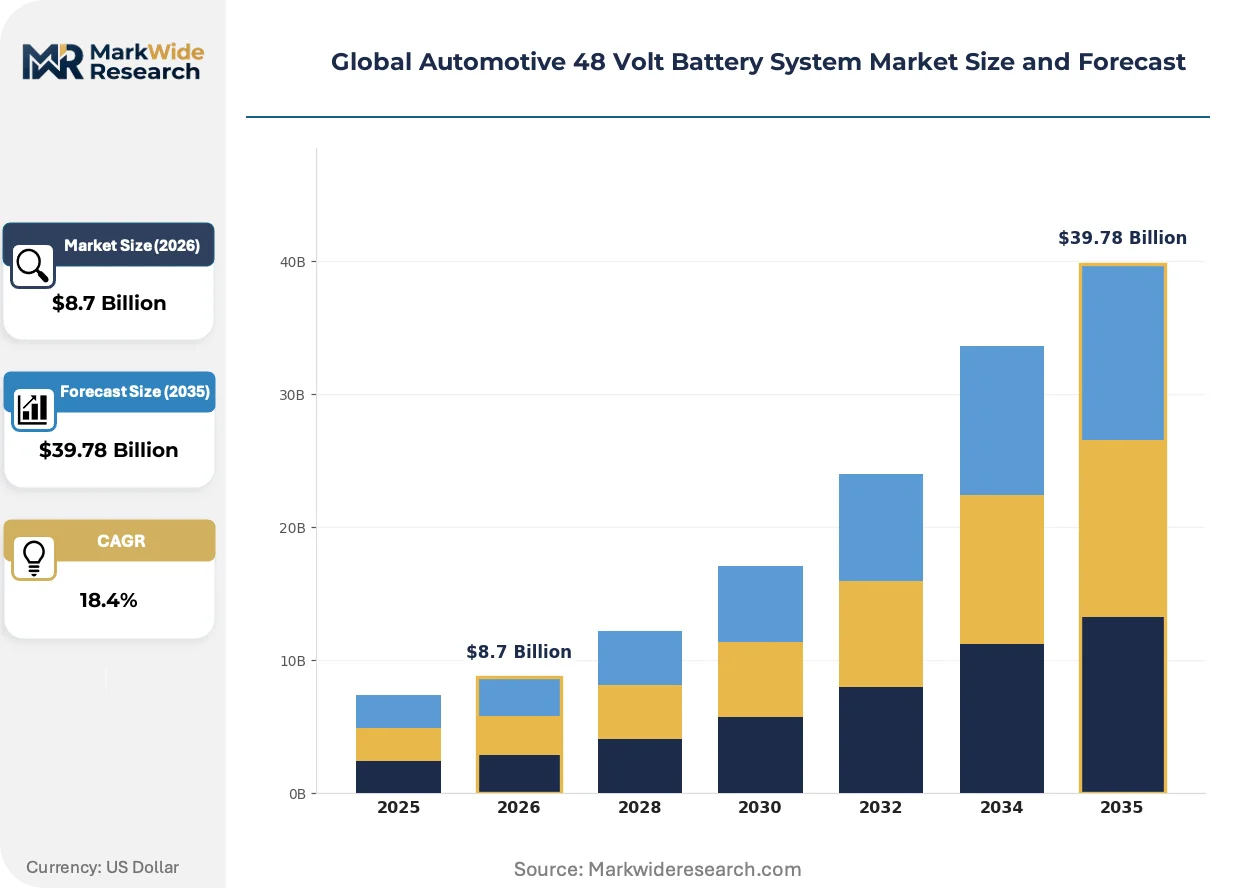
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lead-Acid, Lithium-Ion, Nickel-Metal Hydride, Solid-State End User: Passenger Vehicles, Commercial Vehicles, Motorcycles, Electric Bicycles Technology: Regenerative Braking, Start-Stop Technology, Hybrid Systems, Advanced Energy Management Application: Power Assist, Electrification, Energy Recovery, Auxiliary Power |
| Companies Covered | Robert Bosch GmbH, BorgWarner Inc., Continental AG, Valeo SA, Magna International Inc., Lear Corporation, Dana Incorporated, Mitsubishi Electric Corporation, Denso Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive 48 Volt Battery System Market Emerging Trajectories
Silicon carbide power electronics and solid-state cell chemistries are compressing 48V system footprints while software-defined recuperation strategies extract incremental efficiency gains from existing hardware investments.
Lithium iron phosphate chemistry is supplanting nickel-manganese-cobalt formulations in 48V cell packs due to superior thermal stability and cycle life under repeated shallow discharge conditions. Chinese OEMs at BYD and CATL partnerships have accelerated adoption since 2022. This chemistry shift is enabling thinner module packaging that preserves cabin and cargo space in compact vehicle architectures.
EPA tailpipe standards and their divergence from EU Green Deal trajectory are fragmenting platform engineering decisions for multinational OEMs. The US framework emphasizes fleet-average gram-per-mile targets that favor 48V deployment in light truck segments. German engineering centers now maintain parallel powertrain calibration streams to satisfy both jurisdictions without common global architectures.
Fleet procurement departments at rental and commercial leasing operators now specify 48V mild-hybrid availability as a residual value protection mechanism. Hertz and Enterprise Holdings volume agreements with Ford and General Motors prioritize fuel economy certification tiers over absolute acquisition cost. This specification behavior concentrates most visibly in California and New York markets where state-level efficiency mandates amplify federal requirements.
Global Automotive 48 Volt Battery System Market Segmentation
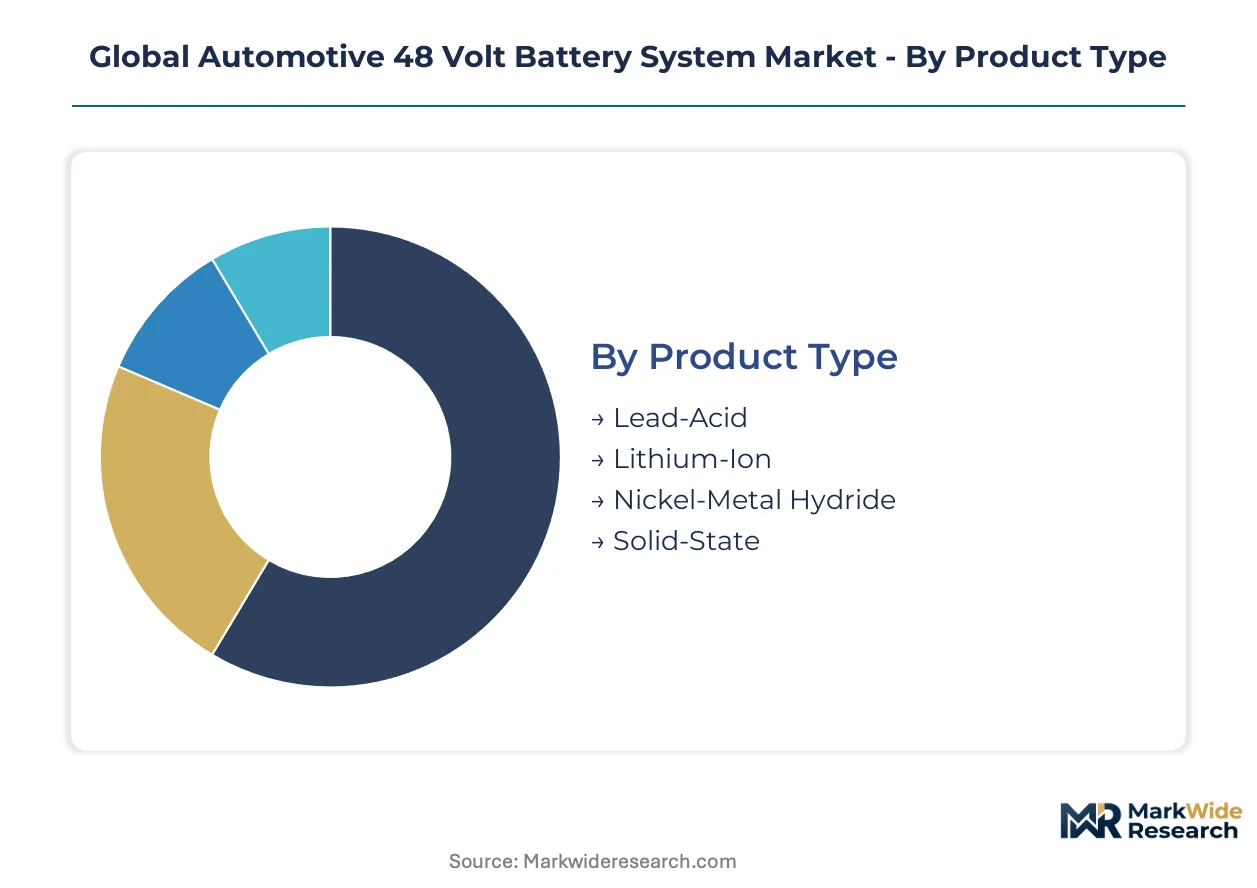
Segmentation in the 48V battery market reveals how chemistry choices, vehicle applications, and technology tiers map to distinct procurement channels and margin profiles. Each dimension carries implications for certification requirements, thermal management complexity, and OEM platform integration timelines.
Product Type:
Channel distribution varies sharply by chemistry: lithium-ion flows through tier-one system integrators to German and Chinese OEMs, while lead-acid retains aftermarket and light-commercial channels.
- Lithium-Ion:Dominant chemistry for mild-hybrid architectures requiring repeated shallow discharge cycles and superior power density. Demand concentrates in C-segment and above passenger vehicles from Volkswagen, BMW, and Mercedes-Benz assembly plants as EU CO2 fleet mandates tighten compliance windows.
- Lead-Acid:Lower-cost option for entry-level start-stop applications with limited regenerative capability. Volume runs through aftermarket distributors serving legacy vehicle parc and light-commercial fleets in India and Southeast Asia where cost sensitivity overrides cycle-life requirements.
- Nickel-Metal Hydride:Mature chemistry with established recycling infrastructure, primarily serving commercial vehicle auxiliary power units where thermal stability outweighs energy density priorities.
- Solid-State:Emerging cell architecture promising thinner packaging and enhanced safety profiles. Toyota and QuantumScape partnerships are accelerating prototype validation for next-generation 48V modules.
Lithium-ion dominates installed base. Solid-state is where expansion concentrates.
End User:
Customer type determines specification stringency: passenger vehicle OEMs demand ASIL-D functional safety, while commercial operators prioritize total-cost-of-ownership metrics.
- Passenger Vehicles:Primary volume driver encompassing C-segment sedans through luxury SUVs. German OEM platform refreshes at Wolfsburg, Munich, and Stuttgart plants anchor procurement concentration.
- Commercial Vehicles:Delivery van and light-truck segments adopt 48V for auxiliary power and stop-start fuel savings. Ford Transit and Mercedes-Benz Sprinter configurations lead deployment.
- Motorcycles:Premium touring and adventure bike segments from BMW Motorrad and Ducati integrate 48V for electric supercharger assist and enhanced start-stop smoothness.
- Electric Bicycles:Cargo e-bike and speed-pedelec categories in the Netherlands and Germany utilize 48V packs for extended range and hill-climb torque support.
Passenger vehicles command revenue concentration. Electric bicycles are climbing the fastest as urban mobility regulations tighten across Northern Europe.
Technology:
Technology tier correlates with software content and calibration complexity, directly impacting supplier margin structure and OEM engineering resource allocation.
- Regenerative Braking:Software-defined recuperation algorithms maximize energy recovery during deceleration events. EPA tailpipe certification thresholds in the United States and EU Green Deal mandates in Europe are driving adoption across light-truck segments where fuel economy gains translate directly to compliance credits.
- Start-Stop Technology:Entry-level 48V application enhancing idle shutdown smoothness and restart speed. Bosch and Continental supply integrated starter-generator modules to Volkswagen Group and Stellantis platforms.
- Hybrid Systems:Integrated motor-generator configurations delivering torque-fill during acceleration. Mercedes-Benz M256 inline-six and BMW B58 engines incorporate this architecture.
- Advanced Energy Management:Predictive battery state-of-charge optimization using navigation and traffic data. Valeo and Harman collaborations are piloting cloud-connected variants.
Start-stop technology holds the broadest installed base. Advanced energy management is gaining share fastest as software-defined vehicle architectures mature.
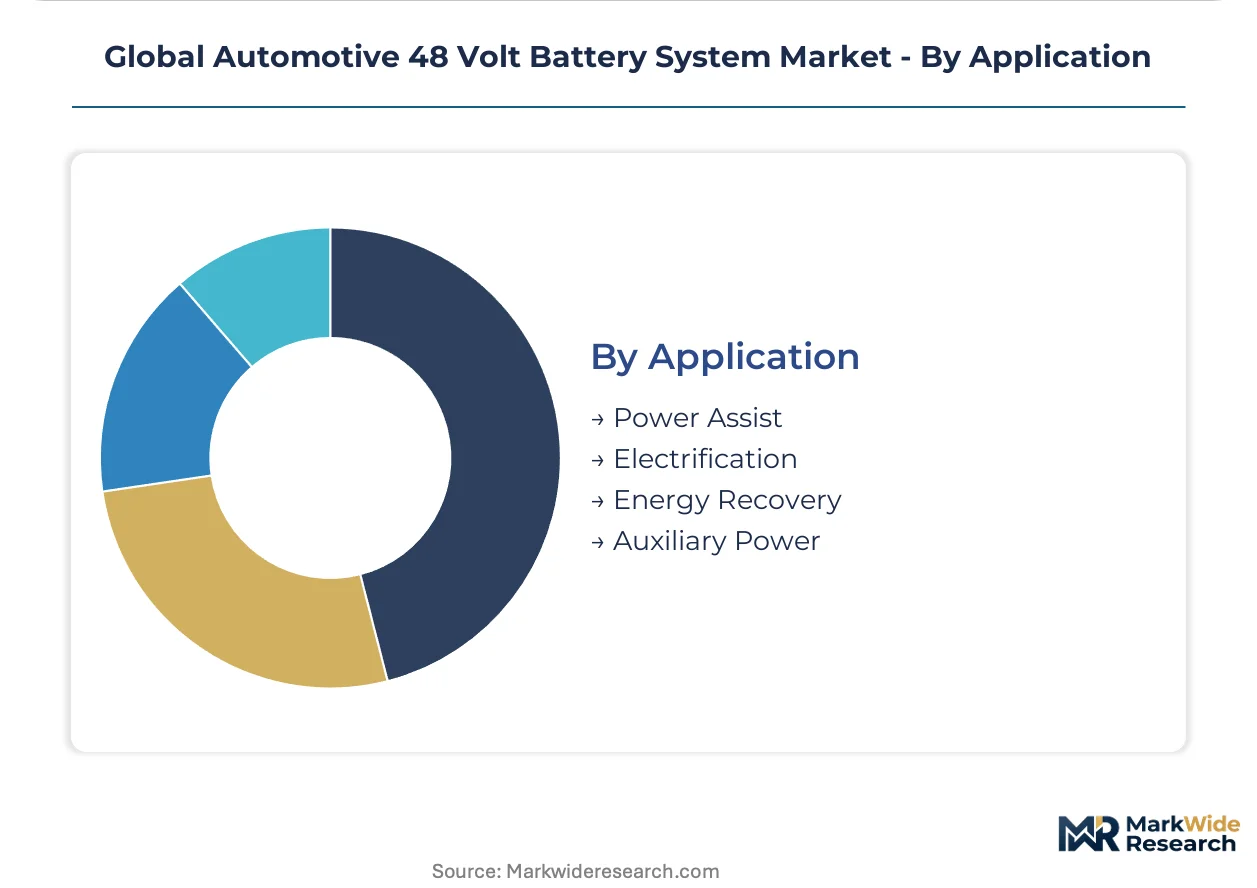
Application:
Application focus determines thermal management requirements and DC-DC converter specification, with power assist demanding the most sophisticated cell balancing electronics.
- Power Assist:Integrated starter-generator delivering torque supplementation during launch and overtaking maneuvers. Audi and Porsche deployment in MLB Evo platforms demonstrates performance-tier validation.
- Electrification:48V subsystem enabling electric air conditioning, active anti-roll bars, and other high-load accessories without engine loading. BMW 48V mild-hybrid variants utilize this approach.
- Energy Recovery:Dedicated recuperation-focused configurations optimizing charge acceptance during braking events. Mazda Skyactiv-X 48V implementations prioritize this function.
- Auxiliary Power:Standalone 48V supply for commercial vehicle hotel loads, tool power, and refrigeration units. Fleet specifications from Hertz and Enterprise Holdings are incorporating this capability.
Power assist commands premium positioning. Electrification applications are expanding most quickly as electrical load demands outgrow legacy 12V architecture capacity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's container throughput anchors Germany's role as the primary European entry point for lithium-ion cell imports from Asian suppliers. This maritime infrastructure underwrites the concentration of 48V battery system assembly across German OEM plants.
United States
Detroit's automotive corridor drives procurement concentration as Ford and General Motors retool Michigan assembly plants for 48V mild-hybrid truck platforms. EPA tailpipe standards favor 48V deployment in light truck segments where gram-per-mile fleet averaging creates compliance pressure. The Detroit-Hamtramck and Dearborn Truck plants represent the densest North American demand cluster for integrated 48V modules.
Germany
Wolfsburg, Munich, and Stuttgart anchor European 48V system demand as Volkswagen, BMW, and Mercedes-Benz accelerate platform electrification. The EU Green Deal vehicle CO2 mandates compress engineering timelines for C-segment and above refreshes. Continental AG's dedicated 48V inverter-motor-battery module production in Lower Saxony reinforces the regional supply chain concentration.
China
Shanghai's Yangshan Deep Water Port facilitates lithium carbonate import flows that feed CATL and BYD cell manufacturing partnerships. MIIT new energy vehicle credit system rewards 48V deployment as a compliance bridge technology during the transition to pure battery electric platforms. The Yangtze River Delta manufacturing belt concentrates domestic OEM assembly for Geely and SAIC Motor 48V platform launches.
India
Maruti Suzuki's Gujarat assembly complex and Tata Motors' Pune operations introduce 48V mild-hybrid options to meet BIS efficiency norms. The country's national automotive regulator mandates corporate average fuel economy standards that 48V architectures satisfy without full powertrain redesign. Tamil Nadu and Maharashtra states host the fastest-expanding supplier park development for DC-DC converter and battery management system localization.
Japan
Toyota City and Nagoya manufacturing clusters prototype solid-state 48V cell architectures through Toyota-QuantumScape partnerships. METI industrial policy supports next-generation battery chemistry development with targeted R&D subsidies. The Chubu region's precision electronics supply chain enables advanced battery management system semiconductor fabrication for domestic OEM integration.
Global Automotive 48 Volt Battery System Market Vendor Landscape
Listed leaders compete with private specialists across functional safety certification tiers, creating a bifurcated competitive structure. ASIL-D compliance timelines extend 18-24 months, freezing access for capital-constrained entrants. Three archetypes dominate: captive semiconductor fabricators with in-house cell-pack integration, dedicated inverter-motor-battery module producers, and thermal management bundlers. Capacity expansion and backward integration into semiconductor supply represent the primary competitive moves.
Among German-based system integrators, Robert Bosch GmbH and Continental AG occupy positions spanning full-system and module-specialist archetypes respectively. Valeo SA exemplifies the thermal management convergence strategy. BorgWarner Inc. represents North American-scale fabrication capabilities. These companies anchor the competitive structure without exhausting the vendor landscape.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| BorgWarner Inc. |
| Continental AG |
| Valeo SA |
| Magna International Inc. |
| Lear Corporation |
| Dana Incorporated |
| Mitsubishi Electric Corporation |
| Denso Corporation |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts between German OEMs and South Korean cell suppliers lock in lithium-ion supply access while constraining price visibility for mid-tier integrators lacking equivalent procurement scale. This contract structure concentrates margin pressure on standalone battery management system vendors competing for residual module assembly volume.
Pricing Analysis
Volume-discount tiering separates ASIL-D certified system integrators from uncertified component suppliers across premium, standard, and economy levels. Pricing stratifies across certification grade and captive semiconductor fabrication capability, with Bosch and Continental commanding premium positioning. Cost compression in entry-level lead-acid replacements is intensifying because Indian OEMs prioritize acquisition cost over cycle-life metrics. Commercial fleet procurement departments exhibit lowest price sensitivity due to residual value protection specifications.
Supply Chain Analysis
Germany and China anchor 48V module assembly while South Korea and Japan feed precision semiconductor fabrication. The supply chain draws from Chilean and Australian lithium carbonate, German copper winding substrates, and Taiwanese power management ICs. Single-source vulnerability concentrates in ASIL-D certified battery management system firmware where qualified engineering talent scarcity limits supplier diversification. Distribution runs through Tier 1 system integrators directly to OEM assembly plants with limited aftermarket channel penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal CO2 mandates and EPA tailpipe standard divergence are accelerating 48V mild-hybrid deployment as a compliance bridge technology, creating high-growth disruption for powertrain electrification suppliers.
For Market Incumbents: Shield market position through captive semiconductor fabrication investments that compress ASIL-D certification timelines below competitor reach. Deepen backward integration into lithium iron phosphate cell chemistry partnerships with CATL and BYD to secure thermal-stable supply. High-voltage hybrid substitution from Toyota and Honda 200V+ architectures threatens 48V relevance in premium willingness-to-pay segments. For New Entrants and Emerging Players: Aftermarket thermal management retrofit services represent a service-layer gap where incumbents under-serve legacy vehicle parc operators. Penetrate Indian passenger vehicle electrification through Maruti Suzuki and Tata Motors platform refresh cycles where BIS efficiency norms drive 48V adoption without full hybrid cost premiums. Pursue DC-DC converter localization partnerships with Tamil Nadu supplier park development as the primary go-to-market angle. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated specialists with in-house semiconductor fabrication and established OEM platform engineering relationships. The five-to-ten year viability window favors suppliers positioned across both 48V mild-hybrid and full battery electric architectures. Monitor solid-state cell chemistry validation timelines at Toyota-QuantumScape partnerships as the primary inflection signal for next-generation module packaging disruption.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | CATL and BYD partnerships with German OEMs secure lithium iron phosphate chemistry access for EU CO2 compliance. |
| Software-Defined Vehicle Investment | Predictive energy management algorithms using navigation data differentiate Valeo and Harman cloud-connected offerings. |
| Geographic Manufacturing Footprint | Continental AG's Lower Saxony production anchors localized 48V module supply for Volkswagen Group platforms. |
| Platform Standardization | MLB Evo architecture deployment across Audi and Porsche concentrates procurement for integrated starter-generator modules. |
| Charging Infrastructure Partnership | Fleet agreements with Hertz and Enterprise Holdings prioritize 48V mild-hybrid availability for residual value protection. |
Methodological Framework
Operator-level perspectives from OEM platform engineers, Tier 1 supplier procurement leads, aftermarket distributors, and dealership operations anchored the qualitative base for this study. Primary interviews combined with secondary validation from vehicle production databases, IHS Markit registration data, SEC filings, and customs trade records. Bottom-up segment sizing triangulated against top-down OEM production planning disclosures.
Sensitivity analysis tested volume and value outputs across vehicle class, propulsion architecture, content per vehicle, and regional production cluster dimensions throughout the forecast period. CAGRs derived from modeled unit shipment trajectories weighted by lithium-ion versus lead-acid chemistry mix and ASIL certification tier penetration. Forecast inputs incorporated MIIT credit system evolution, EPA tailpipe standard stringency scenarios, and lithium carbonate price volatility bands.
Forecasts assume regulatory continuity in EU Green Deal vehicle CO2 mandates, EPA tailpipe standards, and China's MIIT new energy vehicle credit system; material policy shifts would require re-modeling. Specific risks include high-voltage hybrid substitution acceleration, solid-state chemistry commercialization timelines, and ISO 26262 certification requirement changes. Recalibration cycles align with material shifts in named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Battery Infrastructure
Battery Enclosure Market
Battery Infrastructure
Germany Electric Vehicle Battery Separator Market
Battery Infrastructure
EV Battery Sealant Market
Battery Infrastructure
Germany Electric Vehicle Battery Manufacturing Equipment Market
Battery Infrastructure
Europe Electric Vehicle Battery Separator Market
Battery Infrastructure
South America Electric Vehicle Battery Separator Market
Battery Infrastructure
China Electric Vehicle Battery Electrolyte Market
Battery Infrastructure
France Electric Vehicle Battery Separator Market
Battery Infrastructure
France Electric Vehicle Battery Materials Market
Battery Infrastructure
Advance Battery Technologies Market
Battery Infrastructure
Substation Battery Market
Battery Infrastructure
Battery Tray Market
Battery Infrastructure
Global Battery Technology Market
Battery Infrastructure
Automotive Battery Plate Market
Battery Infrastructure
Carbon Battery Bank Market
Battery Infrastructure
Battery-As-A-Service Market