
 Global Quinine Sulphate Market | 2026-2036
Global Quinine Sulphate Market Size, Share, and Industry Trends Forecast 2026-2036
Global Quinine Sulphate Market Foresight
Modular API sourcing is recalibrating how pharmaceutical buyers contract for quinine sulphate, shifting from long-term single-supplier agreements to multi-source qualification programs. Sanofi leverages its integrated alkaloid extraction network to secure cinchona bark supply chains across South American growing regions. GlaxoSmithKline plc anchors its position through sustained investment in antimalarial R&D pipelines that absorb high-purity pharmaceutical-grade material.
Quinine sulphate is a salt derivative of the cinchona alkaloid, typically manufactured with minimum purity thresholds and crystalline morphology specifications that determine dissolution rates in tablet formulations; it serves primarily as an active pharmaceutical ingredient for antimalarial combination therapies and as a bittering agent in regulated beverage applications. Pharmaceutical-grade material dominates value capture due to stringent pharmacopeial compliance costs, while food additive-grade volumes are accelerating fastest as tonic water producers in craft beverage segments expand bittering agent procurement. Laboratory-grade supply occupies specialized margin pools tied to analytical reference standard contracts.
FDA, EMA, and WHO prequalification standards collectively shape market access by mandating impurity profiling and stability testing protocols that filter out non-compliant producers. India's CDSCO and the EU's REACH framework add overlapping compliance layers for export-oriented manufacturers. Stakeholders must monitor evolving pharmacopeial monograph revisions and cinchona cultivation sustainability certifications that could restrict bark-derived supply availability.
Market Dynamics
Modular API sourcing is fragmenting long-term supplier relationships as pharmaceutical buyers in malaria-endemic regions diversify procurement across multiple qualified sources to mitigate cinchona bark supply volatility.
Growth Catalysts
- WHO Prequalification Program:The tightening of purity standards for essential antimalarial medicines is filtering out substandard producers and consolidating demand around compliant API manufacturers.
- India:Domestic formulation capacity expansion in Indian pharmaceutical hubs is accelerating local procurement of pharmaceutical-grade quinine sulphate for export-oriented combination therapies.
- Cinchona Cultivation Certification:Emerging sustainability verification systems for South American bark sourcing are opening premium supply channels for ethically qualified extractors.
Market Restraints
- Cinchona Bark Concentration:Overreliance on Ecuador, Peru, and Bolivia for raw alkaloid extraction creates geographic supply vulnerability to climate disruption and export policy shifts.
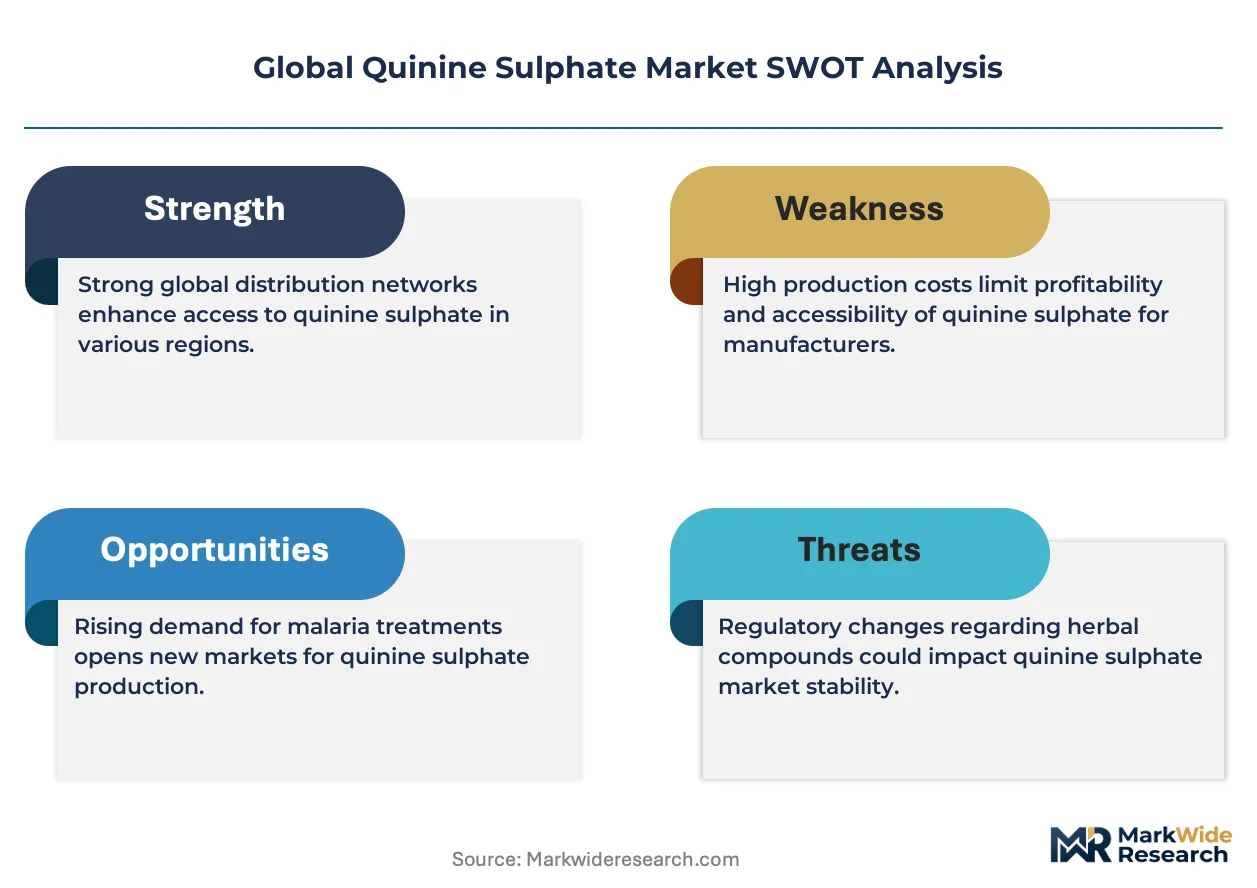
- Synthetic Substitute Threat:Artemisinin-based combination therapies continue displacing quinine-derived first-line treatments in WHO treatment guidelines for uncomplicated malaria.
- REACH Compliance Burden:EU chemical registration requirements impose documentation costs that exclude smaller API producers from European pharmaceutical supply chains.
Strategic Opportunities
- Kenya and Nigeria:Underpenetrated local formulation capacity in East and West African markets creates openings for integrated API-to-tablet manufacturing investments.
- Craft Beverage Bittering:Premium tonic water producers are expanding procurement of food-grade quinine sulphate as a differentiated ingredient in regulated beverage applications.
- Continuous Flow Chemistry:Convergence of automated synthesis platforms with real-time impurity monitoring is enabling smaller-batch pharmaceutical-grade production with reduced solvent waste.
Industry Challenges
- Pharmacopeial Analytical Talent:Scarcity of specialists in ICH Q3D elemental impurity testing and stability protocol design constrains laboratory capacity expansion at mid-tier API manufacturers.
- Multi-Jurisdiction Certification Timelines:Sequential FDA, EMA, and WHO prequalification reviews extend product launch cycles by 18-36 months for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Quinine Sulphate Market |
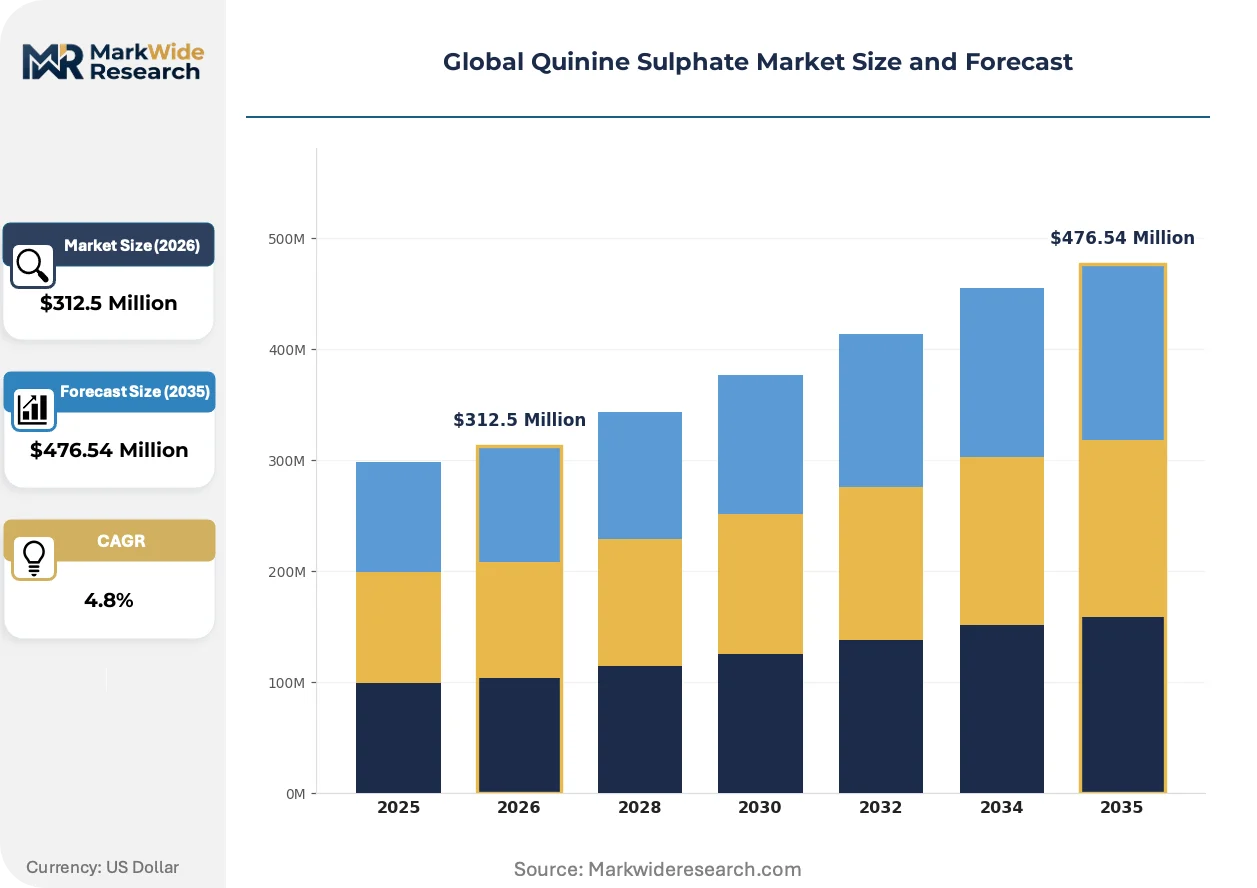
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $476.54 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pharmaceutical Grade, Food Additive Grade, Laboratory Grade, Cosmetic Grade Application: Antimalarial Treatment, Food Flavoring, Beverage Production, Chemical Research End User: Pharmaceutical Manufacturers, Food & Beverage Companies, Cosmetic Producers, Research Institutions Packaging Type: Bulk Containers, Retail Bottles, Sachets, Laboratory Vials |
| Companies Covered | Sanofi, GlaxoSmithKline plc, Wockhardt, Actavis, Shreeji Pharma International, Novartis AG, Cipla Limited, A. B. Enterprises, Teva Pharmaceutical Industries Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Quinine Sulphate Market Shifts & Advancements
Digital batch records and spectroscopic in-line monitoring are compressing quality assurance cycles while regulatory data integrity requirements reshape how API producers document process control.
Continuous manufacturing platforms for alkaloid salt production are unifying extraction, purification, and crystallization into integrated processing trains. Mid-sized API manufacturers in India are adopting these systems to reduce solvent inventory and accelerate batch release. This technology is unifying previously separate unit operations and enabling real-time release testing that compresses pharmacopeial compliance timelines.
EMA's revised ICH Q14 guideline on analytical procedure development is mandating enhanced method robustness documentation for impurity profiling in antimalarial APIs. European formulation manufacturers must now demonstrate lifecycle management of chromatographic methods used for quinine sulphate identity testing. High-purity pharmaceutical-grade suppliers are responding by investing in dedicated stability chambers and forced degradation studies to preempt regulatory queries.
Multi-source qualification programs are replacing sole-source contracts as the dominant procurement model among large antimalarial buyers. Pharmaceutical procurement teams in sub-Saharan African markets are fragmenting orders across three to four prequalified API suppliers to reduce concentration risk. This behavioral shift is most visible in Kenyan and Nigerian government tender processes, where technical evaluation criteria now explicitly reward supply diversification.
Global Quinine Sulphate Market Segmentation
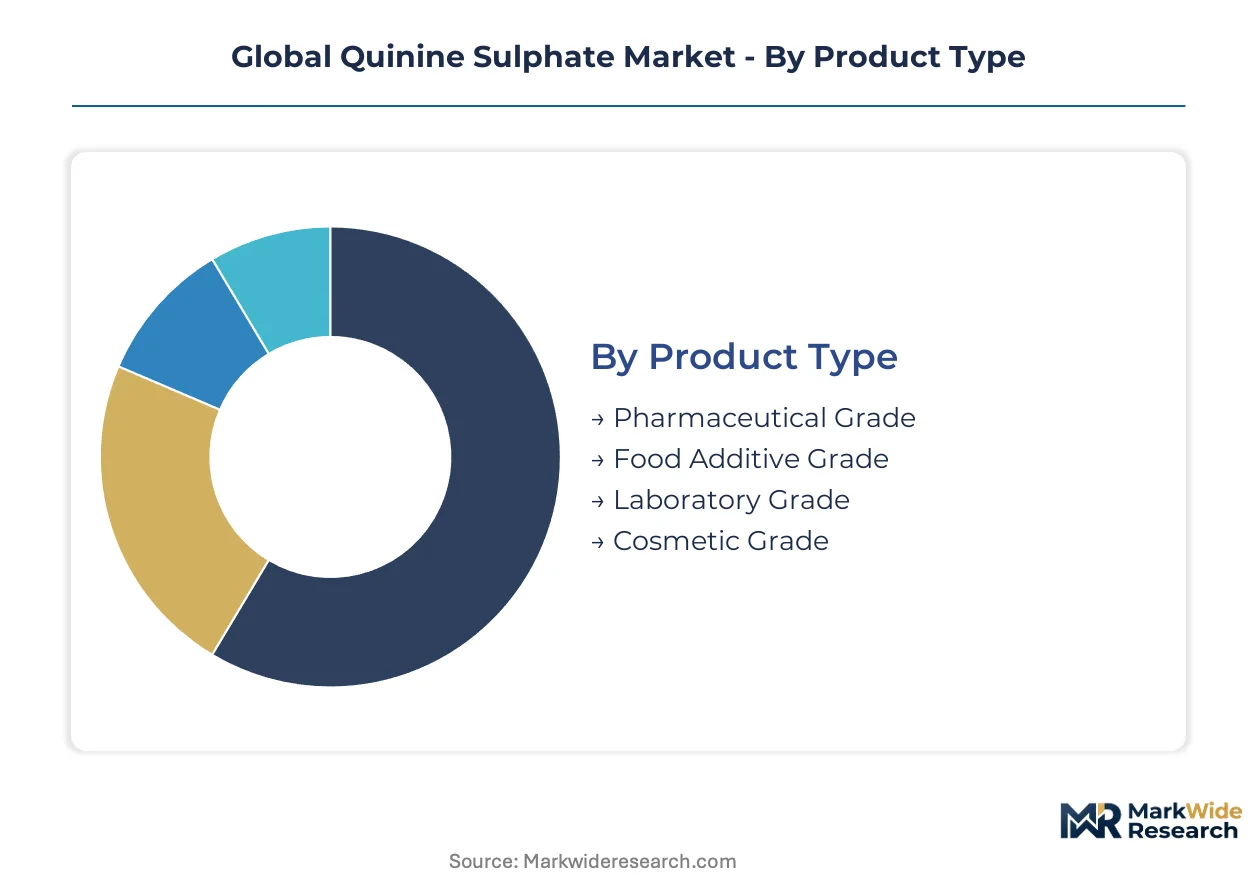
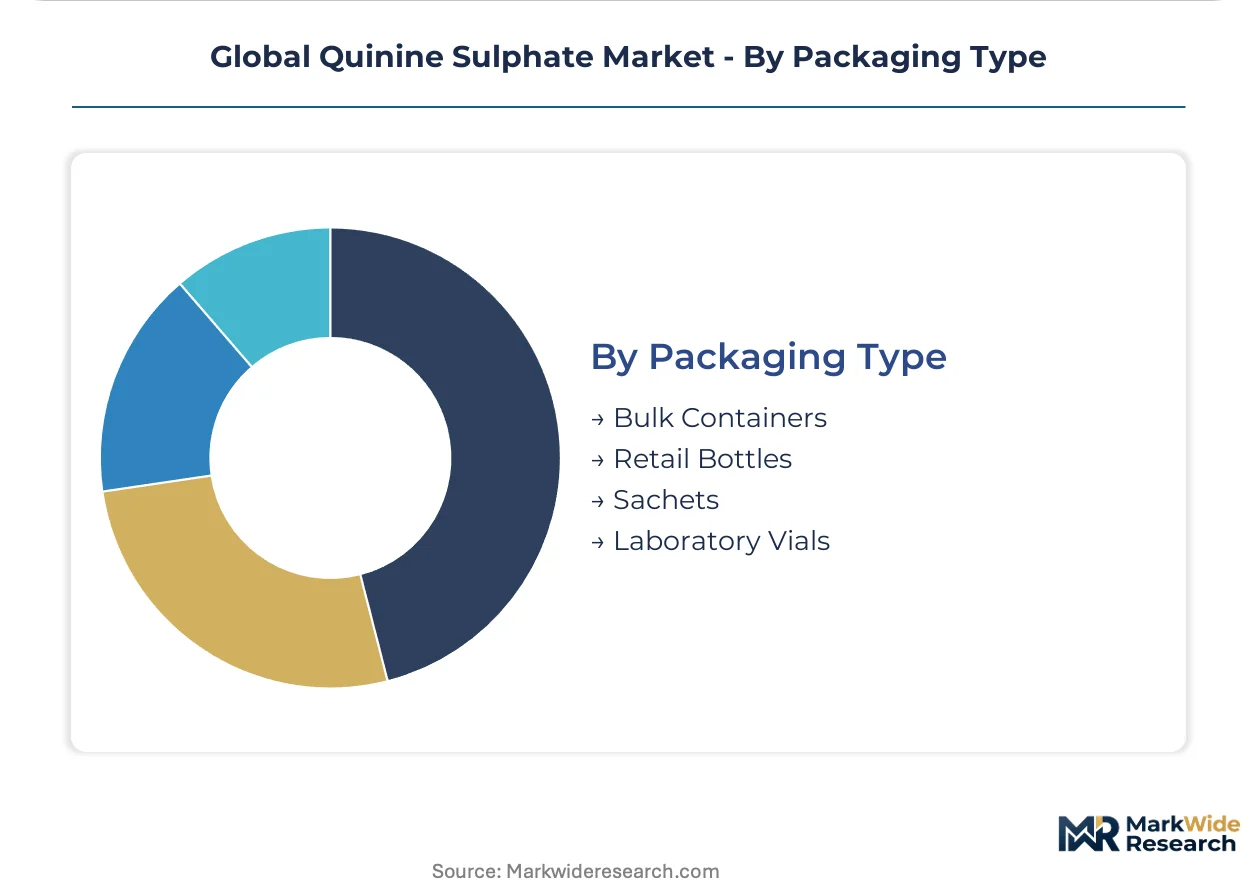
Quinine sulphate procurement patterns diverge sharply across purity grades and end-use specifications. Pharmaceutical buyers enforce pharmacopeial compliance thresholds that food and cosmetic segments rarely match. Packaging and distribution configurations further stratify supply economics between bulk API shipments and precision-dosed retail formats.
Product Type:
Purity thresholds and crystalline morphology specifications define functional suitability across pharmaceutical, food, laboratory, and cosmetic applications.
- Pharmaceutical Grade:Minimum purity mandates and ICH Q3D elemental impurity compliance determine tablet dissolution performance in antimalarial combination therapies. Indian formulation manufacturers absorb the majority of pharmaceutical-grade volume for export-oriented ACT production.
- Food Additive Grade:Bittering intensity measured in ppm quinine governs regulatory acceptance in tonic water and bitter liqueur formulations. Craft beverage producers in the United States and United Kingdom are expanding procurement of certified food-grade material as a differentiated ingredient claim.
- Laboratory Grade:Analytical reference standard contracts require certificate-of-analysis documentation with full impurity profiling.
- Cosmetic Grade:Topical formulation compatibility limits alkaloid concentration in skin-conditioning applications.
Mature deployment sits with Pharmaceutical Grade. Newer deployment is concentrated in Food Additive Grade.
Application:
End-use functionality spans therapeutic intervention, sensory modification, and analytical methodology.
- Antimalarial Treatment:WHO prequalification standards mandate stability testing protocols that filter out non-compliant API sources. Sub-Saharan African government tenders concentrate demand for injectable and oral quinine sulphate in severe malaria management protocols.
- Food Flavoring:Regulatory caps on bittering agent concentration vary by jurisdiction, with FDA and EFSA maintaining distinct maximum permissible levels.
- Beverage Production:Premium tonic water brands specify quinine sulphate origin and extraction method for label transparency.
- Chemical Research:Chiral separation applications and fluorescence quenching studies consume high-purity laboratory quantities.
Volume concentration remains with Antimalarial Treatment. Steepest expansion trajectory is visible in Beverage Production.
End User:
Procurement scale and compliance burden diverge across industrial buyers, with pharmaceutical manufacturers facing the most stringent qualification requirements.
- Pharmaceutical Manufacturers:Multi-source qualification programs now dominate contracting behavior, with three to four prequalified API suppliers replacing sole-source agreements. Kenyan and Nigerian government tender processes explicitly reward supply diversification in technical evaluation criteria.
- Food & Beverage Companies:Craft segment buyers prioritize sustainability certifications and cinchona bark traceability for consumer-facing marketing claims.
- Cosmetic Producers:Formulation R&D teams evaluate quinine sulphate for hair conditioning and skin toning applications at experimental scale.
- Research Institutions:Reference standard procurement operates on small-batch, high-documentation contract terms.
Contract sophistication peaks with Pharmaceutical Manufacturers. Emerging procurement investment is flowing toward Food & Beverage Companies.
Packaging Type:
Logistics configuration aligns with end-user handling capabilities and inventory turnover requirements.
- Bulk Containers:Drum and fiberboard intermediate bulk container formats serve high-volume pharmaceutical formulation facilities with dedicated weighing and dispensing infrastructure.
- Retail Bottles:Amber glass and HDPE pharmaceutical bottles with child-resistant closures support compounding pharmacy and small-batch food production needs.
- Sachets:Unit-dose foil laminate pouches enable field deployment in malaria-endemic regions with limited cold chain access.
- Laboratory Vials:Certified reference material packaging includes nitrogen headspace and tamper-evident seals for analytical stability.
Standardization is deepest with Bulk Containers. Format innovation is concentrating in Sachets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's pharmaceutical special economic zones in Hyderabad and Ahmedabad concentrate API formulation capacity for export markets. Kenya's emerging industrial parks near Nairobi attract integrated manufacturing investments. Brazil's tax-advantaged pharmaceutical free zones in São Paulo state reshape South American supply chain configuration.
India
Domestic formulation capacity expansion in Hyderabad and Ahmedabad drives pharmaceutical-grade quinine sulphate procurement for export-oriented antimalarial combination therapies. CDSCO mandates ICH Q3D elemental impurity compliance for API exports to regulated markets. Gujarat's Vadodara cluster hosts multiple WHO-prequalified manufacturers scaling continuous processing infrastructure.
Kenya
Government tender processes for severe malaria management protocols concentrate demand for injectable and oral formulations. The Pharmacy and Poisons Board enforces stability testing protocols aligned with WHO prequalification standards. Nairobi's industrial zone attracts East African API-to-tablet manufacturing investments from Indian pharmaceutical conglomerates.
Brazil
ANVISA's tightened pharmacopeial monograph requirements filter substandard producers from antimalarial supply chains. São Paulo state's tax-incentivized pharmaceutical free zones enable import substitution for previously API-dependent formulation facilities. The Campinas research corridor anchors alkaloid extraction technology partnerships with South American cinchona bark suppliers.
United States
Craft beverage producers in Pacific Northwest and Northeast corridors expand food-grade quinine sulphate procurement for premium tonic water differentiation. FDA maintains distinct maximum permissible bittering agent concentration caps separate from EFSA thresholds. Brooklyn and Portland anchor label-transparent sourcing networks emphasizing cinchona bark traceability for consumer-facing marketing claims.
Germany
EMA's revised ICH Q14 guideline on analytical procedure development mandates enhanced method robustness documentation for impurity profiling. REACH compliance burdens exclude smaller API producers from European pharmaceutical supply chains. Frankfurt's chemical logistics hub facilitates high-purity pharmaceutical-grade distribution to formulation manufacturers across the continent.
Global Quinine Sulphate Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across three discernible tiers. Integrated pharmaceutical majors leverage captive cinchona bark supply networks and sustained antimalarial R&D pipelines to absorb high-purity material volumes. Mid-tier API manufacturers adopt modular sourcing and continuous flow chemistry to reduce solvent waste and accelerate batch release. Geographic expansion and multi-source qualification programs constitute the dominant competitive moves as procurement teams fragment orders across prequalified suppliers.
Within the integrated pharmaceutical tier, Sanofi and GlaxoSmithKline plc occupy positions exemplifying backward integration into South American alkaloid extraction networks. Among India-based specialists, Cipla Limited and Wockhardt represent archetypes of export-oriented formulation capacity expansion serving WHO-prequalified antimalarial markets. These entities anchor competitive positioning through pharmacopeial compliance infrastructure rather than price-based rivalry.
| Leading Market Players |
|---|
| Sanofi |
| GlaxoSmithKline plc |
| Wockhardt |
| Actavis |
| Shreeji Pharma International |
| Novartis AG |
| Cipla Limited |
| A. B. Enterprises |
| Teva Pharmaceutical Industries Ltd. |
| Others |
Supply & Pricing Matrix
Government procurement programs in sub-Saharan Africa and Indian pharmaceutical exporters dominate demand concentration, anchoring contract-based long-term offtake pricing with volume-tier discounts and pharmacopeial certification premiums. This buyer structure rewards multi-year supply agreements over spot transactions, compressing margin flexibility for API producers facing cinchona bark cost volatility.
Pricing Analysis
Short lead-time premiums of fifteen to twenty percent apply to rush orders from malaria-endemic regions facing stockout scenarios, while spot inventory from non-prequalified producers trades at discounts. Three-tier pricing structure across WHO-prequalified, national-regulator-approved, and non-certified grades separates pharmaceutical buyers by compliance burden. Cost compression in food-grade material is intensifying because craft beverage producers are consolidating purchase volumes through distributor cooperatives. Government tenders in Kenya and Nigeria demonstrate lowest price sensitivity due to WHO mandate compliance requirements.
Supply Chain Analysis
Direct-to-formulator channels handle pharmaceutical-grade volumes from Ecuador, Peru, and Bolivia extraction sites through Indian API processing hubs. Raw material dependencies center on cinchona bark alkaloid content, South American climate conditions, and Ecuadorian export licensing procedures. Single-source vulnerability concentrates in Ecuadorian bark supply corridors exposed to El Niño precipitation disruption. Distribution runs through pharmaceutical-specialized freight forwarders with temperature-controlled handling and customs pre-clearance at Mumbai and Nairobi ports.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Continuous flow chemistry platforms are displacing batch alkaloid extraction, compressing capital requirements for pharmaceutical-grade production and enabling real-time release testing that shortens compliance timelines.
For Market Incumbents: Hedge against artemisinin-based combination therapy displacement by diversifying into food-grade bittering agent supply chains serving premium beverage producers. Secure backward integration into certified sustainable cinchona cultivation partnerships in Bolivia and Peru to lock bark supply before sustainability verification mandates tighten. Prioritize investment in ICH Q14-compliant analytical procedure documentation to preempt EMA regulatory queries on impurity profiling methods. For New Entrants and Emerging Players: Launch via craft beverage distributor networks in the United States Pacific Northwest and United Kingdom premium mixer segments, where traceability marketing commands ingredient premiums. Target Kenyan and Nigerian government tender processes with sachet-format unit-dose packaging designed for field deployment without cold chain infrastructure. White-space availability concentrates in East African API-to-tablet integrated manufacturing, where local formulation capacity lags demand growth for severe malaria management protocols. For Investors and Strategic Acquirers: The window for entry favors mid-tier Indian API manufacturers with WHO prequalification infrastructure and underutilized continuous processing capacity. Long-term viability hinges on cinchona bark supply security rather than synthetic quinine economics, favoring targets with South American sourcing partnerships over pure formulation plays. Watch for EMA pharmacopeial monograph revisions on elemental impurity thresholds as the signal for consolidation pressure on non-compliant producers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Cinchona Cultivation | Secures alkaloid supply chains in Ecuador and Peru against sustainability verification mandates. |
| Continuous Flow Chemistry Platform Deployment | Reduces solvent waste and accelerates batch release for WHO-prequalified manufacturers in Gujarat. |
| Multi-Source Qualification Program Adoption | Fragments pharmaceutical procurement across three to four API suppliers to mitigate concentration risk. |
| Food-Grade Bittering Agent Market Entry | Captures craft beverage procurement growth in United States and United Kingdom premium tonic segments. |
| East African API-to-Tablet Manufacturing Investment | Addresses underpenetrated formulation capacity in Kenyan and Nigerian government tender markets. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with pharmaceutical procurement managers, CDSCO regulatory affairs leads, WHO prequalification officers, and South American cinchona cultivation cooperative representatives. Secondary sources incorporated FDA drug master file submissions, EMA marketing authorization applications, Indian customs export statistics, and UN Comtrade pharmaceutical API movement records. Bottom-up volume estimates from formulation manufacturer consumption patterns triangulated against top-down alkaloid extraction capacity assessments across Ecuador, Peru, and Bolivia.
Granularity-level modeling addressed pharmaceutical grade versus food additive grade purity tiers, antimalarial treatment versus beverage production end-use applications, and bulk container versus sachet packaging configurations. CAGRs derived from segment-level demand elasticity coefficients applied to baseline procurement volumes, with cross-validation against WHO essential medicines list revision schedules and artemisinin combination therapy displacement curves. Forecast inputs incorporated CDSCO export compliance timelines, EMA ICH Q14 guideline implementation phases, and craft beverage sector growth trajectories in designated metropolitan corridors.
Cinchona bark yield volatility, regulatory monograph revision timing, and synthetic antimalarial substitution rates are the dominant revision risks to projection assumptions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Europe Barium Carbonate Market
Bulk Chemicals
Gluconic Acid Market
Bulk Chemicals
Ethylbenzene Market
Bulk Chemicals
Europe Lipids Market
Bulk Chemicals
United States Lime Market
Bulk Chemicals
Methyl Gluceth-10 Market
Bulk Chemicals
Calcium Chloride Market
Bulk Chemicals
Monoethylene Glycol (MEG) Market
Bulk Chemicals
Aniline Market
Bulk Chemicals
Pyridine Market
Bulk Chemicals
North America and Europe Palm Derivatives Market
Bulk Chemicals
Carbonate Market
Bulk Chemicals
Cyclamate Market
Bulk Chemicals
Asia-Pacific Starch Derivatives Market
Bulk Chemicals
Global Crude Sulfate Turpentine Market
Bulk Chemicals
United States Calcium Carbonate Market