
 Potassium Benzoate Market | 2026-2036
Potassium Benzoate Market Size, Share, and Industry Trends Forecast 2026-2036
Potassium Benzoate Market Analytics
Asset-light toll manufacturing and third-party contract production is reshaping competitive entry in potassium benzoate supply, lowering capital barriers for regional challengers. Emerald Kalama Chemical leverages backward integration into toluene oxidation to sustain margin stability across cycles. Tengzhou Aolong Chemical anchors its position through captive soda ash supply and proximity to Shandong province's chemical cluster. LANXESS AG differentiates via pharmaceutical-grade certification and European distribution density.
Potassium benzoate (C7H5KO2) is the potassium salt of benzoic acid, typically manufactured through neutralization of benzoic acid with potassium hydroxide or carbonate, yielding a white crystalline powder with solubility of approximately 67 g per 100 mL water at 25°C; it functions primarily as a broad-spectrum antimicrobial preservative effective in acidic pH environments below 4.5. Food Grade material dominates volume due to widespread use in carbonated beverages, fruit juices, and condiments, while Pharmaceutical Grade commands premium pricing through USP-NF compliance and lower heavy-metal thresholds. Powder form leads current shipments for blending flexibility, though granular variants are gaining share in automated dosing systems for beverage bottling lines.
FDA food additive regulations under 21 CFR 184.1733, EU REACH registration requirements for benzoate substances, and China's GB 2760 food safety national standards collectively define purity benchmarks, labeling obligations, and maximum permitted concentrations across jurisdictions. These frameworks directly determine which grades manufacturers can produce for human-contact applications and which export markets remain accessible. Stakeholders must track evolving preservative maximum limits in infant food categories and emerging restrictions on combined benzoate-sorbate systems in several European member states.
Market Dynamics
Clean-label formulation mandates from major retailers are compressing synthetic preservative tolerance windows, forcing potassium benzoate suppliers to demonstrate equivalency through enhanced purity certification and transparent supply chain documentation.
Growth Catalysts
- GB 2760 Compliance Expansion:China's food safety national standards are tightening purity thresholds for benzoate salts, compelling domestic manufacturers to upgrade quality systems and creating premium-grade supply shortages.
- Carbonated Beverage Volume:Southeast Asian bottling lines are expanding capacity for acidic soft drinks where potassium benzoate maintains antimicrobial efficacy below pH 4.5.
- REACH Registration Completion:EU benzoate substance dossiers under ECHA are consolidating compliant supplier pools, advantaging registrants with full toxicological data packages.
Market Restraints
- Toluene Feedstock Volatility:Benzoic acid precursors track benzene-toluene-xylene complex pricing, exposing margin stability to petrochemical cycle swings.
- Shandong Province Concentration:Captive soda ash supply and oxidation capacity clusters in eastern China create geographic single-point vulnerability for global pharmaceutical-grade material.
- Natural Extract Substitution:Rosemary oleoresin and cultured dextrose formulations are displacing synthetic preservatives in premium condiment and sauce categories.
Strategic Opportunities
- Indian Processed Food Expansion:FSSAI modernization of food additive schedules is opening formulation latitude for benzoate-sorbate combinations in ready-to-eat meals.
- Automated Dosing Systems:Granular potassium benzoate variants are penetrating beverage bottling lines seeking dust-free handling and precision feed control.
- Pharmaceutical-Grade Certification:USP-NF compliance is creating pricing stratification between food-grade commodity supply and excipient-qualified material for oral dosage forms.
Industry Challenges
- Dual-Grade Production Complexity:Switching between food-grade and pharmaceutical-grade campaigns requires cleaning validation protocols that compress asset utilization rates.
- Heavy-Metal Testing Bottlenecks:ICP-MS arsenic and lead threshold compliance for infant food categories is extending batch release timelines by 48-72 hours.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Potassium Benzoate Market |
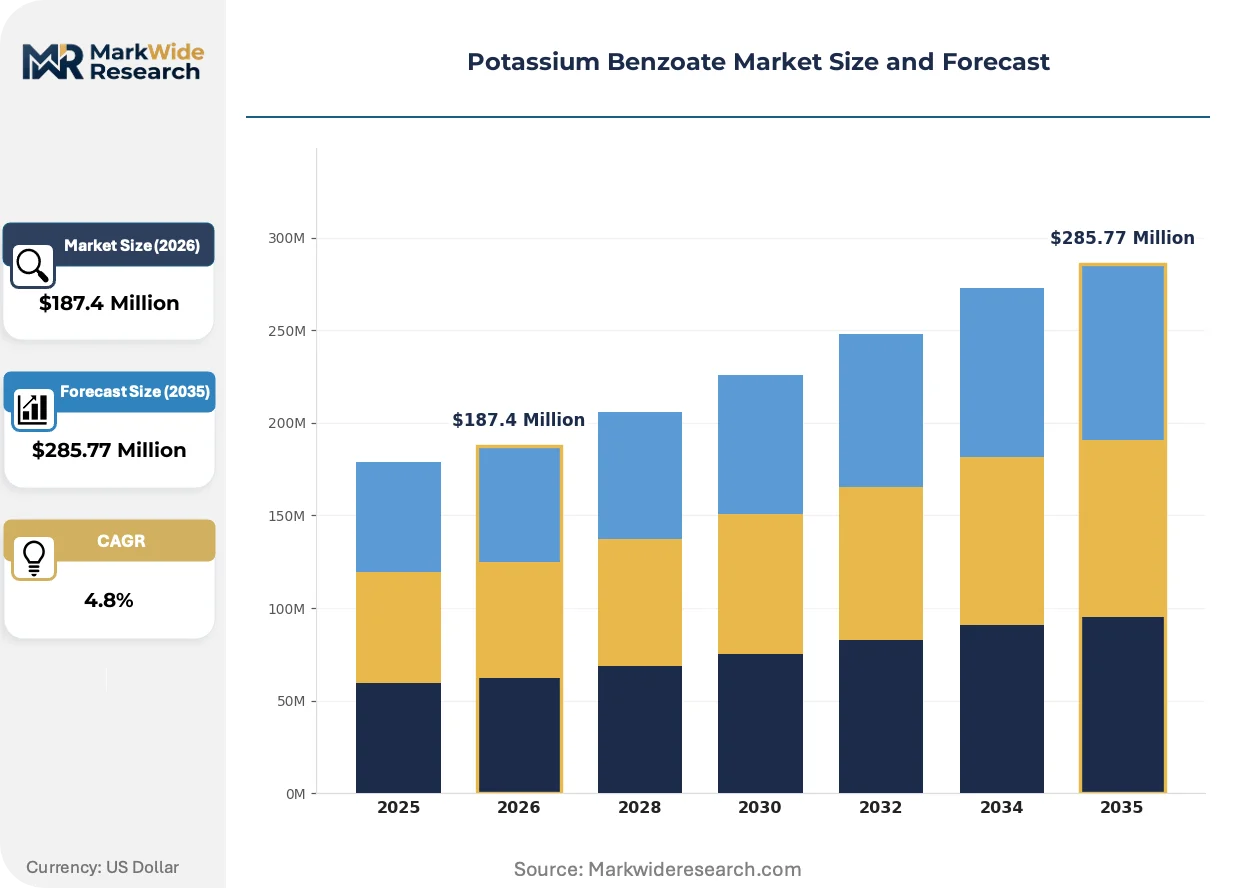
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Grade, Pharmaceutical Grade, Industrial Grade, Cosmetic Grade End Use: Food & Beverage, Pharmaceuticals, Cosmetics, Personal Care Form: Powder, Crystal, Liquid, Granular Distribution Channel: Online, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Emerald Kalama Chemical, Tengzhou Aolong Chemical, A.M Food Chemical, LANXESS AG, Eastman Chemical Company, Macco Organiques Inc., FBC Industries, Foodchem International Corporation, Wuhan Youji Industries Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Potassium Benzoate Market Evolving Landscape
Preservative efficacy demonstration is migrating from laboratory challenge studies to real-time shelf-life monitoring systems, compressing the evidentiary burden for supplier qualification.
Encapsulated potassium benzoate using lipid or polymer matrices is migrating from specialty nutraceutical applications toward mainstream beverage preservation, enabling controlled release in acidic environments. Functional drink manufacturers in South Korea and Japan are piloting these systems for extended ambient stability. The technology is migrating from premium positioning toward cost-competitive scale as toll encapsulation capacity expands across contract manufacturers.
EFSA's 2023 benzoate exposure reassessment and subsequent member-state maximum limit adjustments are forcing reformulation across children's food categories in France, Germany, and Italy. Combined benzoate-sorbate restrictions in several EU jurisdictions are driving single-preservative system adoption. Infant food manufacturers are responding by accelerating natural acidification and high-pressure processing investments to reduce chemical preservative dependency.
Specification-driven procurement is consolidating buyer-seller relationships around certified-grade contracts with multi-year purity guarantees. Large beverage conglomerates are reducing approved supplier lists from regional fragmentation toward single-source pharmaceutical-grade agreements. This concentration is most visible in North American and Western European carbonated soft drink supply chains, where traceability documentation now extends through three tiers of chemical processing.
Potassium Benzoate Market Segmentation
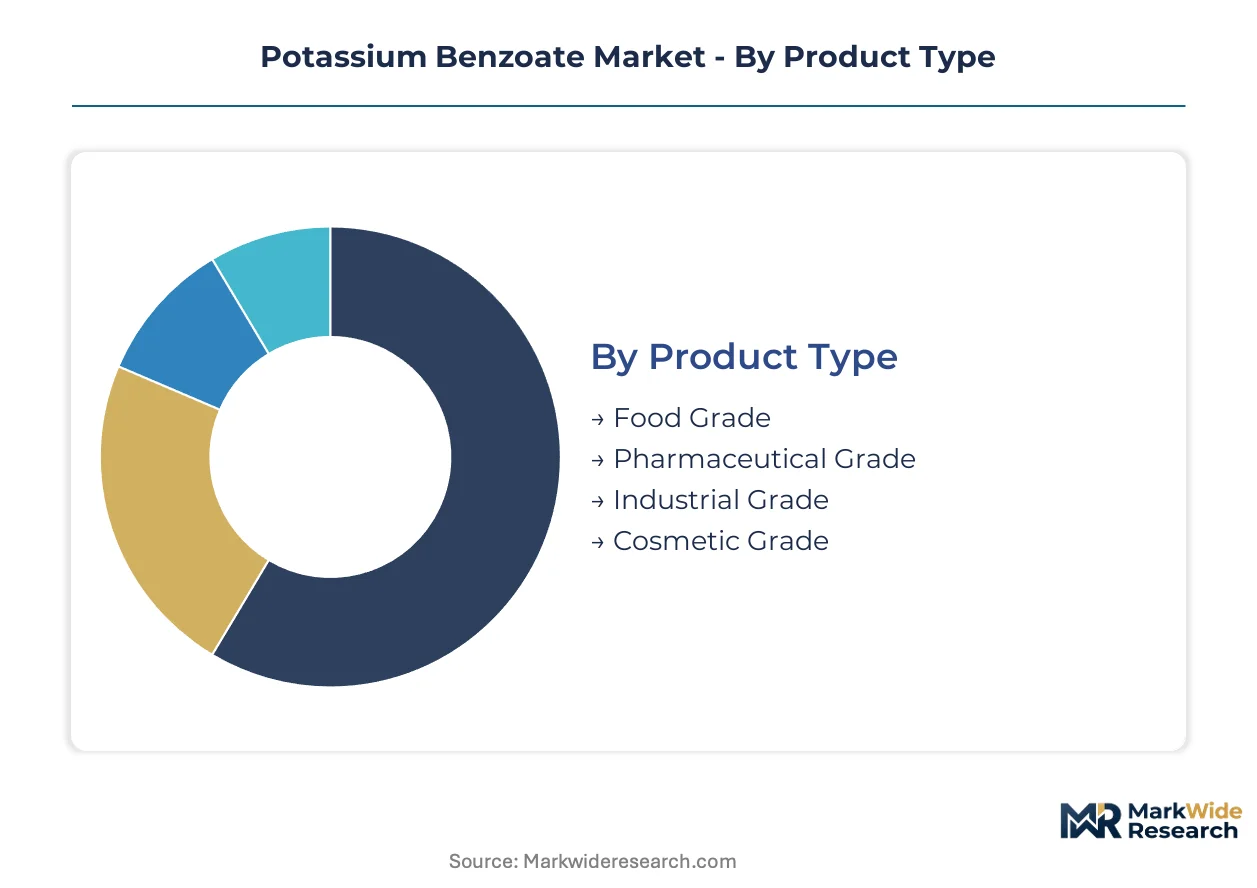
Segmentation in potassium benzoate markets tracks how purity thresholds, formulation requirements, and handling specifications fragment demand across end-use verticals. Each dimension carries distinct certification burdens and margin profiles that determine supplier qualification pathways.
Product Type:
Purity gradients separate commodity supply from certified-grade material, with each tier commanding distinct testing protocols and buyer relationships.
- Food Grade:Material meeting FDA 21 CFR 184.1733 and GB 2760 standards for benzoic acid salts, typically 99.0-99.5% purity with controlled heavy-metal thresholds. Demand concentrates in carbonated beverage bottling across China and India, where acidic pH environments below 4.5 maximize antimicrobial efficacy. Clean-label pressures from major retailers are compressing synthetic preservative tolerance windows, forcing enhanced purity certification.
- Pharmaceutical Grade:USP-NF compliant material with arsenic limits below 3 ppm and lead below 10 ppm, qualifying as an excipient for oral dosage forms. Procurement is consolidating around single-source agreements with multi-year purity guarantees from North American and Western European buyers. Heavy-metal testing bottlenecks extend batch release timelines by 48-72 hours for infant food categories.
- Industrial Grade:Technical specification material for corrosion inhibition and polymer applications, typically 98.0-99.0% purity without food-contact certification.
- Cosmetic Grade:Material meeting regional cosmetic safety standards for preservative function in rinse-off and leave-on formulations.
Food Grade commands the established base. The steepest expansion runs through Pharmaceutical Grade.
End Use:
Application verticals impose divergent regulatory frameworks and formulation constraints that determine grade selection and supplier qualification depth.
- Food & Beverage:Carbonated soft drinks, fruit juices, condiments, and sauces requiring antimicrobial preservation in acidic matrices. Southeast Asian bottling lines are expanding capacity for acidic soft drinks where potassium benzoate maintains efficacy. EFSA's benzoate exposure reassessment is forcing reformulation across children's food categories in France, Germany, and Italy.
- Pharmaceuticals:Oral dosage forms, liquid preparations, and topical applications requiring excipient-grade material with full toxicological documentation. REACH registration completion under ECHA is consolidating compliant supplier pools, advantaging registrants with complete dossiers.
- Cosmetics:Rinse-off and leave-on formulations requiring regional cosmetic safety compliance.
- Personal Care:Shampoos, lotions, and hygiene products with preservative function requirements.
Food & Beverage anchors current volume. Pharmaceuticals is climbing the fastest on certification premiums.
Form:
Physical presentation determines handling characteristics, dissolution kinetics, and compatibility with automated production systems.
- Powder:Fine crystalline material with approximately 67 g per 100 mL water solubility at 25°C, offering blending flexibility for dry mix applications. Current shipments dominate due to versatility across formulation types, though dust generation creates occupational exposure management requirements.
- Granular:Dust-free agglomerated particles penetrating beverage bottling lines seeking precision feed control and automated dosing compatibility. Toll encapsulation capacity expansion is enabling cost-competitive scale migration from premium positioning.
- Crystal:Coarse crystalline form for applications requiring controlled dissolution rates.
- Liquid:Pre-dissolved solutions for direct addition to aqueous processing streams.
Powder retains the incumbent position. Granular variants are gaining share fastest in automated systems.
Distribution Channel:
Channel structure reflects buyer scale, specification complexity, and documentation requirements across end-use segments.
- Direct Sales:Long-term certified-grade contracts with multi-year purity guarantees, dominant among large beverage conglomerates reducing approved supplier lists from regional fragmentation. Traceability documentation now extends through three tiers of chemical processing in North American and Western European carbonated soft drink supply chains.
- Specialty Stores:Regional chemical distributors serving mid-tier manufacturers with technical support and smaller lot sizes.
- Online:Digital procurement platforms for standardized grades with transparent pricing and rapid fulfillment.
- Supermarkets:Limited retail presence for small-scale food producers and institutional buyers.
Direct Sales commands the premium segment. Specialty Stores are expanding most quickly for regional challenger access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's GB 2760 food safety standards are tightening benzoate purity thresholds, compelling domestic manufacturers to upgrade quality systems and creating regional supply shortages that reshape procurement patterns across Asia-Pacific markets.
China
Shandong province's chemical cluster anchors domestic benzoate oxidation capacity, with captive soda ash supply chains supporting cost-competitive food-grade production. SAMR enforcement of updated GB 2760 standards is disqualifying sub-scale producers from infant food categories. Tengzhou and surrounding municipalities concentrate pharmaceutical-grade material output for export markets.
United States
FDA 21 CFR 184.1733 compliance requirements drive specification-driven procurement among carbonated beverage conglomerates. Heavy-metal testing protocols under EPA guidance extend batch release timelines for excipient-grade material. Gulf Coast petrochemical corridors supply toluene feedstock to benzoic acid precursors, though pricing volatility exposes margin compression risks.
Germany
EFSA's 2023 benzoate exposure reassessment triggered member-state maximum limit adjustments across children's food categories. REACH registration completion under ECHA consolidated compliant supplier pools, advantaging registrants with full toxicological dossiers. Leverkusen and Ludwigshafen chemical corridors host pharmaceutical-grade certification facilities serving European oral dosage form manufacturers.
India
FSSAI modernization of food additive schedules is opening formulation latitude for benzoate-sorbate combinations in ready-to-eat meals. Maharashtra and Gujarat processed food corridors are expanding bottling capacity for acidic soft drinks. Mumbai-Pune industrial clusters concentrate toll manufacturing capacity for regional challenger entry.
South Korea
MFDS cosmetic safety standards drive preservative demand in rinse-off and leave-on formulations. Seoul-Incheon metropolitan manufacturers are piloting encapsulated potassium benzoate systems for functional beverage stability. Gyeonggi-do chemical parks support toll encapsulation capacity expansion from premium nutraceutical positioning toward mainstream scale.
Potassium Benzoate Market Competitive Landscape
On the supply side, the industry is consolidating around three distinct capability tiers: integrated petrochemical players with backward control over toluene oxidation, regional specialists leveraging captive raw material access, and toll manufacturers offering asset-light contract production. Strategic archetypes include purity-grade certifiers competing on USP-NF compliance, cluster-proximity producers optimizing logistics costs, and encapsulation technology licensors capturing value from controlled-release formulations. Dominant competitive moves involve M&A activity to secure pharmaceutical-grade certification assets and strategic partnerships with beverage bottlers for multi-year supply agreements.
Within the integrated petrochemical tier, Emerald Kalama Chemical and LANXESS AG exemplify archetypes built on upstream control and European distribution density respectively. Among Asia-Pacific specialists, Tengzhou Aolong Chemical occupies a position anchored by Shandong province chemical cluster proximity. These three represent the strategic segmentation between margin-stable oxidation-integrated supply, premium-grade certification premiums, and regional cost-competitive positioning.
| Leading Market Players |
|---|
| Emerald Kalama Chemical |
| Tengzhou Aolong Chemical |
| A.M Food Chemical |
| LANXESS AG |
| Eastman Chemical Company |
| Macco Organiques Inc. |
| FBC Industries |
| Foodchem International Corporation |
| Wuhan Youji Industries Co., Ltd. |
| Others |
Value Network & Pricing Analysis
Overcapacity in Shandong province's benzoic acid oxidation units is compressing food-grade potassium benzoate spot pricing while simultaneously concentrating pharmaceutical-grade premiums among certified producers, creating divergent supplier behavior across purity tiers.
Pricing Analysis
Certification level creates the primary spread between commodity and premium tiers, with USP-NF pharmaceutical-grade material commanding substantial premiums over FDA 21 CFR 184.1733 food-grade supply. Three-tier pricing structure across pharmaceutical, food, and industrial grades reflects testing burden and heavy-metal compliance thresholds. Cost compression in food-grade segments is intensifying because Shandong province capacity expansion outpaces Southeast Asian beverage demand growth. Mid-tier processed food manufacturers exhibit highest price sensitivity, while infant formula and oral dosage form buyers prioritize purity guarantees over unit economics.
Supply Chain Analysis
Toluene feedstock availability from Gulf Coast and Rotterdam petrochemical corridors anchors benzoic acid precursor economics for oxidation-integrated producers. Manufacturing concentrates in China, Germany, and India, with Shandong province hosting captive soda ash supply chains. Raw material sourcing draws from benzene-toluene-xylene complex pricing, potassium carbonate mining operations, and specialty catalyst suppliers. Single-source vulnerability runs through Shandong province's pharmaceutical-grade oxidation clusters. Distribution runs through direct long-term contracts for certified grades and specialty chemical distributors for regional spot purchases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Encapsulation toll manufacturing and real-time shelf-life monitoring services are expanding faster than commodity potassium benzoate volume, creating attach-rate opportunities for suppliers who bundle technical validation with material supply.
For Market Incumbents: Build regulatory dossier depth as the primary moat against REACH registrant consolidation and EFSA exposure limit tightening. Secure backward integration into toluene oxidation to buffer margin volatility from BTX complex pricing swings. Expand pharmaceutical-grade certification assets in Leverkusen and Ludwigshafen corridors to capture excipient-premium stratification. Counter natural extract substitution in premium condiment categories with enhanced purity documentation and transparent supply chain traceability. For New Entrants and Emerging Players: Maharashtra and Gujarat processed food corridors offer underpenetrated white-space for benzoate-sorbate combination formulations as FSSAI schedules modernize. Automated dosing system compatibility with granular potassium benzoate variants presents equipment-integrated entry angle against incumbent powder dominance. Target toll encapsulation partnerships with Seoul-Incheon functional beverage manufacturers piloting controlled-release systems. Lead with technical service bundling rather than price undercutting to bypass established supplier qualification barriers. For Investors and Strategic Acquirers: Capital is best deployed toward pharmaceutical-grade certification assets with existing USP-NF compliance and infant food category testing infrastructure. Long-term viability hinges on regulatory dossier completeness rather than commodity scale across the analysis window. Acquisition focus should center on regional specialists with captive raw material access in Shandong or Gujarat clusters. Monitor EFSA member-state maximum limit adjustments as inflection indicator for natural preservative substitution acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Toluene Oxidation | Emerald Kalama Chemical's captive feedstock supply buffers margin volatility from BTX pricing cycles. |
| Pharmaceutical-Grade Certification Investment | USP-NF compliance creates pricing stratification between commodity food-grade and excipient-qualified material. |
| Encapsulation Technology Licensing | Seoul-Incheon manufacturers pilot lipid-matrix systems for functional beverage ambient stability extension. |
| Long-term Supply Agreement with Beverage Bottlers | North American carbonated soft drink chains consolidate approved supplier lists toward single-source pharmaceutical-grade contracts. |
| Joint Venture in Maharashtra-Gujarat Corridor | FSSAI modernization opens formulation latitude for benzoate-sorbate combinations in ready-to-eat meals. |
Research Methodology
Desk research of customs trade data, SEC 10-K chemical segment disclosures, and ECHA REACH registration dossiers preceded structured interviews with benzoic acid plant managers, beverage procurement leads, pharmaceutical excipient qualification officers, and specialty chemical distribution channel partners. Primary fieldwork combined with secondary validation from FDA 21 CFR guidance documents, GB 2760 standard updates, and FSSAI additive schedule notifications. Bottom-up volume modeling across grade tiers and end-use verticals was cross-checked against top-down petrochemical derivative demand estimates.
Assumptions held fixed include current REACH registration compliance thresholds and existing FDA food additive purity benchmarks, while variables tested included EFSA member-state limit adjustment scenarios and natural extract substitution elasticity in premium condiment categories. Segmentation dimensions modeled encompass grade tier, end-use industry, physical form factor, and regional production hub clustering. CAGRs were derived from installed beverage bottling capacity expansion trajectories and pharmaceutical oral dosage form production growth across the projection horizon. Forecast inputs incorporated toluene feedstock pricing volatility bands and heavy-metal testing protocol extension timelines for infant food categories.
Practitioners should monitor EFSA exposure reassessment implementation across France, Germany, and Italy, combined benzoate-sorbate restriction proposals in additional EU jurisdictions, and Shandong province environmental enforcement intensity for early signals requiring forecast revision. Cross-checking against Cefic petrochemical derivative demand reports and ACC specialty chemical trade flow data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemical Intermediates
Global Glycinates Market
Chemical Intermediates
3-Chloropropionyl Chloride Market
Chemical Intermediates
Ethylene Diamine Tetra Acetic Acid (EDTA) Market
Chemical Intermediates
Natural Chelating Agents Market
Chemical Intermediates
Dimethyl Dicarbonate Market
Chemical Intermediates
Epoxy Silanes Market
Chemical Intermediates
Global Biochemical Reagents Market
Chemical Intermediates
Montelukast Intermediate Market
Chemical Intermediates
Penicillin Intermediate Market
Chemical Intermediates
Thioesters Market
Chemical Intermediates
Japan Formic Acid Market
Chemical Intermediates
Diethyl Phthalate Market
Chemical Intermediates
Isosafrole Market
Chemical Intermediates
Fungal Staining Reagent Market
Chemical Intermediates
Global Etoricoxib Intermediate Market
Chemical Intermediates
Acid Chlorides Market