
 2-Methylfuran Market | 2026-2036
2-Methylfuran Market Size, Share, and Industry Trends Forecast 2026-2036
2-Methylfuran Market Outlook
Modular supply of 2-methylfuran in blended solvent kits and tailored fuel-additive packages is broadening procurement options for downstream formulators. International Furan Chemicals BV leverages integrated furfural-to-derivatives production to sustain feedstock cost advantages across European distribution networks. Sigma-Aldrich anchors high-purity catalog supply for pharmaceutical and analytical laboratories, while Capot Chemical Co. Ltd. competes on custom synthesis scale for specialty chemical intermediates.
2-methylfuran is a heterocyclic compound (C5H6O) produced primarily via catalytic hydrogenation of furfural, featuring a five-membered furan ring with a methyl substituent that yields a boiling point near 63°C and makes it valuable as a renewable solvent, fuel blending component, and platform chemical for pharmaceuticals. The chemical intermediate segment dominates value capture due to pharmaceutical and agrochemical contract manufacturing demand, while fuel additive applications represent the fastest-expanding structural pocket as renewable diesel and sustainable aviation fuel standards harden. Industrial grade purity anchors volume throughput, though high purity grades command premium positioning in regulated pharmaceutical and food-contact applications.
REACH registration requirements in Europe and EPA fuel additive compliance pathways in the United States shape product specifications and market access timelines for 2-methylfuran suppliers. China's GB standards for chemical purity and industrial emissions, administered by SAMR and MEE, govern export-grade production from the dominant furfural manufacturing base. Stakeholders must monitor evolving renewable fuel certification schemes and pharmaceutical impurity profiling standards to align purity grades with jurisdiction-specific compliance thresholds.
Market Dynamics
Catalytic hydrogenation breakthroughs are compressing production costs for furfural-derived 2-methylfuran, redistributing margin capture from raw material suppliers to integrated derivative manufacturers and reshaping procurement economics for fuel blenders and pharmaceutical formulators alike.
Growth Catalysts
- Renewable Fuel Mandates:The EPA's renewable fuel standard compliance pathways and the EU Green Deal's sustainable aviation fuel targets are pulling 2-methylfuran into diesel and jet fuel additive formulations across North American and European refineries.
- Pharmaceutical Contract Manufacturing:Agrochemical and active pharmaceutical ingredient producers are expanding heterocyclic intermediate offtake for crop protection chemistry and antiviral synthesis routes.
- Furfural Supply Concentration:China's dominance in corncob and bagasse-derived furfural feedstock anchors cost-competitive 2-methylfuran output along East Asian manufacturing corridors serving export markets.
Market Restraints
- Feedstock Price Volatility:Agricultural residue availability fluctuates with corn harvest cycles and sugarcane crushing seasons, transmitting commodity volatility into furfural input costs.
- Upstream Supply Concentration:Over two-thirds of global furfural capacity sits in Chinese provinces, exposing derivative producers to single-geography logistics disruptions and export policy shifts.
- REACH Registration Burden:ECHA's substance evaluation timelines and data requirements for tonnage band upgrades create multi-year market access delays for European volume expansion.
Strategic Opportunities
- Brazilian Biofuel Integration:ANP's RenovaBio program and expanding sugarcane ethanol infrastructure create feedstock-adjacent opportunities for furfural-derived biofuel additive localization.
- Modular Blended Solvent Kits:Custom-formulated solvent packages combining 2-methylfuran with tetrahydrofuran and 2-methyltetrahydrofuran are opening pharmaceutical extraction and coating application niches.
- Carbon Border Adjustment Mechanism:The EU CBAM's phased implementation on chemical imports incentivizes low-carbon 2-methylfuran production from biomass waste streams versus petroleum-derived alternatives.
Industry Challenges
- Catalytic Process Engineering Talent:Specialized expertise in selective hydrogenation catalyst design and reactor optimization remains concentrated among a limited pool of academic and industrial research groups.
- Pharmaceutical Impurity Profiling:ICH Q3D elemental impurities and residual solvent guideline compliance requires dedicated analytical infrastructure for high-purity grade certification.
- Multi-Jurisdiction Registration Coordination:Simultaneous EPA fuel additive petitions, REACH dossier updates, and China's MEE chemical inventory filings strain regulatory affairs bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 2-Methylfuran Market |
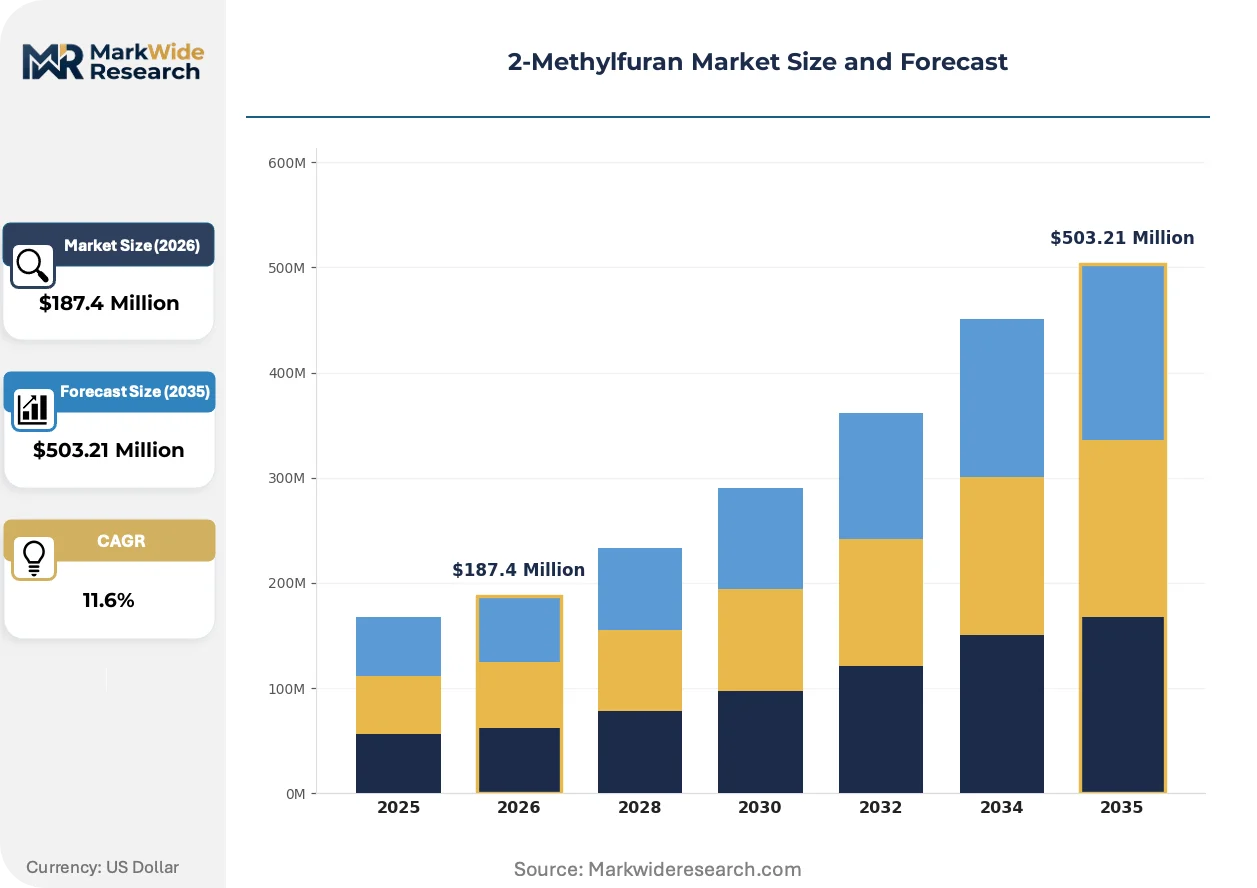
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solvent, Fuel Additive, Chemical Intermediate, Polymer End Use Industry: Automotive, Pharmaceuticals, Food & Beverage, Agriculture Distribution Channel: Online Retail, Direct Sales, Wholesale, Distributors Purity Grade: Analytical Grade, Industrial Grade, High Purity, Technical Grade |
| Companies Covered | A&J Pharmtech Co. Ltd., ChemExper Inc., Capot Chemical Co. Ltd., Amadis Chemical Co. Ltd., MP Biomedicals, LLC., Sigma-Aldrich, Finetech Industry Ltd., International Furan Chemicals BV, Angene Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
2-Methylfuran Market Strategic Shifts
Process intensification and regulatory carbon accounting are converging to redefine competitive advantage in 2-methylfuran production, with technology adopters capturing margin from energy efficiency gains and verified emissions reductions.
Continuous-flow catalytic hydrogenation is consolidating batch reactor capacity in furfural-to-2-methylfuran conversion. Specialty chemical producers in the Netherlands and Germany are retrofitting fixed-bed systems with structured catalyst packings that cut residence times and thermal energy inputs. This technology compression is enabling smaller-scale distributed production closer to European pharmaceutical demand clusters.
REACH's 2023-2025 substance evaluation roadmap is tightening impurity disclosure thresholds for furan derivatives used in food-contact and medical device applications. The European Chemicals Agency's dossier compliance checks are forcing suppliers to upgrade analytical protocols for genotoxic impurity detection. Pharmaceutical-grade 2-methylfuran specifications are diverging from industrial grades as a result, with premium certification tiers emerging for EU-sourced material.
Fuel blenders are unbundling long-term offtake contracts into quarterly procurement windows with certified carbon intensity scores. Renewable diesel producers in California and Oregon are requiring batch-level lifecycle analysis documentation to satisfy LCFS credit calculations. This specification granularization favors suppliers with integrated biomass traceability systems and third-party verified carbon accounting.
2-Methylfuran Market Segmentation
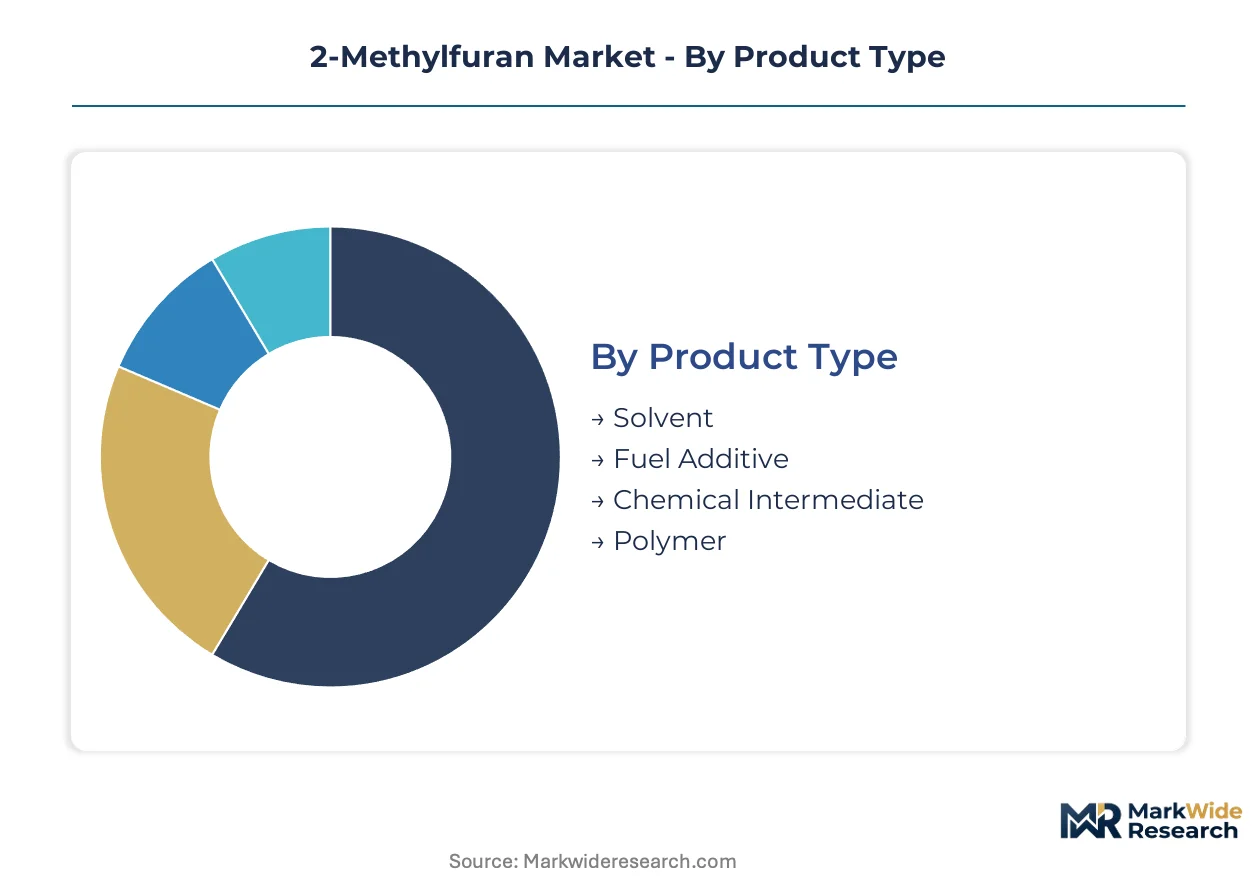
Segmentation in 2-methylfuran markets separates commodity-scale fuel additive volumes from precision-grade pharmaceutical intermediates, each demanding distinct purity certifications, supply chain configurations, and regulatory compliance pathways. Understanding these divides reveals where margin pools concentrate versus where throughput dominates.
Product Type:
Chemical Intermediate and Fuel Additive segments operate as embedded inputs within downstream manufacturing systems, while Solvent and Polymer applications function more often as standalone procurement decisions by end-users.
- Chemical Intermediate:Heterocyclic building block for antiviral synthesis and crop protection chemistry, typically procured under long-term contract manufacturing agreements. Demand concentrates in pharmaceutical hubs across Germany, Switzerland, and India, where CDSCO and Swissmedic oversight elevates documentation burdens.
- Fuel Additive:Renewable diesel and sustainable aviation fuel blending component, shipped in bulk to refiners seeking LCFS credit qualification. Expansion concentrates in California, Oregon, and EU member states with binding SAF mandates.
- Solvent:Extraction and coating applications in pharmaceutical processing.
- Polymer:Specialty resin synthesis for electronic and medical device materials.
Volume placements concentrate in Chemical Intermediate; the faster expansion belongs to Fuel Additive.
End Use Industry:
Automotive and Agriculture segments absorb 2-methylfuran through fuel and agrochemical value chains respectively, while Pharmaceuticals and Food & Beverage impose the strictest purity gatekeeping.
- Pharmaceuticals:Active pharmaceutical ingredient manufacturing and analytical reagent supply, governed by ICH Q3D elemental impurity limits and residual solvent guidelines. Procurement clusters near Mumbai, Basel, and New Jersey to minimize cold-chain logistics for temperature-sensitive intermediates.
- Automotive:Renewable diesel blending and racing fuel formulations, with EPA fuel additive petitions required for US market access. Refiner demand concentrates in Texas, Rotterdam, and Singapore storage terminals.
- Food & Beverage:Extraction solvent for flavor and fragrance compounds, requiring food-contact compliance.
- Agriculture:Herbicide and fungicide intermediate synthesis for crop protection chemistry.
Margin capture peaks in Pharmaceuticals; Automotive commands the steepest volume expansion trajectory.
Distribution Channel:
Direct Sales and Distributor networks handle embedded system procurement for industrial accounts, whereas Online Retail serves fragmented laboratory and research-scale demand.
- Direct Sales:Long-term offtake contracts with refiners and pharmaceutical manufacturers, often incorporating quarterly carbon intensity score verification. Relationship density concentrates among integrated furfural-to-derivatives producers serving European fuel blenders.
- Distributors:Regional chemical distribution networks managing inventory for mid-scale pharmaceutical formulators and agrochemical compounders. Presence strongest in German industrial corridors and US Gulf Coast chemical clusters.
- Wholesale:Bulk terminal transfers and tank farm deliveries for fuel additive volumes.
- Online Retail:Catalog supply for analytical laboratories and research institutions.
Direct Sales anchor volume throughput; Online Retail is climbing the fastest on laboratory outsourcing trends.
Purity Grade:
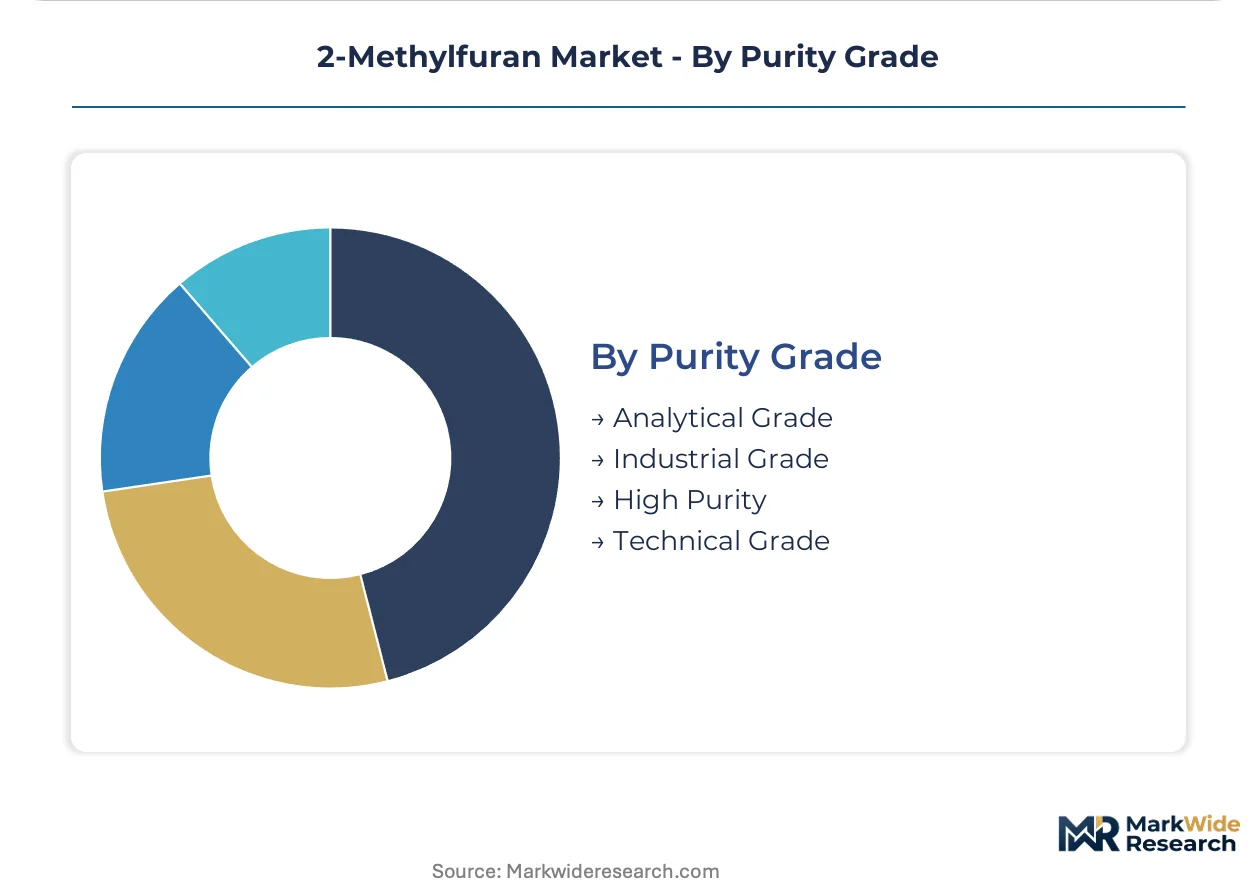
Industrial and Technical grades ship as commodity inputs, while Analytical and High Purity grades penetrate regulated applications where impurity profiling documentation determines market access.
- Industrial Grade:Standard specification for fuel additive blending and bulk chemical synthesis, produced via continuous-flow hydrogenation with minimal downstream purification. Cost positioning depends on furfural feedstock proximity in Shandong and Henan provinces.
- High Purity:Pharmaceutical and electronic material applications requiring genotoxic impurity screening and batch-level certificates of analysis. Premium tier emerging from REACH substance evaluation pressures on food-contact and medical device applications.
- Analytical Grade:Reference standard and chromatography applications with stringent certification requirements.
- Technical Grade:General-purpose solvent and polymer intermediate uses with relaxed specifications.
Industrial Grade dominates tonnage placements; High Purity is gaining share fastest on regulatory specification divergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates upstream furfural supply while the United States and Germany absorb downstream derivative demand through fuel additive and pharmaceutical channels. Consumption clusters in industrial corridors where renewable fuel mandates and pharmaceutical manufacturing intersect.
China
Shandong and Henan provinces host corncob-derived furfural refineries that feed hydrogenation units producing industrial-grade 2-methylfuran for export markets. SAMR-administered GB standards for chemical purity and MEE emissions protocols govern export-grade production from the dominant manufacturing base. The Yangtze River Delta corridor ships bulk volumes to European fuel blenders and Asian pharmaceutical formulators.
United States
California and Oregon refiners procure 2-methylfuran for renewable diesel blending to satisfy LCFS credit calculations and EPA renewable fuel standard compliance pathways. EPA fuel additive petitions create multi-year market access timelines for new suppliers seeking entry into transportation fuel formulations. Texas Gulf Coast storage terminals handle bulk terminal transfers for fuel additive volumes destined for West Coast blending facilities.
Germany
Pharmaceutical contract manufacturers in the Rhine-Ruhr and Bavarian chemical corridors source high-purity grades for heterocyclic intermediate synthesis under REACH-registered supply agreements. ECHA substance evaluation timelines and data requirements for tonnage band upgrades shape procurement relationships with integrated furfural-to-derivatives producers. Continuous-flow hydrogenation retrofits in the Netherlands and Germany enable distributed production closer to European demand clusters.
India
Mumbai and Hyderabad pharmaceutical hubs expand heterocyclic intermediate offtake for antiviral synthesis routes and crop protection chemistry under CDSCO oversight. The country's agrochemical compounders integrate 2-methylfuran into herbicide and fungicide manufacturing for domestic and export markets. Gujarat's specialty chemical parks attract toll manufacturing arrangements for international pharmaceutical clients.
Brazil
Sugarcane bagasse availability in São Paulo and Minas Gerais states creates feedstock-adjacent opportunities for furfural-derived biofuel additive localization under ANP's RenovaBio program. The expanding ethanol infrastructure supports pilot-scale hydrogenation capacity for renewable diesel blending components. Domestic refiners evaluate quarterly procurement windows with certified carbon intensity scores to align with emerging biofuel certification schemes.
2-Methylfuran Market Competitive Environment
The competitive structure tilts toward integrated furfural-to-derivatives producers with captive feedstock access and catalog suppliers serving fragmented laboratory demand. Three archetypes dominate: upstream-integrated hydrogenation specialists with Shandong and Henan production bases; high-purity catalog distributors serving pharmaceutical and analytical laboratories; and custom synthesis houses competing on specialty chemical intermediate scale. Capacity expansion in continuous-flow reactor systems and strategic partnerships for carbon intensity certification represent the dominant competitive moves reshaping procurement economics.
Among catalog distributors, Sigma-Aldrich anchors high-purity supply for pharmaceutical and analytical laboratories, while Capot Chemical Co. Ltd. occupies a position within the custom synthesis tier for specialty chemical intermediates. International Furan Chemicals BV exemplifies the integrated archetype, leveraging furfural-to-derivatives production to sustain feedstock cost advantages across European distribution networks. These three represent the structural poles around which procurement relationships organize.
| Leading Market Players |
|---|
| A&J Pharmtech Co. Ltd. |
| ChemExper Inc. |
| Capot Chemical Co. Ltd. |
| Amadis Chemical Co. Ltd. |
| MP Biomedicals, LLC. |
| Sigma-Aldrich |
| Finetech Industry Ltd. |
| International Furan Chemicals BV |
| Angene Chemical |
| Others |
Value Chain & Pricing Dynamics
Quarterly carbon intensity score verification demanded by California and Oregon refiners forces suppliers to restructure batch-level documentation and third-party certification workflows, elevating compliance costs that compress margins in industrial-grade segments while widening spreads for certified low-carbon material.
Pricing Analysis
Cost-down pressure on industrial-grade volumes accelerates because continuous-flow hydrogenation retrofits in Shandong and Henan provinces are expanding cost-competitive export capacity. Three-tier pricing structure across pharmaceutical-grade, fuel-additive, and technical levels reflects divergence in REACH registration status and ICH Q3D compliance documentation. Price differentiation rests on genotoxic impurity screening depth and batch-level lifecycle analysis verification. Fuel blenders exhibit highest price sensitivity due to LCFS credit arbitrage calculations, while pharmaceutical contract manufacturers absorb premium positioning for Swissmedic and CDSCO-aligned certification.
Supply Chain Analysis
Direct-to-refiner long-term offtake contracts handle renewable diesel and sustainable aviation fuel volume procurement, with quarterly renegotiation windows replacing annual agreements. Geographic supply concentrates in China, the United States, and Germany, with Shandong corncob-derived furfural refineries feeding hydrogenation units for export markets. Raw material dependencies center on agricultural residue availability from corn harvest cycles and sugarcane crushing seasons, plus specialized selective hydrogenation catalysts. Single-geography logistics exposure creates vulnerability to Chinese export policy shifts and Yangtze River Delta shipping disruptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Continuous-flow catalytic hydrogenation is displacing legacy batch reactor systems across furfural-to-2-methylfuran conversion, rewarding technology adopters with energy efficiency gains and verified emissions reductions that satisfy tightening renewable fuel certification schemes.
For Market Incumbents: Acquire selective hydrogenation catalyst design expertise through targeted recruitment from academic research groups concentrated in the Netherlands and Germany. Backward integration into corncob and bagasse preprocessing secures feedstock cost advantages against Chinese supply concentration risks. Defensive positioning requires upgrading analytical infrastructure for ICH Q3D elemental impurity compliance before REACH substance evaluation timelines force reactive investment. For New Entrants and Emerging Players: Launch via modular blended solvent kit formulations targeting pharmaceutical extraction and coating application niches in Mumbai and Hyderabad. Brazilian sugarcane bagasse feedstock-adjacent production under ANP's RenovaBio program offers the most penetrable geography for furfural-derived biofuel additive localization. Go-to-market execution should emphasize batch-level lifecycle analysis documentation to satisfy California LCFS credit calculations. For Investors and Strategic Acquirers: Re-rating potential sits with integrated furfural-to-derivatives producers given EU CBAM phased implementation on chemical imports incentivizing low-carbon biomass waste stream sourcing. Long-term viability favors archetypes with captive Shandong or Henan production bases and established REACH-registered European distribution networks. Monitor EPA fuel additive petition approval velocity as inflection indicator for North American market access expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Furfural Feedstock | Captive corncob and bagasse supply secures margin protection against Chinese export policy volatility. |
| Continuous-Flow Reactor Retrofit | Structured catalyst packings cut residence times and thermal energy inputs for European pharmaceutical clusters. |
| REACH Tonnage Band Upgrade | ECHA dossier compliance expansion unlocks food-contact and medical device application premium tiers. |
| Carbon Intensity Certification Partnership | Third-party verified accounting satisfies California LCFS credit calculations for renewable diesel blenders. |
| Modular Solvent Kit Formulation | Custom 2-methylfuran and tetrahydrofuran blends penetrate pharmaceutical extraction outsourcing trends. |
Study Parameters
Document review covered customs and trade flow databases, ECHA REACH registration filings, EPA fuel additive petitions, and SEC 10-K disclosures from listed chemical producers, complemented by interviews with hydrogenation plant managers, pharmaceutical procurement leads at CDSCO-registered contract manufacturers, renewable diesel refinery planning officers, and specialty chemical distribution channel partners. Bottom-up volume estimates from furfural refinery capacity and top-down demand triangulation from fuel additive blending ratios and pharmaceutical intermediate offtake were cross-validated.
Segment-level value outputs across the projection horizon were generated through analytical frameworks modeling purity grade tier, end-use industry application, and regional regulatory cluster adoption patterns. CAGRs were derived from elasticity-adjusted demand curves incorporating renewable fuel mandate stringency indices and pharmaceutical impurity profiling standard evolution. Industry-specific forecast inputs included LCFS credit price trajectories and REACH substance evaluation roadmap timing.
Feedstock price volatility from agricultural residue availability, REACH registration timeline delays, and EPA fuel additive petition approval velocity are the dominant revision risks for trajectory assumptions. Practitioners should monitor California Air Resources Board LCFS regulatory amendments and ECHA dossier compliance check outcomes for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Europe Soda Ash Market
Bulk Chemicals
Mercaptan Market
Bulk Chemicals
Lithium Benzoate Market
Bulk Chemicals
Acetyl Tributyl Citrate Market
Bulk Chemicals
Powdered Cellulose Market
Bulk Chemicals
Isoprene Monomer Market
Bulk Chemicals
2-Ethyl Hexanol Market
Bulk Chemicals
Middle East and Africa Ferric Chloride Market
Bulk Chemicals
Global Plastics Market
Bulk Chemicals
Ferric Sulfate Market
Bulk Chemicals
North America Copper Sulphate Market
Bulk Chemicals
Benzyl Chloride Market
Bulk Chemicals
Global Boric Acid Market
Bulk Chemicals
United States Calcium Carbonate Market
Bulk Chemicals
North America Polyvinyl Chloride (PVC) Market
Bulk Chemicals
Bulk Chemical Packaging Market