
 Mercaptan Market | 2026-2036
Mercaptan Market Size, Share, and Industry Trends Forecast 2026-2036
Mercaptan Market Foresight
Asset-light leasing models for specialty chemical storage and handling infrastructure are reconfiguring competitive entry barriers across the mercaptan value chain. Evonik Industries AG leverages its integrated methionine and specialty mercaptan platform to sustain feedstock flexibility across European and Asian production nodes. Chevron Phillips Chemical Company LLC anchors North American supply through its Gulf Coast petrochemical complex, while Arkema S.A. differentiates via fluorinated and specialty thiol chemistry for pharmaceutical and agrochemical precursors.
Mercaptans comprise organosulfur compounds bearing a thiol functional group, characterized by distinctive odor thresholds detectable below one part per billion and reactivity with heavy metal salts that enables precise analytical quantification. These properties make mercaptans indispensable for odorizing odorless natural gas and LPG, for synthesizing rubber accelerators, and for producing animal feed additives. Aliphatic mercaptans dominate volume consumption in petrochemical odorization, while specialty mercaptans command premium positioning in pharmaceutical intermediate synthesis where purity specifications exceed standard industrial grades. The agriculture application segment shows accelerated uptake as methionine hydroxy analog demand expands in poultry and swine nutrition formulations.
EPA regulations under the Clean Air Act mandate mercaptan-based odorant injection for all interstate natural gas transmission pipelines, while REACH compliance in Europe restricts certain volatile thiol emissions during manufacturing. China's GB standards for city gas odorization, administered by SAMR, require minimum odorant concentration thresholds that directly specify ethyl mercaptan or tetrahydrothiophene formulations. Stakeholders must monitor regulatory divergence between sulfur emission caps and odorant performance mandates, as tightening environmental standards in one jurisdiction can constrain formulation choices in adjacent markets.
Market Dynamics
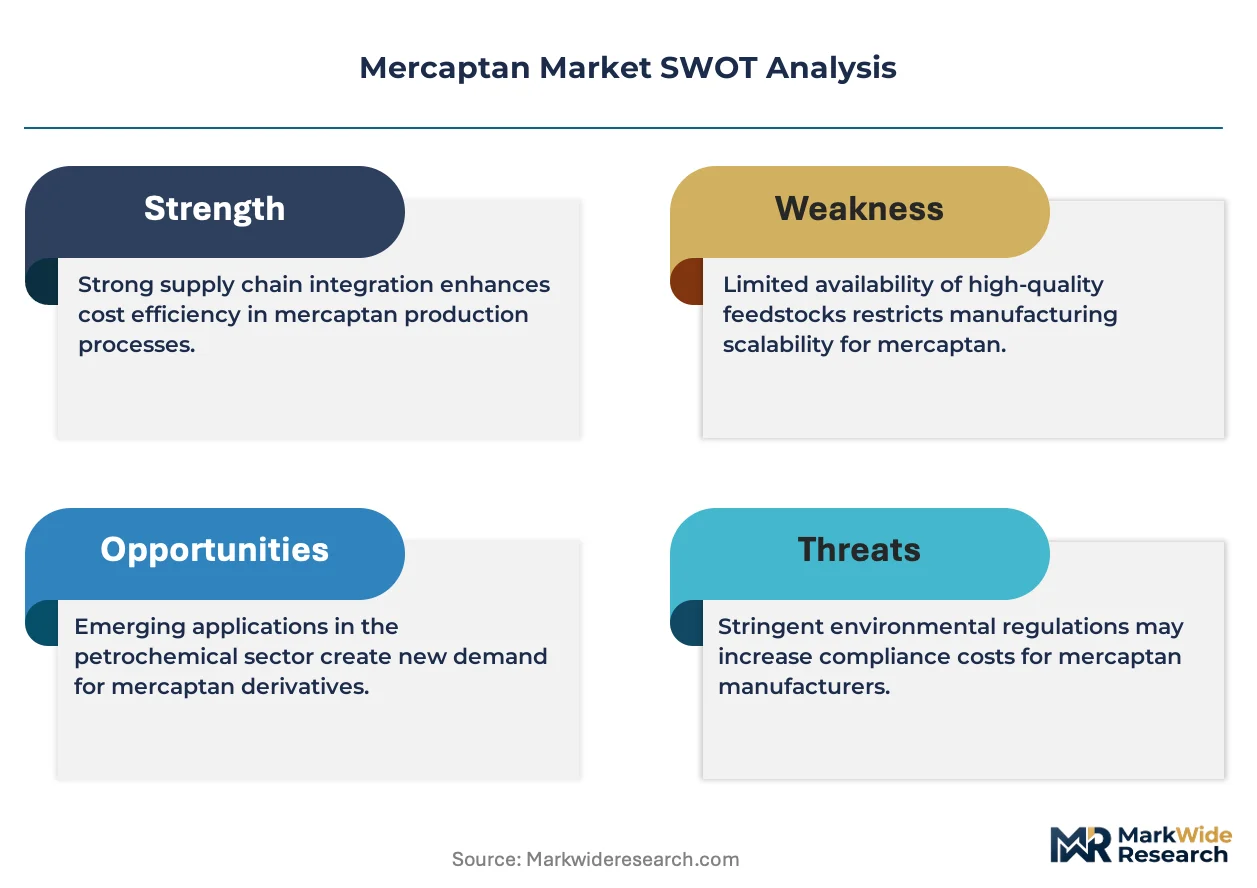
Sulfur emission caps across industrial jurisdictions are compressing formulation flexibility while pipeline odorization mandates expand, creating a regulatory tension that rewards producers with multi-plant sulfur handling capabilities.
Growth Catalysts
- EPA Clean Air Act odorization mandates:Interstate natural gas transmission pipelines in the United States require continuous mercaptan injection, sustaining baseline demand regardless of commodity price cycles.
- China's city gas infrastructure buildout:SAMR-administered GB standards for odorant concentration thresholds drive procurement volumes as municipal distribution networks expand into secondary cities.
- Methionine hydroxy analog formulations:Poultry and swine nutrition sectors are absorbing specialty mercaptan derivatives as antibiotic-free feed protocols proliferate across integrated livestock operations.
Market Restraints
- Crude sulfur price volatility:Feedstock cost swings for hydrogen sulfide and elemental sulfur inputs compress margin stability for non-integrated producers.
- Gulf Coast supply concentration:North American production gravity centers on Texas-Louisiana petrochemical corridors, exposing buyers to hurricane-related disruption risk.
- Tetrahydrothiophene substitution in select formulations:Some municipal gas utilities are piloting non-mercaptan odorants where sulfur content restrictions tighten.
Strategic Opportunities
- India's city gas distribution expansion:The Petroleum and Natural Gas Regulatory Board's geographic authorization rounds for CGD networks create new odorant specification requirements.
- Fluorinated thiol pharmaceutical precursors:Agrochemical and active pharmaceutical ingredient manufacturers are qualifying ultra-high-purity mercaptans for synthesis steps.
- Modular odorant injection systems:Leasing models for skid-mounted injection equipment reduce capital barriers for midstream pipeline operators entering new basins.
Industry Challenges
- REACH compliance timeline compression:European Chemicals Agency registration dossiers for novel thiol derivatives require extended toxicological study periods that delay commercialization.
- Specialized sulfur handling certification:Plant operators must maintain OSHA process safety management credentials alongside state-level air quality permits, multiplying compliance overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mercaptan Market |
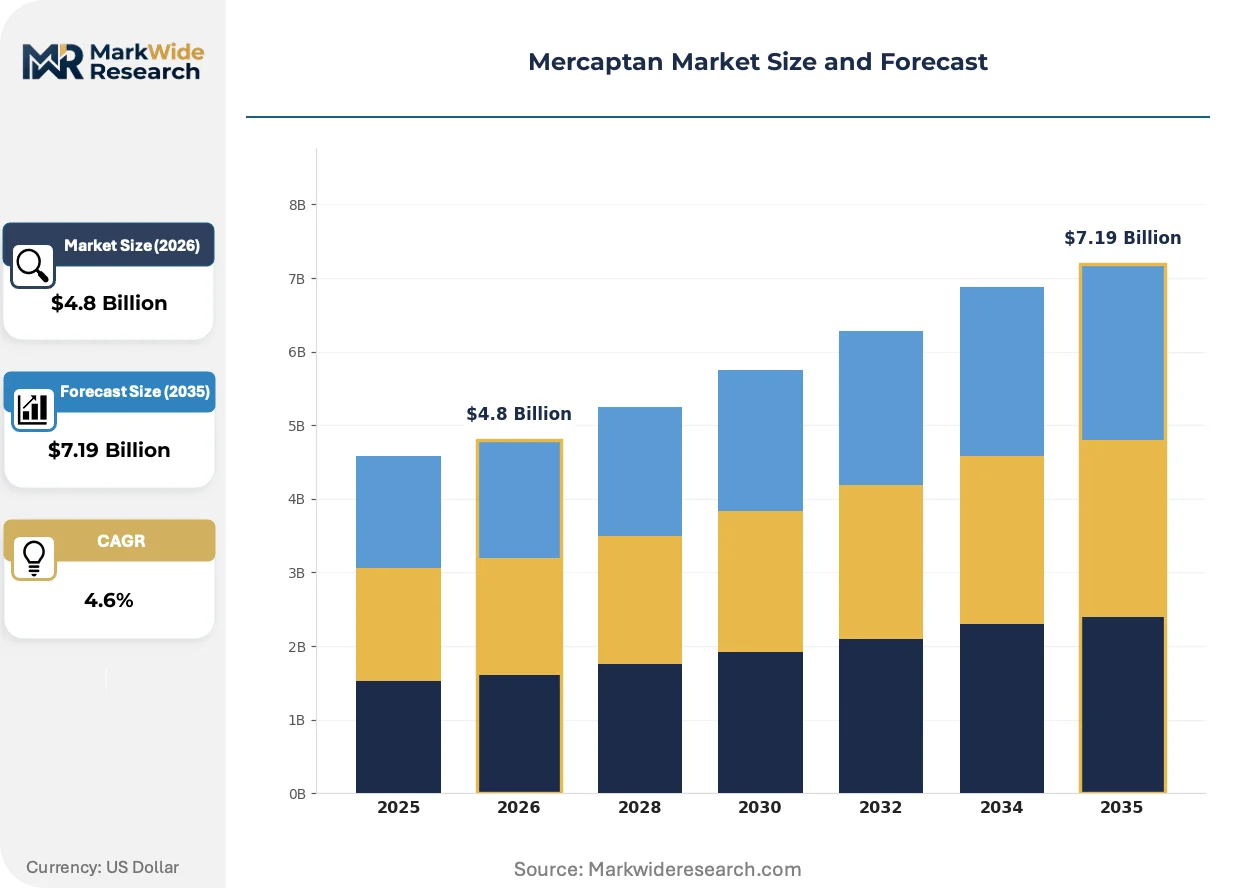
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aliphatic, Aromatic, Cyclic, Specialty Application: Petrochemical, Pharmaceuticals, Agriculture, Personal Care End User: Chemical Manufacturers, Oil & Gas Industry, Agriculture Sector, Cosmetics Industry Distribution Channel: Direct Sales, Online Sales, Distributors, Retail |
| Companies Covered | Evonik Industries AG, Jiande Lvke Chemical Industry Co., Ltd., Chevron Phillips Chemical Company LLC, DuPont de Nemours, Inc., Sanmenxia Aoke Chemical Industry, Arkema S.A., Jiande Xingfeng Chemical, Solvay S.A., Huntsman International LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mercaptan Market Shifts & Advancements
Digital odorant monitoring systems and bio-based synthesis pathways are displacing conventional batch production and manual injection calibration across the mercaptan value chain.
Membrane separation technology for mercaptan recovery is hybridizing with traditional distillation units in refinery off-gas processing. European petrochemical complexes are retrofitting hybrid units to capture sulfur values from previously flared streams. This hybridizing approach is compressing waste disposal costs while generating merchant-grade mercaptan feedstock.
China's GB standards for city gas odorization are tightening minimum detectability thresholds beyond existing European norms. SAMR enforcement inspections have increased frequency in coastal provinces, forcing reformulation of odorant blends. Municipal gas distributors in Jiangsu and Zhejiang are responding by qualifying higher-potency ethyl mercaptan concentrations.
Integrated livestock operators are consolidating methionine procurement through long-term offtake agreements directly with chemical producers. Feed compounders are being disintermediated as poultry integrators in the United States and Brazil establish captive supply relationships. This pattern is most visible in the southeastern United States, where vertical poultry processors have absorbed odorant logistics into their nutrition divisions.
Mercaptan Market Segmentation
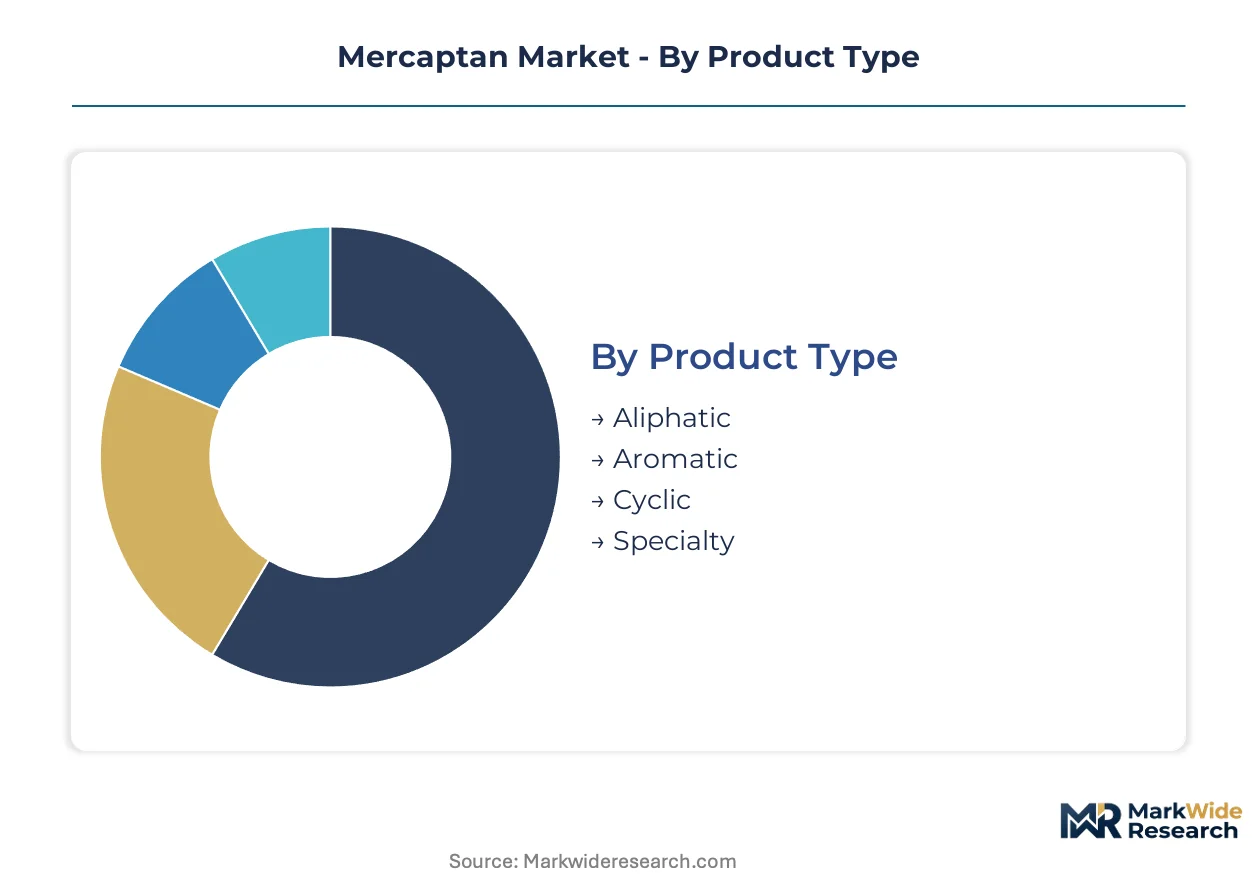
Mercaptan segmentation reveals how odorization mandates, feed additive specifications, and pharmaceutical purity requirements partition demand across distinct chemical grades and supply channels. Each dimension carries implications for sulfur handling infrastructure, regulatory compliance scope, and customer relationship intensity.
Product Type:
Mature commodity grades dominate volume throughput while specialty derivatives command formulation premiums in regulated end-uses.
- Aliphatic:Straight-chain thiols including methyl, ethyl, and propyl mercaptans serve as the workhorse odorants for natural gas and LPG odorization. Pipeline operators in the United States specify ethyl mercaptan blends under EPA Clean Air Act mandates, with procurement volumes tied to interstate transmission mileage expansion rather than commodity price cycles.
- Specialty:Fluorinated thiols and ultra-high-purity grades meet pharmaceutical intermediate specifications where impurity thresholds fall below 50 parts per million. Agrochemical manufacturers in Germany and Switzerland are qualifying these grades for active ingredient synthesis, with qualification timelines extending across multiple regulatory submission cycles.
- Aromatic:Thiophenol derivatives find niche application in rubber accelerator formulations and polymer modification chemistry.
- Cyclic:Tetrahydrothiophene and structurally related heterocyclic thiols offer alternative odorant profiles where sulfur content restrictions limit aliphatic mercaptan loading.
Aliphatic mercaptans handle the majority of throughput; specialty grades are climbing the fastest on share as pharmaceutical and agrochemical qualification programs advance.
Application:
Application segmentation tracks the divergence between pipeline odorization mandates and specialty chemical synthesis requirements.
- Petrochemical:Natural gas odorization absorbs the largest single application volume, with municipal distribution networks in China expanding under SAMR-administered GB standards. Ethyl mercaptan injection systems operate continuously across transmission infrastructure, creating baseline demand insulated from industrial production cycles.
- Agriculture:Methionine hydroxy analog production for poultry and swine nutrition represents the fastest-expanding specialty application. Integrated livestock operators in the United States and Brazil are establishing direct offtake relationships with chemical producers, bypassing traditional feed compounder intermediaries.
- Pharmaceuticals:Thiol-based intermediates for cysteine derivatives and peptide synthesis require GMP-compliant manufacturing and documented batch traceability.
- Personal Care:Trace mercaptan derivatives function as polymerization regulators in hair care and cosmetic formulation chemistry.
Petrochemical odorization commands the dominant revenue position; agriculture applications are expanding most quickly as antibiotic-free feed protocols proliferate.
End User:
End user segmentation reflects the split between infrastructure-driven procurement and specification-intensive specialty purchasing.
- Oil & Gas Industry:Midstream pipeline operators and municipal gas utilities constitute the largest mercaptan consumer category. Procurement concentrates on long-term supply agreements with odorant injection service providers, with contract structures bundling chemical supply and equipment maintenance.
- Chemical Manufacturers:Diversified chemical producers absorb mercaptan feedstock for downstream derivative synthesis including rubber accelerators, polymer modifiers, and agrochemical intermediates.
- Agriculture Sector:Poultry and swine integrators are consolidating methionine procurement through captive supply arrangements directly with production facilities.
- Cosmetics Industry:Personal care formulators source trace quantities for specific polymerization control applications.
Oil and gas infrastructure operators anchor volume demand; agriculture sector procurement is gaining share fastest through vertical integration trends.
Distribution Channel:
Channel segmentation tracks the shift from conventional bulk supply toward service-integrated delivery models.
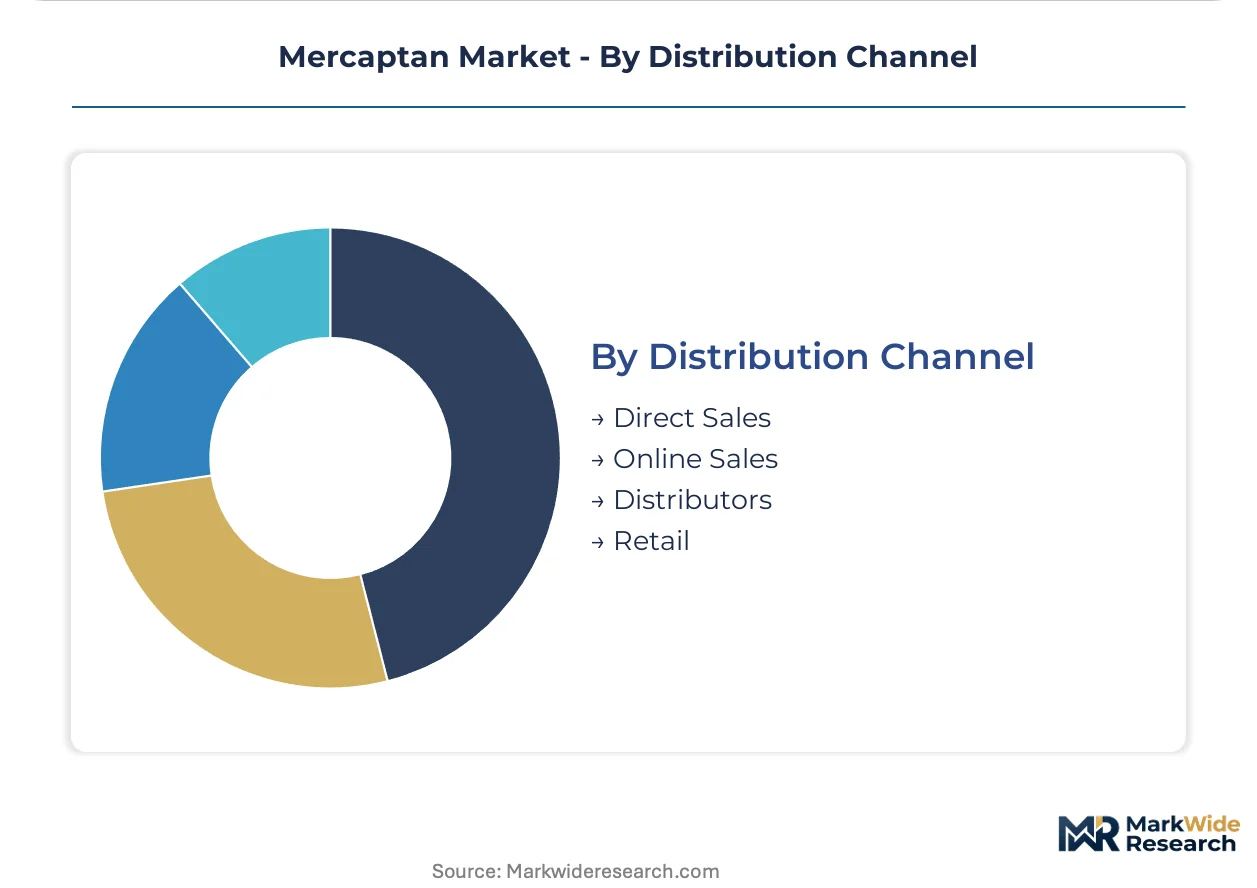
- Direct Sales:Odorant injection service providers contract directly with pipeline operators, bundling chemical supply with equipment leasing and calibration maintenance. This channel captures the majority of petrochemical odorization volume through multi-year agreements.
- Distributors:Regional chemical distributors serve smaller municipal utilities and industrial formulators with packaged mercaptan blends and technical support services.
- Online Sales:E-procurement platforms are emerging for standardized industrial grades with documented specifications and rapid replenishment cycles.
- Retail:Limited to specialty packaged quantities for laboratory and small-scale industrial applications.
Direct sales channels handle the majority of value throughput; distributor relationships are expanding fastest as mid-size utilities seek technical service bundling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances vary sharply across major mercaptan-consuming economies, with integrated petrochemical complexes in some regions supplying odorant formulations to pipeline operators in import-dependent markets.
United States
Interstate natural gas transmission networks under FERC jurisdiction sustain continuous ethyl mercaptan procurement regardless of commodity price cycles. EPA Clean Air Act odorization mandates require injection systems across all federally regulated pipelines. Gulf Coast petrochemical corridors in Texas and Louisiana concentrate domestic production capacity, exposing buyers to hurricane-related disruption risk during peak storm seasons.
China
Municipal distribution network expansion into secondary cities drives odorant volume growth as city gas infrastructure buildout accelerates. SAMR-administered GB standards for minimum odorant concentration thresholds specify ethyl mercaptan or tetrahydrothiophene formulations. Jiangsu and Zhejiang provinces have tightened detectability requirements beyond existing European norms, forcing distributors to qualify higher-potency blends.
Germany
Specialty mercaptan demand for pharmaceutical and agrochemical precursor synthesis anchors premium-grade consumption in industrial chemical clusters. REACH compliance restricts volatile thiol emissions during manufacturing, constraining formulation choices for producers serving adjacent European markets. BASF-Ludwigshafen and Bayer-Leverkusen chemical complexes represent key qualification centers for ultra-high-purity grades.
India
Petroleum and Natural Gas Regulatory Board geographic authorization rounds for city gas distribution networks create new odorant specification requirements as pipeline infrastructure expands. Domestic production capacity remains limited, necessitating import reliance for standardized industrial grades. Gujarat and Maharashtra industrial corridors are emerging as primary offtake centers for municipal utility procurement.
Saudi Arabia
SABIC-affiliated petrochemical complexes leverage integrated sulfur handling capabilities to supply merchant-grade mercaptan feedstock to regional pipeline operators. Domestic natural gas distribution network expansion under Vision 2030 infrastructure programs generates incremental odorant demand. Eastern Province industrial cities including Jubail and Yanbu concentrate production and formulation capabilities.
Mercaptan Market Competitive Landscape
On the supply side, the industry is consolidating around integrated petrochemical producers with captive sulfur feedstock access and multi-plant sulfur handling capabilities. Three archetypes dominate: diversified chemical conglomerates with methionine-mercaptan integration, Gulf Coast petrochemical specialists serving North American pipeline operators, and European fluorinated thiol specialists targeting pharmaceutical qualification programs. Capacity expansion and backward integration into hydrogen sulfide feedstock sourcing represent the dominant competitive moves.
Within the integrated chemical conglomerate tier, Evonik Industries AG and Arkema S.A. exemplify producers combining methionine platform economics with specialty mercaptan flexibility. Chevron Phillips Chemical Company LLC anchors the Gulf Coast specialist archetype. DuPont de Nemours, Inc. occupies a position bridging industrial and specialty grade supply.
| Leading Market Players |
|---|
| Evonik Industries AG |
| Jiande Lvke Chemical Industry Co., Ltd. |
| Chevron Phillips Chemical Company LLC |
| DuPont de Nemours, Inc. |
| Sanmenxia Aoke Chemical Industry |
| Arkema S.A. |
| Jiande Xingfeng Chemical |
| Solvay S.A. |
| Huntsman International LLC |
| Others |
Supply & Pricing Matrix
Hurricane exposure across the Gulf Coast petrochemical corridor compresses margin stability for odorant buyers while simultaneously widening price spreads between spot procurement and long-term offtake contracts. This concentration risk determines both the three-tier pricing structure across premium, standard, and economy levels and the geographic shape of supplier relationships.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake pricing across the mercaptan market. Three-tier pricing structure across premium, standard, and economy levels separates GMP-compliant pharmaceutical grades from industrial odorant specifications and bulk commodity blends. Cost compression in standard-grade aliphatic mercaptans is intensifying because crude sulfur feedstock volatility transmits directly into producer margins. Municipal gas utilities exhibit the highest price sensitivity due to regulated rate-base constraints, while pharmaceutical manufacturers prioritize batch traceability over unit cost.
Supply Chain Analysis
Export-control restrictions on fluorinated thiol synthesis equipment limit technology transfer to emerging production jurisdictions. Supply concentrates in the United States, China, and Germany, with hydrogen sulfide and elemental sulfur feedstocks drawn from integrated petrochemical complexes and refinery off-gas recovery streams. Single-source vulnerability runs through Gulf Coast corridor exposure to Atlantic hurricane seasons. Distribution runs through direct sales channels bundling chemical supply with injection equipment leasing and calibration maintenance services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Odorant injection service contracts represent a service-attach opportunity expanding faster than standalone chemical sales, as midstream operators outsource equipment calibration and regulatory compliance monitoring to specialty providers.
For Market Incumbents: Build captive sulfur handling capabilities as the primary moat against feedstock volatility. Secure multi-plant certifications under EPA Clean Air Act and REACH frameworks to defend against European specialty producers entering North American pipeline markets. Expand backward integration into hydrogen sulfide recovery from refinery operations to compress input cost exposure. For New Entrants and Emerging Players: Pursue modular odorant injection system leasing as the most penetrable entry vector into India's expanding city gas distribution networks. Target mid-size municipal utilities in Gujarat and Maharashtra seeking technical service bundling without capital-intensive infrastructure ownership. Qualify tetrahydrothiophene formulations where SAMR-administered GB standards tighten sulfur content restrictions. For Investors and Strategic Acquirers: REACH registration timeline compression for novel thiol derivatives reshapes the acquisition landscape toward producers with existing ECHA dossiers. Long-term viability favors integrated petrochemical conglomerates with methionine-mercaptan platform economics and multi-plant sulfur handling infrastructure. Monitor SAMR enforcement inspection frequency in Jiangsu and Zhejiang provinces as the signal indicating reformulation-driven demand inflection for higher-potency ethyl mercaptan blends.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive hydrogen sulfide recovery from refinery off-gas streams insulates margin stability from crude sulfur volatility. |
| Long-term Supply Agreement | Multi-year odorant injection service contracts with FERC-jurisdictioned pipeline operators lock in baseline demand regardless of commodity cycles. |
| Green Manufacturing Transition | Membrane separation hybrid units for mercaptan recovery from previously flared streams reduce waste disposal costs and generate merchant-grade feedstock. |
| Capacity Expansion | Additional production nodes in India address import dependence as Petroleum and Natural Gas Regulatory Board authorization rounds accelerate city gas distribution buildout. |
| Joint Venture | Partnerships with integrated livestock operators for methionine hydroxy analog supply bypass traditional feed compounder intermediaries in poultry nutrition markets. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and SAMR-administered regulatory enforcement records. Interviews with plant operations managers, procurement leads at municipal gas utilities, odorant injection service technicians, and technical R&D directors at pharmaceutical qualification centers inform demand-side segmentation. Bottom-up volume modeling triangulates against top-down value estimates derived from production capacity disclosures and regional pipeline mileage expansion data.
Forecast inputs include grade tier specifications, end-use industry absorption rates, regional production hub capacity utilization, and odorant concentration threshold evolution under tightening GB standards. Modeled dimensions span aliphatic versus specialty versus aromatic product categories, petrochemical versus agriculture versus pharmaceutical applications, and direct sales versus distributor channel splits. CAGRs were derived from regression analysis of historical procurement volumes against pipeline infrastructure investment cycles and livestock nutrition formulation shifts.
Sensitivities concentrate around SAMR enforcement intensity, Atlantic hurricane season disruption frequency, and REACH registration timeline compression for novel thiol derivatives. Forecasts reflect assumptions regarding continued EPA Clean Air Act odorization mandates and antibiotic-free feed protocol proliferation in integrated livestock operations. Material shifts in sulfur emission caps across European or Chinese jurisdictions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Calcium Chloride Market
Bulk Chemicals
Middle East Formaldehyde Market
Bulk Chemicals
Global Acrolein Market
Bulk Chemicals
United States Starch Derivatives Market
Bulk Chemicals
Activated Bleaching Earth Market
Bulk Chemicals
FT Wax Market
Bulk Chemicals
Elemental Sulfur Market
Bulk Chemicals
Calcium Bromide Market
Bulk Chemicals
Asia-Pacific Solid Sulfur Market
Bulk Chemicals
Antimony Trioxide Market
Bulk Chemicals
Magnesium Nitrate Hexahydrate Market
Bulk Chemicals
Germany Propylene Glycol Market
Bulk Chemicals
Hydrogen Bromide Market
Bulk Chemicals
Europe Acetic Acid Market
Bulk Chemicals
North America Acrylamide Monomer Market
Bulk Chemicals
Sodium Sulphate Market