
 Germany Propylene Glycol Market | 2026-2036
Germany Propylene Glycol Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Propylene Glycol Market Insights
A capital-intensity divergence between integrated refiners and specialty chemical operators is bifurcating the Germany propylene glycol landscape. BASF SE leverages its Ludwigshafen Verbund complex to sustain captive propylene oxide supply, anchoring cost positions across pharmaceutical and industrial grades. Evonik Industries AG differentiates through high-purity capabilities for sensitive end uses, while INEOS competes on merchant market volume and European logistics reach.
Propylene glycol designates a synthetic organic compound, C3H8O2, existing as a viscous, colorless liquid with a freezing point near -59°C and hygroscopic properties enabling moisture retention across formulations. Its primary commercial purpose spans solvent carriers, humectants, and heat-transfer fluids in food processing, drug delivery systems, and industrial de-icing. Pharmaceutical grade commands premium positioning due to USP/EP compliance burdens, whereas industrial grade occupies volume-driven segments where purity thresholds relax and margin pools compress. Food grade sustains steady offtake from German bakery and dairy processors seeking GRAS-certified additives.
Germany's Federal Institute for Drugs and Medical Devices enforces EMA-aligned pharmacopeia standards that elevate entry barriers for pharmaceutical grade supply, while REACH registration requirements govern industrial grade chemical safety dossiers. The EU Green Deal's chemical sustainability targets are forcing producers to document bio-based feedstock shares and carbon intensity across propylene glycol value chains. Stakeholders must monitor how Berlin implements the EU AI Act's quality-system mandates for automated pharmaceutical manufacturing, as these will reshape batch-release protocols and supplier qualification criteria.
Market Dynamics
Bio-based propylene glycol production is restructuring Germany's chemical manufacturing base as producers retrofit conventional petrochemical infrastructure to process glycerol-derived feedstocks. This conversion wave is compressing margins for fossil-route operators while creating certification premiums for renewable-origin supply.
Growth Catalysts
- EMA Pharmacopeia Revisions:Tightened purity mandates for pharmaceutical-grade propylene glycol are disqualifying marginal suppliers and consolidating volume with certified German producers.
- Food Processing Expansion:German bakery and dairy manufacturers are expanding humectant offtake for extended-shelf-life formulations under GRAS certification requirements.
- North Rhine-Westphalia Cluster Density:Proximity of specialty chemical infrastructure, logistics terminals, and technical universities is shortening R&D-to-commercialization cycles for novel propylene glycol derivatives.
Market Restraints
- Propylene Oxide Feedstock Volatility:Merchant buyers face margin compression when naphtha-cracker co-product availability fluctuates with regional refinery operating rates.
- REACH Dossier Burden:Industrial-grade suppliers must maintain extensive chemical safety documentation under ECHA registration requirements, elevating compliance overhead relative to non-EU competitors.
- Substitution by 1,3-Propanediol:Polymer manufacturers in select coating applications are reformulating around bio-sourced diol alternatives with comparable humectant performance.
Strategic Opportunities
- Bavarian Pharmaceutical Manufacturing Corridor:Underpenetrated contract manufacturing capacity around Munich offers anchor demand for USP-grade supply expansion.
- EU Green Deal Carbon Accounting:Mandatory feedstock origin disclosure creates pricing power for producers with documented bio-based content and verified lifecycle emissions.
- Heat-Transfer Fluid Electrification:Battery thermal management systems in German EV assembly plants are adopting propylene glycol coolants as dielectric alternatives to mineral oils.
Industry Challenges
- Pharmacopeia Certification Timelines:German drug manufacturers face extended batch-release protocols as BfArM aligns inspection procedures with EU AI Act automated manufacturing mandates.
- Glycerol Feedstock Quality Variance:Bio-based producers encounter yield inconsistency when sourcing crude glycerol from heterogeneous biodiesel waste streams across European collection networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Propylene Glycol Market |
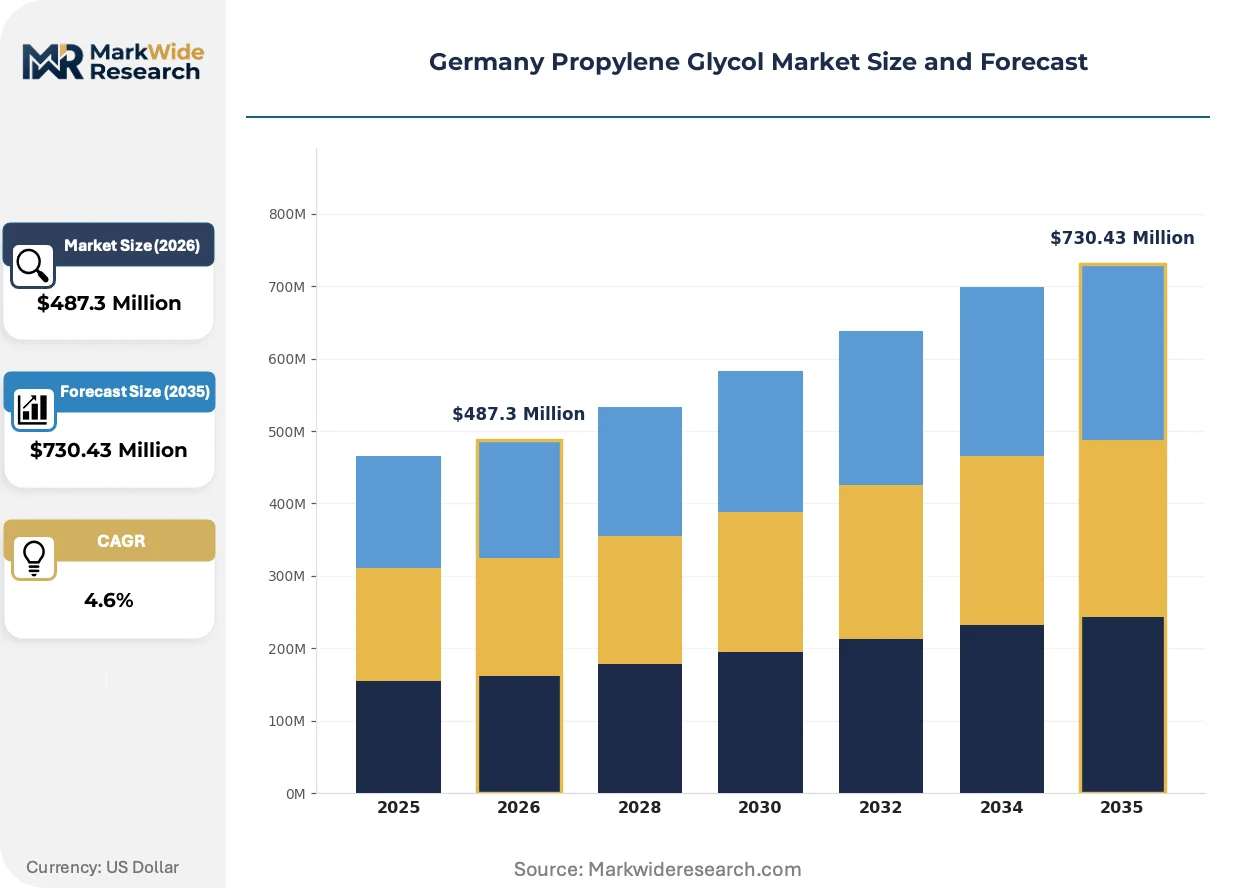
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $730.43 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Grade, Pharmaceutical Grade, Industrial Grade, Cosmetic Grade Application: Food & Beverage, Pharmaceuticals, Cosmetics, Industrial Manufacturing End User: Food Manufacturers, Drug Manufacturers, Cosmetic Brands, Industrial Enterprises Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | Evonik Industries AG, Archer Daniels Midland Company, BASF SE, MOL Group, Shell PLC, INEOS, LyondellBasell Industries Holdings B.V., HELM AG, Dow, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Propylene Glycol Market Trends and Innovations
Process chemistry innovations and regulatory disclosure mandates are simultaneously elevating sustainability credentials and manufacturing complexity for German propylene glycol suppliers. These forces are compressing the viable supplier base while opening premium positioning for verified low-carbon production.
Continuous-flow hydrogenolysis of glycerol to propylene glycol is bifurcating the technology landscape between batch-reactor legacy assets and integrated continuous-processing installations. Pharmaceutical compounders in Baden-Württemberg are prioritizing suppliers with continuous-manufacturing qualifications for supply security. This technology divide is enabling first-movers to capture ESG-linked procurement contracts while stranding conventional batch capacity in industrial-grade segments.
REACH registration requirements under ECHA oversight are expanding substance data obligations for industrial-grade propylene glycol derivatives used in de-icing and antifreeze formulations. German formulators must now document downstream exposure scenarios across professional and consumer use categories. Industrial-grade suppliers serving construction and automotive aftermarket channels are absorbing elevated testing costs that compress margin pools relative to pharmaceutical-grade alternatives.
Long-term offtake agreements are displacing spot-market purchasing among German pharmaceutical and food-grade buyers seeking supply continuity amid feedstock transition uncertainty. Contract structures now embed bio-content minimums and carbon-intensity thresholds that align with corporate Scope 3 reduction targets. This contracting evolution is most visible among multinational drug manufacturers with German manufacturing footprints, where procurement teams are consolidating supplier panels to reduce qualification overhead.
Germany Propylene Glycol Market Segmentation
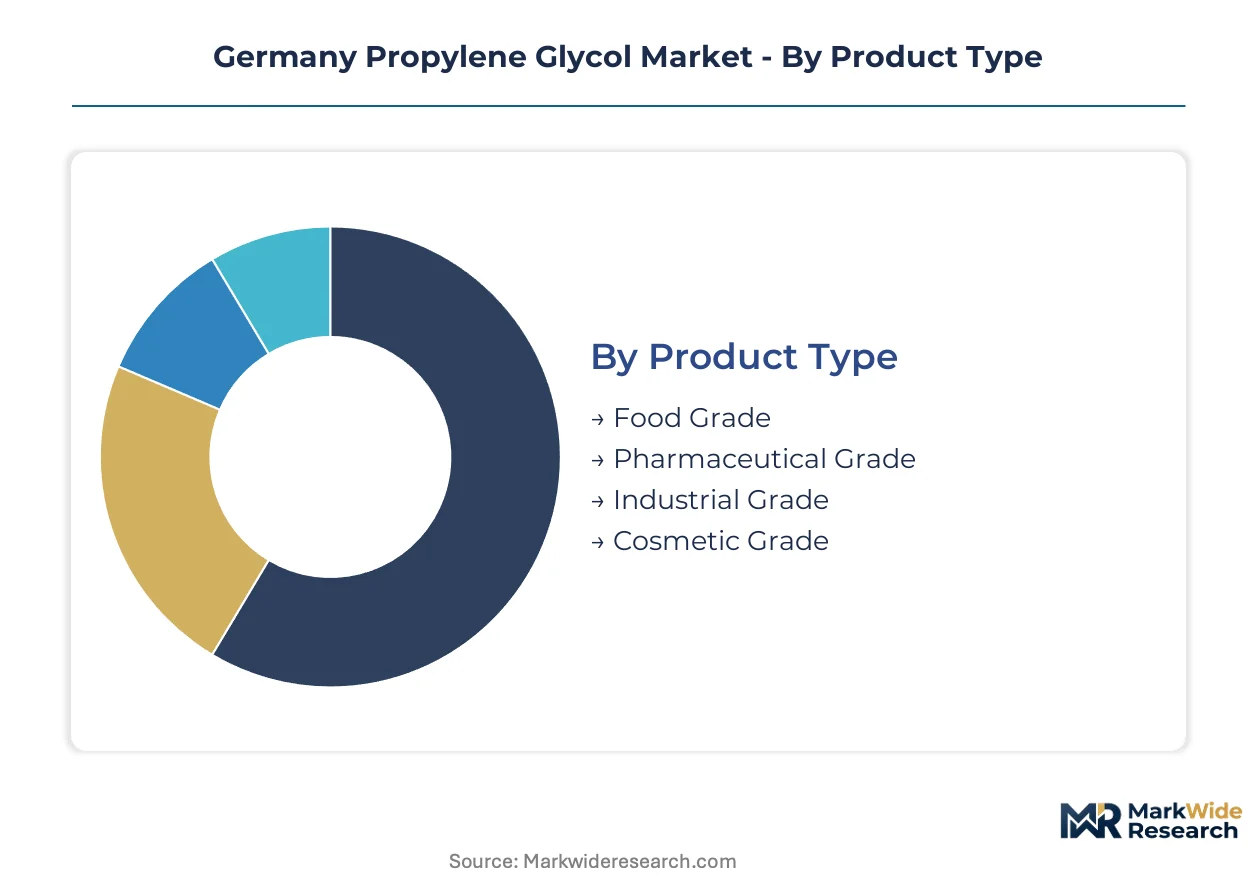
Propylene glycol pricing stratifies sharply across purity tiers, with pharmaceutical and food grades commanding substantial premiums over industrial volumes. German buyers segment procurement by regulatory burden, with EMA-aligned certification requirements filtering supplier eligibility and compressing the viable vendor base.
Product Type:
Margin pools concentrate in pharmaceutical grade where USP/EP compliance burdens elevate pricing power, while industrial grade competes on volume scale with compressed returns.
- Pharmaceutical Grade:USP/EP-compliant specification with purity thresholds exceeding 99.5% and strict limits on diethylene glycol impurities. German drug manufacturers in Baden-Württemberg and Bavaria anchor demand as BfArM tightens batch-release protocols under EU AI Act alignment.
- Food Grade:GRAS-certified formulation meeting EFSA purity standards for direct food contact applications. German bakery and dairy processors in North Rhine-Westphalia expand humectant offtake for extended-shelf-life bread and frozen dessert formulations.
- Industrial Grade:Technical specification for solvent carriers, de-icing fluids, and heat-transfer applications where purity thresholds relax. REACH dossier requirements under ECHA elevate compliance overhead relative to non-EU supply.
- Cosmetic Grade:Refined specification for personal care humectants and fragrance carriers meeting EU Cosmetics Regulation safety standards.
Pharmaceutical grade holds installed capacity concentration at Ludwigshafen and Marl sites. Cosmetic grade is rotating up the share rankings as German personal care exporters expand formulation capacity.
Application:
Application demand distributes across regulated consumer sectors and technical industrial uses, with pharmaceutical and food processing commanding priority in German procurement portfolios.
- Pharmaceuticals:Solvent carrier for oral, injectable, and topical drug delivery systems requiring pyrogen-free specification. German contract manufacturers around Munich and Frankfurt anchor offtake as EMA pharmacopeia revisions disqualify marginal suppliers.
- Food & Beverage:Humectant, solvent, and preservative carrier across bakery, dairy, and beverage processing. North Rhine-Westphalia's food manufacturing corridor sustains steady demand for moisture-retention formulations in extended-shelf-life products.
- Cosmetics:Personal care humectant and emollient base for skincare, haircare, and fragrance applications serving German export-oriented beauty brands.
- Industrial Manufacturing:Heat-transfer fluid, antifreeze, and chemical intermediate for automotive, construction, and electronics cooling systems.
Pharmaceuticals application captures the steepest expansion trajectory from Bavarian manufacturing corridor investments. Industrial Manufacturing is rotating up the share rankings as German EV battery plants adopt propylene glycol dielectric coolants.
End User:
End user procurement patterns diverge between multinational pharmaceutical compounders with consolidated supplier panels and fragmented industrial buyers exposed to spot market volatility.
- Drug Manufacturers:Multinational pharmaceutical compounders with German manufacturing footprints prioritize long-term offtake agreements embedding bio-content minimums and carbon-intensity thresholds for Scope 3 reduction compliance.
- Food Manufacturers:German bakery and dairy processors seeking GRAS-certified supply with documented feedstock origin for clean-label positioning in export markets.
- Cosmetic Brands:Personal care formulators requiring cosmetic-grade specification with batch traceability for EU Cosmetics Regulation compliance.
- Industrial Enterprises:Automotive, construction, and chemical processors purchasing industrial grade through merchant market channels with price sensitivity to propylene oxide feedstock fluctuations.
Drug Manufacturers hold installed capacity reservation through multi-year contracts. Food Manufacturers are rotating up the share rankings as clean-label demand intensifies procurement scrutiny.
Distribution Channel:
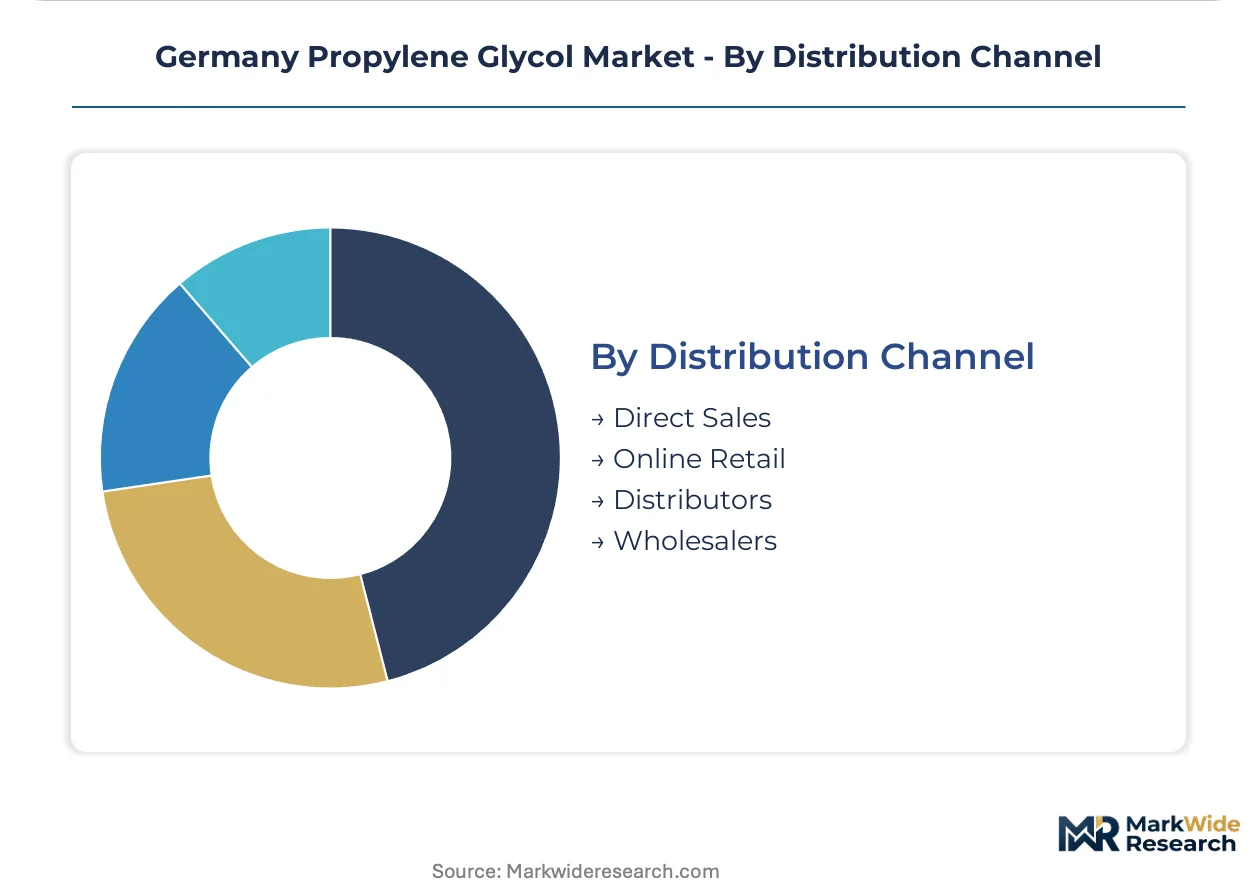
Channel selection tracks buyer scale and certification burden, with direct sales dominating pharmaceutical grade and intermediaries serving fragmented industrial demand.
- Direct Sales:Producer-to-manufacturer supply for pharmaceutical and food grade buyers requiring supplier qualification, audit trails, and batch documentation for regulatory compliance.
- Distributors:Regional chemical distributors holding inventory positions for industrial grade and mid-volume cosmetic applications across German manufacturing clusters.
- Wholesalers:Volume aggregation for industrial de-icing, antifreeze, and construction sector buyers with standardized technical specifications.
- Online Retail:Emerging channel for small-scale cosmetic and food processing buyers seeking rapid procurement with documented certification.
Direct Sales holds installed capacity lock-in from pharmaceutical qualification protocols. Online Retail is rotating up the share rankings as digital procurement platforms expand chemical marketplace coverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German propylene glycol consumption diverges from neighboring markets through its pharmaceutical-heavy demand mix, where EMA-aligned purity standards concentrate procurement with domestic certified producers rather than the industrial-grade dominance seen in Eastern European markets.
North Rhine-Westphalia
Cologne-Düsseldorf chemical corridor anchors industrial-grade demand from automotive coolant formulators and construction de-icing compounders. ECHA REACH registration requirements filter supplier eligibility for technical applications. Marl industrial complex sustains integrated propylene oxide-to-glycol production serving merchant market channels.
Bavaria
Munich-Frankfurt pharmaceutical manufacturing belt drives USP-grade offtake for injectable and topical drug delivery systems. BfArM batch-release protocols under EU AI Act alignment extend supplier qualification timelines. Penzberg biologics cluster contracts for pyrogen-free specification propylene glycol in mRNA formulation buffers.
Baden-Württemberg
Stuttgart pharmaceutical compounders prioritize continuous-manufacturing qualified suppliers for supply security in oral solid dosage applications. EMA pharmacopeia revisions disqualify marginal importers from certified procurement panels. Ludwigshafen chemical complex feeds downstream formulators across the state via dedicated logistics corridors.
Lower Saxony
Food processing manufacturers in Hanover-Braunschweig corridor expand GRAS-certified humectant procurement for extended-shelf-life bakery formulations. EFSA purity standards govern direct food contact applications. Wolfsburg automotive cluster tests propylene glycol dielectric coolants for battery thermal management in EV assembly.
Hesse
Frankfurt chemical distributors aggregate industrial-grade volumes for construction and automotive aftermarket channels. EU Green Deal carbon accounting mandates drive feedstock origin documentation requirements. Rhein-Main logistics hub enables just-in-time delivery to pharmaceutical contract manufacturers in adjacent regions.
Germany Propylene Glycol Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with backward integration into propylene oxide feedstock separating cost-competitive volume players from margin-dependent merchant buyers. The market structure rewards captive raw material access and pharmacopeia certification depth over pure scale. Two strategic archetypes dominate: integrated petrochemical operators with Verbund site economics, and high-purity specialists with pharmaceutical-grade qualification protocols. Competitive moves concentrate on bio-based capacity retrofits and long-term offtake contract structures embedding carbon-intensity thresholds.
Among Germany-based integrated operators, BASF SE and Evonik Industries AG exemplify divergent positioning archetypes. BASF SE anchors cost positions through Ludwigshafen Verbund captive supply, while Evonik Industries AG occupies the high-purity specialist tier. INEOS represents the merchant-market volume competitor with European logistics reach. These three entities collectively illustrate how feedstock control, certification depth, and distribution scale segment competitive positioning across pharmaceutical, food, and industrial grade segments.
| Leading Market Players |
|---|
| Evonik Industries AG |
| Archer Daniels Midland Company |
| BASF SE |
| MOL Group |
| Shell PLC |
| INEOS |
| LyondellBasell Industries Holdings B.V. |
| HELM AG |
| Dow |
| Others |
Pricing and Supply Chain Analysis
Glycerol-to-propylene glycol conversion is displacing naphtha-cracker co-product routes across Germany's chemical corridor, simultaneously compressing fossil-route margins and redrawing supply geography toward Marl and Ludwigshafen integrated sites with captive bio-feedstock processing.
Pricing Analysis
Long-term offtake agreements now dominate pharmaceutical and food-grade procurement, embedding bio-content minimums and carbon-intensity thresholds that compress spot-market liquidity. Three-tier pricing structure across pharmaceutical, food, and industrial grades reflects certification burden divergence, with USP/EP compliance elevating pharmaceutical premiums. Pricing pressure stems from glycerol feedstock quality variance across European biodiesel waste streams. Industrial-grade buyers in construction and automotive aftermarket channels exhibit highest price sensitivity to propylene oxide availability fluctuations.
Supply Chain Analysis
Rotterdam-Antwerp port congestion and container availability constraints on North Sea trade lanes elevate inbound logistics costs for merchant propylene oxide feedstock. Supply concentrates in Germany, Belgium, and the Netherlands through integrated Verbund sites and Marl production complex. Raw material dependencies rest on propylene oxide, crude glycerol, and hydrogen feedstocks. Single-source vulnerability from concentrated propylene oxide supply creates structural risk. Distribution runs through direct sales for certified grades and regional chemical distributors for industrial volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Carbon accounting and Scope 3 disclosure services represent a faster-expanding recurring-revenue layer than commodity propylene glycol production, as pharmaceutical buyers embed verification requirements into procurement contracts.
For Market Incumbents: Shield certified-grade market share by accelerating continuous-flow hydrogenolysis retrofits before batch-reactor assets strand in industrial segments. Prioritize BfArM qualification protocol completion ahead of EU AI Act implementation timelines. Backward integration into glycerol purification infrastructure mitigates yield inconsistency from heterogeneous biodiesel waste streams. For New Entrants and Emerging Players: Differentiate on documented bio-based content with third-party lifecycle verification to capture ESG-linked procurement contracts from multinational drug manufacturers. The Bavarian pharmaceutical manufacturing corridor around Munich offers the most penetrable white-space for USP-grade supply expansion. Pursue anchor tenant arrangements with Penzberg biologics cluster formulators seeking pyrogen-free specification buffers. For Investors and Strategic Acquirers: The market sits at a feedstock-transition phase that favors continuous-manufacturing-qualified assets with pharmacopeia certification depth. Long-term viability hinges on carbon-intensity documentation capabilities rather than scale economics alone. Watch glycerol spot-price spreads against propylene oxide as the inflection indicator for bio-route margin sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Glycerol Purification | Captures margin from biodiesel waste stream processing while securing feedstock quality consistency. |
| Continuous-Flow Hydrogenolysis Retrofit | Positions assets for pharmaceutical compounder qualification under EU AI Act batch-release alignment. |
| Long-term Supply Agreement with Carbon Clauses | Locks in multinational drug manufacturer procurement panels before supplier consolidation completes. |
| Green Certification Program | Enables premium positioning under EU Green Deal mandatory feedstock origin disclosure mandates. |
| Joint Venture with Biodiesel Producer | Secures preferential crude glycerol offtake from European collection networks at stabilized transfer pricing. |
Research Methodology
A spread of perspectives from plant managers at integrated chemical sites, procurement leads at German pharmaceutical compounders, distribution channel partners in North Rhine-Westphalia, and technical R&D directors converged on the working assumptions. These primary insights combined with customs and trade data, Cefic industry reports, SEC 10-K chemical sector filings, and BfArM regulatory guidance documents. Bottom-up capacity assessments and top-down demand triangulation validated volume estimates.
Grade tier, end-use industry, and regional production hub dimensions structured the analytical framework across the projection horizon. CAGRs derived from segment-level growth rate synthesis and feedstock transition elasticity modeling. Propylene oxide price forecasting and pharmaceutical manufacturing capacity expansion timelines served as industry-specific inputs.
Forecasts assume regulatory continuity in EMA pharmacopeia standards and REACH registration requirements; material policy shifts would require re-modeling. Glycerol feedstock availability variance and EU AI Act implementation timing represent specific risk factors. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Sulfamic Acid Market
Bulk Chemicals
United Kingdom Lime Market
Bulk Chemicals
Copper Sulfate Market
Bulk Chemicals
Polyferric Sulfate Market
Bulk Chemicals
Glucaric Acid Market
Bulk Chemicals
Furfural Market
Bulk Chemicals
DL-Methionine Market
Bulk Chemicals
North America Lime Market
Bulk Chemicals
Cyclohexane Market
Bulk Chemicals
2-Ethyl Hexanol Market
Bulk Chemicals
Isoprene Monomer Market
Bulk Chemicals
Aluminum Sulfide Market
Bulk Chemicals
Mexico Calcium Carbonate Market
Bulk Chemicals
Chemical Warehousing Market
Bulk Chemicals
Ammonium Nitrate Market
Bulk Chemicals
Global Cyclohexylbenzene Market