
 Helical Submerged Arc Welded Pipe Market | 2026-2036
Helical Submerged Arc Welded Pipe Market Size, Share, and Industry Trends Forecast 2026-2036
Helical Submerged Arc Welded Pipe Market Insights
Certified welder availability is rotating toward constraint in several producing regions, pressuring throughput timelines at spiral pipe mills. Nippon Steel Corporation leverages captive steelmaking to secure coil supply for its helical SAW operations. TMK anchors its position through dedicated threading and coating facilities serving Russian and Caspian trunkline projects. JFE Steel Corporation differentiates via high-strength API grades and sour-service metallurgy for deepwater applications.
Helical submerged arc welded pipe is manufactured from hot-rolled steel strip formed into a helical seam and welded by submerged arc processes, typically yielding diameters from 16 to 100 inches with wall thicknesses suited to high-pressure hydrocarbon service. The product serves primarily as line pipe for oil and gas transmission, water conveyance, and structural piling where diameter flexibility and cost efficiency outweigh seamless alternatives. Large diameter and jumbo diameter categories dominate volume owing to trunkline replacement cycles in North America and Middle East water infrastructure. API 5L X70 material grade captures expanding share as operators specify higher operating pressures and reduced wall thickness for transport economy.
API monogram licensing requirements, ASME B31.8 pipeline codes, and national pressure-equipment regulations in Germany and Japan govern design qualification and market access for helical SAW products. Compliance with these frameworks shapes R&D allocation toward fracture toughness and hydrogen embrittlement resistance. Stakeholders must monitor evolving integrity-management mandates for hydrogen blending in natural gas networks.
Market Dynamics
Certified welder scarcity across the US Gulf Coast and Middle East production corridors is compressing spiral mill throughput timelines while API 5L X70 grade specifications accelerate under stricter ASME B31.8 interpretations.
Growth Catalysts
- Offshore pipeline mandates:Deepwater trunkline specifications in the US Gulf of Mexico and Brazil's pre-salt fields require high-strength helical SAW pipe for pressure ratings exceeding 1,000 psi.
- Hydrogen blending infrastructure:Germany's national hydrogen strategy and amended EU gas quality standards are creating demand for fracture-tolerant pipe grades capable of hydrogen service.
- Water conveyance modernization:Saudi Arabia's National Water Company and India's Jal Jeevan Mission are specifying large-diameter helical pipe for desalination and rural distribution networks.
Market Restraints
- Hot-rolled coil volatility:Steel input costs fluctuate with scrap and iron ore pricing, squeezing mill margins on fixed-price trunkline contracts.
- API monogram concentration:Licensed manufacturing capacity clusters in China, Japan, and South Korea, creating geographic supply risk for European and North American project timelines.
- Seamless pipe substitution:Premium sour-service applications in high-H2S Canadian oil sands increasingly specify seamless alternatives for extreme corrosion resistance.
Strategic Opportunities
- Carbon capture transport:Supercritical CO2 pipeline specifications in the US Permian Basin and Norway's Northern Lights project require thick-wall helical pipe with enhanced toughness.
- India's pipeline expansion:The Petroleum and Natural Gas Regulatory Board's city gas distribution licensing rounds are generating demand for 18-36 inch distribution mains.
- Digital twin integration:Real-time weld monitoring and automated ultrasonic testing convergence enables predictive integrity management for aging North American infrastructure.
Industry Challenges
- ASME Section IX welder certification:Qualification timelines for spiral SAW procedures extend 12-18 months, constraining workforce elasticity during demand surges.
- Coating facility bottlenecks:Three-layer polyethylene and fusion-bonded epoxy application capacity lags pipe production, creating finished goods inventory pressure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Helical Submerged Arc Welded Pipe Market |
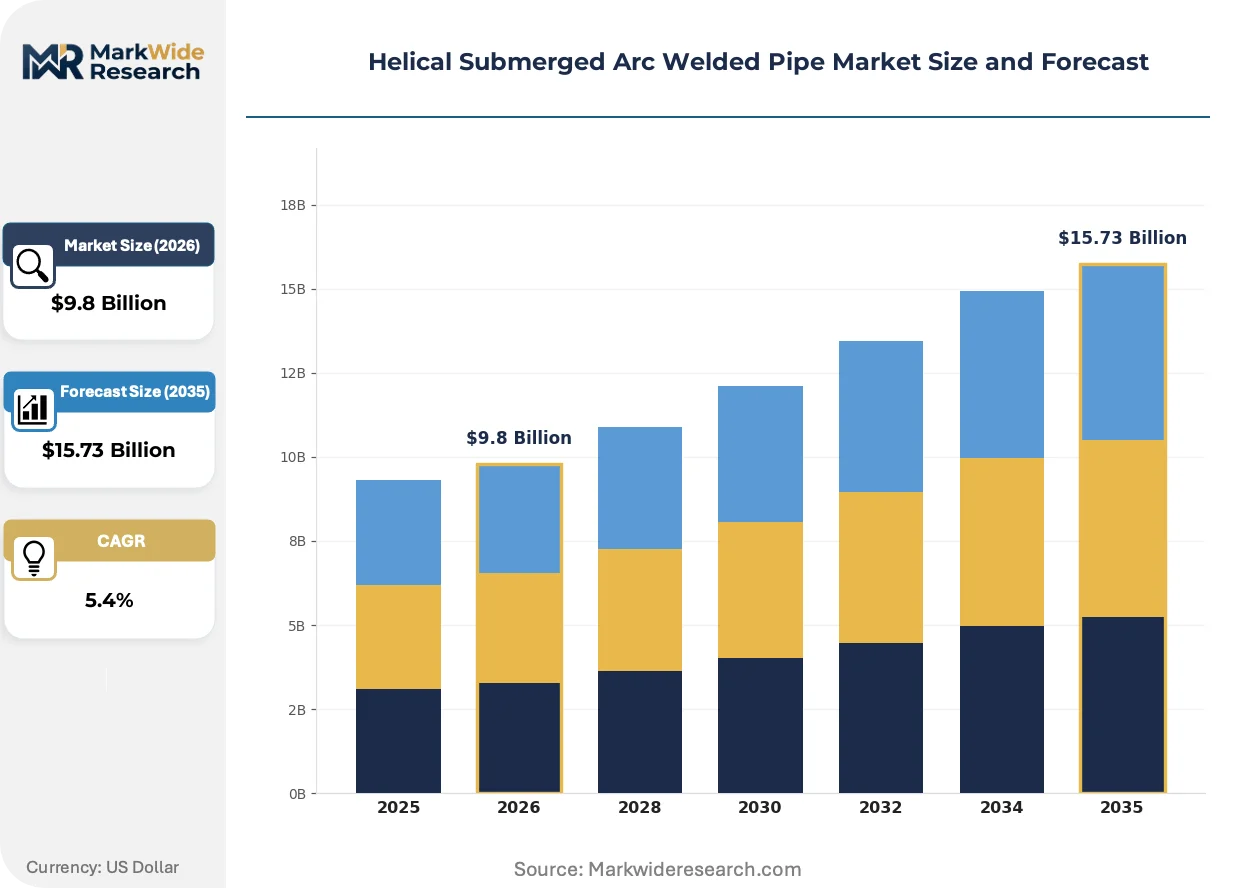
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Pipe Size: Small Diameter, Medium Diameter, Large Diameter, Jumbo Diameter Material Grade: API 5L B, API 5L X42, API 5L X52, API 5L X70 End Use Industry: Oil & Gas, Construction, Water Transportation, Energy Generation Application Type: Pipeline Transportation, Structural Support, Water Supply Systems, Industrial Process Piping |
| Companies Covered | Nippon Steel Corporation, EVRAZ, TMK, Baosteel Group Corporation, Jindal SAW, JFE Steel Corporation, Welspun Corporation Limited, Europipe GmbH, ArcelorMittal, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Helical Submerged Arc Welded Pipe Market Trends and Innovations
Helical SAW manufacturing is experiencing simultaneous pressure from metallurgical advancement, regulatory tightening on hydrogen compatibility, and procurement consolidation among major trunkline operators.
High-frequency induction heating for seam normalizing is decomposing traditional furnace-based heat treatment cycles. US and Middle East mills adopting this technology reduce energy consumption per ton by half while achieving API 5L X80 yield strengths. The process compression is enabling faster qualification timelines for ultra-high-strength grades.
EU F-Gas Regulation amendments and the EU Green Deal hydrogen backbone initiative are mandating leak-tightness verification for blended hydrogen service. German transmission operators now require 100% ultrasonic inspection of helical seams plus supplemental Charpy testing at sub-zero temperatures. Pipe mills serving European projects are retooling inspection lines to meet these protocols.
Integrated service contracts now bundle pipe supply with field joint coating and integrity monitoring. Major operators in Australia's Browse Basin and Kazakhstan's Tengiz expansion are sourcing through single-source agreements that shift technical risk to manufacturers. This consolidation favors mills with captive threading, coating, and logistics capabilities over pure pipe producers.
Helical Submerged Arc Welded Pipe Market Segmentation
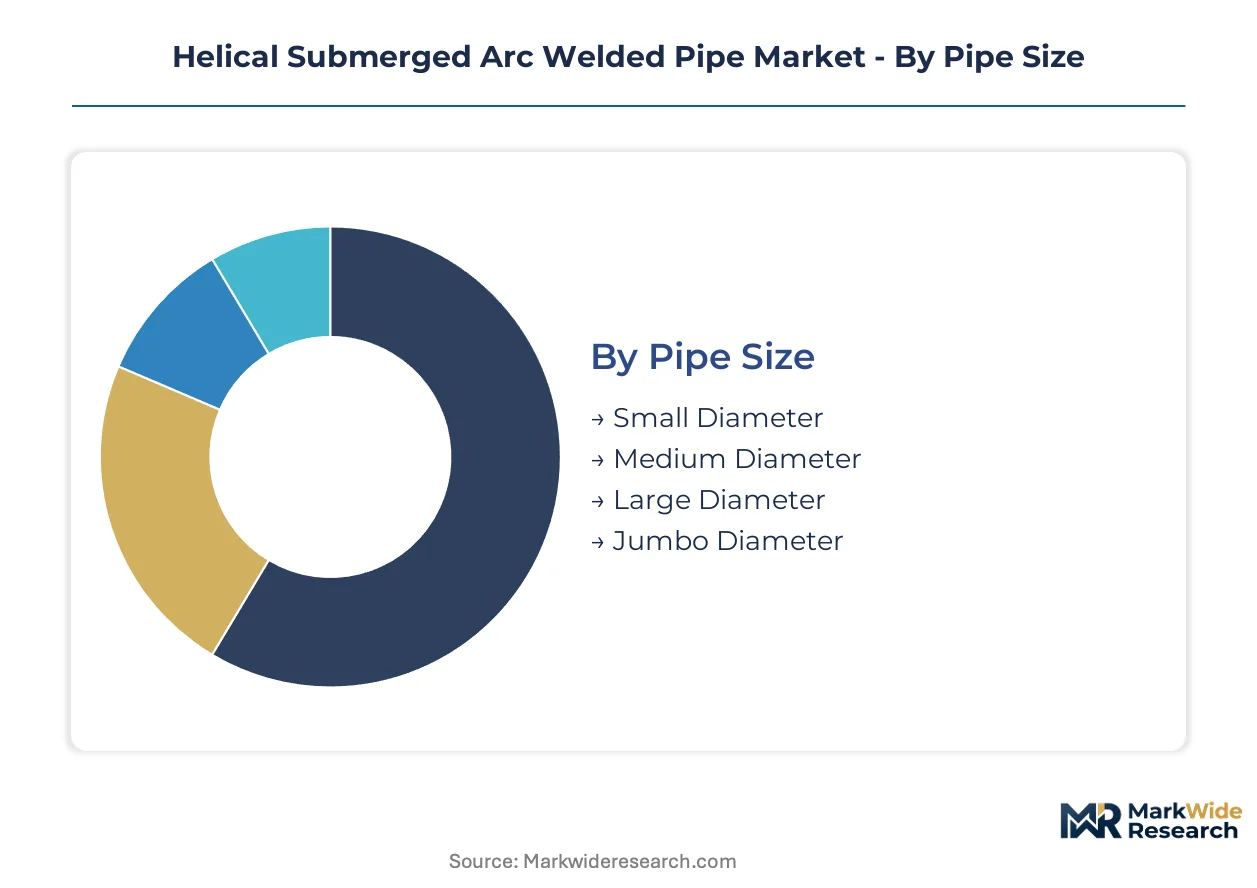
Helical SAW pipe procurement stratifies across diameter, metallurgical grade, and end-use specifications. Each dimension carries distinct substitution pressures from seamless alternatives and composite materials.
Pipe Size:
Seamless pipe substitution pressure intensifies as diameter decreases, with small-diameter segments facing the strongest competitive displacement.
- Large Diameter:Specified for 24-48 inch trunkline applications where spiral mill efficiency outweighs seamless cost premiums. North American pipeline replacement cycles and Middle East water infrastructure projects concentrate demand here. API 5L X70 grade penetration is deepest in this tier due to pressure-equipment code requirements.
- Jumbo Diameter:Exceeds 48 inches for desalination intake lines and offshore platform riser supports. Saudi Arabia's National Water Company and India's Jal Jeevan Mission specify these dimensions for bulk conveyance. Manufacturing requires specialized forming equipment that limits qualified supplier pools.
- Medium Diameter:Serves distribution networks and gathering lines at 16-24 inch specifications.
- Small Diameter:Below 16 inches faces seamless pipe displacement in high-pressure sour-service environments.
Large Diameter anchors the volume base while Jumbo Diameter gains share at the steepest rate.
Material Grade:
Cost tiering separates specification-driven premium grades from commodity interchangeables in procurement portfolios.
- API 5L X70:High-strength low-alloy steel delivering 70,000 psi minimum yield strength. ASME B31.8 interpretations and FERC pressure-equipment mandates in the United States accelerate specification. Operators achieve reduced wall thickness for equivalent pressure ratings, improving transport economics on long-haul trunklines.
- API 5L X52:Workhorse grade for standard-pressure hydrocarbon transmission and water conveyance. India's Petroleum and Natural Gas Regulatory Board city gas distribution rounds specify this grade for 18-36 inch distribution mains. Mills achieve faster qualification timelines versus X70, supporting surge capacity.
- API 5L B:Base specification for low-pressure structural and piling applications.
- API 5L X42:Intermediate grade for moderate-pressure rural distribution networks.
API 5L X52 retains the largest shipment volume while API 5L X70 climbs the fastest on specification upgrades.
End Use Industry:
Application maturity determines margin structure, with established hydrocarbon segments defending price against emerging energy transition demand.
- Oil & Gas:Dominant demand source spanning gathering, transmission, and distribution infrastructure. Deepwater specifications in the US Gulf of Mexico and Brazil's pre-salt fields require enhanced toughness and sour-service metallurgy. Integrated service contracts now bundle pipe supply with field joint coating and integrity monitoring.
- Water Transportation:Desalination and municipal distribution networks in Saudi Arabia, India, and the United Arab Emirates specify large-diameter helical pipe. Corrosion-resistant coatings and cement mortar lining differentiate offerings versus ductile iron alternatives.
- Construction:Structural piling and foundation applications compete with concrete and composite substitutes.
- Energy Generation:Cooling water intake and thermal cycle piping for power plants.
Oil & Gas commands the revenue base while Water Transportation expands most quickly on infrastructure modernization.
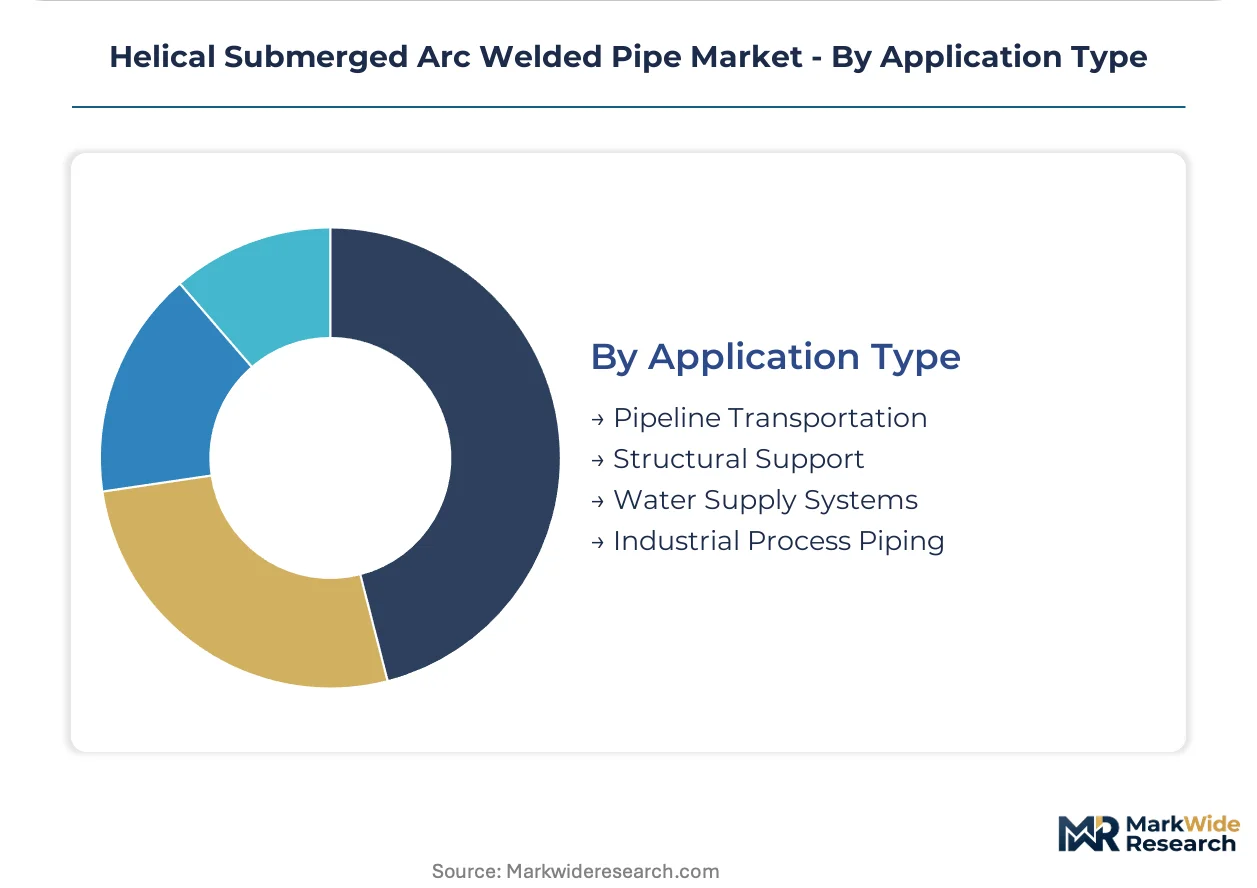
Application Type:
Customer procurement patterns separate long-term trunkline commitments from spot structural purchases.
- Pipeline Transportation:Long-haul hydrocarbon and CO2 trunklines requiring fracture toughness verification and automated ultrasonic testing. Germany's hydrogen backbone initiative and Norway's Northern Lights carbon capture project specify thick-wall helical pipe with sub-zero Charpy requirements. EU F-Gas Regulation amendments mandate enhanced leak-tightness protocols.
- Water Supply Systems:Municipal distribution and agricultural irrigation networks. India's Jal Jeevan Mission and Saudi Arabia's National Water Company drive specification toward large-diameter, cement-lined configurations.
- Structural Support:Piling and foundation applications with shorter procurement cycles.
- Industrial Process Piping:Refinery and petrochemical unit connections.
Pipeline Transportation dominates contract value while Water Supply Systems show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FERC pressure-equipment mandates and ASME B31.8 interpretations in the United States anchor regulatory gravity for helical SAW pipe specifications worldwide. Procurement concentrates around energy corridors where trunkline replacement cycles intersect with deepwater exploration frontiers.
United States
The US Gulf of Mexico pre-salt fields and Permian Basin carbon capture networks drive demand for API 5L X70 grades. FERC interstate pipeline safety standards mandate enhanced fracture toughness testing. Houston-Galveston petrochemical clusters host spiral mill capacity serving trunkline operators.
Germany
Hydrogen backbone infrastructure and Northern Lights carbon transport specifications require sub-zero Charpy-rated helical pipe. EU F-Gas Regulation amendments mandate 100% ultrasonic seam inspection. Ruhr industrial corridors concentrate coating and threading facilities serving North Sea projects.
Saudi Arabia
Desalination intake lines and National Water Company distribution networks specify jumbo-diameter helical configurations. The country's national pressure-equipment regulator enforces API monogram compliance for hydrocarbon service. Jubail Industrial City anchors manufacturing capacity for Middle East water infrastructure.
India
Petroleum and Natural Gas Regulatory Board city gas distribution licensing generates demand for 18-36 inch distribution mains. BIS standards alignment with API 5L grades accelerates domestic specification. Gujarat pipeline corridors concentrate spiral mill investment serving Jal Jeevan Mission rural networks.
Brazil
Pre-salt deepwater trunklines require high-strength helical SAW pipe rated above 1,000 psi operating pressure. ANP petroleum regulator mandates sour-service metallurgy for offshore applications. Rio de Janeiro-Santos logistics basins coordinate pipe supply for Campos Basin development.
Helical Submerged Arc Welded Pipe Market Competitive Landscape
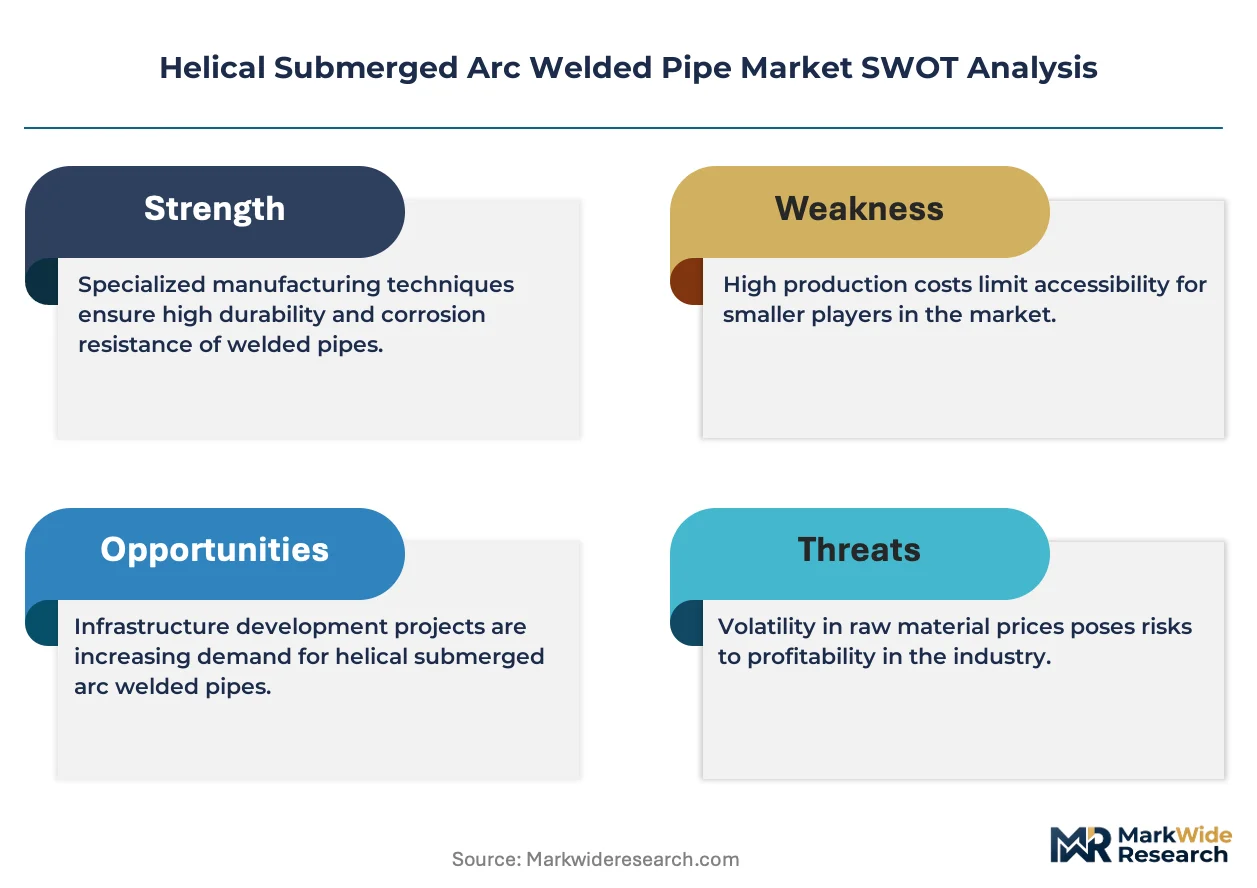
A small set of integrated leaders sits above a broader specialist tier in helical SAW pipe manufacturing. Captive steelmaking and coating capabilities separate the upper tier from coil-dependent fabricators. Strategic archetypes include integrated steelmakers with spiral mill operations, pure-play pipe specialists with threading facilities, and regional champions serving protected domestic markets. Capacity expansion and backward integration into hot-rolled coil supply represent dominant competitive moves.
Among Japanese integrated steelmakers, Nippon Steel Corporation and JFE Steel Corporation exemplify the captive-supply archetype through in-house coil production for helical seam operations. TMK anchors the specialist tier with dedicated threading and coating infrastructure. These three occupy positions reflecting distinct strategic bets on metallurgical control versus fabrication flexibility.
| Leading Market Players |
|---|
| Nippon Steel Corporation |
| EVRAZ |
| TMK |
| Baosteel Group Corporation |
| Jindal SAW |
| JFE Steel Corporation |
| Welspun Corporation Limited |
| Europipe GmbH |
| ArcelorMittal |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake contracts between trunkline operators and spiral mills lock in hot-rolled coil supply visibility while fixing API 5L grade pricing across multi-year project horizons. This structure concentrates pricing power with integrated steelmakers possessing captive coil production, leaving coil-dependent fabricators exposed to margin compression during scrap and iron ore volatility.
Pricing Analysis
Price spreads between US Gulf Coast and Middle East delivery points widen during FERC-mandated specification upgrades, with API 5L X70 grades commanding premiums over X52 workhorse specifications. Three-tier pricing structure across premium sour-service, standard high-pressure, and economy water-conveyance tiers separates procurement portfolios. Cost compression in economy grades intensifies as Indian and Chinese mills compete on volume for Jal Jeevan Mission and desalination contracts. Municipal water authorities exhibit highest price sensitivity, while deepwater trunkline operators prioritize fracture toughness over unit cost.
Supply Chain Analysis
Strategic stockpiling of certified coil inventory dominates procurement behavior among Japanese and South Korean integrated mills, whereas US and European fabricators lean toward just-in-time delivery to minimize working capital exposure. Hot-rolled coil supply concentrates in China, Japan, and South Korea, with API monogram licensing clustering manufacturing capacity in these jurisdictions. Production draws from scrap-fed electric arc and iron ore-based blast furnace routes, with energy costs and carbon border adjustments creating divergence in input economics. Single-source vulnerability in specialized forming equipment for jumbo-diameter pipe limits qualified supplier pools. Distribution runs through port-centric logistics corridors serving Gulf Coast petrochemical clusters and Middle East water infrastructure hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Helical SAW pipe procurement is consolidating around integrated service platforms bundling pipe, coating, and integrity monitoring, with interoperability between mill digital systems and operator asset management platforms becoming the decisive ecosystem battleground.
For Market Incumbents: Shield market position through backward integration into captive hot-rolled coil supply and dedicated coating facility expansion. Nippon Steel Corporation's coil-to-pipe control and TMK's threading infrastructure exemplify defensive moats against emerging Asian competitors. Prioritize API 5L X80 qualification timelines to capture premium deepwater specifications before technology diffusion erodes metallurgical differentiation. For New Entrants and Emerging Players: Anchor in India's city gas distribution expansion and Saudi Arabia's desalination modernization as penetrable demand corridors where specification requirements remain less stringent than North American deepwater standards. Target 18-36 inch distribution mains for Petroleum and Natural Gas Regulatory Board licensing rounds. Pursue joint qualification partnerships with established coating facilities to overcome three-layer polyethylene application bottlenecks. For Investors and Strategic Acquirers: Regional champions with API monogram compliance and protected domestic market access represent the most defensible acquisition archetype for long-horizon infrastructure exposure. Mills serving Germany's hydrogen backbone or Brazil's pre-salt development offer transition-optionality between hydrocarbon and energy-transition demand. Monitor ASME Section IX welder certification queue lengths as inflection signal—extended timelines indicate demand surge capacity constraints that favor integrated operators with established qualification pipelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hot-Rolled Coil | Nippon Steel Corporation's captive steelmaking secures supply continuity for helical SAW operations during scrap price spikes. |
| API 5L X80 Metallurgical Qualification | High-frequency induction heating enables faster certification timelines for ultra-high-strength grades serving US Gulf of Mexico deepwater. |
| Integrated Service Contract Bundling | Single-source agreements covering pipe, field joint coating, and integrity monitoring shift technical risk from Browse Basin operators to manufacturers. |
| Three-Layer Polyethylene Coating Expansion | Coating facility capacity lags pipe production, creating finished goods inventory pressure and margin compression for pure-play producers. |
| Digital Twin Weld Monitoring Deployment | Real-time automated ultrasonic testing convergence enables predictive integrity management for aging North American trunkline infrastructure. |
Research Methodology
Operator-level perspectives from pipeline procurement directors, spiral mill operations managers, ASME Section IX welding inspectors, and FERC compliance officers anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with secondary validation against API monogram licensing databases, ASME B31.8 code interpretation filings, and customs trade records for hot-rolled coil and finished pipe movements. Bottom-up shipment data from spiral mill capacity assessments triangulated with top-down energy infrastructure investment tracking across the analysis window.
Sensitivity analysis tested forecast robustness against welder certification timeline extensions, scrap price volatility scenarios, and hydrogen blending infrastructure acceleration. Segmentation modeling spanned diameter tier, API grade specification, end-use industry, and regional regulatory cluster dimensions. CAGRs derived from project pipeline visibility and replacement cycle timing, with inputs including deepwater trunkline sanctioning rates, city gas distribution licensing rounds, and desalination capacity expansion schedules.
Decision-makers should treat outputs as directional under base assumptions of sustained hydrocarbon trunkline investment and gradual hydrogen network retrofit adoption; material deviation would warrant model refresh. Forecasts reflect these assumptions with acknowledged sensitivity to ASME code amendments, carbon border adjustment implementation, and seamless pipe substitution in sour-service applications. Revision becomes warranted when certified welder queue durations exceed 18-month thresholds or when API 5L X70 specification penetration diverges from FERC pressure-equipment code adoption trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Petroleum Products
Asia-Pacific Lubricants Market
Petroleum Products
Crude Tall Oil Market
Petroleum Products
PAG Base Oil Market
Petroleum Products
Petroleum Liquid Feedstock Market
Petroleum Products
United States Refined Petroleum Products Market
Petroleum Products
Pale Oil Market
Petroleum Products
South Africa Petroleum Market
Petroleum Products
Saudi Arabia Refined Petroleum Products Market
Petroleum Products
India White Oil Market
Petroleum Products
North America Natural Gas Liquids Market
Petroleum Products
Southeast Asia Refined Petroleum Products Market
Petroleum Products
Germany Refined Petroleum Products Market
Petroleum Products
Asia Pacific Base Oil Market
Petroleum Products
Refined Petroleum Products Market
Petroleum Products
Natural Gas Liquid Market
Petroleum Products
Uganda Petroleum Products Market