
 Southeast Asia Refined Petroleum Products Market | 2026-2036
Southeast Asia Refined Petroleum Products Market Size, Share, and Industry Trends Forecast 2026-2036
Southeast Asia Refined Petroleum Products Market Analytics
Indonesia's cleaner fuel standards is shifting procurement toward low-sulfur gasoline and diesel across archipelagic distribution networks. PT Pertamina (Persero) leverages its monopoly over domestic refining and retail infrastructure to anchor national supply security. PETRONAS competes through integrated petrochemical complexes in Malaysia that extend downstream value capture. Shell PLC differentiates via premium lubricant and specialty fuel formulations targeting urban commercial fleets.
Refined petroleum products are hydrocarbon outputs from crude oil distillation and conversion processes, typically characterized by specific gravity ranges, sulfur content below 50 ppm for Euro-5 grades, and energy densities between 34-45 MJ/kg depending on cut fraction; these fuels power internal combustion engines, industrial heat systems, and aviation turbines across commercial and defense applications. Gasoline retains the largest volume share across Southeast Asian retail channels as motorcycle and passenger vehicle ownership expands, while jet fuel represents the fastest-growing product type as low-cost carriers add intra-ASEAN routes. The marine application segment commands premium pricing through IMO-compliant very low sulfur fuel oil, contrasting with power generation's declining share as renewables displace diesel baseload across island grids.
Indonesia's Ministry of Energy and Mineral Resources enforces progressive sulfur caps that force refinery upgrades or increased product imports, while Singapore's Maritime and Port Authority implements bunker fuel standards that redirect blending activity through the Strait of Malacca hub. Thailand's Department of Energy Business monitors retail pump quality through periodic sampling protocols that protect consumer engine warranties and emissions compliance. Stakeholders must track national refinery upgrade timelines against import dependency risks as regional demand outpaces installed cracking and hydrotreating capacity.
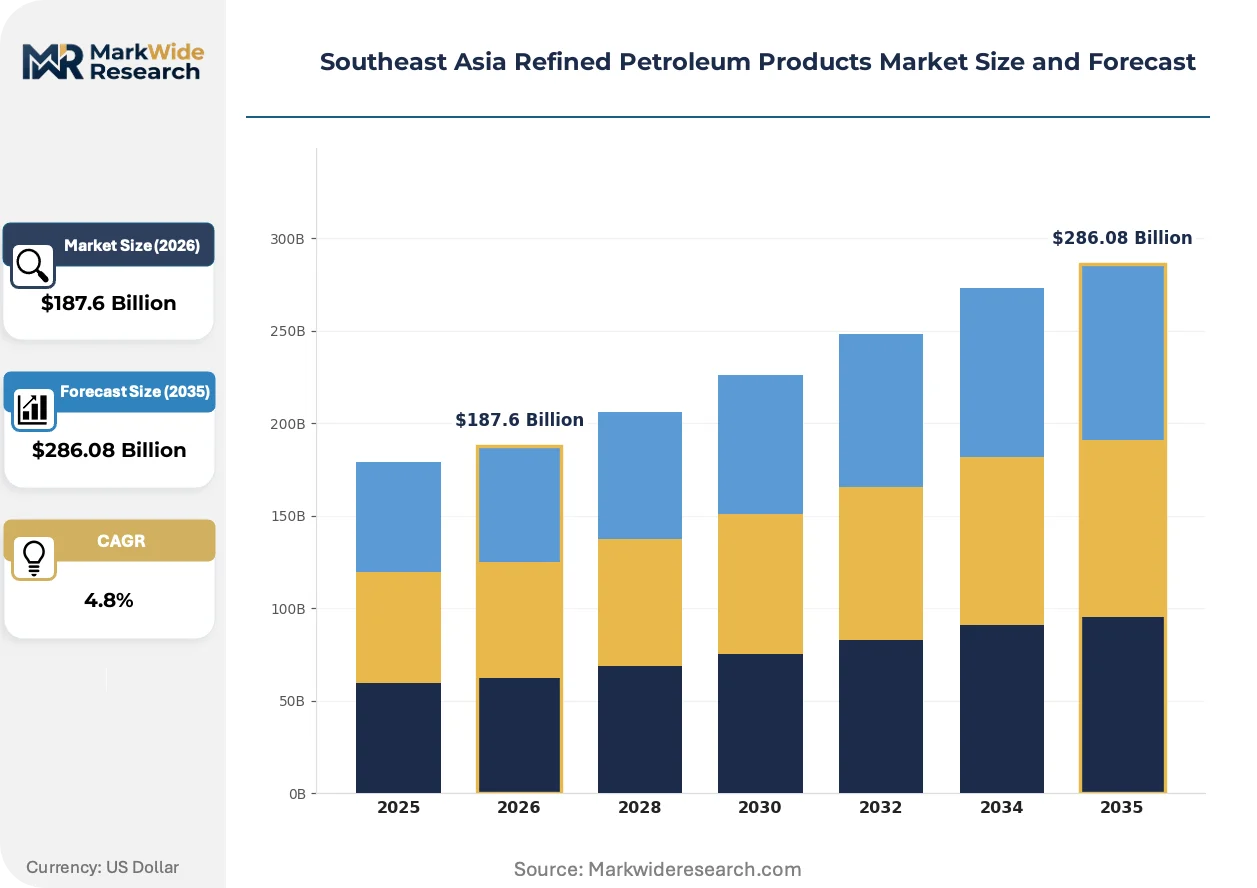
Market Dynamics
The Southeast Asia refined petroleum products market faces a structural mismatch between installed refinery capacity and consumption growth, forcing national oil companies to choose between import dependency and billion-dollar upgrade investments while sulfur specifications tighten across archipelagic distribution networks.
Growth Catalysts
- Aviation Turbine Fuel Demand:Low-cost carriers are adding intra-ASEAN routes at unprecedented frequency, driving jet fuel consumption above historical correlations with GDP growth. Bangkok, Jakarta, and Manila airports now rank among Asia's fastest-growing aviation hubs.
- Indonesia's BIS-Equivalent Sulfur Mandates:The Ministry of Energy and Mineral Resources enforces progressive caps on gasoline and diesel sulfur content, compelling fuel switching toward Euro-5 compliant products across the archipelago's 17,000 islands.
- Marine Fuel Oil Reformulation:IMO 2020 very low sulfur fuel oil standards have redirected blending activity through Singapore's Strait of Malacca hub, creating captive demand for regional refinery upgrades and specialized storage infrastructure.
Market Restraints
- Crude Oil Import Dependency:Southeast Asian refiners source 85% of feedstock from Middle Eastern suppliers, exposing margins to Dubai-Oman benchmark volatility and freight rate spikes through the Strait of Hormuz.
- Hydrotreating Capacity Bottleneck:Regional installed desulfurization capacity lags behind mandated sulfur reductions, forcing Indonesia and Vietnam to import finished low-sulfur products rather than processing domestic crude.
- Renewables Displacement:Solar and geothermal generation is eroding diesel demand for island grid baseload power, particularly in the Philippines and eastern Indonesian provinces where distributed renewable projects accelerate.
Strategic Opportunities
- Myanmar Market Opening:Sanctions relaxation and infrastructure rehabilitation create first-mover advantages for suppliers establishing coastal import terminals and inland distribution networks in this underpenetrated frontier market.
- Integrated Petrochemical Expansion:Malaysia's PETRONAS and Thailand's PTT are extending refining margins through aromatics and olefins integration, capturing value that previously leaked to Northeast Asian chemical producers.
- Biofuel Blending Mandates:Indonesia's B35 biodiesel program and Thailand's B10 ethanol requirements create structured demand for palm oil methyl ester and cassava-based ethanol, anchoring agricultural offtake agreements.
Industry Challenges
- Refinery Upgrade Execution Risk:PT Pertamina's Cilacap and Balikpapan facility modernization programs face cost overruns and contractor delays, threatening Indonesia's self-sufficiency targets and import substitution timeline.
- Archipelagic Logistics Complexity:Product distribution across Indonesia's eastern islands requires multi-modal transfers through shallow-draft ports, inflating delivered costs and quality assurance risks in remote consumption centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Southeast Asia Refined Petroleum Products Market |
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $286.08 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gasoline, Diesel, Jet Fuel, Liquefied Petroleum Gas End User: Transportation, Industrial, Residential, Commercial Distribution Channel: Retail, Wholesale, Direct Sales, E-commerce Application: Automotive, Aviation, Marine, Power Generation |
| Companies Covered | PT Pertamina (Persero), Petroliam Nasional Berhad (PETRONAS), Vietnam Oil and Gas Group, Shell PLC, BP PLC, TotalEnergies SE, Exxon Mobil Corporation, Chevron Corporation, PTT Public Company Limited, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Southeast Asia Refined Petroleum Products Market Evolving Landscape
Digital fuel quality tracking and low-carbon process technologies are reshaping how refiners demonstrate compliance and capture margin in a market where sulfur content now determines product access more than energy density.
Residual fluid catalytic cracking units with integrated propylene recovery are expanding into Southeast Asian refinery configurations, enabling gasoline and petrochemical feedstock flexibility from heavier crude slates. Thai and Vietnamese operators are retrofitting existing FCC trains with this dual-output architecture to hedge against gasoline demand plateau. The technology is expanding into the region's refining economics by compressing the payback period for upgrade investments previously justified on transport fuels alone.
Indonesia's Ministry of Energy and Mineral Resources has accelerated its Euro-5 equivalent fuel quality roadmap, advancing sulfur caps from 500 ppm to 50 ppm for gasoline and 10 ppm for diesel on compressed timelines. This regulatory compression forces importers to source from Northeast Asian refiners with spare hydrotreating capacity while domestic facilities face stranded asset risk. The policy is tightening fastest in Java's industrial corridor, where Jakarta's air quality mandates override national implementation schedules.
Fleet operators across Vietnam and Thailand now specify fuel procurement through certified carbon intensity metrics rather than volumetric spot contracts, unbundling commodity purchase from emissions accounting. This specification shift disrupts traditional trader-intermediary relationships, favoring integrated suppliers with verified lifecycle data. The behavioral pivot is most visible in Bangkok's commercial logistics sector, where multinational retailers enforce Scope 3 reporting requirements on contracted hauliers.
Southeast Asia Refined Petroleum Products Market Segmentation
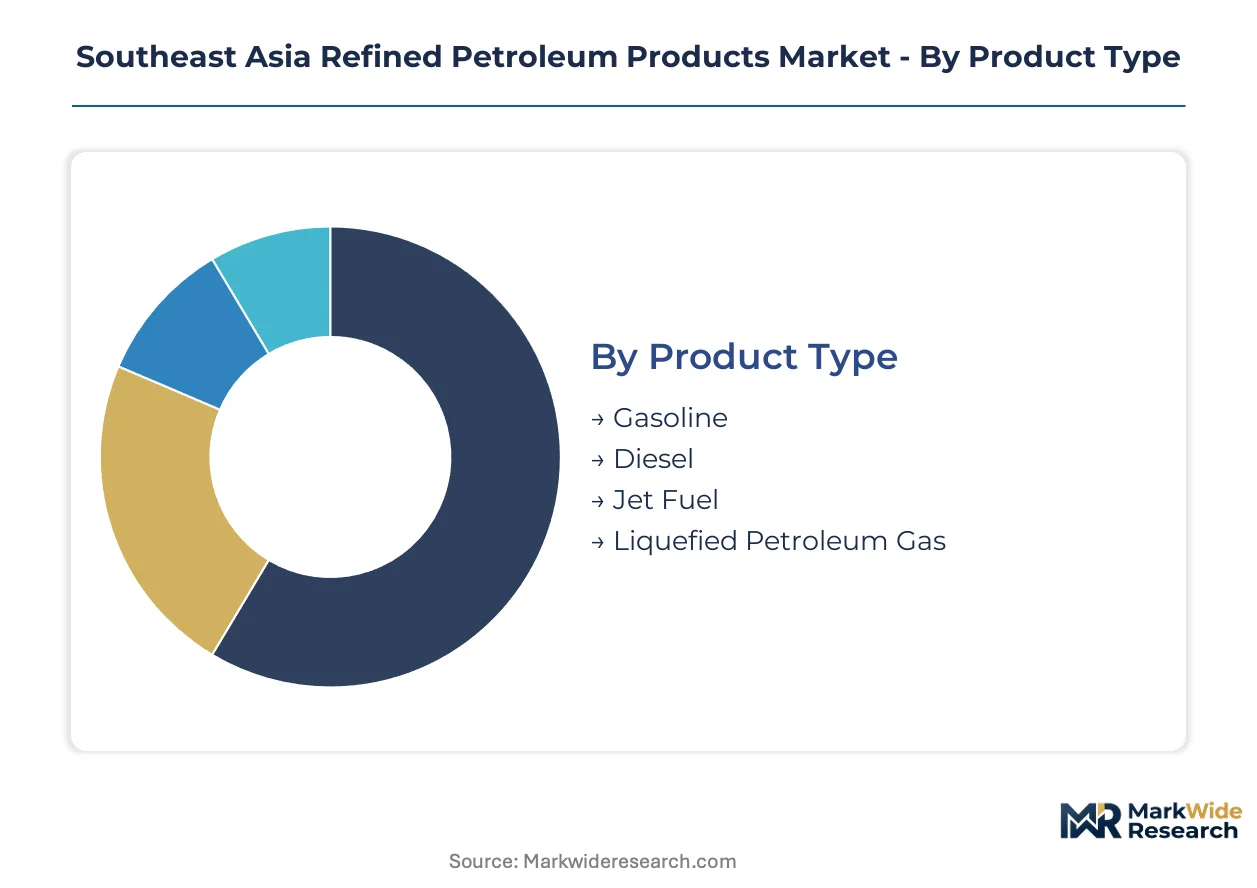
Southeast Asian fuel markets segment along sulfur compliance tiers and archipelagic logistics constraints. Each dimension carries distinct certification burdens that determine supplier eligibility and margin capture.
Product Type:
Certification requirements vary sharply across fuel grades, with Euro-5 sulfur mandates creating bifurcated supply pools between compliant importers and stranded domestic refiners.
- Gasoline:RON 88-92 octane blends dominate motorcycle and passenger vehicle fleets across Indonesia and Vietnam. Demand concentrates in Java's urban corridors where Pertamina's retail network faces competition from Shell and TotalEnergies premium formulations.
- Diesel:Automotive and industrial middle distillate with sulfur specifications compressing from 500 ppm toward 10 ppm under Indonesia's MEMR roadmap. Hydrotreating capacity bottlenecks force import dependency for Euro-5 grades.
- Jet Fuel:Aviation turbine kerosene meeting Jet A-1 specifications with freeze point below -47°C. Low-cost carrier expansion across Bangkok, Jakarta, and Manila airports drives above-GDP consumption growth.
- Liquefied Petroleum Gas:Propane-butane mixtures for residential cooking and light industrial heating. Indonesian households and small enterprises anchor regional offtake.
Gasoline sits at the top of the volume ranking, with jet fuel climbing the fastest.
End User:
Cost tier differentiation separates bulk contract purchasers from spot buyers, with transportation fleets commanding the steepest volume discounts.
- Transportation:Fleet operators across Vietnam and Thailand now specify carbon intensity metrics alongside volumetric contracts. Multinational retailers enforce Scope 3 reporting requirements on contracted hauliers in Bangkok's logistics corridor.
- Industrial:Manufacturing heat systems and process energy in Java and Penang. Sulfur compliance costs are passed through to export-oriented electronics and textile producers.
- Residential:LPG for cooking predominates in Indonesian and Philippine households. Subsidized pricing distorts procurement patterns toward state distributors.
- Commercial:Retail fuel stations, hospitality generators, and small business fleets. Premium branded outlets capture urban consumers willing to pay for quality assurance.
Transportation commands the largest share of offtake, with industrial demand expanding most quickly on manufacturing reshoring.
Distribution Channel:
Application-specific logistics determine channel selection, with marine and aviation fuels bypassing retail infrastructure entirely.
- Retail:Branded service stations with quality-certified pumps. Indonesia's 17,000-island geography forces multi-modal transfers through shallow-draft eastern ports.
- Wholesale:Bulk deliveries to industrial zones and secondary distributors. Singapore's Strait of Malacca hub concentrates regional blending activity.
- Direct Sales:Long-term contracts between refiners and large fleet operators. Verified lifecycle data requirements favor integrated suppliers over trader intermediaries.
- E-commerce:Emerging digital platforms for commercial fleet procurement. Digital fuel quality tracking systems enable compliance documentation.
Retail maintains volume leadership, with direct sales gaining share fastest on corporate sustainability mandates.
Application:
Margin structure varies by application, with marine IMO-compliant fuels commanding premium pricing over power generation diesel.
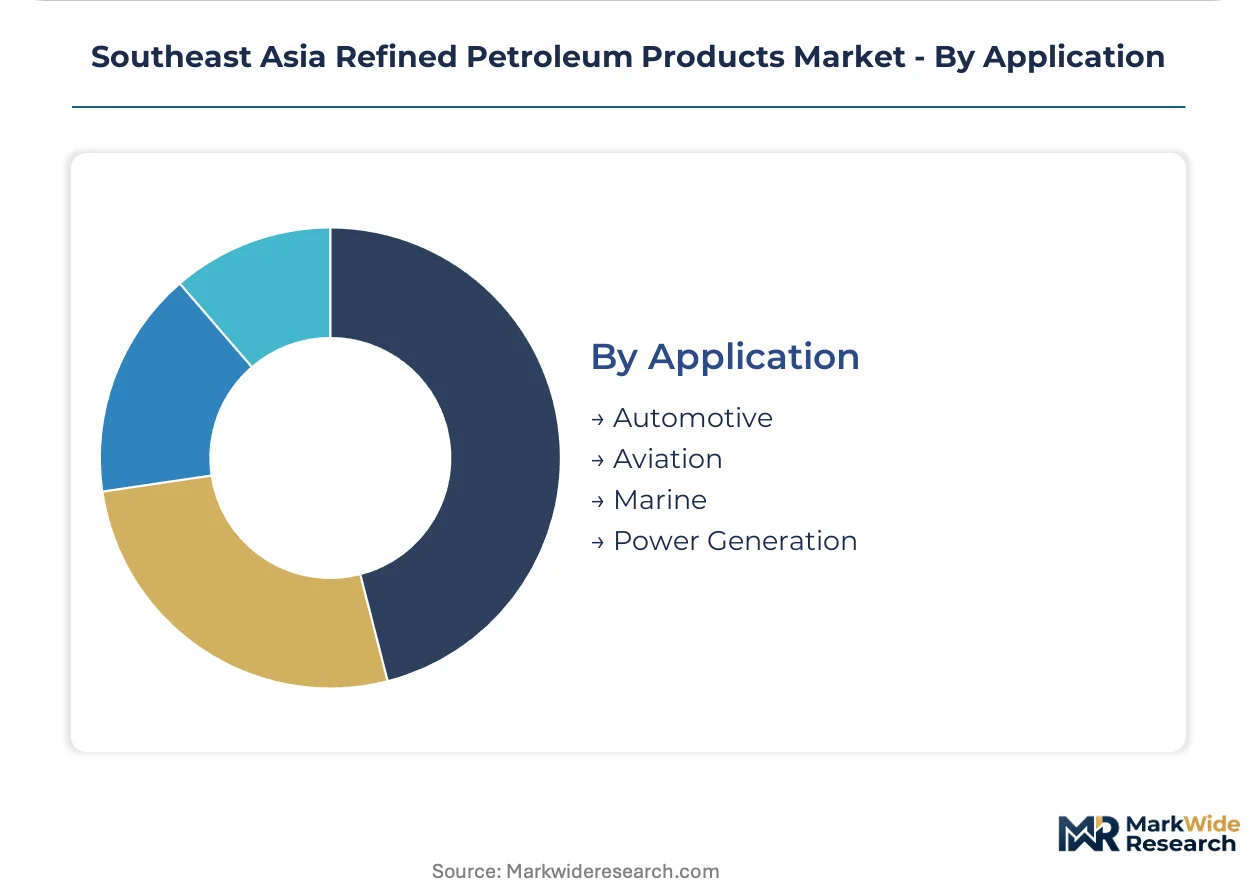
- Automotive:Motorcycle and passenger vehicle propulsion across ASEAN urban centers. Indonesia's motorcycle fleet exceeds 100 million units, anchoring gasoline demand.
- Aviation:Turbine fuel for commercial and cargo operations. Intra-ASEAN route expansion by low-cost carriers outpaces long-haul recovery.
- Marine:Very low sulfur fuel oil and marine gasoil for IMO 2020 compliance. Singapore's port authority standards redirect regional blending through the Malacca hub.
- Power Generation:Diesel baseload for island grids in Philippines and eastern Indonesia. Solar and geothermal displacement erodes historical demand.
Automotive leads by volume, with marine applications showing the steepest margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore's 1960s refining cluster established the region's hydrocarbon processing lineage, attracting Shell and Esso to build export-oriented capacity along Jurong Island. This hub-and-spoke model now distributes refined products across archipelagic Southeast Asia.
Indonesia
PT Pertamina's retail monopoly serves 100 million motorcycles and expanding passenger vehicle fleets across Java's urban corridors. The Ministry of Energy and Mineral Resources compresses sulfur caps toward Euro-5 standards on accelerated timelines. Cilacap and Balikpapan refinery upgrades face execution delays, forcing import dependency for low-sulfur gasoline and diesel.
Singapore
The Maritime and Port Authority's bunker fuel standards redirect IMO-compliant blending through the Strait of Malacca hub. Jurong Island's integrated complexes process Middle Eastern crude for re-export across ASEAN. Storage and blending terminals on Pulau Bukom anchor regional marine fuel oil reformulation activity.
Vietnam
Nghi Son and Dung Quat refineries struggle with hydrotreating capacity as motorcycle and industrial diesel demand outpaces domestic cracking upgrades. The national oil and gas group coordinates coastal import terminals to cover low-sulfur product shortfalls. Ho Chi Minh City's logistics corridor drives jet fuel consumption as low-cost carriers expand domestic routes.
Thailand
PTT's integrated petrochemical complexes extend downstream value capture from aromatics and olefins production. The Department of Energy Business enforces retail pump quality sampling that protects consumer engine warranties. Bangkok's commercial fleet operators now specify carbon intensity metrics alongside volumetric fuel contracts.
Malaysia
PETRONAS leverages integrated refining-petrochemical complexes at Pengerang and Kerteh to capture margin leaking to Northeast Asian chemical producers. The national petroleum corporation balances domestic retail supply with LNG export commitments. Penang's electronics manufacturing cluster anchors industrial diesel demand for process heat systems.
Southeast Asia Refined Petroleum Products Market Competitive Landscape
Capital-heavy national oil companies compete with asset-light international traders for margin capture across Southeast Asian fuel markets. The structure concentrates around state-owned refiners with domestic infrastructure monopolies, integrated majors with premium brand positioning, and trading houses with arbitrage logistics. Three archetypes dominate: archipelagic distribution network operators, integrated petrochemical extenders, and specialty formulation differentiators. Capacity expansion and backward integration into crude sourcing represent the dominant competitive vectors as sulfur specifications tighten.
Among archipelagic network operators, PT Pertamina (Persero) occupies a position exemplifying state monopoly over retail infrastructure across Indonesia's 17,000 islands. PETRONAS anchors the integrated petrochemical extender archetype through Malaysian complex operations. Shell PLC sits within the specialty formulation tier, representing premium lubricant and certified fuel positioning toward urban commercial fleets in Bangkok and Jakarta.
| Leading Market Players |
|---|
| PT Pertamina (Persero) |
| Petroliam Nasional Berhad (PETRONAS) |
| Vietnam Oil and Gas Group |
| Shell PLC |
| BP PLC |
| TotalEnergies SE |
| Exxon Mobil Corporation |
| Chevron Corporation |
| PTT Public Company Limited |
| Others |
Value Network & Pricing Analysis
Captive backward integration into crude sourcing and coastal refining infrastructure anchors both supply security and margin capture for Southeast Asian national oil companies. PT Pertamina's control over Indonesia's 17,000-island distribution network and PETRONAS's integrated Pengerang complex demonstrate how ownership of upstream feedstock agreements and downstream retail terminals translates directly into pricing power over spot-market dependent competitors.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates Shell's certified lubricant formulations from Pertamina's subsidized base grades and unbranded trader products. Price differentiation rests on sulfur certification tiers and archipelagic delivery costs, with Euro-5 compliant gasoline commanding substantial premiums over 500-ppm legacy stock. Cost compression in standard-tier diesel is intensifying because Vietnam and Indonesia must import low-sulfur volumes while domestic hydrotreating capacity lags. Fleet operators in Bangkok's logistics corridor show least price sensitivity due to multinational Scope 3 reporting mandates, while eastern Indonesian households anchor the most price-sensitive residential LPG segment.
Supply Chain Analysis
Freight costs through shallow-draft eastern Indonesian ports and Strait of Malacca congestion surcharges inflate delivered product costs by double-digit percentages over Singapore hub benchmarks. Supply concentrates in Singapore's Jurong Island refining cluster, Malaysia's Pengerang complex, and Thailand's Map Ta Phut facilities, with Vietnam and Indonesia dependent on coastal import terminals for Euro-5 compliant volumes. Feedstock draws from Middle Eastern Dubai-Oman benchmarks, regional sweet crude differentials, and spot LNG for refinery fuel. Single-source vulnerability through the Strait of Hormuz exposes 85% of regional crude intake to geopolitical disruption. Distribution runs through Singapore's storage and blending terminals for marine fuels, archipelagic barge networks for Indonesian retail, and direct pipeline connections for Thai industrial zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Southeast Asian refined petroleum products constitute a late-cycle quality story as sulfur specifications compress toward Euro-5 equivalence and carbon intensity metrics displace volumetric contracting. Fleet operators and marine buyers now pay premiums for certified low-sulfur and verified lifecycle products, rewarding suppliers with integrated quality assurance over trader intermediaries.
For Market Incumbents: Deepen hydrotreating capacity investments at Cilacap and Balikpapan to capture import substitution premiums as Indonesia's MEMR accelerates sulfur caps. Expand certified carbon intensity documentation for Bangkok and Jakarta commercial fleets facing multinational Scope 3 mandates. Defend against trader arbitrage by locking long-term crude supply agreements with Middle Eastern national oil companies.
For New Entrants and Emerging Players: The 40-60% price spread between Singapore premium marine fuels and Indonesian economy gasoline creates entry space for mid-tier suppliers with blended product flexibility. Target Myanmar's coastal import terminal rehabilitation for first-mover terminal access before sanctions normalization accelerates. Lead with digital fuel quality tracking platforms that unbundle compliance documentation from commodity supply.
For Investors and Strategic Acquirers: Roll-up economics work for archipelagic distribution network operators because Indonesia's 17,000-island geography fragments procurement into sub-scale local distributors with captive customer relationships. Five-to-ten year viability favors suppliers with integrated refining-petrochemical complexes over pure trading plays. Watch Indonesia's refinery upgrade execution timelines as the inflection signal—delays at Cilacap and Balikpapan extend import dependency windows for coastal terminal operators.
| Strategic Initiative | Industry Significance |
|---|---|
| Hydrotreating Capacity Expansion | Captures Euro-5 import substitution premiums as Indonesia's MEMR tightens sulfur mandates. |
| Integrated Petrochemical Extension | PETRONAS and PTT capture olefins value previously leaking to Northeast Asian chemical producers. |
| Marine Fuel Oil Reformulation | Singapore's MPA standards redirect IMO-compliant blending through Strait of Malacca storage terminals. |
| Digital Quality Tracking Platform | Enables carbon intensity verification for Bangkok fleet operators under multinational Scope 3 mandates. |
| Archipelagic Distribution Network | PT Pertamina's 17,000-island retail monopoly anchors national supply security against trader competition. |
Research Methodology
Direct dialogue with refinery operations managers, marine fuel procurement officers at Singapore bunker suppliers, Indonesian MEMR regulatory affairs leads, and Thai industrial fleet operators grounded qualitative assessment in operational reality. Secondary validation drew from IEA oil market reports, Singapore Maritime and Port Authority bunker fuel standards filings, Indonesian customs refined product import statistics, and ASEAN energy balance databases. Bottom-up capacity utilization models triangulated against top-down GDP-elasticity demand projections.
Bottom-up segment modeling across gasoline octane tiers, diesel sulfur grades, aviation turbine specifications, and marine fuel oil categories combined with archipelagic logistics cost build-ups. The analytical lens weighted refinery upgrade timelines against import dependency scenarios throughout the forecast period. CAGRs derived from elasticity-adjusted demand curves incorporating low-cost carrier route expansion, biodiesel blending mandate trajectories, and renewable displacement rates in Philippine island grids.
The model assumes a particular technology adoption path; alternative pathways for residual fluid catalytic cracking with propylene recovery would alter the outlook for petrochemical feedstock flexibility. Forecasts reflect assumptions around MEMR regulatory enforcement consistency and IMO marine fuel standard stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Petroleum Products
Ultra Low Sulphur Fuel Oil (ULSFO) Market
Petroleum Products
India White Oil Market
Petroleum Products
Petroleum Liquid Feedstock Market
Petroleum Products
South Africa Lubricants Market
Petroleum Products
France Refined Petroleum Product Market
Petroleum Products
Alkylate Gasoline Market
Petroleum Products
Automotive Oil Market
Petroleum Products
Refined Petroleum Products Market
Petroleum Products
Paraffin Oil Market
Petroleum Products
Germany Refined Petroleum Products Market
Petroleum Products
Green Petcoke Market
Petroleum Products
Automotive Oil Strainer Market
Petroleum Products
Global Petroleum Pitch Market
Petroleum Products
Asia Pacific Base Oil Market
Petroleum Products
Nigeria Petrol Station Market
Petroleum Products
West Africa Refined Petroleum Products Market