
 Europe Ethane Market | 2026-2036
Europe Ethane Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Ethane Market Insights
Pipeline and terminal distribution across Northwest Europe is fragmenting as US Gulf Coast export capacity reshapes Atlantic basin supply geography. INEOS leverages its Grangemouth and Rafnes cracker complexes to sustain captive ethane offtake from dedicated import infrastructure. Shell competes through control of midstream terminals at Rotterdam and Moerdijk, while Borealis differentiates via feedstock flexibility at its Stenungsund and Porvoo sites.
Ethane is a two-carbon alkane hydrocarbon (C₂H₆) typically recovered from natural gas processing or refinery off-gas streams, with purity grades ranging from technical grade to polymer-grade specifications above 95 percent purity; its primary commercial purpose is steam cracker feedstock for ethylene production, with secondary roles as refrigerant and fuel. Industrial grade ethane dominates volume throughput across Northwest European crackers, while feedstock application captures the largest margin pool given ethylene derivative economics. Refrigerant application is gaining structural traction under EU F-Gas phase-down schedules, displacing higher-GWP alternatives in commercial cooling systems.
REACH registration requirements and the EU F-Gas Regulation constrain product formulation and market access for non-compliant suppliers, while ECHA classification protocols govern handling standards across the value chain. The EU Green Deal carbon border adjustment mechanism will reshape feedstock cost structures for importers of ethane-derived petrochemicals. Stakeholders must monitor regulatory calibration of biogenic content thresholds and carbon intensity benchmarks for cracker feedstock certification.
Market Dynamics
Naphtha-to-ethane feedstock switching at Rhine-Ruhr petrochemical complexes is compressing regional naphtha demand while Atlantic basin LNG export terminal expansions reroute US Gulf Coast ethane toward Northwest European crackers.
Growth Catalysts
- EU F-Gas Regulation phase-down:Refrigerant-grade ethane demand is accelerating as commercial cooling systems abandon higher-GWP hydrofluorocarbons. Cold chain operators in Germany and the Netherlands are retrofitting equipment specifications.
- Steam cracker feedstock flexibility:Petrochemical producers are expanding ethane intake capacity to exploit ethylene yield advantages over naphtha. Technical modifications at crackers in Belgium and Norway enable rapid feedstock pivoting.
- Rotterdam-Moerdijk terminal infrastructure:Dedicated ethane import and storage facilities at Dutch port complexes are reducing landed cost differentials versus domestic naphtha supply. Midstream investment is unlocking volume throughput for inland crackers.
Market Restraints
- Atlantic supply concentration:US Gulf Coast export terminal operators control over 80 percent of seaborne ethane supply to Europe. Disruption at Marcus Hook or Morgan's Point facilities would immediately constrain Northwest European cracker operations.
- REACH registration complexity:Non-European suppliers face extended ECHA substance evaluation timelines for polymer-grade ethane certification. Registration dossier preparation costs exceed mid-tier importer thresholds.
- Naphtha price volatility transmission:Ethane-naphtha price spreads remain sensitive to crude oil benchmark swings. Crackers without feedstock switching capability face margin compression during oil price spikes.
Strategic Opportunities
- Biogenic feedstock certification:The EU Green Deal carbon border adjustment mechanism will reward cracker operators sourcing bio-based ethane. Early certification under developing ECHA protocols positions suppliers for premium pricing.
- Poland and Baltic corridor expansion:Underpenetrated Central European markets lack dedicated ethane terminal infrastructure. Greenfield import facility development at Gdańsk or Świnoujście would capture inland petrochemical demand.
- Hydrogen co-production integration:Cracker operators are exploring ethane pyrolysis with carbon capture to produce low-carbon hydrogen. EU Innovation Fund financing supports pilot projects at German chemical manufacturing sites.
Industry Challenges
- Cryogenic handling expertise scarcity:Ethane storage and transport requires minus 90 degree Celsius infrastructure. Qualified technicians for boil-off management and tanker loading are concentrated at Rotterdam and Grangemouth facilities.
- Dual-grade inventory complexity:Refrigerant-grade and polymer-grade ethane demand cycles are decoupling. Distributors face working capital strain maintaining separate cold chain certifications and storage segregation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Ethane Market |
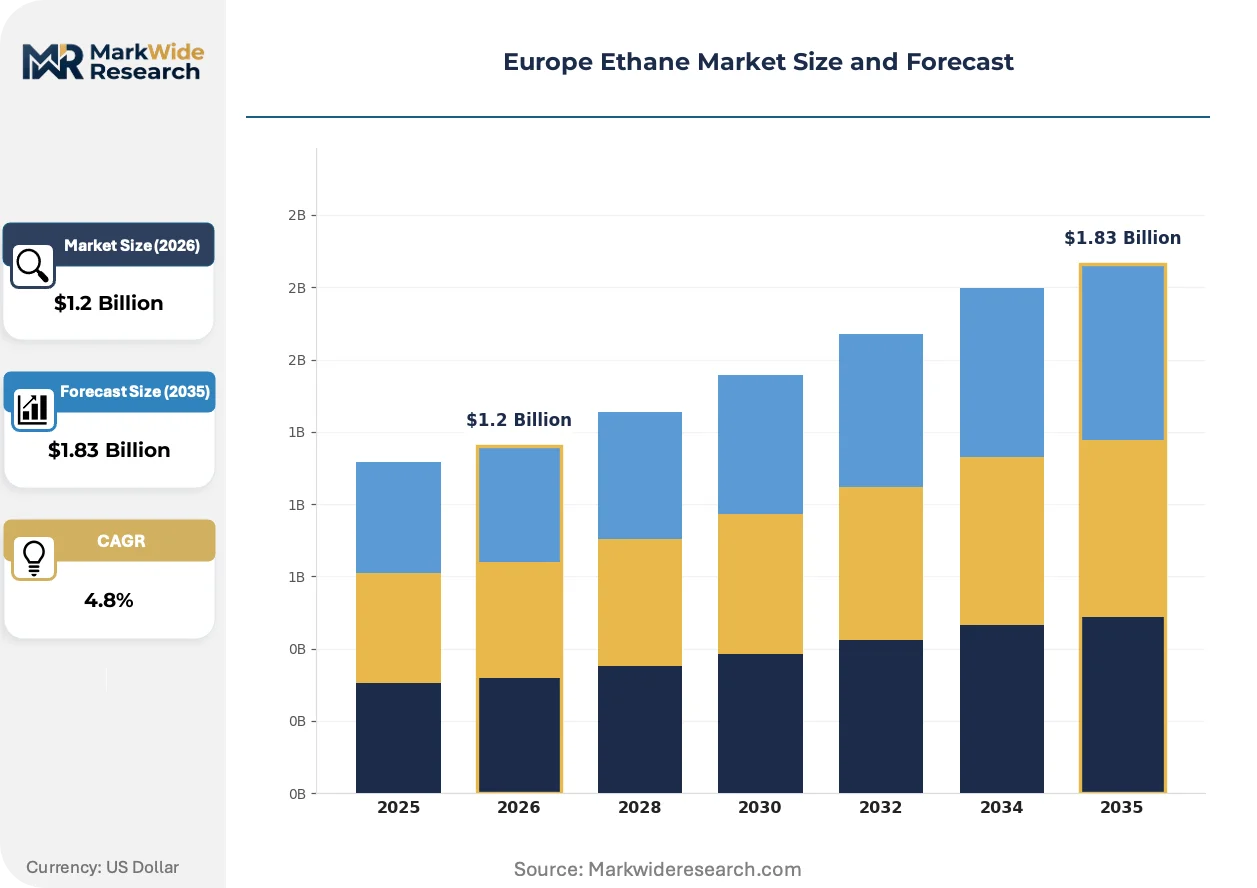
| Market Size in 2026 | $1.2 Billion |
| Market Size in 2035 | $1.83 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Pharmaceutical Grade, Food Grade, Technical Grade End User: Petrochemical Industry, Chemical Manufacturers, Energy Sector, Food Processing Application: Fuel, Feedstock, Refrigerants, Solvents Distribution Channel: Direct Sales, Distributors, Online Sales, Retail |
| Companies Covered | INEOS, LyondellBasell Industries, Borealis, Shell, ExxonMobil, BP, TotalEnergies, SABIC, Eni, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Ethane Market Trends and Innovations
Electrification of steam cracker furnaces and modular carbon capture retrofits are restructuring capital deployment patterns across Northwest European petrochemical corridors. Technology providers are repositioning around low-carbon feedstock processing.
Electric cracking furnace technology is collapsing the carbon intensity profile of ethylene production from ethane feedstock. INEOS and Borealis are piloting 100 megawatt electrode boilers at Belgian and Swedish sites. This electrification pathway is compressing the timeline for fossil-fuel-fired cracker decarbonization.
The EU Green Deal carbon border adjustment mechanism is forcing importers of ethane-derived petrochemicals to document upstream emissions. ECHA is developing product carbon footprint calculation methodologies for cracker feedstock certification. German chemical manufacturers are restructuring supplier qualification requirements to preempt CBAM compliance costs.
Spot market purchasing is displacing traditional long-term ethane supply contracts among mid-sized European crackers. Traders at Rotterdam are offering flexible volume call options with floating price linkage to Mont Belvieu benchmarks. This liquidity expansion is most visible among independent crackers in the Netherlands and Belgium lacking captive US supply arrangements.
Europe Ethane Market Segmentation
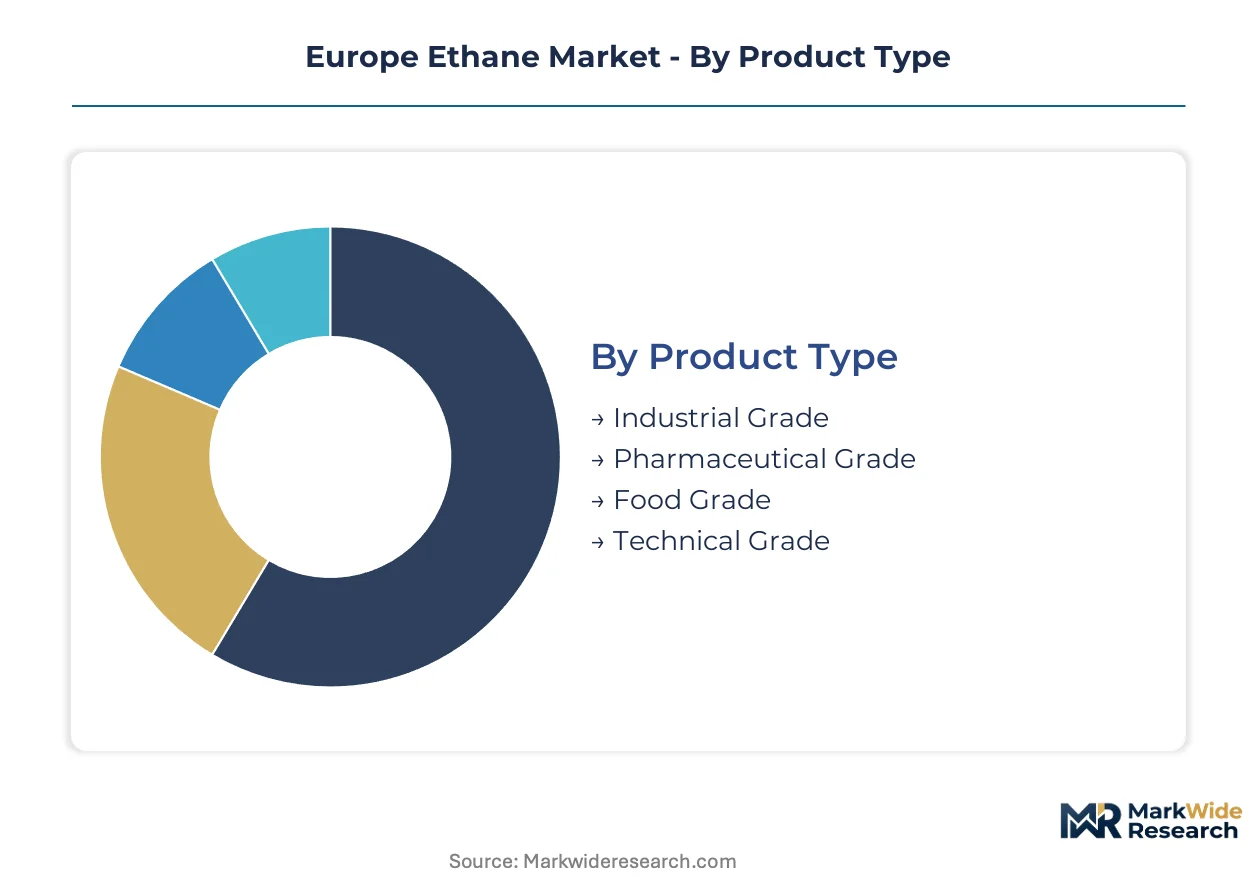
Ethane demand patterns across Europe fragment sharply across purity specifications and thermal applications. Steam cracker operators, refrigerant system retrofitters, and specialty chemical processors each impose distinct specification requirements that reshape supplier portfolio priorities.
Product Type:
The use-case spectrum stretches from bulk petrochemical throughput to precision-controlled pharmaceutical synthesis, with purity thresholds determining terminal access and margin capture.
- Industrial Grade:Specifications typically range from 90 to 95 percent purity with controlled sulfur and moisture content. Rhine-Ruhr petrochemical complexes absorb the majority of volume, driven by naphtha substitution economics at crackers with flexible feedstock intake.
- Pharmaceutical Grade:Ultra-high purity above 99.5 percent with full batch traceability and endotoxin testing. Demand concentrates at Swiss and German active pharmaceutical ingredient manufacturers facing EMA GMP compliance deadlines for inert process gases.
- Food Grade:Meets EFSA purity standards for direct and indirect food contact applications. Cold chain operators in the Netherlands specify this grade for modified atmosphere packaging systems.
- Technical Grade:Intermediate purity for non-critical industrial applications including welding shield gases and calibration mixtures. Regional distributors in Belgium stock this grade for maintenance supply contracts.
The dominant share belongs to Industrial Grade, while Pharmaceutical Grade is closing the gap fastest.
End User:
Cost tier differentiation separates commodity volume buyers from specification-sensitive purchasers willing to absorb premium logistics for certified supply security.
- Petrochemical Industry:Steam cracker operators at INEOS Grangemouth, Borealis Stenungsund, and Shell Moerdijk represent the anchor demand pool. These facilities require polymer-grade specifications with guaranteed vapor pressure curves for furnace injection systems.
- Chemical Manufacturers:Specialty and intermediate producers use ethane as process inertant and hydrogen source. German fine chemical clusters along the Rhine corridor are expanding offtake for halogenation reactions.
- Energy Sector:Power generators and industrial fuel consumers deploy ethane in dual-fuel turbine applications. Polish energy utilities are testing ethane blending for peak shaving capacity.
- Food Processing:Freezing and chilling operations in France and Spain specify refrigerant-grade ethane for spiral freezer retrofits under F-Gas phase-down compliance schedules.
Petrochemical Industry commands the volume base, though Chemical Manufacturers are expanding offtake most aggressively.
Application:
Margin structure varies dramatically across thermal conversion versus physical property exploitation, with feedstock applications capturing value through ethylene yield economics.
- Feedstock:Steam cracker feedstock dominates value capture, with ethane yielding up to 80 percent ethylene versus 30 percent from naphtha. Northwest European crackers are retrofitting furnaces to maximize ethane flexibility.
- Refrigerants:Low global warming potential makes ethane the preferred replacement for R-404A and R-507 in commercial refrigeration. German supermarket chains are accelerating retrofit timelines ahead of EU F-Gas quota reductions.
- Fuel:Industrial heating and power generation applications favor ethane for clean combustion profiles. Cement kilns in Poland are piloting ethane as alternative fuel to reduce NOx emissions.
- Solvents:Extraction and cleaning applications exploit ethane's non-polar characteristics. Olive oil processors in Spain use food-grade ethane for supercritical extraction systems.
Feedstock maintains the revenue concentration, while Refrigerants is gaining share fastest on regulatory tailwinds.
Distribution Channel:
Supply chain configuration determines working capital intensity and specification custody, with cryogenic logistics constraining channel options for high-purity grades.
- Direct Sales:Major crackers contract directly with US Gulf Coast export terminals for dedicated vessel charters. INEOS and Borealis operate this model for captive supply security.
- Distributors:Regional gas specialists manage inventory pooling and last-mile delivery for mid-volume purchasers. Rotterdam-based traders are expanding flexible volume contracts with Mont Belvieu price linkage.
- Online Sales:Digital platforms serve small-volume technical grade purchasers with standardized cylinder deliveries. This channel remains marginal for cryogenic bulk requirements.
- Retail:Welding supply stores and industrial gas retailers stock compressed ethane cylinders for maintenance and hobbyist applications. Limited to non-cryogenic packaging formats.
Direct Sales controls the volume majority, though Distributors are capturing incremental share through spot market liquidity expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power tilts toward Dutch and Belgian terminal operators over inland German crackers as Rotterdam-Moerdijk infrastructure captures margin from feedstock switching economics. Atlantic basin supply geography concentrates leverage at import nodes while Rhine-Ruhr manufacturers absorb transport cost premiums.
Germany
Rhine-Ruhr petrochemical complexes drive ethane intake expansion at crackers in Cologne-Leverkusen and Marl. ECHA REACH registration protocols govern polymer-grade certification for import suppliers. BASF and Covestro operations along the Rhine corridor are retrofitting furnaces for maximum ethane flexibility.
Netherlands
Rotterdam terminal operators control midstream access for Northwest European cracker feed. EU F-Gas Regulation phase-down schedules accelerate refrigerant-grade demand from Dutch cold chain operators. Shell Moerdijk and storage facilities at Rotterdam harbor anchor Atlantic basin supply distribution.
Belgium
Antwerp petrochemical ring processors seek feedstock diversification away from naphtha dependence. ECHA classification protocols for cryogenic handling constrain non-compliant logistics providers. INEOS operations at the Port of Antwerp integrate dedicated ethane import infrastructure with cracker complexes.
United Kingdom
Grangemouth cracker complex sustains captive ethane offtake through dedicated import terminals. UK REACH alignment with EU substance evaluation timelines affects cross-border supplier certification. Scottish petrochemical operations leverage deep-water access for US Gulf Coast vessel charters.
Sweden
Stenungsund cracker site exemplifies Nordic feedstock flexibility investments under carbon reduction mandates. EU Green Deal carbon border adjustment mechanism pressures documentation of upstream emissions for petrochemical output. Borealis operations anchor Scandinavian ethylene production with dual-feed capability.
Europe Ethane Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in feedstock logistics and terminal operations. Market structure consolidates around integrated petrochemical majors with captive import infrastructure, while midstream operators and regional distributors occupy fragmented niches. Three archetypes dominate: vertically integrated crackers with dedicated supply chains, independent terminal operators monetizing throughput fees, and flexible feedstock traders capturing arbitrage from naphtha-ethane spreads. Capacity expansion at Rotterdam and Moerdijk terminals and strategic partnerships for biogenic feedstock certification represent the dominant competitive moves.
Among integrated European operators, INEOS, Shell, and Borealis occupy positions across the value chain from import terminal access to cracker operations. INEOS exemplifies the captive supply archetype through Grangemouth and Rafnes complex integration. Shell represents terminal-centric positioning with Rotterdam and Moerdijk infrastructure control. Borealis anchors flexible feedstock operations at Stenungsund and Porvoo with rapid pivot capability between naphtha and ethane.
| Leading Market Players |
|---|
| INEOS |
| LyondellBasell Industries |
| Borealis |
| Shell |
| ExxonMobil |
| BP |
| TotalEnergies |
| SABIC |
| Eni |
| Others |
Pricing and Supply Chain Analysis
Single-source dependency on US Gulf Coast export terminals determines both the polymer-grade premium over industrial-grade ethane and the cryogenic logistics network shape across Northwest Europe. Atlantic basin supply concentration compresses margins for inland crackers while rewarding Rotterdam-Moerdijk terminal operators with structural pricing power.
Pricing Analysis
The configured-to-order premium spread separates long-term contract pricing from spot market transactions. Three-tier pricing structure across polymer-grade, refrigerant-grade, and technical-grade specifications reflects purity certification costs and cryogenic handling requirements. Price differentiation rests on REACH registration status and dedicated vessel charter availability. Cost compression in the technical-grade tier is intensifying because mid-sized distributors are pooling inventory to share boil-off management expenses. Independent crackers without captive US supply arrangements exhibit the highest price sensitivity, while integrated majors with dedicated import infrastructure absorb fluctuations with minimal volume adjustment.
Supply Chain Analysis
Tariff exposure between the United States and European Union member states dominates supply chain risk calculus for importers of ethane-derived petrochemicals. Geographic supply concentration centers on Texas and Pennsylvania export terminals, with secondary aggregation at Rotterdam and Grangemouth receiving facilities. Raw material dependencies draw from shale gas processing streams, specialized cryogenic vessel fleets, and boil-off recapture systems. Single-source vulnerability at Marcus Hook or Morgan's Point facilities would immediately constrain Northwest European cracker operations. Distribution runs through dedicated terminal-to-pipeline networks for integrated majors, with regional gas specialists managing cylinder and small-batch logistics for specialty chemical purchasers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe ethane market functions as a defensive-moat arena where regulatory entrenchment around REACH certification and EU F-Gas compliance creates durable barriers against unqualified entrants. Incumbents leverage captive import infrastructure and established ECHA dossiers to sustain margin premiums.
For Market Incumbents: Insulate polymer-grade supply contracts through backward integration into Rotterdam terminal capacity expansion. Extend REACH registration coverage to emerging bio-based ethane certification protocols before ECHA finalizes biogenic content thresholds. The threat of electrified cracker technology disrupting feedstock yield economics demands preemptive pilot investment at Belgian and Swedish sites. Channel control through dedicated vessel charters remains the priority defensive lever against spot market liquidity expansion.
For New Entrants and Emerging Players: Establish a beachhead in the underpenetrated Poland-Baltic corridor where dedicated ethane terminal infrastructure remains absent. Target refrigerant-grade distribution partnerships with German supermarket chains accelerating F-Gas retrofit timelines ahead of quota reductions. The most penetrable segment sits in technical-grade cylinder supply for Rhine corridor maintenance contracts, where incumbent majors disengage due to working capital intensity. A go-to-market angle anchored on flexible volume call options with Mont Belvieu price linkage captures independent cracker demand.
For Investors and Strategic Acquirers: EU Green Deal carbon border adjustment mechanism implementation reshapes the acquisition landscape toward operators with documented upstream emissions and bio-based feedstock certification pathways. Long-term viability favors integrated assets with dual-feed cracker flexibility and cryogenic logistics expertise concentrated at Rotterdam and Grangemouth. The target archetype combines captive terminal access with rapid feedstock pivoting capability. Watch for ECHA calibration of biogenic content thresholds as the signal indicating premium pricing window opening for certified suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion at Rotterdam Terminals | Captures margin from Rhine-Ruhr naphtha substitution economics through reduced landed cost differentials. |
| Backward Integration into US Export Infrastructure | Secures dedicated vessel charter capacity against Atlantic basin supply concentration risks. |
| Biogenic Feedstock Certification Investment | Positions operators for EU Green Deal carbon border adjustment mechanism premium pricing. |
| Electrified Cracker Furnace Pilot Deployment | Collapses carbon intensity profiles at INEOS and Borealis sites ahead of regulatory mandates. |
| Long-term Supply Agreement with Baltic Importers | Locks in offtake from greenfield terminal development at Gdańsk or Świnoujście. |
Research Methodology
Initial hypotheses were tested against primary input from cracker operations managers, cryogenic logistics coordinators, ECHA regulatory affairs specialists, and petrochemical procurement leads, then refined through secondary validation. Primary fieldwork combined structured interviews with downstream chemical manufacturers and terminal operators with trade data analysis from Eurostat customs records, Cefic industry reports, ECHA substance registration databases, and SEC filings from integrated majors. Bottom-up volume modeling across grade tiers and end-use segments was cross-checked against top-down macroeconomic indicators for ethylene derivative demand.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning purity grade, end-use industry, application thermal profile, and regional production hub. CAGRs were synthesized from ethylene capacity expansion timelines, naphtha-to-ethane switching elasticity estimates, and refrigerant-grade penetration curves under EU F-Gas phase-down schedules. Industry-specific inputs included cracker feedstock flexibility retrofit investments and Mont Belvieu benchmark price volatility transmission effects.
Stress conditions across US export terminal disruption scenarios, REACH registration timeline delays, and crude oil benchmark swings were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about naphtha-ethane spread sustainability and electrification technology cost curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Petroleum Products
Green Petcoke Market
Petroleum Products
South Africa Petroleum Market
Petroleum Products
Marine Minerals Market
Petroleum Products
Liquefied Petroleum Gas Market
Petroleum Products
Global Petroleum Pitch Market
Petroleum Products
Petroleum Wax Market
Petroleum Products
Global Petroleum Coke Market
Petroleum Products
North Africa Refined Petroleum Products Market
Petroleum Products
Oil Refining Market
Petroleum Products
Helical Submerged Arc Welded Pipe Market
Petroleum Products
Europe Refined Petroleum Products Market
Petroleum Products
Performance Oil Sales Market
Petroleum Products
Paraffin Oil Market
Petroleum Products
Malaysia Refined Petroleum Products Market
Petroleum Products
Gasoline-Naphtha-Crude-MTBE Market
Petroleum Products
Oil Shale Market