
 Petroleum Wax Market | 2026-2036
Petroleum Wax Market Size, Share, and Industry Trends Forecast 2026-2036
Petroleum Wax Market Outlook
The capital-intensity divergence between integrated refiners and standalone blenders is bifurcating competitive returns across the petroleum wax value chain. Exxon Mobil Corporation leverages captive crude sourcing and hydrofinishing infrastructure to sustain margin capture on food-grade paraffin. Sasol Limited differentiates through Fischer-Tropsch synthetic wax output, occupying a premium tier in high-melt-point applications where petroleum-derived alternatives face performance ceilings.
Petroleum wax comprises saturated hydrocarbon mixtures distilled from lubricating oil fractions, with melting points typically ranging from 46°C to 68°C for paraffin grades and 63°C to 93°C for microcrystalline variants, serving primarily as moisture barriers, release agents, and aesthetic modifiers across industrial and consumer goods. Paraffin wax dominates volume flows into candle and packaging applications where cost sensitivity structures procurement, while microcrystalline wax commands tighter supply pools in cosmetics and rust-preventive coatings due to its finer crystal structure and superior adhesion. Synthetic wax from Fischer-Tropsch synthesis represents the fastest-growing product type as formulators seek consistent carbon chain distribution and reduced oil dependency in personal care and pharmaceutical end uses.
REACH registration requirements in Europe and FDA food-contact substance notifications in the United States constrain market access for non-compliant producers, elevating testing and certification costs that favor scaled refiners with dedicated regulatory affairs functions. China's SAMR national food safety standards and GB specifications for industrial wax grades add parallel compliance layers for exporters targeting Asia-Pacific demand clusters. Stakeholders must monitor bio-based wax substitution curves and refinery capacity reallocation toward renewable diesel, as these shifts will reshape feedstock availability and grade premiums before the forecast horizon closes.
Market Dynamics
Refinery capacity reallocation toward renewable diesel production is constraining slack wax feedstock availability, forcing petroleum wax producers to compete for shrinking lubricant base oil streams while candle and packaging buyers accelerate procurement to secure volume commitments.
Growth Catalysts
- Candle manufacturing expansion:Southeast Asian candle producers are scaling procurement of refined paraffin grades to serve export markets and domestic consumption growth, tightening spot availability for standard melting-point grades.
- REACH compliance elevation:ECHA registration requirements for fully refined paraffin are filtering out non-compliant suppliers from European cosmetics and pharmaceutical channels, consolidating procurement toward certified refiners.
- Coating formulator demand:India's industrial coating sector is absorbing additional microcrystalline wax volumes as Numaligarh Refinery Limited and domestic blenders expand capacity to serve rust-preventive and moisture-barrier applications.
Market Restraints
- Crude-linked feedstock volatility:Paraffin wax margins compress when lubricating oil base stock prices spike, as slack wax costs move with vacuum gas oil differentials that refiners prioritize for diesel and jet fuel production.
- Asian supply concentration:China and India together control the majority of incremental refining capacity for wax-grade base oils, creating geographic chokepoints when regional maintenance cycles or export policy shifts disrupt spot flows.
- Fischer-Tropsch substitution ceiling:Synthetic wax from Sasol's South African facilities and Shell's gas-to-liquids plants captures premium applications above 80°C melting points where petroleum-derived microcrystalline waxes suffer performance constraints.
Strategic Opportunities
- Food-contact certification gaps:FDA food-contact substance notifications for petroleum wax remain underutilized in Latin American packaging markets, creating first-mover advantages for refiners completing migration testing and substance inventories.
- Pharmaceutical-grade hydrofinishing:Supercritical solvent deoiling and catalytic hydrogenation upgrades enable entry into USP-grade ointment bases and tablet coatings where current supply relies on European and US Gulf Coast producers.
- Carbon accounting convergence:EU Green Deal embedded carbon reporting requirements and emerging corporate Scope 3 targets are rewarding refiners with methane-flare-reduction certifications and renewable electricity integration in wax finishing.
Industry Challenges
- Hydrofinishing technician scarcity:Specialized operators capable of managing high-pressure hydrogenation units for food-grade and pharmaceutical-grade wax production command premium wages, constrating capacity expansion timelines for mid-scale refiners.
- Multi-jurisdiction certification synchronization:Simultaneous pursuit of FDA food-contact notifications, REACH full registrations, and China's GB standards for industrial wax grades extends product launch timelines and strains regulatory affairs staffing.
- Legacy tank farm segregation:Existing storage infrastructure at coastal refineries often lacks dedicated tanks for kosher-certified or halal-certified wax grades, forcing batch sequencing that reduces throughput and increases contamination risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Petroleum Wax Market |
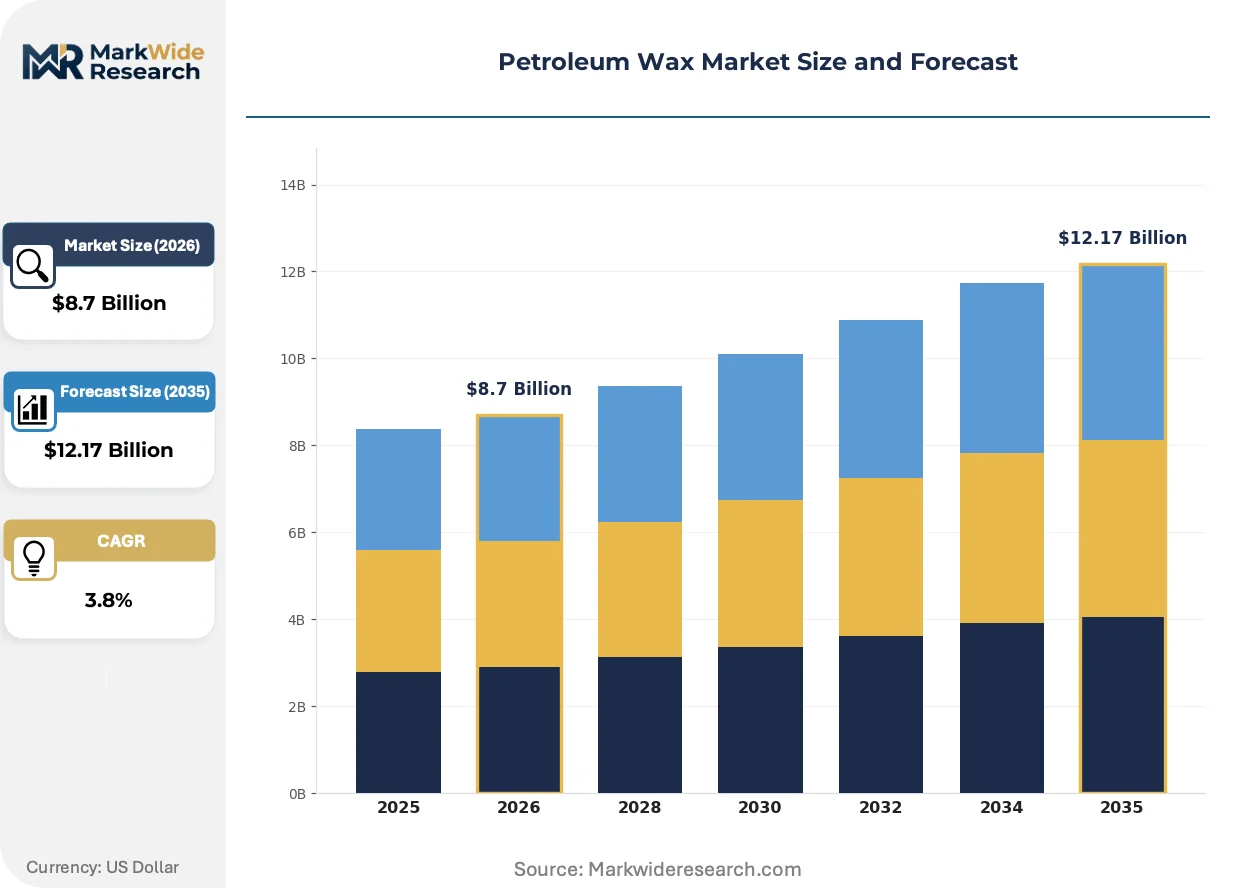
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $12.17 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Paraffin Wax, Microcrystalline Wax, Synthetic Wax, Blended Wax Application: Candles, Coatings, Packaging, Personal Care End User: Food Industry, Cosmetics, Pharmaceuticals, Tableware Grade: Food Grade, Industrial Grade, Cosmetic Grade, Technical Grade |
| Companies Covered | Numaligarh Refinery Limited, Sinopec Corp, Exxon Mobil Corporation, HollyFrontier Corporation, China National Petroleum Corporation, Shell plc, Petrobras, The International Group, Sasol Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Petroleum Wax Market Strategic Shifts
Synthetic and bio-based wax alternatives are compressing the addressable market for conventional petroleum grades, while regulatory carbon accounting and supply chain traceability requirements reshape procurement specifications across cosmetics, food packaging, and pharmaceutical end uses.
Gas-to-liquids Fischer-Tropsch wax is supplanting petroleum-derived microcrystalline wax in high-performance hot-melt adhesives and tire manufacturing, where consistent carbon chain distribution and absence of aromatic impurities justify 15-25% price premiums. European automotive sealant formulators and Asian tire producers are accelerating qualification programs for GTL feedstocks. This displacement is narrowing the premium tier available to petroleum wax refiners and forcing investment in supercritical solvent deoiling to match purity benchmarks.
EU F-Gas Regulation phase-down schedules and parallel US EPA SNAP restrictions on hydrofluorocarbon propellants are indirectly pressuring petroleum wax producers serving aerosol corrosion inhibitors and mold-release sprays, as formulators reformulate toward compressed gas and mechanical pump systems that alter wax carrier requirements. Aerosol packaging manufacturers in Germany and California are redesigning canister specifications and valve geometries to accommodate higher-viscosity wax dispersions, compressing demand for low-melt-point paraffin diluents previously standard in HFC-driven formulations.
Specification-driven consolidation among multinational candle and personal care brands is concentrating procurement toward refiners offering bundled certification packages spanning food-contact, pharmaceutical, and cosmetic-grade attestations. Buyers are reducing qualified supplier lists from twelve-plus vendors to three-to-four strategic partners capable of managing dual-audit programs for RSPO mass-balance claims and ISO 22000 food safety management. This preference shift is most visible in Northern European retail private-label programs and US mass-market candle chains, where procurement teams prioritize supply assurance and regulatory defensibility over spot-price minimization.
Petroleum Wax Market Segmentation
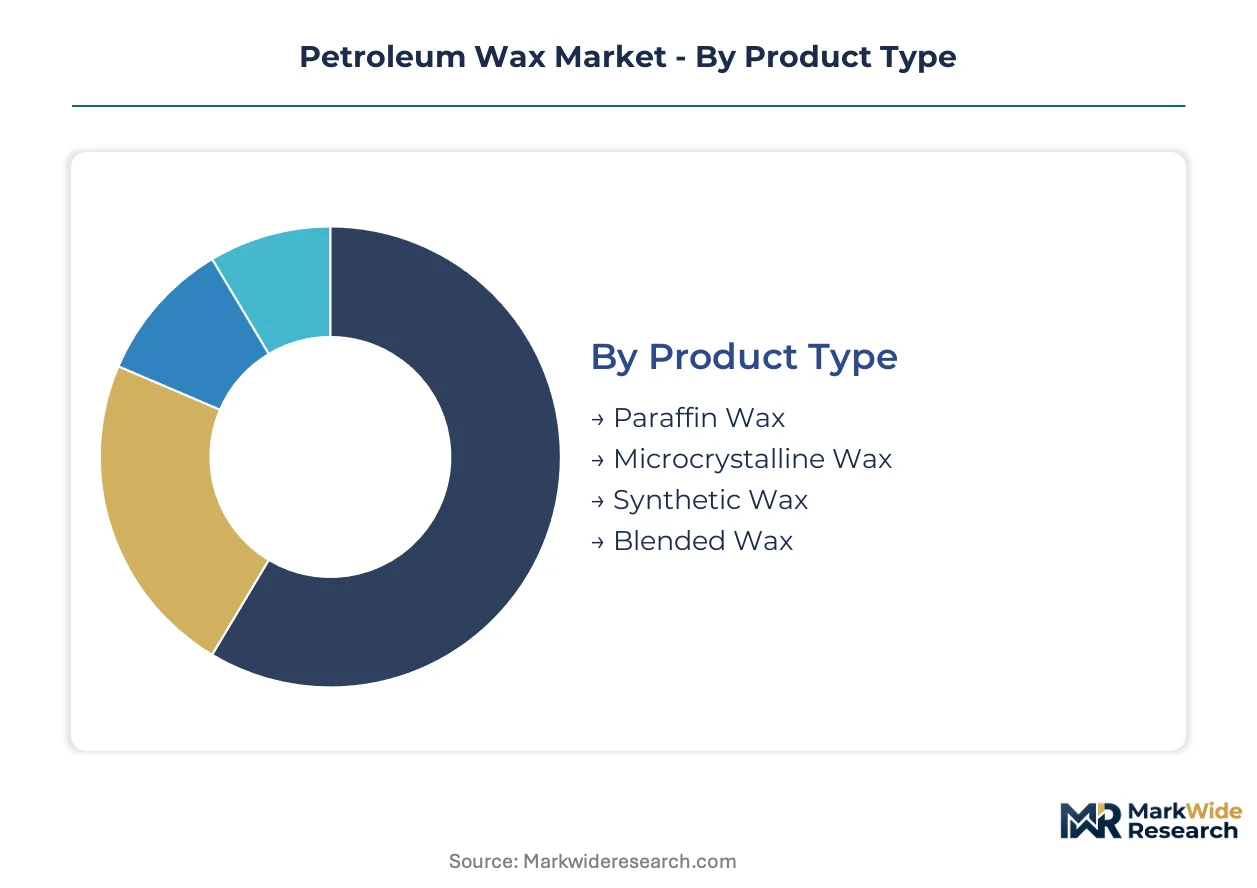
Petroleum wax procurement patterns diverge sharply across product chemistries and end-use certifications, with food-contact compliance and high-melt performance creating distinct margin tiers that reshape refinery investment priorities.
Product Type:
Domestic consumption dominates paraffin procurement in India and China, while synthetic wax flows concentrate toward export-led automotive and adhesive formulators in Germany and Japan.
- Paraffin Wax:Saturated hydrocarbon mixtures distilled from lubricating oil fractions with melting points between 46°C and 68°C. Candle manufacturers in Vietnam and Indonesia absorb the bulk of standard-grade volumes, though refinery capacity reallocation toward renewable diesel is tightening slack wax feedstock availability and forcing buyers toward longer-term supply contracts.
- Microcrystalline Wax:Finer crystal structures derived from heavier residual fractions deliver superior adhesion and moisture barrier properties across the 63°C to 93°C melting range. Rust-preventive coating formulators in India's Maharashtra industrial corridor are scaling procurement as Numaligarh Refinery Limited expands domestic finishing capacity.
- Synthetic Wax:Fischer-Tropsch output from gas-to-liquids plants offers consistent carbon chain distribution for pharmaceutical and personal care applications where petroleum-derived alternatives face aromatic impurity constraints.
- Blended Wax:Custom formulations combining paraffin and microcrystalline fractions serve specialty packaging and candle applications requiring tuned melting profiles.
Paraffin wax commands the established base. The steepest expansion runs through synthetic wax.
Application:
Cost sensitivity structures procurement tiers, with commodity candles at one extreme and pharmaceutical-grade coatings at the other.
- Candles:Standard melting-point paraffin dominates volume flows, though Southeast Asian producers are consolidating supplier lists from twelve-plus vendors to three-to-four strategic partners capable of managing bundled certification packages.
- Coatings:Microcrystalline grades serve moisture-barrier and rust-preventive functions in industrial metal protection and paperboard lamination.
- Packaging:FDA food-contact substance notifications and REACH full registrations filter procurement toward scaled refiners with dedicated regulatory affairs functions.
- Personal Care:Cosmetic-grade specifications demand supercritical solvent deoiling and catalytic hydrogenation to meet purity benchmarks for emollient and thickening applications.
Candle applications anchor volume demand. Packaging certification requirements are climbing fastest.
End User:
Regulatory jurisdiction determines accessible supply pools, with food-contact and pharmaceutical channels imposing the strictest purity gates.
- Food Industry:FDA food-contact substance notifications and China's SAMR national food safety standards constrain market access, elevating testing costs that favor refiners with captive hydrofinishing infrastructure.
- Cosmetics:REACH registration requirements through ECHA filter non-compliant suppliers from European channels, consolidating procurement toward certified producers with dedicated regulatory staffing.
- Pharmaceuticals:USP-grade ointment bases and tablet coatings require supercritical solvent deoiling upgrades currently concentrated among US Gulf Coast and European refiners.
- Tableware:Food-grade paraffin for disposable plates and cups faces bio-based substitution pressure from polylactic acid and plant-derived alternatives.
Food industry specifications dominate procurement volume. Pharmaceutical-grade channels are expanding most quickly.
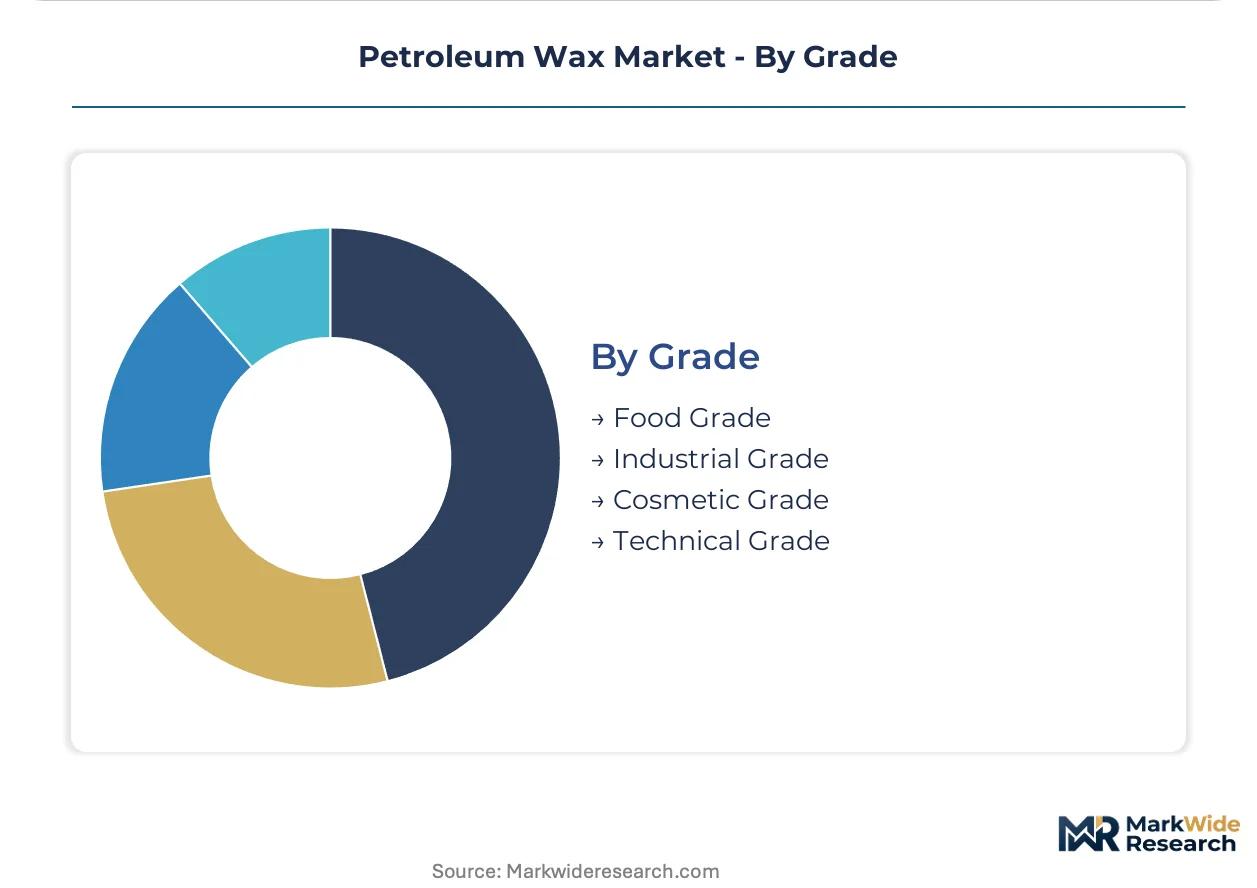
Grade:
Certification tier directly determines addressable end-use scope and achievable margin capture.
- Food Grade:FDA notifications and China's GB standards for food-contact substances require migration testing and substance inventories that extend product launch timelines.
- Industrial Grade:Standard specifications for rust prevention, moisture barriers, and release agents face feedstock cost pressure from vacuum gas oil differentials tied to diesel and jet fuel production.
- Cosmetic Grade:ECHA REACH registrations and dual-audit programs for RSPO mass-balance claims strain regulatory affairs staffing at mid-scale refiners.
- Technical Grade:General-purpose applications in adhesives, sealants, and electrical insulation absorb volume when higher-certification grades face supply constraints.
Industrial grade holds the volume base. Food-contact certification is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Refiners in India and China capture pricing leverage through captive crude access and domestic slack wax availability, while European and North American producers absorb feedstock volatility through premium-grade specialization. This asymmetry reshapes procurement geography as candle and packaging buyers seek supply assurance.
United States
Candle manufacturers in Texas and the Gulf Coast absorb standard-grade paraffin volumes for domestic retail chains. FDA food-contact substance notifications constrain market access for non-compliant imports, elevating procurement toward refiners with dedicated regulatory affairs functions. Houston-area hydrofinishing facilities serve pharmaceutical-grade channels where USP certification commands margin premiums.
China
SAMR national food safety standards and GB specifications for industrial wax grades create parallel compliance layers for domestic producers and exporters. Yangtze River Delta refiners scale slack wax processing to serve packaging and coating formulators, though capacity reallocation toward renewable diesel tightens feedstock availability. Shanghai-based blenders consolidate procurement lists from fragmented suppliers toward strategic partners with bundled certification packages.
Germany
ECHA REACH registration requirements filter non-compliant suppliers from European cosmetics and pharmaceutical channels. Ruhr industrial corridor refiners leverage hydrofinishing infrastructure to serve automotive sealant formulators and hot-melt adhesive producers. Cologne-area storage terminals face legacy tank farm segregation constraints for kosher-certified and halal-certified wax grades.
India
Numaligarh Refinery Limited and domestic coating formulators expand microcrystalline wax capacity to serve Maharashtra industrial corridor rust-preventive applications. FSSAI food-contact standards and BIS industrial specifications add certification layers for packaging and tableware channels. Gujarat-based blenders absorb incremental paraffin volumes as Southeast Asian candle producers diversify supply sources.
Brazil
ANVISA pharmaceutical regulations and national food safety standards structure import requirements for food-grade and cosmetic-grade waxes. São Paulo state packaging manufacturers absorb technical-grade volumes for moisture-barrier applications. Petrobras refining complex in Rio de Janeiro state supplies slack wax feedstocks to domestic blenders serving Latin American coating markets.
Petroleum Wax Market Competitive Environment
Concentration sits with integrated oil majors possessing captive crude sourcing and hydrofinishing infrastructure. Mid-scale standalone blenders compete on regional logistics and certification agility rather than feedstock cost position. Three archetypes dominate: integrated refiners with lubricant base oil streams, gas-to-liquids synthetic wax specialists, and regional blenders with flexible sourcing networks. Capacity expansion and strategic partnerships represent the dominant competitive vectors as producers secure long-term supply commitments from candle and packaging buyers.
Among integrated refiners, Exxon Mobil Corporation and Shell plc occupy positions anchored by global lubricant base oil networks and hydrofinishing assets. Sasol Limited exemplifies the synthetic wax archetype through Fischer-Tropsch output serving high-melt-point applications. Numaligarh Refinery Limited represents regional scale expansion within India's domestic market. These three company types illustrate how feedstock access, synthesis technology, and geographic positioning stratify competitive returns across the value chain.
| Leading Market Players |
|---|
| Numaligarh Refinery Limited |
| Sinopec Corp |
| Exxon Mobil Corporation |
| HollyFrontier Corporation |
| China National Petroleum Corporation |
| Shell plc |
| Petrobras |
| The International Group |
| Sasol Limited |
| Others |
Value Chain & Pricing Dynamics
REACH full registration requirements gate both supply qualification and price differentiation simultaneously, as ECHA compliance costs filter non-certified producers from European cosmetics and pharmaceutical channels while enabling certified refiners to capture 15-25% premiums over standard grades. Candle manufacturers in Vietnam and Indonesia face compressed procurement flexibility as slack wax feedstock tightens, forcing longer contract terms that lock in price exposure to vacuum gas oil differentials.
Pricing Analysis
The customization-premium spread separates pharmaceutical-grade hydrofinished wax from standard candle paraffin, with supercritical solvent deoiling and catalytic hydrogenation adding cost layers that USP-certified producers recover through specialty channel pricing. Price differentiation rests on certification tier and captive crude access, with integrated refiners leveraging upstream control over lubricant base oil streams to defend margins while standalone blenders absorb volatility. Cost compression in standard-grade paraffin is intensifying because renewable diesel capacity reallocation diverts slack wax feedstocks toward biofuel production. Commodity candle producers exhibit highest price sensitivity, while pharmaceutical formulators prioritize supply assurance over spot-price minimization.
Supply Chain Analysis
Strategic stockpile preferences dominate procurement behavior as Southeast Asian candle manufacturers secure 12-18 month volume commitments to hedge against feedstock tightening. Supply concentrates in China, India, and the US Gulf Coast, where Yangtze River Delta refiners, Numaligarh Refinery Limited, and Houston-area hydrofinishing facilities control incremental wax-grade base oil capacity. Raw material dependencies include vacuum gas oil from lubricant production, slack wax intermediates, and hydrogen for food-grade finishing. Single-source vulnerability runs through Asian supply concentration, where regional maintenance cycles or export policy shifts disrupt spot flows. Distribution runs through coastal tank terminals with dedicated kosher and halal segregation capabilities, though legacy infrastructure constraints force batch sequencing that reduces throughput.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Petroleum wax demand sits in early-cycle expansion as pharmaceutical-grade applications accelerate qualification programs for USP-certified ointment bases and tablet coatings. Fischer-Tropsch substitution in high-melt adhesives and tire manufacturing creates parallel growth vectors that extend addressable market boundaries beyond conventional petroleum grades.
For Market Incumbents: Secure long-term supply commitments from multinational candle and personal care brands consolidating procurement lists toward three-to-four strategic partners with bundled certification packages. Invest in supercritical solvent deoiling upgrades to match Sasol's Fischer-Tropsch purity benchmarks in high-melt-point applications above 80°C where petroleum-derived microcrystalline waxes face performance constraints. Backward integration into captive hydrogenation infrastructure defends margin capture against vacuum gas oil differential volatility. For New Entrants and Emerging Players: Lead with FDA food-contact substance notification completion in Latin American packaging markets, where migration testing gaps create first-mover advantages for refiners with substance inventories and compliance documentation. Target Brazil's São Paulo state moisture-barrier coating manufacturers and Mexico's expanding candle export sector, where ANVISA and national food safety standards structure import requirements less stringently than REACH or FDA channels. Partner with established distributors possessing kosher and halal certification capabilities to bypass legacy tank farm segregation constraints. For Investors and Strategic Acquirers: EU Green Deal embedded carbon reporting requirements reshape the acquisition landscape, rewarding refiners with methane-flare-reduction certifications and renewable electricity integration in wax finishing. Five-to-ten year viability favors integrated producers with lubricant base oil streams and hydrofinishing assets over standalone blenders exposed to feedstock volatility. Target mid-scale refiners with regulatory affairs staffing capable of synchronizing multi-jurisdiction certifications. Watch for carbon accounting convergence crossing procurement specification thresholds in Northern European retail private-label programs as the inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Numaligarh Refinery Limited's microcrystalline wax buildout serves Maharashtra rust-preventive coating demand. |
| Backward Integration | Captive vacuum gas oil processing insulates margin capture from renewable diesel feedstock competition. |
| Green Manufacturing Transition | Renewable electricity integration in hydrofinishing satisfies EU Green Deal Scope 3 procurement specifications. |
| Long-term Supply Agreement | Southeast Asian candle producers lock 12-18 month commitments to hedge slack wax availability tightening. |
| Joint Venture | Partnerships with kosher/halal-certified terminal operators bypass legacy tank farm segregation constraints. |
Study Parameters
Two parallel data streams informed the analysis: primary field engagement with refinery operations managers, candle procurement directors at Southeast Asian manufacturers, coating formulator technical leads, and regulatory affairs specialists at ECHA and FDA; alongside secondary validation through customs trade data, SEC 10-K filings of integrated oil majors, SAMR national food safety standard disclosures, and IEA refinery capacity reports. Bottom-up volume modeling across grade tiers and applications triangulated against top-down macroeconomic drivers.
Across the analysis window, the analytical framework modeled petroleum wax demand through segmentation by product chemistry, certification grade, end-use industry, and regional production hub. CAGRs were derived from trend extrapolation of feedstock availability constraints, regulatory compliance cost trajectories, and substitution elasticities for Fischer-Tropsch alternatives. Forecast inputs incorporated renewable diesel capacity reallocation timelines and pharmaceutical-grade hydrofinishing capacity expansion schedules.
The analysis sits within stated boundaries; outcomes outside sustained crude price stability, unaltered REACH enforcement intensity, or predictable Fischer-Tropsch supply growth would require recalibration. Forecasts reflect assumptions regarding refinery maintenance cycles, export policy continuity, and certification timeline standardization. Revision becomes warranted when renewable diesel capacity reallocation crosses thresholds that eliminate slack wax merchant availability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Petroleum Products
Marine Minerals Market
Petroleum Products
Petroleum Benzine Market
Petroleum Products
Very Low Sulphur Fuel Oil (VLSFO) Market
Petroleum Products
Gasoline-Naphtha-Crude-MTBE Market
Petroleum Products
Helical Submerged Arc Welded Pipe Market
Petroleum Products
Performance Oil Sales Market
Petroleum Products
North Africa Refined Petroleum Products Market
Petroleum Products
Oil Refinery Market
Petroleum Products
Global Petroleum Pitch Market
Petroleum Products
West Africa Refined Petroleum Products Market
Petroleum Products
Alkylate Gasoline Market
Petroleum Products
Global Petroleum Coke Market
Petroleum Products
LPG [Liquefied Petroleum Gas] Market
Petroleum Products
Naphtha Market
Petroleum Products
Quenching Oil Market
Petroleum Products
Liquefied Petroleum Gas Market