
 West Africa Refined Petroleum Products Market | 2026-2036
West Africa Refined Petroleum Products Market Size, Share, and Industry Trends Forecast 2026-2036
West Africa Refined Petroleum Products Market Analytics
Product import channels across West Africa are fragmenting as regional storage and coastal depot networks multiply. TotalEnergies leverages its integrated supply chain from European refineries to coastal terminals in Cotonou and Lomé. Dangote Refinery anchors Nigerian supply with its large-scale domestic processing complex near Lagos. Vitol competes through floating storage and offshore blending operations that bypass traditional onshore bottlenecks.
Refined petroleum products encompass hydrocarbon fuels derived from crude oil distillation, catalytic cracking, and hydrotreating, with specifications governed by sulfur content, octane rating, and cetane index for combustion performance. These products power transportation fleets, industrial machinery, and thermal generation equipment across energy-deficient economies. Diesel commands the largest volume share within the product type dimension, reflecting its dominance in heavy-duty trucking and backup power systems across Nigeria and Ghana. The transportation application leads absolute consumption, though industrial offtake is expanding fastest as manufacturing clusters near Tema and Lekki scale operations. Government end users sustain strategic stockpiling programs that buffer against supply disruptions during West African piracy surges or European refinery maintenance cycles.
Nigeria's Department of Petroleum Resources enforces gasoline and diesel quality standards, while Ghana's National Petroleum Authority monitors import licensing and pricing formulas. The Economic Community of West African States' draft petroleum protocol aims to harmonize technical specifications and cross-border trade rules. Stakeholders must track Dangote Refinery's ramp-up trajectory and corresponding displacement of imported volumes when assessing terminal infrastructure investments and offtake contract structures.
Market Dynamics
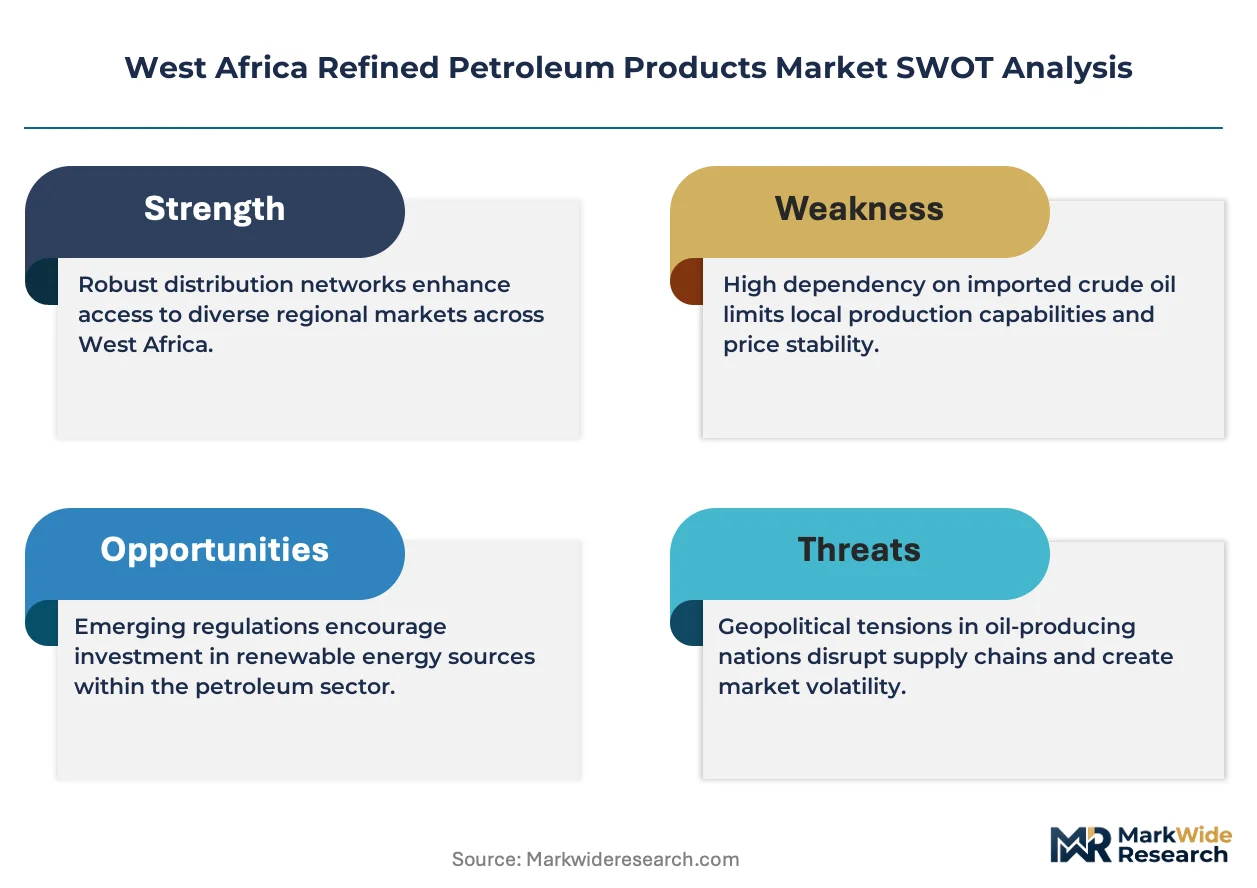
Dangote Refinery's domestic processing ramp-up is compressing import dependency across Nigeria's Lagos-Abuja corridor and forcing terminal operators to reconfigure storage contracts around displaced Atlantic basin cargoes.
Growth Catalysts
- Diesel-fired power generation:Nigeria's grid instability and Ghana's gas supply shortfalls are accelerating conversion of thermal fleets to diesel backup systems, tightening regional product offtake.
- AFRI-4 fuel quality roadmap:The African Petroleum Producers Organization's harmonized sulfur specifications are creating upgrade demand for hydrotreating capacity and low-sulfur blending infrastructure.
- Industrial corridor expansion:Manufacturing clusters near Tema and Lekki are scaling operations, lifting diesel and fuel oil consumption for process heat and captive power.
Market Restraints
- European refinery maintenance cycles:West Africa's import dependency on Northwest European supply exposes buyers to volume disruptions during turnaround seasons.
- Atlantic basin freight volatility:Clean tanker rate swings between Rotterdam and Lagos directly impact landed costs, compressing importer margins.
- Gas-to-power substitution:Ghana's offshore gas field development threatens diesel generator economics in baseload power applications.
Strategic Opportunities
- Coastal depot multiplication:Côte d'Ivoire and Senegal offer underpenetrated storage infrastructure for traders seeking alternatives to Nigerian and Ghanaian concentration.
- Floating storage and blending:Offshore processing vessels bypass onshore bottlenecks and enable sulfur specification adjustments at point of delivery.
- ECOWAS petroleum protocol:The draft harmonization framework promises simplified cross-border trade rules and unified technical standards.
Industry Challenges
- Hydrotreating technician scarcity:The shift to low-sulfur production requires specialized catalyst management skills that regional labor pools currently lack.
- Terminal asset stranding risk:Dangote's displacement of imported volumes threatens returns on coastal storage investments predicated on continued import dependency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | West Africa Refined Petroleum Products Market |
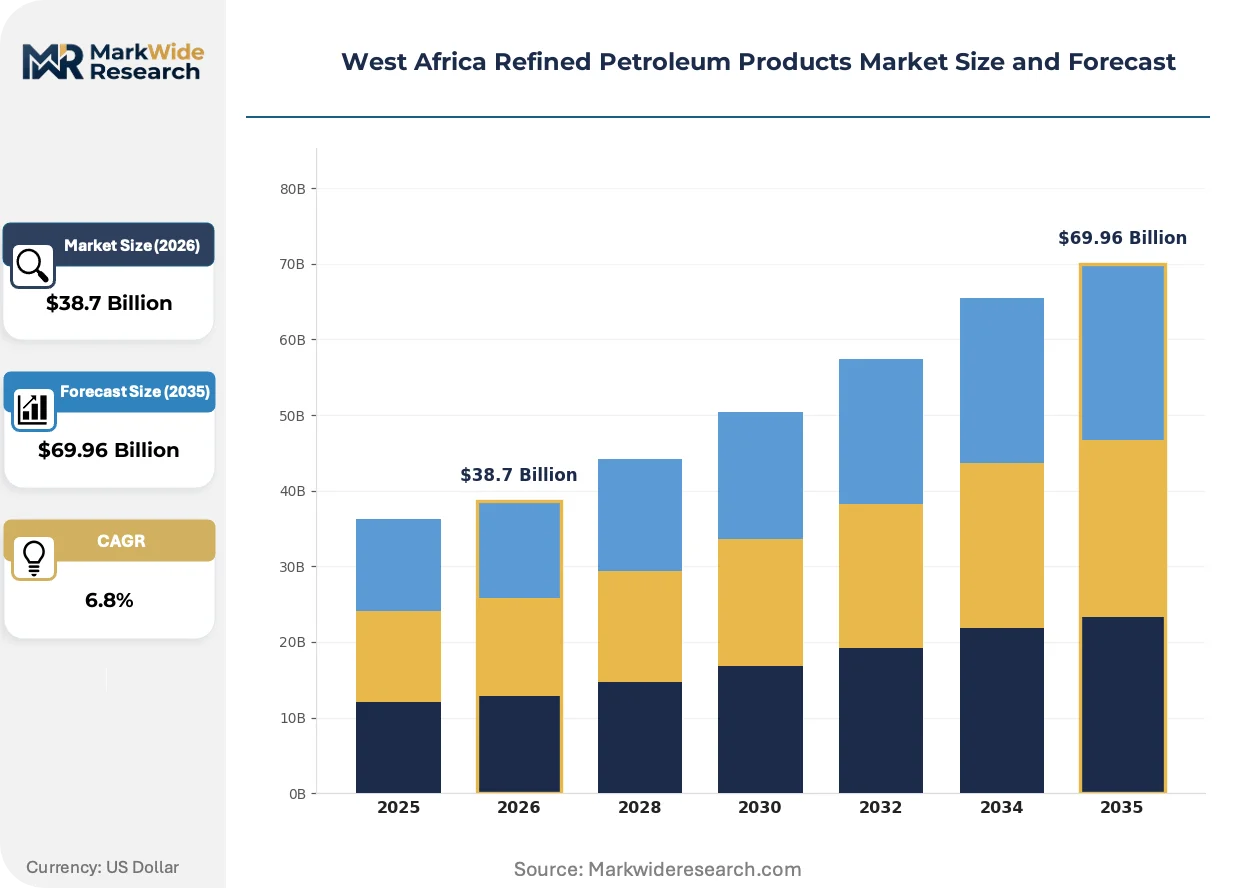
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gasoline, Diesel, Jet Fuel, Kerosene Application: Transportation, Industrial, Residential, Commercial End User: Government, Private Sector, Utilities, Transport Services Distribution Channel: Retail, Wholesale, Direct Sales, Online |
| Companies Covered | Mercuria Energy, TotalEnergies, Vitol, Sahara Group, Puma Energy, Trafigura, Oando Plc, Dangote Refinery, Glencore, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
West Africa Refined Petroleum Products Market Evolving Landscape
Fuel quality upgrading, supply chain reconfiguration, and procurement model evolution are compressing legacy trading structures while opening pathways for integrated operators and specialized logistics providers.
Advanced hydrotreating catalysts with higher sulfur conversion efficiency are rendering obsolete conventional single-stage desulfurization units at coastal blending facilities. Terminal operators in Lomé and Cotonou are retrofitting existing tanks to accommodate these systems, compressing the economic viability of high-sulfur fuel oil storage.
The African Petroleum Producers Organization's AFRI-4 specification timeline is tightening sulfur limits for diesel and gasoline across member states. Refiners and importers must reformulate product slates or face market exclusion, with Nigeria's Department of Petroleum Resources accelerating enforcement ahead of regional deadlines.
Bulk buyers in Ghana's Tema industrial zone are consolidating procurement through direct refinery offtake agreements, bypassing traditional intermediary traders. This concentration shifts credit risk to end-users while compressing wholesale margins, with manufacturing clusters negotiating multi-year supply contracts indexed to Platts European benchmarks.
West Africa Refined Petroleum Products Market Segmentation
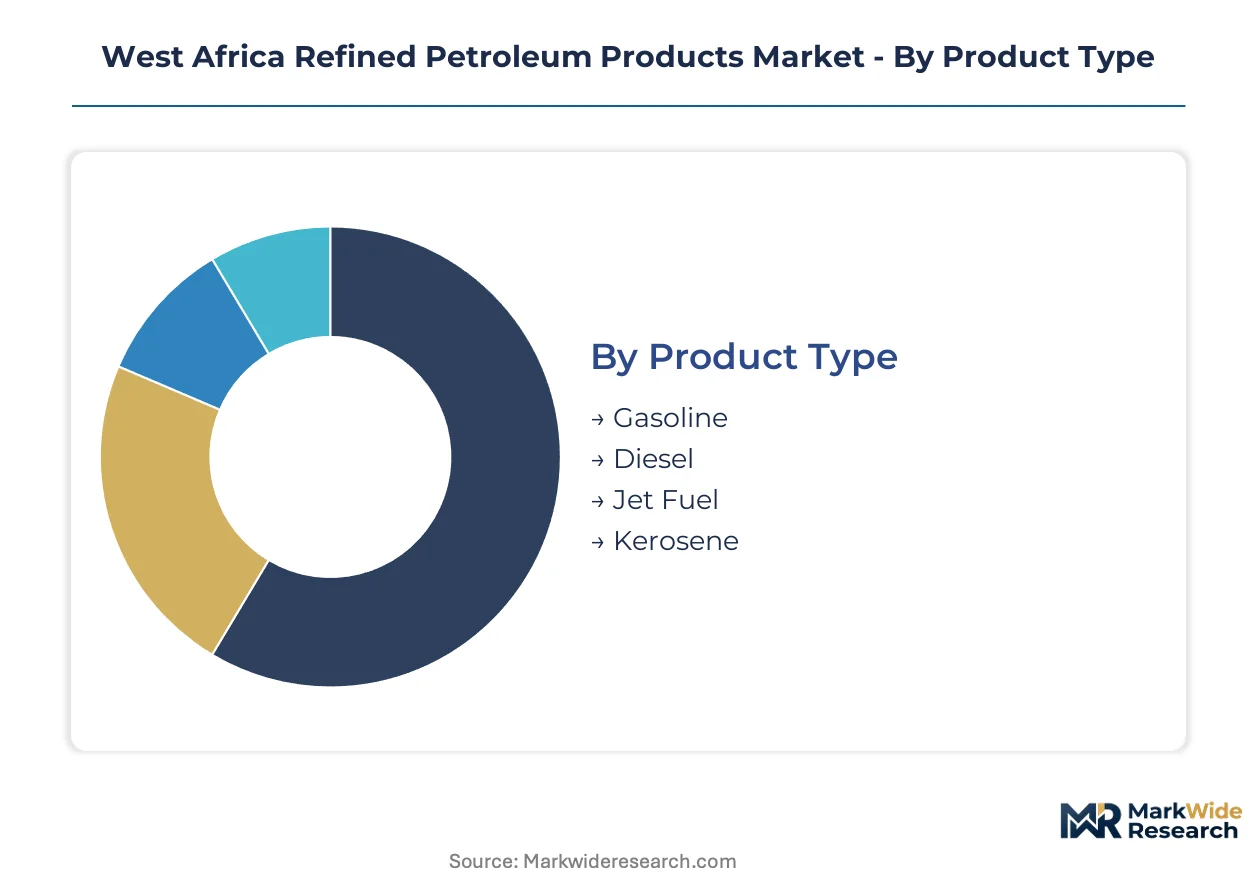
Refined petroleum products in West Africa fragment across four distinct dimensions, each governing procurement patterns and margin structures differently. Product type and application dictate infrastructure requirements, while end-user concentration and channel choice determine pricing power and working capital intensity.
Product Type:
Mature gasoline and diesel segments coexist with emerging jet fuel demand as regional aviation networks expand.
- Diesel:Distillate fuel with cetane index specifications governing compression ignition performance. Demand concentrates in Nigeria's Lagos-Abuja corridor where grid instability drives backup generator deployment across manufacturing and logistics operations.
- Gasoline:Spark-ignition fuel graded by octane rating for light-duty vehicle fleets. Ghana's Tema industrial zone and Nigerian urban centers absorb the largest volumes as private vehicle ownership accelerates.
- Jet Fuel:Kerosene-based aviation turbine fuel meeting strict flash point and freezing point specifications for regional carriers.
- Kerosene:Illuminating and cooking fuel prevalent in residential off-grid segments across rural Nigeria and northern Ghana.
Diesel retains volume leadership; jet fuel holds the steepest expansion curve.
Application:
Volume distribution follows the energy intensity of economic activity, with transport and industrial segments commanding infrastructure investment priority.
- Transportation:Road freight, passenger vehicles, and marine bunkering absorb the majority of gasoline and diesel offtake. Nigeria's Dangote Refinery ramp-up is redirecting Atlantic basin cargoes previously serving this segment through Lagos terminals.
- Industrial:Process heat, captive power generation, and manufacturing equipment drive diesel and fuel oil consumption. Tema and Lekki manufacturing clusters are scaling direct refinery offtake agreements that bypass traditional trader intermediaries.
- Residential:Kerosene for lighting and cooking persists in electrification-deficient areas despite LPG substitution programs.
- Commercial:Retail fuel stations, hospitality backup power, and construction equipment represent fragmented, price-sensitive demand.
Transportation dominates absolute consumption; industrial applications are expanding most quickly.
End User:
Government procurement operates on strategic stockpiling mandates, while private sector buyers optimize around credit terms and delivery reliability.
- Transport Services:Fleet operators and logistics companies constitute the largest private diesel consumers, negotiating bulk supply contracts indexed to European benchmarks.
- Government:Strategic petroleum reserves, military procurement, and public sector vehicle fleets sustain buffer stocks against supply disruptions during West African piracy surges.
- Private Sector:Manufacturing, mining, and agricultural enterprises procure through term contracts or spot markets depending on storage capacity.
- Utilities:Grid operators and independent power producers consume diesel for peaking capacity during gas supply shortfalls.
Transport Services anchor private sector volume; Government maintains the most rigid procurement protocols.
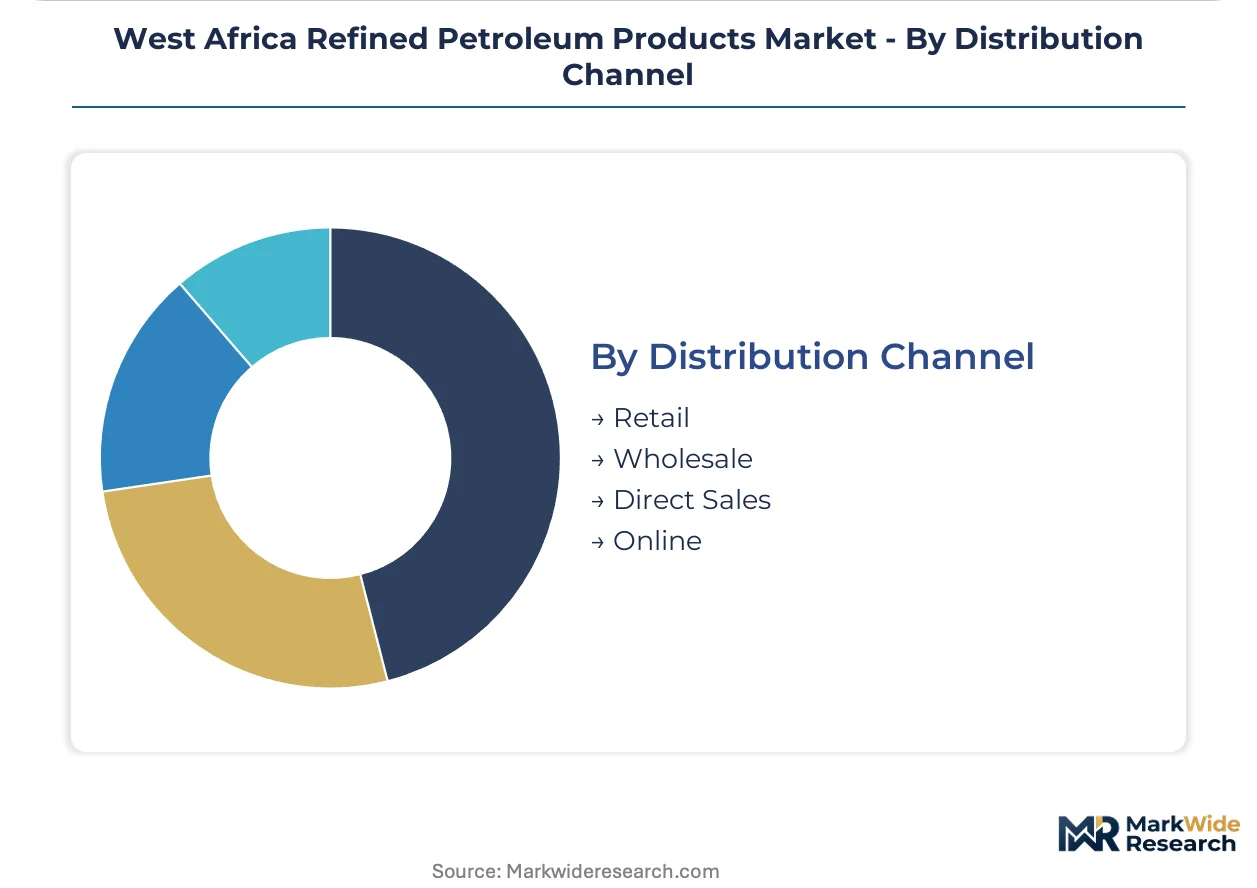
Distribution Channel:
Channel selection reflects buyer scale and credit sophistication, with direct sales expanding at the expense of traditional wholesale intermediaries.
- Wholesale:Bulk traders and depot operators aggregate volumes for redistribution to retail networks and large industrial accounts across Cotonou and Lomé coastal terminals.
- Direct Sales:Refinery-to-consumer agreements eliminate margin stacking for manufacturing clusters with sufficient storage and offtake scale.
- Retail:Branded and independent fuel stations serve fragmented vehicle and small commercial demand.
- Online:Digital procurement platforms remain nascent, limited by payment infrastructure and delivery logistics constraints.
Wholesale retains channel dominance; Direct Sales are climbing the fastest as bulk buyers consolidate procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Lagos-Abuja pipeline corridor and Apapa port complex anchor Nigerian supply logistics, while Ghana's Tema port and Takoradi terminal network underpin product import flows across the Gulf of Guinea coastal belt.
Nigeria
Diesel generator fleets and industrial manufacturing clusters in Lagos and Kano drive distillate consumption. Nigeria's Department of Petroleum Resources enforces gasoline and diesel quality standards under the AFRI-4 harmonization roadmap. Dangote Refinery's Lekki processing complex is displacing Atlantic basin imports across the Lagos-Abuja corridor.
Ghana
Grid instability and gas supply shortfalls accelerate diesel-fired backup power deployment. Ghana's National Petroleum Authority monitors import licensing and pricing formulas for petroleum product marketers. Tema's manufacturing zone scales direct refinery offtake agreements that bypass traditional trader intermediaries.
Côte d'Ivoire
Abidjan's port infrastructure and coastal depot expansion attract traders seeking alternatives to Nigerian concentration. The country's national petroleum regulator oversees product quality specifications aligned with regional harmonization. San-Pédro's emerging industrial corridor lifts fuel oil demand for process heat applications.
Senegal
Dakar's refining and storage terminal network serves as a distribution hub for Sahelian markets. The national energy ministry coordinates strategic petroleum reserve policies with regional stockpiling protocols. The Diamniadio industrial park near Dakar scales manufacturing operations requiring captive diesel power generation.
Benin
Cotonou's coastal terminal infrastructure handles transshipment volumes for landlocked Niger and Burkina Faso. The national petroleum products regulator implements import licensing frameworks under ECOWAS draft protocols. The Seme border corridor facilitates cross-border diesel trade with Nigerian manufacturing clusters.
West Africa Refined Petroleum Products Market Competitive Landscape
On the supply side, the industry is consolidating around integrated refiners, global commodity traders, and regional terminal operators with coastal logistics control. Strategic archetypes divide between large-scale domestic processors, floating storage specialists, and depot network aggregators. Competitive moves center on backward integration into refining capacity and geographic expansion through coastal terminal acquisitions.
Among integrated energy majors, TotalEnergies exemplifies the European refinery-to-terminal supply chain model, while Vitol occupies a position within the floating storage and offshore blending tier. Dangote Refinery anchors the domestic processing archetype with its large-scale Nigerian complex. These three entities represent the dominant competitive configurations reshaping procurement patterns across West African coastal markets.
| Leading Market Players |
|---|
| Mercuria Energy |
| TotalEnergies |
| Vitol |
| Sahara Group |
| Puma Energy |
| Trafigura |
| Oando Plc |
| Dangote Refinery |
| Glencore |
| Others |
Value Network & Pricing Analysis
The Rotterdam-Lagos clean tanker corridor anchors landed cost calculations for Atlantic basin cargoes, with freight rate volatility compressing margins for importers while enabling price differentiation between coastal terminals with floating storage access and onshore depot operators bearing higher logistics overhead.
Pricing Analysis
Volume-discount tiering structures separate large manufacturing clusters negotiating direct refinery offtake agreements from fragmented retail networks purchasing through wholesale intermediaries. Price differentiation hinges on sulfur specification compliance under AFRI-4 standards and delivery reliability during European refinery maintenance cycles. Cost compression in standard-grade diesel is intensifying because Dangote Refinery's domestic ramp-up displaces imported Atlantic basin volumes. Transport fleet operators exhibit the highest price sensitivity due to thin operating margins, while government strategic stockpilers prioritize supply security over unit economics.
Supply Chain Analysis
Upstream feedstock flows draw from Northwest European refineries in the Netherlands and Belgium, supplemented by Mediterranean processing capacity in Italy and Spain. Crude oil sourcing, hydrotreating catalyst procurement, and specialized tanker chartering constitute critical input dependencies. Single-source vulnerability concentrates in the Rotterdam-Amsterdam hub during turnaround seasons. Distribution runs through coastal terminals in Lomé, Cotonou, and Tema, with floating storage vessels enabling offshore blending that bypasses congested onshore infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fuel quality certification services and terminal storage management contracts represent expanding recurring-revenue layers growing faster than physical product trading margins, as traders pivot from arbitrage to logistics provision under tightening AFRI-4 specifications.
For Market Incumbents: Pre-empt terminal asset stranding by reconfiguring storage contracts around Dangote Refinery's displacement dynamics and redirecting capacity toward floating blending operations. Backward integration into hydrotreating catalyst management addresses technician scarcity threatening low-sulfur production compliance. Channel control over Côte d'Ivoire and Senegal coastal depots defends position against concentration risk in Nigerian markets.
For New Entrants and Emerging Players: Pursue underpenetrated storage infrastructure in San-Pédro and Diamniadio industrial corridors where manufacturing clusters lack captive supply arrangements. Côte d'Ivoire's emerging industrial zone offers the most penetrable geography given limited incumbent terminal coverage. Direct sales to bulk industrial offtakers bypass entrenched wholesale networks and capture margin compression from trader disintermediation.
For Investors and Strategic Acquirers: Carve-out targets emerge from integrated energy majors divesting non-core West African terminal assets amid portfolio rationalization. Long-term viability centers on coastal logistics control rather than product trading exposure over the next decade. Acquisition candidates with floating storage capabilities and AFRI-4-ready blending infrastructure command premium positioning. The signal to watch is Dangote Refinery's export volume trajectory as an inflection indicator for regional import dependency.
| Strategic Initiative | Industry Significance |
|---|---|
| Floating Storage Deployment | Offshore blending vessels bypass Lagos port congestion and enable sulfur specification adjustments at delivery. |
| AFRI-4 Compliance Investment | Hydrotreating retrofits at Lomé and Cotonou terminals secure market access under tightening regional standards. |
| Direct Refinery Offtake Agreements | Tema manufacturing clusters consolidate procurement, shifting credit risk from traders to end-users. |
| Coastal Depot Geographic Expansion | Côte d'Ivoire and Senegal storage multiplication reduces Nigerian concentration risk for trading portfolios. |
| Catalyst Management Service Layer | Technical service contracts address hydrotreating technician scarcity constraining low-sulfur production. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs import records, refinery production disclosures, and coastal terminal capacity registries. Primary interviews engaged petroleum product traders, terminal operators, manufacturing procurement leads, and national regulatory officials across Nigeria, Ghana, and Côte d'Ivoire. Secondary validation drew from Department of Petroleum Resources enforcement notices, National Petroleum Authority licensing data, and African Petroleum Producers Organization protocol drafts. Bottom-up volume aggregation across product type and application segments triangulates against top-down macroeconomic energy demand modeling.
Forecast inputs incorporate diesel generator fleet conversion rates, industrial corridor manufacturing expansion trajectories, and gas-to-power substitution timelines across the analysis window. Segmentation dimensions modeled include product type, application, end user, and distribution channel, with cross-cutting geographic clustering by coastal terminal network. CAGRs derive from historical volume trajectories adjusted for Dangote Refinery displacement effects and AFRI-4 specification enforcement acceleration. Industry-specific inputs include clean tanker freight rate volatility patterns and European refinery maintenance cycle scheduling.
Sensitivities concentrate around Dangote Refinery ramp-up delays, ECOWAS petroleum protocol ratification timelines, and offshore gas field development pace in Ghana. Forecasts reflect assumptions regarding sulfur specification harmonization adherence and piracy risk premiums in Gulf of Guinea shipping lanes. Cross-checking against IEA West Africa energy balance data and Platts product pricing benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Petroleum Products
Crude Tall Oil Market
Petroleum Products
Spindle Oil Market
Petroleum Products
South Africa Refined Petroleum Products Market
Petroleum Products
Liquefied Petroleum Gas Market
Petroleum Products
Pygas (Pyrolysis Gasoline) Market
Petroleum Products
Malaysia Refined Petroleum Products Market
Petroleum Products
Oil Shale Market
Petroleum Products
Uganda Petroleum Products Market
Petroleum Products
Australia Refined Petroleum Products Market
Petroleum Products
Petroleum Liquid Feedstock Naphtha and Gas Oil Sales Market
Petroleum Products
Oil Storage Sales Market
Petroleum Products
Crude Oil Flow Improvers Market
Petroleum Products
Quenching Oil Market
Petroleum Products
Very Low Sulphur Fuel Oil (VLSFO) Market
Petroleum Products
Balanos Oil Market
Petroleum Products
Africa Refined Petroleum Products Market