
 Green Petcoke Market | 2026-2036
Green Petcoke Market Size, Share, and Industry Trends Forecast 2026-2036
Green Petcoke Market Insights
Anthracite coal is pivoting toward displacement across carbon-intensive industries as green petcoke offers comparable calorific value with lower ash content. Chevron Corporation leverages its integrated refining network to supply consistent green needle coke grades to electrode manufacturers. Saudi Aramco anchors long-term offtake agreements with smelters in the Middle East. Rain Carbon Inc. specializes in calcination technology that upgrades raw green petcoke into higher-value anode-grade material.
Green petcoke denotes the raw, uncalcined solid carbon residue produced from delayed coker units in oil refineries, typically containing 15-30% volatile matter and sulfur levels ranging from 1-7% depending on crude source. Its primary commercial purpose centers on calcination into anode-grade or fuel-grade products for aluminum electrolysis and energy-intensive manufacturing. Green sponge coke dominates volume flows into aluminum anode production due to its low metal content and uniform structure. The fuel application segment captures margin pools in power generation and cement kilns where sulfur-tolerant combustion economics apply. Green needle coke commands premium positioning within the carbon source category for ultra-high-power graphite electrodes.
EPA regulations under the Clean Air Act limit sulfur dioxide emissions from industrial combustion, directly shaping fuel-grade petcoke acceptance criteria at US facilities. China's MEE enforces dual carbon goals that restrict high-sulfur petcoke imports while favoring lower-carbon intensity feedstocks in coastal provinces. India's CEA monitors particulate emissions from cement and power installations, influencing domestic blending requirements for green petcoke. Stakeholders must track evolving carbon-border adjustment mechanisms and refinery decarbonization timelines to anticipate raw material availability shifts.
Market Dynamics
Refinery decarbonization timelines are compressing green petcoke availability as coker units face carbon intensity scrutiny across North America and Europe. This supply constraint is forcing aluminum smelters and electrode manufacturers to renegotiate long-term offtake terms and diversify crude sourcing strategies.
Growth Catalysts
- EPA Clean Air Act enforcement:Sulfur dioxide emission limits at US industrial facilities are accelerating fuel-grade green petcoke substitution for higher-sulfur alternatives in cement kiln operations.
- Aluminum smelting corridor expansion:India's Odisha and Chhattisgarh states are adding electrolytic capacity that requires anode-grade green sponge coke with low metal impurities.
- Calcination technology advancement:Rotary kiln and shaft calciner upgrades are expanding the share of raw green petcoke convertible to premium anode-grade specifications.
Market Restraints
- Crude slate volatility:Heavy sour crude discounts fluctuate with OPEC+ production decisions, destabilizing green petcoke sulfur content predictability and pricing.
- Integrated refinery concentration:Over 70% of exportable green petcoke originates from Gulf Coast and Middle Eastern coker units, creating geographic supply vulnerability.
- Anthracite coal substitution economics:Pulverized coal injection in Chinese steelmaking retains cost advantage in regions with weak carbon pricing mechanisms.
Strategic Opportunities
- India's PLI scheme for specialty chemicals:Domestic calcination capacity expansion incentives could capture value-add steps currently performed in China and the Middle East.
- Carbon capture integration:Coker unit CO2 capture retrofits at US refineries may qualify for IRA tax credits, preserving feedstock output under tightening emissions frameworks.
- Sponge-to-needle upgrading:Advanced thermal treatment processes are opening pathways to produce lower-cost needle coke precursors from standard green sponge coke grades.
Industry Challenges
- Calciner operator skill scarcity:Experienced kiln engineers capable of optimizing volatile matter removal without structural damage to coke morphology are concentrated at legacy Rain Carbon and Oxbow facilities.
- Anode-grade certification timelines:Aluminum smelters require 18-24 month qualification periods for new green petcoke suppliers, locking out emerging producers from premium segments.
- Legacy coker unit retrofit complexity:Delayed coker drums built before 2005 lack instrumentation for real-time sulfur monitoring, compling compliance with China's MEE import documentation requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Green Petcoke Market |
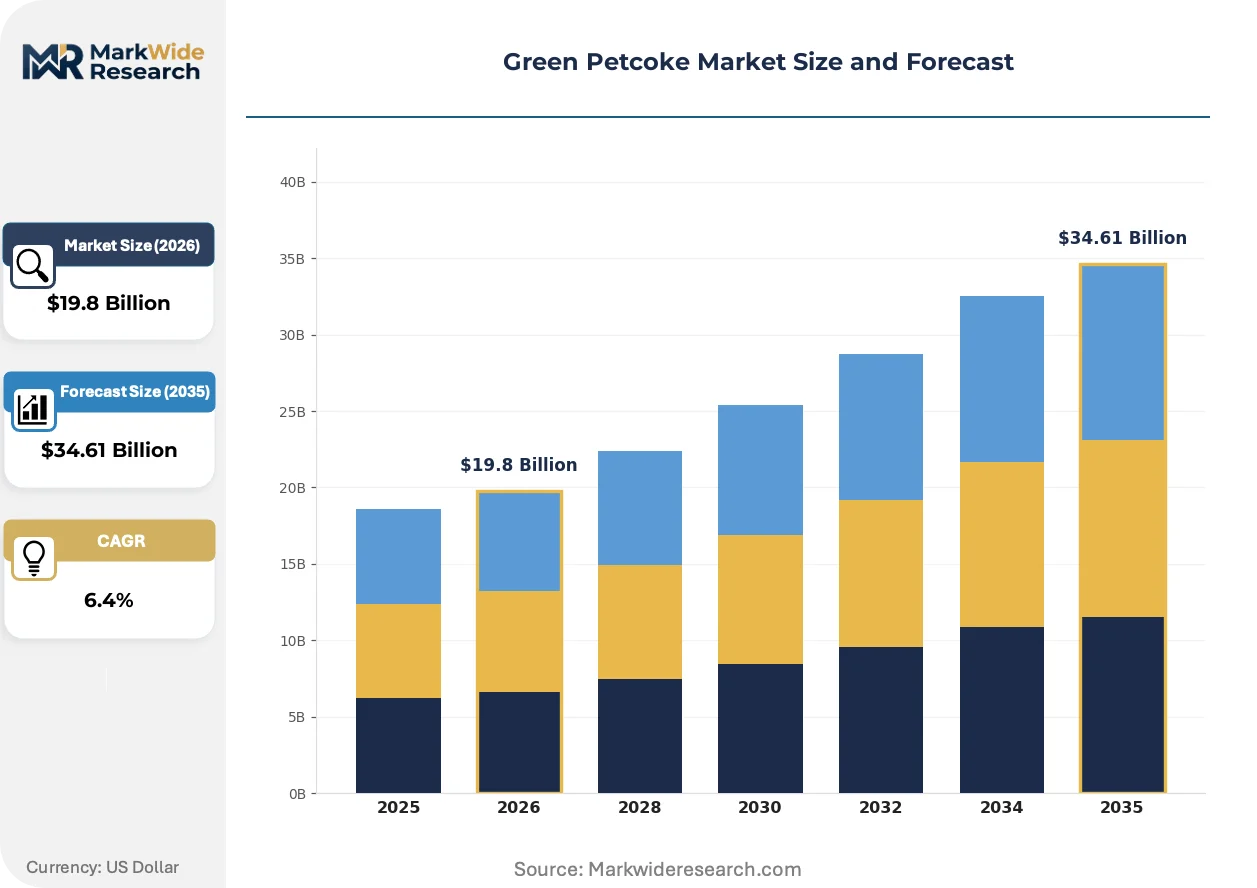
| Market Size in 2026 | $19.8 Billion |
| Market Size in 2035 | $34.61 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Green Needle Coke, Green Shot Coke, Green Sponge Coke, Green Petroleum Coke End User: Aluminum Industry, Chemical Manufacturing, Power Generation, Cement Production Form: Pulverized, Granular, Lumps, Powder Application: Fuel, Carbon Source, Additive, Reducing Agent |
| Companies Covered | Chevron Corporation, ExxonMobil Corporation, BP plc, Royal Dutch Shell plc, Saudi Arabian Oil Company (Saudi Aramco), Reliance Industries Limited, Phillips 66, Rain Carbon Inc., Oxbow Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Green Petcoke Market Trends and Innovations
Digital twin modeling of coker drum thermal profiles is reshaping how refineries optimize green petcoke structure and volatile content. These simulation tools are compressing development cycles for custom grades while enabling predictive maintenance that extends drum campaign life.
Advanced calcination control systems using real-time volatile matter sensors are absorbing variability in raw green petcoke feedstocks. Aluminum smelters in Canada and Norway are adopting these instrumented kilns to secure consistent anode performance. The technology is absorbing quality assurance costs previously passed through to electrode manufacturers.
China's MEE dual carbon enforcement is tightening documentary evidence requirements for imported green petcoke carbon intensity. Coastal province customs authorities now demand third-party verified sulfur and heavy metal content certificates. Fuel-grade importers in Shandong and Jiangsu are responding by pre-qualifying Middle Eastern suppliers through extended laboratory audit protocols.
Smelter procurement teams are consolidating supplier relationships from fragmented spot-market purchasing toward multi-year tolling arrangements with calcination partners. This behavior shift transfers inventory risk upstream while locking in anode-grade availability. The transformation is most visible in India's aluminum corridor, where Hindalco and Vedanta have executed five-year coke supply agreements with Saudi and Kuwaiti refiners.
Green Petcoke Market Segmentation
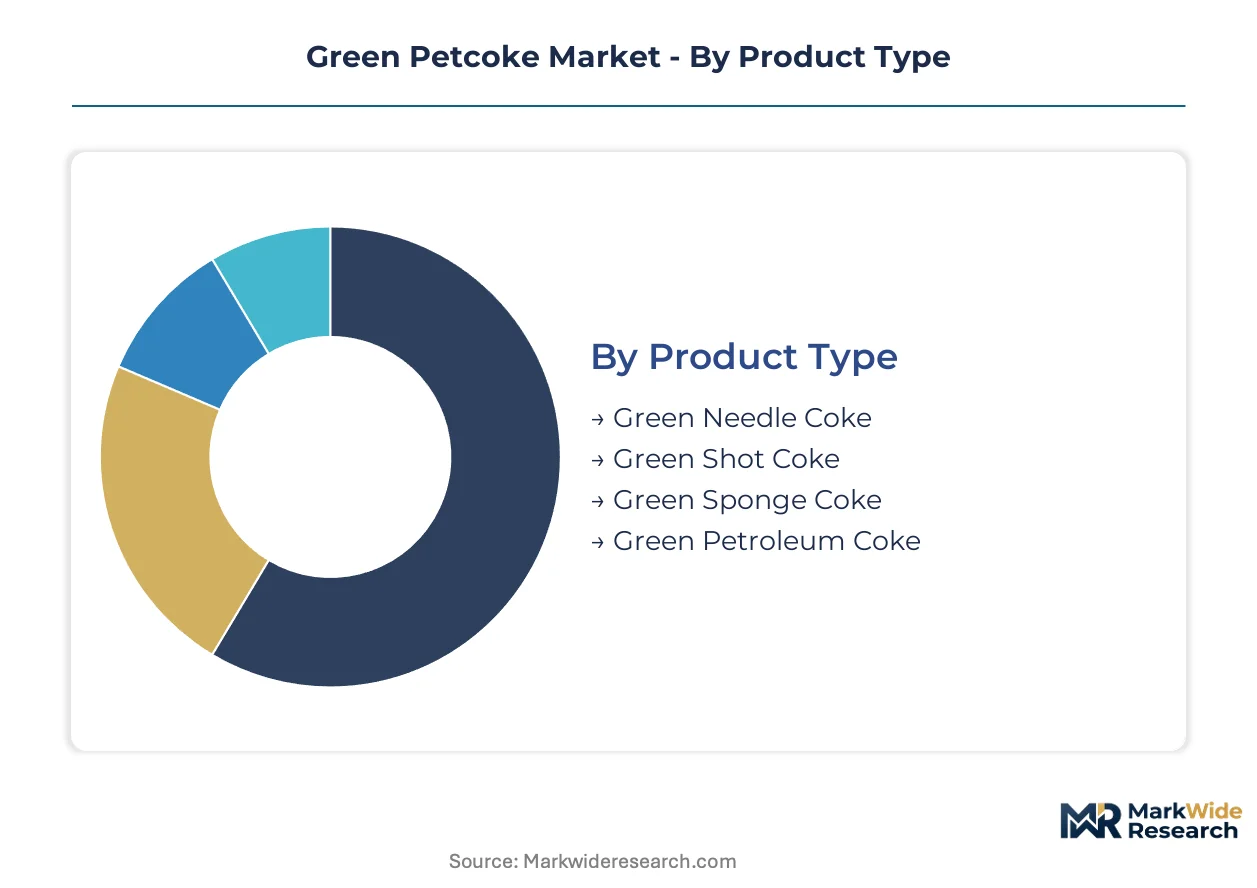
Green petcoke segmentation reveals how physical properties and end-use specifications create distinct value pools across the carbon materials supply chain. Refinery output characteristics and calcination requirements fragment procurement strategies across aluminum smelters, electrode manufacturers, and energy-intensive industries.
Product Type:
Supply concentration in coker unit technology determines which grades dominate exportable volumes and which command calcination premiums.
- Green Sponge Coke:Porous, amorphous carbon structure with 8-15% volatile matter and low metal content. Demand concentrates in India's Odisha smelting corridor where Hindalco and Vedanta require anode-grade feedstock with strict vanadium and nickel limits for electrolytic aluminum production.
- Green Needle Coke:Highly ordered crystalline structure with distinctive fibrous texture from specific feedstock selection in delayed cokers. Premium positioning in ultra-high-power graphite electrode manufacturing for electric arc furnaces, with Saudi Aramco and Chevron controlling specialized supply through long-term offtake agreements.
- Green Shot Coke:Spherical particle morphology from fluid coking operations with higher volatile content. Boiler fuel applications in cement kilns with sulfur-tolerant combustion economics.
- Green Petroleum Coke:Generic classification encompassing all uncalcined refinery carbon residues. Baseline fuel-grade material for power generation in regions with relaxed emissions standards.
Today's leader: Green Sponge Coke. Tomorrow's challenger: Green Needle Coke.
End User:
Customer concentration patterns reveal how regulatory stringency and process economics reshape procurement across carbon-intensive manufacturing.
- Aluminum Industry:Primary demand driver requiring low-sulfur, low-metal green sponge coke for prebaked anode production. India's CEA emission monitoring and expanding smelter capacity in Chhattisgarh anchor volume growth through qualified supplier relationships.
- Cement Production:Fuel-grade consumption in rotary kilns where sulfur dioxide scrubbing economics determine acceptance thresholds. EPA Clean Air Act enforcement in US facilities accelerates substitution away from higher-sulfur alternatives.
- Power Generation:Combustion applications with variable sulfur tolerance depending on regional emissions frameworks. China's MEE dual carbon restrictions constrain import eligibility for coastal province utilities.
- Chemical Manufacturing:Feedstock for carbon black and specialty chemical synthesis. Process requirements for consistent volatile matter content drive tolling arrangements with calcination specialists.
Procurement gravity centers on aluminum sector qualification timelines, while cement operators exploit sulfur-tolerant fuel arbitrage.
Form:
Physical processing economics fragment handling requirements and transportation cost structures across downstream applications.
- Granular:Standard sizing for aluminum anode manufacturing with controlled particle distribution. Dominates calciner intake specifications for rotary kiln operations.
- Pulverized:Fine grinding for pulverized coal injection systems and fluidized bed combustion. Chinese steelmakers evaluate substitution economics against anthracite coal.
- Lumps:Minimal processing for direct fuel use in cement kilns with mechanical handling systems. Gulf Cooperation Council exports favor this low-cost preparation state.
- Powder:Specialized sizing for chemical synthesis and carbon black feedstock. Dust control requirements elevate handling costs.
Granular form commands calcination premiums, while lump shipments minimize preprocessing overhead for fuel buyers.
Application:
Functional differentiation separates commodity fuel markets from specification-driven carbon material value chains.
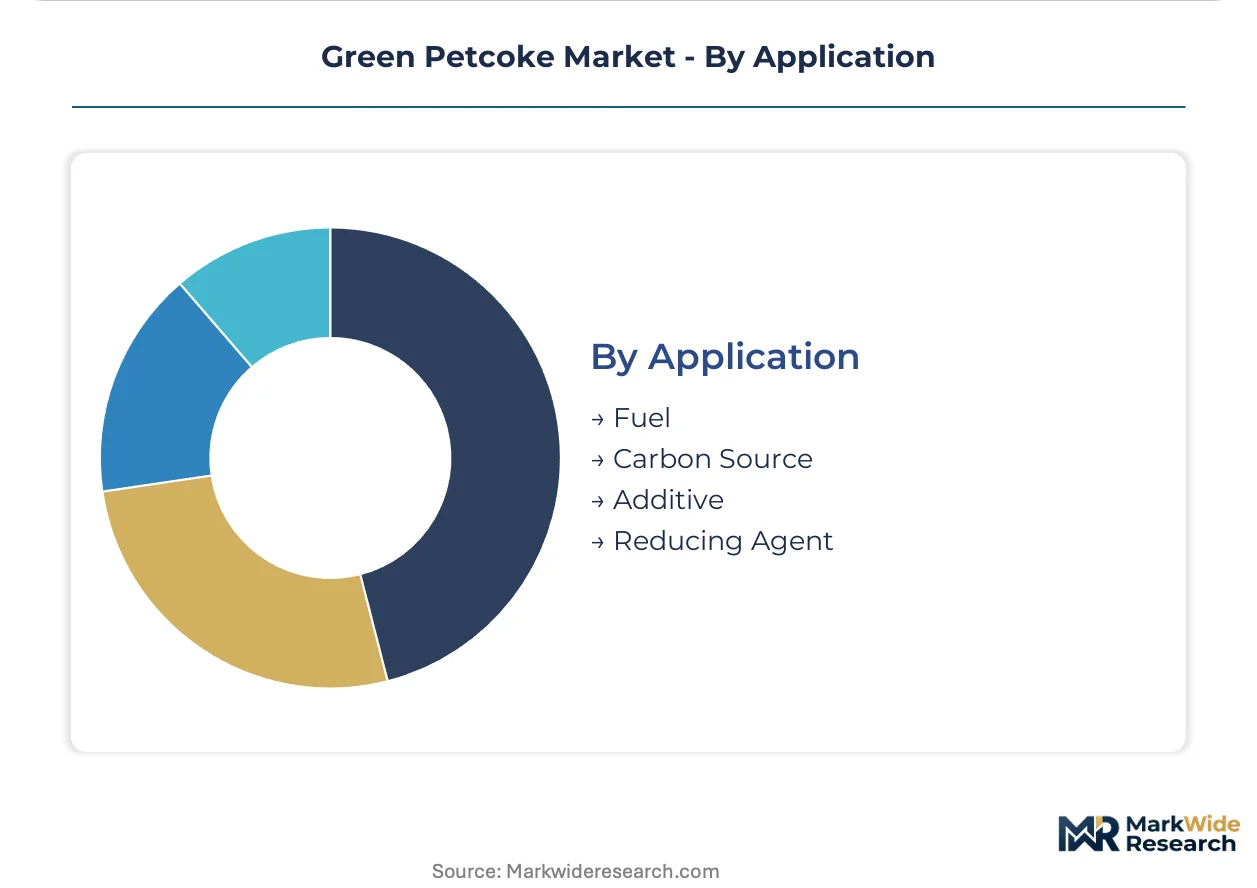
- Carbon Source:Anode-grade and electrode-grade calcination requiring precise structural properties. Aluminum smelters enforce 18-24 month supplier qualification protocols.
- Fuel:Energy recovery from volatile matter combustion in power and cement applications. Sulfur content variability drives spot-market pricing fragmentation.
- Reducing Agent:Metallurgical applications in silicon and ferroalloy production. Specific reactivity requirements limit qualified supply sources.
- Additive:Minor applications in construction materials and specialty chemicals. Volume concentration remains marginal.
Carbon source applications absorb quality assurance investment, while fuel markets trade on sulfur tolerance and calorific value.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's aluminum smelting corridor anchors regional demand concentration for anode-grade green sponge coke, with procurement patterns reshaping across multiple industrial clusters worldwide.
United States
EPA Clean Air Act enforcement tightens sulfur dioxide thresholds at cement kilns and power facilities, accelerating fuel-grade green petcoke substitution for higher-sulfur alternatives. Carbon capture retrofits at Gulf Coast refineries seek IRA tax credit qualification. Houston-area coker units supply electrode manufacturers through long-term offtake structures.
India
Odisha and Chhattisgarh states expand electrolytic aluminum capacity requiring low-metal green sponge coke for prebaked anode production. CEA particulate emission monitoring shapes domestic blending requirements for cement and power installations. Vedanta and Hindalco execute multi-year supply agreements with Middle Eastern refiners to secure qualified feedstock.
China
MEE dual carbon enforcement restricts high-sulfur petcoke imports at coastal province utilities while favoring lower-carbon intensity feedstocks. Shandong and Jiangsu customs authorities demand third-party verified sulfur and heavy metal certificates. Independent refiners pre-qualify suppliers through extended laboratory audit protocols.
Saudi Arabia
Integrated refining complexes at Ras Tanura and Yanbu anchor exportable green petcoke supply through specialized coker unit configurations. Long-term offtake agreements with South Asian smelters transfer inventory risk upstream while locking in anode-grade availability. SFDA industrial emission frameworks shape fuel-grade acceptance criteria at domestic facilities.
Germany
EU Green Deal carbon border adjustment mechanisms threaten import competitiveness of high-carbon intensity feedstocks at aluminum and chemical installations. REACH documentation requirements complicate green petcoke qualification for electrode manufacturers. Industrial clusters in North Rhine-Westphalia evaluate calcination technology upgrades to preserve feedstock access.
Green Petcoke Market Competitive Landscape
Global majors compete with regional champions across crude sourcing and calcination technology, creating a tiered structure where integrated oil companies control raw material output while specialized processors capture value-add margins. The vendor base separates into upstream refinery operators, midstream calcination specialists, and downstream tolling partners. Three archetypes dominate: Gulf-based integrated refiners with captive coker capacity, North American calcination technology licensors, and Asian tolling arrangements with smelter-backed offtake. Competitive moves concentrate on backward integration into crude sourcing and multi-year supply contract restructuring.
Within the integrated refiner tier, Chevron Corporation and Saudi Arabian Oil Company occupy positions as upstream feedstock anchors, while Rain Carbon Inc. exemplifies the calcination-specialist archetype through its technology-focused operational model. These three entities represent distinct competitive vectors: crude-integrated supply security, geographic proximity to demand corridors, and thermal processing capability for anode-grade upgrading.
| Leading Market Players |
|---|
| Chevron Corporation |
| ExxonMobil Corporation |
| BP plc |
| Royal Dutch Shell plc |
| Saudi Arabian Oil Company (Saudi Aramco) |
| Reliance Industries Limited |
| Phillips 66 |
| Rain Carbon Inc. |
| Oxbow Corporation |
| Others |
Pricing and Supply Chain Analysis
Anode-grade certification tiers versus fuel-grade commodity positioning create divergent margin architectures across the green petcoke value chain, with aluminum smelter qualification protocols locking in premium pricing for low-metal sponge coke while cement kilns arbitrage sulfur-tolerant spot markets. EPA Clean Air Act thresholds and China's MEE dual carbon documentation requirements enforce these pricing boundaries through compliance cost differentials that reshape refinery output allocation decisions.
Pricing Analysis
Crude slate sulfur content passes directly into green petcoke pricing through OPEC+ heavy sour production decisions that destabilize feedstock cost predictability. Contract-based long-term offtake structures dominate anode-grade transactions where Hindalco and Vedanta lock in multi-year supply security, while fuel-grade trades on commodity spot mechanisms sensitive to regional emissions enforcement intensity. Quality grade and certification level differentiation separates qualified anode material from cement kiln feedstock, with pricing pressure intensifying in fuel-grade tiers as China's MEE restrictions constrain import eligibility. Aluminum smelters exhibit lowest price sensitivity due to 18-24 month supplier qualification timelines, while coastal Chinese utilities face acute cost compression from documentary compliance burdens.
Supply Chain Analysis
Regional distribution centers at Ras Tanura and Yanbu anchor hub-and-spoke patterns that concentrate exportable green petcoke flows through Gulf Cooperation Council integrated refining complexes. Supply draws from Saudi Arabia, Kuwait, and United States Gulf Coast coker units, with raw material dependencies on heavy sour crude slates, delayed coker drum capacity, and calcination technology access. Single-source vulnerability concentrates in Middle Eastern export corridors where over 70 percent of tradeable volume originates, exposing procurement networks to geopolitical disruption and OPEC+ production policy shifts. Distribution runs through long-term tolling arrangements with calcination partners that transfer inventory risk upstream while securing anode-grade availability for qualified smelters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where aluminum smelter procurement teams prioritize low-metal, low-sulfur sponge coke specifications over fuel-grade alternatives, compressing margin pools in commodity tiers while calcination specialists capture value-add premiums.
For Market Incumbents: Anchor calcination capacity expansion in India's aluminum corridor to defend against emerging Middle Eastern tolling competitors seeking direct smelter relationships. Secure backward integration into crude sourcing through long-term offtake agreements with Gulf Coast refiners facing IRA tax credit qualification pressures, preserving feedstock access as EPA enforcement tightens sulfur thresholds at domestic facilities. For New Entrants and Emerging Players: Begin with India's PLI scheme for specialty chemicals to capture domestic calcination value-add steps currently performed in China and the Middle East. Target Odisha and Chhattisgarh smelter procurement teams with pre-qualified green sponge coke offerings that bypass 18-24 month certification timelines through technical partnership structures with established Rain Carbon or Oxbow engineering networks. For Investors and Strategic Acquirers: Consolidation pressure builds where calciner operator skill scarcity concentrates at legacy facilities and anode-grade certification timelines lock out emerging producers from premium segments. Five-to-ten year viability favors specialized thermal processing capability over commodity fuel-grade exposure, with acquisition targets exhibiting instrumented kiln technology and established smelter qualification protocols. Watch for carbon-border adjustment mechanism enforcement in EU Green Deal implementation as inflection indicator for high-carbon intensity feedstock competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Hindalco and Vedanta lock in five-year coke supply security with Saudi and Kuwaiti refiners. |
| Backward Integration | Chevron leverages integrated refining network to supply consistent green needle coke grades. |
| Capacity Expansion | Rain Carbon rotary kiln upgrades expand raw green petcoke conversion to premium anode-grade specifications. |
| Green Manufacturing Transition | US Gulf Coast coker unit CO2 capture retrofits seek IRA tax credit qualification under tightening frameworks. |
| Joint Venture | Saudi Aramco anchors long-term offtake structures with South Asian smelters transferring inventory risk upstream. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with refinery operations managers, aluminum smelter procurement leads, calcination technology licensors, cement kiln fuel buyers, and electrode manufacturing R&D directors with secondary validation from EIA petroleum data, IEA energy transition reports, SEC refinery filings, and customs trade records. Bottom-up segment sizing and top-down macroeconomic triangulation anchored volume and value estimates across the analysis window.
Segment-weighting approaches modeled green petcoke flows across product type differentiation, end-use industry concentration, physical form processing economics, and application-specific quality requirements. CAGRs derived from historical trade flow analysis and projected capacity addition timelines incorporated crude slate sulfur content variability, refinery decarbonization policy trajectories, and aluminum smelter corridor expansion schedules as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including unannounced OPEC+ production policy shifts, unscheduled coker unit maintenance events, and rapid carbon capture technology cost reductions that could alter refinery output economics. Decision-makers should treat outputs as directional within the stated assumption set, recognizing that EPA enforcement intensity and China's MEE dual carbon documentation requirements may accelerate or delay projected feedstock availability shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Petroleum Products
South Africa Petroleum Market
Petroleum Products
Uganda Petroleum Products Market
Petroleum Products
Southeast Asia Refined Petroleum Products Market
Petroleum Products
Saudi Arabia Refined Petroleum Products Market
Petroleum Products
Global Petroleum Pitch Market
Petroleum Products
Automotive Oil Market
Petroleum Products
Refined Petroleum Products Market
Petroleum Products
Europe Ethane Market
Petroleum Products
Pyrolysis Oil Market
Petroleum Products
United States Refined Petroleum Products Market
Petroleum Products
South Africa Lubricants Market
Petroleum Products
Ultra Low Sulphur Fuel Oil (ULSFO) Market
Petroleum Products
Pyrolysis Gasoline Market
Petroleum Products
Very Low Sulphur Fuel Oil (VLSFO) Market
Petroleum Products
Balanos Oil Market
Petroleum Products
Hydrocarbon Market