
 Uganda Petroleum Products Market | 2026-2036
Uganda Petroleum Products Market Size, Share, and Industry Trends Forecast 2026-2036
Uganda Petroleum Products Market Analytics
Skilled petroleum storage and logistics labor is rotating toward refined product handling as Uganda's refinery infrastructure matures. Vivo Energy Uganda leverages its retail network density to sustain downstream dominance across the Kampala metropolitan area. TotalEnergies SE anchors its position through integrated supply chains spanning import terminals to forecourt operations. Uganda National Oil Company competes as the state-backed entity with upstream-to-downstream strategic mandates.
Uganda petroleum products encompass refined hydrocarbon fuels including gasoline, diesel, jet fuel, and liquefied petroleum gas, typically characterized by octane ratings, cetane indices, and sulfur content specifications governed by national standards; these products serve as primary energy inputs for internal combustion engines, industrial heat systems, and domestic cooking applications. Diesel dominates product type volumes due to its centrality in heavy-duty transport and agricultural mechanization across Uganda's farming belts. LPG within the residential end user segment records the fastest structural expansion as urban households shift from biomass to cleaner cooking fuels. Direct sales through the distribution channel command premium margin pools by serving industrial buyers with contracted volume commitments and dedicated storage solutions.
The Petroleum Authority of Uganda enforces storage licensing and product quality standards that shape market access for new entrants, while the Uganda National Bureau of Standards mandates fuel specification compliance through periodic testing protocols. The Ministry of Energy and Mineral Development coordinates import quota allocations and strategic reserve policies that directly influence supply security and pricing dynamics. Stakeholders must monitor regulatory alignment between national standards and evolving East African Community harmonization frameworks to anticipate compliance cost shifts and competitive repositioning requirements.
Market Dynamics
Uganda's petroleum products sector faces structural pressure from the Petroleum Authority of Uganda's tightening storage licensing requirements, which force distributors to upgrade tankage infrastructure or surrender market access.
Growth Catalysts
- East African Community Trade Corridors:Expanding freight volumes along the Northern Corridor link Mombasa to Kampala, accelerating diesel offtake for heavy-duty trucking fleets serving regional cargo flows.
- Petroleum Supply Act Enforcement:Mandatory licensing for bulk storage facilities is consolidating the distributor base and creating regulated capacity expansion opportunities for compliant operators.
- LPG Infrastructure Buildout:Urban household transition from charcoal to bottled gas is driving cylinder distribution network expansion across Kampala metropolitan zones.
Market Restraints
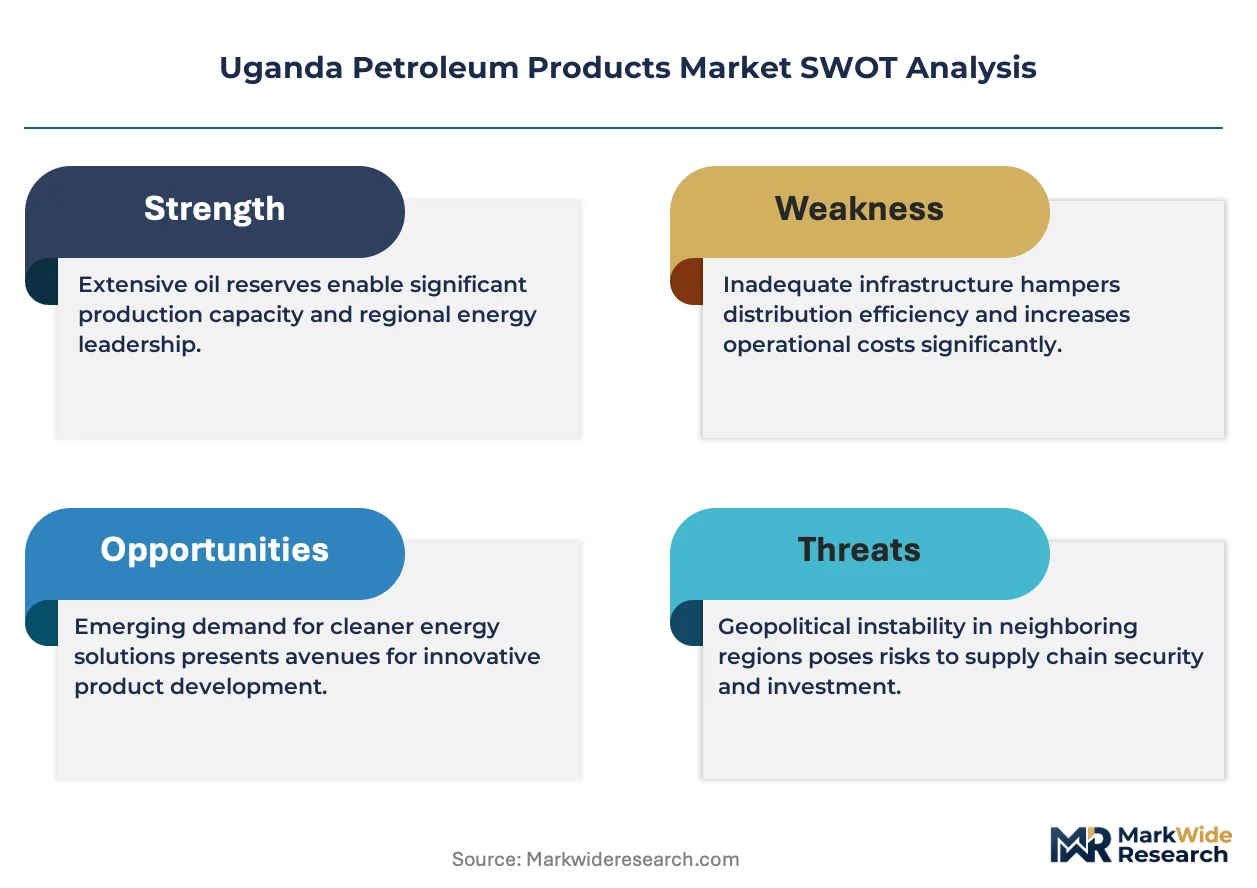
- Import Dependency Concentration:Refined product supply chains terminate at Mombasa and Dar es Salaam terminals, exposing Ugandan distributors to Kenyan and Tanzanian port congestion and foreign exchange volatility.
- Storage Capex Burden:Compliance with Petroleum Authority of Uganda tankage standards requires welded steel construction and secondary containment systems that triple facility development costs versus legacy designs.
- Biomass Substitution Persistence:Rural households continue relying on firewood and agricultural residue for thermal energy, capping LPG penetration rates outside major urban centers.
Strategic Opportunities
- Western Uganda Logistics Hubs:Oil refinery development near Hoima creates demand for dedicated product evacuation infrastructure and regional distribution terminals.
- Digital Fleet Management Integration:Telematics-enabled fuel monitoring systems allow commercial transporters to optimize consumption patterns and negotiate volume-based supply contracts.
- East African Community Harmonization:Converging fuel quality standards across member states enables cross-border product pooling and consolidated procurement strategies for regional fleet operators.
Industry Challenges
- Certified Welding Labor Scarcity:Petroleum Authority of Uganda licensing demands API-certified tank fabricators, but Uganda's technical institutes produce fewer than fifty qualified welders annually.
- Legacy Tank Farm Retrofitting:Existing above-ground storage facilities lack leak detection systems and fire suppression infrastructure required under revised safety codes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Uganda Petroleum Products Market |
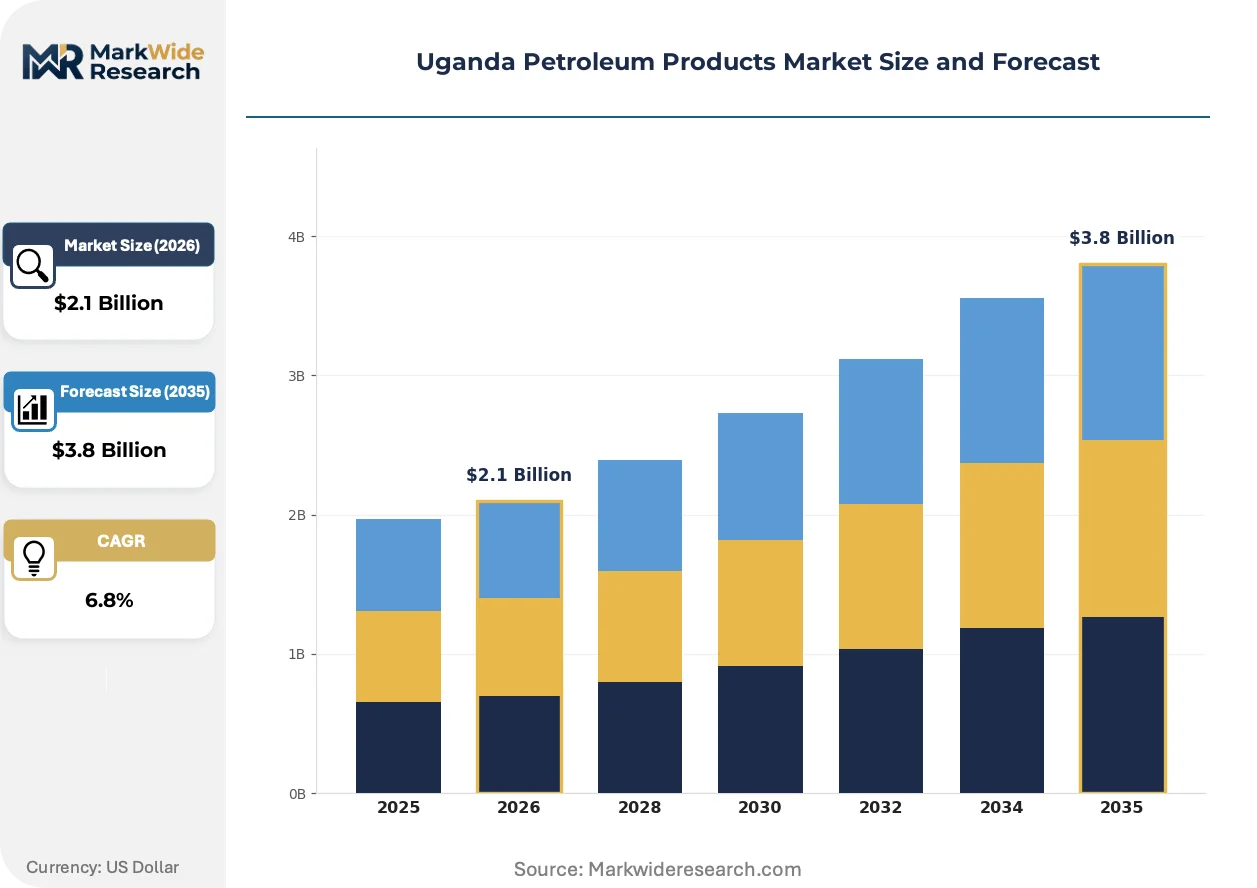
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gasoline, Diesel, Jet Fuel, LPG End User: Transportation, Industrial, Residential, Agriculture Distribution Channel: Retail Outlets, Direct Sales, Wholesalers, Online Platforms Application: Power Generation, Automotive, Heating, Marine |
| Companies Covered | Vivo Energy Uganda, TotalEnergies SE, Uganda National Oil Company, Nile Energy Limited, Stabex International Limited, Hass Petroleum Uganda Limited, Rubis Energy Uganda Limited, Ola Energy Uganda, Maestro Oil and Gas Solutions, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Uganda Petroleum Products Market Evolving Landscape
Digitalization of fuel logistics and quality assurance systems is restructuring how petroleum products flow from import terminals to end-users across Uganda's fragmented distribution landscape.
Automated tank gauging and wet-stock management software is supplanting manual dipstick measurements and paper-based inventory reconciliation at bulk storage terminals. Major depot operators in Kampala and Jinja are deploying sensor networks that transmit real-time level data to central dispatch systems. This visibility compression is reducing stock losses from leakage and theft while enabling just-in-time replenishment scheduling.
The Petroleum Authority of Uganda's electronic licensing portal now mandates digital submission of storage facility inspection reports and product quality test certificates. This regulatory digitization is forcing smaller distributors to acquire enterprise resource planning capabilities or outsource compliance documentation to specialized service providers. Industrial buyers with contracted volume commitments are prioritizing suppliers with demonstrated digital audit trails.
Commercial fleet operators are consolidating fuel purchasing through fuel card networks that aggregate consumption across multiple vehicle classes and geographic operating territories. This procurement concentration is displacing traditional station-by-station cash transactions and enabling direct supplier relationships between transporters and primary importers. Long-haul trucking companies operating the Northern Corridor represent the most advanced adopters of this purchasing rationalization.
Uganda Petroleum Products Market Segmentation
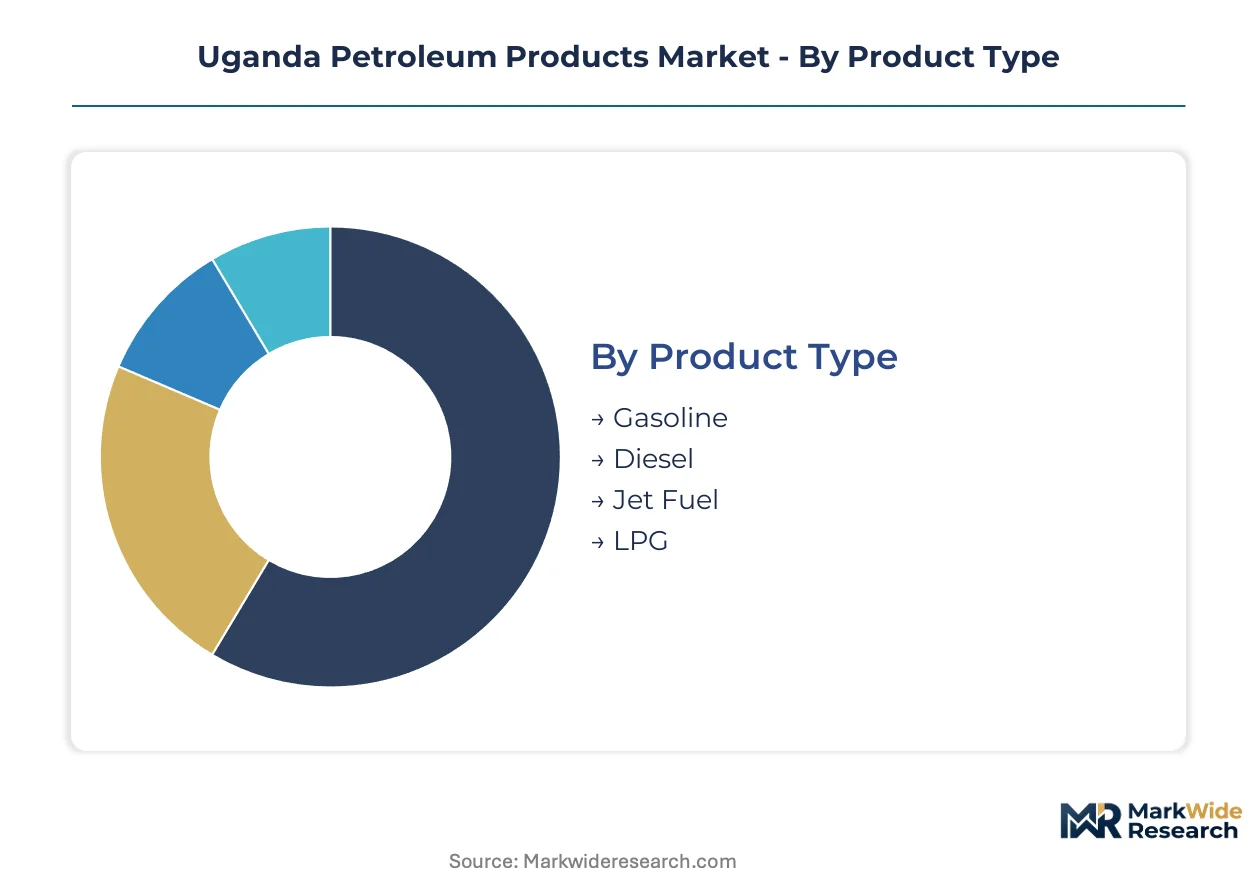
Petroleum Authority of Uganda licensing tiers create divergent compliance burdens across product categories and distribution modes. Segmentation reveals where regulatory differentiation concentrates investment and where margin pools shift toward compliant operators.
Product Type:
Petroleum Authority of Uganda mandates distinct storage standards by volatility class, forcing capital allocation toward higher-specification tankage for lighter fractions.
- Diesel:Middle distillate with cetane index specifications governing combustion quality in compression-ignition engines. Heavy-duty trucking fleets along the Kampala-Jinja corridor anchor demand as regional freight volumes expand. Diesel handles the majority of throughput; LPG is the fastest mover on share.
- LPG:Liquefied petroleum gas comprising propane and butane mixtures stored under pressure for vaporization at point of use. Urban households in Kampala metropolitan zones are shifting from charcoal, cylinder distribution networks are scaling to match replacement rates. LPG infrastructure buildout attracts dedicated logistics investment separate from liquid fuel handling systems.
- Gasoline:Light hydrocarbon blend with octane ratings determining knock resistance in spark-ignition engines, serving private vehicle and motorcycle fleets.
- Jet Fuel:Kerosene-based aviation turbine fuel meeting strict flash point and freezing point specifications for aircraft propulsion systems.
Refined product flows concentrate in diesel volumes; LPG cylinder distribution is climbing the fastest on household conversion rates.
End User:
Customer scale determines procurement modality and storage infrastructure requirements, with bulk consumers commanding dedicated tankage and contracted supply terms.
- Transportation:Fleet operators purchasing diesel and gasoline through retail networks or direct supply agreements, consumption patterns tracked via fuel card systems. Long-haul trucking companies operating Northern Corridor routes negotiate volume commitments with primary importers. Transportation absorbs the largest share of refined product offtake; Residential is expanding most quickly on LPG adoption.
- Industrial:Manufacturing facilities and mining operations consuming diesel for captive power generation and process heat, typically sourcing through direct sales channels with on-site storage.
- Residential:Households purchasing LPG in cylinder exchanges or kerosene for lighting, concentrated in Kampala and secondary urban centers.
- Agriculture:Mechanized farming operations in western and northern Uganda consuming diesel for irrigation pumps and harvest equipment, seasonal demand patterns aligned to planting cycles.
Transportation channels dominate volume throughput; Residential LPG conversion is gaining share fastest on urban air quality concerns.
Distribution Channel:
Channel selection dictates margin structure and capital intensity, with direct sales capturing premium pricing through dedicated infrastructure commitments.
- Direct Sales:Contracted supply relationships between importers and large consumers with private storage facilities, bypassing retail markup layers. Industrial buyers in Kampala industrial parks and mining concessions in southwestern Uganda anchor this channel. Direct Sales commands the highest margin pool; Online Platforms are emerging fastest on fleet management digitization.
- Retail Outlets:Branded and independent service stations dispensing gasoline and diesel to private motorists and small commercial operators.
- Wholesalers:Intermediate distributors supplying smaller commercial accounts and rural retail points without direct import access.
- Online Platforms:Digital procurement interfaces enabling fleet operators to aggregate purchases across multiple depots and optimize routing.
Direct Sales handles premium volume commitments; Online Platforms are scaling fastest on telematics integration.
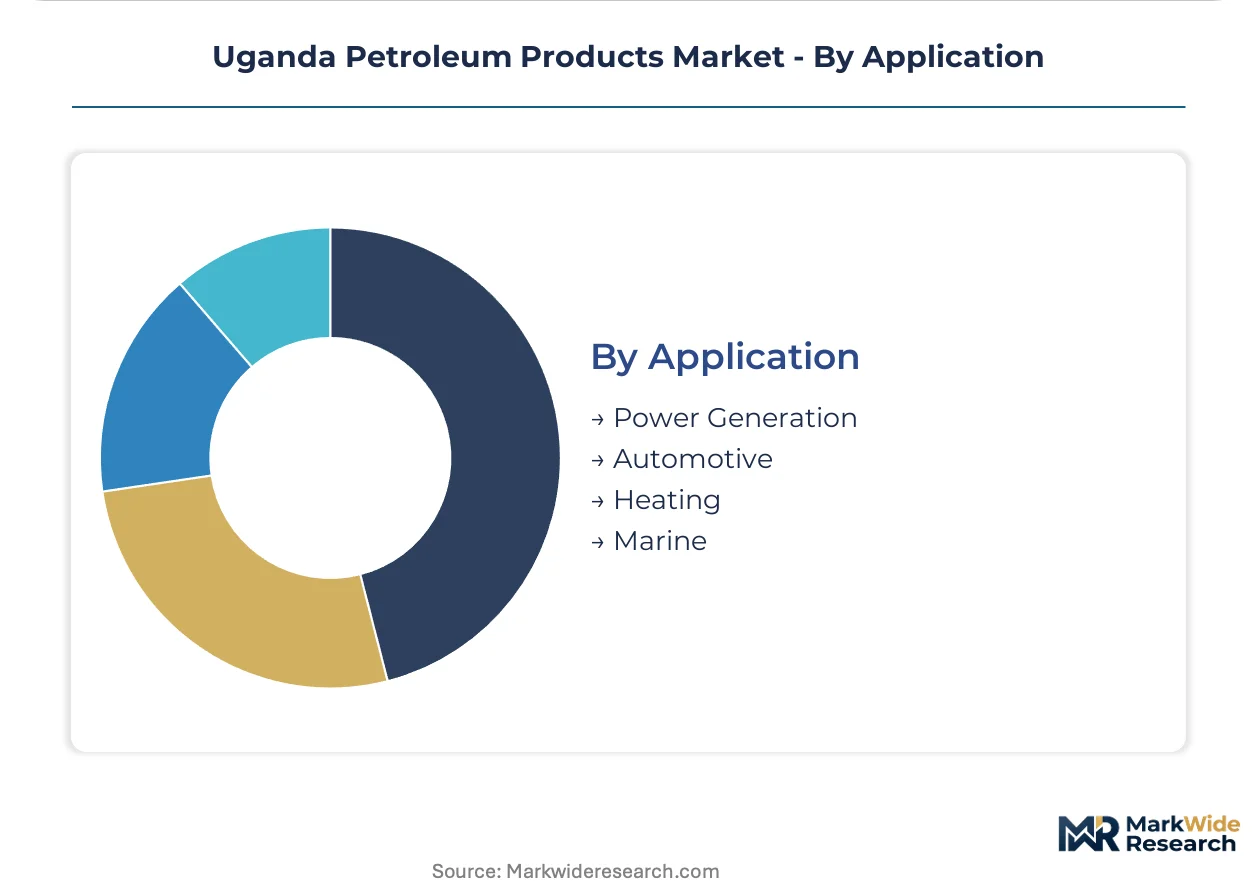
Application:
End-use function determines product specification requirements and seasonal demand patterns, with automotive and power generation commanding year-round offtake.
- Automotive:Internal combustion engine propulsion across passenger vehicles, motorcycles, and commercial trucks, specifications governed by national fuel quality standards. Kampala metropolitan congestion and Northern Corridor freight flows concentrate automotive diesel and gasoline consumption. Automotive represents the dominant application; Heating is expanding fastest on LPG household conversion.
- Power Generation:Diesel-fueled backup and prime power systems for industrial facilities, hospitals, and telecommunications infrastructure facing grid reliability constraints.
- Heating:Residential and commercial thermal applications, LPG displacing biomass and kerosene in urban cooking and water heating.
- Marine:Lake Victoria vessel operations consuming marine diesel oil and residual fuel oils for cargo and passenger transport.
Automotive applications anchor throughput volumes; Heating is climbing fastest on clean cooking policy alignment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Petroleum Authority of Uganda anchors regulatory oversight across East African petroleum corridors. National standards diverge from regional harmonization timelines, creating compliance complexity for cross-border distributors.
Kampala Metropolitan Area
Industrial zones in Namanve and Luzira drive diesel consumption for captive power and logistics fleets. The Petroleum Supply Act mandates secondary containment systems for all new bulk storage facilities. Kampala's fuel terminals are consolidating under licensed operators with API-certified tankage.
Jinja Corridor
Heavy-duty trucking terminals along the Kampala-Jinja highway anchor gasoline and diesel offtake for Northern Corridor freight. Petroleum Authority of Uganda licensing tiers favor welded steel construction over riveted legacy tankage. Jinja's industrial parks are attracting dedicated petroleum logistics investment from compliant distributors.
Hoima Region
Refinery infrastructure development near Lake Albert is creating demand for product evacuation pipelines and regional distribution terminals. The Ministry of Energy and Mineral Development coordinates strategic reserve policies affecting local supply security. Hoima's logistics hubs are positioning for refined product handling as upstream output matures.
Mbarara and Western Uganda
Agricultural mechanization in the Ankole cattle corridor drives seasonal diesel demand for irrigation and harvest equipment. Uganda National Bureau of Standards enforces fuel quality testing protocols at regional depots. Mbarara's commercial crossroads function is attracting cylinder distribution networks for LPG conversion.
Gulu and Northern Uganda
Post-conflict reconstruction and agricultural expansion are expanding petroleum product access corridors. Import quota allocations from the Ministry of Energy influence supply reliability for northern distributors. Gulu's emerging commercial center is drawing wholesale petroleum investment from Kampala-based operators.
Uganda Petroleum Products Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in Uganda's petroleum distribution structure. Vivo Energy Uganda and TotalEnergies SE anchor the upper tier through combined import terminal access and retail network density. Below them, a fragmented specialist tier includes state-backed entities and regional wholesalers competing on geographic coverage. Competitive moves concentrate on storage licensing compliance and fleet management digitization rather than price-based rivalry.
Within the integrated tier, TotalEnergies SE represents multinational supply chain integration, while Vivo Energy Uganda exemplifies retail network dominance across metropolitan fuel corridors. Uganda National Oil Company occupies a position as the state-mandated upstream-to-downstream entity with strategic reserve responsibilities. Among regional specialists, Nile Energy Limited and Stabex International Limited sit within the wholesale distribution archetype serving secondary urban centers. Hass Petroleum Uganda Limited anchors East African regional coverage from its Uganda base. These five entities collectively illustrate the market's structural segmentation between integrated leaders with import terminal control and specialists with corridor-specific logistics expertise.
| Leading Market Players |
|---|
| Vivo Energy Uganda |
| TotalEnergies SE |
| Uganda National Oil Company |
| Nile Energy Limited |
| Stabex International Limited |
| Hass Petroleum Uganda Limited |
| Rubis Energy Uganda Limited |
| Ola Energy Uganda |
| Maestro Oil and Gas Solutions |
Value Network & Pricing Analysis
Fourteen-day inventory cycles at Mombasa import terminals concentrate pricing power among licensed distributors with dedicated tankage, while Ugandan buyers absorb foreign exchange volatility passed through coastal supply contracts. This lead-time compression rewards operators with secondary containment infrastructure and penalizes cash-constrained wholesalers dependent on spot procurement.
Pricing Analysis
Kampala-Jinja corridor diesel spreads widen against Mombasa benchmarks during Kenyan port congestion episodes, amplifying margin capture for integrated importers with floating storage. Contract-based long-term offtake dominates industrial procurement, with price differentiation resting on volume scale and Petroleum Authority of Uganda certification tier. Pricing pressure stems from storage capex burdens forcing smaller distributors to surrender licensed capacity. Fleet operators with fuel card aggregation exhibit lowest price sensitivity; rural retail points show highest sensitivity to pump price movements.
Supply Chain Analysis
Kenya and Tanzania anchor refined product supply for Uganda, with Mombasa and Dar es Salaam terminals feeding the Northern Corridor pipeline and road tanker networks. Crude oil draws from Middle Eastern and West African sources, while specialized LPG cargoes originate from Algerian and Qatari export facilities. Single-source vulnerability concentrates at Mombasa's Kipevu Oil Terminal, where vessel queuing delays cascade through Ugandan distributor scheduling. Distribution runs through licensed bulk depots in Kampala and Jinja, with final-mile cylinder networks penetrating metropolitan households.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Uganda's petroleum products market fragments around regulatory compliance tiers, with Petroleum Authority of Uganda licensing standards creating defendable niches for tankage-equipped operators as household LPG conversion accelerates urban demand segmentation.
For Market Incumbents: Secure API-certified welding labor through technical institute partnerships before competitor recruitment exhausts annual graduate pools. Extend secondary containment retrofit programs to legacy tank farms ahead of enforcement deadlines, converting compliance burden into capacity consolidation opportunities. Vertical integration into cylinder distribution networks captures residential LPG growth while raising rival entry barriers. For New Entrants and Emerging Players: Digital fleet management services represent the most penetrable service layer, with telematics-enabled fuel monitoring underserved by incumbent distributors focused on physical infrastructure. Target long-haul trucking companies operating Northern Corridor routes with consumption analytics bundled into supply contracts. Go-to-market execution centers on pilot deployments with single fleet operators to demonstrate routing optimization value before scaling. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across welded steel tankage construction as Petroleum Authority of Uganda standards displace legacy riveted designs. Viability over the coming decade favors acquisition of distressed licensed distributors with compliant infrastructure rather than greenfield development. Watch for strategic reserve policy announcements from the Ministry of Energy as signals of supply security premium capture opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Storage Licensing Compliance | Petroleum Authority of Uganda certification creates regulated capacity moats for welded steel operators. |
| LPG Cylinder Network Expansion | Kampala metropolitan household conversion drives dedicated logistics investment separate from liquid fuels. |
| Digital Fleet Management Integration | Telematics-enabled procurement displaces station-by-station cash transactions for Northern Corridor operators. |
| Refinery Evacuation Infrastructure | Hoima region product pipelines position compliant distributors for western Uganda supply anchoring. |
| East African Community Harmonization Alignment | Converging fuel quality standards enable cross-border product pooling for regional fleet procurement. |
Research Methodology
Operator-level perspectives from petroleum depot managers, fleet procurement officers, Petroleum Authority of Uganda licensing administrators, and LPG cylinder distributors anchored the qualitative base for this study. Primary fieldwork combined structured interviews with secondary validation through Petroleum Supply Act regulatory filings, Uganda National Bureau of Standards test protocols, and Ministry of Energy import quota records. Bottom-up volume modeling across product type, end user, and distribution channel segments triangulated against top-down energy consumption benchmarks.
Sensitivity analysis tested forecast outputs against regulatory enforcement timing, refinery commissioning schedules, and East African Community tariff regime scenarios across the projection horizon. Segmentation dimensions modeled encompass product volatility class, customer scale tier, channel capital intensity, and geographic corridor access. CAGRs derived from historical throughput trends at Kampala and Jinja terminals, adjusted for LPG household penetration elasticity and diesel freight demand correlation with Northern Corridor cargo volumes.
Forecasts assume regulatory continuity in Petroleum Authority of Uganda licensing frameworks and Ministry of Energy strategic reserve policies; material policy shifts would require re-modeling. Specific risks include Kenyan port congestion duration, biomass substitution persistence in rural markets, and certified fabrication labor supply constraints. Recalibration cycles align with material shifts in storage infrastructure commissioning and regional trade corridor throughput.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Petroleum Products
Crude Oil Market
Petroleum Products
PAG Base Oil Market
Petroleum Products
Africa Refined Petroleum Products Market
Petroleum Products
United States Refined Petroleum Products Market
Petroleum Products
Tar Oil Market
Petroleum Products
Refined Petroleum Products Market
Petroleum Products
Petroleum Liquid Feedstock Market
Petroleum Products
Petroleum Benzine Market
Petroleum Products
Australia Refined Petroleum Products Market
Petroleum Products
Asia-Pacific Lubricants Market
Petroleum Products
South Africa Refined Petroleum Products Market
Petroleum Products
Nigeria Petrol Station Market
Petroleum Products
Alkylate Gasoline Market
Petroleum Products
Oil Shale Market
Petroleum Products
Base Oil Market
Petroleum Products
Naphtha Market