
 United States Pressure Sensitive Adhesives (PSA) Market | 2026-2036
United States Pressure Sensitive Adhesives (PSA) Market Size, Share, and Industry Trends Forecast 2026-2036
United States Pressure Sensitive Adhesives (PSA) Market Analytics
Aftermarket service revenue for PSA application equipment is fragmenting as OEMs push preventive maintenance contracts and remote diagnostics. 3M sustains technology leadership through its acrylic adhesive platform and tape bonding solutions for electronics miniaturization. Henkel AG & Co. KGaA dominates automotive structural bonding with its epoxy-acrylic hybrid systems. Avery Dennison Corporation specializes in label and packaging adhesives, leveraging film casting expertise to serve beverage and logistics customers.
Pressure sensitive adhesives are viscoelastic materials that bond to surfaces through applied pressure alone, typically formulated from acrylic, rubber, or silicone polymers with glass transition temperatures between minus sixty and minus twenty degrees Celsius, and they serve primarily as joining, mounting, and sealing solutions across manufacturing and consumer applications. Water-based formulations lead volume due to EPA VOC compliance advantages, though hot melt systems are capturing share in high-speed packaging lines where set speed determines throughput. Medical applications command premium positioning because biocompatibility testing and FDA device master file requirements create formulation lock-in and extend product lifecycles.
FDA biocompatibility standards for skin-contact medical devices, EPA National Emission Standards for Hazardous Air Pollutants for adhesive manufacturing, and OSHA Permissible Exposure Limits for solvent constituents collectively elevate compliance costs and favor larger formulated product manufacturers with dedicated regulatory affairs functions. The Federal Trade Commission Green Guides additionally constrain environmental marketing claims, requiring substantiation for recyclable or biodegradable adhesive assertions. Stakeholders must monitor state-level extended producer responsibility legislation in California and New York, where packaging adhesive take-back requirements could reshape cost allocation across value chains.
Market Dynamics
Automotive lightweighting programs and EPA VOC compliance mandates are restructuring formulation priorities across the United States Pressure Sensitive Adhesives market, pulling volume toward water-based acrylic systems while solvent-based alternatives face mounting regulatory pressure.
Growth Catalysts
- Automotive Composite Bonding:OEM lightweighting targets are accelerating PSA adoption in carbon-fiber and aluminum joining applications, particularly around Detroit and Cleveland manufacturing clusters.
- EPA National Emission Standards for Hazardous Air Pollutants:The 2024 amendments are mandating solvent recovery systems and favoring water-based formulation investments by mid-sized manufacturers.
- Medical Device Skin-Contact Applications:FDA biocompatibility testing requirements for ISO 10993 compliance are locking in qualified suppliers for wound care and wearable sensor markets.
Market Restraints
- Petrochemical Feedstock Volatility:Acrylic monomer and tackifier resin prices fluctuate with crude oil derivatives, compressing margins for formulation houses without backward integration.
- Great Lakes Supply Concentration:Over sixty percent of domestic automotive PSA volume flows through a three-state corridor, creating weather and logistics vulnerability.
- Hot Melt Performance Ceiling:Polyolefin and EVA-based hot melts lack the shear resistance and temperature range of solvent acrylics, limiting penetration in structural automotive bonding.
Strategic Opportunities
- California Extended Producer Responsibility:Pending packaging take-back legislation in Sacramento is creating first-mover advantage for adhesive suppliers with recyclable film and liner technologies.
- Electronics Miniaturization:Die-attach and flexible circuit bonding for semiconductor packaging represents underpenetrated volume with pricing premiums over industrial grades.
- Silicone Hybrid Formulation:Convergence of silicone weathering resistance with acrylic processability is opening outdoor signage and photovoltaic module assembly applications.
Industry Challenges
- Formulation Chemist Shortage:The talent pipeline for viscoelastic polymer design and rheology optimization has tightened as universities reduce adhesive science programs.
- FDA Master File Timeline:Biocompatibility certification cycles for new medical-grade PSAs now exceed thirty-six months, delaying revenue recognition for development programs.
- Legacy Coating Line Retrofit:Converting solvent-based coating equipment for water-based or hot-melt operation requires capital outlays that strain mid-tier manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Pressure Sensitive Adhesives (PSA) Market |
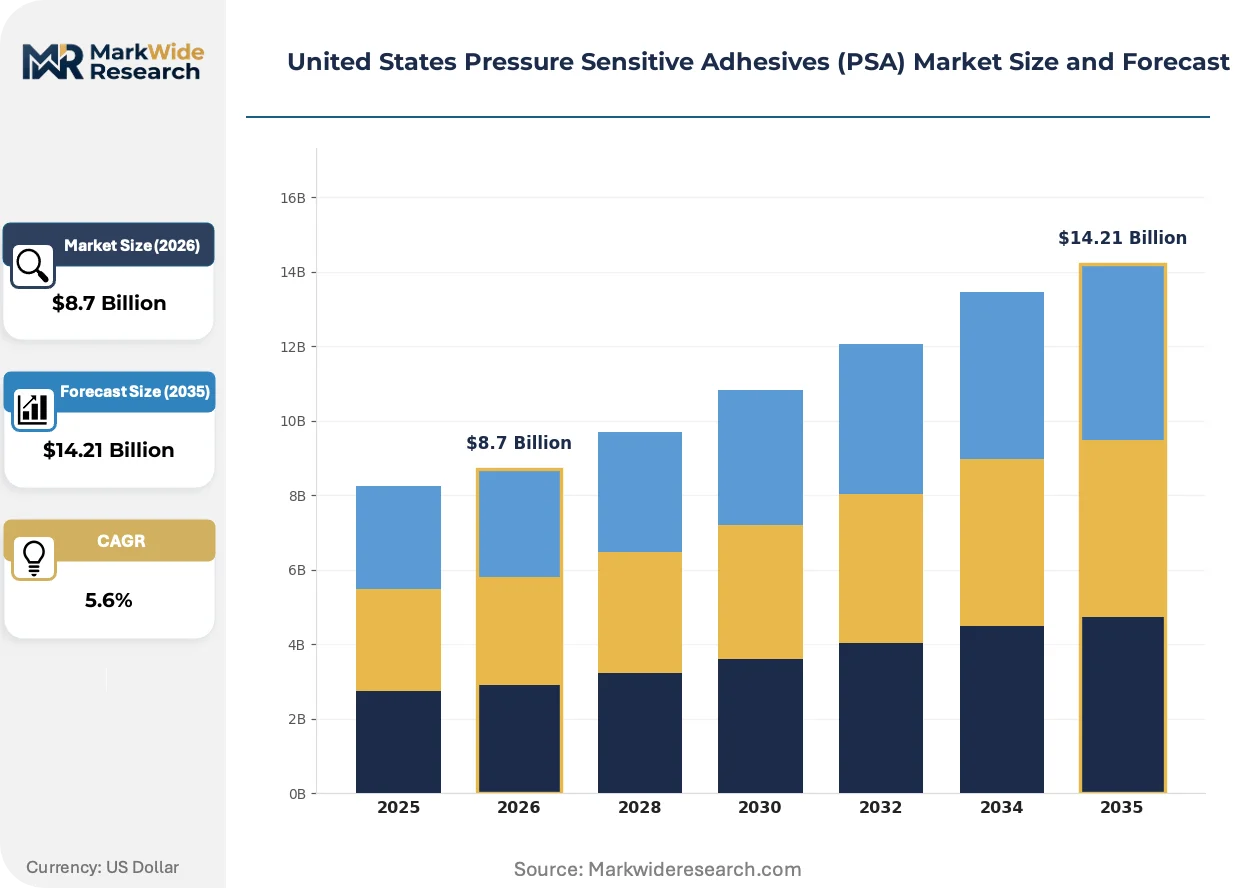
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-Based, Solvent-Based, Hot Melt, Ultra-Low Tack Application: Labels, Tapes, Medical, Packaging Technology: Surface Modification, Film Casting, Coating, Composite End User: Automotive, Electronics, Construction, Consumer Goods |
| Companies Covered | Henkel AG & Co. KGaA, Illinois Tool Works, 3M, Sika AG, Arkema, Avery Dennison Corporation, Dow, Wacker Chemie AG, H.B. Fuller Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Pressure Sensitive Adhesives (PSA) Market Evolving Landscape
Digital simulation tools and predictive formulation software are compressing R&D cycles across the United States PSA industry, while regulatory pressure and buyer consolidation reshape competitive requirements.
Digital twin technology for adhesive performance modeling is virtualizing traditional lab-based qualification workflows. Automotive tier suppliers in Michigan and Ohio now simulate peel strength and shear failure modes before physical prototyping. This virtualization is collapsing development timelines from eighteen months to under six for new vehicle programs.
EPA enforcement of workplace exposure limits under OSHA Permissible Exposure Limits is tightening solvent-based system availability. Formulators face capital decisions on carbon adsorption or thermal oxidizer investments. Small and mid-sized manufacturers in the Ohio River Valley are responding by exiting solvent acrylic production entirely.
Automotive OEMs now bundle adhesive procurement with preventive maintenance contracts for automated dispensing equipment. Tier suppliers displace spot-buy arrangements with multi-year service agreements. This pattern is most visible in the Chicago corridor, where Ford and Stellantis assembly plants consolidate vendor bases to reduce qualification overhead.
United States Pressure Sensitive Adhesives (PSA) Market Segmentation
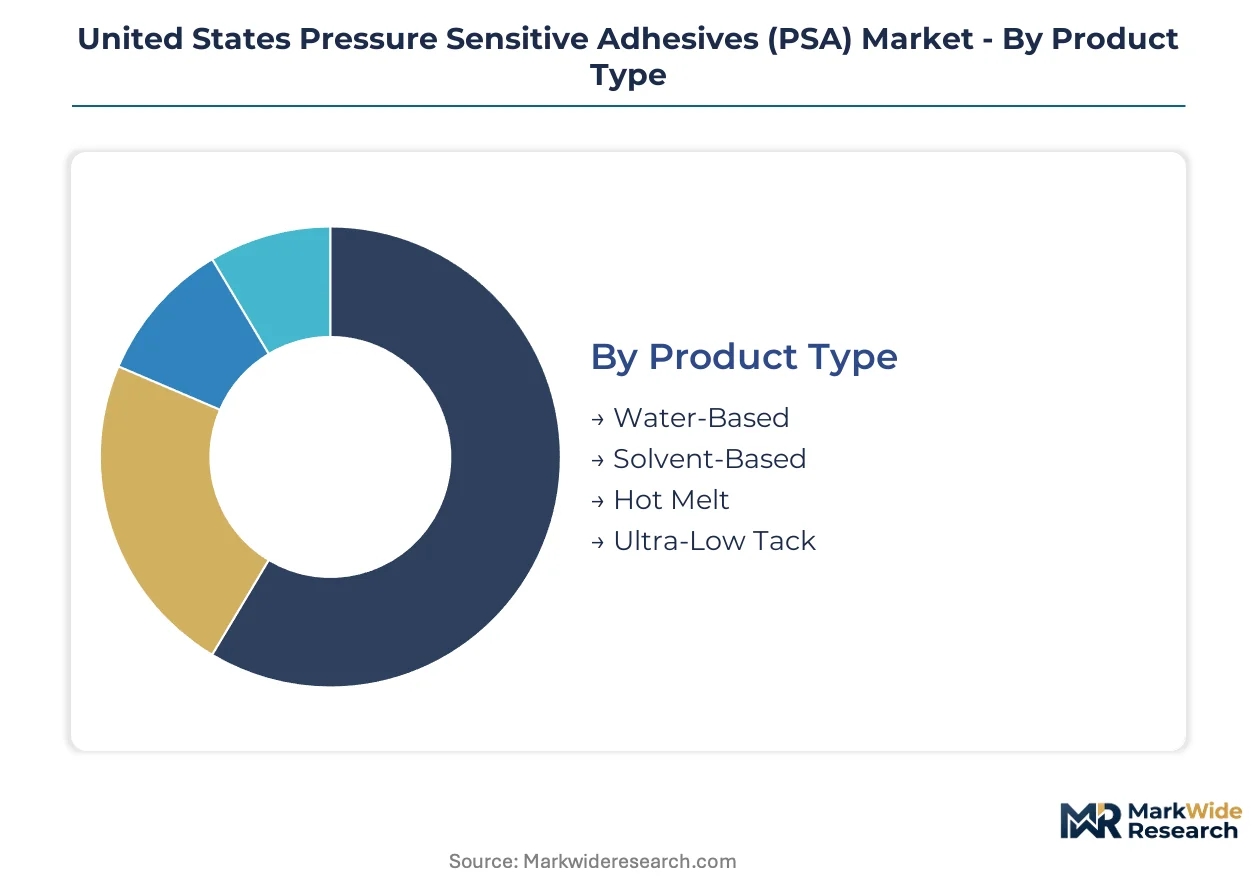
Segmentation in the United States PSA market reveals how formulation chemistry, application requirements, and end-user specifications create distinct competitive arenas with diverging margin profiles and qualification timelines. Understanding these divides exposes where capital deployment yields the highest returns.
Product Type:
Cycle times vary dramatically across formulation platforms, with hot melt systems turning inventory weekly while medical-grade solvent acrylics sit in qualification queues for months.
- Water-Based:Acrylic emulsion polymers suspended in aqueous carriers achieve EPA VOC compliance without carbon recovery infrastructure. Detroit automotive interiors and Chicago packaging converters drive volume as OSHA workplace exposure standards tighten.
- Solvent-Based:Solution acrylics and rubber-resin systems deliver superior shear resistance and temperature performance for structural bonding. Regulatory pressure from EPA National Emission Standards for Hazardous Air Pollutants is constraining capacity expansion in the Ohio River Valley.
- Hot Melt:Thermoplastic EVA and polyolefin formulations enable sub-second set speeds on high-speed packaging lines.
- Ultra-Low Tack:Specialty removable adhesives for temporary surface protection and repositionable graphics.
Water-based systems anchor the volume base while hot melt gains share at the steepest rate.
Application:
Margin structures stratify sharply across use cases, with medical and electronics applications commanding multiples of industrial tape pricing due to certification barriers.
- Labels:Film and paper facestock adhesives for beverage, logistics, and retail shelf applications. Avery Dennison's film casting expertise concentrates demand in California and Wisconsin label converting corridors.
- Tapes:Industrial masking, electrical insulation, and consumer packaging tapes represent the highest volume outlet.
- Medical:ISO 10993 biocompatibility testing and FDA device master file requirements create formulation lock-in for wound care and wearable sensor attachment. Certification cycles exceeding thirty-six months extend product lifecycles and protect pricing.
- Packaging:Corrugated box sealing and flexible food packaging adhesives compete primarily on throughput and applied cost per thousand units.
Tapes generate the highest absolute volume while medical applications expand most quickly.
Technology:
Process intensity separates segments, with composite bonding requiring capital-heavy automation while surface modification operates at laboratory scale.
- Surface Modification:Corona, plasma, and primer treatments that prepare substrates for adhesion. Electronics miniaturization in Arizona and Texas semiconductor packaging facilities drives precision requirements.
- Film Casting:Continuous web processing of adhesive-coated films for label and tape backings. Thin-gauge capability distinguishes suppliers serving beverage and logistics customers.
- Coating:Slot-die, gravure, and reverse-roll application systems for converting bulk adhesive into finished tape and label constructions.
- Composite:Multi-layer laminations combining adhesives with reinforcing films for automotive structural applications.
Coating technology anchors the volume base while composite systems climb the fastest.
End User:
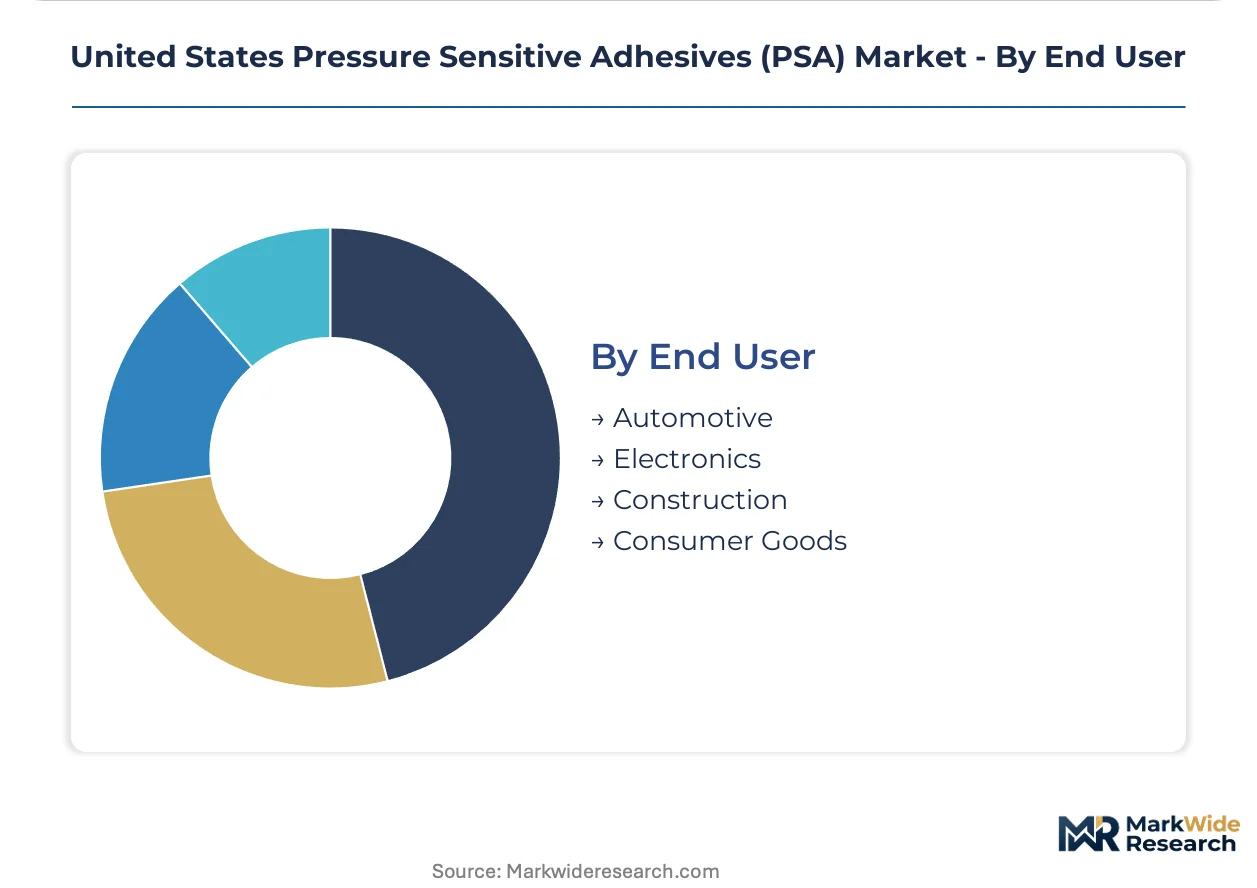
Customer concentration patterns differ markedly, with automotive procurement consolidating around Detroit while electronics demand fragments across multiple design centers.
- Automotive:Lightweighting programs in Michigan and Ohio are pulling PSA volume into carbon-fiber and aluminum joining applications. Ford and Stellantis assembly plants now bundle adhesive procurement with equipment service contracts.
- Electronics:Die-attach, flexible circuit bonding, and semiconductor packaging applications command pricing premiums over industrial grades.
- Construction:Weatherproofing membranes, flooring installation, and HVAC sealing tapes compete on durability specifications and contractor brand loyalty.
- Consumer Goods:Stationery, DIY mounting, and personal care products face price pressure from private label competition.
Automotive anchors the volume base while electronics gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Over sixty percent of domestic PSA volume flows through the Great Lakes manufacturing corridor, where automotive OEMs and tier suppliers cluster around Detroit, Chicago, and Cleveland. EPA VOC regulations and OSHA workplace exposure standards are tightening formulation requirements for solvent-based systems across this concentrated geography.
Great Lakes Manufacturing Corridor
Automotive lightweighting programs in Michigan and Ohio are pulling PSA volume into carbon-fiber and aluminum joining applications. EPA National Emission Standards for Hazardous Air Pollutants amendments mandate solvent recovery systems for manufacturers operating near the Ohio River Valley. Detroit, Cleveland, and Chicago host the densest concentrations of Ford and Stellantis assembly plants bundling adhesive procurement with equipment service contracts.
Southeast Industrial Belt
Packaging converters and label manufacturers in Georgia, North Carolina, and Tennessee drive water-based acrylic demand for beverage and logistics applications. OSHA Permissible Exposure Limits enforcement is accelerating facility upgrades across this region. Atlanta and Charlotte serve as distribution hubs where Avery Dennison's film casting expertise concentrates label converting activity.
Texas and Southwest
Electronics miniaturization for semiconductor packaging creates die-attach and flexible circuit bonding demand in Arizona and Texas facilities. The region's relatively lighter regulatory burden attracts formulation investments from manufacturers exiting solvent-based production elsewhere. Phoenix and Austin design centers fragment electronics demand across multiple semiconductor packaging facilities.
California and Pacific Coast
Pending extended producer responsibility legislation in Sacramento creates first-mover advantage for adhesive suppliers with recyclable film and liner technologies. FDA biocompatibility requirements for ISO 10993 compliance concentrate medical-grade PSA development in Southern California. Los Angeles and San Diego host wound care and wearable sensor attachment specialists facing thirty-six-month certification cycles.
Northeast Corridor
Construction weatherproofing and HVAC sealing tape demand concentrates in New York, Pennsylvania, and New England markets. State-level extended producer responsibility legislation in New York could reshape packaging adhesive take-back requirements. Boston and Philadelphia anchor specialty chemical R&D activity for silicone hybrid formulations targeting outdoor signage applications.
United States Pressure Sensitive Adhesives (PSA) Market Competitive Landscape
Integrated chemical conglomerates and specialized adhesive formulators split the market between scale-driven supply security and application-specific technical service. The vendor base concentrates around three tiers: multinational material science platforms with captive polymer supply, mid-sized formulators with regional coating infrastructure, and niche specialists holding FDA master files for medical grades. Dominant competitive moves include backward integration into acrylic monomer production and multi-year service bundling with automated dispensing equipment procurement.
Among German-origin chemical platforms, Henkel AG & Co. KGaA and Wacker Chemie AG exemplify the integrated archetype with upstream control over polymer building blocks. 3M and Avery Dennison Corporation anchor the specialty tier, representing U.S.-based material science companies with differentiated tape and label platforms. These five entities occupy positions across automotive structural bonding, electronics miniaturization, and medical skin-contact applications.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| Illinois Tool Works |
| 3M |
| Sika AG |
| Arkema |
| Avery Dennison Corporation |
| Dow |
| Wacker Chemie AG |
| H.B. Fuller Company |
| Others |
Value Network & Pricing Analysis
Petrochemical feedstock volatility determines both the pricing tier spreads and supply chain shape across the United States Pressure Sensitive Adhesives market, compressing margins for formulation houses without backward integration while forcing geographic consolidation around captive monomer sources.
Pricing Analysis
EPA National Emission Standards for Hazardous Air Pollutants dictates the pricing tier structure across the United States PSA market, separating medical-grade solvent acrylics with FDA master file protection from commodity water-based emulsions competing on applied cost. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale, with wound care and wearable sensor applications commanding multiples over industrial tape pricing. Cost compression in the mid-tier water-based segment is intensifying because OSHA workplace exposure standards are accelerating facility upgrades. Packaging converters in the Southeast Industrial Belt exhibit the highest price sensitivity, while automotive OEMs bundling adhesive procurement with equipment service contracts show the lowest.
Supply Chain Analysis
Export-control restrictions on advanced silicone polymer synthesis technology limit flows from Wacker Chemie AG's German facilities, constraining domestic access to weathering-resistant hybrid formulations for photovoltaic and outdoor signage applications. Acrylic monomer and tackifier resin supply concentrates in Texas and Louisiana petrochemical corridors, with finished adhesive production anchored in the Great Lakes manufacturing cluster. Raw material dependencies on crude oil derivatives, natural rubber, and specialty tackifier resins expose margins to commodity price swings. Single-source vulnerability around FDA-qualified medical-grade production creates qualification bottlenecks. Distribution runs through tiered converter networks where Avery Dennison and 3M maintain direct channel control.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States Pressure Sensitive Adhesives market operates as a defensive-moat story where FDA biocompatibility certification and thirty-six-month qualification timelines create formulation lock-in that protects incumbent pricing power.
For Market Incumbents: Harden regulatory entrenchment by deepening FDA master file portfolios for ISO 10993-compliant medical grades before biocompatibility certification cycles extend further. Expand backward integration into acrylic monomer production in Texas and Louisiana to neutralize petrochemical feedstock volatility threatening margin stability. Channel control through multi-year preventive maintenance contracts for automated dispensing equipment locks out substitute technology from automotive tier suppliers. For New Entrants and Emerging Players: Electronics miniaturization applications in Arizona and Texas semiconductor packaging facilities represent the most penetrable entry point, as die-attach and flexible circuit bonding demand fragments across multiple design centers with pricing premiums over industrial grades. California extended producer responsibility legislation for packaging take-back creates first-mover advantage for adhesive suppliers with recyclable film and liner technologies. A go-to-market angle targeting sustainability-positioned beverage and logistics customers with verified recyclable constructions bypasses entrenched label converting relationships. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors mid-sized formulators with regional coating infrastructure and captive FDA master files. Long-term viability rests on regulatory entrenchment rather than technology disruption, given formulation lock-in dynamics. Acquisition targets should display qualified supplier status for medical skin-contact applications. The signal to watch as inflection indicator is state-level extended producer responsibility legislation passage in New York, which would reshape packaging adhesive cost allocation and accelerate vendor consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Monomer Production | Captive supply of petrochemical feedstock neutralizes margin compression from crude oil derivative volatility. |
| FDA Master File Expansion for Medical Grades | ISO 10993 biocompatibility certification creates thirty-six-month formulation lock-in protecting pricing power. |
| Equipment Service Contract Bundling | Ford and Stellantis procurement patterns favor multi-year adhesive-plus-maintenance agreements reducing qualification overhead. |
| Recyclable Film and Liner Technology Development | California extended producer responsibility legislation creates first-mover advantage for verified sustainable constructions. |
| Silicone Hybrid Formulation Platform | Convergence of silicone weathering resistance with acrylic processability opens photovoltaic module assembly applications. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across the United States Pressure Sensitive Adhesives value chain, including formulation chemists at mid-sized manufacturers, procurement leads at Detroit automotive tier suppliers, technical R&D directors at tape and label converters, and regulatory affairs specialists managing FDA device master files. Secondary validation drew from EPA National Emission Standards for Hazardous Air Pollutants amendments, OSHA Permissible Exposure Limits enforcement records, SEC 10-K filings from listed chemical conglomerates, and American Chemistry Council industry statistics. Bottom-up volume estimates from coating line capacity and top-down demand aggregation from end-use consumption patterns were triangulated to cross-check outputs.
Calibration against historical acrylic monomer price cycles and automotive production volumes anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include formulation chemistry, application requirements, technology process intensity, and end-user industry concentration. CAGRs were derived from regression analysis of volume trends against regulatory enforcement timelines and OEM lightweighting program announcements. Industry-specific forecast inputs incorporated EPA VOC compliance investment cycles and FDA biocompatibility certification queue lengths.
Practitioners should monitor EPA enforcement intensity and state-level extended producer responsibility legislative progress for early signals of supply chain restructuring. Forecasts reflect assumptions around regulatory timeline stability and automotive lightweighting program continuity. Material shifts in petrochemical feedstock cost trajectories or FDA medical device review timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Plastic Adhesives Market
Adhesives & Sealants
Mexico Adhesives Market
Adhesives & Sealants
Two Component Adhesive Market
Adhesives & Sealants
UV-Curable Adhesives Market
Adhesives & Sealants
Tile and Stone Adhesive Market
Adhesives & Sealants
Global Bone Glue Market
Adhesives & Sealants
Laminating Adhesives Market
Adhesives & Sealants
Wood Adhesives and Binders Market
Adhesives & Sealants
Europe Automotive Adhesives and Sealants Market
Adhesives & Sealants
Structural Adhesives Market
Adhesives & Sealants
North America Bone Glue Market
Adhesives & Sealants
North America Laminating Adhesives Market
Adhesives & Sealants
North America Human Fibrin Glue Market
Adhesives & Sealants
Ethylene Butyl Acrylate Market
Adhesives & Sealants
Europe Human Fibrin Glue Market
Adhesives & Sealants
Middle-East and Africa Acrylic Adhesives Market