
 Global Human Fibrin Glue Market | 2026-2036
Global Human Fibrin Glue Market Size, Share, and Industry Trends Forecast 2026-2036
Global Human Fibrin Glue Market Foresight
Aftermarket service revenue for fibrin glue application systems is fragmenting as device makers and plasma fractionators dispute ownership of training, maintenance, and consumable replenishment contracts. Baxter International Inc. leverages its integrated hospital supply chain to bundle glue cartridges with applicator servicing, while Grifols S.A. anchors its position through captive plasma supply and in-house fractionation capacity. Takeda Pharmaceutical Company Limited competes by extending its biologics distribution network into emerging markets where surgical infrastructure is expanding.
Human fibrin glue is a biological adhesive composed of concentrated human fibrinogen and thrombin, typically derived from pooled plasma and stabilized with aprotinin or tranexamic acid to prevent premature degradation; it polymerizes upon mixing to form a clot-like matrix that adheres tissue surfaces and promotes hemostasis during operative procedures. Freeze-dried formulations dominate hospital procurement due to extended shelf life and cold-chain flexibility, while spray delivery systems represent the fastest-expanding segment as laparoscopic and minimally invasive surgery protocols standardize aerosolized application techniques. Surgical hemostasis remains the largest application category by volume, though tissue sealing in thoracic and hepatic procedures is capturing disproportionate margin growth as complexity premiums expand.
The FDA regulates human fibrin glue as a combination biologic-device product requiring BLA or PMA pathways, while the EU MDR mandates notified body oversight and enhanced clinical evidence for plasma-derived surgical sealants. China's NMPA enforces batch-release testing and traceability requirements that limit import velocity but incentivize local plasma collection partnerships. Stakeholders must monitor evolving MDR transition timelines and plasma sourcing constraints as regulatory stringency and raw material access become the decisive variables for capacity planning and geographic prioritization.
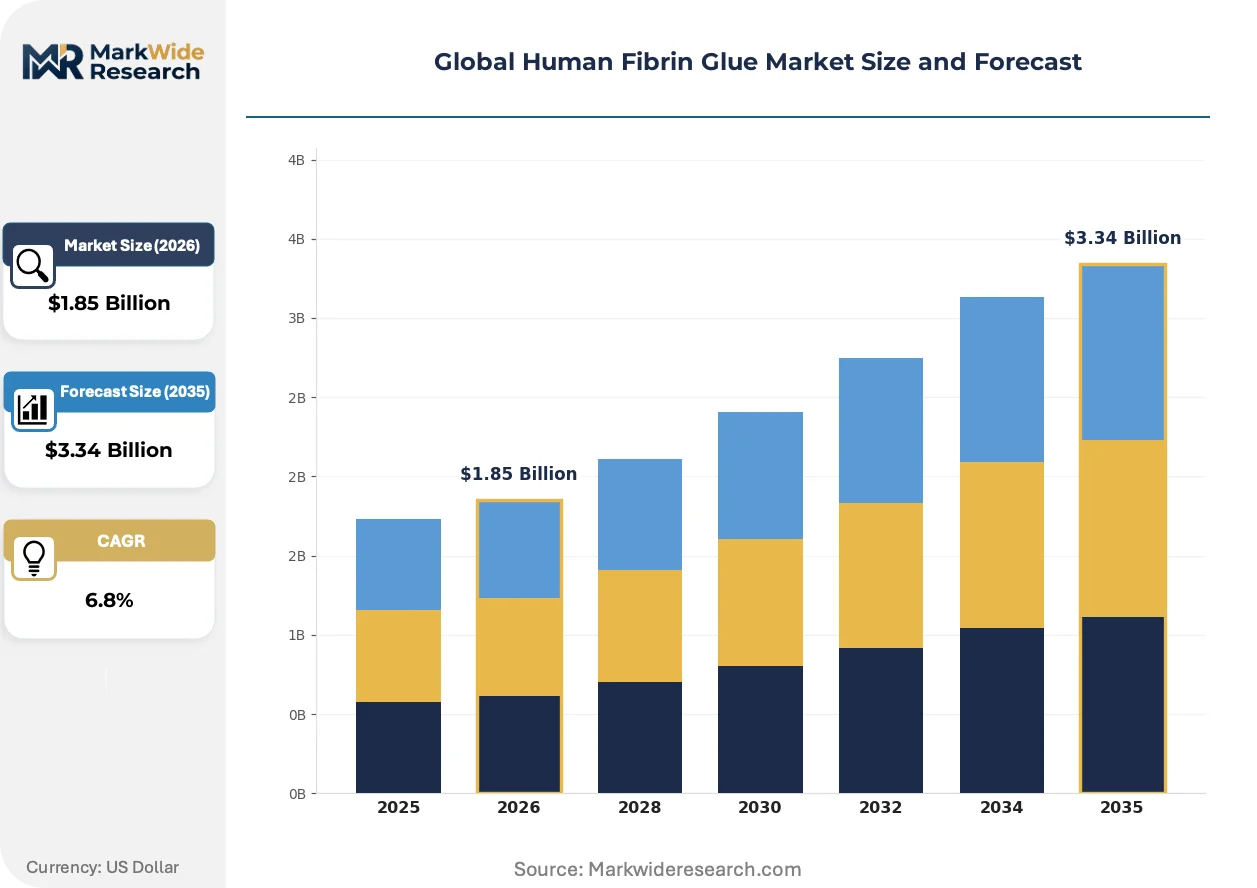
Market Dynamics
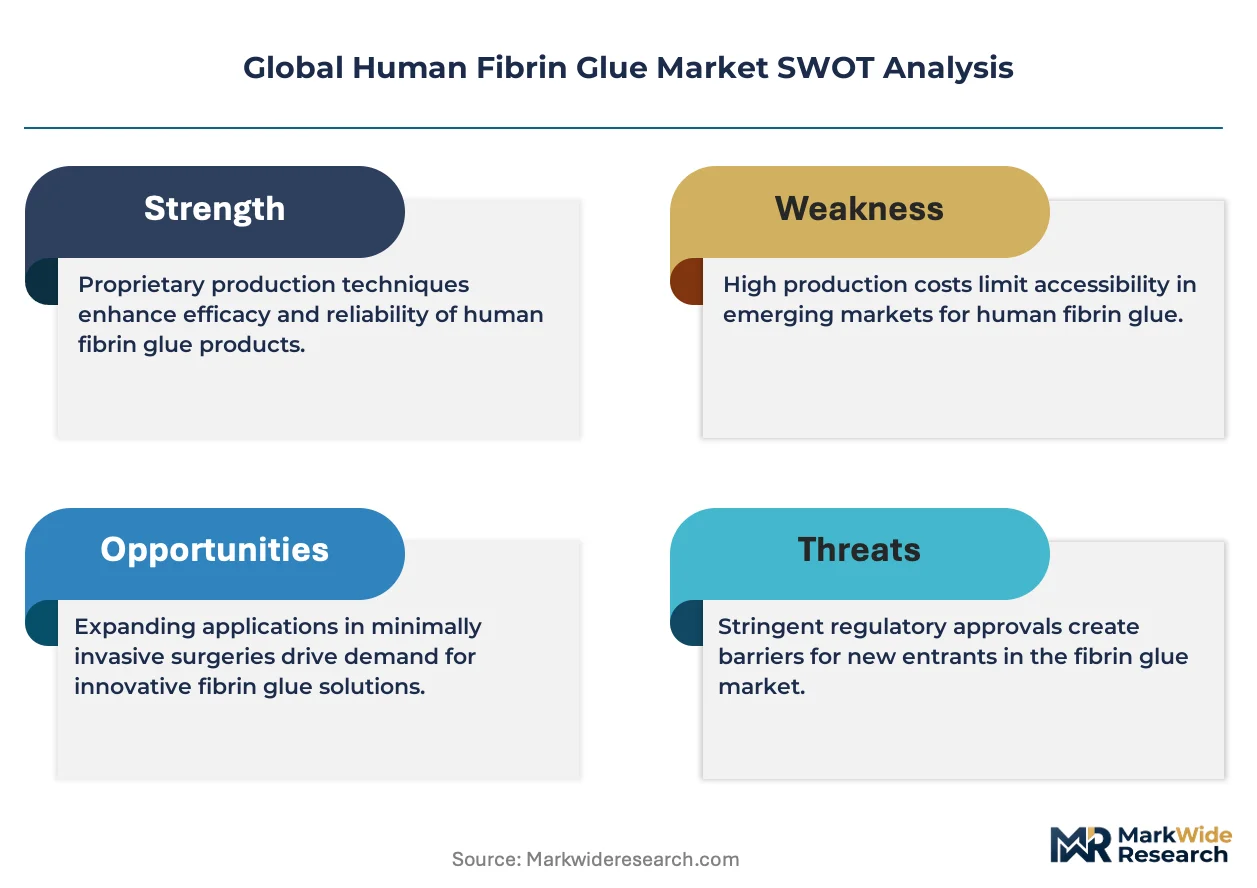
EU MDR compliance timelines and plasma fractionation capacity constraints are tightening supply-side discipline, forcing manufacturers to prioritize geographies with established cold-chain infrastructure and captive plasma sourcing.
Growth Catalysts
- Cardiovascular procedure volumes:Aging demographics in Germany, the United States, and Japan are expanding the addressable patient base for coronary artery bypass grafting and valve replacement surgeries requiring hemostatic sealants.
- EU MDR Article 120 transition extensions:Staggered certification deadlines through 2027-2028 are creating temporary competitive windows for manufacturers with early notified body approvals.
- Spray applicator miniaturization:Laparoscopic surgical protocols are standardizing aerosolized delivery systems that reduce operative time and improve tissue coverage precision.
Market Restraints
- Plasma supply concentration:United States plasma collection centers supply over 70% of global raw material, exposing fractionators to single- geography sourcing risk and tariff exposure.
- Freeze-drying capex intensity:Lyophilization equipment and cleanroom infrastructure require substantial capital deployment, limiting new entrant viability.
- Synthetic sealant substitution:Polyethylene glycol-based adhesives and cyanoacrylate formulations are capturing price-sensitive segments in outpatient settings.
Strategic Opportunities
- China NMPA localization partnerships:Domestic plasma collection joint ventures with state-owned blood product centers can bypass import batch-release bottlenecks.
- Tissue engineering convergence:Fibrin scaffold matrices combined with mesenchymal stem cell delivery are opening regenerative medicine applications beyond hemostasis.
- Direct-to-hospital digital procurement:E-procurement platforms are disintermediating traditional distributor markups in India's tier-2 and tier-3 hospital networks.
Industry Challenges
- Biologics-device combination product expertise:BLA-PMA pathway navigation requires specialized regulatory affairs talent that remains scarce outside established plasma fractionators.
- Cold-chain integrity failures:Temperature excursion during last-mile delivery to rural surgical centers compromises product efficacy and triggers batch recalls.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Human Fibrin Glue Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Freeze-Dried, Liquid, Spray, Patch, Injectable Application: Surgical Hemostasis, Wound Closure, Tissue Sealing, Orthopedic Procedures, Dental Surgery End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Research Institutes Delivery Mode: Topical Application, Injection, Spray Application, Patch Application |
| Companies Covered | Grifols S.A., Takeda Pharmaceutical Company Limited, Baxter International Inc., Hualan Biological Engineering Inc., Shanghai RAAS Blood Products Co. Ltd, Johnson & Johnson (Ethicon), Vivostat A/S, CryoLife, Inc., CSL Behring, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Human Fibrin Glue Market Shifts & Advancements
Product formulation and delivery system architectures are converging around shelf-life extension and point-of-care reconstitution, while regulatory frameworks and procurement modalities undergo parallel restructuring.
Lyophilized fibrinogen-thrombin kits with room-temperature stability are collapsing the cold-chain infrastructure requirements that historically limited distribution to tertiary surgical centers. Rural hospitals in India and Brazil are adopting these formulations to bypass refrigeration dependency. The technology is collapsing the historical urban-rural access gap in emerging market surgical care.
EU MDR Annex XVI classification expansions are redefining surgical sealants as Class III implantable devices requiring clinical follow-up data. Manufacturers must now generate post-market surveillance evidence that was previously exempt. Cardiac surgery applications face the steepest compliance burden due to extended patient monitoring obligations.
Hospital value analysis committees are consolidating hemostasis product selection authority away from individual surgeons toward centralized pharmacy and procurement functions. Spray delivery systems with quantified blood-loss reduction data are displacing conventional flowable formats in United States IDN contract negotiations. Germany's university hospital networks are piloting this consolidated sourcing model most aggressively.
Global Human Fibrin Glue Market Segmentation
Segmentation in human fibrin glue markets reveals how formulation chemistry, delivery mechanics, and care setting economics create distinct competitive arenas. Manufacturers configure R&D and commercial resources differently across these dimensions.
Product Type:
Mature formats with established reimbursement dominate procurement contracts, while emerging formats target point-of-care flexibility and cold-chain reduction.
- Freeze-Dried:Lyophilized fibrinogen-thrombin complexes stabilized with aprotinin deliver extended shelf stability without continuous refrigeration. Hospital systems in Germany and the United States prioritize this format for centralized pharmacy inventory management and reduced wastage from temperature excursions.
- Spray:Aerosolized delivery systems atomize fibrin components through laparoscopic ports or open-field applicators. Demand concentrates in thoracic and hepatic surgery suites where tissue coverage precision reduces operative time; spray configurations are displacing flowable formats in United States IDN tenders.
- Liquid:Pre-mixed solutions requiring frozen storage and rapid thawing protocols.
- Patch:Solid matrix formats impregnated with fibrin components for mechanical compression applications.
- Injectable:Low-viscosity formulations for subcutaneous and intra-articular delivery.
Freeze-Dried handles the majority of throughput; Spray is the fastest mover on share.
Application:
Volume concentration follows cardiac and orthopedic procedure scheduling, with margin concentration shifting toward complex tissue reconstruction.
- Surgical Hemostasis:Intraoperative bleeding control during coronary artery bypass grafting, valve replacement, and major vessel reconstruction. Cardiac surgery departments in Japan and the United States drive procurement volume through standardized bypass protocols that mandate fibrin sealant application.
- Tissue Sealing:Air-tight and fluid-tight closure of pulmonary resection margins and hepatic transection surfaces. Thoracic surgery units in Germany's university hospital networks capture disproportionate margin premiums for complexity-adjusted procedures.
- Wound Closure:External tissue approximation in trauma and dermatological reconstruction.
- Orthopedic Procedures:Cementless implant fixation and meniscal repair augmentation.
- Dental Surgery:Socket preservation and sinus lift membrane stabilization.
Surgical Hemostasis commands the largest procedure volume; Tissue Sealing is climbing the fastest on complexity-adjusted revenue per case.
End User:
Procurement authority concentration and reimbursement scale separate institutional tiers.
- Hospitals:Tertiary medical centers with cardiac surgery, transplant, and trauma capabilities. Centralized value analysis committees in United States integrated delivery networks and Germany's university hospital consortia negotiate multi-year fibrin glue contracts with bundled applicator servicing.
- Ambulatory Surgical Centers:Same-day procedure facilities performing arthroscopy, endoscopy, and minor orthopedic interventions. India's tier-2 and tier-3 urban centers are expanding ASC capacity for cost-sensitive hemostasis applications.
- Specialty Clinics:Dermatological and dental practices with limited surgical throughput.
- Research Institutes:Tissue engineering and regenerative medicine laboratories utilizing fibrin scaffolds for mesenchymal stem cell delivery.
Hospitals absorb the dominant procurement share; Ambulatory Surgical Centers are gaining share fastest as same-day surgery protocols expand.
Delivery Mode:
Instrumentation compatibility and operative workflow integration determine format selection.
- Spray Application:Pneumatic or gas-propelled aerosolization through specialized laparoscopic ports. Minimally invasive surgery adoption in China's tier-1 city hospital networks is standardizing spray protocols for reduced blood loss documentation.
- Topical Application:Direct flowable or droplet placement onto exposed tissue surfaces. Open cardiac and trauma procedures in Brazil's public hospital system rely on topical formats for immediate hemostasis without capital equipment requirements.
- Injection:Needle-based delivery for submucosal or intra-articular deposition.
- Patch Application:Mechanical compression with solid matrix adherence.
Topical Application retains the largest installed base; Spray Application shows the steepest expansion trajectory as laparoscopic protocols proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies: Germany and the United States prioritize centralized hospital procurement of freeze-dried formulations, while China and India concentrate demand in tier-1 city surgical networks adopting spray delivery systems for minimally invasive protocols.
United States
Cardiovascular procedure volumes at Cleveland Clinic and Mayo Clinic drive concentrated demand for surgical hemostasis products. FDA BLA-PMA pathway requirements for combination biologic-device products enforce stringent clinical evidence standards that favor established plasma fractionators. Texas Medical Center in Houston anchors the largest cluster of cardiac surgery programs standardizing fibrin sealant protocols.
Germany
University hospital networks in Bavaria and North Rhine-Westphalia pilot consolidated value analysis committees for hemostasis procurement. EU MDR notified body oversight and Annex XVI classification expansions impose extended clinical follow-up obligations on manufacturers. Berlin-Brandenburg's Charité hospital system leads European adoption of spray applicator miniaturization for thoracic procedures.
China
Shanghai and Beijing tier-1 hospital networks expand laparoscopic surgery capacity requiring aerosolized delivery systems. NMPA batch-release testing and plasma traceability requirements incentivize local collection partnerships with state-owned blood product centers. Yangtze River Delta medical clusters pioneer direct-to-hospital digital procurement platforms disintermediating traditional distributor networks.
Japan
Aging demographics in Tokyo and Osaka metropolitan areas expand coronary artery bypass grafting volumes requiring standardized hemostatic sealant application. PMDA regulatory frameworks align with international standards while maintaining distinct pharmacovigilance reporting requirements. Kansai region university hospitals concentrate tissue sealing expertise in hepatic and thoracic surgery subspecialties.
India
Tier-2 and tier-3 urban centers in Maharashtra and Gujarat expand ambulatory surgical center capacity for cost-sensitive hemostasis applications. CDSCO import regulations and cold-chain infrastructure gaps limit freeze-dried formulation distribution to tertiary metropolitan facilities. Mumbai's hospital networks pilot room-temperature stable lyophilized kits to bypass rural refrigeration dependency.
Global Human Fibrin Glue Market Competitive Landscape
Capability concentration sits with integrated plasma fractionators possessing captive sourcing and in-house lyophilization infrastructure; scale advantage sits with diversified medical technology conglomerates leveraging established hospital supply chain relationships. The market structure tiers around three archetypes: plasma-derived biologics specialists with backward integration into collection networks, diversified surgical device manufacturers bundling consumables with capital equipment, and regional blood product processors serving protected domestic markets. Dominant competitive moves include strategic partnerships for plasma supply security and geographic expansion through regulatory localization.
Within the plasma fractionation tier, Grifols S.A. and CSL Behring exemplify captive supply chain control from collection through finished product, while Baxter International Inc. occupies a position bridging device integration with biologics distribution. Takeda Pharmaceutical Company Limited represents the diversified pharmaceutical archetype extending biologics networks into surgical adjacencies. Among Asia-Pacific-based processors, Hualan Biological Engineering Inc. and Shanghai RAAS Blood Products Co. Ltd anchor regional supply positions serving NMPA-regulated domestic demand.
| Leading Market Players |
|---|
| Grifols S.A. |
| Takeda Pharmaceutical Company Limited |
| Baxter International Inc. |
| Hualan Biological Engineering Inc. |
| Shanghai RAAS Blood Products Co. Ltd |
| Johnson & Johnson (Ethicon) |
| Vivostat A/S |
| CryoLife, Inc. |
| CSL Behring |
| Others |
Supply & Pricing Matrix
United States plasma collection centers supplying over 70% of global raw material concentrate pricing power with integrated fractionators, while hospital value analysis committees in Germany and the United States extract concessions through multi-year contract consolidation.
Pricing Analysis
Long-term offtake agreements dominate hospital procurement, with three-tier pricing structure across premium, standard, and economy levels reflecting certification grade and volume scale. Price differentiation hinges on FDA BLA-PMA pathway completion and bundled applicator servicing contracts. Cost compression in standard-tier freeze-dried formulations is intensifying because synthetic sealant substitution pressures outpatient segments. Ambulatory surgical centers in India exhibit highest price sensitivity, while cardiac surgery departments in Japan and the United States accept premium positioning for complexity-adjusted tissue sealing applications.
Supply Chain Analysis
Contract manufacturing concentration sits with CSL Behring's Kankakee facility, Grifols S.A.'s Barcelona complex, and Baxter International Inc.'s Los Angeles operations holding lyophilization capacity. Raw material dependencies center on source plasma, aprotinin stabilizers, and specialized applicator polymers. Single-source vulnerability concentrates in United States collection center networks, exposing fractionators to tariff exposure and geographic sourcing risk. Distribution runs through plasma fractionator direct sales forces and GPO-negotiated hospital contracts, with emerging digital procurement platforms in China and India disintermediating traditional distributor markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR Annex XVI classification expansions and spray applicator miniaturization are disrupting competitive positioning, creating temporary windows for manufacturers with early notified body approvals and aerosolized delivery expertise.
For Market Incumbents: Insulate plasma supply security through captive collection network expansion and backward integration into state-owned blood product partnerships in China. Prioritize lyophilization capacity additions in Germany and the United States to defend against synthetic sealant substitution in price-sensitive outpatient tiers. Lock hospital value analysis committees through multi-year contracts bundling freeze-dried cartridges with spray applicator servicing and training protocols. For New Entrants and Emerging Players: Build out room-temperature stable formulation capabilities to bypass cold-chain infrastructure gaps in India's tier-2 and tier-3 urban centers. Target tissue engineering convergence applications combining fibrin scaffold matrices with mesenchymal stem cell delivery, where regulatory pathways remain less congested than surgical hemostasis. Pursue direct-to-hospital digital procurement partnerships in China's Yangtze River Delta medical clusters to circumvent established distributor relationships. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed surgical device manufacturers lacking captive plasma supply, presenting consolidation targets for integrated fractionators seeking spray delivery system capabilities. Five-to-ten year viability favors backward-integrated specialists with notified body MDR approvals and established hospital GPO contracts. Monitor EU MDR transition timeline extensions and NMPA localization partnership announcements as inflection indicators for competitive access shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Plasma Collection Joint Venture | CSL Behring's partnership with Chinese state-owned blood centers bypasses NMPA batch-release bottlenecks. |
| Spray Applicator Miniaturization | Baxter International's laparoscopic port compatibility reduces operative time in thoracic procedures at Charité Berlin. |
| Room-Temperature Stability Formulation | Grifols S.A.'s lyophilized kits collapse cold-chain requirements for rural Indian hospital networks. |
| EU MDR Notified Body Engagement | Early Annex XVI classification compliance secures competitive windows through staggered 2027-2028 deadlines. |
| Direct-to-Hospital Digital Procurement | Takeda's platform deployment in Maharashtra ASCs disintermediates traditional distributor markups. |
Research Methodology
A spread of perspectives from plasma fractionation executives, hospital purchasing committee chairs, regulatory affairs specialists at notified bodies, and GPO contracts managers converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) and BLA filings, EMA MDR submission databases, NMPA batch-release records, and hospital procurement contract disclosures. Bottom-up procedure volume modeling and top-down plasma fractionation capacity analysis were triangulated to anchor demand-supply balances.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include formulation chemistry, delivery mechanism, application complexity tier, and regional regulatory cluster. CAGRs were derived from procedure volume elasticity analysis and pricing trajectory assessment. Industry-specific forecast inputs incorporated EU MDR transition timeline assumptions and plasma collection center capacity expansion schedules.
The forecast holds incumbent behavior within observed patterns; aggressive moves by synthetic sealant manufacturers or state-backed Chinese fractionators would shift outcomes. Quarterly review of notified body approval backlogs, NMPA partnership announcements, and hospital value analysis committee consolidation trends is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Pvc Based Adhesive Market
Adhesives & Sealants
Global Construction Silicone Sealants Market
Adhesives & Sealants
Europe Acrylic Adhesives Market
Adhesives & Sealants
Adhesive Primer Market
Adhesives & Sealants
Global Lithium Ion Battery Binders Market
Adhesives & Sealants
Adhesives and Sealants Market
Adhesives & Sealants
Chlorinated Polyolefin Adhesion Promoter Market
Adhesives & Sealants
North America Acrylic Adhesives Market
Adhesives & Sealants
Fabric Adhesive Market
Adhesives & Sealants
Global Medical Adhesives and Sealants Market
Adhesives & Sealants
North America Polyurethane (PU) Hot-Melt Adhesives Market
Adhesives & Sealants
Southeast Asia Adhesives and Sealants Market
Adhesives & Sealants
Thailand Sealants Market
Adhesives & Sealants
High Temperature Adhesives and Sealants Market
Adhesives & Sealants
Tissue Sealants and Tissue Adhesive Market
Adhesives & Sealants
Middle East and Africa Human Fibrin Glue Market