
 Electric Vehicle Adhesives and Sealants Market | 2026-2036
Electric Vehicle Adhesives and Sealants Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Vehicle Adhesives and Sealants Market Insights
Automotive-grade thermal conductivity specifications are unwinding legacy adhesive portfolios across the electric vehicle supply chain. Henkel AG & Co. KGaA leverages its European manufacturing footprint to dominate OEM qualification programs. Sika AG anchors its position through specialized polyurethane systems for battery module encapsulation. Dow competes on silicone chemistry leadership for high-voltage insulation applications.
Electric vehicle adhesives and sealants comprise formulated polymer systems—typically epoxy, polyurethane, or silicone base chemistries with fillers such as alumina or boron nitride for thermal management—designed to bond dissimilar substrates, seal against moisture ingress, and dissipate heat in electrified powertrains. These materials replace mechanical fasteners to reduce mass, improve crash performance, and enable automated assembly of battery packs, electric motors, and lightweight body structures. Polyurethane formulations lead volume consumption due to their flexibility and impact resistance in structural bonding applications, while silicone segments capture premium margin pools where thermal stability above 150°C is non-negotiable. Two-part adhesive technology is displacing one-part systems in battery assembly as OEMs demand controlled cure profiles for high-throughput production lines.
EPA vehicle emissions standards, EU REACH chemical registration requirements, and China's GB standards for new energy vehicle safety collectively mandate flame-retardant formulations, restricted substance compliance, and documented material traceability throughout the adhesive supply chain. These regulatory layers force reformulation cycles that favor suppliers with in-house testing and certification capabilities over commodity distributors. Stakeholders must monitor evolving battery safety test protocols and pre-qualify alternative chemistries before incumbent supply agreements expire.
Market Dynamics
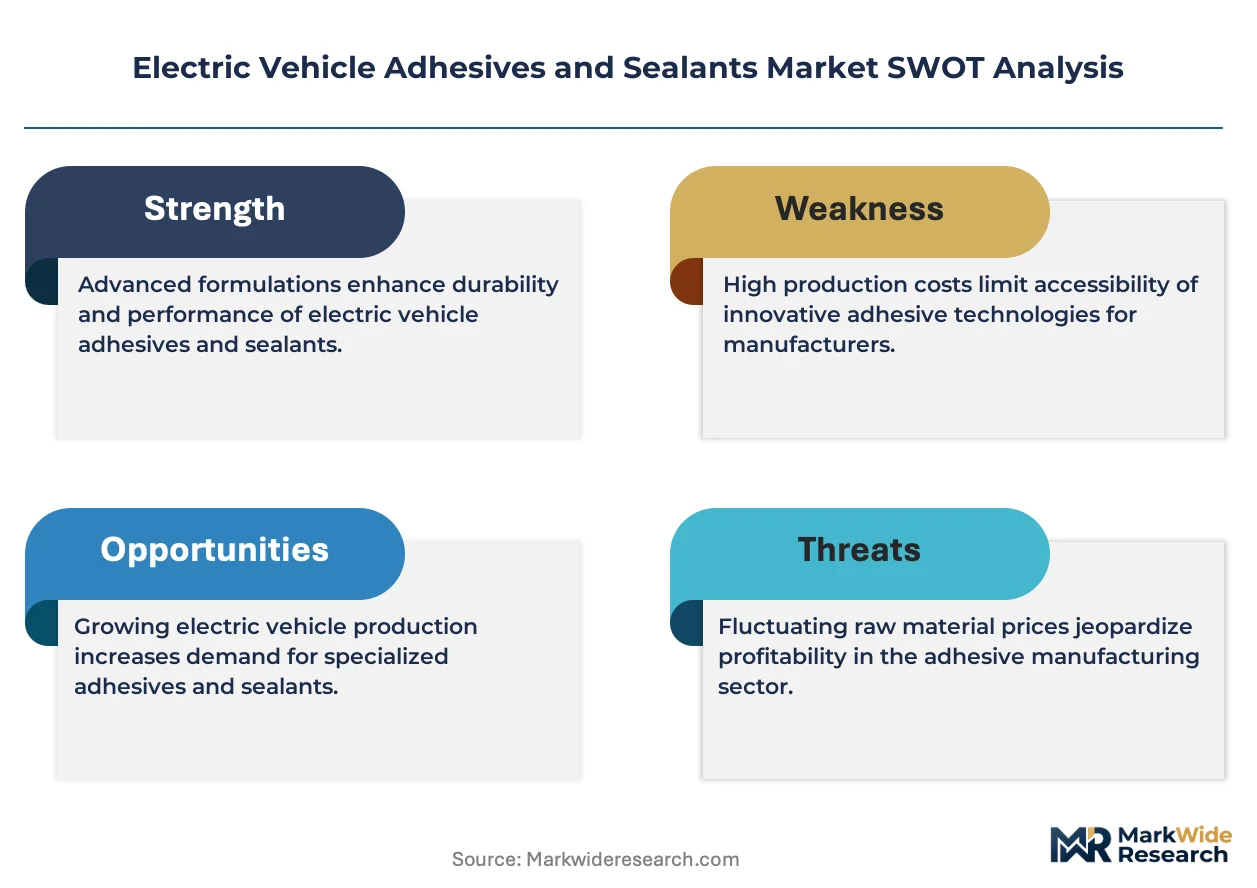
Battery pack thermal management requirements are compressing adhesive qualification timelines from 24 months to under 12 months as OEMs rush platform launches. This acceleration privileges suppliers with captive testing infrastructure and pre-certified material libraries over commodity distributors.
Growth Catalysts
- EU battery passport regulations:Material traceability mandates under ECHA frameworks are forcing automakers to document adhesive composition chains, creating pull for certified suppliers with batch-level tracking systems.
- Structural bonding in battery modules:Polyurethane systems are replacing mechanical fasteners in pack assembly to reduce mass and improve crash energy absorption.
- Jiangsu province cluster concentration:CATL and BYD supplier parks in eastern China are co-locating adhesive blending facilities to eliminate cross-border logistics for thermally conductive formulations.
Market Restraints
- Alumina filler cost volatility:Thermal conductivity additives face price swings tied to bauxite processing capacity in Guangxi and Henan provinces.
- Single-source silicone supply risk:High-purity silicone precursors concentrate among three German and Japanese chemical conglomerates.
- Flame-retardant formulation limits:Halogen-free alternatives cannot yet match brominated compounds in UL 94 V-0 ratings at equivalent cost.
Strategic Opportunities
- Solid-state battery interfaces:Next-generation cell architectures demand adhesives compatible with lithium-metal anodes and sulfide electrolytes.
- India PLI scheme for ACC batteries:Domestic cell manufacturing incentives are creating adhesive demand from Reliance and Ola Electric gigafactories in Gujarat and Tamil Nadu.
- Repair and second-life battery channels:Disassembly-friendly adhesives open aftermarket revenue streams as EU right-to-repair directives expand.
Industry Challenges
- Electrochemical compatibility testing:Adhesive outgassing validation against NMC 811 cathodes requires 18-month aging protocols that delay commercialization.
- Automation integration:Two-part dispensing systems demand robotic precision that Tier 2 pack assemblers lack capital to deploy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Vehicle Adhesives and Sealants Market |
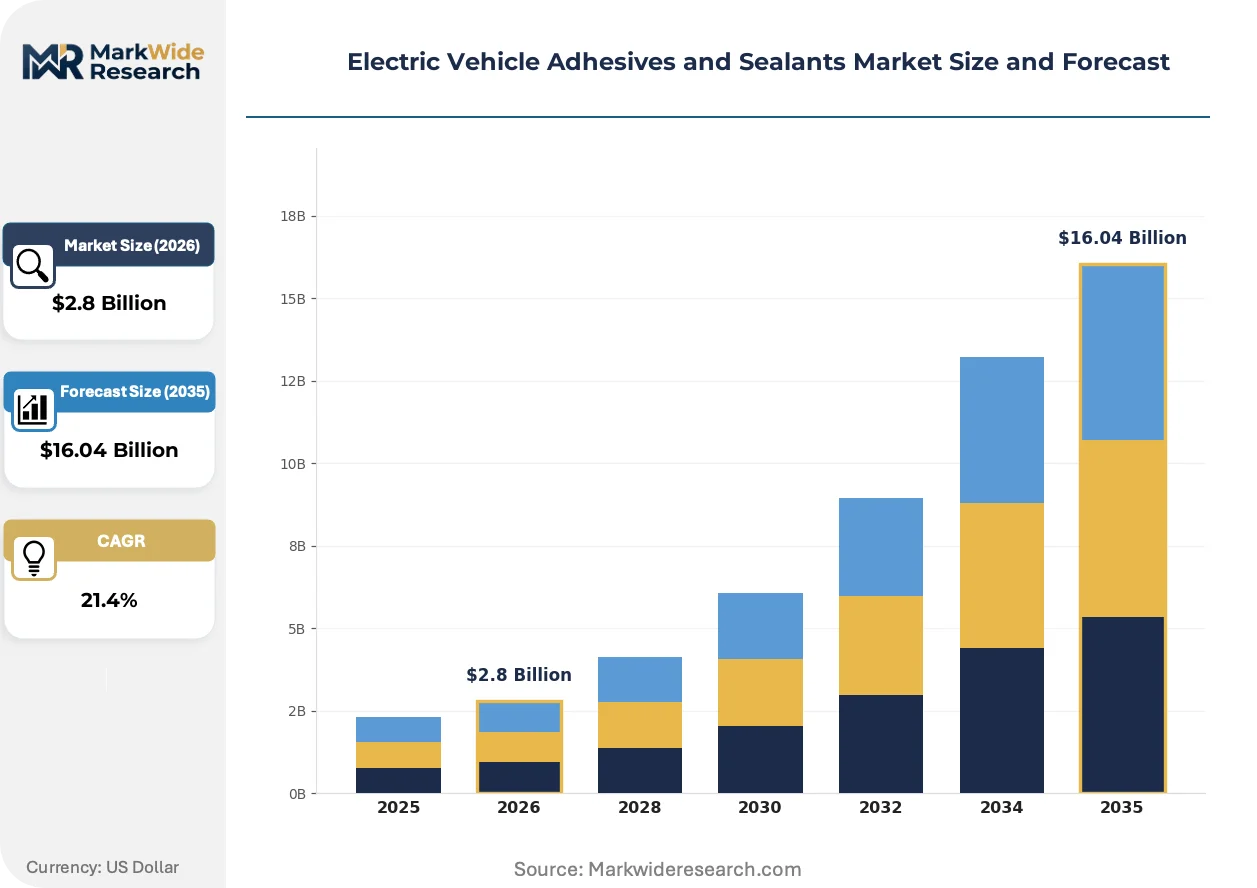
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $16.04 Billion |
| CAGR (2026 – 2036) | 21.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
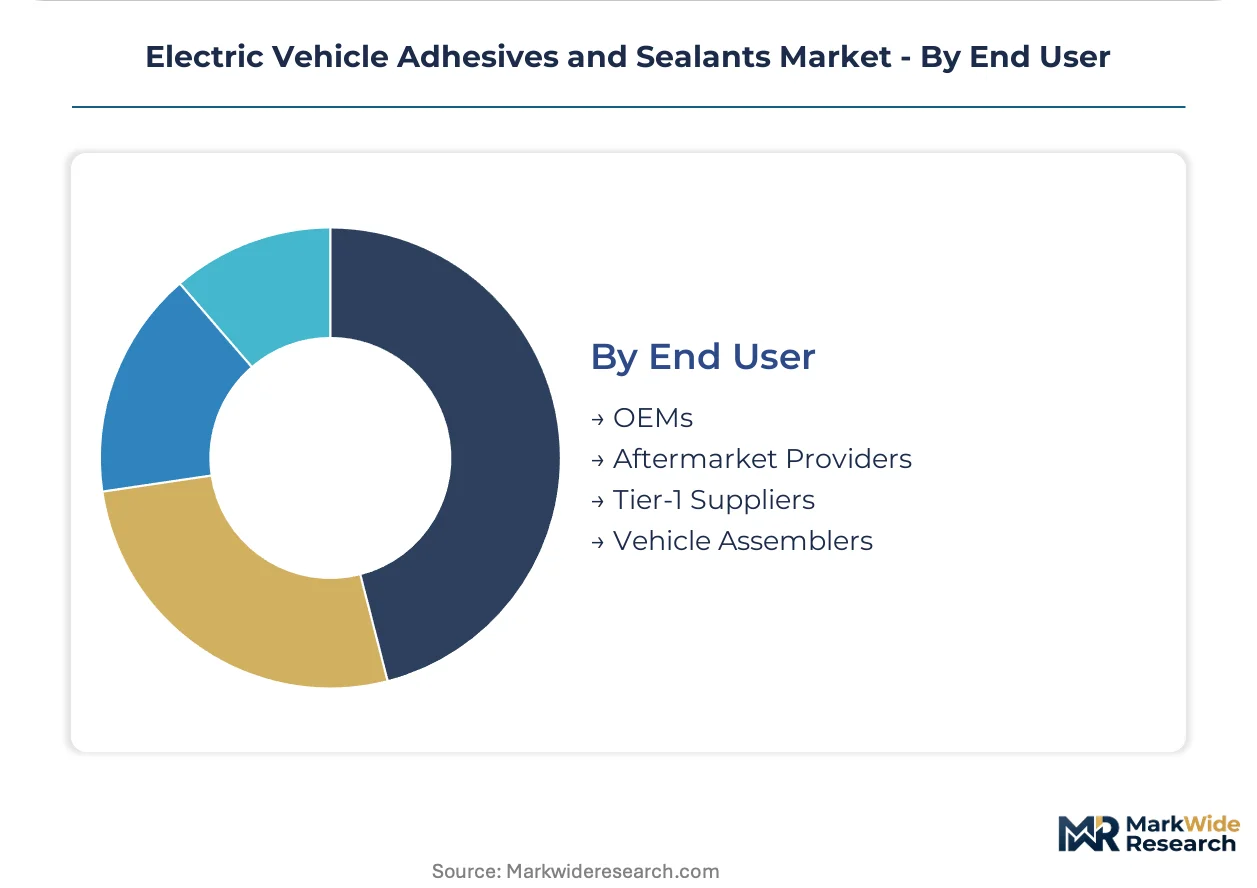
| Segmentation | Product Type: Epoxy, Polyurethane, Silicone, Acrylic Application: Battery Assembly, Structural Bonding, Interior Attachment, Exterior Sealing Technology: Two-Part Adhesives, One-Part Adhesives, Hot Melt Adhesives, Reactive Adhesives End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers |
| Companies Covered | Henkel AG & Co. KGaA, 3M Company, Sika AG, H.B. Fuller Company, Huntsman Corporation, Arkema, Dow, BASF, Wacker Chemie AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Vehicle Adhesives and Sealants Market Trends and Innovations
Thermal interface materials are evolving from passive gap-fillers to active structural elements that manage heat, vibration, and electrical isolation simultaneously. This convergence is compressing the supplier base toward multi-functional chemistry platforms.
Phase-change materials integrated with graphite sheets are supplanting traditional silicone thermal pads in high-performance battery modules. Porsche and Rimac are specifying these hybrids for 800V architectures where heat flux exceeds 15 W/mK. The shift is compressing margins for single-function gap filler suppliers and rewarding compounders with in-house phase-change R&D.
REACH SVHC candidate list expansions are forcing reformulation of polyurethane catalysts and tin-based stabilizers. ECHA's 2024-2025 screening roadmap targets organotin compounds used in moisture-cure systems. German OEM qualification programs now require pre-submission of alternative catalyst packages, disadvantaging smaller Asian blenders without EU regulatory affairs teams.
Cell-to-pack architectures are eliminating module housings and shifting adhesive consumption from structural bonding to direct cell attachment. This reduces per-vehicle adhesive mass by 30-40% but increases performance requirements for the remaining material. Chinese OEMs at BYD and CATL are driving this transition fastest, with European programs trailing 18-24 months behind.
Electric Vehicle Adhesives and Sealants Market Segmentation
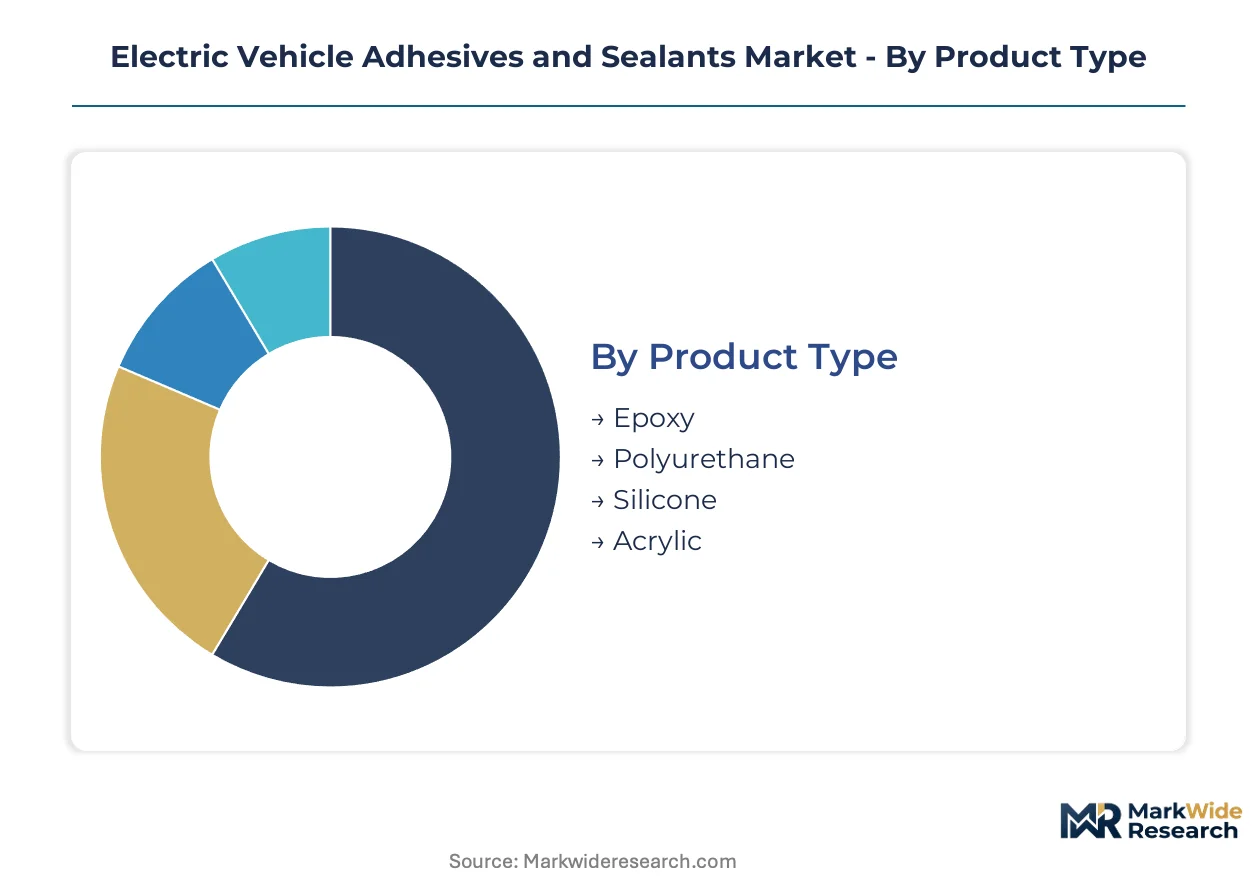
Material substitution pressures and evolving assembly automation requirements fragment the electric vehicle adhesives landscape across chemistry platforms, cure mechanisms, and supply chain tiers. Segmentation clarity determines procurement strategy as OEMs balance thermal performance specifications against regulatory compliance timelines.
Product Type:
Polyurethane formulations face the most acute substitution threat from silicone alternatives in high-temperature battery zones, while epoxy systems confront phase-change material displacement in premium thermal management applications.
- Polyurethane:Flexible aliphatic and aromatic systems dominate structural bonding applications where impact resistance and vibration damping are critical. BYD and CATL procurement teams in Jiangsu province specify these formulations for module-to-pack assembly where crash energy absorption requirements exceed 40 kJ. Cost advantages over silicone sustain volume leadership despite thermal ceiling limitations around 120°C.
- Silicone:Heat-cured and addition-cure systems command premium positioning in 800V architectures requiring continuous operation above 150°C. Porsche specifications for the Taycan and Macan EV platforms specify silicone thermal interface materials where heat flux densities surpass 15 W/mK. REACH SVHC screening on tin catalysts is forcing reformulation investments that favor suppliers with captive R&D infrastructure.
- Epoxy:Rigid thermoset systems anchor motor lamination bonding and inverter potting applications where dielectric strength and dimensional stability are non-negotiable.
- Acrylic:UV-cure and anaerobic variants capture interior attachment applications where fast fixture speed and low odor emissions align with cabin air quality protocols.
Polyurethane retains volume leadership; silicone holds the steepest expansion curve.
Application:
Cost tier stratification separates commodity sealants from engineered thermal materials, with battery assembly commanding per-kilogram premiums that exceed structural bonding by factors of three to five.
- Battery Assembly:Thermally conductive adhesives for cell-to-cell bonding, module encapsulation, and pack sealing constitute the highest-value application segment. Cell-to-pack architectures at BYD and CATL are shifting consumption patterns from module housing bonds to direct cell attachment, reducing per-vehicle mass by 30-40% while intensifying performance requirements for remaining material. EU battery passport traceability mandates are forcing batch-level documentation that disadvantages distributors without laboratory certification capabilities.
- Structural Bonding:Load-bearing adhesives for body-in-white and chassis applications replace spot welds and mechanical fasteners to enable multi-material vehicle construction. BMW and Mercedes-Benz qualification programs in Germany's automotive corridor specify crash-durable formulations that maintain bond integrity through 15-year service life simulations.
- Interior Attachment:Low-VOC acrylic and hot-melt systems for trim, headliner, and carpet bonding where aesthetic finish and worker safety drive specification.
- Exterior Sealing:UV-stable polyurethane and silicone sealants for windshield, lighting, and closure panel applications where moisture ingress protection and paint compatibility are critical.
Structural bonding captures the widest OEM qualification footprint; battery assembly generates the highest margin concentration.
Technology:
Volume concentration favors two-part systems in automated battery lines, while one-part technologies retain relevance in aftermarket repair channels where dispensing equipment capital is unavailable.
- Two-Part Adhesives:Meter-mix-dispense systems enable controlled cure profiles and pot life management essential for high-throughput battery assembly. CATL and LG Energy Solution production lines in Nanjing and Ningde specify two-part polyurethanes with 3-5 minute working times that gel within 10 minutes to accommodate 60-second takt times. Capital requirements for robotic dispensing infrastructure exclude Tier 2 pack assemblers from this technology tier.
- One-Part Adhesives:Moisture-cure and heat-cure systems serve lower-volume applications and repair scenarios where mixing equipment investment cannot be justified. Henkel's European manufacturing footprint dominates OEM qualification for these formulations in legacy platform maintenance.
- Hot Melt Adhesives:Thermoplastic systems for interior trim attachment where instant handling strength and solvent-free application align with sustainability targets.
- Reactive Adhesives:Cyanoacrylate and anaerobic chemistries for fast-fixturing electrical component assembly where cure speed outweighs thermal performance requirements.
Two-part adhesives dominate new platform procurement; one-part systems retain aftermarket relevance.
End User:
Customer type determines specification authority, with OEMs controlling thermal material selection while Tier-1 suppliers retain autonomy in structural bonding procurement.
- OEMs:Volkswagen, Tesla, and SAIC specify adhesive platforms at the vehicle architecture level, particularly for battery thermal management where cell chemistry compatibility and warranty liability concentrate decision authority. Direct OEM procurement of thermally conductive materials is expanding as platform electrification intensifies.
- Tier-1 Suppliers:Contemporary Amperex Technology, Samsung SDI, and SK On integrate adhesive selection into pack design responsibility, qualifying multiple suppliers to mitigate single-source risk. These firms balance OEM specification compliance against total landed cost optimization.
- Vehicle Assemblers:Contract manufacturers and joint venture operations execute adhesive application under OEM or Tier-1 technical direction with limited specification autonomy.
- Aftermarket Providers:Independent repair networks and battery remanufacturing specialists source disassembly-friendly formulations as EU right-to-repair directives expand second-life battery channels.
OEMs control thermal material specification; Tier-1 suppliers drive structural bonding procurement volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in thermally conductive formulations favor net-producing regions with captive bauxite processing and silicone precursor capacity. Trade flows concentrate from German chemical corridors and Chinese coastal provinces toward battery assembly clusters in emerging manufacturing zones.
China
Jiangsu province hosts CATL and BYD supplier parks driving thermally conductive adhesive consumption. GB standards for new energy vehicle safety mandate flame-retardant formulations with documented material traceability. Nanjing and Ningde production lines specify two-part polyurethanes for 60-second takt times in automated battery assembly.
Germany
Bavaria and Baden-Württemberg anchor OEM qualification programs for silicone thermal interface materials in 800V architectures. ECHA REACH frameworks enforce SVHC screening on organotin catalysts used in moisture-cure systems. Stuttgart and Munich automotive corridors concentrate Henkel and Wacker Chemie manufacturing footprints for direct OEM supply.
United States
EPA vehicle emissions standards accelerate structural bonding substitution for mechanical fasteners in multi-material body construction. IRA domestic content provisions incentivize localized adhesive blending for battery pack assembly. Michigan and Ohio automotive clusters integrate thermal management materials into platform electrification programs.
India
Gujarat and Tamil Nadu gigafactories under the PLI scheme for ACC batteries generate adhesive demand from Reliance and Ola Electric operations. BIS certification requirements for automotive chemicals create entry barriers for uncertified imports. Domestic blending facilities are co-locating with cell manufacturing parks to eliminate cross-border logistics.
Japan
METI carbon neutrality roadmaps drive reformulation investments for halogen-free flame retardants in battery applications. High-purity silicone precursor supply concentrates among domestic chemical conglomerates serving premium thermal management segments. Nagoya and Tokyo industrial corridors maintain specialized polyurethane R&D for motor lamination bonding.
Electric Vehicle Adhesives and Sealants Market Competitive Landscape
Listed leaders compete with private specialists across formulation chemistry and geographic coverage dimensions. The vendor base organizes into three tiers: diversified chemical conglomerates with full polymer portfolios, mid-cap adhesive specialists with regional manufacturing depth, and niche compounders serving single-application segments. Strategic moves concentrate on captive testing infrastructure expansion and pre-certified material library development to compress OEM qualification timelines.
Within the diversified chemical tier, Henkel AG & Co. KGaA and Dow exemplify European and North American archetypes with integrated manufacturing and regulatory affairs capabilities. Sika AG occupies a position among specialized polyurethane system suppliers with focused battery encapsulation expertise. These three anchors represent distinct competitive vectors: conglomerate scale, regional regulatory proximity, and application-specific formulation depth.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| 3M Company |
| Sika AG |
| H.B. Fuller Company |
| Huntsman Corporation |
| Arkema |
| Dow |
| BASF |
| Wacker Chemie AG |
| Others |
Pricing and Supply Chain Analysis
Polyurethane substitution for mechanical fasteners in battery module assembly simultaneously concentrates procurement authority with OEM platform engineers and compresses margin pools for distributors without captive blending capacity. This chemistry shift redraws supply geography toward Jiangsu province co-location clusters while pricing power migrates to suppliers with pre-certified thermal conductivity libraries.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake structure that locks volume commitments against qualification investment recovery. Price differentiation separates REACH-certified formulations from uncertified alternatives, with volume scale and customization level as secondary tiering factors. Cost compression in commodity polyurethane grades is intensifying because alumina filler volatility transfers directly from Guangxi bauxite processors. Tier-2 pack assemblers exhibit the highest price sensitivity due to capital constraints on robotic dispensing infrastructure, while Porsche and Rimac specifications for 800V architectures show minimal elasticity.
Supply Chain Analysis
Strategic stockpiling of high-purity silicone precursors dominates inventory strategy as German and Japanese chemical conglomerates concentrate supply. Manufacturing gravity centers on China, Germany, and the United States, with raw material dependencies on alumina from Guangxi, silicone precursors from German chemical corridors, and polyurethane base resins from BASF Ludwigshafen operations. Single-source vulnerability in silicone precursor supply creates structural risk exposure for 800V thermal interface material specifications. Distribution runs through direct OEM qualification programs and Tier-1 supplier integration partnerships, bypassing traditional chemical distribution channels for thermally conductive formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cell-to-pack architecture standardization across BYD and CATL platforms creates platform-economics inflection where adhesive interoperability becomes a gating factor for second-life battery channel participation.
For Market Incumbents: Shield formulation libraries against REACH SVHC catalyst displacement by accelerating organotin-free polyurethane R&D through captive European laboratory infrastructure. Backward integration into alumina filler processing in Guangxi secures margin position against bauxite price volatility. Pre-certify alternative thermal interface materials before ECHA screening deadlines to maintain OEM qualification status. For New Entrants and Emerging Players: Lead with disassembly-friendly adhesive development targeting EU right-to-repair directive compliance as battery remanufacturing channels expand. India PLI scheme gigafactories in Gujarat represent the most penetrable geography given nascent local blending capacity and BIS certification entry barriers for imports. Pursue joint qualification programs with Reliance and Ola Electric procurement teams to bypass incumbent specification lock-in. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors mid-cap specialists with regional regulatory affairs capabilities over diversified chemical conglomerates. Five-to-ten year viability hinges on solid-state battery interface compatibility investments. Acquisition target archetype: European polyurethane compounders with ECHA pre-submission track records and Nanjing logistics proximity. The signal to watch is OEM qualification timeline compression below nine months as platform launch acceleration intensifies.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alumina Processing | Captive supply of thermal conductivity fillers from Guangxi bauxite operations secures margin against price volatility. |
| REACH Pre-Certification Investment | Early organotin-free catalyst validation with ECHA preserves OEM qualification status ahead of SVHC screening deadlines. |
| Co-Location with Jiangsu Supplier Parks | Proximity to CATL and BYD operations eliminates cross-border logistics costs for thermally conductive formulations. |
| Solid-State Battery Interface R&D | Lithium-metal anode compatibility development positions suppliers for next-generation cell architecture procurement. |
| Disassembly-Friendly Formulation Launch | EU right-to-repair directive alignment opens aftermarket revenue streams in battery remanufacturing channels. |
Research Methodology
Operator-level perspectives from OEM platform engineers, Tier-1 battery pack procurement leads, adhesive blending facility managers, and ECHA regulatory affairs specialists anchored the qualitative base. Primary interview findings triangulated against secondary sources including customs trade data for thermally conductive formulation imports, SEC 10-K filings from listed chemical conglomerates, and GB standards documentation from China's Ministry of Industry and Information Technology. Bottom-up volume estimates from cell-to-pack adhesive content per vehicle combined with top-down market sizing from automotive production forecasts.
Sensitivity analysis across alumina filler cost scenarios, REACH implementation timelines, and solid-state battery commercialization curves stress-tested projection robustness. Segmentation modeling spanned chemistry platform, cure mechanism technology, application function, and regional production cluster dimensions. CAGRs derived from weighted average of OEM platform launch schedules and supplier capacity expansion announcements throughout the forecast period. Battery passport traceability mandates and 800V architecture penetration served as industry-specific demand drivers.
The analysis sits within stated boundaries; outcomes outside sustained NMC 811 cathode dominance or delayed EU battery passport enforcement would require recalibration. Forecasts reflect documented assumptions regarding OEM qualification timeline compression and alumina supply concentration. Revision becomes warranted when solid-state battery interface compatibility requirements cross commercialization thresholds or when ECHA expands SVHC screening beyond organotin compounds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
De-Seamable Adhesives Market
Adhesives & Sealants
North America Reactive Adhesives Market
Adhesives & Sealants
2-Octyl Cyanoacrylate Adhesives Market
Adhesives & Sealants
Two Component Adhesive Market
Adhesives & Sealants
United Kingdom Sealants Market
Adhesives & Sealants
Metal Bonding Adhesives Market
Adhesives & Sealants
Automotive Adhesives and Sealants Market
Adhesives & Sealants
Carpet Adhesive Market
Adhesives & Sealants
Global Epoxy Adhesive Market
Adhesives & Sealants
Instant Adhesive Market
Adhesives & Sealants
Anti-Corrosion Tape Market
Adhesives & Sealants
Asia-Pacific Epoxy Adhesive Market
Adhesives & Sealants
Middle-East and Africa Hot-Melt Adhesives Market
Adhesives & Sealants
Chemical Anchors Market
Adhesives & Sealants
Asia-Pacific Waterproofing Products Market
Adhesives & Sealants
Asia-Pacific Hot-Melt Adhesives Market