
 Global Automotive Adhesive Market | 2026-2036
Global Automotive Adhesive Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Adhesive Market Analysis
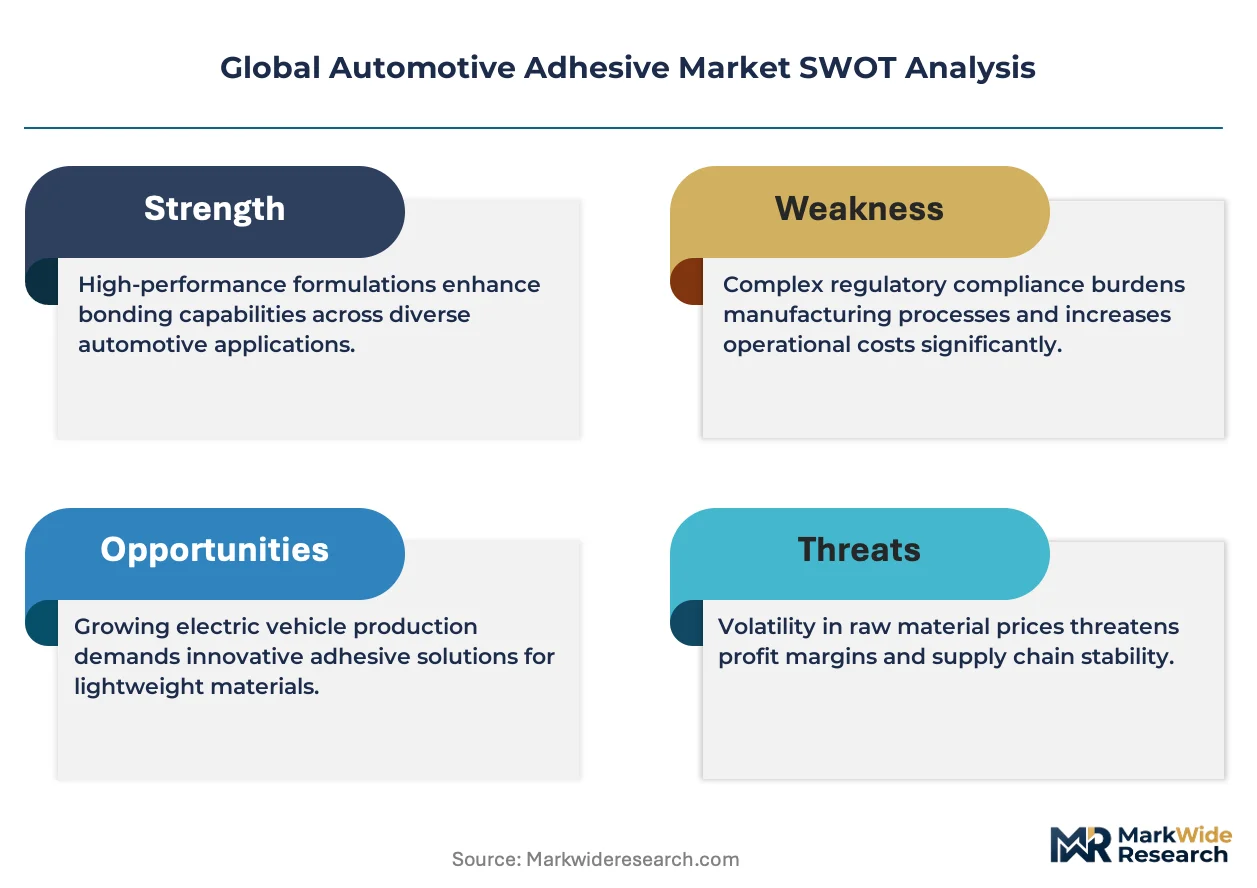
ISO 9001 and IATF 16949 qualification cycles is bifurcating the supplier base into qualified tier-1 feedstock partners and commodity resin traders. Henkel AG & Co. KGaA leverages its captive epoxy and polyurethane resin capabilities to anchor long-term contracts with German and Chinese OEMs. Dow Inc. competes through upstream control over silane-modified polymer feedstocks, while Sika AG specializes in acoustic-damping adhesive systems for premium cabin assemblies.
Automotive adhesives are formulated polymeric bonding agents, typically comprising epoxy resins, polyurethane prepolymers, or acrylic monomers cured through thermal, moisture, or ultraviolet initiation, designed to join dissimilar substrates while distributing structural loads across bonded joints. Their primary industrial purpose is to enable lightweight vehicle construction by substituting mechanical fasteners in aluminum-steel multimaterial body-in-white assemblies. Polyurethane formulations lead volume consumption due to their flexibility and crash-energy absorption in structural bonding applications, while UV-cured technology represents the fastest-expanding segment as cycle-time pressures intensify in high-volume EV production lines. Water-based systems command premium positioning in interior applications where cabin air quality regulations restrict residual solvent content.
FDA oversight of indirect food-contact materials in cabin interiors, EPA regulations on hazardous air pollutant emissions from solvent-based adhesive operations, and REACH substance restrictions in Europe collectively reshape formulation roadmaps and plant-location decisions for multinational suppliers. China's MIIT dual carbon goals and GB standards on vehicle lifecycle emissions extend these compliance pressures into the world's largest automotive production base. Stakeholders must monitor the divergence between regional chemistries as trade barriers harden around carbon-border adjustment mechanisms and localized content requirements.
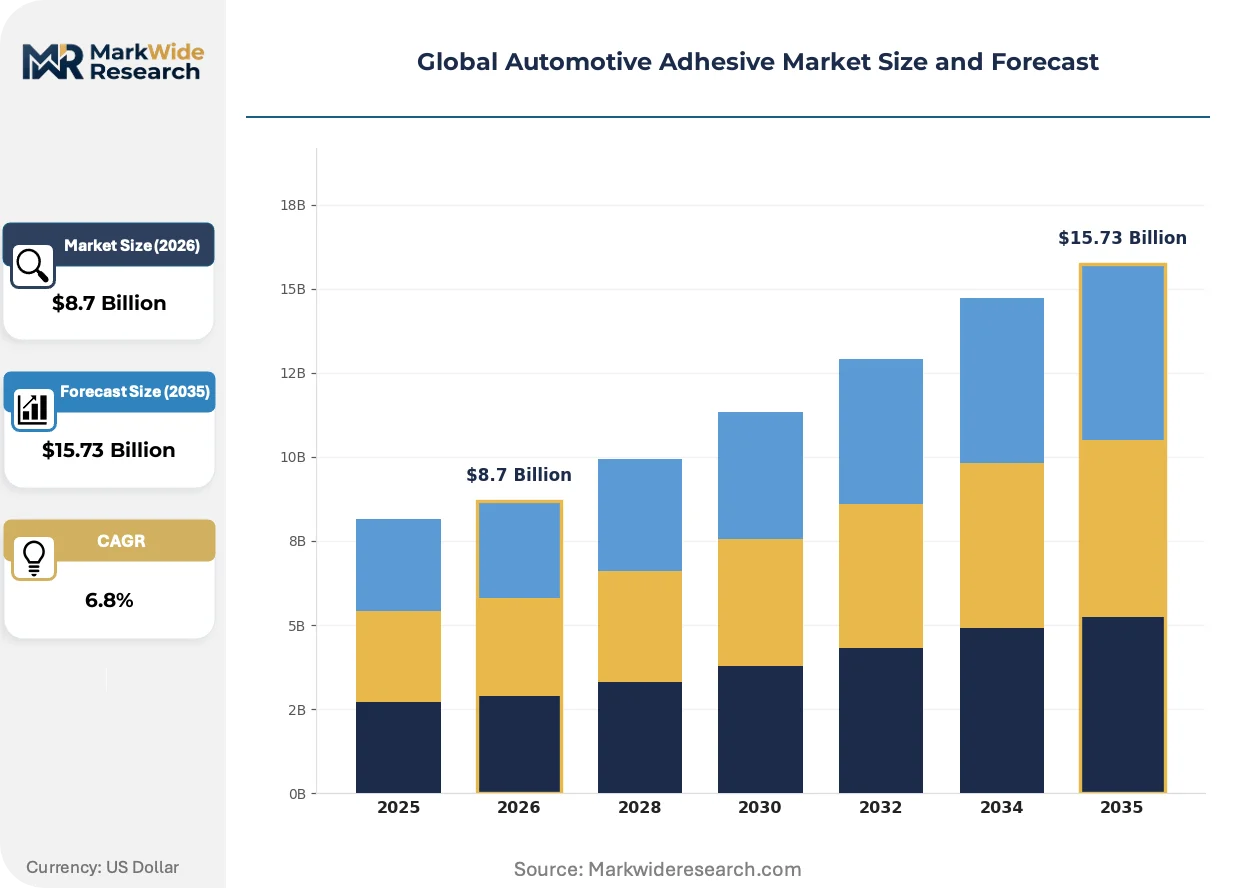
Market Dynamics
EV battery pack assembly is compressing adhesive cure cycles from hours to minutes while multimaterial body-in-white architectures multiply bonding points per vehicle. This dual pressure is restructuring supplier qualification requirements and resin formulation priorities across OEM supply chains.
Growth Catalysts
- REACH substance restrictions:Europe's phased limits on volatile organic compounds in solvent-based systems are accelerating water-based and UV-cured chemistry development for cabin interior applications.
- Aluminum-intensive vehicle architectures:Chinese domestic EV manufacturers are scaling bonded multimaterial designs that substitute adhesives for spot welding in crash-critical joints.
- MIIT dual carbon goals:China's GB standards on vehicle lifecycle emissions mandate lightweighting through adhesive bonding to offset battery mass penalties.
Market Restraints
- Epoxy resin price volatility:Petrochemical feedstock fluctuations and energy cost spikes in European production clusters compress formulation margins unpredictably.
- Qualified supplier concentration:ISO 9001 and IATF 16949 certification cycles limit approved feedstock sources to a narrow tier-1 base in Germany and Japan.
- Mechanical fastener residual preference:Legacy repair infrastructure and technician training in North American aftermarket channels slow full adhesive substitution.
Strategic Opportunities
- India automotive manufacturing expansion:PLI scheme incentives for EV production create first-mover positioning for adhesive suppliers establishing local formulation capacity.
- Acoustic-damping cabin systems:Premium vehicle segments in South Korea and Germany are specifying viscoelastic adhesives that combine structural bonding with NVH reduction.
- UV-cured technology convergence:Integration of LED curing systems with automated dispensing equipment enables single-minute cycle times on high-volume EV assembly lines.
Industry Challenges
- IATF 16949 certification timelines:New entrants face 18-24 month approval cycles to supply German and Japanese OEMs, freezing out speculative capacity investments.
- Multimaterial joint design complexity:Aluminum-steel-carbon fiber interfaces require customized adhesive formulations with mismatched thermal expansion coefficients and corrosion isolation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Adhesive Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Polyurethane, Acrylic, Silicone Application: Body Shop, Interior, Exterior, Chassis End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Technology: Solvent-Based, Water-Based, Hot Melt, UV-Cured |
| Companies Covered | H.B. Fuller Company, Arkema SA, Henkel AG & Co. KGaA, PPG Industries, Inc., Huntsman International LLC, 3M Company, Dow Inc., BASF SE, Sika AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Adhesive Market Emerging Trajectories
Adhesive formulation is splitting along performance-grade lines as EV production volumes expose the cost-performance trade-offs that were tolerable in low-volume premium vehicles. This division is forcing suppliers to choose between scale economics and specialization.
One-component epoxy systems with latent thermal initiators are bifurcating the structural bonding segment. German and Chinese EV battery pack assemblers are adopting these chemistries for their pot-life stability and rapid hot-platen cure. This technology is compressing the competitive set into high-purity resin specialists versus commodity compounders lacking temperature-controlled supply chains.
EPA hazardous air pollutant regulations on solvent-based adhesive operations are forcing plant-location recalculations for multinational suppliers. Facilities in US states with delegated air-quality authority face patchwork compliance costs that favor consolidated production in jurisdictions with unified permitting. Water-based interior-grade formulations are capturing share in Michigan and Tennessee assembly corridors where cabin air quality standards are tightening fastest.
Buyer concentration among top-tier EV battery pack integrators is shortening qualification cycles and demanding application-engineering co-development. Direct OEM-supplier technical partnerships are replacing traditional tiered distribution in South Korea and Sweden. This pattern is most visible in Gothenburg and Seoul metropolitan clusters where cell-to-pack architectures require adhesive suppliers to embed engineers in customer design centers.
Global Automotive Adhesive Market Segmentation
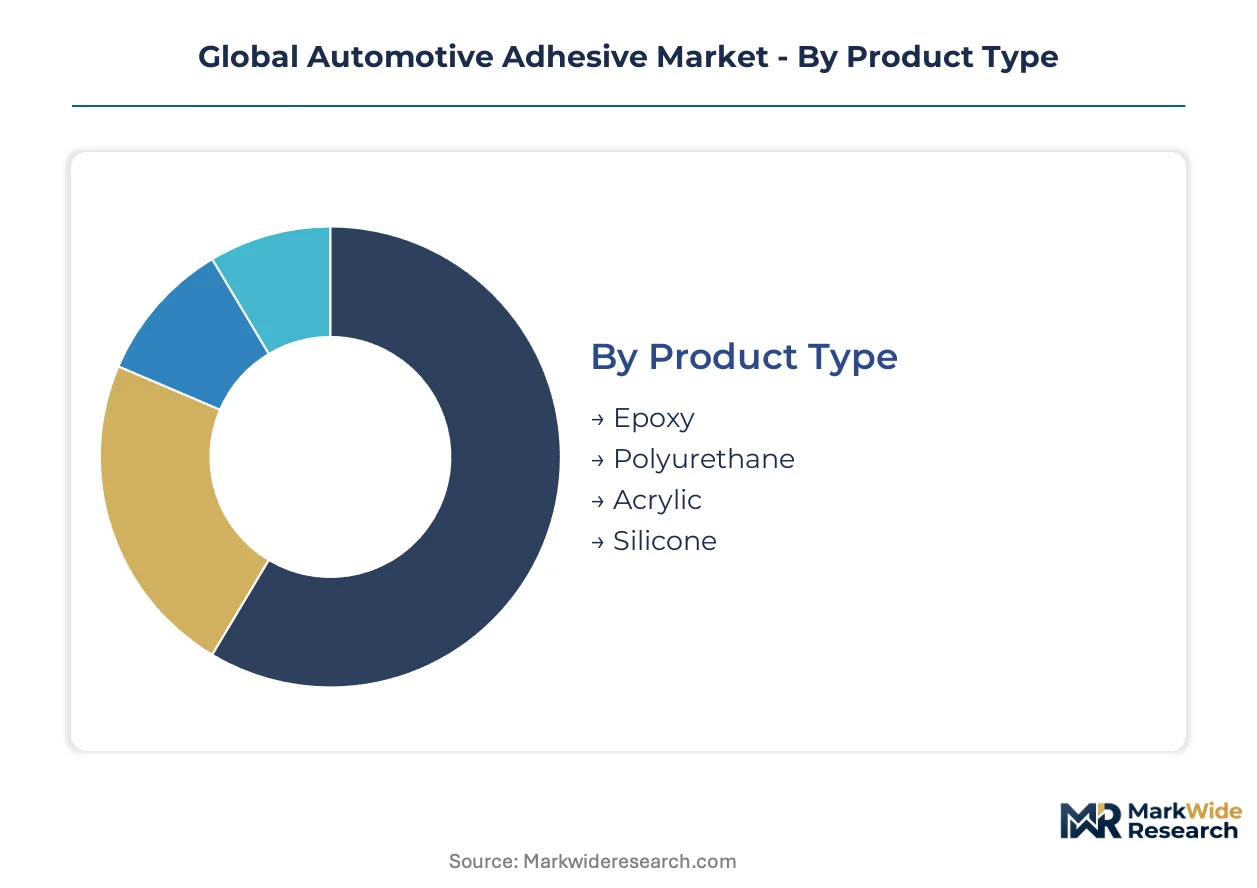
Automotive adhesive segmentation reflects divergent performance requirements across vehicle subsystems. Substitution threats from mechanical fasteners and welding vary sharply by bonding location and load-bearing demands.
Product Type:
Polyurethane faces the strongest substitution pressure from next-generation acrylics in crash-critical joints, while epoxy resins defend position through thermal cycling endurance in powertrain applications.
- Polyurethane:Flexible prepolymer systems dominate structural bonding for aluminum-steel multimaterial assemblies. Henkel and Dow anchor long-term supply contracts with German and Chinese OEMs seeking crash-energy absorption in battery pack enclosures.
- Epoxy:Rigid thermoset formulations withstand thermal cycling in electric motor stator bonding and powertrain component assembly. One-component latent cure systems from Japanese suppliers compress cycle times in high-volume Chinese EV lines.
- Acrylic:Rapid-cure methacrylate chemistry penetrates exterior panel bonding where UV stability and color match tolerance matter. Sika AG and Huntsman Corporation target premium German OEMs with toughened grades for carbon fiber roof assemblies.
- Silicone:Elastomeric sealants protect electronic control modules and lighting assemblies from moisture ingress. Dow's silane-modified polymer feedstock integration secures cost positioning in Michigan and Tennessee assembly corridors.
Polyurethane retains volume leadership; UV-cured acrylic formulations hold the steepest expansion curve in exterior applications.
Application:
Cost tier stratification separates qualified structural grades from commodity interior formulations, with certification requirements widening the margin gap between tiers.
- Body Shop:Structural adhesives substitute for spot welds in aluminum-intensive architectures. Chinese domestic EV manufacturers scale bonded designs through Shanghai and Shenzhen engineering centers, compressing mechanical fastener share in crash-critical joints.
- Interior:Low-VOC water-based systems command premium positioning under REACH substance restrictions and EPA hazardous air pollutant regulations. Cabin air quality standards in Michigan and Tennessee accelerate solvent-based displacement.
- Exterior:UV-resistant grades bond polycarbonate headlamp lenses and composite body panels. Korean and German premium segments specify acoustic-damping formulations that combine structural integrity with NVH reduction.
- Chassis:High-shear epoxy and polyurethane hybrids secure suspension component attachment. IATF 16949 qualification limits approved suppliers to German and Japanese tier-1 feedstock partners.
Body Shop applications concentrate the highest per-vehicle adhesive value; Interior segments gain share fastest as cabin air quality regulations tighten across production regions.
End User:
Customer type determines procurement leverage, with direct OEM partnerships displacing traditional tiered distribution in battery pack integration.
- OEMs:Volkswagen, BYD, and Hyundai Motor Group negotiate direct technical partnerships for cell-to-pack adhesive specification. Application engineers embed in Gothenburg and Seoul design centers to compress qualification cycles.
- Tier-1 Suppliers:Battery pack integrators like CATL and LG Energy Solution concentrate purchasing power, forcing resin suppliers into co-development contracts. ISO 9001 and IATF 16949 certification requirements narrow the qualified supplier base.
- Vehicle Assemblers:Contract manufacturers in India and Mexico source commodity-grade formulations through regional distributors. PLI scheme incentives in India attract first-mover adhesive suppliers establishing local formulation capacity.
- Aftermarket Providers:Legacy repair infrastructure in North American channels sustains mechanical fastener preference, slowing full adhesive substitution in collision repair.
OEM direct procurement dominates value capture; Tier-1 supplier concentration is accelerating fastest as battery pack integration consolidates.
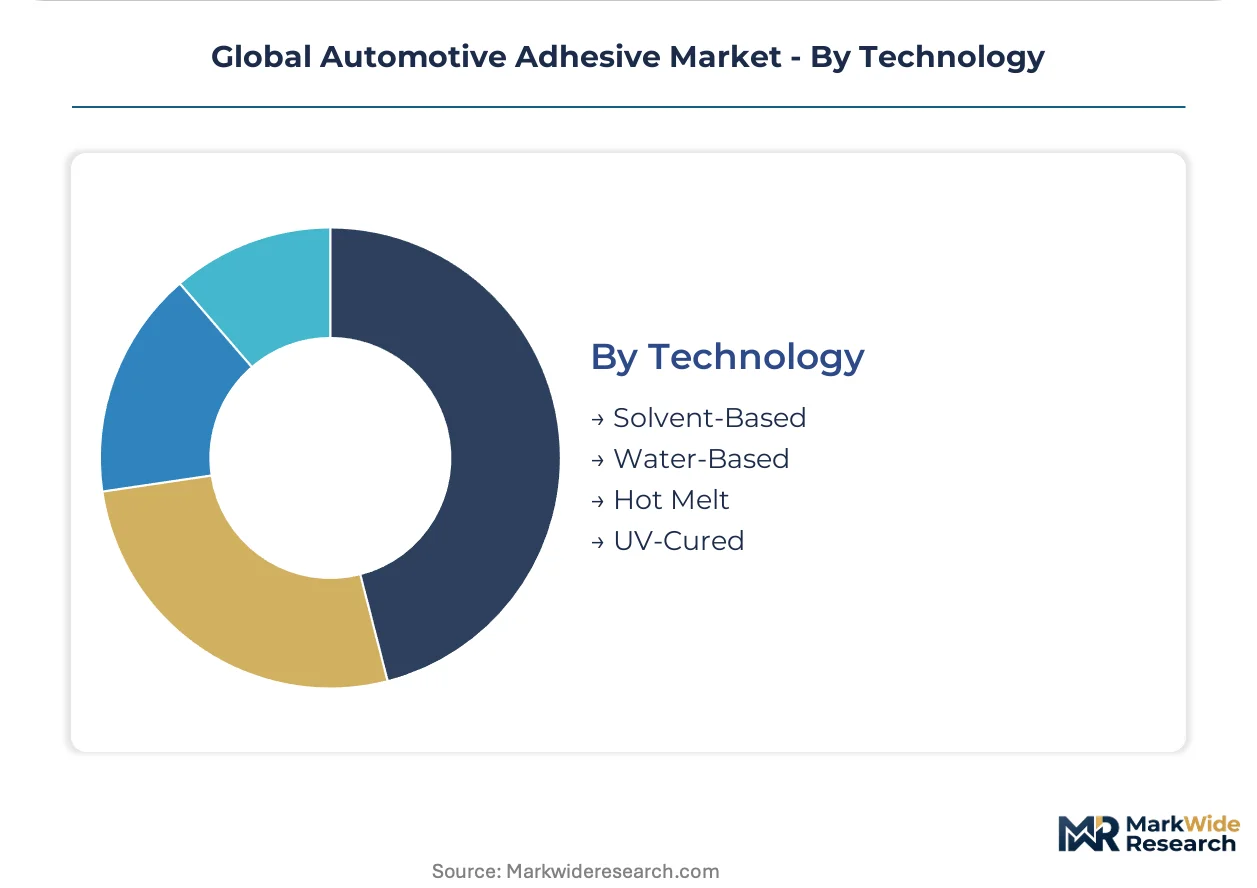
Technology:
Supply concentration in UV-cured chemistry is restructuring plant-location decisions as EPA regulations fragment US compliance costs.
- UV-Cured:LED-initiated acrylic systems enable sub-minute cure cycles on automated EV assembly lines. Korean and Chinese manufacturers lead adoption in high-volume battery pack production.
- Water-Based:Emulsion polymers penetrate interior applications where REACH and GB standards restrict residual solvent content. European facilities face phased VOC limits that favor consolidated production in unified-permitting jurisdictions.
- Solvent-Based:High-performance urethane and epoxy solutions defend position in exterior structural bonding where moisture cure speed matters. EPA hazardous air pollutant regulations force recalculation of US plant locations.
- Hot Melt:Reactive polyurethane hot melts bond interior trim and carpet assemblies with instant green strength. Lower capital requirements attract regional compounders serving secondary automotive markets.
Solvent-Based technology retains installed-base dominance; UV-Cured systems climb the fastest as cycle-time pressures intensify in EV production.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Shanghai-Ningbo port complex underwrites China's dominance in automotive adhesive logistics, handling resin feedstocks for EV battery pack assembly across the Yangtze Delta manufacturing corridor.
China
Domestic EV manufacturers scale bonded aluminum-intensive architectures through Shenzhen and Shanghai engineering centers. MIIT dual carbon goals and GB standards on vehicle lifecycle emissions mandate lightweighting to offset battery mass penalties. Cell-to-pack adhesive specification concentrates purchasing power with CATL and BYD procurement teams in the Pearl River Delta.
Germany
REACH substance restrictions on volatile organic compounds force formulation shifts toward water-based and UV-cured chemistries for cabin interior applications. IATF 16949 certification requirements limit approved suppliers to a narrow tier-1 base concentrated in Baden-Württemberg and Bavaria. Henkel and Sika anchor long-term contracts with Volkswagen and BMW through Stuttgart and Munich technical centers.
United States
EPA hazardous air pollutant regulations on solvent-based adhesive operations force plant-location recalculations toward jurisdictions with unified permitting. Michigan and Tennessee assembly corridors tighten cabin air quality standards fastest, accelerating water-based interior-grade adoption. Dow's silane-modified polymer feedstock integration secures cost positioning in Detroit-area supply chains.
South Korea
Hyundai Motor Group and LG Energy Solution negotiate direct technical partnerships for battery pack adhesive specification. MFDS oversight of indirect food-contact materials in cabin interiors complements REACH-aligned voluntary standards. Application engineers from global suppliers embed in Seoul metropolitan design centers to compress qualification cycles.
India
PLI scheme incentives for EV production create first-mover positioning for adhesive suppliers establishing local formulation capacity. BIS standards on automotive component quality parallel ISO 9001 and IATF 16949 requirements. Maharashtra and Tamil Nadu manufacturing clusters attract regional compounders serving Maruti Suzuki and Tata Motors assembly operations.
Global Automotive Adhesive Market Vendor Landscape
Listed leaders compete with private specialists across capital access and certification speed. The supplier base bifurcates into qualified tier-1 feedstock partners holding long-term OEM contracts and commodity resin traders serving secondary markets. Three archetypes dominate: integrated resin producers with captive epoxy and polyurethane capabilities, application-engineering specialists co-developing cell-to-pack solutions, and regional compounders exploiting lower capital barriers in hot-melt segments. Competitive moves concentrate on backward integration into silane-modified polymer feedstocks and geographic expansion into Indian PLI-subsidized manufacturing zones.
Among European-anchored diversified chemical groups, Henkel AG & Co. KGaA and BASF SE exemplify the integrated-resin-producer archetype through their captive supply capabilities. Sika AG occupies a position within the application-engineering specialist tier, particularly in acoustic-damping systems for premium cabin assemblies. These three entities represent the competitive tension between scale-driven formulation breadth and co-development depth with battery pack integrators.
| Leading Market Players |
|---|
| H.B. Fuller Company |
| Arkema SA |
| Henkel AG & Co. KGaA |
| PPG Industries, Inc. |
| Huntsman International LLC |
| 3M Company |
| Dow Inc. |
| BASF SE |
| Sika AG |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at German and Japanese epoxy resin clusters shapes both supply concentration and price floors for qualified automotive adhesive grades. IATF 16949 certification barriers restrict approved feedstock sources to a narrow tier-1 base, concentrating pricing power with incumbent suppliers while compressing margins for commodity compounders lacking temperature-controlled supply chains.
Pricing Analysis
Certification level creates the primary spread between IATF 16949-qualified structural grades and uncertified commodity formulations. Three-tier pricing structure across premium, standard, and economy levels reflects quality grade differentiation and volume scale, with battery pack integrators commanding lowest unit costs through co-development contracts. Cost compression in water-based interior segments is intensifying because REACH VOC limits force formulation redevelopment. Tier-1 suppliers exhibit lowest price sensitivity; aftermarket distributors in North America show highest.
Supply Chain Analysis
Inventory lead times for silane-modified polymer feedstocks stretch across 8-12 week procurement cycles from German and Chinese production hubs. Geographic supply concentrates in Germany, China, and Japan, with raw material dependencies on petrochemical-derived epoxy resins, polyurethane prepolymers, and acrylic monomers. Single-source vulnerability in Japanese latent-cure epoxy initiators threatens battery pack assembly continuity. Distribution runs through direct OEM technical partnerships displacing traditional tiered channels in South Korea and Sweden.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric vehicle battery pack integration represents a high-growth disruption as cell-to-pack architectures compress adhesive cure cycles from hours to minutes. MIIT dual carbon goals and REACH substance restrictions create simultaneous regulatory inflections reshaping formulation roadmaps.
For Market Incumbents: Secure captive resin capabilities through backward integration into silane-modified polymer feedstocks to defend margin position against Dow's upstream cost advantage. Lock in 18-24 month IATF 16949 certification renewal cycles before new entrants complete approval timelines. Prioritize acoustic-damping formulation patents as Korean and German premium OEMs specify NVH-integrated bonding systems.
For New Entrants and Emerging Players: Application-engineering co-development gaps in Indian PLI-subsidized manufacturing zones offer white-space positioning before Henkel and Sika establish local technical centers. Target commodity hot-melt interior formulations for Maruti Suzuki and Tata Motors assembly operations in Maharashtra and Tamil Nadu clusters. Pursue joint-venture structures with regional resin distributors to bypass ISO 9001 qualification barriers.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors UV-cured acrylic specialists with LED curing system integration capabilities. Long-term viability over a 5-10 year horizon rests on suppliers capturing cell-to-pack specification lock-in before platform standardization freezes adhesive selection. Watch Korean and Chinese battery pack integrator consolidation rates as the inflection signal for pricing power shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silane-Modified Polymers | Dow's upstream feedstock control secures cost positioning in Detroit-area supply chains. |
| UV-Cured Technology Convergence | LED curing integration with automated dispensing enables sub-minute cycle times at Hyundai Motor Group lines. |
| Acoustic-Damping Formulation Development | Sika AG's viscoelastic systems capture premium cabin specifications from BMW and Mercedes-Benz. |
| India Manufacturing Footprint Expansion | PLI scheme subsidies attract first-mover adhesive suppliers to Maharashtra EV clusters. |
| Direct OEM Technical Partnership | CATL and BYD procurement teams concentrate purchasing power through embedded application engineers. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with Tier 1 supplier procurement managers, OEM platform engineers, aftermarket distributors, and adhesive formulation chemists; and secondary validation through customs/trade data, SEC 10-K filings, ACC industry reports, and vehicle production databases. Bottom-up segment sizing triangulated against top-down market estimates derived from IHS Markit registration data and resin feedstock consumption patterns.
Across the analysis window, forecasts reflect analytical frameworks modeling segmentation by vehicle class, propulsion architecture, content per vehicle, and regional production cluster. CAGRs were derived from trend extrapolation of EV penetration rates and adhesive substitution ratios in multimaterial body-in-white assemblies, cross-referenced with MIIT dual carbon compliance timelines and REACH substance restriction implementation phases.
Underlying assumptions cover sustained EV production scaling and stable petrochemical feedstock availability, with deviation risk concentrated in epoxy resin price volatility and IATF 16949 certification timeline extensions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
United States Construction Adhesives and Sealants Market
Adhesives & Sealants
American Epoxy Adhesives Market
Adhesives & Sealants
Middle East & Africa Construction Adhesives & Sealants Market
Adhesives & Sealants
High Temperature Adhesives Market
Adhesives & Sealants
Marine Adhesives Market
Adhesives & Sealants
Epoxy Putty and Construction Chemicals Market
Adhesives & Sealants
Polyurethane (PU) Adhesives Market
Adhesives & Sealants
Timber Laminating Adhesives Market
Adhesives & Sealants
South America Polyurethane (PU) Adhesives Market
Adhesives & Sealants
Asia-Pacific Reactive Adhesives Market
Adhesives & Sealants
Elastic Bonding Adhesive and Sealant Market
Adhesives & Sealants
US Tile Adhesive Market
Adhesives & Sealants
Elastomeric Adhesive Market
Adhesives & Sealants
Cycloaliphatic Epoxy Market
Adhesives & Sealants
Light Curing Adhesives Market
Adhesives & Sealants
Europe Bone Glue Market