
 Coffee Capsules and Pod Packaging Market | 2026-2036
Coffee Capsules and Pod Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Coffee Capsules and Pod Packaging Market Outlook
Italy is rewriting competitive dynamics in coffee capsule manufacturing through expanded flexible packaging capacity and established espresso heritage. Nestlé S.A. leverages its Nespresso system to sustain premium positioning across European and North American channels. Amcor plc anchors global supply with multi-material barrier expertise for oxygen-sensitive coffee formats. Huhtamäki Oyj differentiates through fiber-based alternatives that respond to plastic reduction mandates.
Coffee capsules and pod packaging comprise sealed, single-dose containers engineered from aluminum, plastic, or compostable laminates with oxygen barrier properties exceeding 0.1 cc/m²/day to preserve volatile aromatic compounds during shelf storage. Modified Atmosphere Packaging technology dominates premium segments by flushing nitrogen to displace residual oxygen and extend roast freshness. Aluminum pods retain the largest value share due to infinite recyclability and superior flavor protection, though biodegradable capsules represent the fastest-expanding category as Extended Producer Responsibility schemes tighten across European markets. Home consumers generate the highest volume throughput, while coffee shops command richer per-unit margins through branded private-label programs.
The EU Green Deal, FDA food contact substance regulations, and Germany's national packaging law shape material selection and end-of-life obligations for capsule producers entering Western markets. ECHA's microplastics restriction proposal threatens conventional polypropylene formats, accelerating migration toward paper-based and bio-polymer constructions. Stakeholders must monitor evolving compostability certification standards and infrastructure readiness before committing capital to next-generation material platforms.
Market Dynamics
The EU Green Deal's packaging waste directives are forcing material transitions across the coffee capsule supply chain, compelling manufacturers to abandon multi-layer plastics and aluminum in favor of certified compostable laminates with equivalent oxygen barrier performance.
Growth Catalysts
- Single-serve hospitality consumption:Hotels and corporate pantries in Germany, Italy, and the United States are replacing batch brewing systems with pod-based equipment to reduce waste and labor costs.
- REACH-compliant bio-polmer innovation:ECHA's evolving substance restrictions are accelerating R&D investment in polylactic acid and polyhydroxyalkanoate formulations that meet food contact standards.
- Extended Producer Responsibility expansion:Germany's national packaging law mandates full cost internalization for end-of-life collection, creating competitive advantage for producers with established reverse logistics.
Market Restraints
- Aluminum price volatility:Primary aluminum ingot costs fluctuate with energy input prices, compressing margins for barrier-layer dependent formats.
- Composting infrastructure gaps:Industrial composting facility coverage remains sparse in Eastern European markets, limiting addressable demand for certified biodegradable capsules.
- Modified Atmosphere Packaging equipment concentration:Nitrogen-flushing machinery suppliers cluster in Northern Italy and Southern Germany, creating procurement bottlenecks.
Strategic Opportunities
- Office pantry channel expansion:Facility management providers in France and the Netherlands are consolidating coffee service contracts, creating volume aggregation points for private-label capsule programs.
- Home-compostable certification:TÜV Austria's OK compost HOME standard opens distribution in markets lacking industrial composting infrastructure.
- Smart brewing system integration:RFID-enabled capsules communicating brew parameters to connected machines enable usage-based subscription models and flavor customization.
Industry Challenges
- Barrier polymer formulation expertise:The intersection of food safety chemistry and polymer science creates hiring competition with pharmaceutical packaging sectors.
- Compostability certification timelines:Multi-month validation cycles for ASTM D6400 and EN 13432 compliance delay product launches and tie up working capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coffee Capsules and Pod Packaging Market |
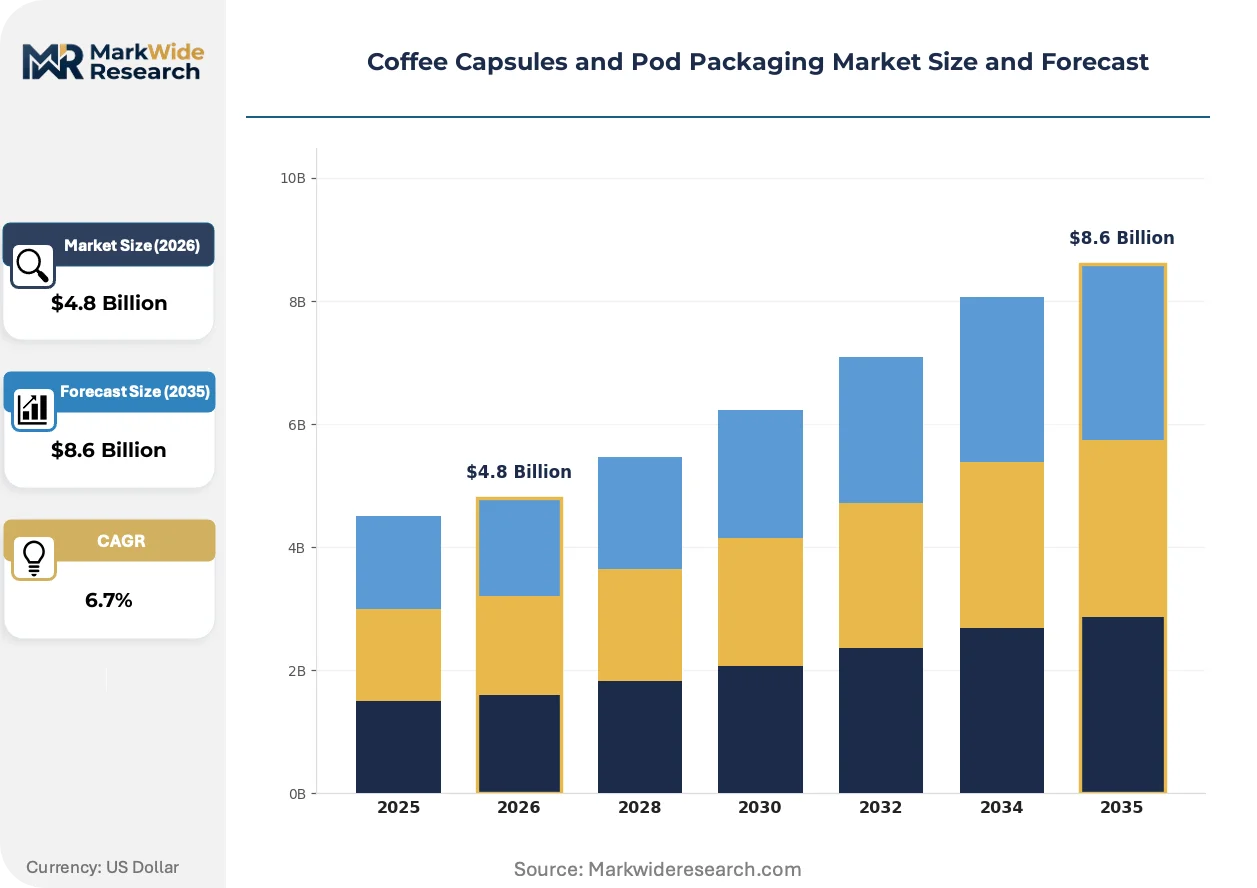
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic Capsules, Aluminum Pods, Biodegradable Capsules, Composite Pods Form: Single Serve, Multi Serve, Reusable Pods, Disposable Pods Technology: Traditional Packaging, Modified Atmosphere Packaging, Active Packaging, Vacuum Packaging End User: Coffee Shops, Retail Outlets, E-Commerce, Home Consumers |
| Companies Covered | Constantia Flexibles International GmbH, Nestlé S.A., Amcor plc, Lavazza Group, JDE Peet's N.V., Huhtamäki Oyj, Graphic Packaging International, LLC, Keurig Dr Pepper Inc., Sonoco Products Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coffee Capsules and Pod Packaging Market Strategic Shifts
Material science breakthroughs and regulatory compliance automation are converging to redefine competitive advantage in coffee capsule manufacturing, with sustainability credentials now functioning as primary purchase criteria rather than premium differentiators.
Barrier-coated fiber substrates are hybridizing oxygen protection with end-of-life biodegradability. Specialty coffee roasters in Scandinavia and the Pacific Northwest are adopting these laminates at pilot scale. The technology is hybridizing supply chain requirements, forcing converters to maintain parallel aluminum and fiber-based production lines.
The EU Green Deal's packaging waste directives are mandating minimum recycled content thresholds and extended producer responsibility fee modulation based on recyclability scores. This is reallocating capital toward mono-material and fiber-based formats. Premium at-home segments in Germany and the Netherlands are absorbing compliance costs through price premiums.
Direct-to-consumer subscription models are consolidating purchasing decisions away from retail shelf selection toward algorithm-driven flavor curation. Roasters in Italy and the United States are bypassing traditional grocery distribution to capture lifetime value through recurring revenue. This pattern concentrates most visibly in urban centers with established specialty coffee culture and reliable last-mile logistics.
Coffee Capsules and Pod Packaging Market Segmentation
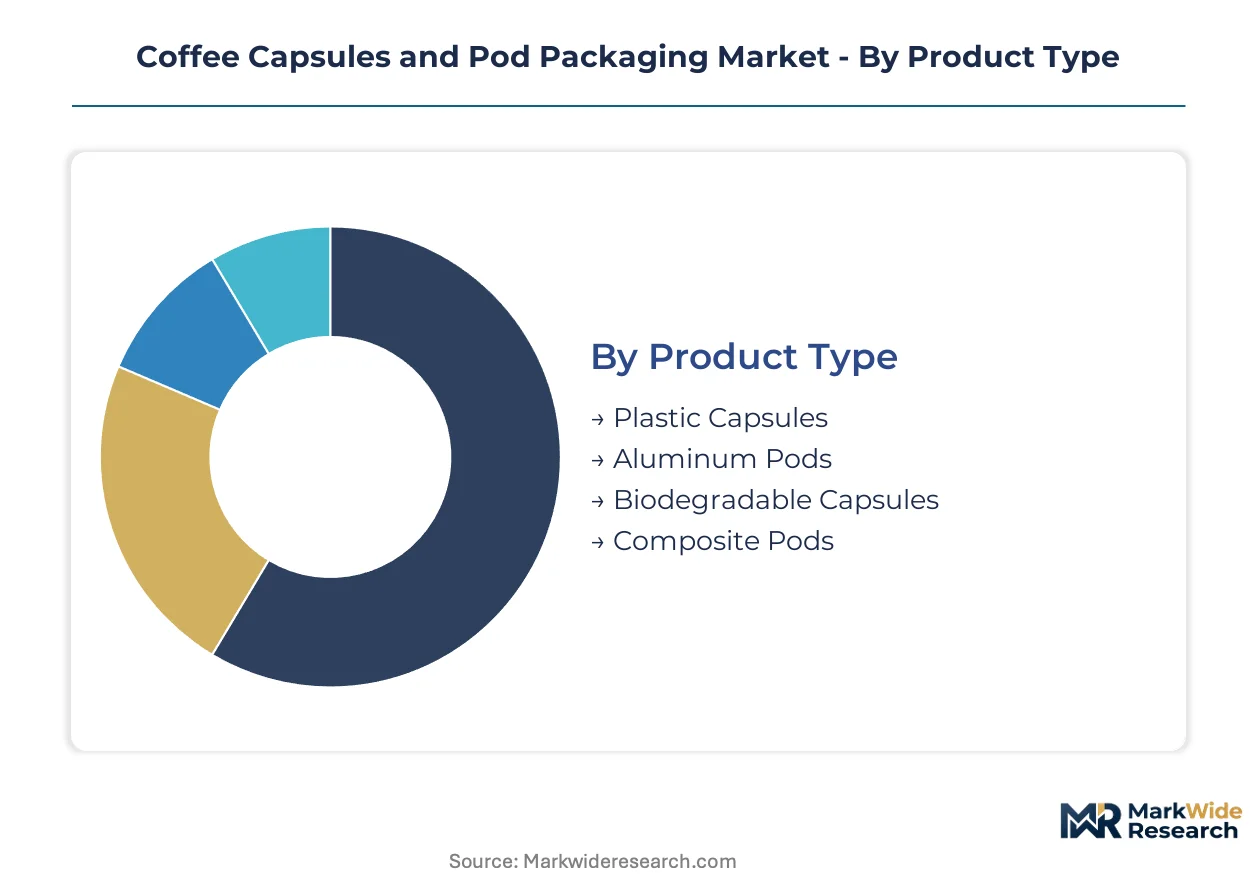
Material selection and packaging format choices in coffee capsules determine oxygen barrier performance, end-of-life compliance costs, and channel access. Segmentation reveals where premium pricing power concentrates versus where volume throughput dominates procurement economics.
Product Type:
Inventory velocity varies dramatically by material platform, with aluminum and plastic formats turning on weekly replenishment cycles while biodegradable alternatives face longer adoption timelines due to certification requirements.
- Plastic Capsules:Polypropylene and polystyrene constructions dominate mass-market retail through cost-efficient thermoforming and injection molding. German and Italian supermarkets source these formats for private-label programs where price positioning trumps sustainability credentials.
- Aluminum Pods:Drawn aluminum shells with integrated membranes deliver infinite recyclability and sub-0.1 cc/m²/day oxygen transmission rates. Premium roasters in Switzerland and Austria specify these for high-altitude-grown arabica preservation despite energy-intensive production.
- Biodegradable Capsules:Polylactic acid and polyhydroxyalkanoate laminates certified to EN 13432 standards.
- Composite Pods:Multi-layer plastic-aluminum hybrids facing regulatory pressure under EU Green Deal recyclability mandates.
Aluminum pods anchor the volume base while biodegradable capsules gain share at the steepest rate.
Form:
Consumption occasion and equipment compatibility segment the market into convenience-driven disposables versus sustainability-oriented reusables, with subscription economics favoring different formats across channels.
- Single Serve:Individually sealed 5-12 gram doses compatible with Nespresso, Keurig, and proprietary brewing systems. Office pantry providers in the Netherlands and France aggregate demand through facility management contracts.
- Reusable Pods:Stainless steel or silicone shells requiring consumer-filled ground coffee. Scandinavian specialty coffee enthusiasts drive adoption where roast freshness customization outweighs convenience tradeoffs.
- Multi Serve:Larger format pods for hospitality batch brewing.
- Disposable Pods:Single-use convenience formats without reusability infrastructure.
Single serve commands the installed equipment base while reusable pods climb the fastest among sustainability-motivated segments.
Technology:
Preservation science investment separates commodity converters from premium-positioned suppliers, with gas-flushing capabilities requiring specialized capital equipment concentrated in Northern Italy.
- Modified Atmosphere Packaging:Nitrogen displacement systems achieving residual oxygen below 1% to extend volatile aromatic compound retention. Italian roasting houses deploy MAP for single-origin espresso capsules distributed through Milan and Turin retail networks.
- Traditional Packaging:Ambient atmosphere sealing without active gas management. Commodity producers in Eastern European markets employ these methods for cost-sensitive retail channels where shelf life requirements remain modest.
- Active Packaging:Oxygen scavenger integration within capsule walls or secondary packaging.
- Vacuum Packaging:Pre-roast green bean preservation and select ground coffee applications.
Traditional packaging holds the volume foundation while Modified Atmosphere Packaging expands most quickly in premium at-home segments.
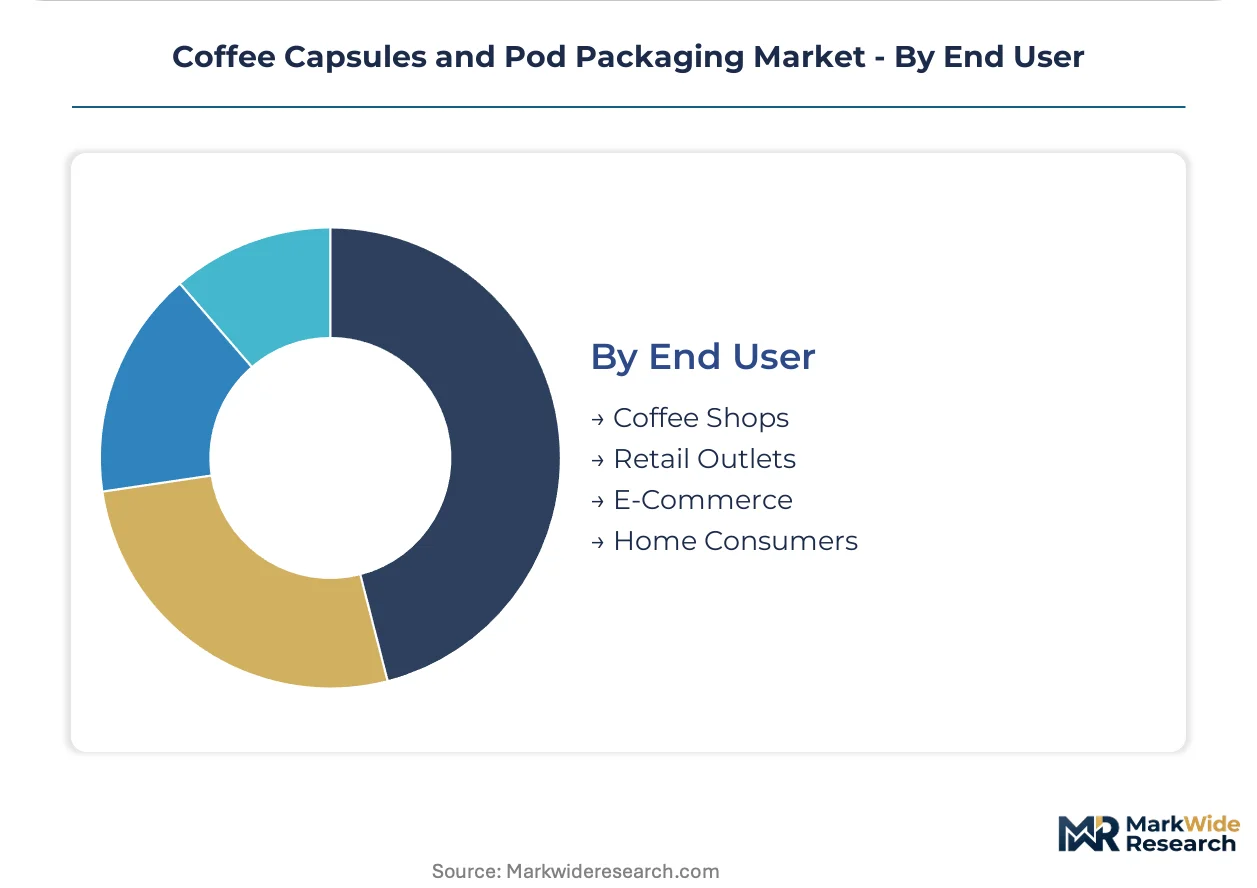
End User:
Channel economics diverge sharply between high-frequency home consumption and commercial accounts demanding branded customization with richer per-unit margins.
- Home Consumers:Individual households purchasing through grocery retail, specialty roaster direct channels, and e-commerce subscriptions. Urban centers in Germany and the United States concentrate demand for premium single-origin capsules with provenance storytelling.
- Coffee Shops:Independent cafés and regional chains sourcing private-label capsules for retail resale and loyalty program integration. Italian roasting cooperatives supply these accounts with customized artwork and seasonal limited editions.
- Retail Outlets:Supermarkets and hypermarkets carrying branded and private-label assortments.
- E-Commerce:Direct-to-consumer platforms and marketplace aggregators.
Home consumers generate the highest throughput volumes while coffee shops deliver the steepest margin expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal anchors European regulatory pressure on material transitions, while single-serve consumption patterns concentrate manufacturing investment in Germany, Italy, and the United States. National packaging laws and extended producer responsibility schemes are reshaping where converters locate compostable laminate capacity.
Germany
Corporate pantry contracts and facility management consolidation drive volume demand in Frankfurt and Munich metropolitan areas. The national packaging law mandates full cost internalization for end-of-life collection, advantaging producers with established reverse logistics networks. Bavaria hosts nitrogen-flushing machinery clusters serving premium roasting houses.
Italy
Single-origin espresso culture and heritage roasting infrastructure sustain demand for high-barrier aluminum formats in Milan and Turin. ECHA's evolving substance restrictions accelerate migration toward EN 13432-certified compostable alternatives. Northern Italian flexible packaging converters are expanding fiber-based laminate capacity to serve Scandinavian export markets.
United States
Direct-to-consumer subscription models and specialty coffee culture concentrate demand in Seattle, Portland, and New York urban corridors. FDA food contact substance regulations shape bio-polymer formulation requirements for polylactic acid capsules. Pacific Northwest roasting cooperatives are piloting home-compostable certification programs.
Netherlands
Office pantry channel aggregation and facility management provider consolidation create volume concentration in Amsterdam and Rotterdam logistics hubs. Extended producer responsibility fee modulation based on recyclability scores reallocates capital toward mono-material formats. Dutch converters are investing in parallel aluminum and fiber-based production lines.
Switzerland
Premium at-home brewing culture and high-altitude arabica preservation requirements sustain aluminum pod demand in Zurich and Geneva retail networks. Swissmedic-aligned food safety standards exceed baseline EU requirements for barrier polymer migration limits. Alpine roasting houses specify sub-0.1 cc/m²/day oxygen transmission rates for limited-edition releases.
Coffee Capsules and Pod Packaging Market Competitive Environment
Capability concentration sits with barrier polymer specialists and modified atmosphere packaging equipment providers; scale advantage sits with multi-material converters and vertically integrated roasting houses. The market structures around three tiers: global packaging conglomerates with aluminum and fiber-based platforms, regional flexible packaging specialists serving private-label programs, and captive roasting house operations with proprietary capsule systems. Dominant competitive moves include capacity expansion in certified compostable laminates and strategic partnerships between converters and industrial composting facility operators.
Within the global packaging tier, Amcor plc and Huhtamäki Oyj exemplify divergent material strategies—one anchored in multi-material barrier expertise, the other in fiber-based alternatives responding to plastic reduction mandates. Nestlé S.A. occupies a position as a vertically integrated roasting house with proprietary system control. Constantia Flexibles International GmbH represents the European flexible packaging specialist archetype serving branded and private-label accounts across German and Italian markets.
| Leading Market Players |
|---|
| Constantia Flexibles International GmbH |
| Nestlé S.A. |
| Amcor plc |
| Lavazza Group |
| JDE Peet's N.V. |
| Huhtamäki Oyj |
| Graphic Packaging International, LLC |
| Keurig Dr Pepper Inc. |
| Sonoco Products Company |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Eastern European thermoforming facilities is compressing converter margins and forcing price concessions to German and Italian buyers seeking volume commitments for private-label programs. This utilization imbalance simultaneously pressures suppliers to absorb aluminum ingot volatility while buyers consolidate procurement through facility management contracts.
Pricing Analysis
German supermarket buyers pay 15-20% premiums versus Eastern European procurement for identical polypropylene capsules due to extended producer responsibility fee modulation and logistics proximity to nitrogen-flushing equipment clusters. Three-tier pricing structure across premium aluminum, certified compostable, and commodity plastic levels stratifies by barrier performance and end-of-life compliance cost. Pricing pressure stems from aluminum ingot cost volatility and converter overcapacity in thermoforming. Mass-market retail channels exhibit highest price sensitivity, while Swiss and Austrian premium roasters absorb premiums for sub-0.1 cc/m²/day oxygen transmission specifications.
Supply Chain Analysis
Tariff exposure between Chinese bio-polymer feedstock suppliers and European converters dominates supply chain risk planning as polylactic acid and polyhydroxyalkanoate formulations face customs scrutiny under evolving EU Green Deal substance restrictions. Manufacturing concentrates in Germany, Italy, and the Netherlands, with Bavaria and Northern Italy hosting nitrogen-flushing machinery clusters. Raw material dependencies center on primary aluminum ingot, food-grade polypropylene resin, and certified compostable laminates. Single-source vulnerability persists for modified atmosphere packaging equipment sourced from Northern Italian specialists. Distribution runs through facility management providers consolidating office pantry contracts in France and the Netherlands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward facility management consolidators and direct-to-consumer subscription platforms, fragmenting traditional retail procurement influence and concentrating volume aggregation in fewer purchasing decision-makers.
For Market Incumbents: Pre-empt private-label disintermediation by deepening backward integration into compostable laminate production and securing TÜV Austria OK compost HOME certification ahead of industrial composting infrastructure gaps in Eastern Europe. Capacity addition in fiber-based platforms near Scandinavian export markets defends margin position against Huhtamäki Oyj's established bio-polymer positioning.
For New Entrants and Emerging Players: Build out home-compostable capsule supply to Pacific Northwest roasting cooperatives piloting direct-to-consumer subscription models, where algorithm-driven flavor curation bypasses traditional grocery slotting fees. Target office pantry channel aggregation in the Netherlands and France through facility management provider contracts, penetrating the most consolidatable volume segment with private-label programs.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among direct-to-consumer subscription platforms and proprietary brewing system operators, suggesting long-term viability rests on customer lifetime value capture rather than transactional retail throughput. Acquisition target archetype: regional flexible packaging specialists with EN 13432 certification capabilities and established relationships with Italian roasting cooperatives. Signal to watch: industrial composting facility coverage expansion rates in Eastern European markets as inflection indicator for biodegradable capsule demand maturation.
| Strategic Initiative | Industry Significance |
|---|---|
| Compostable Laminate Capacity Expansion | EN 13432-certified production lines in Northern Italy serve Scandinavian export demand under EU Green Deal mandates. |
| Backward Integration into Bio-Polymer Feedstock | Polylactic acid formulation control reduces ECHA substance restriction exposure and secures REACH-compliant supply. |
| Direct-to-Consumer Platform Launch | Algorithm-driven subscription models in Seattle and Portland bypass grocery retail slotting fees and capture lifetime value. |
| Facility Management Partnership | Consolidated office pantry contracts in Amsterdam and Rotterdam aggregate volume for private-label capsule programs. |
| Home-Compostable Certification Investment | TÜV Austria OK compost HOME standard opens distribution in markets lacking industrial composting infrastructure. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with roasting house procurement directors, flexible packaging plant managers, facility management category buyers, nitrogen-flushing equipment specialists, and industrial composting facility operators. Secondary validation drew from EU Green Deal directive texts, ECHA substance restriction proposals, German national packaging law implementing regulations, FDA food contact substance guidance, and customs trade data for bio-polymer feedstock flows. Bottom-up segment sizing triangulated against top-down market value estimates across material platforms and end-use channels.
Calibration against historical aluminum price volatility patterns and composting infrastructure deployment timelines anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include material platform, packaging format, preservation technology tier, end-use channel, and regional regulatory cluster. CAGRs were derived from installed equipment base growth, single-serve hospitality adoption curves, and compliance cost pass-through elasticity. Forecast inputs incorporated EPR fee modulation schedules and nitrogen-flushing machinery supplier capacity constraints.
Stress conditions across aluminum ingot price bands, industrial composting facility coverage expansion rates, and bio-polymer certification timeline delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding EU Green Deal implementation pacing and ECHA substance restriction finalization. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Packaging
Fresh Produce Trays Market
Food Packaging
Global Disposable Tableware Market
Food Packaging
Poultry Packaging Market
Food Packaging
Europe Chocolate Packaging Market
Food Packaging
Canada Disposable Tableware Market
Food Packaging
Pizza Box Market
Food Packaging
Probiotics Packaging Market
Food Packaging
Insulated Food and Beverage Carriers Market
Food Packaging
APAC Frozen Food Packaging Market
Food Packaging
Frozen Seafood Packaging Market
Food Packaging
Flexible Frozen Food Packaging Market
Food Packaging
On-The-Go Breakfast Packaging Market
Food Packaging
Produce Packaging Market
Food Packaging
Seafood Packaging Market
Food Packaging
Reclosable Food Packaging Market
Food Packaging
Processed Meat Packaging Market