
 Flexible Frozen Food Packaging Market | 2026-2036
Flexible Frozen Food Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Flexible Frozen Food Packaging Market Foresight
The split between premium high-barrier laminates and commodity polyethylene pouches is realigning procurement patterns across the frozen food supply chain. Amcor plc leverages its global film manufacturing footprint to sustain multi-layer barrier leadership for seafood and ready meal applications. Sealed Air Corporation anchors North American demand through vacuum-seal technology specialization in protein packaging. Mondi Group competes with kraft-paper-based flexible solutions that target retailer sustainability mandates.
Flexible frozen food packaging comprises polymer-based or laminate films engineered to withstand temperatures as low as minus forty degrees Celsius while blocking moisture vapor transmission and oxygen ingress. These structures typically incorporate oriented polypropylene, polyethylene terephthalate, or aluminum foil layers coextruded or adhesive-laminated to prevent freezer burn and extend shelf life for temperature-sensitive food products. Laminates and foil segments command margin pools where barrier performance justifies material cost premiums for meat and poultry applications. Pouches and vacuum seals represent the fastest-growing packaging types as portion-control formats gain traction among single-person households and foodservice providers. Biodegradable films remain nascent but attract R&D investment from converters anticipating extended producer responsibility frameworks.
The FDA governs food contact substance compliance under 21 CFR while the EPA tracks fluorinated greenhouse gas emissions from barrier film production, tightening specifications for domestic converters. The EU Green Deal and REACH restrict certain adhesive chemistries and mandate recyclability targets that reshape laminate design priorities for export-oriented suppliers. Stakeholders must monitor how California's SB 54 implementation and emerging state-level extended producer responsibility laws alter material specifications ahead of federal harmonization efforts.
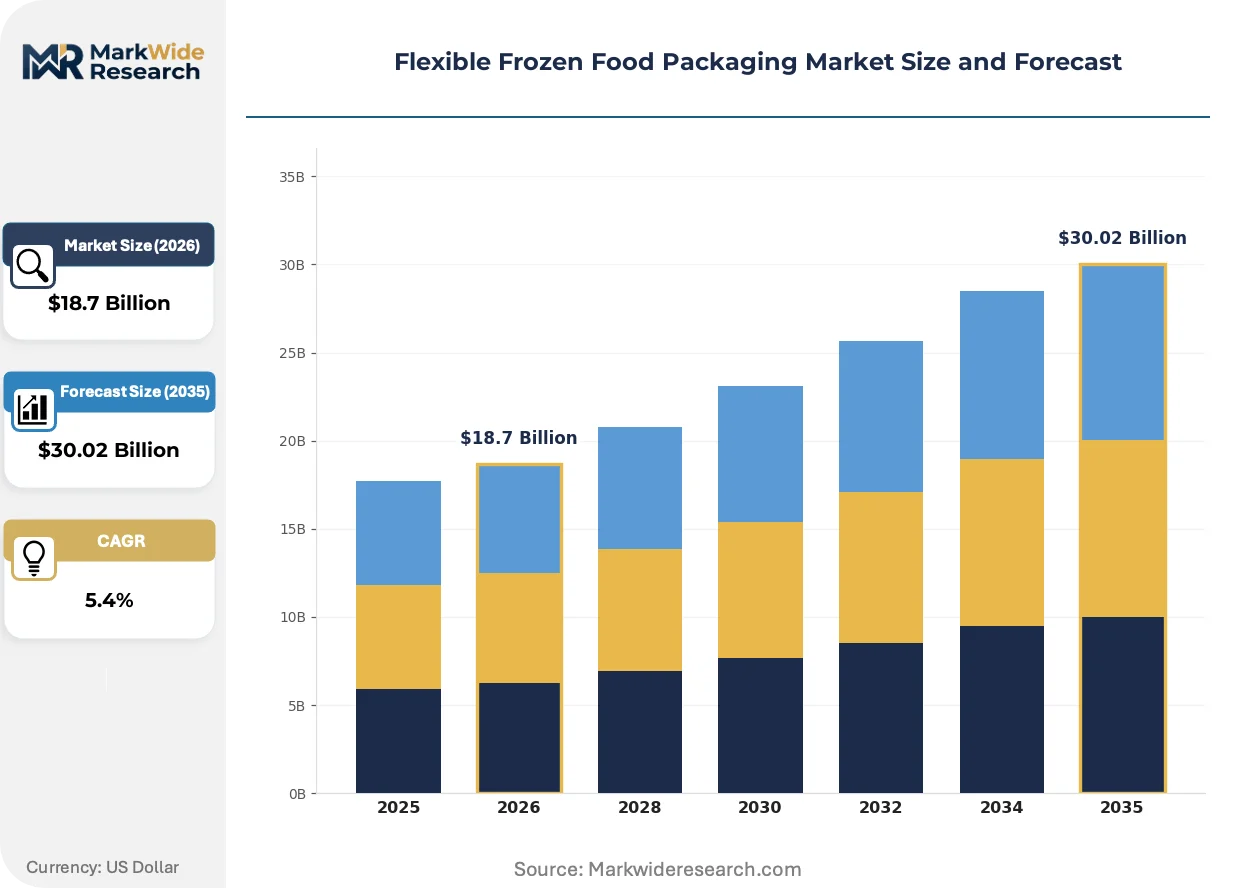
Market Dynamics
EU F-Gas Regulation and the Green Deal are compressing laminate design cycles as converters abandon high-global-warming-potential barrier chemistries ahead of 2030 phase-down mandates.
Growth Catalysts
- EU Green Deal packaging recyclability targets:Retailers in Germany and France now specify mono-material or paper-integrated laminates, pulling converter R&D spend toward approved structures.
- Single-person household formation:Frozen ready meal pouches sized for one-serve portions capture shelf space previously allocated to bulk formats in urban markets.
- Seafood export cold chain expansion:Vietnamese and Norwegian processors invest in high-barrier vacuum seals to extend shelf life through multi-modal transit to EU distribution centers.
Market Restraints
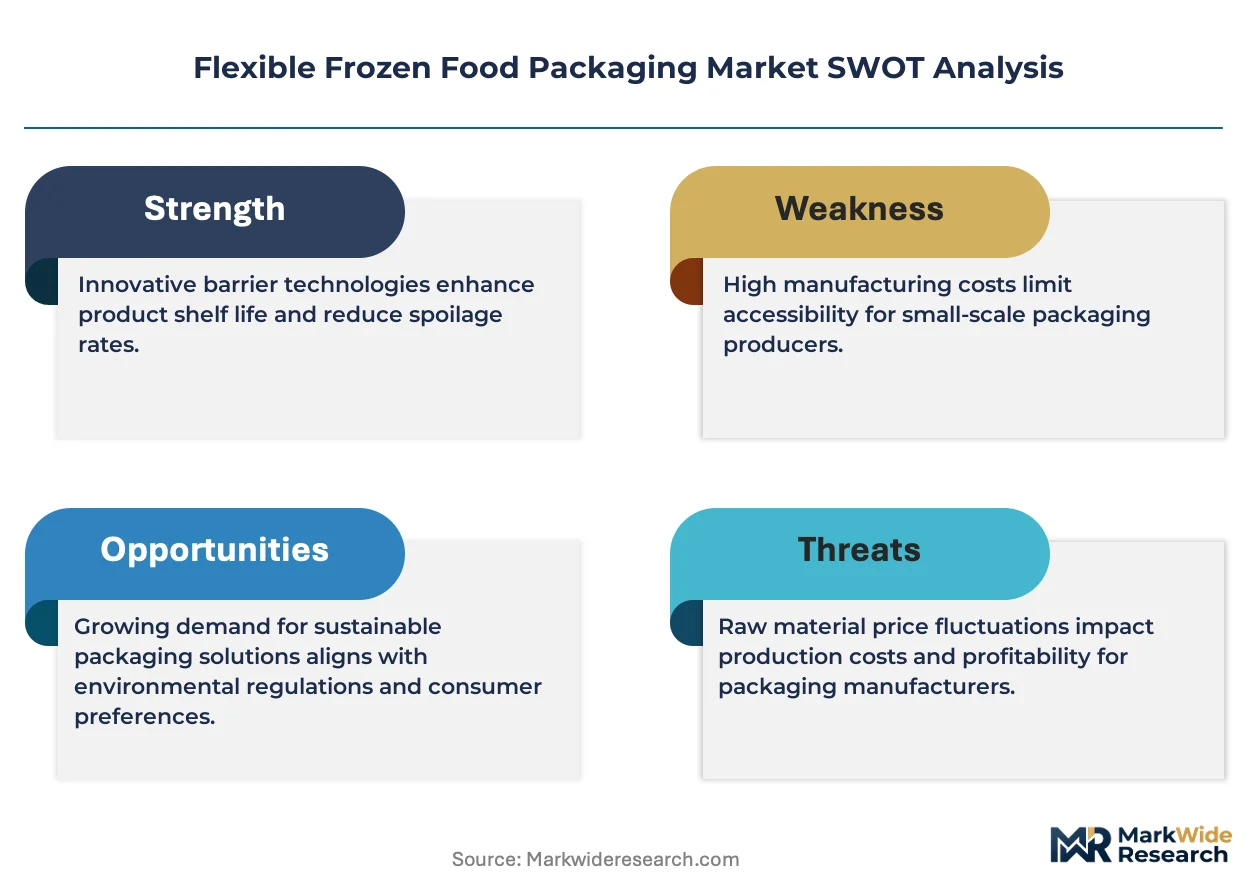
- Aluminum foil supply concentration:European smelter curtailments and Chinese export quotas inflate input costs for multi-layer meat and poultry barrier structures.
- Adhesive chemistry restrictions under REACH:Certain solvent-based laminating adhesives face authorization sunset dates, forcing reformulation validation cycles.
- Mechanical recycling incompatibility:Current multi-material laminates fail near-infrared sortation at materials recovery facilities, limiting post-consumer feedstock availability.
Strategic Opportunities
- India cold chain infrastructure build-out:Government PLI scheme subsidies for food processing parks create first-mover advantage for pouch converters establishing local extrusion capacity.
- Retailer private-label sustainability mandates:UK and Dutch supermarket chains now require recyclable or certified-compostable frozen vegetable packaging by 2027.
- Digital printing convergence with short-run flexible formats:SKU proliferation in ethnic frozen foods enables just-in-time production without plate costs.
Industry Challenges
- Barrier performance validation for novel mono-materials:Replacing aluminum foil with metallized polymer or oxide coatings requires 18-24 month shelf-life testing protocols.
- Extrusion equipment reconfiguration:Shifting from three-layer to five-layer coextrusion lines demands capital deployment and specialized technician training.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flexible Frozen Food Packaging Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $30.02 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Polyethylene, Polypropylene, Laminates, Foil, Biodegradable Films Packaging Type: Pouches, Bags, Films, Trays, Vacuum Seals Application: Vegetables, Meat & Poultry, Seafood, Ready Meals, Desserts End User: Food Processors, Cold Storage Operators, Retail Chains, Foodservice Providers |
| Companies Covered | Amcor plc, Sealed Air Corporation, Mondi Group, Huhtamaki Oyj, Berry Global Group, Inc., ProAmpac LLC, Smurfit Westrock, Constantia Flexibles Group GmbH, Coveris Holdings S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flexible Frozen Food Packaging Market Shifts & Advancements
Barrier technology, regulatory chemistry restrictions, and retail procurement specifications are simultaneously rewriting material selection criteria and converter competitive positioning.
High-barrier metallized polyethylene terephthalate films are converging with water-based adhesive lamination systems to eliminate solvent recovery infrastructure. Frozen seafood processors in Norway and Chile adopt these structures to maintain oxygen transmission rates below 0.1 cc/m²/day while satisfying retailer sustainability scorecards. The technology is converging with existing form-fill-seal lines, compressing capital requirements for mid-tier converters.
The EU F-Gas Regulation mandates 95% phase-down of hydrofluorocarbon blowing agents and propellants by 2030, directly affecting foam tray and insulated pouch production. Converters serving the ready meal segment reformulate thermal barriers using vacuum-insulated panels or cellulose fiber alternatives. German and French frozen food brands accelerate qualification timelines to avoid supply disruption during the 2027-2029 compliance cliff.
Foodservice distributors now specify portion-controlled, cook-in-bag formats for healthcare and institutional catering contracts. Single-serve vacuum-sealed protein portions displace bulk poly-lined corrugated cases in hospital and airline supply chains. This specification shift concentrates procurement volume with converters holding BRCGS and ISO 22000 certifications across North American and Western European markets.
Flexible Frozen Food Packaging Market Segmentation
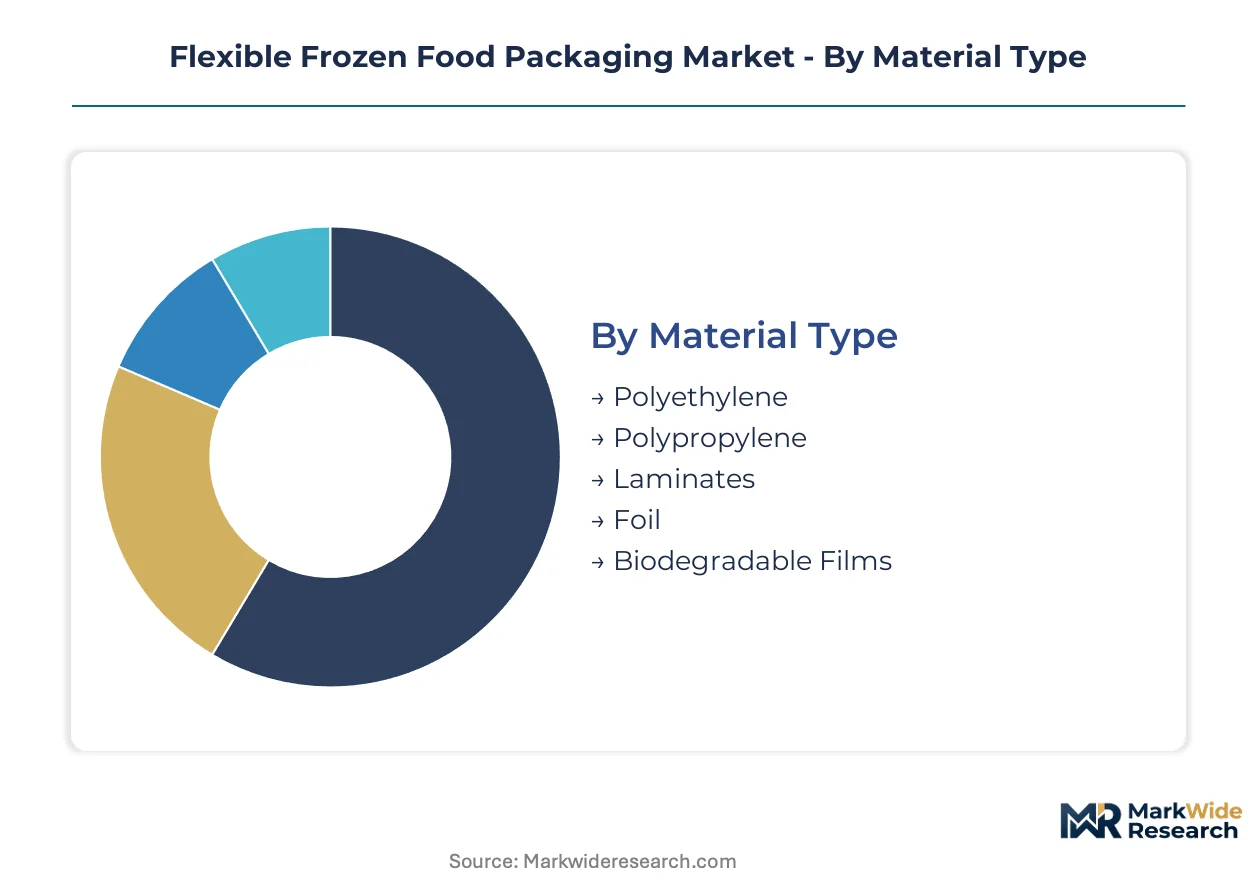
Material selection and format specification in frozen food packaging determine cold chain integrity, shelf-life extension, and compliance with emerging recyclability mandates. Procurement patterns diverge sharply between premium barrier laminates and commodity polyethylene structures as retailers impose sustainability scorecards.
Material Type:
Capital intensity escalates from commodity extrusion through metallized coextrusion to solvent-free lamination lines requiring environmental controls.
- Laminates:Multi-layer adhesive or extrusion-bonded structures combining oriented polypropylene, polyethylene terephthalate, and aluminum foil to achieve oxygen transmission rates below 0.1 cc/m²/day. German and French retailers now mandate mono-material or paper-integrated laminates, pulling converter R&D spend toward approved structures under EU Green Deal packaging recyclability targets.
- Foil:Aluminum barrier layers laminated to polymer substrates for meat and poultry applications where light and oxygen exclusion justifies material cost premiums. European smelter curtailments and Chinese export quotas inflate input costs, compressing margins for multi-layer barrier converters.
- Polyethylene:Linear low-density and high-density grades dominate commodity frozen vegetable bags through blown film extrusion at lower capital thresholds.
- Polypropylene:Biaxially oriented and cast films provide clarity and moisture resistance for overwrap applications in retail display cases.
- Biodegradable Films:Polylactic acid and starch-based alternatives remain nascent but attract investment from converters anticipating extended producer responsibility frameworks in UK and Dutch markets.
Most installed capacity flows through Polyethylene. Expansion is steepest in Laminates as barrier performance requirements intensify.
Packaging Type:
Format selection tracks end-use automation levels, with form-fill-seal compatibility driving standardization across food processor procurement specifications.
- Pouches:Stand-up and flat formats with resealable zipper features dominate frozen ready meal segments as single-person household formation accelerates demand for one-serve portions in urban markets.
- Vacuum Seals:Thermoformed and flow-wrapped structures remove atmospheric oxygen to extend protein shelf life through multi-modal transit. Norwegian and Chilean seafood processors adopt metallized polyethylene terephthalate vacuum seals to maintain barrier performance while satisfying retailer sustainability scorecards.
- Bags:Side-gusseted and wicketed formats serve bulk frozen vegetable distribution through wholesale club channels.
- Films:Shrink and stretch overwrap solutions protect palletized loads during frozen distribution.
- Trays:Thermoformed polypropylene and polyethylene terephthalate structures with lidding film compatibility target premium ready meal presentation.
Volume concentrates in Bags for commodity vegetables. Steepest expansion trajectory belongs to Vacuum Seals as cold chain export distances lengthen.
Application:
Barrier specification intensity correlates with protein oxidation sensitivity and retail price points across frozen food categories.
- Ready Meals:Multi-component trays and pouches requiring microwave compatibility and sauce containment drive laminate complexity as foodservice distributors specify cook-in-bag formats for healthcare and institutional catering contracts.
- Seafood:High-barrier vacuum seals with ice-glaze compatibility prevent dehydration and rancidity through extended marine transit from Vietnamese and Norwegian processing centers to EU distribution hubs.
- Meat & Poultry:Oxygen-scavenging films and modified atmosphere structures preserve color and delay microbial growth in retail case-ready formats.
- Vegetables:Perforated and macro-perforated films balance moisture control with respiration requirements for blanched and IQF products.
- Desserts:High-clarity films with anti-fog coatings maintain visual appeal for frozen bakery and ice cream novelties.
Revenue pools concentrate in Ready Meals. Gaining share fastest is Seafood as export cold chain infrastructure expands.
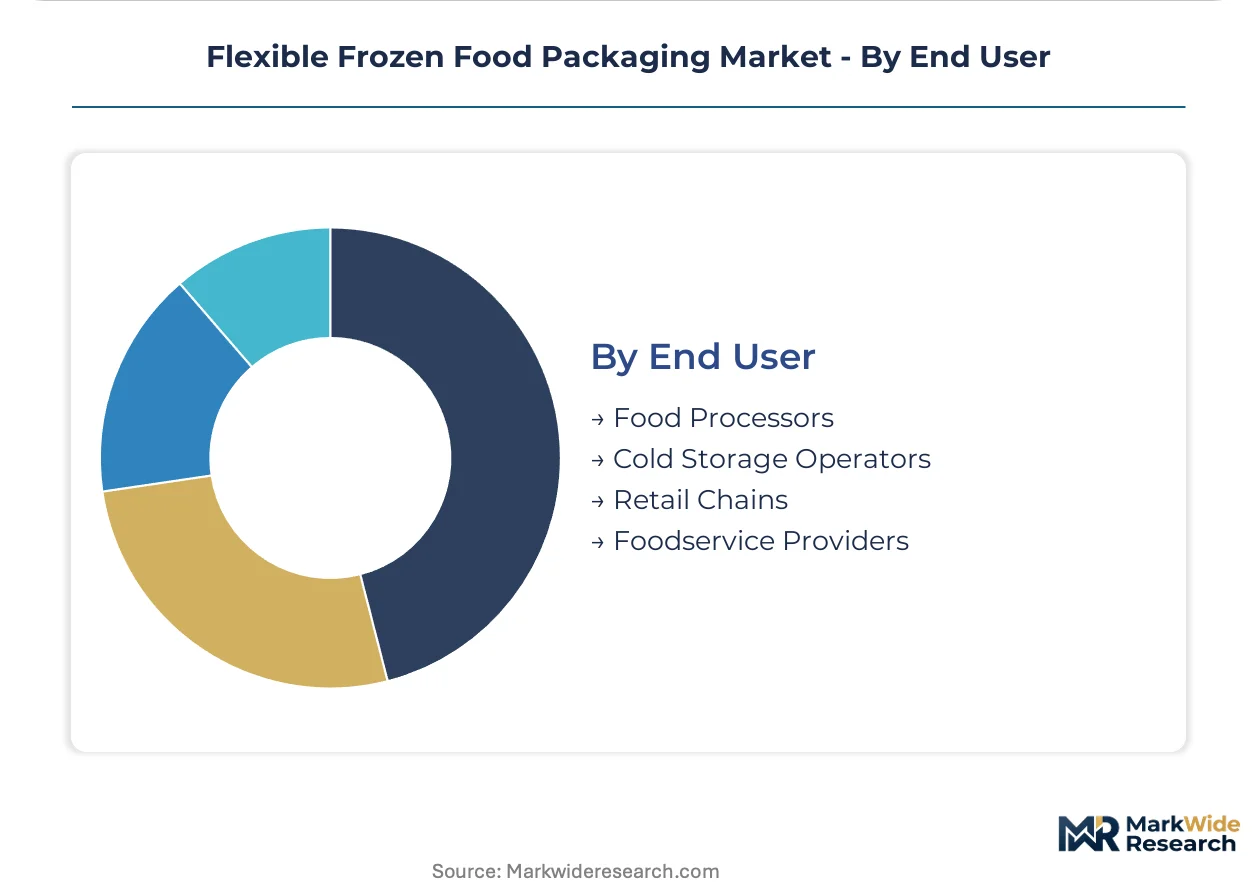
End User:
Certification requirements and volume scale separate procurement specifications across the frozen food value chain.
- Retail Chains:Private-label sustainability mandates from UK and Dutch supermarket chains now require recyclable or certified-compostable frozen vegetable packaging, forcing converter qualification cycles.
- Food Processors:Integrated packaging operations and toll manufacturing relationships drive specifications for high-speed form-fill-seal compatibility and SKU flexibility.
- Foodservice Providers:Portion-control and cook-in-bag specifications concentrate procurement with converters holding BRCGS and ISO 22000 certifications.
- Cold Storage Operators:Pallet-level containment and inventory tracking requirements influence secondary packaging selections.
Procurement volume aggregates at Food Processors. Specification tightening is most pronounced at Retail Chains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Packaging engineers and cold chain logistics specialists cluster in Germany, the United States, and China, anchoring regional innovation hubs for barrier film development and frozen food distribution infrastructure.
Germany
Private-label penetration and retailer sustainability mandates drive laminate specification changes across frozen ready meal segments. The EU F-Gas Regulation and Green Deal packaging recyclability targets force converters to abandon high-global-warming-potential barrier chemistries ahead of 2030 deadlines. The Rhine-Ruhr industrial corridor hosts extrusion and lamination facilities serving pan-European frozen food brands.
United States
Foodservice distributor consolidation and healthcare institutional catering contracts expand demand for portion-controlled cook-in-bag formats. FDA food contact substance compliance under 21 CFR and emerging state-level extended producer responsibility laws reshape material specifications ahead of federal harmonization. The Midwest manufacturing belt concentrates blown film extrusion capacity for commodity frozen vegetable applications.
China
Domestic cold chain infrastructure investment and seafood export processing expansion sustain demand for high-barrier vacuum seals. SAMR food contact material standards and dual carbon goals pressure converters toward lower-emission lamination processes. The Yangtze River Delta clusters metallized film coating facilities serving both domestic frozen food brands and export-oriented processors.
India
Government PLI scheme subsidies for food processing parks create first-mover opportunities for pouch converters establishing local extrusion capacity. FSSAI food safety regulations and BIS packaging standards govern material approval timelines for frozen food applications. Maharashtra and Gujarat host emerging flexible packaging manufacturing zones targeting domestic retail chain procurement.
Vietnam
Seafood export cold chain expansion to EU distribution centers drives investment in high-barrier vacuum seal qualification. National technical regulations on food packaging materials align with EU import requirements for frozen pangasius and shrimp shipments. The Mekong Delta processing corridor anchors barrier film specification discussions between exporters and European retail buyers.
Flexible Frozen Food Packaging Market Competitive Landscape
Top-tier vendors anchor multi-layer barrier technology leadership, while mid-tier converters compete on regional proximity and sustainability certification speed. The vendor base stratifies across integrated film manufacturers, specialized laminators, and paper-based flexible solution providers. Three archetypes dominate: global film extruders with captive resin supply, regional converters with retailer sustainability partnerships, and paper-integrated specialists targeting mono-material mandates. Competitive moves concentrate on M&A for barrier technology access and capacity expansion in high-growth Asian markets.
Within the integrated multinational tier, Amcor plc and Sealed Air Corporation exemplify scale-driven positioning across film manufacturing and vacuum-seal technology domains. Mondi Group occupies a distinct archetype as a paper-integrated flexible solution provider targeting retailer sustainability scorecards. These three entities represent contrasting strategic postures—global extrusion dominance, North American protein packaging specialization, and kraft-paper-based laminate innovation—without implying specific market share or financial performance claims.
| Leading Market Players |
|---|
| Amcor plc |
| Sealed Air Corporation |
| Mondi Group |
| Huhtamaki Oyj |
| Berry Global Group, Inc. |
| ProAmpac LLC |
| Smurfit Westrock |
| Constantia Flexibles Group GmbH |
| Coveris Holdings S.A. |
| Others |
Supply & Pricing Matrix
Extrusion technician clusters in Germany's Rhine-Ruhr corridor and China's Yangtze River Delta create labor-cost differentials that widen spreads between premium barrier laminates and commodity polyethylene structures. German converters command margin premiums for solvent-free lamination expertise while Chinese manufacturers compete on scale economics for standard frozen vegetable bags.
Pricing Analysis
Bundled toll-manufacturing contracts with integrated resin supply dominate premium tier transactions, while unbundled spot purchasing of commodity films persists among mid-tier food processors. Three-tier pricing structure across premium, standard, and economy levels separates multi-layer barrier laminates with aluminum foil from metallized polymer alternatives and basic polyethylene extrusions. Cost compression in standard-tier pouches is intensifying because European smelter curtailments inflate aluminum input costs. Foodservice distributors show least price sensitivity due to specification-locked healthcare contracts, while private-label vegetable processors negotiate aggressively on volume.
Supply Chain Analysis
Direct-to-processor channels handle high-volume ready meal and seafood processor demand, while distributor-mediated supply serves fragmented foodservice operators. Raw material supply draws from Saudi Arabia and Russia for polymer feedstocks, China for metallized film coating capacity, and Germany for precision lamination equipment. Single-source vulnerability concentrates in aluminum foil rolling capacity following European energy-driven curtailments. Distribution runs through cold storage logistics networks anchored in Rotterdam, Chicago, and Shanghai.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The flexible frozen food packaging market reads as a late-cycle quality story where retailer sustainability mandates and EU F-Gas Regulation compliance are concentrating procurement with converters holding certified mono-material capabilities.
For Market Incumbents: Extend barrier technology leadership through captive metallized film coating capacity in Vietnam and Norway to capture seafood export growth. Accelerate solvent-free adhesive validation cycles ahead of REACH authorization sunset dates. Defend margin position by locking long-term toll-manufacturing contracts with integrated resin supply. For New Entrants and Emerging Players: Foodservice distributor partnerships offer the most penetrable channel for portion-controlled cook-in-bag formats targeting healthcare and institutional catering contracts. White-space exists in India's emerging extrusion capacity serving domestic retail chain procurement under PLI scheme subsidies. Lead with BRCGS and ISO 22000 certification speed to differentiate against established players. For Investors and Strategic Acquirers: Specialty chemical conglomerates with adhesive and coating divisions are the most active acquirer in this space, seeking backward integration into film lamination. Target converters holding validated mono-material structures under EU Green Deal recyclability frameworks. Watch for inflection in retailer private-label sustainability mandate timelines as signal for premium laminate demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Laminate Qualification | EU Green Deal recyclability targets force 18-24 month validation cycles for aluminum-foil replacements. |
| Solvent-Free Adhesive Transition | REACH authorization sunsets drive reformulation investment ahead of compliance cliffs. |
| Metallized Film Coating Expansion | Norwegian and Chilean seafood processors adopt metallized PET to satisfy retailer scorecards. |
| India Extrusion Capacity Buildout | PLI scheme subsidies create first-mover advantage for pouch converters establishing local supply. |
| Foodservice Certification Concentration | BRCGS and ISO 22000 credentials become gating factors for healthcare and airline catering contracts. |
Research Methodology
Bottom-up frozen food processor demand modeling reconciled against top-down film extrusion capacity tracking forms the analytical core of this study. Primary interviews with extrusion plant managers, retail chain category buyers, cold storage logistics operators, and foodservice procurement directors combined with secondary validation against EU F-Gas Regulation filings, REACH authorization databases, and customs trade data for polymer resin imports. Triangulation between converter production schedules and end-user inventory cycles ensures volume estimates anchor in observable supply-side constraints.
Historical trendline analysis of laminate specification shifts and barrier technology adoption curves informs projection frameworks across the analysis window. Segmentation dimensions modeled include material type, packaging format, application category, and regional regulatory cluster. CAGRs derive from fitted growth curves applied to processor capacity expansion announcements and retailer sustainability mandate timelines. Industry-specific inputs incorporate cold chain infrastructure investment flows and extended producer responsibility law implementation schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to aluminum foil supply disruptions and adhesive chemistry regulatory revisions. Base assumptions reflect continued EU Green Deal packaging recyclability target enforcement and PLI scheme subsidy continuity in India. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Packaging
Mushroom Packaging Market
Food Packaging
Food and Beverage Packaging Market
Food Packaging
Reclosable Food Packaging Market
Food Packaging
Spices, Dry Seasoning Mix, and Herbal Extract Packaging Market
Food Packaging
Edible Oil Packaging Market
Food Packaging
Microwaveable Liquid Food Packaging Market
Food Packaging
India Food and Beverage Packaging Market
Food Packaging
Latin America Canned Food Packaging Market
Food Packaging
Ice Cream Packaging Market
Food Packaging
Honey Packaging Market
Food Packaging
Global Disposable Plates Market
Food Packaging
Sugar Packaging Market
Food Packaging
Pie Packaging Market
Food Packaging
Food Punnets Market
Food Packaging
Disposable Hot Cups & Lids Market
Food Packaging
North America PET Food Packaging Market