
 Railway Interior Lighting Market | 2026-2036
Railway Interior Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
Railway Interior Lighting Market Analytics
China's manufacturing corridor for rail components is tilting toward domestic LED module sourcing. Signify anchors European retrofit demand through its established luminaire distribution networks. Siemens AG leverages its rolling stock integration expertise to bundle lighting with digital cabin systems. Koito Manufacturing Co. dominates East Asian supply through captive optical design and thermal management specialization.
Railway interior lighting encompasses engineered luminaires, drivers, and control systems installed within passenger and crew compartments, typically operating at 24V–110V DC with color temperatures between 3000K and 6500K to optimize visual comfort and safety compliance. LED product types now command the primary margin pool as thermal efficiency gains and lumen maintenance ratings above 50,000 hours displace fluorescent legacy stock across passenger car applications. Ceiling-mounted installation types retain volume leadership while integrated systems that embed lighting within HVAC and information displays capture premium positioning in new-build locomotive programs.
Europe's EN 13272 and the EU Green Deal framework shape product roadmaps by mandating energy efficiency thresholds and circular material recovery, while China's GB standards and MIIT rail equipment certifications govern market access for imported luminaires. The US Federal Railroad Administration and EPA energy conservation rules further fragment compliance requirements across procurement jurisdictions. Stakeholders must monitor divergence between regional efficiency mandates and the pace of LED driver standardization to align R&D portfolios with enforceable certification timelines.
Market Dynamics
LED thermal efficiency gains above 50,000 hours lumen maintenance are compressing fleet renewal cycles and displacing fluorescent legacy stock across passenger rail applications worldwide.
Growth Catalysts
- Urban metro expansion:Asian operators are accelerating rolling stock orders to accommodate ridership growth in dense metropolitan corridors.
- EN 13272 luminance mandates:European standards mandate minimum passenger safety lighting levels, forcing retrofits across aging fleets.
- High-speed rail fleet renewal:China's rail sector is accelerating LED module adoption through compressed procurement cycles for new-build and refurbishment programs.
Market Restraints
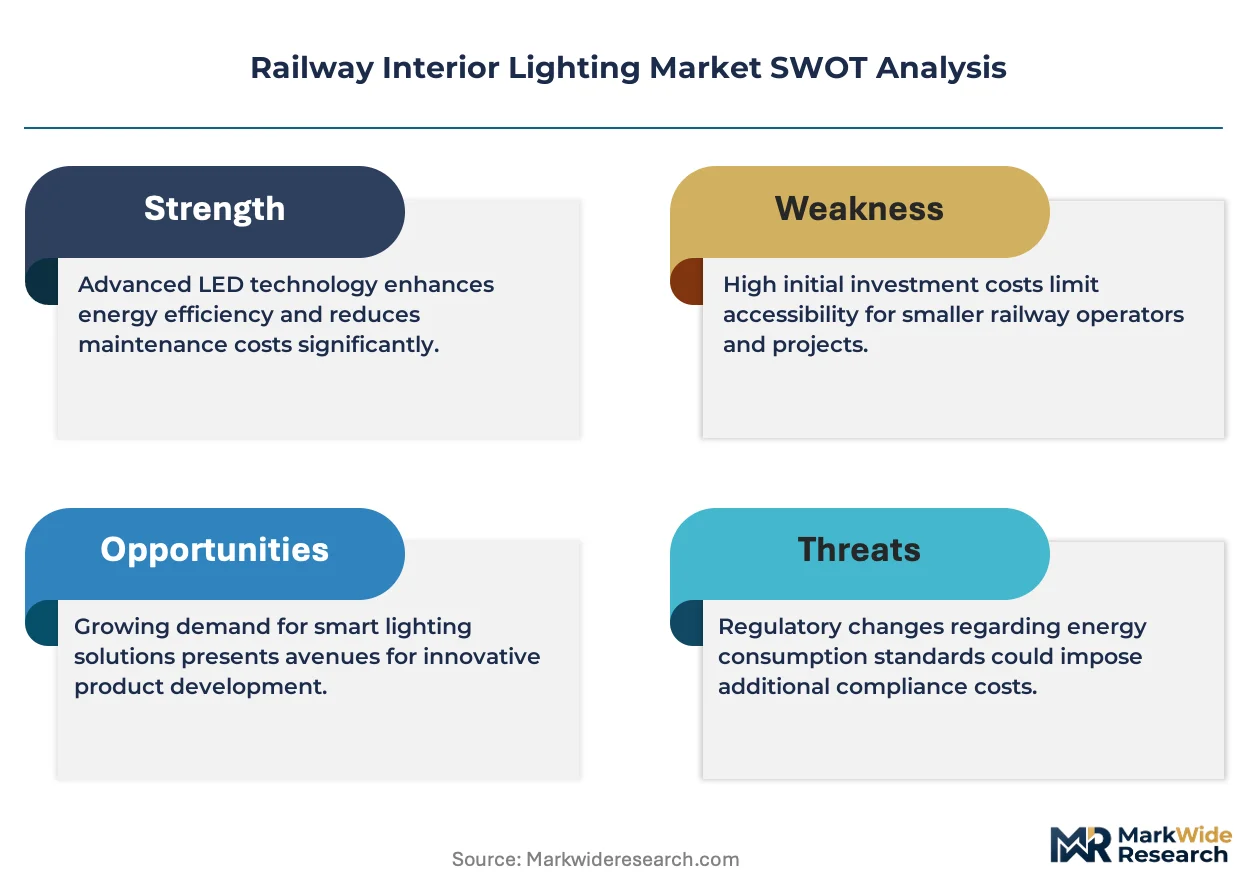
- Driver component concentration:Specialized LED driver supply concentrates among limited Asian electronics manufacturers, creating input vulnerability.
- GB certification friction:China's MIIT rail equipment certifications impose extended market access timelines for imported luminaire vendors.
- Fluorescent residual stock:Existing fluorescent installations in Eastern European and Latin American fleets delay full LED conversion economics.
Strategic Opportunities
- Integrated cabin systems:Convergence of lighting with HVAC and passenger information displays creates premium positioning in new locomotive programs.
- EU Green Deal circularity:Material recovery mandates and energy efficiency thresholds favor vendors with modular, serviceable luminaire designs.
- India's metro buildout:Underpenetrated urban rail networks in cities including Mumbai, Bangalore, and Hyderabad present untapped specification windows.
Industry Challenges
- Optical-thermal engineering talent scarcity:Specialized expertise in LED thermal management and rail-grade optical design concentrates in East Asian and German engineering clusters.
- Multi-jurisdiction certification complexity:Divergent EN 13272, GB standards, and US FRA requirements force redundant testing protocols and extended product validation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Railway Interior Lighting Market |
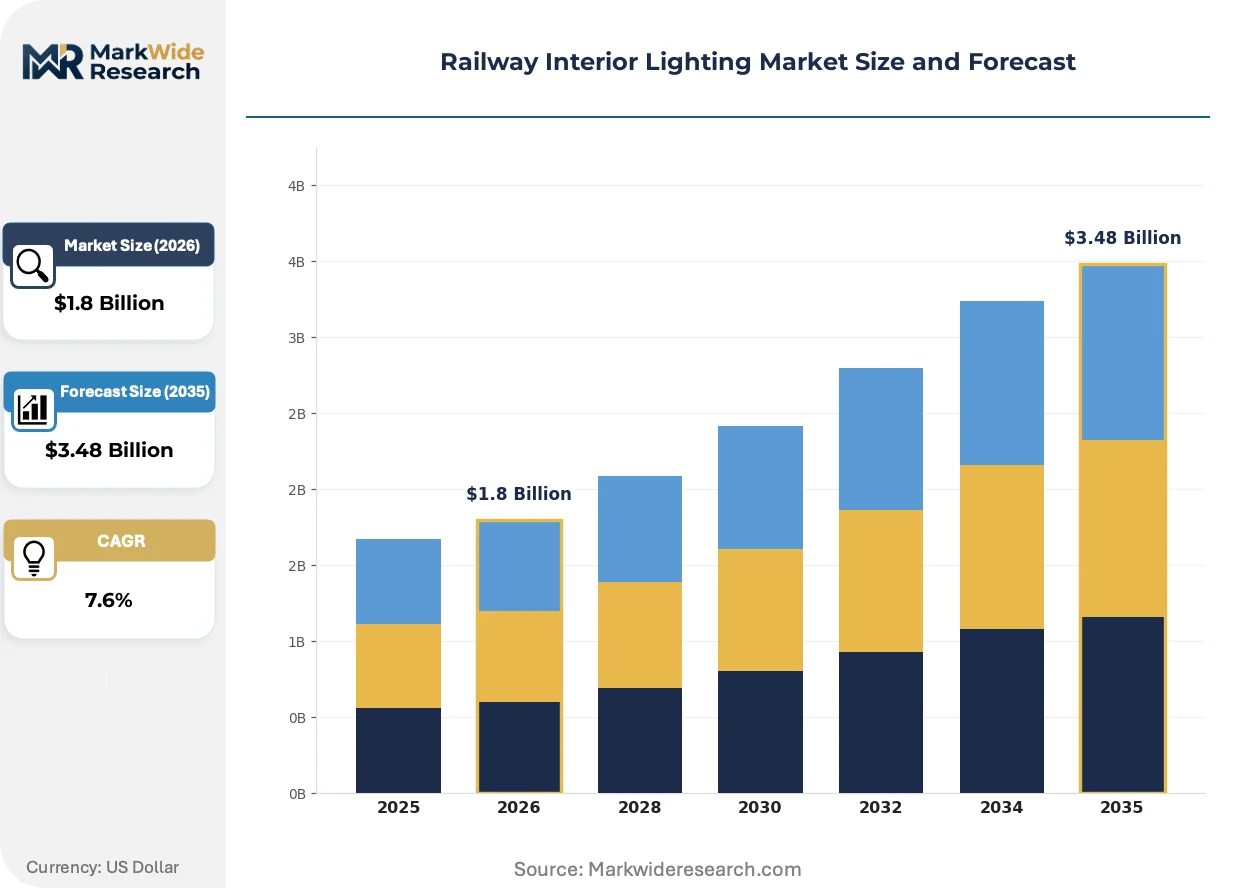
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.48 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, Fluorescent, Halogen, Incandescent Application: Passenger Cars, Freight Cars, Locomotives, Maintenance-of-Way Installation Type: Ceiling Mounted, Wall Mounted, Floor Mounted, Integrated Power Source: Batteries, AC Power, DC Power, Hybrid |
| Companies Covered | Teknoware Oy, Hitachi Ltd, Signify (Philips Lighting), Siemens AG, General Electric, Osram GmbH, Toshiba Corporation, Alstom SA, Koito Manufacturing Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Railway Interior Lighting Market Evolving Landscape
Digital cabin architectures are fusing illumination with environmental controls and real-time passenger data systems, compressing the traditional separation between lighting and building automation vendors.
Human-centric lighting is hybridizing circadian rhythm programming with standard cabin illumination. European operators including Deutsche Bahn and SNCF are piloting tunable white systems across premium service tiers. This convergence is hybridizing the competitive set, drawing building automation specialists into rail supply chains previously dominated by transportation-focused vendors.
The EU Green Deal's circular economy action plan mandates recoverable materials and extended producer responsibility for rail equipment placed on European markets. Manufacturers must redesign luminaire housings for disassembly and rare-earth recovery. German and French procurement authorities are now embedding these requirements into rolling stock tender specifications, favoring modular architectures over sealed integrated units.
Specification authority is migrating from fleet maintenance departments to centralized procurement offices with sustainability mandates. Long-term service contracts bundling installation, energy management, and component replacement are displacing transactional luminaire sales in Western European and North American markets. This shift is most visible in UK and Netherlands commuter rail networks, where operators seek single-accountability partners for decade-long lighting system performance.
Railway Interior Lighting Market Segmentation
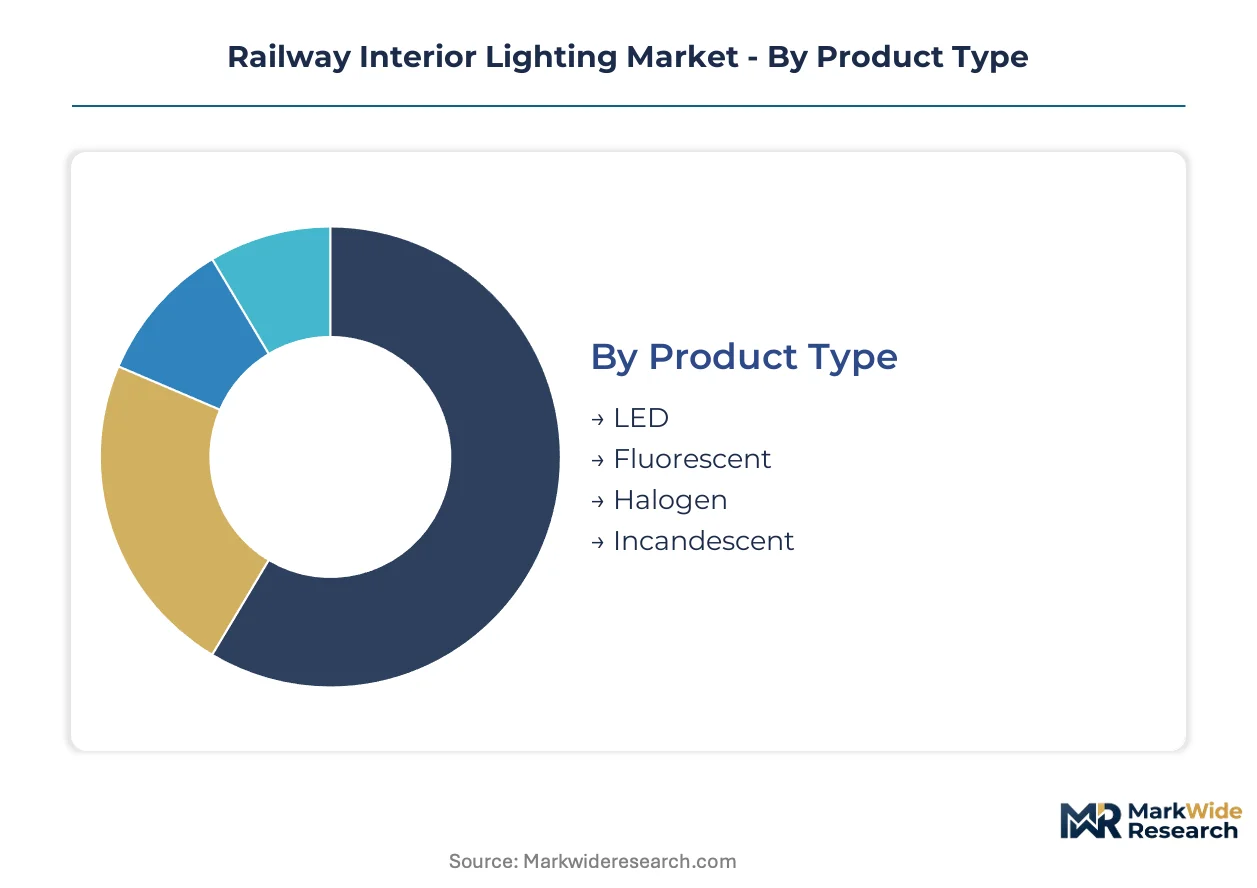
Railway interior lighting procurement fractures across multiple technical and operational dimensions, with specification authority migrating from maintenance departments toward centralized procurement offices. Understanding segment-level demand patterns reveals where thermal efficiency mandates, fleet renewal cycles, and integration complexity concentrate margin capture.
Product Type:
Mature fluorescent and halogen technologies coexist with emerging LED architectures, creating a bifurcated supply landscape where thermal performance and lumen maintenance ratings determine specification winners.
- LED:Solid-state modules operating at 24V–110V DC with color temperatures spanning 3000K–6500K and lumen maintenance above 50,000 hours. China's high-speed rail fleet renewal programs and Deutsche Bahn's EN 13272 compliance retrofits drive specification volume, compressing procurement cycles as operators phase out legacy stock.
- Fluorescent:Linear tube luminaires with magnetic or electronic ballast systems, still prevalent in Eastern European and Latin American rolling stock where full LED conversion economics remain delayed. Aging fleet maintenance departments in Poland and Brazil sustain residual demand despite efficiency disadvantages.
- Halogen:Tungsten-halogen sources with high color rendering indices but poor energy efficiency, now relegated to emergency backup and specialty accent applications in premium passenger cabins.
- Incandescent:Legacy filament technology with minimal thermal efficiency, surviving only in heritage railway preservation fleets and certain developing-market freight applications where capital constraints override operating cost considerations.
LED handles the majority of throughput; integrated smart modules are climbing the fastest on specification share.
Application:
Volume concentrates in passenger-facing installations where circadian programming and safety compliance intersect, while freight and maintenance applications prioritize durability over visual comfort engineering.
- Passenger Cars:Multi-zone illumination systems combining general cabin lighting with reading spotlights and emergency egress pathways. SNCF and Deutsche Bahn pilot tunable white human-centric systems across premium service tiers, blending circadian rhythm programming with standard cabin illumination.
- Locomotives:Operator cab lighting with anti-glare optical design and NVIS-compatible red spectrum preservation for night vision. Driver alertness requirements and EN 13272 luminance mandates force higher specification intensity than passenger areas.
- Freight Cars:Minimal illumination confined to crew compartments and inspection walkways, with specifications prioritizing impact resistance and vibration tolerance over color quality or thermal efficiency.
- Maintenance-of-Way:Portable and fixed lighting for track repair vehicles and inspection equipment, operating under severe environmental exposure with IP65+ ingress protection requirements.
Passenger cars generate the dominant revenue pool; locomotive cab retrofits are expanding most quickly as operators address driver safety regulations.
Installation Type:
Physical mounting geometry determines thermal management architecture and supply chain access, with integrated systems capturing premium positioning through HVAC and information display convergence.
- Ceiling Mounted:Recessed and surface-mounted downlight arrays delivering general cabin illumination, retaining volume leadership across refurbishment programs where existing conduit infrastructure limits redesign scope.
- Integrated:Luminaires embedded within HVAC diffusers, passenger information displays, and overhead luggage rack systems. Siemens AG bundles these with digital cabin architectures in new-build locomotive programs, compressing traditional separation between lighting and building automation vendors.
- Wall Mounted:Sconce and linear fixtures for corridor and vestibule applications, often specifying vandal-resistant polycarbonate housings in urban metro deployments.
- Floor Mounted:Low-level pathway and step illumination with heavy-duty mechanical protection, concentrated in accessibility-mandated egress lighting and platform-train interface visibility zones.
Ceiling mounted retains the installed base; integrated systems are gaining share fastest as new-build programs favor consolidated subsystem procurement.
Power Source:
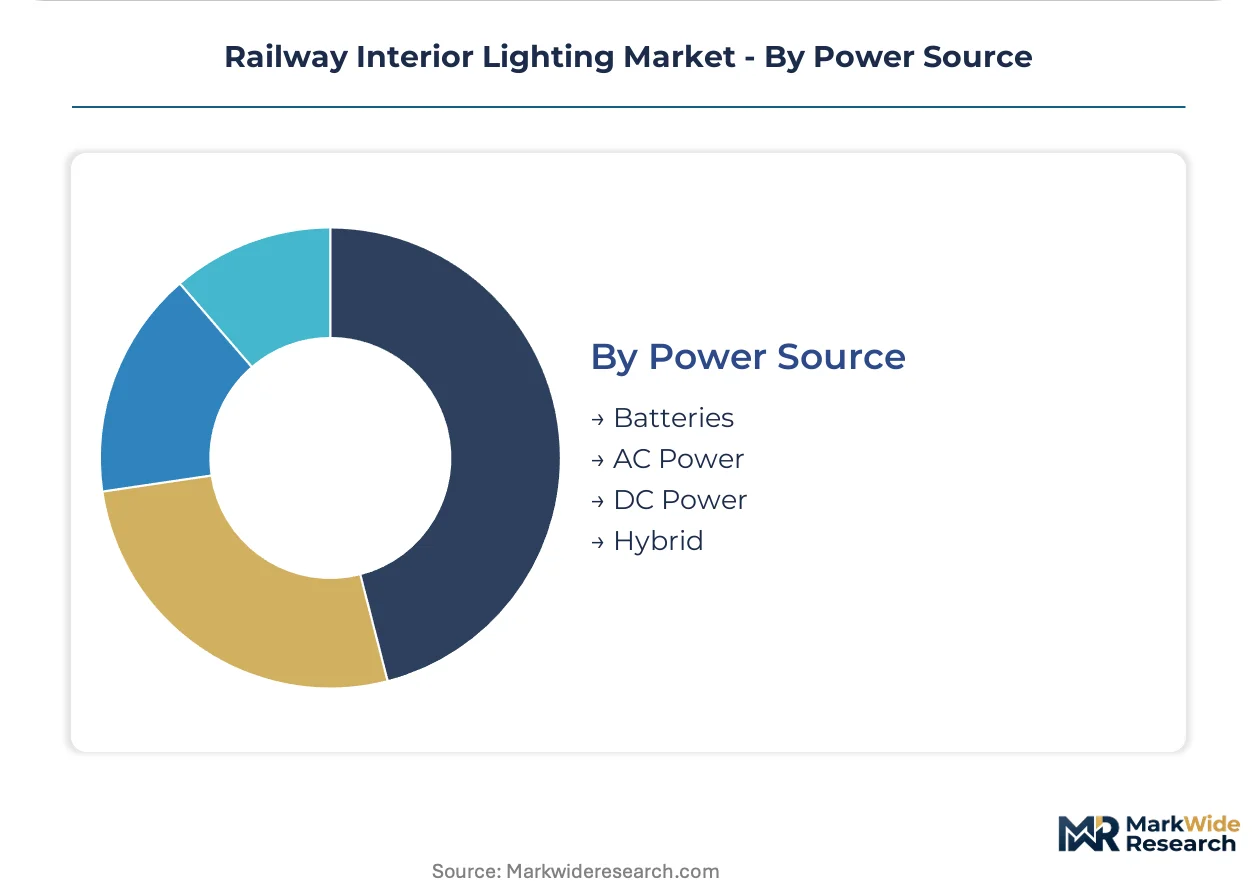
Electrical architecture choices reflect fleet electrification status, auxiliary system design, and emergency preparedness requirements across varying track infrastructure conditions.
- DC Power:Direct feed from trainline batteries at 24V, 48V, 74V, or 110V nominal, standard in electrified rail systems with consistent catenary or third-rail supply. China's high-speed fleet and European commuter networks standardize on this architecture.
- AC Power:Inverter-fed systems for legacy rolling stock and certain regional applications where auxiliary power conversion remains economical, though declining as LED driver efficiency favors native DC operation.
- Batteries:Self-contained emergency lighting units with autonomous operation during catenary failure or tunnel evacuation scenarios, mandated by EN 13272 minimum duration requirements.
- Hybrid:Dual-mode systems switching between trainline power and onboard battery reserves, specified for routes with frequent electrification gaps or diesel-electric multiple-unit operations.
DC power dominates active fleet specifications; hybrid architectures are expanding most quickly as operators seek resilience against infrastructure variability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes railway interior lighting through compressed fleet renewal cycles for high-speed rail, while European operators prioritize EN 13272 compliance retrofits over new-build specifications. The United States and India represent diverging demand profiles: legacy diesel fleet upgrades versus greenfield metro construction.
China
MIIT rail equipment certifications and GB standards govern market access for imported luminaires, compressing procurement timelines for domestic LED module sourcing. The Yangtze River Delta manufacturing corridor concentrates optical design and thermal management engineering talent. CRRC's rolling stock factories in Qingdao and Changchun specify integrated cabin systems bundling lighting with passenger information displays.
Germany
Deutsche Bahn's EN 13272 compliance retrofits and EU Green Deal circularity mandates drive specification of modular, serviceable luminaire architectures. KBA vehicle certification requirements extend validation timelines for non-EU vendors. Bavaria's rail supply cluster around Munich and Nuremberg anchors Signify's European distribution networks and Siemens AG's rolling stock integration programs.
United States
FRA safety regulations and EPA energy conservation rules fragment compliance requirements across commuter rail procurement jurisdictions. Amtrak's Northeast Corridor electrification programs and California's Caltrans rail modernization create specification windows for DC-native LED architectures. Chicago and Los Angeles metro operators pilot human-centric lighting systems for circadian rhythm programming.
India
Urban metro buildouts in Mumbai, Bangalore, and Hyderabad present underpenetrated specification windows as BIS standards and CEA electrical codes converge with international LED driver norms. The Delhi-Mumbai Industrial Corridor concentrates rolling stock manufacturing in Gujarat and Maharashtra. Indian Railways' 100% electrification targets compress fleet renewal cycles for passenger car lighting retrofits.
Japan
METI energy efficiency guidelines and JIS standards for rail equipment shape domestic procurement preferences favoring lumen maintenance ratings above 50,000 hours. Koito Manufacturing Co.'s captive optical design specialization concentrates in Aichi Prefecture's automotive-rail component cluster. JR East and JR West pilot tunable white systems across Shinkansen premium service tiers.
Railway Interior Lighting Market Competitive Landscape
Capability concentration sits with specialized optical-thermal engineering houses; scale advantage sits with diversified industrial conglomerates bundling lighting within broader rolling stock portfolios. The vendor base organizes around three strategic archetypes: captive rail specialists with in-house optical design, diversified electronics manufacturers leveraging component synergies, and building automation vendors penetrating transportation supply chains through digital cabin convergence. Dominant competitive moves include strategic partnerships for integrated subsystem procurement and geographic expansion through certification compliance in high-growth Asian markets.
Among diversified industrial conglomerates, Siemens AG and Hitachi Ltd occupy positions exemplifying the scale-driven integration archetype, bundling lighting specifications within digital cabin architectures and rolling stock platform contracts. Koito Manufacturing Co. represents the captive specialization model, with optical design and thermal management expertise concentrated in East Asian engineering clusters. Signify anchors the retrofit-focused tier through established luminaire distribution networks serving European EN 13272 compliance cycles.
| Leading Market Players |
|---|
| Teknoware Oy |
| Hitachi Ltd |
| Signify (Philips Lighting) |
| Siemens AG |
| General Electric |
| Osram GmbH |
| Toshiba Corporation |
| Alstom SA |
| Koito Manufacturing Co. |
| Others |
Value Network & Pricing Analysis
The Yangtze River Delta freight corridor's container cost dynamics compress LED module sourcing economics while amplifying price spreads between certified European luminaires and Asian commodity alternatives. Supply concentration in optical-thermal engineering clusters feeds downstream price differentiation across procurement tiers.
Pricing Analysis
Geographic price spreads of 40-60% separate EN 13272-certified European luminaires from GB-standard Asian modules. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and lumen maintenance ratings. Pricing pressure stems from CRRC's consolidated procurement leverage in China's high-speed rail sector. State-owned operators exhibit lowest price sensitivity; private Latin American freight carriers face acute budget constraints.
Supply Chain Analysis
Export-control regimes restricting rare-earth phosphor and advanced LED driver technologies limit component flows from Chinese suppliers to European integrators. Manufacturing concentrates in China, Germany, and Japan. Production draws from gallium nitride substrates, aluminum heat sinks, and rail-grade polycarbonate housings. Single-source vulnerability concentrates in specialized driver IC fabrication. Distribution runs through rolling stock OEMs and certified retrofit contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Optical-thermal engineering talent scarcity in rail-grade applications constrains vendor scalability and amplifies acquisition premiums for specialized capabilities. This gap shapes competitive positioning across retrofit and new-build procurement cycles.
For Market Incumbents: Insulate specification authority by deepening captive optical design capabilities and securing long-term service contracts with Deutsche Bahn and SNCF. Vertical integration into LED driver sourcing mitigates Asian electronics concentration risk. Certification investment in India's BIS standards creates defensive positioning against emerging competitors. For New Entrants and Emerging Players: Build out specification presence in India's underpenetrated metro buildouts across Mumbai, Bangalore, and Hyderabad. Target maintenance-of-way applications where IP65+ ingress requirements create niche barriers. Partner with regional rolling stock OEMs for bundled subsystem procurement. For Investors and Strategic Acquirers: EU Green Deal circularity mandates reshape the acquisition landscape toward modular, serviceable luminaire architectures. Five-to-ten-year viability favors vendors with rare-earth recovery capabilities and extended producer responsibility compliance. Monitor MIIT certification timeline acceleration as inflection signal for Chinese market access premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Optical-Thermal Engineering Acquisition | Captures scarce talent pools in Aichi and Bavaria clusters for rail-grade LED specialization. |
| Modular Luminaire Architecture Development | Aligns product roadmaps with EU Green Deal material recovery mandates and tender specifications. |
| India BIS Certification Investment | Unlocks specification windows in Mumbai and Hyderabad metro procurement cycles. |
| Integrated Cabin System Partnership | Bundles lighting with HVAC and passenger information displays for Siemens AG and Alstom SA platforms. |
| Driver IC Supply Agreement | Reduces single-source vulnerability in Asian electronics manufacturing concentration. |
Research Methodology
Desk research of customs trade databases, rolling stock OEM technical specifications, and national rail procurement registries preceded structured interviews with fleet maintenance directors, rolling stock procurement officers, optical design engineers, and regulatory certification specialists. Primary fieldwork across Chinese high-speed rail facilities, German commuter networks, and Indian metro construction sites validated secondary estimates. Bottom-up unit economics triangulated against top-down fleet renewal projections.
Assumptions held fixed include EN 13272 luminance mandate enforcement timelines and LED thermal efficiency improvement curves; variables tested included China's MIIT certification friction intensity and India's BIS-CEA convergence pace. Segmentation modeling spanned product type, application, installation geometry, and power architecture across the projection horizon. CAGRs derived from rolling stock order backlogs and fleet age distribution analysis. Industry-specific inputs incorporated lumen maintenance degradation curves and catenary electrification expansion schedules.
Practitioners should monitor regulatory divergence between EU Green Deal circularity enforcement and GB standards harmonization for early signals of procurement specification shifts. Forecasts reflect assumptions of steady LED cost compression and stable rare-earth supply availability. Material shifts in export-control regime stringency or electrification infrastructure investment would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Global Automotive Tinted Window Pane Market
Automotive Interior & Exterior
Exterior Automotive Plastics Market
Automotive Interior & Exterior
Global Automotive Power Sliding Door Market
Automotive Interior & Exterior
Automotive Door Impact Bars Market
Automotive Interior & Exterior
Auto Ventilated Seat Fan Market
Automotive Interior & Exterior
Automotive Exterior Materials Market
Automotive Interior & Exterior
Reflective Air Bags Market
Automotive Interior & Exterior
Automotive Panoramic Sunroof Market
Automotive Interior & Exterior
Convertible Roof Control Unit Market
Automotive Interior & Exterior
Automotive Outside Rearview Mirrors (ORVM) Market
Automotive Interior & Exterior
Ventilated Seats Market
Automotive Interior & Exterior
India Automotive Adaptive Lighting System Market
Automotive Interior & Exterior
Mexico Automotive Sunroof Market
Automotive Interior & Exterior
Automotive in-Cabin Air Quality Improvement Solutions Market
Automotive Interior & Exterior
Asia-Pacific Automotive Flooring Market
Automotive Interior & Exterior
Automotive Smart Window Market