
 Automotive in-Cabin Air Quality Improvement Solutions Market | 2026-2036
Automotive in-Cabin Air Quality Improvement Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive in-Cabin Air Quality Improvement Solutions Market Analysis
Photocatalytic oxidation integrated with multi-layer filtration is narrowing the performance gap between aftermarket retrofits and factory-fitted systems. Valeo leverages its climate-control integration expertise to anchor premium OEM contracts across European and Asian vehicle platforms. Mann+Hummel specializes in high-efficiency cabin filter media, sustaining R&D intensity that extends its technology leadership in activated carbon composites. Bosch competes through sensor-fusion architectures that combine particulate detection with automated ventilation responses.
Automotive in-cabin air quality improvement solutions encompass filtration, ionization, and ventilation technologies designed to remove particulate matter, volatile organic compounds, and biological contaminants from vehicle interiors, typically achieving PM2.5 capture efficiencies exceeding 99.97% in HEPA-configured systems. Their primary commercial purpose centers on occupant health protection, regulatory compliance, and brand differentiation in passenger and commercial vehicle segments. Cabin filters and air purifiers dominate current revenue pools, with HEPA technology leading penetration in premium vehicle lines while photocatalytic systems represent the fastest-growing technology tier as OEMs seek self-regenerating filtration that reduces maintenance frequency and lifetime cost. Factory-fitted installation controls the highest margin pool, though modular retrofit configurations are gaining traction among fleet operators managing mixed-age vehicle pools.
The EPA's ambient air quality standards indirectly shape cabin filtration benchmarks through state-level passenger health expectations, while China's MEE enforces GB/T vehicle interior air quality limits that mandate formaldehyde and benzene concentration ceilings. Euro 7 provisions from the EU Green Deal framework are extending tailpipe and evaporative emission controls into cabin air circulation requirements, compelling suppliers to certify materials for ultralow volatile release. Stakeholders must monitor whether photocatalytic and UV-based technologies achieve sufficient durability validation to displace conventional replaceable media in next-generation vehicle architectures.
Market Dynamics
Photocatalytic oxidation is collapsing the traditional maintenance-cost advantage of replaceable filter media, forcing suppliers to restructure R&D portfolios around self-regenerating architectures that reduce lifetime ownership costs for fleet operators.
Growth Catalysts
- Euro 7 cabin air provisions:The EU Green Deal framework extends evaporative emission controls into interior circulation requirements, compelling automakers to certify ultralow-volatile materials for factory-fitted systems.
- China GB/T mandates:MEE enforcement of formaldehyde and benzene concentration ceilings creates compliance-driven replacement cycles for cabin filtration across domestic and foreign-brand vehicle lines.
- HEPA penetration in premium segments:Factory-fitted configurations achieving PM2.5 capture efficiencies above 99.97% are anchoring health-focused purchase criteria among luxury SUV and executive sedan buyers.
Market Restraints
- Activated carbon input volatility:Coconut shell and coal-based carbon feedstock prices fluctuate with agricultural yield cycles and mining output, compressing margin predictability for filter media suppliers.
- Photocatalytic durability gaps:Titanium dioxide catalyst deactivation rates in high-humidity vehicle environments remain insufficiently validated for full warranty-period coverage.
- Aftermarket retrofit complexity:Modular add-on systems face integration friction with proprietary HVAC architectures, limiting addressable fleet penetration in mixed-age vehicle pools.
Strategic Opportunities
- Sensor-fusion architectures:Combining particulate detection with automated ventilation responses enables predictive filter replacement scheduling and differentiated service revenue streams.
- Commercial vehicle underpenetration:Long-haul trucking and ride-hail fleets in India represent nascent demand for integrated purification systems beyond basic pollen filtration.
- UV-C LED convergence:Solid-state ultraviolet sterilization paired with existing HVAC ductwork offers pathogen inactivation without photocatalytic material degradation concerns.
Industry Challenges
- Multiphysics simulation talent scarcity:Coupled airflow-chemical reaction modeling for photocatalytic system design requires expertise spanning computational fluid dynamics and surface chemistry.
- Cross-certification timeline compression:Simultaneous validation against GB/T, EPA ambient benchmarks, and Euro 7 material release standards strains testing capacity and extends product launch schedules.
- Legacy HVAC integration friction:Retrofit air purifier installation in vehicles with sealed evaporator housings demands invasive cabin disassembly, elevating labor cost and dealer resistance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive in-Cabin Air Quality Improvement Solutions Market |
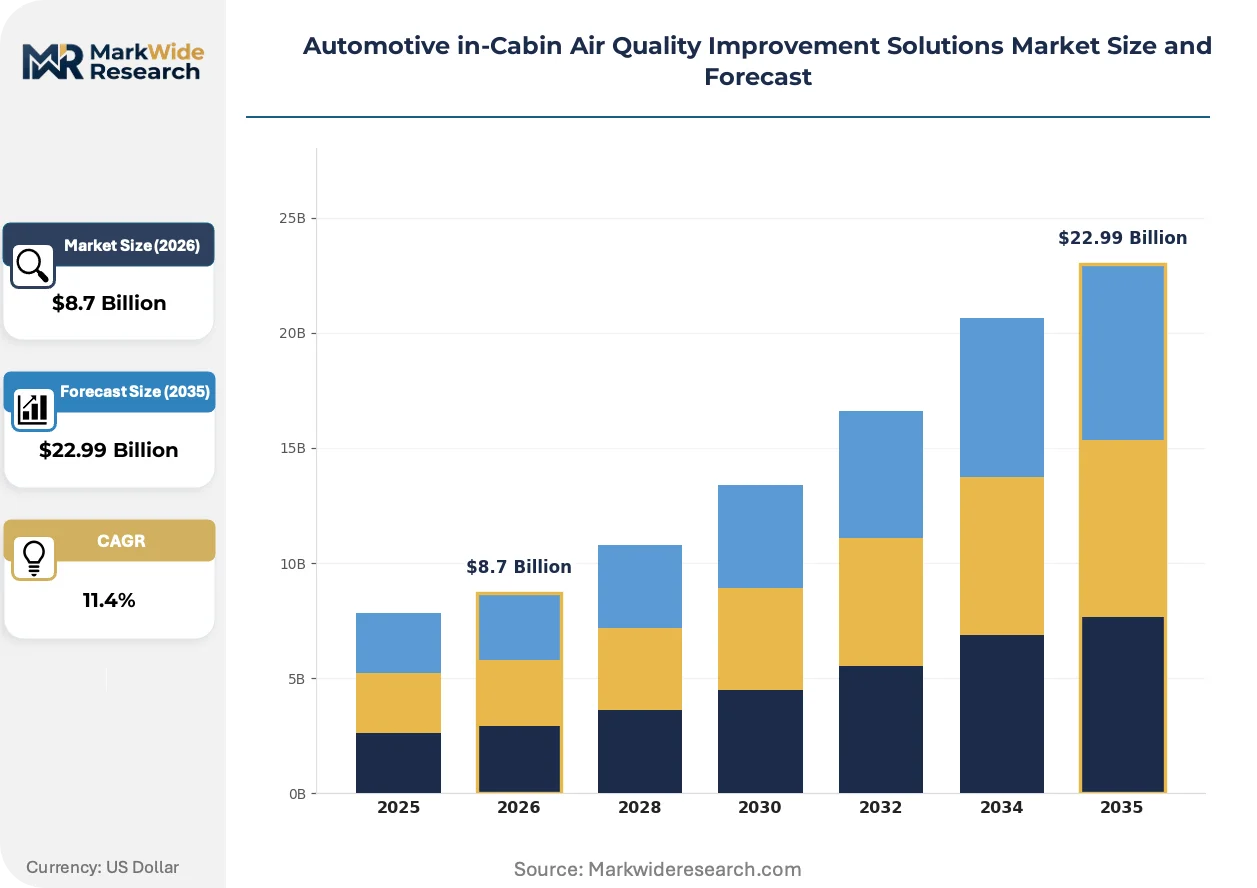
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air Purifiers, Cabin Filters, Ventilation Systems, Ionizers Technology: HEPA, Activated Carbon, Photocatalytic, UV Light End User: OEMs, Aftermarket Providers, Fleet Operators, Vehicle Assemblers Installation: Factory-Fitted, Retrofit, Modular, Integrated |
| Companies Covered | Valeo, Mann+Hummel, DENSO Corporation, Bosch, MAHLE GmbH, Marelli, Air International, Hella, Honeywell International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive in-Cabin Air Quality Improvement Solutions Market Emerging Trajectories
Active filtration architectures are displacing passive media across all vehicle price tiers, with convergence between climate-control hardware and air quality management software creating new competitive battlegrounds for system integration contracts.
Photocatalytic oxidation is collapsing the distinction between maintenance-free and replaceable filtration tiers. Titanium dioxide coatings integrated into HVAC evaporator surfaces decompose captured VOCs under UV-A exposure, eliminating filter replacement labor. European premium OEMs are piloting these configurations in flagship electric vehicle platforms where reduced service intervals align with brand positioning. The technology is collapsing aftermarket revenue pools for conventional cabin filter replacement while shifting value capture toward climate-system suppliers with catalyst application expertise.
China's MEE is tightening GB/T vehicle interior air quality enforcement through expanded spot-check protocols and public disclosure of formaldehyde exceedance incidents. Domestic automakers are accelerating factory-fitted activated carbon composite adoption to preempt regulatory penalty and consumer reputation damage. The policy is compressing certification timelines for foreign suppliers seeking access to volume production contracts with state-owned vehicle manufacturers.
Fleet procurement of air quality systems is consolidating around total-cost-of-ownership metrics that weight filter replacement frequency against energy consumption penalties from high-pressure-drop media. Large ride-hail operators in Germany and the United States are specifying multi-year service contracts bundling hardware, installation, and predictive maintenance analytics. This purchasing pattern is visible most acutely in urban mobility fleets where driver retention correlates with cabin environment ratings on ride-hailing platforms.
Automotive in-Cabin Air Quality Improvement Solutions Market Segmentation
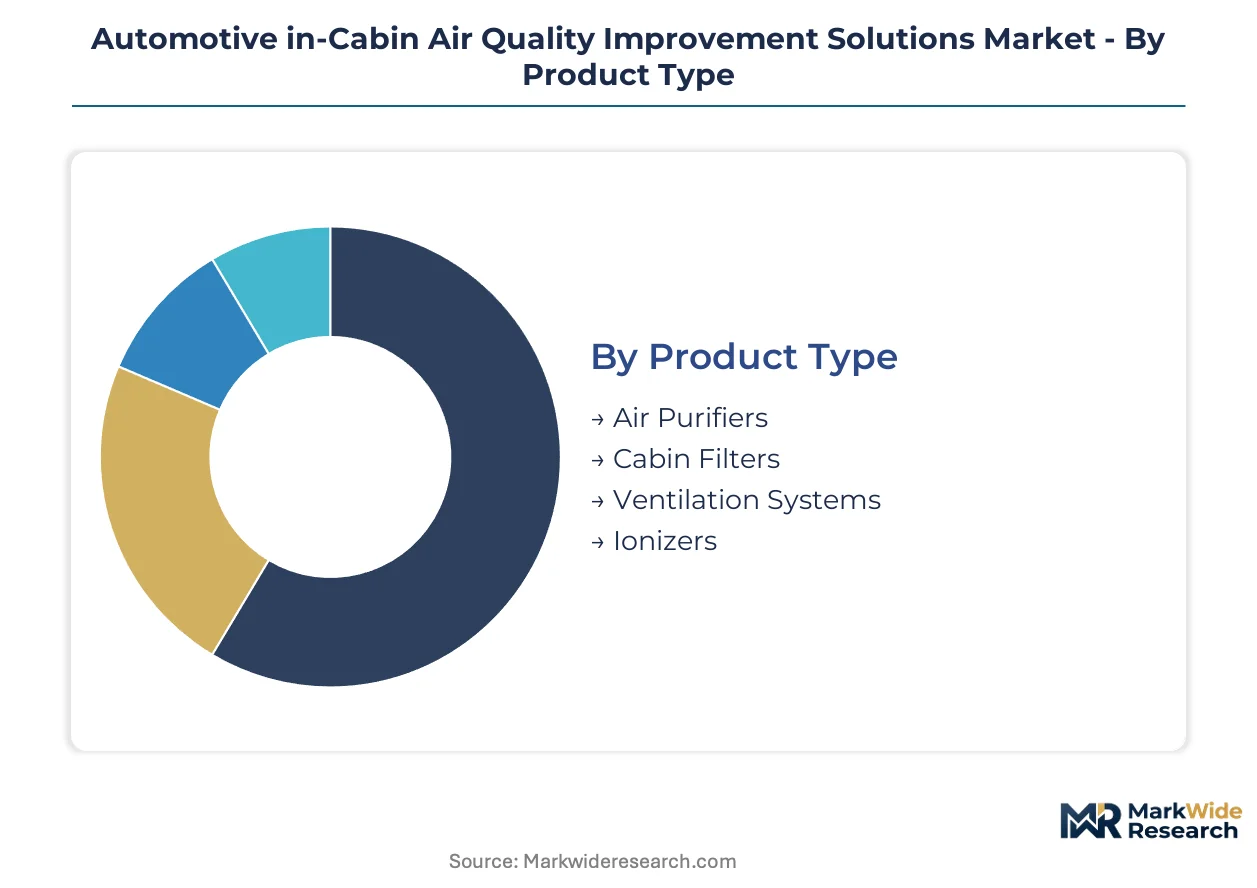
Segmentation in cabin air quality solutions reveals divergent replacement cycles and margin structures across hardware categories. Technology tiers and installation modes determine whether suppliers capture recurring service revenue or one-time system sales.
Product Type:
Replacement cycles vary dramatically — cabin filters turn over every 12-18 months while ventilation systems persist for vehicle lifetime, creating fundamentally different revenue recognition patterns for suppliers.
- Cabin Filters:Multi-layer media combining synthetic fibers with activated carbon or HEPA substrates achieve PM2.5 capture above 99.97% in premium configurations. Demand clusters in Germany and China where regulatory spot-checks accelerate replacement frequency among fleet operators. Euro 7 material certification requirements are compressing supplier margins while extending validation timelines.
- Air Purifiers:Standalone or HVAC-integrated units deploy ionization, filtration, or photocatalytic stages to reduce particulate and VOC loads in real time. Chinese domestic automakers are factory-fitting these systems to preempt GB/T formaldehyde enforcement and consumer reputation damage. The segment is climbing the fastest as OEMs bundle air quality into health-focused brand positioning.
- Ventilation Systems:Automated intake and recirculation architectures respond to sensor-detected ambient pollution levels.
- Ionizers:Electrostatic precipitators release charged particles to agglomerate ultrafine contaminants for capture or deposition.
Cabin filters dominate installed base across all vehicle age cohorts. Air purifiers are where expansion concentrates as factory-fit penetration accelerates in premium electric platforms.
Technology:
Performance validation requirements stratify technology tiers — HEPA and activated carbon carry established certification protocols while photocatalytic and UV systems face durability uncertainty in automotive duty cycles.
- HEPA:High-efficiency particulate air media rated H13 or H14 capture 99.95% to 99.995% of 0.3-micron particles through dense glass fiber matrices. Premium SUV and executive sedan lines in the United States and Germany specify factory-fitted HEPA as a health-differentiation feature. Pressure-drop penalties from dense media impose energy consumption costs that fleet operators weigh against filtration performance.
- Activated Carbon:Coconut shell or coal-based substrates adsorb VOCs, ozone, and NOx through microporous surface chemistry. China's MEE enforcement of benzene concentration ceilings is driving compliance-driven adoption across domestic and foreign-brand vehicle lines. Feedstock price volatility from agricultural yield cycles compresses margin predictability for media suppliers.
- Photocatalytic:Titanium dioxide coatings decompose captured organic compounds under UV-A exposure, enabling self-regenerating filtration.
- UV Light:UV-C LED or mercury-vapor sources inactivate biological contaminants within HVAC ductwork without filter media replacement.
Activated carbon and HEPA dominate current installed base. Photocatalytic configurations are gaining share fastest as OEMs pilot self-regenerating systems to align with reduced-service-interval brand positioning in electric vehicles.
End User:
Procurement sophistication varies sharply — OEMs negotiate multi-year system integration contracts while aftermarket providers and fleet operators optimize total cost of ownership across mixed-age vehicle pools.
- OEMs:Vehicle manufacturers specify factory-fitted air quality architectures during platform development, locking in climate-system suppliers for production cycles spanning 5-7 years. German and Chinese premium automakers are prioritizing integrated purification systems as health-focused purchase criteria harden. Euro 7 cabin air provisions and GB/T mandates are compelling ultralow-volatile material certification.
- Aftermarket Providers:Independent distributors and service chains supply replacement filters and retrofit purifiers for vehicles outside factory warranty. Integration friction with proprietary HVAC architectures limits penetration in sealed evaporator housing designs. Labor cost from invasive cabin disassembly elevates dealer resistance to modular retrofit installation.
- Fleet Operators:Ride-hail and logistics fleets in Germany and the United States are bundling hardware, installation, and predictive maintenance analytics into multi-year service contracts.
- Vehicle Assemblers:Contract manufacturers and regional assembly operations source air quality systems to meet local regulatory requirements.
OEMs control the highest-margin contract pool. Fleet operators represent the steepest expansion trajectory as total-cost-of-ownership procurement consolidates around predictive maintenance and driver retention metrics.
Installation:
Integration depth determines warranty liability and service revenue capture — factory-fitted systems anchor long-term supplier relationships while retrofit and modular configurations face technical and commercial friction.
- Factory-Fitted:Systems designed into vehicle platforms during HVAC architecture development achieve seamless climate-control integration and full warranty coverage. Premium automakers in Germany and China are specifying these configurations to meet tightening regulatory mandates and health-focused consumer expectations. The segment commands margin premiums but requires multi-year validation cycles and platform-specific engineering investment.
- Integrated:Air quality hardware embedded within climate-control modules shares ductwork, sensors, and control logic with heating and cooling functions.
- Retrofit:Aftermarket installation of purification systems in vehicles lacking factory-fit provision demands cabin disassembly and HVAC modification.
- Modular:Self-contained plug-in units operate independently of vehicle HVAC systems, typically through 12V power or USB connections.
Factory-fitted systems dominate revenue concentration in premium segments. Integrated architectures are where supplier R&D investment concentrates as climate-control and air quality management software converge.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium SUV buyers in Germany, fleet operators in the United States, and domestic automakers in China concentrate purchasing power for factory-fitted cabin air quality systems. Each geography imposes distinct regulatory timelines and certification requirements.
United States
Luxury SUV and executive sedan segments drive HEPA specification as a health-differentiation feature. EPA ambient air quality standards indirectly shape cabin filtration benchmarks through state-level passenger health expectations. California's South Coast Air Quality Management District enforces the nation's strictest indoor air quality guidelines, influencing automotive cabin standards through consumer expectation spillover.
Germany
Premium automakers anchor European demand for integrated climate-control and air purification architectures. Euro 7 provisions from the EU Green Deal framework extend evaporative emission controls into cabin air circulation requirements. Stuttgart and Munich clusters concentrate supplier engineering centers validating ultralow-volatile material certifications for next-generation vehicle platforms.
China
Domestic automakers accelerate factory-fitted activated carbon composite adoption to preempt regulatory penalty and consumer reputation damage. MEE enforcement of GB/T vehicle interior air quality limits mandates formaldehyde and benzene concentration ceilings. Shanghai and Beijing metropolitan areas concentrate spot-check protocols and public disclosure of exceedance incidents.
Japan
Automotive climate-control specialists compete for integration contracts on electric vehicle platforms emphasizing reduced service intervals. METI guidelines on vehicle interior air quality influence domestic manufacturer specifications. Toyota City and Nagoya industrial corridors concentrate HVAC system development for export-oriented production.
South Korea
Premium electric vehicle manufacturers specify sensor-fusion architectures combining particulate detection with automated ventilation responses. MFDS guidelines on indoor air quality inform automotive cabin benchmarks. Seoul Capital Area clusters concentrate R&D investment in solid-state UV-C LED sterilization paired with existing HVAC ductwork.
Automotive in-Cabin Air Quality Improvement Solutions Market Vendor Landscape
Channel-controlling players compete with product-specialist players across factory-fitted and aftermarket installation modes. The supplier base organizes around three tiers: climate-system integrators with platform-development relationships, filter media specialists with materials science expertise, and sensor-technology providers with automated-response capabilities. Dominant competitive moves include multi-year system integration contracts locking in production cycles and strategic partnerships bundling hardware with predictive maintenance analytics.
Among European climate-system integrators, Valeo and MAHLE GmbH exemplify the platform-integration archetype, anchoring supplier positions through HVAC architecture development relationships. Mann+Hummel represents the filter media specialist tier, occupying a position defined by activated carbon and HEPA substrate expertise. Bosch sits within the sensor-technology provider category, exemplifying the automated-response competitive vector through detection-ventilation fusion architectures.
| Leading Market Players |
|---|
| Valeo |
| Mann+Hummel |
| DENSO Corporation |
| Bosch |
| MAHLE GmbH |
| Marelli |
| Air International |
| Hella |
| Honeywell International |
| Others |
Supply Flow & Price Mechanics
Coconut shell and coal-based activated carbon feedstock concentration in Southeast Asian agricultural zones and Chinese mining regions directly determines margin predictability for cabin filter media suppliers, compressing pricing power at the component tier while OEM system integrators capture service-attach premiums downstream.
Pricing Analysis
Cost-plus contracts with coconut shell carbon indexation dominate Tier 1 supplier agreements, insulating manufacturers from agricultural yield volatility while passing feedstock risk to OEM buyers. Three-tier pricing structure across premium HEPA, standard activated carbon, and economy particulate-only configurations stratifies by certification grade and after-sales bundling. Pricing pressure stems from Euro 7 validation cost inflation extending product launch timelines. Fleet operators exhibit highest price sensitivity through total-cost-of-ownership procurement, while premium OEMs prioritize performance differentiation over unit cost.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from German and Japanese automotive OEMs squeeze working capital for filter media specialists dependent on Southeast Asian carbon feedstock and Chinese synthetic fiber substrate production. Raw material dependencies span coconut shell carbon, glass microfiber for HEPA matrices, and titanium dioxide photocatalyst precursors. Single-source vulnerability concentrates in specialty carbon activation capacity. Distribution runs through climate-system integrators with platform-development relationships anchoring multi-year production cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Predictive maintenance analytics and filter replacement subscription services are expanding faster than hardware sales, transforming air quality system procurement from capital expenditure to recurring operating expense across fleet operator segments.
For Market Incumbents: Pre-empt photocatalytic durability validation gaps by accelerating titanium dioxide catalyst warranty coverage before competitors achieve breakthrough humidity-resistance certifications. Consolidate backward integration into activated carbon activation capacity to defend margin position against feedstock price volatility from Southeast Asian agricultural yield cycles. For New Entrants and Emerging Players: Pursue sensor-fusion architecture white space in commercial vehicle segments where long-haul trucking and ride-hail fleets in India remain underpenetrated beyond basic pollen filtration. Target aftermarket retrofit configurations with plug-and-play modular designs bypassing proprietary HVAC integration friction through standalone 12V power operation. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed climate-system specialists holding dated platform-integration contracts vulnerable to photocatalytic technology displacement. Five-to-ten year viability favors suppliers with validated self-regenerating filtration and software-defined air quality management capabilities. Watch for GB/T enforcement acceleration in China as inflection indicator compressing foreign supplier certification timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Photocatalytic System Validation | Titanium dioxide warranty coverage anchors premium electric vehicle platform contracts. |
| Sensor-Fusion Architecture Development | Particulate detection integration with automated ventilation responses creates predictive service revenue. |
| Activated Carbon Backward Integration | Captive coconut shell activation capacity insulates margin from agricultural yield volatility. |
| GB/T Compliance Certification | Formaldehyde and benzene ceiling validation unlocks Chinese state-owned manufacturer volume contracts. |
| Fleet Analytics Platform Launch | Predictive filter replacement scheduling transforms hardware sales into recurring subscription revenue. |
Methodological Framework
Initial hypotheses were tested against primary input from OEM platform engineers, Tier 1 supplier procurement leads, aftermarket distributors, and fleet operations managers, then refined against vehicle production databases, IHS Markit registration data, EPA ambient air quality standards documentation, and MEE GB/T enforcement protocols. Bottom-up segment sizing triangulated with top-down market validation across technology tier, installation mode, and end-user category dimensions.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, modeling vehicle class, propulsion architecture, content per vehicle, and regional production cluster segmentation. CAGRs derived from installed base turnover rates and factory-fit penetration curves incorporated Euro 7 regulatory timeline assumptions and photocatalytic technology adoption S-curves.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese domestic suppliers or accelerated photocatalytic durability breakthroughs would shift outcomes. Macroeconomic deviation, regulatory enforcement acceleration, or solid-state UV-C LED sterilization substitution would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive OEM Interior Coatings Market
Automotive Interior & Exterior
Zero Gravity Seat Market
Automotive Interior & Exterior
Global Automotive Luggage Trim Market
Automotive Interior & Exterior
Heated Steering Wheel Market
Automotive Interior & Exterior
Automotive Fabric Market
Automotive Interior & Exterior
Seat Comfort and Lumbar Actuator Systems Market
Automotive Interior & Exterior
Global Automotive Window Power Sunshade Market
Automotive Interior & Exterior
Train Ceiling Modules Market
Automotive Interior & Exterior
Automotive Sunroof Market
Automotive Interior & Exterior
Automotive Heated Seat Market
Automotive Interior & Exterior
Auto Dimming Mirror Market
Automotive Interior & Exterior
Automotive Intake Manifold Cover Market
Automotive Interior & Exterior
LED Fog Lamp Market
Automotive Interior & Exterior
Automotive Exterior Trim Parts Market
Automotive Interior & Exterior
Automotive Head Up Display (HUD) Market
Automotive Interior & Exterior
Decorative Car Accessories Market