
 Automotive Interior Cleaner Market | 2026-2036
Automotive Interior Cleaner Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Interior Cleaner Market Insights
Automotive aftermarket retail is tilting toward e-commerce and direct-to-consumer platforms as traditional auto parts stores cede shelf space to digital-native brands. Turtle Wax leverages its established retail partnerships to sustain shelf dominance in mass-market channels across North America. Chemical Guys competes through content-driven digital marketing that anchors its premium positioning among enthusiast segments. Sonax GmbH dominates professional-grade distribution in Europe through certified supply relationships with dealership networks.
Automotive interior cleaners comprise formulated surfactant blends, solvents, conditioning agents, and fragrance compounds engineered to remove soils, oils, and microbial contamination from vehicle cabin surfaces without degrading plastics, leather, or synthetic textiles; pH-neutral formulations typically range between 6.5 and 7.5 to prevent surface etching on sensitive dashboard polymers. Sprays lead volume shipments due to application versatility across dashboard and upholstery surfaces, while wipes capture premium margin pools through convenience positioning in consumer channels. Foams represent the fastest-growing product type as detailers adopt clinging formulations that extend dwell time on vertical carpet and fabric surfaces.
EPA regulations under the Clean Air Act limit VOC emissions from consumer products, directly constraining solvent selection and propelling water-based formulation R&D among domestic manufacturers. REACH registration requirements in Europe mandate full chemical substance disclosure, raising compliance costs for imported formulations and favoring regional production. California Air Resources Board standards operate as a de facto national benchmark through market scale effects. Stakeholders must monitor evolving state-level chemical restriction trajectories and build formulation flexibility into supply chains ahead of anticipated regulatory tightening.
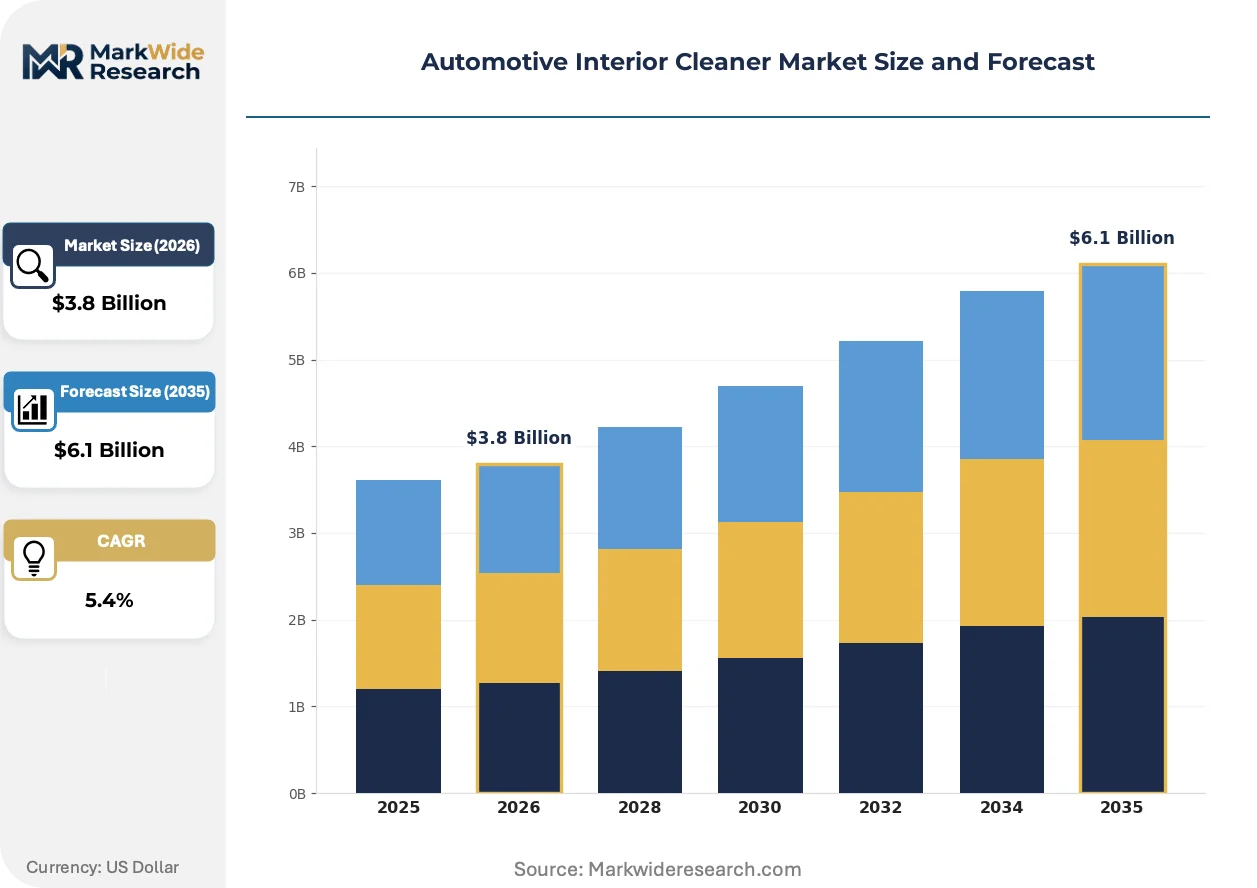
Market Dynamics
Fleet maintenance providers tightening cabin hygiene protocols represent the dominant demand pulse, while REACH and EPA restrictions on volatile organic compounds force simultaneous reformulation across solvent bases.
Growth Catalysts
- Fleet hygiene mandates:Commercial vehicle operators in Germany and the US now enforce quarterly cabin sanitization protocols, expanding contract volumes for professional-grade formulations.
- REACH chemical registration:Full substance disclosure requirements favor regional European producers with established compliance infrastructure over imported competitors.
- Bio-based solvent R&D:Water-borne chemistry platforms are displacing petroleum-derived solvents in premium OEM-certified detailing channels.
Market Restraints
- Petrochemical feedstock volatility:Surfactant and solvent input costs fluctuate with crude oil indices, compressing margin stability for mid-tier formulators.
- California ARB de facto standard:Stringent VOC limits in the state's consumer products regulation force national formulation compliance despite regional variation in enforcement.
- Concentrated professional distribution:Certified supply relationships with dealership networks in Germany limit market entry for non-OEM-approved brands.
Strategic Opportunities
- India commercial vehicle fleet expansion:Underpenetrated professional detailing channels present first-mover potential as BIS standards formalize.
- Subscription-based replenishment:Direct-to-consumer platforms enable recurring revenue capture from enthusiast segments previously served through retail.
- EU Green Deal chemical taxonomy:Bio-based certification incentives accelerate premium positioning for formulators with verified renewable content.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in pH-neutral polymer-safe surfactant blending commands wage premiums that strain mid-cap R&D budgets.
- Dual regulatory certification timelines:Simultaneous EPA registration and REACH dossier preparation extends product launch windows by 18-24 months.
- Legacy equipment compatibility:Water-borne formulations require spray system recalibration that detailers resist due to capital investment requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Interior Cleaner Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.1 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wipes, Sprays, Gels, Foams End User: Consumers, Dealerships, Maintenance Providers, OEMs Packaging Type: Bottles, Canisters, Pouches, Bulk Packs Application: Dashboard, Upholstery, Carpets, Windows |
| Companies Covered | 3M Company, Turtle Wax, Meguiar's Inc., Armor All, Sonax GmbH, Chemical Guys, Autoglym, Liqui Moly GmbH, Simoniz USA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Interior Cleaner Market Trends and Innovations
Formulation chemistry and distribution architecture are undergoing parallel transformation as regulatory pressure and channel fragmentation reshape competitive requirements.
Foam-based interior cleaners are migrating from niche professional applications toward mainstream adoption among independent detailers seeking extended dwell time on vertical carpet surfaces. The clinging formulation technology enables single-pass cleaning efficiency that spray applications cannot match. Equipment suppliers now bundle foam cannons with bulk concentrate systems to capture this workflow shift.
EPA restrictions under the Clean Air Act constrain solvent selection for domestic manufacturers, directly propelling water-based formulation R&D investment. The regulatory friction elevates compliance costs for petroleum-dependent legacy portfolios. California Air Resources Board standards operate as the effective national benchmark through sheer market scale, forcing reformulation decisions in Ohio and Texas laboratories alike.
Automotive aftermarket retail tilts toward e-commerce and direct-to-consumer platforms as traditional auto parts stores cede shelf space. Digital-native brands capture enthusiast segment loyalty through content-driven education and subscription replenishment models. This channel rotation concentrates in North America and Germany where vehicle ownership density and shipping infrastructure support last-mile delivery economics.
Automotive Interior Cleaner Market Segmentation
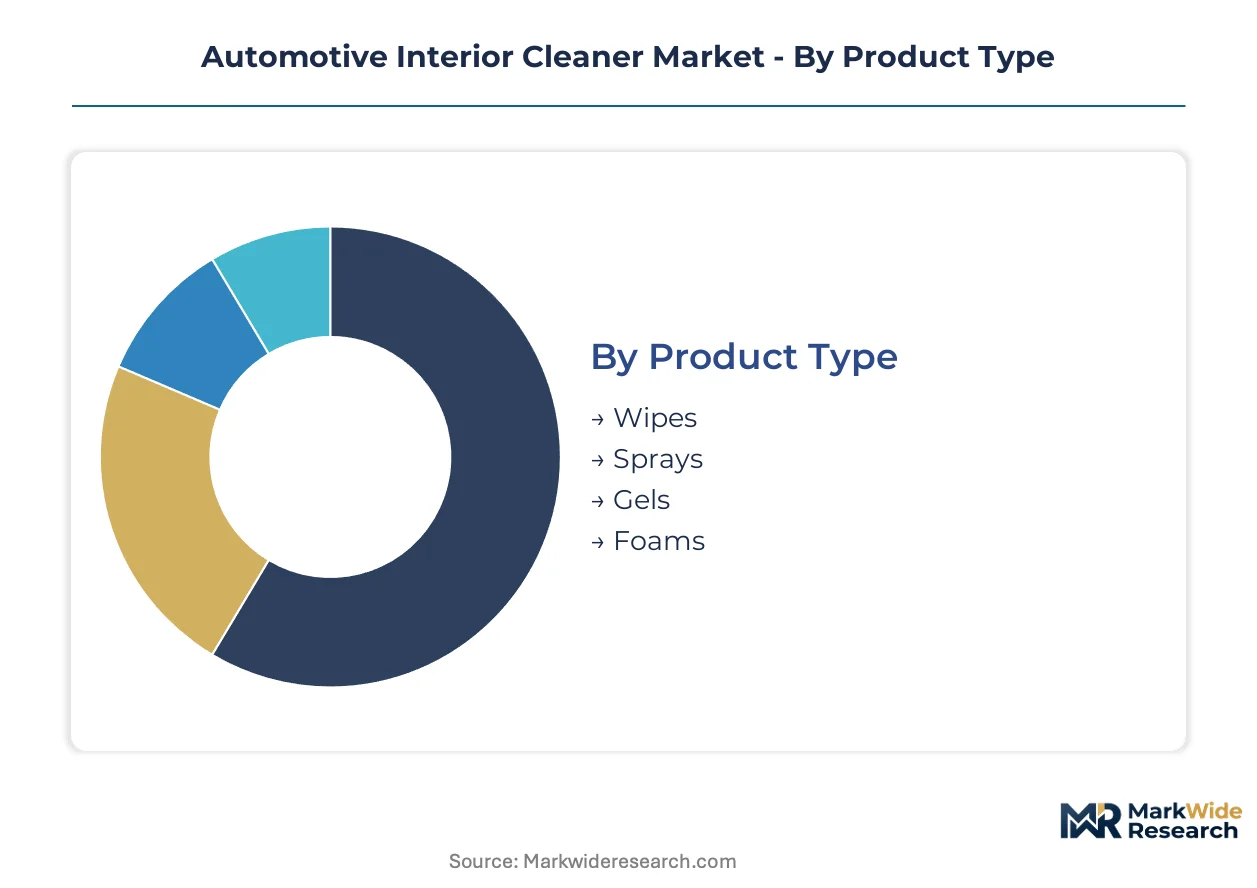
Automotive interior cleaner segmentation reflects divergent performance requirements across amateur detailing, professional fleet maintenance, and OEM-certified channels. Formulators must balance pH-neutral polymer safety, VOC compliance, and application ergonomics across distinct use cases.
Product Type:
Application ergonomics span quick wipe-downs to deep extraction protocols, with dwell time and surface adhesion driving chemistry selection.
- Sprays:Aqueous surfactant blends in trigger-dispensed formats dominate volume shipments due to dashboard and hard-surface versatility. Demand concentrates in US retail channels where consumers prioritize application speed over deep cleaning efficacy.
- Foams:Clinging formulations extend dwell time on vertical carpet and fabric surfaces, enabling single-pass efficiency that detailers value for labor cost control. Germany's professional detailing networks favor foam cannons bundled with bulk concentrate systems.
- Wipes:Pre-saturated towelettes capture premium positioning through convenience, with compact canister formats dominating glove compartment storage scenarios.
- Gels:High-viscosity formulations target precision application on textured plastics and leather grain where runoff must be eliminated.
Established volume favors sprays; emerging adoption favors foams.
End User:
Procurement authority shifts from individual preference to corporate specification as vehicle fleet scale increases.
- Maintenance Providers:Fleet operators in Germany and the US now enforce quarterly cabin sanitization protocols, expanding contract volumes for professional-grade concentrates. EPA-compliant water-borne formulations displace solvent-based chemistries in these high-frequency applications.
- Consumers:Enthusiast segments in North America drive subscription replenishment through direct-to-consumer platforms, with pH-neutral claims influencing purchase decisions for leather upholstery protection.
- Dealerships:Certified supply relationships with OEM networks in Germany limit market entry to approved formulators meeting specific polymer compatibility standards.
- OEMs:Factory-applied interior protection programs require bulk concentrate supply agreements with formulation disclosure under REACH registration requirements.
Maintenance providers are expanding most quickly; consumer channels retain margin concentration.
Packaging Type:
Distribution economics and usage frequency determine primary container selection across retail and professional channels.
- Bottles:Standard trigger-spray and flip-top formats dominate mass-market retail shelf presence, with 16-24 ounce sizes optimizing shipping cube efficiency for e-commerce fulfillment.
- Canisters:Rigid plastic tubs with moisture-sealing lids preserve wipe saturation integrity through variable temperature vehicle storage conditions.
- Pouches:Flexible film packaging reduces material cost and shipping weight for single-use or travel-format products targeting ride-share driver segments.
- Bulk Packs:Five-gallon pails and drum formats serve high-volume professional users with dedicated dilution and dispensing equipment.
Retail velocity favors bottles; professional conversion favors bulk packs.
Application:
Surface material composition dictates pH requirements and mechanical action tolerance across cabin zones.
- Upholstery:Fabric and leather seating surfaces require conditioning agents that restore suppleness without residue accumulation that attracts subsequent soiling. German premium vehicle density sustains above-average per-unit consumption of leather-specific formulations.
- Dashboard:UV-stabilized polymers demand pH-neutral cleaners between 6.5 and 7.5 to prevent surface etching and premature embrittlement.
- Carpets:High-pile fiber extraction requires foam or gel formulations with extended dwell capability for soil suspension before extraction.
- Windows:Glass-specific surfactants eliminate streaking without ammonia content that degrades tinted film or surrounding trim plastics.
Upholstery commands formulation premium; dashboard applications drive volume scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German OEM-certified detailing standards command 40% pricing premiums over US mass-market formulations, while Indian commercial fleet expansion creates volume absorption at the economy tier.
United States
California Air Resources Board VOC limits de facto govern national formulation standards, forcing Ohio and Texas laboratories into compliance. EPA registration timelines extend product launches by 18-24 months. The Southeast corridor concentrates contract manufacturing for water-borne chemistry platforms serving fleet maintenance providers.
Germany
Premium vehicle density sustains above-average per-unit consumption of leather-specific formulations. REACH dossier requirements favor regional producers with established compliance infrastructure. The Stuttgart-Munich corridor anchors OEM-certified supply relationships that exclude non-approved brands.
China
Domestic automaker aftersales networks expand factory-applied interior protection programs requiring bulk concentrate supply. GB standards for volatile organic compounds in consumer products tighten formulation flexibility. The Yangtze River Delta clusters surfactant production for cost-competitive export formulations.
India
Commercial vehicle fleet operators underpenetrated in professional detailing channels present first-mover potential. BIS standards formalization accelerates as domestic OEMs adopt international cabin hygiene protocols. Maharashtra and Gujarat concentrate automotive manufacturing hubs driving aftermarket chemical demand.
Japan
MetI guidance on chemical substance management elevates disclosure requirements for imported formulations. JIS standards for automotive care products create certification barriers for non-domestic suppliers. The Kanto region maintains precision manufacturing clusters for pH-neutral polymer-safe surfactant blending.
Automotive Interior Cleaner Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in formulation chemistry and bulk concentrate supply. The vendor base stratifies across mass-market retail, professional-grade distribution, and OEM-certified channels with limited cross-tier mobility. Three archetypes dominate: heritage brands with retail shelf dominance, digital-native direct-to-consumer specialists, and regional producers with regulatory compliance infrastructure. Competitive moves concentrate on e-commerce platform expansion and bio-based certification acquisition.
Within the heritage brand tier, 3M Company and Turtle Wax occupy positions sustained through established retail partnerships and mass-market channel penetration. Among European specialists, Sonax GmbH exemplifies the professional-grade distribution archetype through certified supply relationships with dealership networks. Chemical Guys represents the digital-native model, anchoring enthusiast segment loyalty through content-driven education and subscription replenishment platforms.
| Leading Market Players |
|---|
| 3M Company |
| Turtle Wax |
| Meguiar's Inc. |
| Armor All |
| Sonax GmbH |
| Chemical Guys |
| Autoglym |
| Liqui Moly GmbH |
| Simoniz USA |
| Others |
Pricing and Supply Chain Analysis
The Rotterdam-Antwerp chemical corridor anchors surfactant and solvent logistics for European formulators, with barge and rail cost fluctuations directly transmitting to OEM-certified premium tiers while compressing margin buffers in mass-market spray formulations. This freight nexus concentrates supply-side leverage among REACH-registered producers who capture pricing power through compliance infrastructure that imported competitors cannot replicate.
Pricing Analysis
The customization-premium spread separates bulk concentrate supply agreements for fleet operators from configured-to-order OEM-certified detailing programs. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale, with pH-neutral polymer-safe formulations commanding substantial premiums over commodity surfactant blends. Pricing pressure stems from petrochemical feedstock volatility that squeezes mid-tier formulators between crude-indexed input costs and fixed contract pricing with maintenance providers. Fleet procurement teams exhibit highest price sensitivity due to quarterly sanitization protocol volumes, while enthusiast consumers through direct-to-consumer platforms show lowest sensitivity to per-unit premiums.
Supply Chain Analysis
Export-control regime friction on specialized surfactant manufacturing equipment limits technology transfer to emerging production hubs, constraining capacity expansion outside established chemical clusters. Supply concentrates in Germany, the United States, and China, with surfactant production drawing from petroleum derivatives, bio-based alcohols, and conditioning agent feedstocks. Single-source vulnerability pervades pH-neutral polymer-safe surfactant blending expertise, where specialized formulation chemists command wage premiums that strain mid-cap R&D budgets. Distribution runs through certified dealership networks in Germany, mass-market retail in North America, and direct-to-consumer platforms capturing enthusiast segment loyalty.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are reshaping competitive positioning as subscription replenishment models and digital-native brand ecosystems displace traditional retail shelf dominance, with interoperability between bulk concentrate systems and foam cannon equipment bundling creating new winner-take-most dynamics.
For Market Incumbents: Insulate certified supply relationships with OEM networks through accelerated bio-based certification acquisition under EU Green Deal chemical taxonomy, while backward integration into captive surfactant production hedges petrochemical feedstock volatility that threatens contract margin stability with fleet maintenance providers.
For New Entrants and Emerging Players: India's underpenetrated commercial vehicle fleet detailing channels present first-mover positioning as BIS standards formalize and domestic OEMs adopt international cabin hygiene protocols, with professional-grade foam concentrate supply bundled with equipment financing offering the most penetrable go-to-market angle.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with automotive care divisions lacking dedicated REACH compliance infrastructure, with long-term viability hinging on water-borne formulation patent portfolios and regional production footprint density; the signal to watch is EPA registration timeline compression as state-level chemical restrictions tighten.
| Strategic Initiative | Industry Significance |
|---|---|
| Bio-Based Certification Acquisition | EU Green Deal chemical taxonomy incentives accelerate premium positioning for verified renewable content formulators. |
| Direct-to-Consumer Platform Launch | Subscription replenishment models capture enthusiast segment loyalty previously served through retail auto parts stores. |
| Fleet Maintenance Contract Expansion | Quarterly cabin sanitization protocols in Germany and the US expand contract volumes for professional-grade concentrates. |
| REACH Compliance Infrastructure Investment | Full substance disclosure requirements favor regional European producers over imported competitors with dossier preparation gaps. |
| Foam Cannon Equipment Bundling | Clinging formulation technology adoption among detailers creates system-level lock-in through workflow-integrated supply agreements. |
Research Methodology
A spread of perspectives from formulation chemists, fleet maintenance procurement directors, OEM aftersales managers, and automotive aftermarket distributors converged on the working assumptions that shaped demand modeling and competitive intensity scoring. Primary interviews with these stakeholders combined with secondary validation through EPA registration databases, REACH dossier filings, customs trade data on surfactant imports, and vehicle production statistics from national automotive associations. Bottom-up segment sizing and top-down macroeconomic constraint checks triangulated volume and value estimates.
Demand-supply-balance dynamics across the analysis window anchored the forecast framework, with segmentation modeling spanning product type, end-user archetype, packaging format, and application surface. CAGRs derived from trend extrapolation of fleet hygiene mandate adoption curves, regulatory phase-in schedules, and channel shift velocity toward e-commerce platforms. Industry-specific inputs included pH-neutral formulation R&D investment flows and professional detailing equipment upgrade cycles.
The forecast holds incumbent behavior within observed patterns; aggressive moves by digital-native direct-to-consumer specialists or accelerated bio-based solvent platform launches would shift outcomes beyond modeled ranges. Material shifts in EPA state-level preemption rulings, REACH substance restriction expansions, or crude oil index volatility would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
US Automotive Wrap Films Market
Automotive Interior & Exterior
Automotive Mudguards Market
Automotive Interior & Exterior
Automotive Bovine Leather Market
Automotive Interior & Exterior
Automotive Sunroof Market
Automotive Interior & Exterior
Auto Dimming Mirror Market
Automotive Interior & Exterior
Vehicle Interior Air Quality Sensor Platforms Market
Automotive Interior & Exterior
Automotive Intelligent Rear-View Mirror Market
Automotive Interior & Exterior
Automotive Portable Refrigerator Market
Automotive Interior & Exterior
Automotive Roof Liners Market
Automotive Interior & Exterior
Automotive Heated Seat Market
Automotive Interior & Exterior
Automotive Cabin Insulation Market
Automotive Interior & Exterior
Automotive Airbag Fabric Market
Automotive Interior & Exterior
Automotive Liftgate Market
Automotive Interior & Exterior
Zero Gravity Seat Market
Automotive Interior & Exterior
Global Automotive Window Power Sunshade Market
Automotive Interior & Exterior
Automotive Energy Absorption (EA) Pads Market