
 Low-Noise Anti-Squeak Additives for Automotive Interiors Market | 2026-2036
Low-Noise Anti-Squeak Additives for Automotive Interiors Market Size, Share, and Industry Trends Forecast 2026-2036
Low-Noise Anti-Squeak Additives for Automotive Interiors Market Insights
Specialty chemical producers in Germany is expanding capacity for automotive-grade friction modifiers to serve premium OEM programs. BASF leverages its polymer blending expertise to supply OEMs with tailored additive packages. Evonik Industries anchors its position through surface modification technologies that reduce stick-slip in thermoplastic assemblies. Croda International specializes in bio-derived slip agents that help Tier-1 suppliers meet sustainability targets without sacrificing acoustic performance.
Low-noise anti-squeak additives are surface-active compounds, typically comprising PTFE, silicone, or graphite dispersed at 0.5-5 wt% loadings, that modify the tribological interface between contacting plastic or metal interior components to eliminate audible friction. These materials function by forming low-shear transfer films that prevent stick-slip oscillations at polymer-polymer and polymer-metal contact points, directly addressing NVH complaints that degrade perceived vehicle quality. Silicone-based formulations currently dominate OEM specifications due to their broad temperature stability and compatibility with polypropylene and ABS substrates, while fluoropolymer grades command premium positioning in luxury segments where ultra-low friction coefficients are specified. Nanocomposite technologies represent the fastest-growing technology category as suppliers integrate layered silicates or ceramic platelets to achieve synergistic lubrication and mechanical reinforcement in thin-walled interior parts.
FDA regulations on indirect food contact materials influence additive selection for cabin components near passenger touchpoints, while EPA guidelines on perfluorinated substances constrain fluoropolymer formulation strategies in US-sold vehicles. ECHA's REACH restrictions on graphite purity and particle classification affect raw material sourcing for European compounders, creating compliance-driven demand for certified supply chains. Stakeholders must monitor evolving substance restrictions across multiple jurisdictions while building formulation flexibility that permits rapid substitution between silicone, mineral, and advanced polymer lubricant platforms.
Market Dynamics
REACH substance restrictions and the EU Green Deal are forcing formulators to abandon legacy graphite and mineral oil lubricants in favor of silicone and fluoropolymer alternatives that satisfy tightening chemical content rules for cabin assemblies.
Growth Catalysts
- Electric vehicle NVH specifications:Battery-electric platforms eliminate engine noise, exposing friction-induced squeaks in interior assemblies. OEMs specify anti-squeak additives at higher loadings to maintain perceived quality in silent powertrain environments.
- REACH Annex XVII expansions:ECHA restrictions on graphite purity and particle classification create compliance-driven demand for certified silicone supply chains among European compounders serving premium automotive programs.
- Luxury segment acoustic differentiation:German premium automakers maintain rigorous NVH standards that mandate ultra-low friction coefficients in thermoplastic contact points, pulling advanced additive formulations into serial production.
Market Restraints
- Fluoropolymer input cost volatility:PTFE feedstock prices fluctuate with fluorspar mining concentration in China, compressing margins for formulators serving cost-sensitive standard vehicle segments.
- REACH authorization bottlenecks:ECHA's substance of very high concern listings delay commercialization timelines for novel surface-active chemistries, extending R&D-to-revenue cycles beyond typical automotive program windows.
- Silicone compatibility limitations:Polar thermoplastic substrates including polyamides and polycarbonates exhibit poor adhesion with standard silicone slip agents, restricting formulation options in high-temperature interior zones.
Strategic Opportunities
- India automotive production expansion:Domestic OEMs and joint ventures operating under PLI scheme incentives present untapped demand for NVH-optimized cabin materials as local premium vehicle output scales.
- Nanocomposite technology convergence:Layered silicate integration with fluoropolymer matrices enables simultaneous friction reduction and mechanical reinforcement in thin-walled injection molded parts.
- EU Green Deal circularity mandates:Recyclable mono-material interior designs require bio-derived slip agents that maintain acoustic performance through multiple reprocessing cycles without cross-contamination.
Industry Challenges
- Formulation-to-substrate matching complexity:Each polymer-polymer and polymer-metal contact pair demands customized additive packages, multiplying qualification workloads for Tier-1 suppliers managing diverse OEM material specifications.
- NVH testing protocol fragmentation:Absence of standardized stick-slip measurement methods across German, Japanese, and US automakers forces redundant validation cycles and delays platform approvals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low-Noise Anti-Squeak Additives for Automotive Interiors Market |
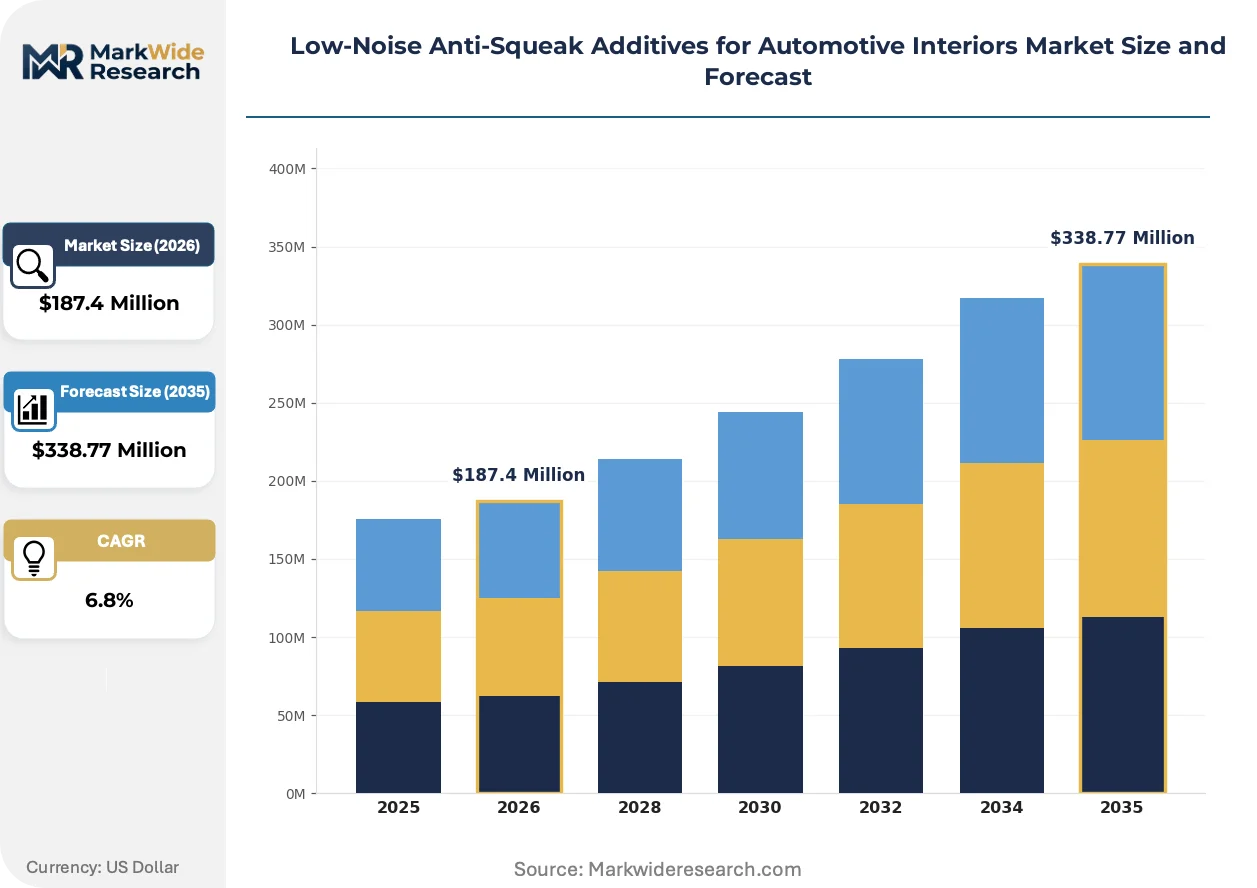
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Graphite, PTFE, Molybdenum Disulfide, Silicone, Fluoropolymer, Mineral Technology: Surface Modification, Polymer Blending, Nanocomposite, Microencapsulation, Emulsion, Solution Processing Application: Door Panels, Dashboard Components, Seat Frames, Headliners, Center Consoles, Air Vents End User: OEMs, Tier-1 Suppliers, Aftermarket Service Providers, Vehicle Refurbishment Shops |
| Companies Covered | Lubrizol, BASF, Dow, Evonik Industries, Clariant, DuPont, LANXESS, Croda International, Avient, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low-Noise Anti-Squeak Additives for Automotive Interiors Market Trends and Innovations
Additive technologies are pivoting toward multifunctional surface engineering that combines acoustic damping with mechanical durability, while regulatory pressure accelerates substitution away from legacy chemistries.
Silicone-fluoropolymer hybrid formulations are overtaking conventional single-polymer additives in premium electric vehicle programs. These materials form stable transfer films across broader temperature ranges than standalone chemistries. German and Korean battery-electric OEMs specify hybrids for battery housing adjacent trim where thermal cycling extremes occur.
ECHA's evolving REACH restrictions on per- and polyfluoroalkyl substances constrain fluoropolymer formulation strategies for vehicles sold in Europe. Formulators must maintain dual product portfolios or accelerate silicone-based alternatives that satisfy substance restrictions without sacrificing coefficient-of-friction performance. US EPA guidelines on perfluorinated substances create parallel compliance pressures for North American supply chains.
Direct OEM-formulator technical partnerships are compressing traditional distribution channels. Tier-1 suppliers historically mediated additive specification, but premium automakers now engage BASF, Evonik, and Croda directly for co-development of vehicle-platform-specific packages. This pattern concentrates most visibly in Germany where vertically integrated material development centers sit adjacent to OEM engineering headquarters.
Low-Noise Anti-Squeak Additives for Automotive Interiors Market Segmentation
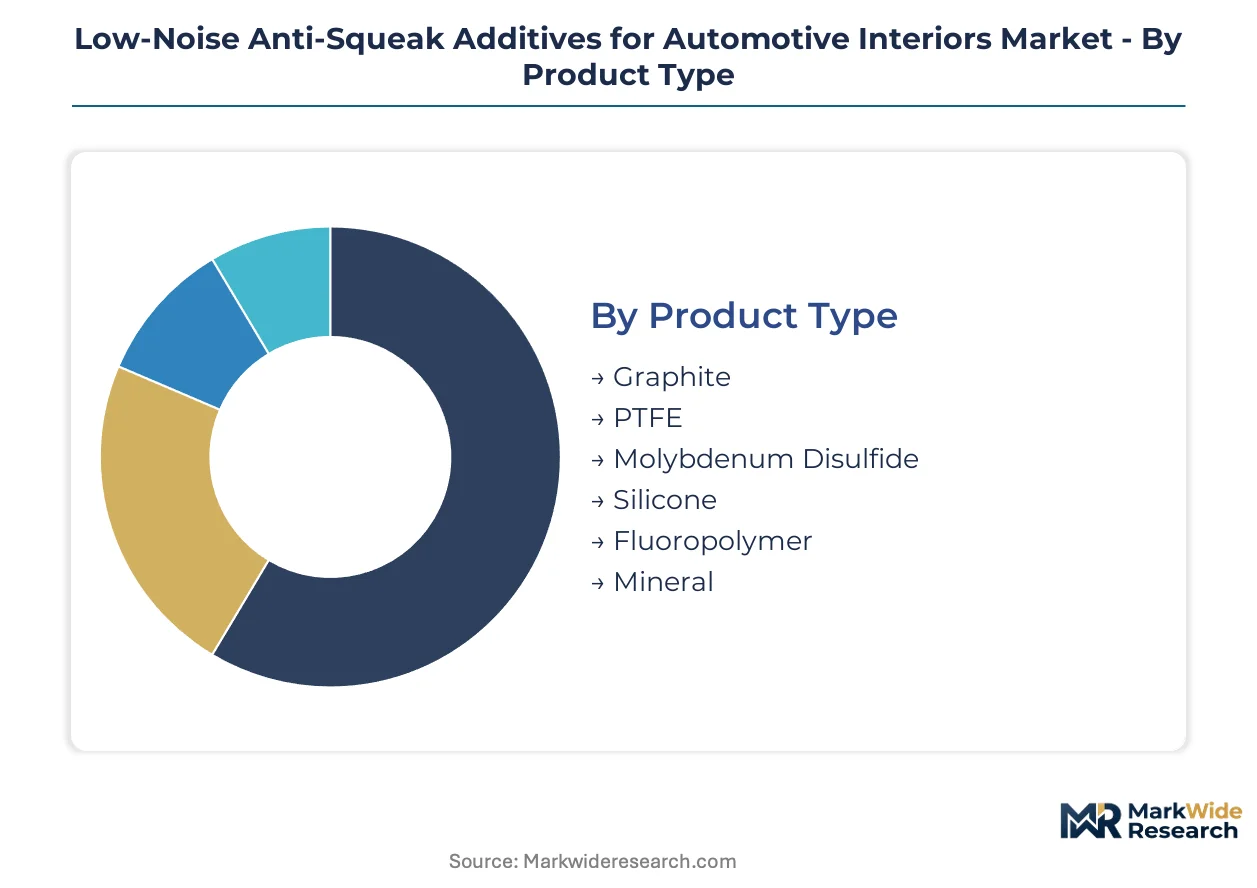
Segmentation in this market maps directly to formulation complexity and regulatory exposure. Product type determines REACH compliance burden, while technology choice dictates qualification timelines with German premium OEMs.
Product Type:
REACH Annex XVII restrictions on perfluorinated substances and graphite purity standards create divergent certification pathways across chemistries. ECHA substance of very high concern listings force formulators to maintain dual technical portfolios.
- Silicone:Polydimethylsiloxane-based formulations dominate serial production for polypropylene and ABS substrates. German OEMs specify silicone additives at higher loadings in battery-electric platforms where thermal cycling demands broad temperature stability.
- Fluoropolymer:PTFE and fluorinated ethylene propylene variants command premium positioning in luxury segments requiring ultra-low friction coefficients. EPA guidelines on perfluorinated substances constrain formulation strategies for US-sold vehicles, compressing margins through feedstock volatility.
- Graphite:Lamellar carbon lubricants face ECHA particle classification restrictions that complicate European supply chains.
- Molybdenum Disulfide:Transition metal dichalcogenide chemistry serves high-load metal-polymer contacts in seat frame assemblies.
- Mineral:Legacy oil-based lubricants are retreating from OEM specifications under EU Green Deal circularity mandates.
Silicone sits at the top of the volume ranking, with fluoropolymer climbing the fastest.
Technology:
Process selection determines capital intensity and scale economics. Surface modification and nanocomposite platforms require specialized equipment that fragments supplier capabilities.
- Nanocomposite:Layered silicate or ceramic platelet integration with polymer matrices achieves simultaneous friction reduction and mechanical reinforcement. Korean battery-electric OEMs specify nanocomposite additives for thin-walled battery housing adjacent trim where space constraints dominate.
- Surface Modification:Plasma or chemical grafting techniques alter substrate surface energy without bulk additive loading. German Tier-1 suppliers favor this approach for recyclable mono-material interior designs that must survive multiple reprocessing cycles.
- Polymer Blending:Masterbatch compounding of lubricant concentrates into thermoplastic resins serves high-volume injection molding operations.
- Microencapsulation:Shell-core particle architectures enable controlled release of active lubricants under mechanical stress.
- Emulsion:Aqueous dispersion formats suit post-molding coating applications on assembled interior modules.
- Solution Processing:Solvent-borne systems persist in specialty applications requiring deep substrate penetration.
Polymer blending commands the highest shipment volumes, while nanocomposite platforms are expanding most quickly.
Application:
NVH criticality varies by passenger contact frequency and thermal exposure. Dashboard and door panel applications drive formulation specifications across OEM programs.
- Dashboard Components:Large surface area assemblies with multiple polymer-polymer contact points generate the most warranty claims. German premium automakers mandate anti-squeak treatment for all visible and hidden dashboard interfaces.
- Door Panels:Map pocket, armrest, and trim attachment points experience repetitive mechanical loading. Electric vehicle platforms expose these assemblies to wider temperature swings than internal combustion architectures.
- Seat Frames:Metal-polymer interfaces in track mechanisms and adjustment hardware require high-load lubrication.
- Center Consoles:Sliding lid mechanisms and storage compartment hinges demand low-friction films with cosmetic transparency.
- Headliners:Overhead component attachments present acoustic challenges in silent powertrain environments.
- Air Vents:Louver pivot points require precision friction control without outgassing that degrades interior air quality.
Dashboard components generate the largest absolute demand, with door panels gaining share fastest in electric vehicle programs.
End User:
Channel structure determines technical engagement depth and pricing power. Direct OEM relationships compress traditional distribution margins.
- OEMs:Premium German and Korean battery-electric manufacturers engage formulators directly for platform-specific co-development. These partnerships bypass Tier-1 mediation and concentrate technical resources at vehicle development centers.
- Tier-1 Suppliers:Interior module integrators manage diverse OEM material specifications and qualification workloads. Their procurement decisions balance formulation performance against inventory simplification across customer programs.
- Aftermarket Service Providers:Repair channel demand concentrates on warranty remediation and squeak-related customer complaints.
- Vehicle Refurbishment Shops:Secondary market applications focus on cosmetic restoration of aged interior assemblies.
Tier-1 suppliers handle the highest transaction volumes, with OEM direct engagement showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands premium additive specifications while China scales production for mass-market electric vehicles. Regulatory divergence between REACH in Europe and EPA guidelines in North America fragments formulation strategies across major automotive markets.
Germany
Battery-electric platforms from BMW, Mercedes-Benz, and Audi expose friction-induced noise in silent cabins, pulling advanced silicone-fluoropolymer hybrids into serial production. ECHA REACH Annex XVII restrictions on perfluorinated substances force formulators to maintain dual technical portfolios for EU and export markets. The Stuttgart and Munich engineering clusters concentrate direct OEM-formulator partnerships that bypass traditional Tier-1 distribution channels.
United States
EPA guidelines on perfluorinated substances constrain PTFE-based formulations for vehicles sold domestically, compressing margins through feedstock volatility. FDA indirect food contact regulations influence additive selection for cabin components near passenger touchpoints. Detroit-area automotive engineering centers and California electric vehicle startups drive divergent specification trends across premium and mass-market segments.
China
Domestic electric vehicle production from BYD, NIO, and Xpeng generates volume demand for cost-optimized anti-squeak solutions in interior assemblies. MIIT vehicle quality standards incorporate NVH metrics that elevate additive specifications for premium domestic brands. Yangtze River Delta chemical manufacturing hubs scale polymer blending capacity to serve both local OEMs and export compounders.
South Korea
Hyundai and Kia battery-electric platforms specify nanocomposite additives for thin-walled battery housing adjacent trim where space constraints dominate thermal management. MFDS chemical safety assessments parallel REACH substance restrictions, creating compliance alignment for Korean suppliers serving European OEMs. Seoul Capital Area and Busan-Ulsan automotive clusters anchor formulation development for next-generation interior materials.
India
PLI scheme incentives attract premium vehicle joint ventures that import NVH-optimized cabin material specifications from parent operations in Germany and Japan. BIS automotive component standards increasingly reference friction and wear performance in interior assemblies. Maharashtra and Gujarat manufacturing corridors scale Tier-1 supplier capacity to localize additive compounding for domestic OEM programs.
Low-Noise Anti-Squeak Additives for Automotive Interiors Market Competitive Landscape
German producers anchor the premium formulation tier; US and Swiss specialists hold positions in diversified chemical portfolios. The market structure concentrates around integrated polymer science conglomerates with captive lubricant expertise, alongside focused additive houses serving automotive-specific channels. Three archetypes dominate: diversified chemical majors with polymer blending capabilities, surface modification specialists with tribology expertise, and bio-derived slip agent innovators targeting circularity mandates. Capacity expansion in Asia-Pacific and direct OEM technical partnerships represent the dominant competitive vectors.
Among diversified chemical majors, BASF, Evonik Industries, and Croda International occupy positions that exemplify distinct strategic archetypes. BASF represents integrated polymer science capabilities spanning masterbatch compounding and tailored additive packages. Evonik Industries anchors the surface modification specialist tier with tribological interface engineering expertise. Croda International sits within the bio-derived innovation arc, supplying slip agents that help Tier-1 suppliers meet EU Green Deal sustainability targets without sacrificing acoustic performance.
| Leading Market Players |
|---|
| Lubrizol |
| BASF |
| Dow |
| Evonik Industries |
| Clariant |
| DuPont |
| LANXESS |
| Croda International |
| Avient |
| Others |
Pricing and Supply Chain Analysis
Polymer compounding specialists concentrated in Germany's Stuttgart and Munich engineering clusters command wage premiums that widen spreads between premium silicone-fluoropolymer hybrid formulations and commodity mineral oil alternatives. REACH compliance costs for certified supply chains feed directly into price differentials across formulation tiers.
Pricing Analysis
Capacity additions in China's Yangtze River Delta chemical manufacturing hubs are reshaping price floors for standard-grade silicone additives serving mass-market electric vehicle programs. Contract-based long-term offtake agreements dominate procurement between German OEMs and BASF or Evonik, insulating premium tiers from spot volatility. Price differentiation hinges on REACH certification grade and volume scale, with standard segments facing compression from cost-optimized Chinese supply. Tier-1 suppliers exhibit highest price sensitivity due to inventory simplification pressures across diverse OEM programs.
Supply Chain Analysis
Freight cost differentials between German chemical manufacturing clusters and Asia-Pacific compounding centers fragment sourcing strategies for European formulators. Raw material supply draws from Chinese fluorspar mining for PTFE feedstock, German polydimethylsiloxane production for silicone bases, and Indian graphite processing for legacy lubricant grades. Tariff exposure on fluoropolymer intermediates creates margin vulnerability for US-sold vehicle specifications. Distribution runs through direct OEM-formulator technical partnerships that displace traditional Tier-1 mediation in premium segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on substitution toward silicone-fluoropolymer hybrids that command premium positioning as battery-electric platforms eliminate engine masking noise.
For Market Incumbents: Anchor formulation leadership through captive supply of REACH-certified silicone feedstocks and backward integration into surface modification technology licensing. Defend against nanocomposite disruptors by accelerating qualification timelines with German premium OEMs. Prioritize certification investment for EU Green Deal circularity mandates to lock in mono-material interior program wins. For New Entrants and Emerging Players: REACH Annex XVII expansions in Europe open a window for bio-derived slip agent specialists to capture sustainability-driven procurement shifts at Croda's Tier-1 customer base. Target India's PLI scheme automotive corridors where domestic OEMs import NVH specifications from German parent operations. Pursue joint development agreements with Korean battery-electric OEMs seeking thin-walled trim solutions. For Investors and Strategic Acquirers: Diversified chemical majors with polymer blending capabilities are the most active acquirer in this space, seeking tribology expertise to complete automotive material portfolios. Five-to-ten-year viability favors surface modification specialists with OEM-direct relationships over distribution-dependent commodity formulators. Monitor ECHA substance of very high concern listing velocity as inflection signal for portfolio substitution timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicone Feedstock | BASF secures REACH-certified supply chains against ECHA purity restrictions. |
| Nanocomposite Platform Development | Layered silicate integration enables Korean OEM thin-walled battery trim specifications. |
| Direct OEM Technical Partnership | Evonik bypasses Tier-1 distribution to co-develop vehicle-platform-specific packages. |
| Bio-Derived Slip Agent Scale-Up | Croda targets EU Green Deal circularity mandates for recyclable mono-material designs. |
| Capacity Expansion in India | Localized compounding serves PLI scheme joint ventures importing German NVH standards. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary engagement with Tier-1 supplier procurement leads, OEM platform engineers, aftermarket distributors, and specialty chemical R&D directors with secondary validation. Customs and trade data, ACC and Cefic industry reports, SEC 10-K filings from diversified chemical majors, and vehicle production databases anchored volume estimates. Bottom-up additive consumption modeling and top-down automotive interior materials spending analysis triangulated market sizing.
Historical reference periods spanning pre-pandemic baseline through electric vehicle platform ramp-up anchored the forecast window across the analysis window. Segmentation dimensions modeled include formulation chemistry, process technology, interior application, and end-user channel structure, with additional granularity on vehicle propulsion architecture. CAGRs derived from regression against automotive production forecasts and NVH content-per-vehicle trends. Input assumptions incorporated ECHA regulatory timeline probabilities and fluorspar supply concentration risk.
Revisions become necessary when REACH substance restriction timelines accelerate, fluorspar supply disruptions materialize, or battery-electric platform adoption curves diverge from automotive industry projections. Forecasts reflect documented assumptions about regulatory enforcement intensity and OEM qualification cycle durations. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Electrically Adjustable Outside Rear View Mirror (ORVM) Market
Automotive Interior & Exterior
Automotive Door Handle Sensors Market
Automotive Interior & Exterior
Automotive in-Cabin Air Quality Improvement Solutions Market
Automotive Interior & Exterior
Automotive Fridge Market
Automotive Interior & Exterior
Global Automotive Window Power Sunshade Market
Automotive Interior & Exterior
Africa and Middle East Automotive Sunroof Market
Automotive Interior & Exterior
Cup Holder Market
Automotive Interior & Exterior
Automotive Sealants Market
Automotive Interior & Exterior
Global Headliner (OE) Market
Automotive Interior & Exterior
Global on Highway Vehicle Lighting Market
Automotive Interior & Exterior
Automotive Heated Steering Wheel Market
Automotive Interior & Exterior
Automotive Panoramic Sunroof Market
Automotive Interior & Exterior
Automotive Structural Steel Market
Automotive Interior & Exterior
Fog Free Mirrors Market
Automotive Interior & Exterior
Global Automotive Intelligent Seats Market
Automotive Interior & Exterior
Automotive Soft Trim Interior Materials Market