
 Global Automotive Interiors Market | 2026-2036
Global Automotive Interiors Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Interiors Market Analysis
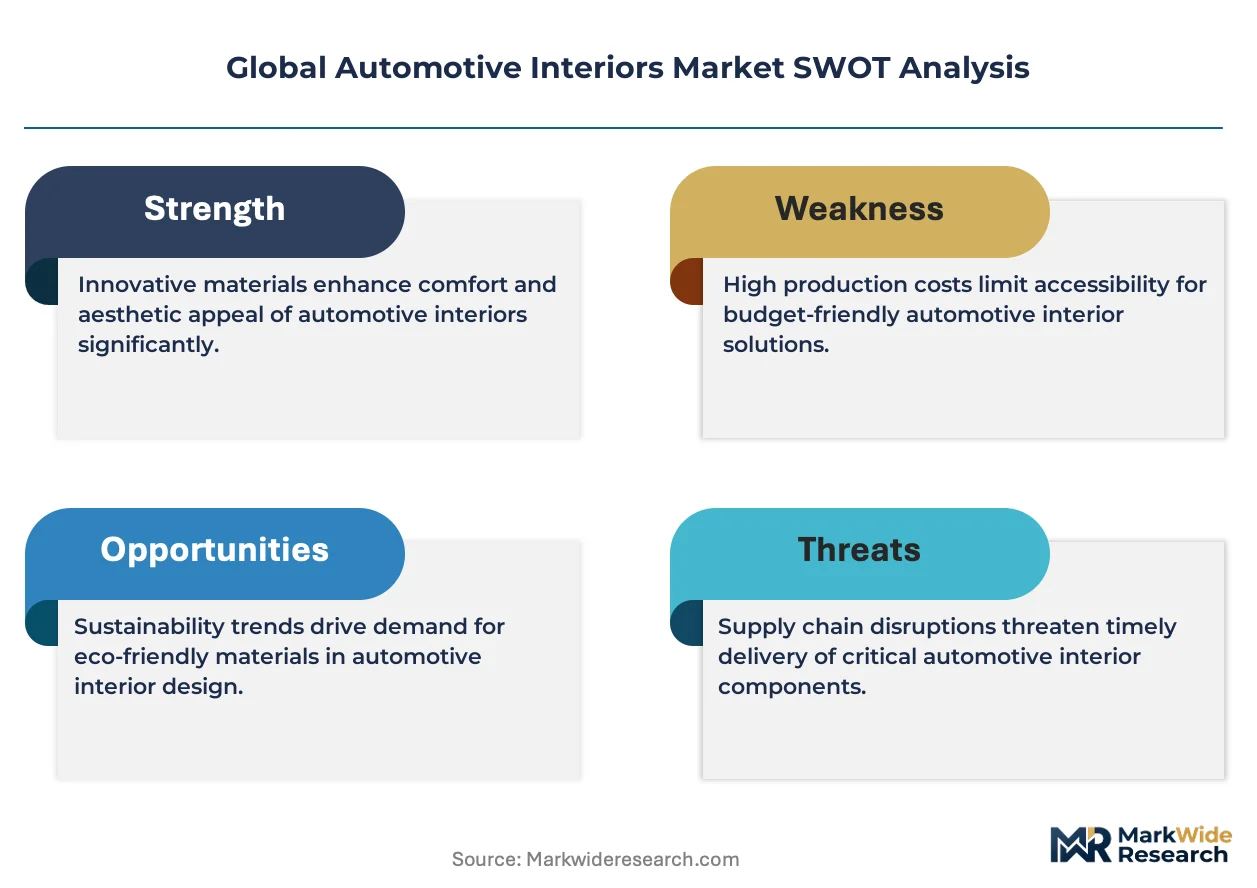
Asset-light manufacturing partnerships and modular leasing arrangements for cockpit assembly capacity is reshaping competitive entry barriers in automotive interiors. FORVIA Faurecia leverages its integrated seating and electronics portfolio to anchor high-value cockpit contracts with premium European OEMs. Lear Corporation specializes in electrical distribution systems embedded within seat architectures, differentiating its offering from conventional trim suppliers. Grupo Antolin dominates overhead console and lighting integration, sustaining margin pools through vertical control of thermoplastic component production.
Automotive interiors encompass the complete cabin environment including instrument panels, seating systems, door modules, and decorative surfaces, typically engineered to meet flammability standards, haptic performance targets, and NVH damping specifications while serving occupant safety and brand differentiation functions for vehicle manufacturers. Dashboard assemblies command substantial engineering investment due to integration of displays, airbag housings, and climate interfaces, whereas seating systems represent the largest material volume category with leather and fabric configurations stratifying across vehicle price tiers. Plastic compounds retain cost-driven volume in mass-market door panels, though wood veneer applications persist in luxury segments where aesthetic appeal justifies premium sourcing.
The EPA drives volatile organic compound limits on interior adhesives and coatings in the United States, while ECHA's REACH framework restricts specific plasticizers and flame retardants across European supply chains, and China's MEE enforces cabin air quality standards that filter through to material specifications from Tier-1 suppliers. These regulatory layers compound testing burdens but also create technical moats for suppliers with certified material libraries and cross-jurisdictional compliance infrastructure. Stakeholders must monitor evolving chemical restriction schedules and decide whether to standardize global material platforms or maintain region-specific formulations.
Market Dynamics
Electric vehicle architectures are compressing cockpit assembly cycles and forcing material substitutions as platforms shed weight to extend range. Tier-1 suppliers face simultaneous pressure from REACH chemical restrictions and OEM demands for faster program launches.
Growth Catalysts
- China MEE cabin air quality mandates:Domestic OEMs upgrade filtration and low-emission materials to comply with GB/T 27630 standards, pulling premium interior specifications into mass-market vehicle classes.
- Modular cockpit platforms:Shared electrical architectures across EV and ICE variants reduce engineering duplication and accelerate supplier contract wins for integrated module providers.
- Lightweight thermoplastic composites:Glass-reinforced polypropylene compounds displace metal substrates in structural seat components, cutting mass while maintaining crash performance targets.
Market Restraints
- Petrochemical feedstock volatility:Polypropylene and polyurethane resin costs fluctuate with crude oil indices, compressing margin visibility for injection-molded trim suppliers on fixed-price contracts.
- Regional chemical restriction divergence:ECHA REACH substance bans on specific plasticizers force formulation changes that lack regulatory reciprocity with EPA TSCA frameworks, fragmenting global material platforms.
- Leather substitution economics:Synthetic suede and microfiber alternatives achieve tactile parity at lower input costs, threatening premium hide processors in entry-luxury vehicle segments.
Strategic Opportunities
- India PLI scheme for auto components:Domestic manufacturing incentives attract cockpit module localization as global OEMs expand Indian EV assembly capacity.
- Biopolymer interior surfaces:Polylactic acid and castor-oil-derived polyamides qualify for EU Green Deal procurement preferences in public fleet tenders.
- Subscription-based interior feature activation:Heated seating and ambient lighting packages shift from hardware bundling to over-the-air software enablement, creating recurring revenue streams for electronics-integrated suppliers.
Industry Challenges
- Cross-functional talent scarcity:Suppliers struggle to hire engineers fluent in both polymer chemistry and embedded software development for smart surface integration.
- Homologation timeline compression:Accelerated EV launch cycles compress the 18-24 month material certification windows traditionally required for flammability and fogging validation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Interiors Market |
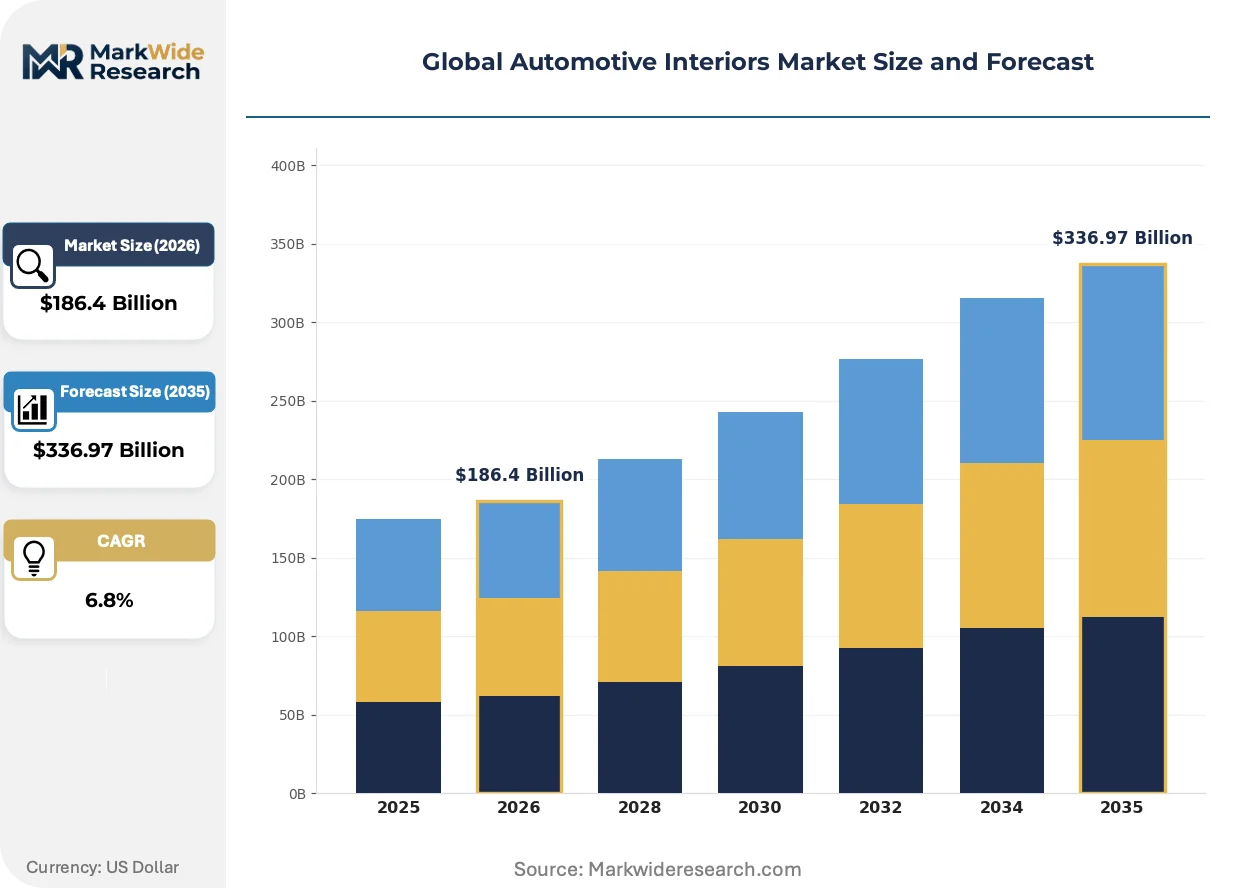
| Market Size in 2026 | $186.4 Billion |
| Market Size in 2035 | $336.97 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dashboard, Seating, Door Panels, Instrument Clusters Material: Leather, Fabric, Plastic, Wood End User: Original Equipment Manufacturers, Aftermarket Providers, Tier-1 Suppliers, Automotive Assemblers Feature: Comfort, Aesthetic Appeal, Durability, Customization |
| Companies Covered | Yanfeng Automotive Interiors, Grupo Antolin, FORVIA Faurecia, Continental AG, Toyota Boshoku Corporation, Adient, Magna International, DRÄXLMAIER, Lear Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Interiors Market Emerging Trajectories
Digital surface technologies and bio-based material portfolios are converging to redefine cabin architecture economics. Suppliers must now engineer for simultaneous software upgradability and end-of-life recyclability.
Large-format display integration is virtualizing the traditional instrument panel cluster. Premium OEMs in Germany and South Korea now specify curved OLED arrays spanning dashboard widths, eliminating discrete gauge housings and reducing mechanical component counts. This consolidation is virtualizing the supplier base as electronics specialists capture value previously held by injection molders.
ECHA REACH authorization requirements for flame retardants are forcing reformulation of polyurethane foam seating cores. European suppliers have accelerated bio-based polyol development to maintain supply continuity as halogenated additives face sunset dates. The seating segment bears the highest compliance burden, with German and French OEMs demanding certified material libraries ahead of regulatory deadlines.
Fleet procurement departments now specify residual value guarantees tied to interior durability metrics. Rental and mobility operators in the United States and United Kingdom negotiate wear-index clauses that transfer refurbishment risk to Tier-1 suppliers. This contractual evolution concentrates contract awards with suppliers offering predictive maintenance data and modular replacement architectures.
Global Automotive Interiors Market Segmentation
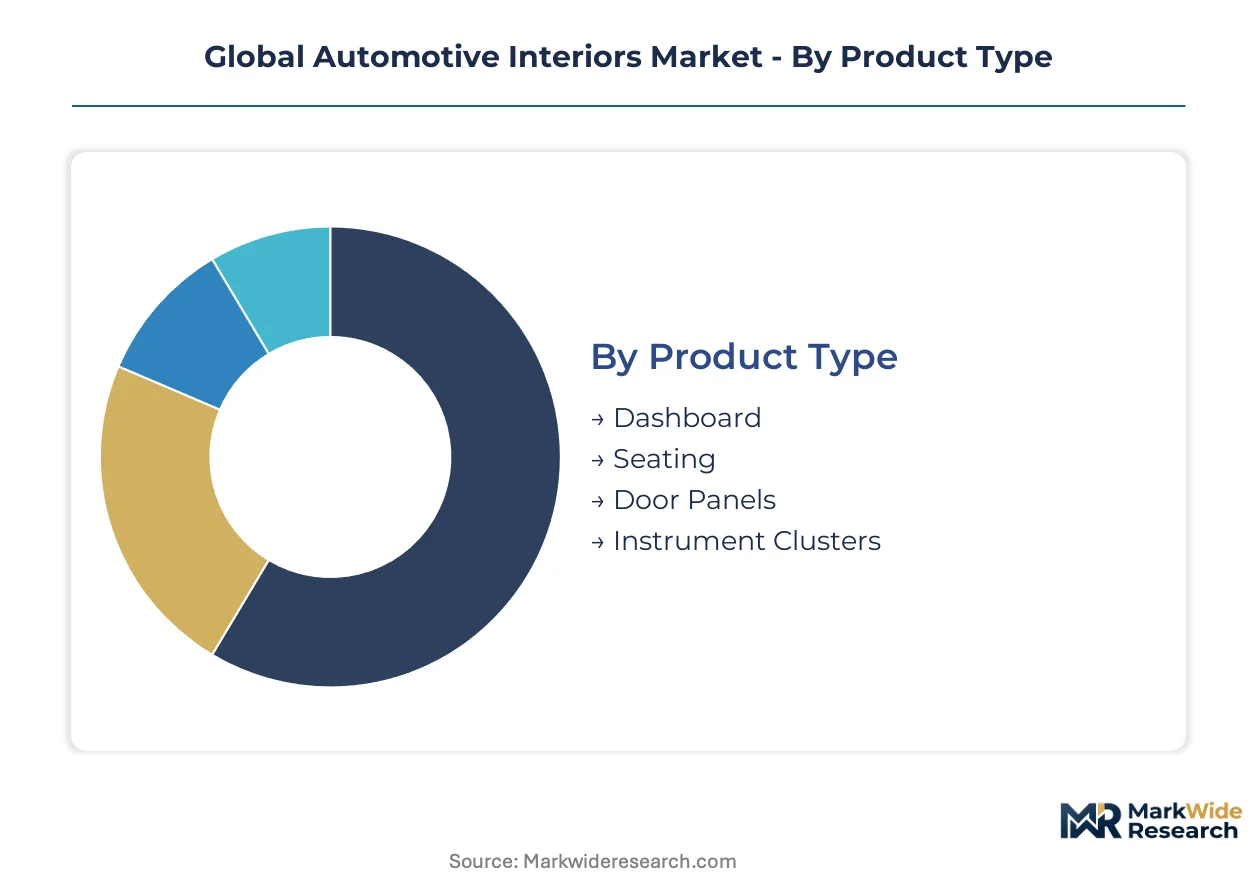
Automotive interiors segment along multiple axes that determine engineering priorities, margin structures, and supplier qualification requirements. Product type dictates capital intensity and assembly complexity. Material selection governs regulatory exposure and sustainability positioning. End-user channels shape contract terms and inventory risk allocation.
Product Type:
Application determines the integration depth with vehicle electronics and safety systems.
- Dashboard:Large-format display housings and airbag integration demand precision injection molding and electromagnetic shielding. German and South Korean OEMs specify curved OLED arrays that eliminate discrete gauge clusters. REACH chemical restrictions on flame-retardant additives complicate polyurethane foam backing formulations for this segment.
- Seating:Structural frames, foam cores, and trim covers represent the highest material volume category. Glass-reinforced polypropylene compounds displace metal substrates to cut mass in electric vehicle platforms. Chinese domestic OEMs upgrade leather and synthetic configurations to match European luxury benchmarks.
- Door Panels:Armrests, map pockets, and speaker grilles balance cost targets with haptic quality. Plastic compounds dominate mass-market applications.
- Instrument Clusters:Digital display modules are virtualizing traditional gauge housings, reducing mechanical component counts.
Seating commands the established base. The steepest expansion runs through dashboard assemblies.
Material:
Cost tier stratification maps directly to vehicle price positioning and regional regulatory exposure.
- Leather:Premium hide processing serves luxury segments where aesthetic differentiation justifies sourcing complexity. Italian and German tanneries face margin pressure from synthetic alternatives achieving tactile parity. ECHA REACH substance bans on specific tanning agents force supply chain restructuring.
- Fabric:Woven and knitted textiles dominate mass-market seating and door applications. Recycled polyethylene terephthalate content is rising to meet EU Green Deal procurement preferences. Japanese OEMs specify anti-soiling treatments that extend service life in fleet applications.
- Plastic:Polypropylene and ABS compounds retain cost-driven volume in injection-molded trim. Petrochemical feedstock volatility compresses margin visibility on fixed-price contracts.
- Wood:Veneer applications persist in ultra-premium segments where natural grain patterns signal craftsmanship. Supply concentrates in Alpine and Scandinavian sourcing regions with certified sustainable forestry.
Plastic commands the established base. The steepest expansion runs through fabric with recycled content.
End User:
Customer type determines contract duration, technical specification authority, and aftermarket exposure.
- Original Equipment Manufacturers:Vehicle brands hold final specification authority and negotiate multi-year platform contracts. Volkswagen Group and Hyundai Motor specify integrated cockpit modules that bundle seating, electronics, and trim.
- Aftermarket Providers:Independent distributors serve collision repair and vehicle customization channels. Inventory risk concentrates with wholesalers serving fragmented installer networks.
- Tier-1 Suppliers:FORVIA Faurecia and Lear Corporation contract directly with OEMs for complete cockpit assembly. These suppliers bear homologation responsibility for flammability and fogging validation.
- Automotive Assemblers:Contract manufacturers in emerging EV hubs purchase pre-integrated interior modules to compress launch timelines.
Original Equipment Manufacturers command the established base. The steepest expansion runs through Tier-1 Suppliers.
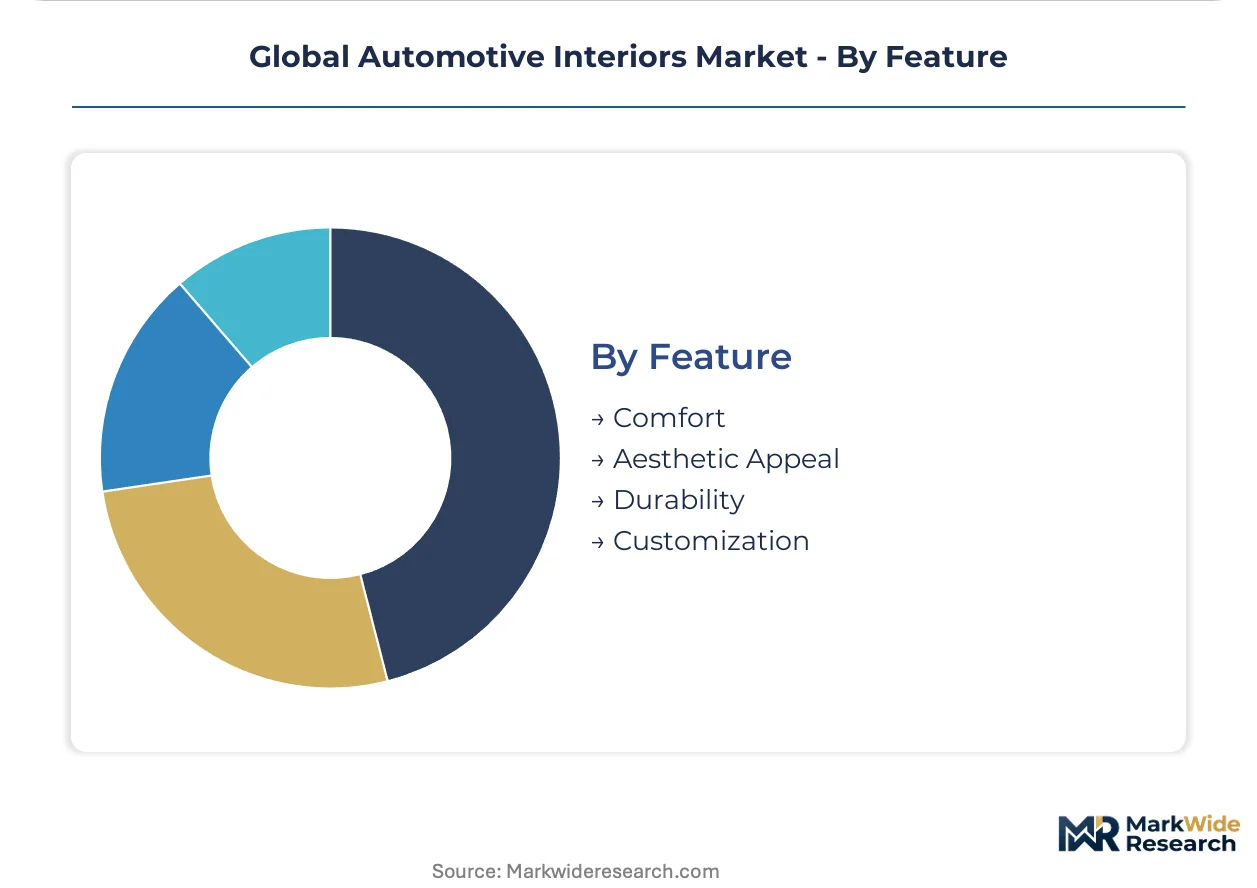
Feature:
Performance attribute prioritization varies by vehicle class and regional consumer preference.
- Comfort:Ergonomic foam density and climate-controlled surfaces differentiate premium offerings. Heated and ventilated seating packages are shifting to subscription-based software activation.
- Aesthetic Appeal:Surface finish quality and color harmony drive brand perception. Ambient lighting integration is virtualizing previously mechanical design elements.
- Durability:Wear-index clauses in fleet contracts transfer refurbishment risk to suppliers. Rental operators in the United States negotiate residual value guarantees tied to interior condition metrics.
- Customization:Configurable trim packages and over-the-air feature enablement support personalization at scale. Chinese OEMs lead in user-configurable cockpit themes.
Durability commands the established base. The steepest expansion runs through customization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government incentive programs and regulatory mandates are steering interior material specifications across major automotive manufacturing hubs. National industrial policies now link subsidy eligibility to localized cockpit module production and certified sustainable material content.
China
Domestic OEMs upgrade interior specifications to compete with European luxury benchmarks, pulling premium leather and synthetic configurations into mass-market EV classes. The MEE enforces GB/T 27630 cabin air quality standards that filter through to Tier-1 supplier material specifications. Shanghai and the Yangtze River Delta concentrate cockpit module assembly capacity as global OEMs expand EV manufacturing footprints.
Germany
Premium OEMs specify curved OLED dashboard arrays spanning instrument panel widths, eliminating discrete gauge housings and reducing mechanical component counts. ECHA REACH authorization requirements for flame retardants force polyurethane foam seating core reformulation ahead of sunset dates. Bavaria and Baden-Württemberg host supplier engineering centers developing bio-based polyol alternatives to maintain supply continuity.
United States
Fleet procurement departments negotiate wear-index clauses and residual value guarantees tied to interior durability metrics, transferring refurbishment risk to Tier-1 suppliers. The EPA drives volatile organic compound limits on interior adhesives and coatings through TSCA enforcement. Michigan and the Southeast automotive corridor concentrate predictive maintenance data and modular replacement architecture development.
India
Domestic manufacturing incentives under the PLI scheme attract cockpit module localization as global OEMs expand Indian EV assembly capacity. BIS standards govern flammability and fogging validation timelines compressed by accelerated launch cycles. Maharashtra and Gujarat host emerging Tier-1 supplier facilities serving both domestic OEMs and export programs.
South Korea
Premium OEMs lead large-format display integration specifications for virtualized instrument clusters, consolidating value capture with electronics specialists. MFDS frameworks intersect with automotive material standards for cabin air quality in export-bound vehicles. Seoul Capital Area and Busan-Ulsan concentrate integrated cockpit module contract manufacturing for Hyundai Motor and Kia platforms.
Global Automotive Interiors Market Vendor Landscape
On the supply side, the industry is consolidating around integrated cockpit module providers capable of bundling seating, electronics, and trim under single-source contracts. Tier-1 suppliers with certified material libraries and cross-jurisdictional compliance infrastructure capture disproportionate contract flow. Three archetypes dominate: full-system integrators, component specialists with vertical control over thermoplastic production, and electrical distribution engineers embedding systems within seat architectures. Competitive moves center on asset-light manufacturing partnerships and modular leasing arrangements for cockpit assembly capacity.
Among the named players, FORVIA Faurecia and Lear Corporation exemplify divergent specialization vectors within the integrated cockpit tier. FORVIA Faurecia occupies a position anchoring high-value contracts through combined seating and electronics portfolios. Lear Corporation sits within the electrical distribution specialist archetype, differentiating through embedded systems rather than conventional trim supply. Grupo Antolin represents the component verticalization model, sustaining margin pools through captive control of thermoplastic production for overhead console and lighting integration.
| Leading Market Players |
|---|
| Yanfeng Automotive Interiors |
| Grupo Antolin |
| FORVIA Faurecia |
| Continental AG |
| Toyota Boshoku Corporation |
| Adient |
| Magna International |
| DRÄXLMAIER |
| Lear Corporation |
| Others |
Supply Flow & Price Mechanics
Petrochemical feedstock concentration in Saudi Arabia, South Korea, and the US Gulf Coast anchors margin distribution across injection-molded trim tiers. Polypropylene and polyurethane resin costs fluctuate with crude indices, compressing visibility for suppliers locked into fixed-price OEM contracts.
Pricing Analysis
Certification level (REACH-compliant versus legacy formulations) creates the primary spread between European and export-tier material pricing. Three-tier pricing structure across premium leather, standard synthetic, and economy polypropylene configurations dominates contract structures. Cost compression in mass-market plastic compounds is intensifying because of petrochemical volatility and fixed-price contract exposure. Fleet procurement departments demonstrate highest price sensitivity through wear-index clause negotiations, while luxury OEMs prioritize haptic performance over unit cost.
Supply Chain Analysis
Magna International, FORVIA Faurecia, and Yanfeng Automotive Interiors hold dominant contract-manufacturing capacity for integrated cockpit modules. Supply concentrates in Germany, China, and Mexico for structural seat components and dashboard assemblies. Raw material flows draw from polypropylene resin producers, glass fiber suppliers, and certified tanneries in Italy and Germany. Single-source vulnerability runs through specialized polyurethane foam formulations facing ECHA REACH sunset dates. Distribution runs through Tier-1 supplier direct contracts with OEM platform engineering teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against synthetic suede and microfiber alternatives achieving tactile parity at lower input costs. Incumbents must navigate material reformulation cycles while preserving premium positioning.
For Market Incumbents: Pre-empt synthetic substitution by accelerating bio-based polyol development for seating cores ahead of REACH flame-retardant sunset dates. Secure backward integration into thermoplastic compound production to defend margin pools against resin volatility. Anchor high-value cockpit contracts through combined electronics and seating portfolios that electronics specialists cannot replicate.
For New Entrants and Emerging Players: India's PLI scheme for auto components offers the most penetrable geographic entry point as global OEMs expand EV assembly capacity. Target modular cockpit platform contracts where shared electrical architectures reduce engineering barriers. Pursue asset-light manufacturing partnerships rather than greenfield capacity to compress qualification timelines.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed Tier-1 suppliers holding certified material libraries but limited electronics integration. Long-term viability hinges on software-defined vehicle exposure and over-the-air feature enablement revenue streams. Monitor subscription-based interior activation adoption rates as the inflection signal for electronics-integrated supplier valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Shared EV and ICE architectures reduce engineering duplication for Lear and Faurecia. |
| Bio-based Material Transition | Castor-oil-derived polyamides qualify for EU Green Deal procurement preferences. |
| Geographic Manufacturing Footprint | Maharashtra and Gujarat facilities capture PLI incentives for Indian EV programs. |
| Software-Defined Vehicle Investment | Over-the-air feature activation creates recurring revenue for electronics-integrated suppliers. |
| Charging Infrastructure Partnership | Cabin air quality systems align with MEE GB/T 27630 mandates in Chinese EVs. |
Methodological Framework
Cross-validation between OEM platform engineering disclosures and Tier-1 supplier contract announcements anchors the qualitative findings. Primary interviews with procurement directors at Volkswagen Group and Hyundai Motor, seating foam R&D leads at Adient, and aftermarket distributors in the US Southeast combined with secondary validation from EPA TSCA filings, ECHA REACH substance databases, and IHS Markit vehicle production data. Bottom-up content-per-vehicle modeling triangulates against top-down market value reconstruction.
Calibration against historical CAGRs from adjacent automotive component categories refines the projection framework. Segmentation dimensions span vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster. Growth rates derive from elasticity modeling against EV penetration curves and regulatory compliance cost pass-through assumptions. Industry-specific inputs include REACH authorization timelines and MEE cabin air quality enforcement intensity.
The forecast holds incumbent behavior within observed patterns; aggressive moves by battery-electric-native OEMs to vertically integrate cockpit modules would shift outcomes. Cross-checking against IHS Markit production forecasts and OEM capital expenditure disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Overhead Console Market
Automotive Interior & Exterior
Automotive Convertible Top Market
Automotive Interior & Exterior
Automotive Clear Coat Paint Market
Automotive Interior & Exterior
Automotive Reconfigurable Body Panel Market
Automotive Interior & Exterior
Auto Internal Connector Market
Automotive Interior & Exterior
Automotive Smart Dashboard Display Market
Automotive Interior & Exterior
Automotive Backlight Moldings Market
Automotive Interior & Exterior
Global Headliner (OE) Market
Automotive Interior & Exterior
Ventilated Seats Market
Automotive Interior & Exterior
Asia-Pacific Automotive Flooring Market
Automotive Interior & Exterior
Automotive Cups and Glass Holder Market
Automotive Interior & Exterior
Global Automotive Intelligent Seats Market
Automotive Interior & Exterior
Car Organizer Market
Automotive Interior & Exterior
Automotive Upholstery Market
Automotive Interior & Exterior
Automotive OE Bumper Cover Market
Automotive Interior & Exterior
Auto Glass Encapsulation Market