
 City Bus Low-Floor Axle Systems Market | 2026-2036
City Bus Low-Floor Axle Systems Market Size, Share, and Industry Trends Forecast 2026-2036
City Bus Low-Floor Axle Systems Market Insights
Urban transit procurement is restructuring around wheelchair-accessible, low-entry platforms that require compact axle packaging and dropped-center designs. ZF Friedrichshafen leverages its integrated driveline portfolio to supply complete axle modules for European OEMs. Dana Incorporated anchors North American aftermarket channels with remanufactured low-floor axle components. Voith competes in electric bus retrofit segments with independently suspended portal axles that preserve floor height without structural chassis changes.
City bus low-floor axle systems integrate hypoid or planetary gearsets within housings compressed to roughly 400-500 mm crown-to-ground clearance, enabling step-free passenger entry across the vehicle width. The primary commercial purpose centers on maximizing cabin flat space while transmitting torque loads exceeding 13,000 Nm in 12-meter articulated configurations. Front axle assemblies with electro-hydraulic steering assist now capture premium positioning as transit agencies specify tighter turning radii for dense corridor operation. Electric drive axles are displacing mechanical layouts in procurement specifications where motor-in-hub or central-motor configurations eliminate differential housings and free additional passenger volume.
European manufacturers face ECE R107 fire suppression and ISO 26262 functional safety mandates that extend validation cycles for new axle platforms. The US DOT Federal Transit Administration enforces 49 CFR Part 38 accessibility standards that prescribe maximum platform gaps and floor heights, directly constraining axle housing envelope dimensions. China's MIIT GB/T standards for electric bus chassis integration require localized testing protocols that filter non-domestic suppliers. Stakeholders must monitor how battery-electric platform skateboard architectures eliminate traditional frame rails and redistribute axle load paths toward subframe-mounted solutions.
Market Dynamics
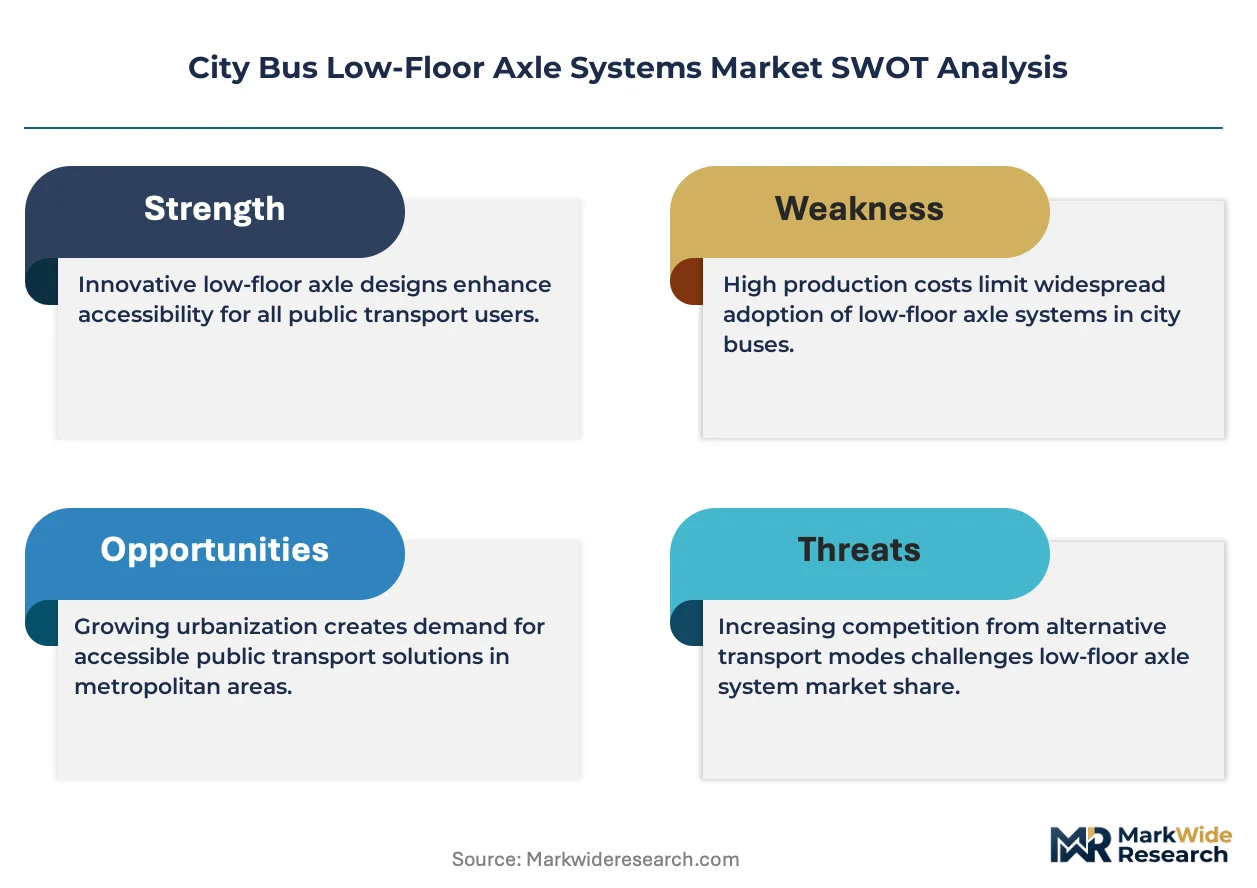
The electric bus platform transition is compressing axle housing envelopes while redistributing structural loads toward subframe-mounted configurations, forcing suppliers to abandon legacy frame-rail architectures.
Growth Catalysts
- European Accessibility Act mandates:Transit authorities in Germany, France, and the Netherlands face binding wheelchair-accessibility deadlines that accelerate low-floor fleet procurement and axle system redesigns.
- Hub motor integration:Motor-in-hub configurations eliminate differential housings entirely, freeing passenger volume and enabling completely flat cabin floors across 12-meter vehicle lengths.
- BRT corridor expansion:Brazil, China, and Turkey are scaling bus rapid transit networks that specify low-entry platforms with sub-350 mm floor heights for level boarding.
Market Restraints
- Specialized steel alloy costs:High-strength housings requiring 900 MPa yield grades face volatile pricing from concentrated European and Japanese mill suppliers.
- Validation cycle extension:ECE R107 fire suppression and ISO 26262 functional safety mandates stretch new platform development timelines by 18-24 months.
- Portal axle substitution:Independently suspended portal designs from Voith and niche competitors threaten conventional dropped-center architectures in retrofit segments.
Strategic Opportunities
- India urban bus electrification:The country's PLI scheme for electric vehicle components creates localized manufacturing incentives for axle system suppliers establishing joint ventures with domestic chassis builders.
- Skateboard battery integration:Convergence between flat-floor axle packaging and battery-electric skateboard platforms enables modular subframe solutions that serve multiple OEMs.
- Aftermarket remanufacturing channels:Transit agencies in North America are unbundling service contracts from initial procurement, opening direct supplier relationships for axle component refurbishment.
Industry Challenges
- Functional safety engineering scarcity:ISO 26262 certification expertise concentrates among German and Japanese engineering consultancies, creating recruitment bottlenecks for new market entrants.
- Legacy fleet integration complexity:Retrofit axle installations must accommodate existing suspension mounting points and brake line routing without structural chassis modifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | City Bus Low-Floor Axle Systems Market |
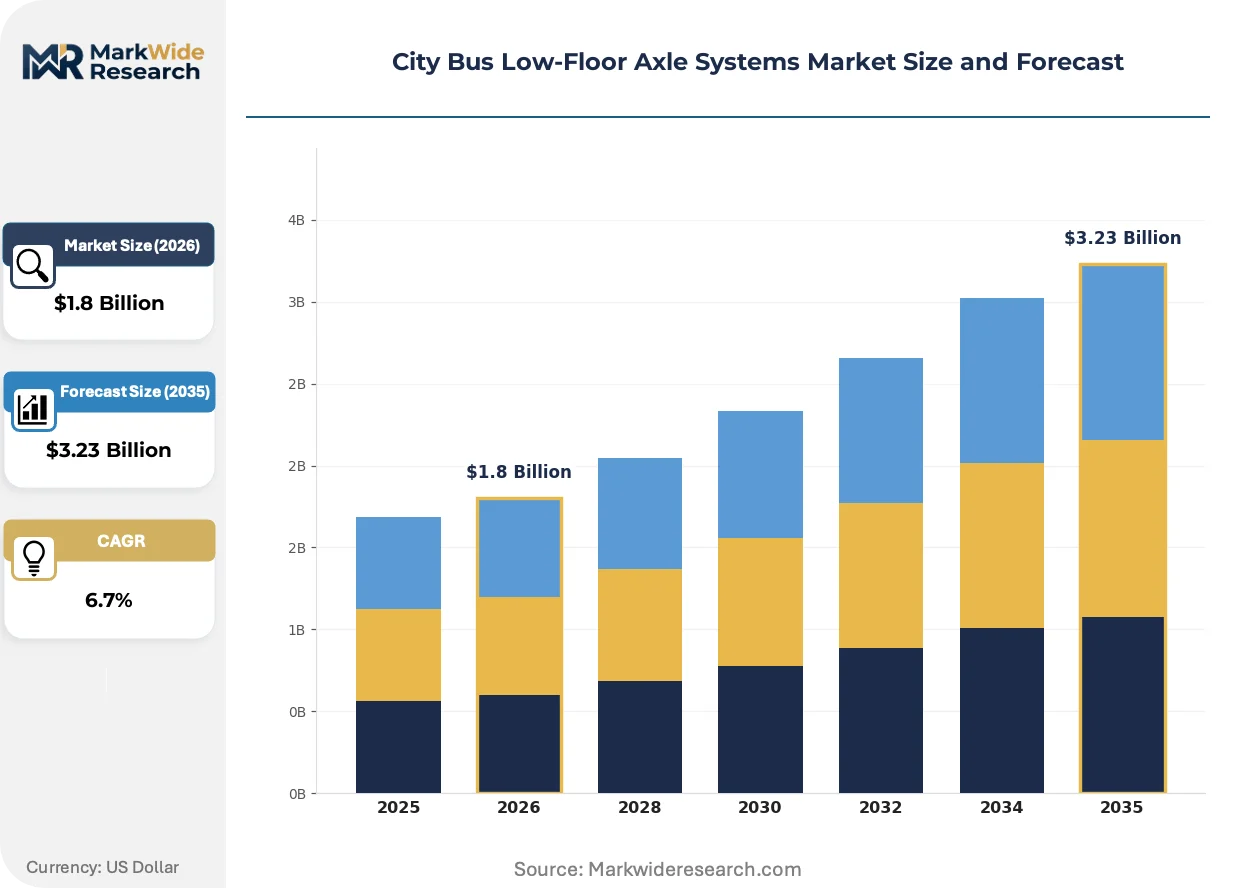
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
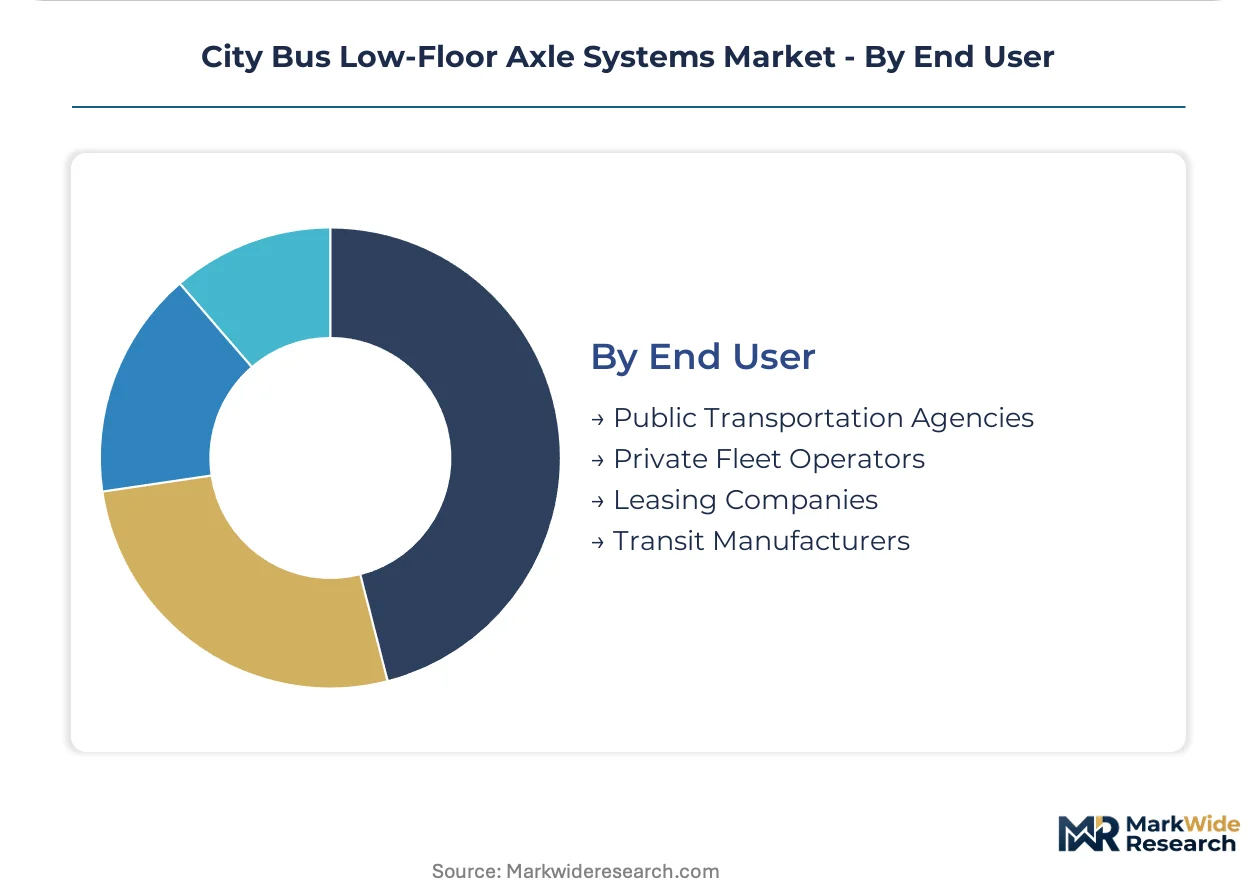
| Segmentation | Product Type: Front Axle, Rear Axle, Drive Axle, Steering Axle, Tag Axle Technology: Electro-Hydraulic, Mechanical, Pneumatic, Electric, Air Suspension Application: Urban Transit, Intercity Transport, Airport Shuttle, Tour Bus, School Transport End User: Public Transportation Agencies, Private Fleet Operators, Leasing Companies, Transit Manufacturers |
| Companies Covered | ZF Friedrichshafen, Meritor, Dana Incorporated, AxleTech, MAN Truck & Bus, Voith, Volvo Buses, WABCO, GK Drive Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
City Bus Low-Floor Axle Systems Market Trends and Innovations
Axle system architecture is converging with electric drivetrain packaging requirements, compressing traditional mechanical layouts while elevating software-defined torque management. Three developments are restructuring competitive positioning.
Integrated electric drive axles are consolidating mechanical complexity into single-housing units that combine motor, reduction gearing, and braking. Transit agencies in Scandinavia and the Netherlands specify these modules for 18-meter articulated buses where space constraints are most severe. The technology is consolidating supplier tiers by eliminating separate gearbox and motor vendors from procurement chains.
China's MIIT GB/T standards for electric bus chassis integration are mandating localized validation protocols that filter non-domestic axle suppliers. The regulations require crash testing and electromagnetic compatibility certification within Chinese laboratories, creating structural barriers for European and North American component manufacturers. Domestic suppliers in Jiangsu and Shandong provinces are capturing procurement share from foreign competitors as a result.
Service contract unbundling is fragmenting traditional OEM-captive distribution. Municipal transit authorities in California, Ontario, and Victoria now negotiate direct axle component supply agreements separate from vehicle purchase contracts. Australia and Canada exhibit the most advanced unbundling, with agencies maintaining dedicated remanufacturing partnerships for portal axle assemblies.
City Bus Low-Floor Axle Systems Market Segmentation
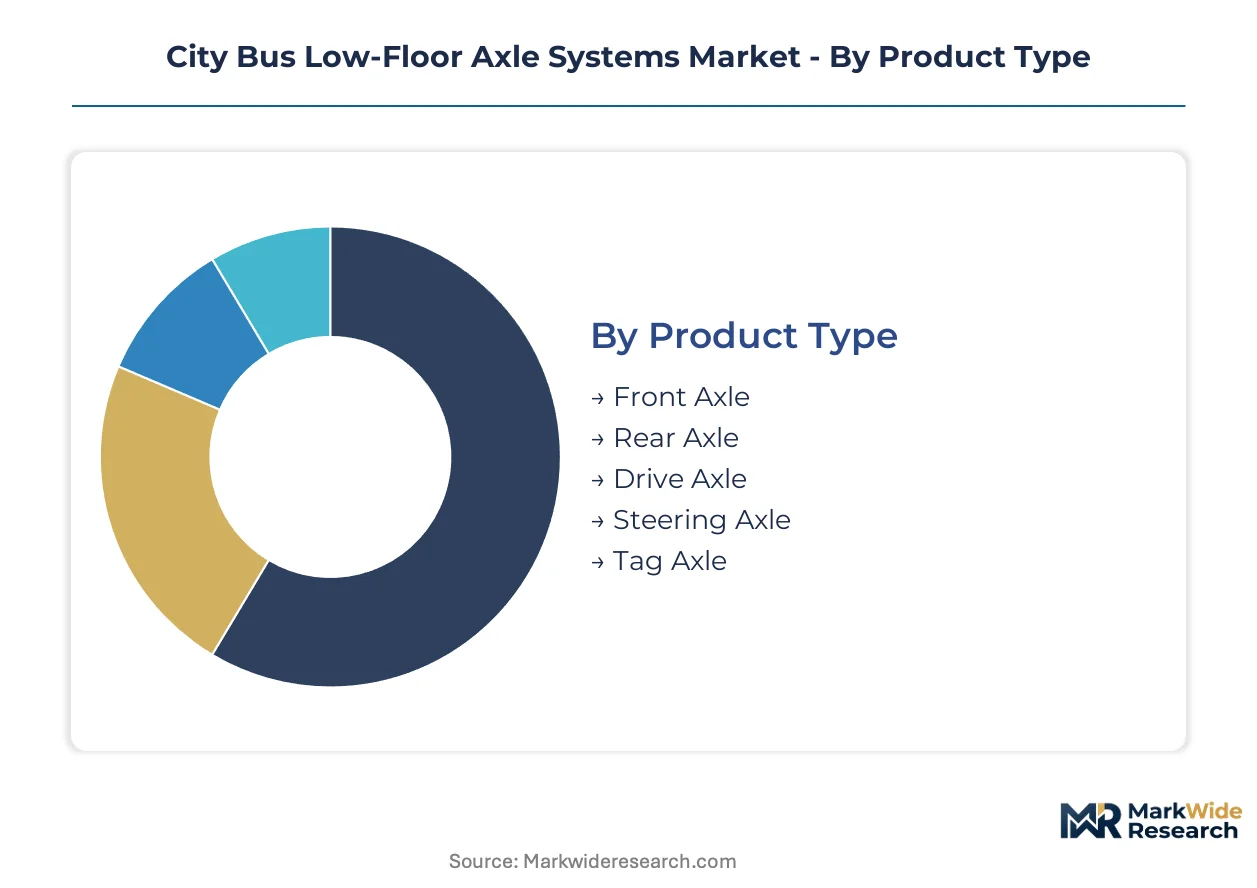
Low-floor axle procurement splits across multiple decision axes. Fleet operators weigh upfront capital against lifecycle service costs. OEM chassis integrators prioritize packaging compatibility with electric drivetrain architectures.
Product Type:
Procurement volume concentrates where floor height constraints are most severe and load ratings highest.
- Front Axle:Electro-hydraulic steering assist variants dominate 12-meter urban configurations requiring sub-11-meter turning circles. German and Dutch transit authorities specify these for dense corridor operations where maneuverability constraints override unit cost premiums.
- Rear Axle:Dropped-center housings with 400-500 mm crown-to-ground clearance enable step-free passenger entry across full vehicle width. Demand clusters in Brazil and Turkey where BRT corridor investments mandate level boarding platforms.
- Drive Axle:Integrated motor-gearbox units for battery-electric buses eliminate differential housings entirely.
- Steering Axle:Articulated bus configurations require independent wheel control for tight-radius navigation.
- Tag Axle:Non-powered lift axles support 18-meter vehicle weight distribution compliance.
Volume sits with Rear Axle; growth tilts toward Drive Axle.
Technology:
Technology selection tracks electrification maturity and local supplier ecosystem depth.
- Electric:Motor-in-hub configurations consolidate torque generation, reduction gearing, and braking into single-housing modules. Scandinavian operators specify these for articulated fleets where cabin space optimization justifies 40% unit cost premiums over mechanical alternatives.
- Electro-Hydraulic:Combines hydraulic power steering with electronic control units for precision feedback. French and Belgian agencies favor this technology for retrofit compatibility with existing fleet maintenance protocols.
- Mechanical:Conventional hypoid gearsets persist in cost-sensitive procurement.
- Pneumatic:Compressed air systems dominate legacy fleet replacement cycles.
- Air Suspension:Height-adjustable configurations enable kneeling functions for accessibility compliance.
Mechanical retains procurement volume; electric climbs the fastest as battery platform architectures mature.
Application:
Application segmentation reflects divergent duty cycles and regulatory exposure.
- Urban Transit:Low-floor mandates and high-frequency stop-and-go operations demand maximum durability. Chinese municipal authorities in Beijing and Shenzhen drive procurement volume through state-directed fleet electrification programs.
- Intercity Transport:Longer duty cycles prioritize fuel efficiency and highway-speed stability over extreme low-floor packaging.
- Airport Shuttle:Premium accessibility specifications and luggage capacity requirements shape axle load ratings.
- Tour Bus:Panoramic window configurations constrain axle housing envelope dimensions.
- School Transport:Regulatory emphasis on crashworthiness and emergency egress dictates structural reinforcement.
Procurement volume concentrates in Urban Transit; Airport Shuttle gains share fastest as aviation hub expansions accelerate.
End User:
End user type determines contract structure and supplier relationship intensity.
- Public Transportation Agencies:Municipal procurement in Germany, France, and the Netherlands operates through multi-year framework agreements with total-cost-of-ownership evaluation criteria. These buyers unbundle service contracts from initial vehicle purchase, opening direct axle component supply relationships.
- Private Fleet Operators:Profit-margin pressure drives preference for remanufactured components and extended service intervals.
- Leasing Companies:Residual value risk focuses specification on standardized, widely serviceable axle platforms.
- Transit Manufacturers:Chassis builders in Jiangsu and Shandong provinces integrate domestically certified axle systems to satisfy MIIT localization requirements.
Public Transportation Agencies anchor procurement volume; Transit Manufacturers expand fastest as Chinese electric bus exports scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentrates in Germany and China while procurement demand clusters in Brazil and the Netherlands. Transit authorities in São Paulo and Amsterdam drive specification standards that suppliers must satisfy. Regulatory fragmentation across these markets forces axle vendors to maintain multiple certification pathways.
Germany
KBA enforces ECE R107 fire suppression mandates that extend validation timelines for new axle platforms. The European Accessibility Act binds municipal operators in Berlin and Hamburg to wheelchair-accessibility deadlines by 2025. ZF Friedrichshafen anchors production in Friedrichshafen and Saarbrücken, supplying complete driveline modules to domestic OEMs.
China
MIIT GB/T standards mandate localized crash testing and electromagnetic compatibility certification within Chinese laboratories. The country's dual carbon goals accelerate state-directed fleet electrification in Beijing and Shenzhen. Domestic suppliers in Jiangsu and Shandong provinces capture procurement share through mandatory localization requirements.
Brazil
ANVISA coordinates with transport regulators on accessibility compliance for BRT corridor expansions in São Paulo and Rio de Janeiro. Federal programs prioritize low-entry platforms with sub-350 mm floor heights for level boarding. Voith competes in retrofit segments with portal axle designs that preserve existing chassis structures.
Netherlands
The country's national transport regulator enforces strict platform gap standards under EU accessibility directives. Transit operators in Amsterdam and Rotterdam specify electro-hydraulic steering assist for dense corridor maneuverability. Dutch procurement frameworks evaluate total-cost-of-ownership across 15-year service lifecycles.
United States
NHTSA and the Federal Transit Administration enforce 49 CFR Part 38 accessibility standards that constrain axle housing envelope dimensions. California transit agencies in Los Angeles and San Francisco unbundle service contracts from initial vehicle purchase. Dana Incorporated anchors aftermarket channels with remanufactured components for legacy fleet maintenance.
City Bus Low-Floor Axle Systems Market Competitive Landscape
Top-tier vendors anchor integrated driveline supply, while mid-tier specialists compete on retrofit compatibility and regional certification speed. The vendor base clusters around three strategic archetypes: European system integrators with complete axle module portfolios, North American aftermarket service providers, and Chinese domestic suppliers leveraging localization mandates. Competitive moves concentrate on strategic partnerships with battery-electric platform developers and geographic expansion through joint ventures in India and Southeast Asia.
Among Germany-based system integrators, ZF Friedrichshafen and MAN Truck & Bus exemplify the integrated driveline archetype, supplying complete axle modules that consolidate mechanical complexity into single-housing units. Dana Incorporated represents the North American aftermarket specialist model, occupying a position in remanufactured component channels as transit agencies unbundle service contracts. Voith sits within the retrofit technology tier, offering independently suspended portal axles that enable low-floor conversion without structural chassis modifications.
| Leading Market Players |
|---|
| ZF Friedrichshafen |
| Meritor |
| Dana Incorporated |
| AxleTech |
| MAN Truck & Bus |
| Voith |
| Volvo Buses |
| WABCO |
| GK Drive Systems |
| Others |
Pricing and Supply Chain Analysis
Hot-rolled steel coil indices from European and Japanese mills cascade through axle housing production into three-tier pricing structures across premium, standard, and economy levels, with 900 MPa yield-grade alloy premiums directly transmitting to municipal procurement budgets in Germany and the Netherlands.
Pricing Analysis
Cost-down pressure on integrated electric drive modules accelerates because motor-in-hub configurations consolidate supplier tiers and eliminate separate gearbox vendors from procurement chains. Three-tier pricing structure across premium, standard, and economy levels separates ISO 26262-certified platforms from ECE R107-compliant variants and mechanical legacy systems. Price differentiation rests on certification grade and after-sales service bundling. Pricing pressure stems from battery-electric platform standardization. Private fleet operators exhibit highest price sensitivity; Scandinavian transit agencies show lowest.
Supply Chain Analysis
Freight cost volatility from Shanghai to Hamburg and Santos compresses margin buffers for housing castings sourced from Jiangsu province foundries. Manufacturing concentrates in Germany, China, and Brazil. Raw material dependencies draw from high-strength steel alloys, aluminum forgings, and rare-earth magnet supply. Single-source vulnerability concentrates in Japanese mill supply for specialized 900 MPa grades. Distribution runs through OEM-captive channels and unbundled direct procurement to municipal transit authorities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story: ECE R107 fire suppression mandates create a barrier-to-entry moat that filters non-certified suppliers and extends validation timelines by 18-24 months for new platform development.
For Market Incumbents: Lock in certification advantages by accelerating ISO 26262 functional safety investments before recruitment bottlenecks for German and Japanese engineering expertise worsen. Deepen backward integration into high-strength steel alloy supply to defend margin position against Japanese mill pricing volatility. Portal axle substitution from Voith and niche competitors threatens conventional dropped-center architectures in retrofit segments.
For New Entrants and Emerging Players: The 40% unit cost premium gap between motor-in-hub electric configurations and mechanical alternatives creates entry space in cost-sensitive procurement. Target Brazil and Turkey BRT corridor expansions where level boarding mandates drive volume without incumbent lock-in. Pursue joint venture structures with Jiangsu and Shandong chassis builders to satisfy MIIT localization requirements.
For Investors and Strategic Acquirers: Distressed-cycle entries favor remanufacturing specialists in North America as California, Ontario, and Victoria transit agencies unbundle service contracts from initial vehicle purchase. Long-term viability centers on aftermarket channel control and electric platform retrofit capability. Watch for battery-electric skateboard architecture adoption rates as inflection signal for subframe-mounted axle demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Joint Venture Formation | MIIT GB/T compliance requires Chinese laboratory certification that filters non-domestic axle suppliers from procurement. |
| Backward Integration | Captive supply of 900 MPa yield-grade steel housings insulates margin from European and Japanese mill pricing volatility. |
| Remanufacturing Scale-Up | Unbundled service contracts in North America open direct supplier relationships for axle component refurbishment revenue. |
| Functional Safety Certification | ISO 26262 expertise concentration among German and Japanese consultancies creates recruitment moats for compliant players. |
| Portal Axle Retrofit | Voith's independently suspended designs enable low-floor conversion without structural chassis modifications in legacy fleets. |
Research Methodology
Independent corroboration across OEM platform engineers, Tier 1 supplier procurement leads, municipal transit authority fleet managers, and aftermarket service directors underwrites the qualitative findings. Secondary validation draws from vehicle production databases, IHS Markit registration data, SEC filings of listed driveline suppliers, and customs records for steel alloy trade flows. Bottom-up segmentation modeling triangulates against top-down market sizing from transit fleet electrification announcements.
Rate-of-change decomposition across the analysis window isolates volume drivers from price-mix effects in electric versus mechanical axle procurement. Segmentation dimensions span product type, propulsion architecture, application duty cycle, and end-user contract structure. CAGRs derive from installed base turnover rates and electrification policy trajectories. Forecast inputs incorporate BRT corridor investment pipelines and battery-electric platform skateboard adoption curves.
Inputs from OEM engineering disclosures and transit authority procurement announcements were available through the study window; gaps in pre-commercial electric axle reliability data introduce uncertainty bands around replacement cycle assumptions. Forecasts reflect documented assumptions about electrification penetration and regulatory enforcement timelines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Buses
Trolley Bus Market
Buses
Buses & Coaches Market
Buses
Europe Trolley Bus Market
Buses
Canada School Bus Market
Buses
Hydrogen CNG Bus Market
Buses
Bus Transmission System Market
Buses
Global Bus Market
Buses
Bus Bellows Market
Buses
Bus Rapid Transit System (BRT) Market
Buses
Airport Bus Market
Buses
Intercity Bus Travel Market
Buses
Airport Shuttle Bus Market
Buses
Bus Flooring Market
Buses
Solar Bus Market
Buses
United States School Bus Market
Buses
Luxury Coaches Market