
 Italy Cold Chain Logistics Market | 2026-2036
Italy Cold Chain Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Cold Chain Logistics Market Foresight
Aftermarket service revenue from temperature monitoring and equipment maintenance is reshaping margin pools away from pure transport tariffs. Frigoscandia SpA leverages its Nordic heritage to anchor premium frozen-food corridors into southern Italy. Lineage Logistics sustains one of the largest automated cold storage networks in Europe from its Italian hub positions. Safim Logistics specializes in pharmaceutical-grade last-mile delivery, occupying a defensible niche in compliance-heavy healthcare distribution.
Italy cold chain logistics denotes the integrated system of temperature-controlled warehousing, refrigerated transport, and real-time thermal monitoring that preserves product integrity from origin to final delivery, typically maintaining chilled conditions between 2°C and 8°C or frozen states below -18°C depending on cargo category. The primary purpose centers on preventing spoilage, maintaining pharmacological efficacy, and satisfying stringent food safety protocols across perishable supply chains. Frozen foods and pharmaceuticals represent the most structurally advantaged segments, with frozen foods commanding established volume scale through retail consolidation while pharmaceuticals extract premium pricing from GDP-validated compliance requirements. Road transportation dominates modal share given Italy's extensive motorway network and the time-sensitive nature of most chilled cargo, though rail is gaining traction for bulk frozen movements between northern distribution hubs.
Italy's cold chain operators navigate overlapping compliance frameworks including EU Good Distribution Practice enforced by the national pharmaceutical regulator, HACCP protocols administered under EU food law, and ISO 23412 for indirect temperature-controlled refrigerated delivery services. These regulations shape capital allocation decisions, mandating redundant cooling systems, validated packaging, and continuous digital traceability that elevates barriers for smaller fleet operators. Stakeholders must monitor whether proposed revisions to EU F-Gas Regulation will accelerate refrigerant conversion timelines and compress margins for warehouse operators with legacy ammonia or hydrofluorocarbon installations.
Market Dynamics
EU Good Distribution Practice enforcement is tightening validation requirements for temperature-controlled pharmaceutical corridors, forcing fleet operators toward redundant cooling architectures and continuous digital traceability systems that elevate capital barriers.
Growth Catalysts
- EU F-Gas Regulation:Phasedown mandates for hydrofluorocarbon refrigerants are accelerating warehouse conversion to ammonia and CO2 systems, creating retrofit demand across northern Italian distribution hubs.
- Pharmaceutical manufacturing clusters:Milan-Verona-Bologna corridor concentration drives dedicated cold chain infrastructure investment for high-value biologics and vaccine distribution.
- Real-time thermal monitoring:IoT sensor networks and blockchain traceability are becoming standard contractual requirements from healthcare procurement teams.
Market Restraints
- Energy cost volatility:Italian industrial electricity tariffs and natural gas pricing compress margins for continuous-cooling warehouse operations with limited demand-response capability.
- Specialized fleet scarcity:Refrigerated truck availability concentrates among established operators with validated GDP-compliant equipment, limiting new entrant scale.
- Refrigerant transition timelines:Legacy hydrofluorocarbon installations face compressed conversion schedules under EU F-Gas phase-down mandates, stranding capital for mid-size cold storage facilities.
Strategic Opportunities
- Southern Italy penetration:Calabria and Sicily fresh produce export corridors remain underserved by pharmaceutical-grade cold chain infrastructure, opening greenfield hub development.
- Rail-modal integration:Bulk frozen movements between Bologna and Verona distribution centers offer rail traction as motorway congestion intensifies.
- Aftermarket service unbundling:Temperature monitoring subscriptions and predictive maintenance contracts are displacing pure transport tariffs as margin anchors.
Industry Challenges
- Validated packaging certification:GDP-compliant thermal packaging qualification timelines extend 12-18 months, delaying new lane approvals for time-sensitive biologics.
- Refrigeration technician scarcity:Specialized ammonia system maintenance and CO2 transcritical cycle expertise concentrates among aging workforce cohorts in Lombardy and Emilia-Romagna.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Cold Chain Logistics Market |
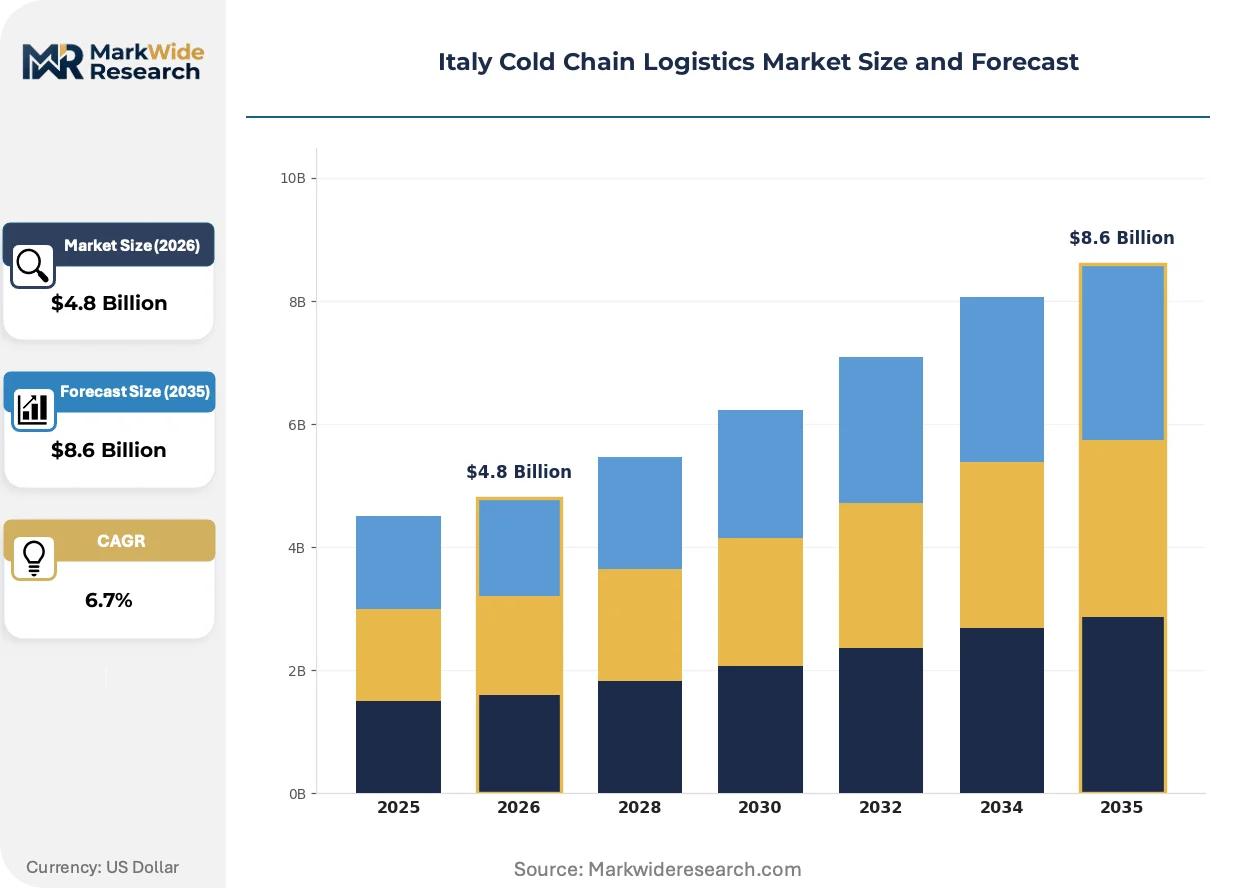
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dairy Products, Frozen Foods, Pharmaceuticals, Beverages Transportation Mode: Road, Rail, Air, Sea Temperature Range: Chilled, Frozen, Ambient, Deep Frozen End User: Retail, Healthcare, Food Service, E-commerce |
| Companies Covered | Frigoscandia SpA, Frigogel Srl, Safim Logistics, Lineage Logistics, Stef Italia, Frigocaserta Srl, DRS Depositi Regionali Surgelati Srl, DHL Supply Chain, Eurofrigo Vernate Srl, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Cold Chain Logistics Market Shifts & Advancements
Digital traceability architectures and modal diversification are compressing traditional transport-margin structures while elevating compliance technology to competitive differentiator status across Italian cold chain operations.
Blockchain-integrated temperature logging is digitizing audit trails for pharmaceutical shipments, enabling instantaneous regulatory submission to Italy's national pharmaceutical regulator. Large healthcare distributors are mandating sensor density at pallet-level granularity. The technology is digitizing dispute resolution between logistics providers and pharmaceutical manufacturers, compressing claims cycles from weeks to hours.
EU F-Gas Regulation revisions are accelerating refrigerant conversion timelines for warehouse operators with legacy installations. Industrial consequence includes stranded asset risk for ammonia facilities approaching end-of-life. Northern Italian cold storage networks are responding with CO2 transcritical system pilots and heat recovery integration to hedge energy exposure.
Healthcare procurement teams are consolidating vendor relationships around GDP-validated operators with integrated warehousing and transport capabilities. Small regional carriers without certification infrastructure are losing access to pharmaceutical accounts. This concentration is most visible across Lombardy's hospital distribution networks, where three-year sole-source contracts are replacing fragmented lane-by-lane tendering.
Italy Cold Chain Logistics Market Segmentation
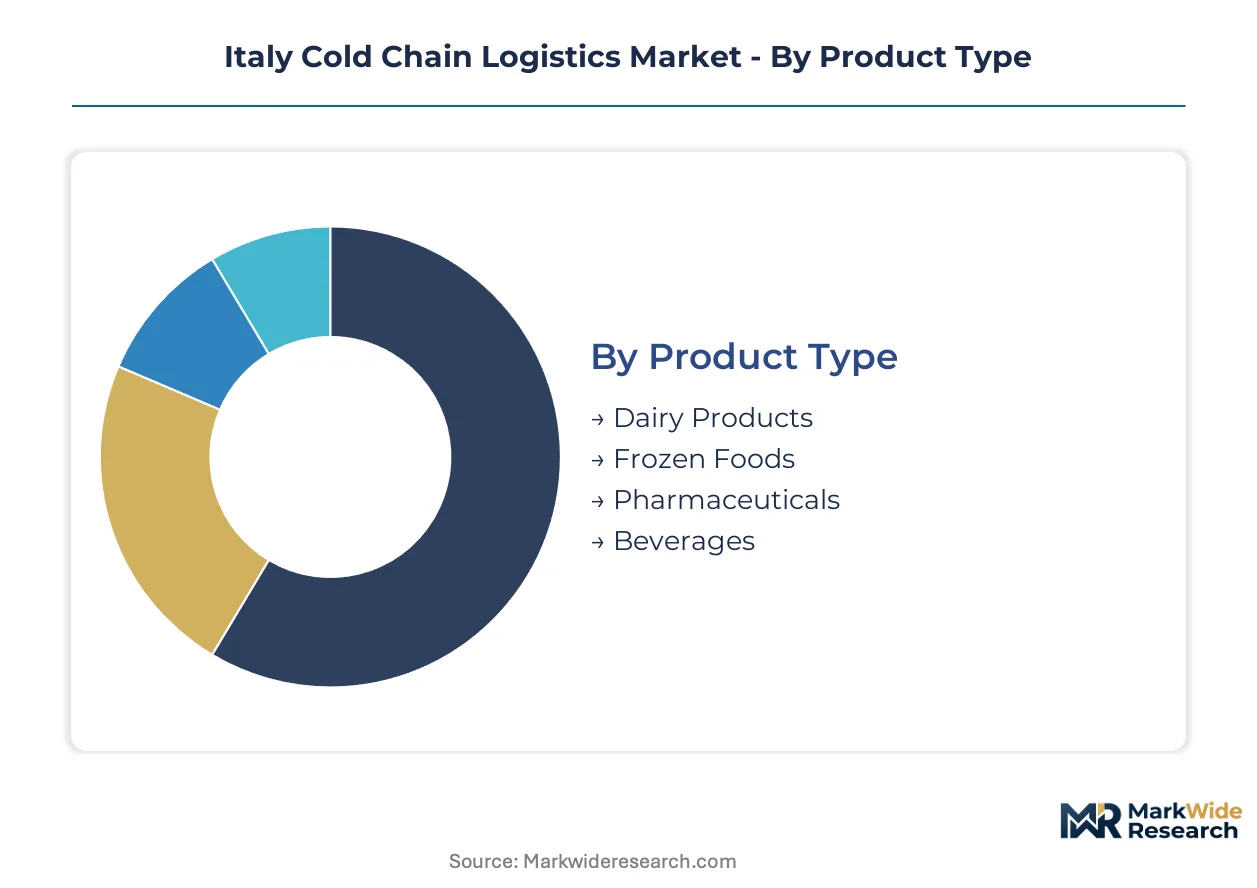
Segmentation in Italy's cold chain logistics reveals how compliance intensity and cargo value stratify infrastructure requirements. Pharmaceutical-grade corridors command premium equipment investments while frozen food volumes drive network density across the northern industrial belt.
Product Type:
Cycle times vary dramatically across cargo categories, with fresh dairy demanding daily replenishment and frozen foods sustaining weekly inventory turns.
- Pharmaceuticals:GDP-validated biologics and vaccines require continuous 2°C to 8°C monitoring with redundant cooling architectures. Milan's hospital procurement networks concentrate demand for validated last-mile delivery, with compliance documentation extending lane approval timelines to 18 months.
- Frozen Foods:Retail consolidation around private-label ice cream and ready meals sustains high-throughput automated storage. Frigoscandia SpA anchors dedicated frozen corridors from Nordic sourcing hubs into southern Italian distribution centers.
- Dairy Products:Fresh cheese and yogurt shipments from Emilia-Romagna processing plants move on 48-hour shelf-life constraints.
- Beverages:Chilled juices and functional drinks concentrate demand in Lombardy's urban retail corridors.
Frozen foods anchor the volume base while pharmaceuticals gain share at the steepest rate.
Transportation Mode:
Cost tiers separate asset-heavy road networks from capital-light intermodal alternatives, with rail emerging as a mid-cost bulk option for frozen corridors.
- Road:Refrigerated trucking dominates modal share through Italy's extensive Autostrada network, with GDP-compliant fleets concentrating among established operators. Time-sensitive pharmaceutical deliveries and fresh dairy distribution lock in road dependency for corridors under 500 kilometers.
- Rail:Bulk frozen movements between Bologna and Verona distribution hubs are gaining traction as motorway congestion intensifies. Lineage Logistics pilots refrigerated block train services for retail consolidation flows.
- Air:High-value biologics and temperature-critical vaccines utilize Milan Malpensa cargo terminals for international connectivity.
- Sea:Reefer containers handle citrus exports from Sicily and Calabria through Mediterranean port gateways.
Road transportation captures the margin premium while rail climbs the fastest as infrastructure investment accelerates.
Temperature Range:
Application requirements stratify equipment specifications, with deep frozen demanding the most energy-intensive infrastructure and ambient chilled allowing flexible multi-use assets.
- Chilled:The 2°C to 8°C band serves fresh produce, dairy, and pharmaceutical stability requirements. Safim Logistics specializes in this range for healthcare last-mile compliance across Lombardy's hospital networks.
- Frozen:Standard -18°C operations support retail frozen food distribution at scale through automated high-bay warehouses in the Milan-Verona corridor.
- Deep Frozen:-25°C to -30°C specifications serve premium ice cream and seafood exports, requiring specialized ammonia or CO2 transcritical systems with heat recovery integration.
- Ambient:Controlled room temperature 15°C to 25°C handles non-refrigerated pharmaceuticals and select beverages, allowing seasonal fleet redeployment.
Chilled applications dominate revenue concentration while deep frozen expands most quickly on export demand.
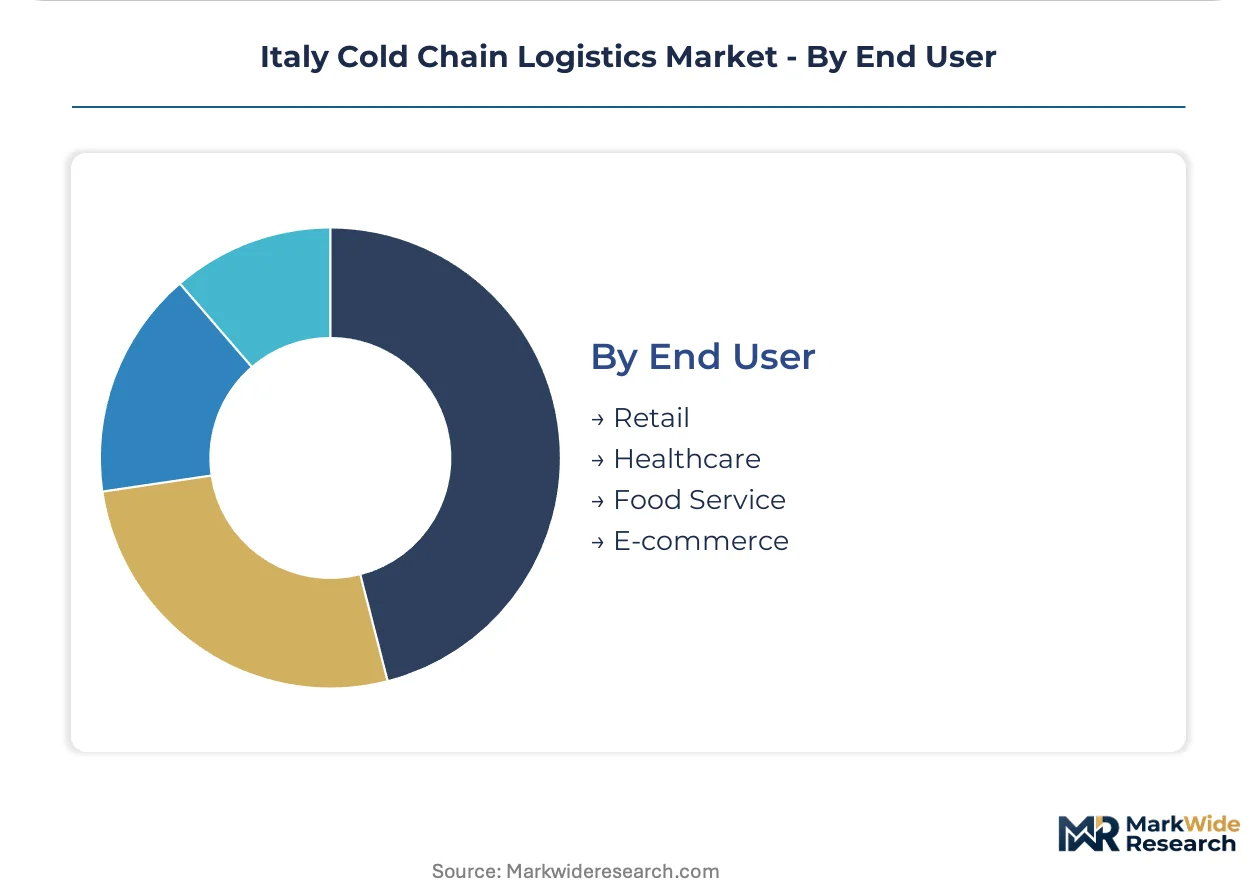
End User:
Customer type determines service level requirements, with healthcare procurement mandating audit-grade traceability and food service prioritizing cost-flexible spot capacity.
- Healthcare:Hospital networks and pharmaceutical manufacturers enforce GDP-validated contracts with three-year sole-source terms. Real-time thermal monitoring at pallet-level granularity is becoming standard procurement language.
- Retail:Grocery chains and hypermarkets drive volume concentration through automated consolidation centers, with private-label expansion sustaining dedicated frozen infrastructure.
- Food Service:Restaurants and institutional catering demand flexible capacity with lower compliance overhead, opening spot market opportunities for non-validated fleet operators.
- E-commerce:Direct-to-consumer fresh delivery remains nascent in Italy, constrained by last-mile cost structures and consumer density outside northern urban cores.
Healthcare anchors the compliance premium while e-commerce shows the steepest expansion trajectory on urban consolidation models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The northern industrial corridor consumes cold chain services differently than southern export zones, with pharmaceutical-grade infrastructure clustering around Milan while citrus and fresh produce corridors dominate Sicily and Calabria.
Lombardy
Pharmaceutical manufacturing and hospital procurement networks drive GDP-validated cold storage demand. AIFA enforces continuous digital traceability for temperature-controlled medicinal products. Milan's automated distribution centers anchor the largest refrigerated warehousing concentration in Italy.
Emilia-Romagna
Fresh cheese and yogurt processing plants require 48-hour shelf-life logistics with chilled transport redundancy. EU food safety protocols mandate HACCP compliance across dairy supply chains. Bologna's consolidation hubs serve as the primary interchange between northern manufacturing and central Italian retail networks.
Veneto
Biologics and vaccine distribution corridors connect Verona manufacturing clusters to European export gateways. The national pharmaceutical regulator validates thermal packaging for international lane approvals. Automated cold storage facilities along the A4 motorway corridor are expanding capacity for high-value pharmaceutical exports.
Sicily
Citrus and fresh produce exports to continental Europe drive reefer container demand through Mediterranean ports. EU F-Gas Regulation mandates accelerate warehouse refrigerant conversion timelines. Catania and Palermo port infrastructure remains underserved by pharmaceutical-grade cold chain capacity.
Calabria
Bergamot and specialty agriculture exports require temperature-controlled handling for premium market access. National energy efficiency programs incentivize CO2 transcritical system adoption. The Gioia Tauro port corridor offers greenfield development potential for integrated cold storage and export logistics.
Italy Cold Chain Logistics Market Competitive Landscape
Capability concentration sits with specialized pharmaceutical-grade operators; scale advantage sits with automated warehousing networks. The market structures around three tiers: international logistics platforms with Italian hub positions, regional cold storage specialists with GDP certification, and family-owned transport operators serving food service spot markets. Consolidation pressure is accelerating through healthcare procurement vendor reduction and energy cost-driven facility closures among mid-size operators.
Within the international platform tier, Lineage Logistics anchors automated cold storage scale across northern distribution corridors. Safim Logistics occupies a defensible position in pharmaceutical-grade last-mile delivery. Frigoscandia SpA represents Nordic-heritage frozen food specialization penetrating southern Italian retail networks.
| Leading Market Players |
|---|
| Frigoscandia SpA |
| Frigogel Srl |
| Safim Logistics |
| Lineage Logistics |
| Stef Italia |
| Frigocaserta Srl |
| DRS Depositi Regionali Surgelati Srl |
| DHL Supply Chain |
| Eurofrigo Vernate Srl |
| Others |
Supply & Pricing Matrix
Milan's automated cold storage corridor concentrates pharmaceutical-grade capacity, enabling Lineage Logistics and Safim Logistics to command premium tariffs for GDP-validated services while spot-market operators absorb margin compression from energy cost volatility.
Pricing Analysis
Long-term offtake contracts dominate pharmaceutical corridors, with three-year sole-source agreements locking in premium pricing for GDP-certified operators while food service spot markets trade on daily capacity availability. Price differentiation hinges on EU Good Distribution Practice certification tier and real-time thermal monitoring granularity, with pallet-level sensor density commanding substantial uplifts. Pricing pressure stems from Italian industrial electricity tariffs and natural gas pricing, which compress margins for continuous-cooling warehouse operations. Healthcare procurement teams exhibit the least price sensitivity due to pharmacological efficacy requirements, whereas food service buyers prioritize cost-flexible spot capacity.
Supply Chain Analysis
Refrigerated transport capacity concentrates among established Italian fleet operators with validated GDP-compliant equipment, while warehouse refrigeration systems draw from German and Danish engineering suppliers for ammonia and CO2 transcritical installations. Critical inputs include hydrofluorocarbon refrigerants facing EU F-Gas phasedown mandates, pallet-level IoT temperature sensors, and validated thermal packaging materials. Single-source vulnerability runs through specialized ammonia system maintenance expertise concentrated among aging workforce cohorts in Lombardy and Emilia-Romagna. Distribution runs through the Autostrada network for time-sensitive pharmaceutical deliveries, with rail gaining traction for bulk frozen movements between Bologna and Verona.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from integrated healthcare distributors building captive cold chain capabilities, requiring defensive repositioning around compliance technology and geographic coverage.
For Market Incumbents: Pre-empt healthcare procurement consolidation by embedding blockchain-integrated temperature logging as a standard contractual deliverable, locking in three-year sole-source renewals before integrated distributors achieve GDP self-certification. Extend automated cold storage capacity along the Milan-Verona-Bologna corridor to capture biologics export growth, anchoring scale advantage against regional specialists.
For New Entrants and Emerging Players: Southern Italy's citrus and fresh produce export corridors through Calabria and Sicily represent the most penetrable entry point, where pharmaceutical-grade cold chain infrastructure remains underserved and EU energy efficiency programs incentivize greenfield CO2 transcritical development. Target bergamot and specialty agriculture shippers with temperature-controlled handling for premium continental European market access, leveraging port infrastructure at Gioia Tauro as a consolidation hub.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors automated warehousing networks with integrated transport capabilities over pure-play fleet operators, as healthcare procurement consolidation rewards scale and compliance depth. Acquisition focus should center on regional cold storage specialists possessing GDP certification infrastructure but lacking capital for refrigerant conversion timelines. Watch EU F-Gas Regulation revision announcements as the critical inflection signal for accelerated retrofit demand and stranded asset risk among legacy ammonia facilities.
| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant System Conversion | EU F-Gas phasedown mandates accelerate warehouse retrofit demand across northern Italian distribution hubs. |
| Blockchain Traceability Integration | Pallet-level sensor density becomes standard procurement language for Lombardy hospital networks. |
| Rail-Modal Capacity Expansion | Lineage Logistics pilots refrigerated block train services to bypass motorway congestion on Bologna-Verona corridors. |
| Southern Hub Development | Greenfield cold storage at Gioia Tauro captures Calabria citrus export growth with CO2 transcritical efficiency. |
| Aftermarket Service Unbundling | Temperature monitoring subscriptions displace pure transport tariffs as margin anchors for fleet operators. |
Research Methodology
Cross-validation between primary interviews with cold chain operations directors, pharmaceutical procurement managers, and refrigerated fleet operators and secondary validation through AIFA regulatory filings, EU F-Gas Regulation implementation reports, and customs trade data anchors the qualitative findings. Bottom-up triangulation from individual facility capacity assessments and top-down reconciliation against national pharmaceutical distribution volumes ensures analytical coherence.
Calibration against historical capacity utilization patterns and energy cost trajectories shapes the projection framework across the analysis window. Segmentation dimensions include product type, temperature range, transportation mode, and end-user category, with pharmaceutical GDP compliance tier and refrigerant system technology as industry-specific modeling inputs. CAGRs derive from compound growth trajectory analysis applied to verified baseline market sizing.
Practitioners should monitor EU F-Gas Regulation revision timelines and AIFA enforcement intensity for early signals of accelerated capital deployment requirements. Forecasts reflect assumptions around refrigerant conversion cost curves and healthcare procurement consolidation velocity. Quarterly review of northern Italian industrial electricity tariffs and ammonia technician workforce demographics is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
United States Chartered Air Freight Transport Market
Logistics and Shipping
Spain Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Saudi Arabia Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Chile Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Spain Freight and Logistics Market
Logistics and Shipping
Middle East Freight Forwarding Market
Logistics and Shipping
LAMEA Last Mile Delivery Market
Logistics and Shipping
South Korea International Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Freight Transport Management Market
Logistics and Shipping
UK Logistics Market
Logistics and Shipping
Last Mile Delivery Transportation Market
Logistics and Shipping
Argentina Freight and Logistics Market
Logistics and Shipping
North America Freight Brokerage Market
Logistics and Shipping
Asia Pacific (APAC) Contract Logistics Market
Logistics and Shipping
North America Logistics Market
Logistics and Shipping
Netherlands Freight and Logistics Market