
 Actigraphy Sensors & PSG Devices Market | 2026-2036
Actigraphy Sensors & PSG Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Actigraphy Sensors & PSG Devices Market Analytics
Software-defined analytics and cloud-based scoring modules are decoupling hardware sales from recurring revenue streams in sleep diagnostics. ResMed Inc. leverages its SaaS infrastructure to anchor long-term contracts with sleep clinics. Philips sustains brand strength through vertical integration across sensor manufacturing and hospital distribution networks. Garmin Ltd. competes in consumer-grade actigraphy by extending GPS-accelerometer fusion into sleep-stage estimation algorithms.
Actigraphy sensors and PSG devices comprise electromechanical systems that measure motor activity, light exposure, and physiologic signals such as electroencephalography and pulse oximetry to quantify sleep architecture and circadian rhythms. Polysomnography systems typically sample at 256 Hz or higher for neurophysiologic channels while wearable actigraphs rely on tri-axial accelerometers with seven-day continuous logging capacity. The home user segment leads volume shipments as direct-to-consumer brands drive unit economics, while polysomnography systems capture concentrated margin pools in hospital sleep laboratories. Wireless and cloud-based technology architectures are displacing analog bedside recorders by enabling remote clinician oversight and automated scoring pipelines.
FDA 510(k) premarket notification requirements govern PSG device commercialization in the United States, while the EU Medical Device Regulation mandates notified body oversight for software-as-medical-device platforms across European member states. Japan's PMDA enforces QMS certification for multi-parameter sleep monitors, creating compliance barriers for unvalidated cloud analytics imports. Stakeholders must monitor evolving reimbursement thresholds for home sleep apnea testing versus in-lab polysomnography as payer policies determine addressable market expansion.
Market Dynamics
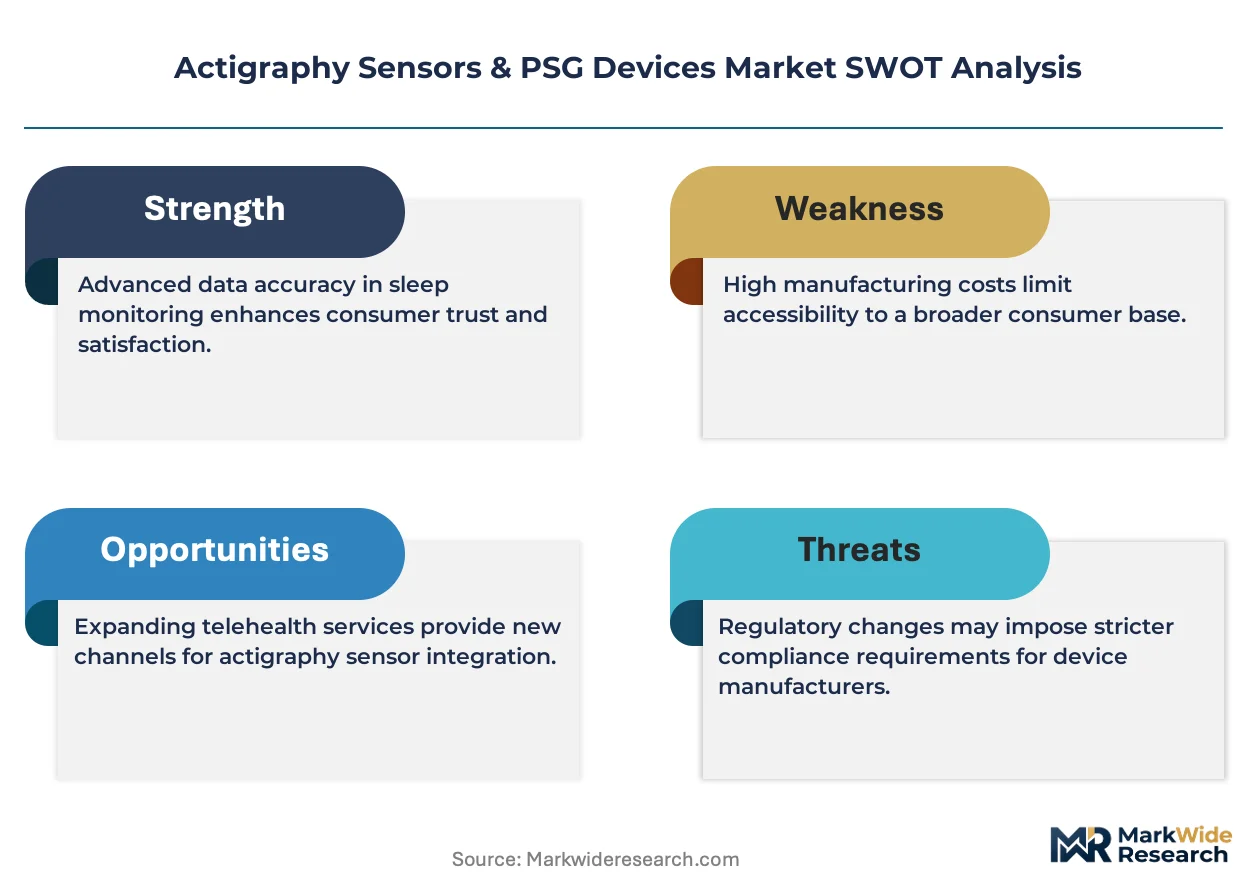
Cloud-connected diagnostic platforms are fragmenting revenue models across sleep diagnostics, decoupling hardware procurement from recurring software subscriptions and forcing vendors to rebuild margin structures around longitudinal patient data contracts.
Growth Catalysts
- Home sleep testing reimbursement codes:Mature reimbursement frameworks in Germany, the United States, and Japan validate clinical-grade actigraphy for remote diagnosis, expanding addressable patient populations beyond hospital sleep laboratories.
- FDA 510(k) clearance pathways:Streamlined premarket notification processes for software-as-medical-device platforms accelerate commercialization timelines for wearable sleep monitors with automated scoring algorithms.
- Tri-axial accelerometer advances:Seven-day continuous logging capacity at reduced power draw enables clinically valid sleep-stage estimation in consumer-form-factor devices, bridging the gap between wellness tracking and diagnostic-grade monitoring.
Market Restraints
- EU Medical Device Regulation software validation:Notified body oversight mandates for cloud analytics platforms create compliance barriers and extend time-to-market for multi-parameter sleep monitors entering European member states.
- Neurophysiologic channel sampling costs:Polysomnography systems requiring 256 Hz or higher sampling rates for EEG channels drive capital intensity in hospital sleep laboratories, limiting procurement frequency.
- Analog bedside recorder installed base:Legacy hardware in established sleep clinics creates switching friction against wireless and cloud-based technology architectures despite superior remote oversight capabilities.
Strategic Opportunities
- Japan PMDA QMS certification gaps:Unvalidated cloud analytics imports face enforcement barriers, creating first-mover advantage for vendors establishing compliant multi-parameter sleep monitor distribution.
- GPS-accelerometer fusion algorithms:Convergence of location tracking with motion sensing enables circadian rhythm quantification for shift-worker populations in transportation and healthcare verticals.
- Direct-to-consumer channel expansion:Home user segment volume leadership allows brands to bypass clinical procurement cycles and capture unit economics through retail and e-commerce distribution.
Industry Challenges
- Automated scoring pipeline validation:Machine learning-based sleep architecture classification requires extensive clinical trials to achieve parity with human polysomnographer interpretation, compressing development timelines.
- Wireless interoperability standards:Proprietary communication protocols between wearable actigraphs and cloud platforms create integration complexity for sleep clinics managing mixed-vendor device fleets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Actigraphy Sensors & PSG Devices Market |
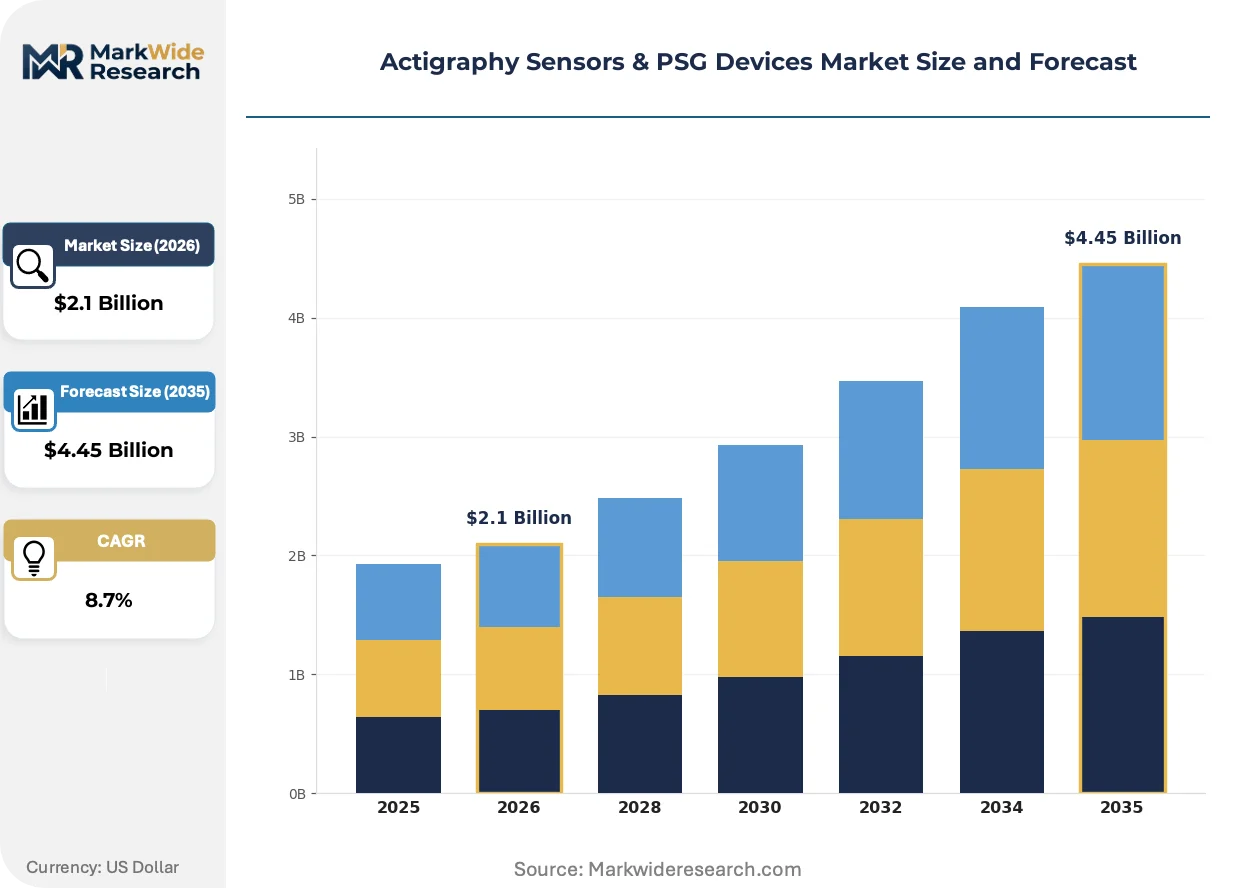
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.45 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Sensors, Sleep Monitors, Polysomnography Systems, Mobile Apps End User: Hospitals, Sleep Clinics, Research Institutions, Home Users Technology: Analog, Digital, Wireless, Cloud-Based Application: Sleep Disorders, Clinical Studies, Sleep Research, Fitness Tracking |
| Companies Covered | Garmin Ltd., SOMNOmedics GmbH, ResMed Inc., Nox Medical, Compumedics Ltd., Philips, Natus Medical, ActiGraph LLC, Fitbit Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Actigraphy Sensors & PSG Devices Market Evolving Landscape
Sleep diagnostics is experiencing fundamental architecture shifts as electromechanical measurement systems converge with software-defined analytics, compressing the boundary between consumer wellness and clinical-grade monitoring.
Photoplethysmography-integrated actigraphy is rewriting how cardiovascular surrogates enter sleep-stage classification workflows. Sleep clinics in the United States are adopting pulse oximetry-enhanced wearables at accelerated procurement cycles. This convergence is compressing the functional gap between hospital polysomnography and home-based diagnostic monitoring, forcing vendors to reposition hardware margins around subscription scoring services.
EU Medical Device Regulation software-as-medical-device classifications are tightening validation requirements for cloud-connected platforms across European member states. Notified body oversight now extends to algorithmic scoring modules previously treated as ancillary services. Multi-parameter sleep monitor vendors targeting Germany and adjacent markets are restructuring quality management systems to accommodate premarket clinical evidence requirements for automated diagnostic outputs.
Subscription-based diagnostic oversight contracts are displacing capital-intensive hardware refresh cycles in North American sleep clinics. Hospital sleep laboratories now prioritize vendors offering longitudinal patient data management over standalone device procurement. This behavioral pivot concentrates purchasing authority with integrated platform providers capable of delivering remote clinician dashboards and automated report generation.
Actigraphy Sensors & PSG Devices Market Segmentation
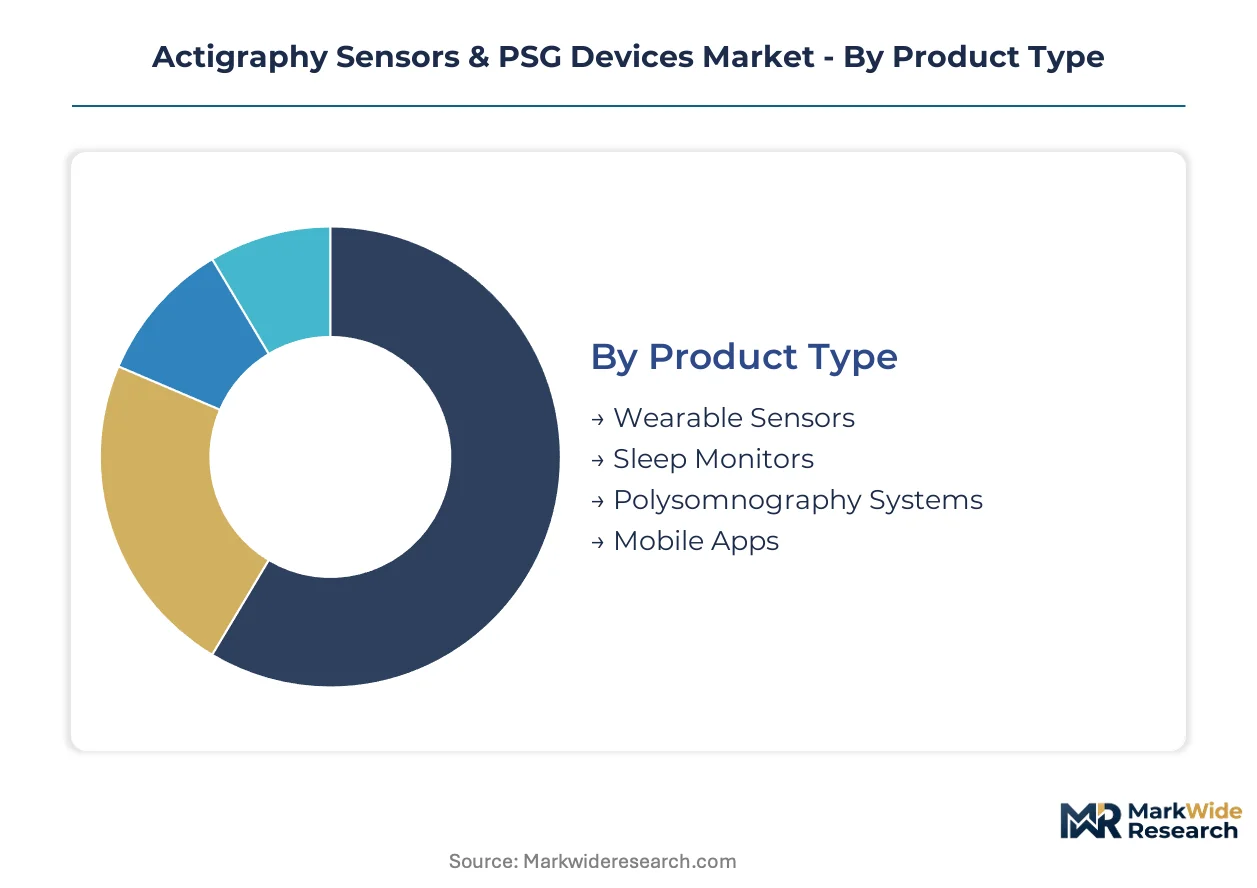
Segmentation in sleep diagnostics reveals how hardware procurement priorities diverge between clinical reimbursement pathways and consumer self-pay channels. Product architecture choices determine whether vendors capture one-time device margins or recurring software revenue across patient monitoring workflows.
Product Type:
Procurement budgets separate diagnostic-grade capital equipment from direct-to-consumer wellness hardware.
- Wearable Sensors:Tri-axial accelerometer devices with seven-day logging capacity dominate home user volume through retail distribution. FDA 510(k) clearances for automated sleep-stage algorithms are compressing the gap between wellness tracking and clinical reimbursement eligibility.
- Polysomnography Systems:Multi-channel electromechanical platforms sample EEG at 256 Hz or higher for neurophysiologic assessment in hospital sleep laboratories. Germany and Japan maintain concentrated installed bases where capital refresh cycles face pressure from cloud-connected alternatives.
- Sleep Monitors:Photoplethysmography-integrated bedside devices capture pulse oximetry and motion data for intermediate diagnostic settings.
- Mobile Apps:Software-as-medical-device platforms deliver automated scoring pipelines without dedicated hardware procurement.
Volume sits with Wearable Sensors; growth tilts toward Polysomnography Systems as cloud architectures displace analog bedside recorders.
End User:
Reimbursement code maturity determines addressable market expansion across patient care settings.
- Home Users:Direct-to-consumer procurement bypasses clinical sales cycles through e-commerce and retail pharmacy channels. United States reimbursement frameworks for home sleep apnea testing validate this segment's diagnostic legitimacy.
- Sleep Clinics:Specialized facilities in North America and Europe prioritize cloud-connected platforms with remote clinician oversight capabilities. Subscription-based diagnostic contracts are displacing capital-intensive hardware refresh cycles.
- Hospitals:Academic medical centers maintain polysomnography laboratories for complex case referral and resident training.
- Research Institutions:Circadian rhythm studies and pharmaceutical trials drive demand for longitudinal actigraphy datasets.
Revenue concentrates in Sleep Clinics; expansion accelerates fastest in Home Users as self-monitoring normalizes.
Technology:
Architecture choices determine compliance burden and interoperability complexity across mixed-vendor deployments.
- Cloud-Based:Software-defined analytics platforms enable automated scoring and longitudinal patient data management. EU Medical Device Regulation notified body oversight extends validation requirements to algorithmic modules previously treated as ancillary services.
- Wireless:Bluetooth and proprietary protocols connect wearable actigraphs to clinician dashboards for remote oversight. Proprietary communication standards create integration friction for sleep clinics managing multi-vendor device fleets.
- Digital:Solid-state recording systems replaced analog tape-based architectures in transitional deployments.
- Analog:Legacy bedside recorders in established sleep clinics create switching friction despite inferior remote capabilities.
Installed base remains with Analog; investment flows fastest into Cloud-Based architectures as hospital procurement shifts toward subscription models.
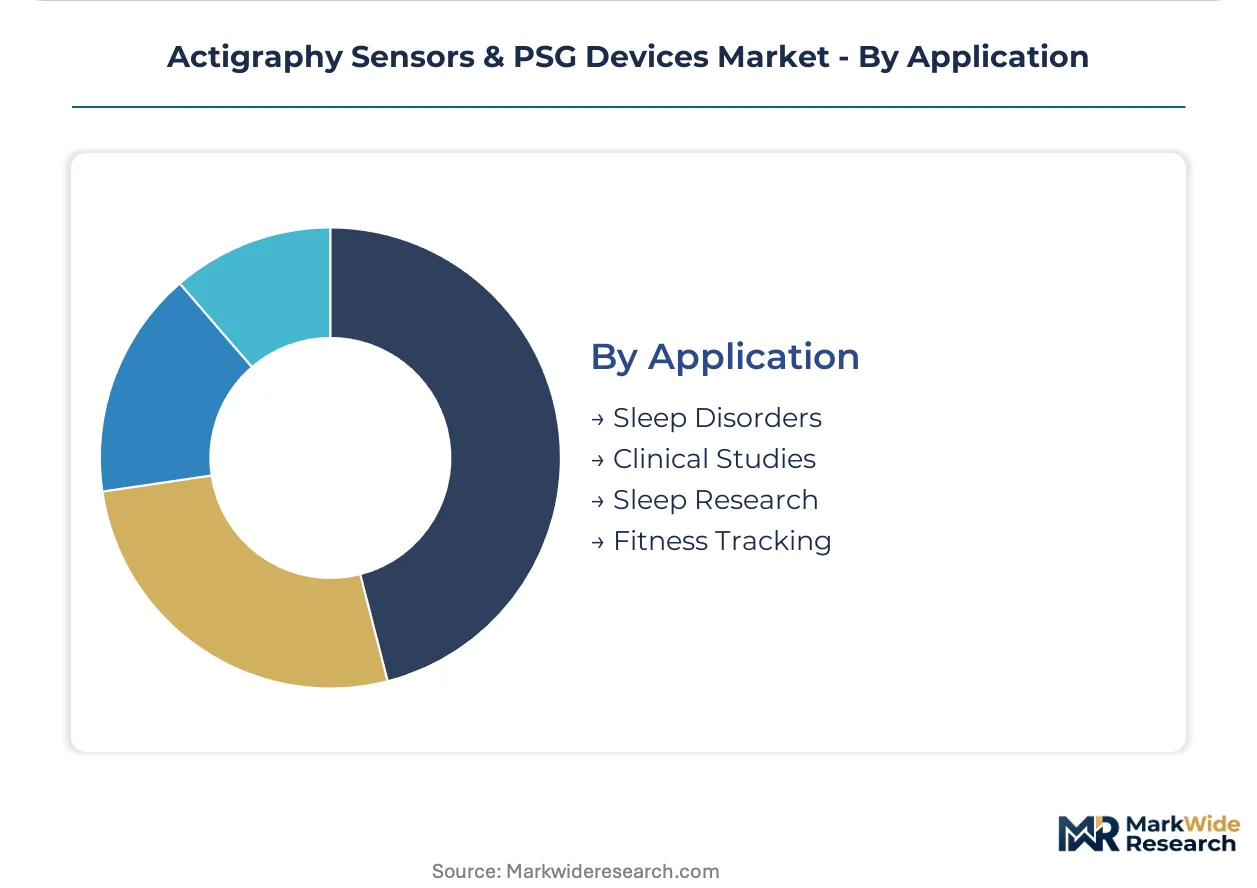
Application:
Clinical validation requirements separate reimbursable diagnostic use from discretionary wellness monitoring.
- Sleep Disorders:Obstructive sleep apnea diagnosis drives reimbursable demand for home testing devices and in-lab polysomnography. Payer policies in the United States and Germany determine whether actigraphy substitutes for traditional multi-channel assessment.
- Sleep Research:Circadian rhythm quantification and pharmaceutical sleep studies require validated actigraphy datasets with established inter-device reliability.
- Clinical Studies:Multi-site trials demand standardized hardware and cloud-based data aggregation to ensure protocol compliance.
- Fitness Tracking:Consumer wellness applications prioritize user engagement metrics over clinical-grade accuracy.
Reimbursement anchors Sleep Disorders; research funding expands fastest in Sleep Research as pharmaceutical pipelines target circadian interventions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's Longwood Medical and Academic Area anchors sleep diagnostics research concentration, with Massachusetts General Hospital and Brigham and Women's Hospital driving clinical validation protocols for wearable sleep monitors across the United States, Germany, Japan, United Kingdom, and Australia.
United States
Medicare reimbursement codes for home sleep apnea testing and FDA 510(k) clearance pathways accelerate commercialization timelines for cloud-connected diagnostic platforms. The Centers for Medicare & Medicaid Services maintains distinct fee schedules distinguishing in-lab polysomnography from home testing devices. Minneapolis-St. Paul corridor hosts concentrated medical device manufacturing clusters where sleep monitor production integrates with broader diagnostic equipment supply chains.
Germany
Sleep clinic procurement networks prioritize EU Medical Device Regulation-compliant platforms with automated scoring capabilities. The Federal Institute for Drugs and Medical Devices enforces notified body oversight for software-as-medical-device classifications. Baden-Württemberg's medical technology corridor around Tübingen and Freiburg sustains specialized sensor manufacturing for multi-parameter sleep monitors.
Japan
PMDA QMS certification requirements create compliance barriers for unvalidated cloud analytics imports, favoring established domestic distribution partnerships. The Ministry of Health, Labour and Welfare maintains stringent quality management system mandates for multi-parameter sleep monitors. Tokyo-Osaka corridor concentrates sleep clinic networks where subscription-based diagnostic contracts displace capital-intensive hardware procurement.
United Kingdom
NHS England procurement frameworks prioritize cost-effective home sleep testing alternatives to reduce hospital sleep laboratory backlogs. The Medicines and Healthcare products Regulatory Agency aligns software-as-medical-device oversight with EU MDR transitional arrangements. Oxford-Cambridge-London research triangle drives circadian rhythm study funding and pharmaceutical sleep trial coordination.
Australia
Therapeutic Goods Administration medical device regulations mandate conformity assessment procedures for wearable sleep monitors entering diagnostic reimbursement pathways. The National Health and Medical Research Council funds longitudinal actigraphy studies for shift-worker health interventions. Melbourne biomedical precinct hosts specialized sleep research institutions collaborating with Asia-Pacific pharmaceutical trial networks.
Actigraphy Sensors & PSG Devices Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the sleep diagnostics value chain, with consolidated revenue concentration among integrated platform providers and fragmented competition in component supply. Three strategic archetypes dominate: medical device conglomerates with hospital distribution networks, specialized polysomnography system manufacturers, and consumer electronics brands extending wellness tracking into clinical-adjacent positioning. Competitive moves center on SaaS infrastructure anchoring for long-term clinic contracts and backward integration into sensor manufacturing to secure component supply.
Within the integrated medical device tier, ResMed Inc. and Philips exemplify platform providers restructuring margin capture around subscription scoring services rather than standalone hardware sales. Garmin Ltd. occupies a distinct position bridging consumer-grade actigraphy with clinical-adjacent sleep-stage estimation algorithms. SOMNOmedics GmbH represents the specialized European manufacturer archetype, with German GmbH structure indicating concentrated regional engineering focus on polysomnography system refinement.
| Leading Market Players |
|---|
| Garmin Ltd. |
| SOMNOmedics GmbH |
| ResMed Inc. |
| Nox Medical |
| Compumedics Ltd. |
| Philips |
| Natus Medical |
| ActiGraph LLC |
| Fitbit Inc. |
| Others |
Value Network & Pricing Analysis
Biomedical engineering talent clusters in Massachusetts and Baden-Württemberg compress labor-cost differentials between premium diagnostic-grade systems and standard wearable sensors, widening pricing-tier spreads as cloud-connected platforms displace capital-intensive polysomnography hardware.
Pricing Analysis
Subscription-based diagnostic contracts anchored to patient throughput outcomes now dominate sleep clinic procurement, displacing per-unit transactional models. Price differentiation hinges on FDA 510(k) clearance tier and cloud analytics certification grade, with premium vendors capturing longitudinal data management fees. Cost compression in the standard wearable tier intensifies as direct-to-consumer brands erode clinical-adjacent positioning. Home users exhibit highest price sensitivity; hospital sleep laboratories prioritize outcome-linked contracts over hardware acquisition costs.
Supply Chain Analysis
Dual-sourcing requirements for tri-axial accelerometer MEMS chips compel manufacturers to qualify suppliers across Taiwan, South Korea, and Japan. Component dependencies center on photoplethysmography sensors, lithium-polymer cells, and Bluetooth Low Energy modules. Single-source vulnerability in cloud infrastructure provisioning threatens continuity for software-as-medical-device platforms. Distribution runs through hospital GPO contracts, sleep clinic procurement networks, and direct-to-consumer e-commerce channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Medical Device Regulation compliance costs and FDA software validation timelines are forcing sub-scale vendors toward exit or acquisition, consolidating purchasing power among integrated platform providers with captive SaaS infrastructure.
For Market Incumbents: Lock in long-term diagnostic oversight contracts with North American sleep clinics before reimbursement codes further favor home testing alternatives. Backward integration into tri-axial accelerometer sourcing insulates against MEMS supply constraints. Prioritize notified body pre-certification for algorithmic scoring modules to accelerate European market access ahead of smaller competitors. For New Entrants and Emerging Players: Direct-to-consumer e-commerce routes offer lowest-friction market entry for wearable sleep monitors with clinical-grade aspirations. White-space concentrates in Japan's QMS-compliant distribution gap and shift-worker circadian monitoring for transportation verticals. Target GPS-accelerometer fusion algorithms as a differentiated go-to-market wedge against established wellness trackers. For Investors and Strategic Acquirers: Re-rating potential sits with SaaS-anchored platform providers given subscription revenue visibility and hospital contract stickiness. Five-to-ten year viability favors vendors with FDA-cleared automated scoring pipelines and EU MDR quality management systems already operational. Watch Japan PMDA enforcement actions against unvalidated cloud imports as an inflection signal for compliant-first movers.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Software-as-Medical-Device Submission | Accelerates commercialization timelines for wearable sleep monitors with automated scoring algorithms in the United States. |
| EU MDR Notified Body Pre-Certification | Enables market entry for cloud-connected diagnostic platforms across Germany and adjacent European member states. |
| Hospital System Partnership | Secures longitudinal patient data contracts displacing capital-intensive polysomnography hardware refresh cycles. |
| Software Companion Development | Extends actigraphy sensor utility into remote clinician oversight dashboards for sleep clinic subscription retention. |
| Reimbursement Strategy | Aligns home sleep testing device positioning with CMS fee schedules and Germany's statutory health insurance frameworks. |
Research Methodology
Independent corroboration across sleep clinic procurement managers, biomedical engineers at academic medical centers, and GPO contracts specialists underwrites the qualitative findings. Primary interviews with FDA regulatory affairs consultants and EU notified body auditors supplemented secondary validation through FDA 510(k) clearance databases, CMS Medicare fee schedule publications, and PMDA QMS certification registries. Bottom-up segment sizing triangulated against top-down expenditure flows from hospital capital equipment budgets and direct-to-consumer retail audit data.
Comparable-period anchoring to historical reimbursement code expansions and regulatory clearance timelines structured the projection horizon. The analytical framework modeled value trajectories across product type, end user, technology architecture, and application segments. CAGRs derived from elasticity-adjusted adoption curves for cloud-connected platforms and replacement-cycle analysis for analog bedside recorders. Forecast inputs incorporated PMDA enforcement intensity assumptions and EU MDR transitional arrangement deadlines.
The model holds under stable reimbursement frameworks and regulatory clearance throughput; deviation in FDA software validation backlogs or EU notified body capacity constraints would shift commercialization timelines materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Medical Bionic Implant Market
Medical Devices
Nonablative Laser Resurfacing Devices Market
Medical Devices
Non-Magnetic Wheelchair Market
Medical Devices
Immunoadsorption Columns Market
Medical Devices
Global Mobile ECG Devices Market
Medical Devices
Carotid Stents Market
Medical Devices
Global Esophageal Catheters Market
Medical Devices
Australia Respiratory Devices Market
Medical Devices
Bone Power Tools Market
Medical Devices
DLIF and XLIF Implants Market
Medical Devices
Australia Insulin Delivery Devices Market
Medical Devices
Global Blood Processing Devices and Consumables Market
Medical Devices
Pressure Ulcer Detection Devices Market
Medical Devices
Muscle Stimulation Devices Market
Medical Devices
Global Nebulizers Market
Medical Devices
Middle East and Africa Medical Device Regulatory Affairs Outsourcing Market