
 Anti-Scratch Film Market | 2026-2036
Anti-Scratch Film Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Scratch Film Market Outlook
Co-extrusion multilayer architectures are reshaping how anti-scratch films achieve hardness without sacrificing optical clarity. 3M leverages its patent portfolio in microreplicated surface structures to command premium positioning in automotive paint protection. Nitto Denko Corporation anchors supply to Japanese electronics OEMs through precision-coated polyethylene terephthalate films with sub-micron scratch resistance.
Anti-scratch film denotes a surface-protective substrate engineered with hardness coatings—typically silica-based or UV-cured acrylate layers measuring 2–10 micrometers—that defend underlying materials from mechanical abrasion while maintaining light transmission above 90%. Polymer films dominate volume production due to scalable extrusion compatibility, while adhesive films capture disproportionate margin pools through value-added bonding chemistries. Laminated films are gaining traction in foldable electronics where multi-axis flexing demands stratified protection.
REACH restricts certain phthalate plasticizers in European film formulations, compelling reformulation toward bio-based polyester alternatives. China's GB standards for electronic product safety mandate flammability ratings that influence substrate selection in Shenzhen's display manufacturing ecosystem. Japan's METI enforces JIS K5600 pencil hardness benchmarks that filter market access for imported protective films. Stakeholders must track regulatory divergence between Asian hardness standards and European chemical restriction frameworks to avoid compliance-driven margin erosion.
Market Dynamics
Co-extrusion multilayer architectures are compressing the trade-off between surface hardness and optical clarity, forcing reformulation cycles across polyurethane and acrylic supply chains as automotive OEMs tighten specifications for interior and exterior protection.
Growth Catalysts
- Automotive OEM specification tightening:Interior dashboard and exterior paint protection films are becoming standard fitment in premium vehicle trims, pulling volume through tier-one coating converters.
- REACH chemical restriction deadlines:ECHA phasing of certain phthalate plasticizers is accelerating migration toward bio-based polyester formulations in European film production.
- Shenzhen-Seoul electronics corridor concentration:Display manufacturing clusters are generating pull-through demand for sub-micron protective layers on foldable and curved screen devices.
Market Restraints
- Silica nanoparticle feedstock volatility:Hard-coat precursor costs fluctuate with semiconductor-grade silicon supply constraints, squeezing margin on premium optical-grade films.
- East Asian substrate concentration:PET film base supply concentrates among Korean and Japanese petrochemical complexes, creating geographic vulnerability to logistics disruption.
- Acrylic-urethane adhesion trade-offs:UV-cured acrylate layers achieve pencil hardness ratings above 2H only at the expense of flexible substrate bonding, limiting foldable electronics adoption.
Strategic Opportunities
- Indian automotive assembly expansion:Domestic OEM paint shops and component molding operations remain underpenetrated by protective film specification, offering first-mover positioning.
- GB standard flammability alignment:China's electronic product safety mandates for display assemblies create compliant-supplier preference for Shenzhen-based converters.
- Nanoimprint lithography convergence:Microreplicated surface structures from semiconductor patterning techniques are crossing into anti-scratch film embossing, enabling sub-wavelength optical features.
Industry Challenges
- Hard-coat application technician scarcity:Precision coating line operation for sub-5-micron layer deposition requires specialized training that outpaces vocational pipeline output.
- JIS K5600 certification timeline compression:Japanese pencil hardness benchmarking demands extended third-party validation cycles that delay product launches by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Scratch Film Market |
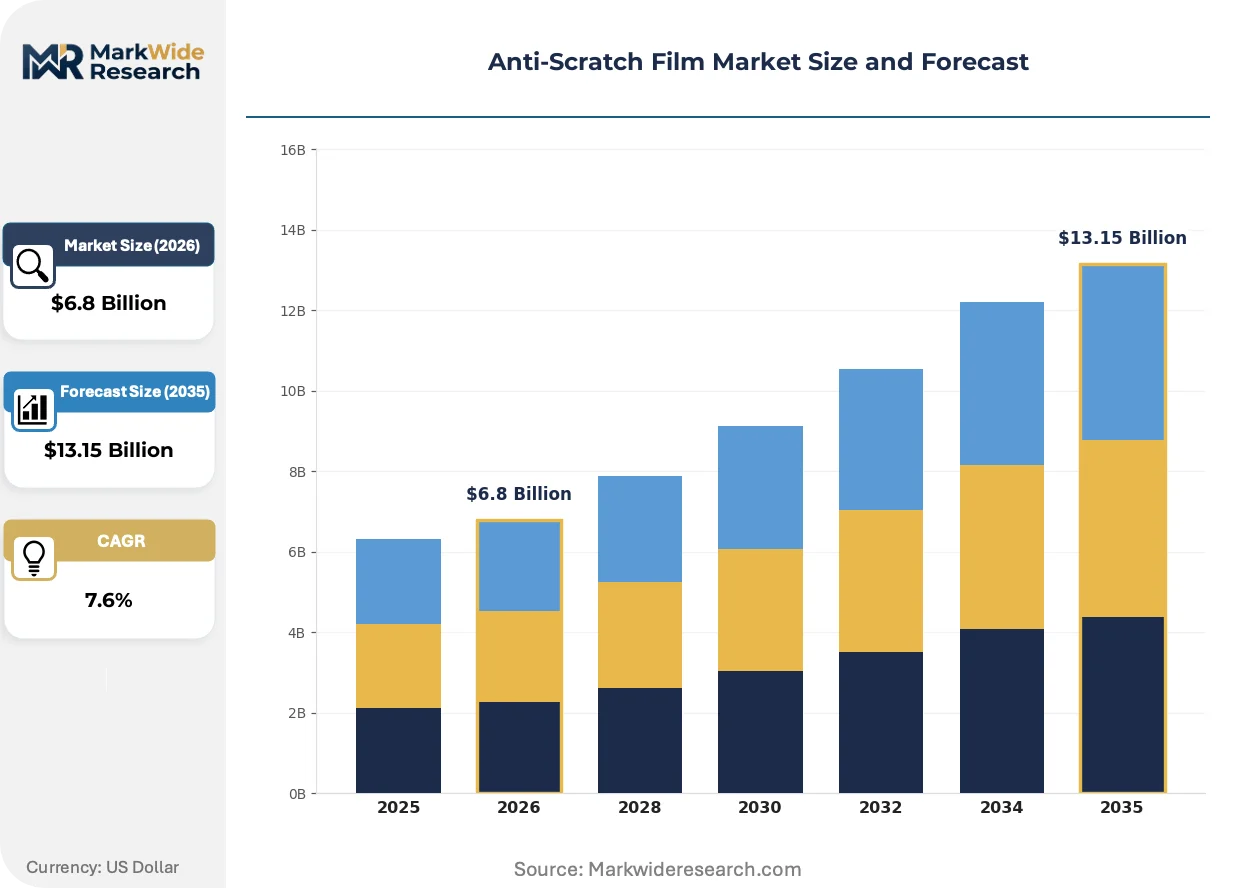
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.15 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymer Films, Adhesive Films, Laminated Films, Coated Films Application: Automotive, Electronics, Packaging, Construction End User: Manufacturers, Retailers, Distributors, Consumers Distribution Channel: Online Retail, Direct Sales, Specialty Stores, Wholesalers |
| Companies Covered | 3M, Avery Dennison Corporation, LINTEC Corporation, Nitto Denko Corporation, Saint-Gobain Performance Plastics, POLIFILM, TEKRA, XPEL, Eastman Chemical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Scratch Film Market Strategic Shifts
Surface protection engineering is pivoting from passive barrier films toward active functional layers that integrate sensing, self-healing, or antimicrobial properties alongside mechanical defense.
Self-healing elastomeric topcoats are digitizing how automotive and electronics manufacturers approach warranty cost containment. Microcapsule-based polymer systems autonomously repair superficial scratches through thermal activation at 40-60°C, a temperature range routinely achieved in vehicle interiors and device operation. Tier-one suppliers are embedding these chemistries into paint protection films to compress service interval frequency and extend replacement cycles.
REACH SVHC candidate list expansion is tightening formulation disclosure requirements across European film imports. ECHA transparency obligations now mandate supply chain communication down to 0.1% weight concentration for substances of very high concern, compelling Asian manufacturers to requalify additive packages. Automotive OEMs sourcing interior trim films are responding by consolidating supplier bases to reduce audit burden.
Specification-led procurement is displacing price-first purchasing in foldable electronics supply chains. Device manufacturers now issue functional performance guarantees tied to 200,000-cycle flex testing, forcing film converters to assume liability for substrate-adhesive-coating integration. This behavioral shift is most visible in Seoul's display component ecosystem, where Samsung and LG procurement teams have eliminated commodity-grade suppliers from qualified vendor lists.
Anti-Scratch Film Market Segmentation
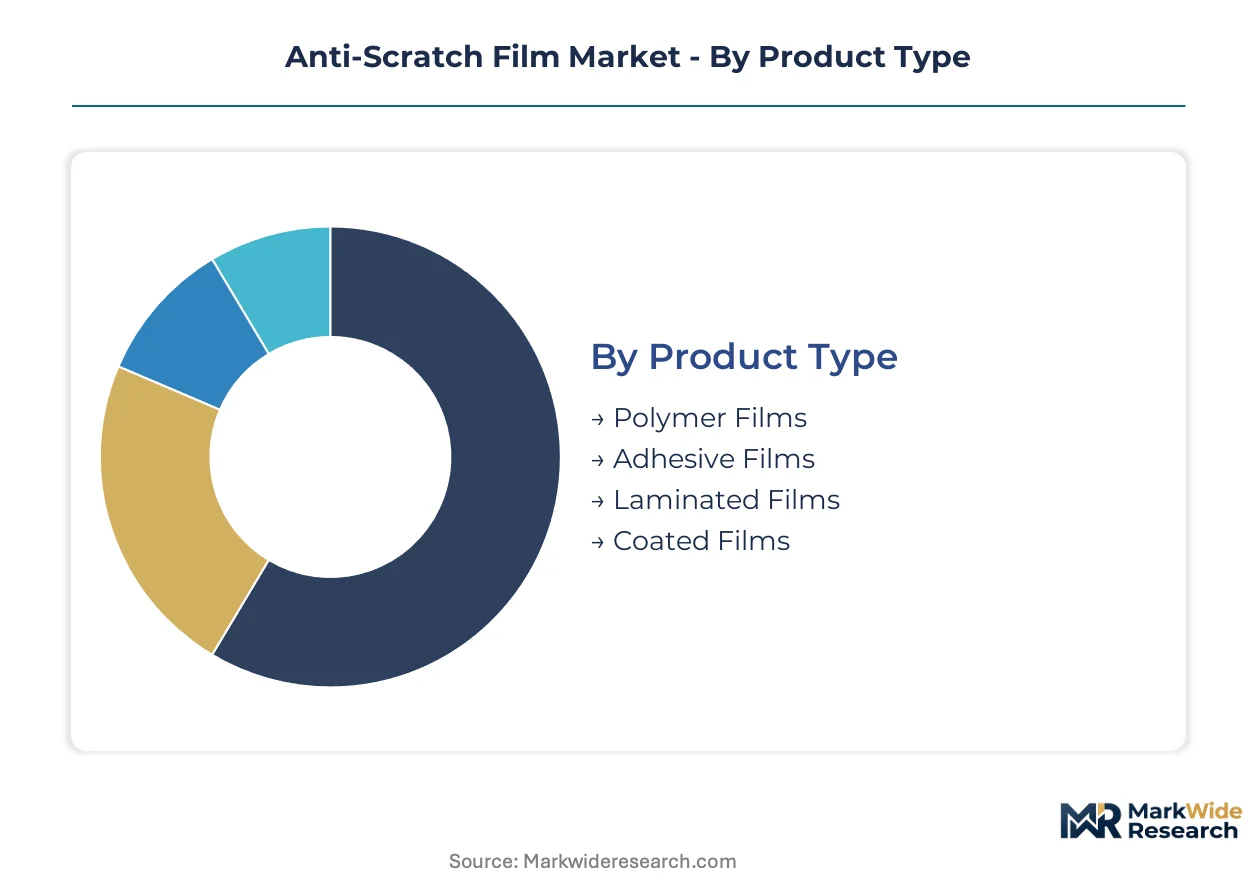
Anti-scratch film specifications diverge sharply across end-use environments. Automotive paint protection demands weatherability and elongation recovery, while electronics applications prioritize optical clarity and sub-micron thickness control. Understanding these use-case boundaries enables targeted formulation development and margin capture.
Product Type:
Polymer films span commodity-grade PET substrates through high-performance polyurethane elastomers, each commanding distinct coating compatibility and conversion economics.
- Polymer Films:Extruded polyester and polycarbonate substrates form the volume base, compatible with roll-to-roll hard-coat deposition. Demand concentrates in Shenzhen display manufacturing, where 50-125 micrometer PET films receive silica-acrylate surface treatments for smartphone and tablet screen protection.
- Adhesive Films:Pressure-sensitive adhesive layers bonded to protective topcoats enable repositionable installation and residue-free removal. Korean automotive OEMs specify solvent-free acrylic adhesives for paint protection films, tightening volatile organic compound compliance in Seoul-area assembly plants.
- Laminated Films:Multi-layer constructions bond dissimilar polymers to combine hardness with flexibility. Foldable electronics manufacturers in Seoul specify stratified PET-TPU laminates for 200,000-cycle hinge durability.
- Coated Films:Liquid-applied UV-cured or thermally cured hard-coats transform base substrates into abrasion-resistant surfaces. Japanese electronics converters favor electron-beam cured coatings for instant processing and reduced thermal stress on heat-sensitive bases.
The dominant share belongs to polymer films, while adhesive films are closing the gap fastest through automotive specification expansion.
Application:
Application segments track directly to surface protection requirements, from vehicle exterior durability to consumer electronics optical performance.
- Automotive:Exterior paint protection films and interior dashboard overlays defend against stone chips, UV degradation, and fingernail abrasion. German OEMs specify self-healing polyurethane films for hood and bumper applications, compressing warranty claim frequency.
- Electronics:Display covers, device housings, and foldable screen substrates demand hardness ratings above 2H pencil with 90%+ light transmission. Samsung and LG procurement teams in Seoul enforce 200,000-cycle flex testing for foldable device films, eliminating commodity suppliers.
- Packaging:Transparent protective layers preserve printed graphics and structural integrity during shipping and handling. European luxury goods packaging converters specify scratch-resistant laminates for premium cosmetic and spirits presentation boxes.
- Construction:Architectural glass, flooring, and fixture protection during installation and occupancy. Japanese commercial building contractors apply temporary protective films to elevator panels and marble surfaces, prioritizing clean removal without adhesive residue.
Automotive commands the largest volume position, though electronics exhibits the steepest expansion trajectory through foldable device proliferation.
End User:
End user categories reflect purchasing sophistication, from specification-engineered OEM procurement through price-sensitive consumer self-installation.
- Manufacturers:Tier-one automotive and electronics OEMs issue detailed material specifications with qualified supplier lists. Shenzhen-based display assemblers mandate REACH-compliant additive packages and JIS K5600 hardness certification for direct material sourcing.
- Retailers:Big-box electronics and automotive aftermarket chains stock consumer-grade screen protectors and DIY paint protection kits. German automotive parts retailers emphasize pre-cut film kits with installation tools for specific vehicle models.
- Distributors:Industrial film converters and coating job shops purchase master rolls for slitting, printing, and value-added conversion. Korean petrochemical distributors maintain regional inventory of PET base films for Seoul-area coating operations.
- Consumers:Individual purchasers of screen protectors, furniture films, and vehicle protection products through e-commerce and retail channels. Japanese consumers demonstrate highest willingness-to-pay for premium-branded optical-grade screen protection.
Manufacturers retain the dominant procurement volume, with distributors gaining share fastest through regional conversion service expansion.
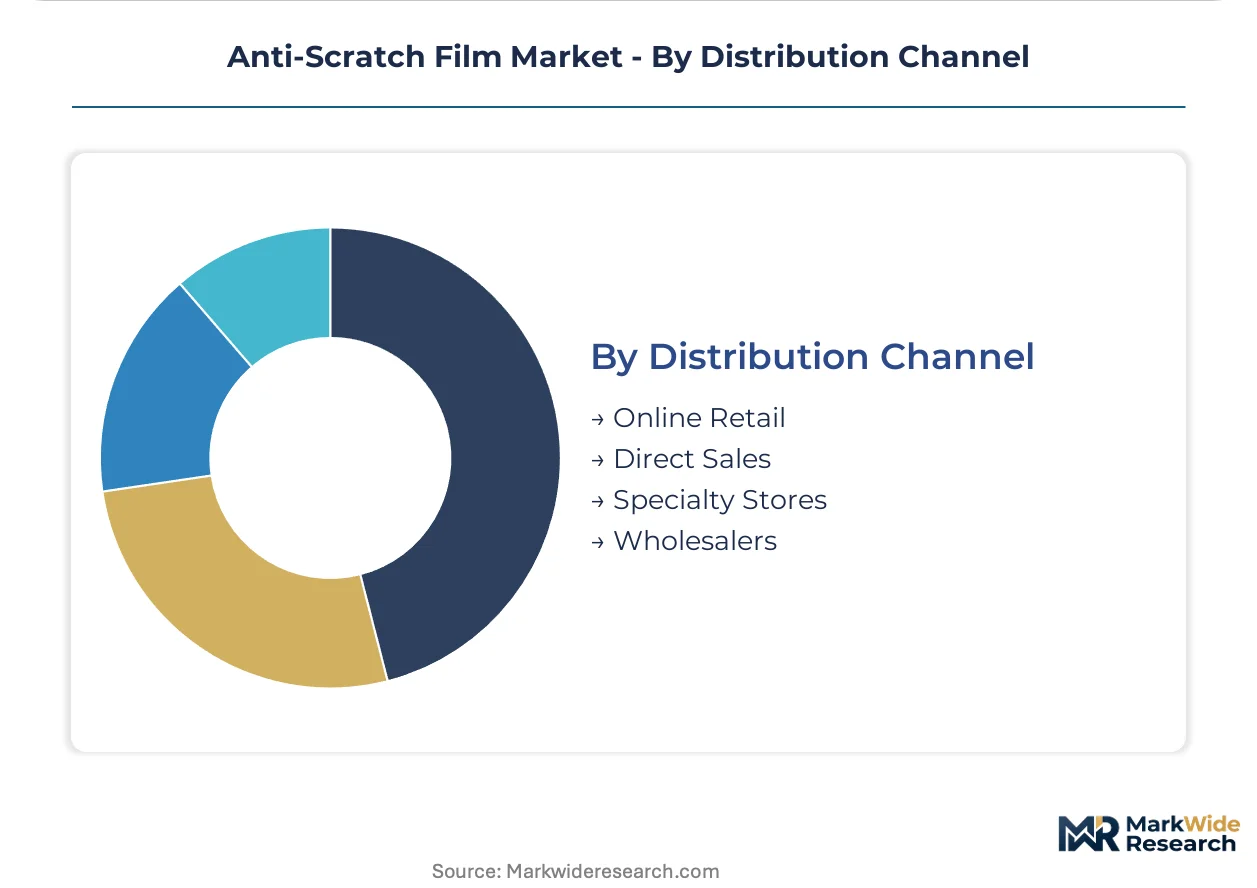
Distribution Channel:
Channel structure reflects product complexity, from specification-heavy direct sales through convenience-oriented online retail.
- Online Retail:E-commerce platforms aggregate consumer screen protectors, automotive DIY kits, and bulk industrial orders. Amazon and Alibaba marketplaces dominate consumer-grade film sales, with German consumers showing strongest preference for detailed specification disclosure.
- Direct Sales:Technical field teams engage OEM specification engineers and tier-one coating converters. 3M and Nitto Denko maintain direct relationships with Seoul and Shenzhen electronics manufacturers for qualified material approval.
- Specialty Stores:Automotive detailing shops and mobile device repair boutiques offer professional installation services. Japanese electronics specialty retailers provide in-store screen protector application with dust-controlled installation environments.
- Wholesalers:Industrial distributors supply master rolls and converted sheets to secondary manufacturers and job shops. Korean petrochemical wholesalers coordinate just-in-time delivery to Seoul-area coating lines.
Direct sales capture the highest-margin specification business, while online retail is expanding most quickly through consumer self-installation trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in anti-scratch film track closely to electronics and automotive manufacturing footprints, with East Asian production clusters supplying converted films to European and North American assembly operations. Trade balances shift as REACH compliance costs and GB standard alignment requirements reshape sourcing decisions.
China
Shenzhen's display manufacturing corridor generates concentrated demand for sub-micron protective layers on foldable devices. GB standards for electronic product safety mandate flammability ratings that filter substrate selection among Pearl River Delta converters. Domestic PET film production around Jiangsu and Zhejiang provinces supplies base materials to local coating operations, reducing import dependency for standard-grade applications.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg specify self-healing polyurethane films for premium vehicle paint protection, compressing warranty exposure. REACH chemical restrictions enforced by ECHA accelerate reformulation toward bio-based polyester alternatives among regional film converters. KBA vehicle type approval processes influence protective film specification for both domestic production and export-bound vehicles.
Japan
METI enforces JIS K5600 pencil hardness benchmarks that filter market access for imported protective films, extending third-party validation timelines. Kanto and Kansai electronics manufacturing clusters anchor precision-coated PET film demand for display and device applications. Domestic converters maintain qualified supplier relationships with Seoul and Shenzhen device assemblers through direct technical engagement.
South Korea
Seoul's display component ecosystem enforces 200,000-cycle flex testing for foldable device films, eliminating commodity-grade suppliers from procurement lists. MFDS chemical safety disclosure requirements parallel REACH frameworks for imported film formulations. Busan-Ulsan petrochemical complexes supply PET base films to regional coating operations serving Samsung and LG procurement teams.
United States
Automotive assembly plants in Michigan and Tennessee specify paint protection films for exterior durability in premium truck and SUV segments. EPA volatile organic compound regulations influence solvent-free adhesive formulation choices among domestic converters. California's electronic device repair market drives consumer-grade screen protector demand through specialty retail and e-commerce channels.
Anti-Scratch Film Market Competitive Environment
On the supply side, the industry is structured around three tiers differentiated by coating technology depth and OEM qualification status. Japanese and Korean chemical conglomerates anchor the premium tier through precision deposition capabilities and JIS-certified hardness ratings. Mid-scale regional converters compete on conversion economics and regional logistics proximity. Strategic moves concentrate on qualified supplier list consolidation by automotive OEMs and backward integration into hard-coat precursor synthesis.
Within the diversified chemical conglomerate tier, 3M and Nitto Denko Corporation exemplify positioning through microreplicated surface structure patent portfolios and precision coating line density. Eastman Chemical Company anchors a second archetype as a petrochemical-origin substrate supplier with downstream film conversion capabilities. Avery Dennison Corporation occupies a distinct position bridging adhesive technology heritage with protective film specification engineering. These three entities collectively represent the supply-side concentration visible in qualified vendor lists across Seoul and Shenzhen electronics corridors.
| Leading Market Players |
|---|
| 3M |
| Avery Dennison Corporation |
| LINTEC Corporation |
| Nitto Denko Corporation |
| Saint-Gobain Performance Plastics |
| POLIFILM |
| TEKRA |
| XPEL |
| Eastman Chemical Company |
| Others |
Value Chain & Pricing Dynamics
Busan-Ulsan to Shenzhen maritime freight corridors transmit Korean petrochemical base film costs directly into Pearl River Delta coating converter economics, compressing margin pools for mid-tier converters while amplifying price differentiation between JIS-certified premium grades and uncertified commodity alternatives.
Pricing Analysis
Current-generation microreplicated surface structures command substantial premiums over prior-generation UV-cured acrylate coatings and next-generation nanoimprint lithography films still in qualification. Three-tier pricing structure across premium, standard, and economy levels tracks JIS K5600 certification status and REACH compliance depth, with automotive OEM procurement teams exhibiting lowest price sensitivity due to warranty cost containment priorities and aftermarket DIY installers showing highest elasticity. Price differentiation hinges on hardness rating precision and optical clarity specifications, while pricing pressure stems from silica nanoparticle feedstock volatility squeezing optical-grade film margins.
Supply Chain Analysis
Tariff exposure between China and major export destinations dominates supply chain risk assessment for anti-scratch film converters. Raw material flows concentrate around Korean and Japanese petrochemical complexes for PET base film, Chinese Jiangsu-Zhejiang provinces for commodity substrate production, and German chemical manufacturers for polyurethane elastomer precursors. Hard-coat precursor synthesis draws from semiconductor-grade silicon supply chains, creating dependency on East Asian wafer manufacturing capacity. Distribution runs through tier-one coating converters supplying qualified vendor lists at Samsung and LG, with logistics disruption vulnerability concentrated in Korean Strait shipping lanes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Glass-ceramic direct deposition technologies threaten substitution for polymer-based protective films in premium electronics applications, compelling incumbents to accelerate functional layer integration beyond passive mechanical protection.
For Market Incumbents: Insulate qualified supplier status through backward integration into hard-coat precursor synthesis and captive JIS K5600 certification laboratory capacity. 3M and Nitto Denko patent thickets in microreplicated surface structures defend against commodity erosion, while consolidation of Shenzhen-area coating converters reduces audit burden from REACH SVHC disclosure mandates. Priority investment targets electron-beam curing equipment for instant processing advantages. For New Entrants and Emerging Players: Indian automotive assembly paint shops and component molding operations represent the most penetrable entry point for specification-engineered protective films, with domestic OEM procurement teams currently sourcing through European and Korean distributor intermediaries. GB standard flammability alignment for Shenzhen display manufacturing creates compliant-supplier preference for new entrants investing in additive package requalification. Go-to-market execution should anchor on direct technical field engagement with tier-one coating converters rather than price-competitive commodity positioning. For Investors and Strategic Acquirers: Precision coating line operators with existing JIS certification infrastructure and established relationships with Seoul electronics OEMs present the highest acquisition value for long-term market participation. Viability across the projection horizon depends on foldable electronics proliferation sustaining 200,000-cycle flex testing specification intensity. Signal to monitor: Samsung and LG procurement team decisions to internalize film conversion versus maintain external qualified supplier lists.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hard-Coat Precursors | Captive silica nanoparticle supply insulates margin from semiconductor-grade silicon volatility. |
| JIS K5600 Certification Laboratory Investment | In-house validation compresses third-party testing timelines from 14 months toward 6-month cycles. |
| REACH-Compliant Additive Package Requalification | ECHA SVHC disclosure mandates filter competitor field for European automotive interior specifications. |
| Electron-Beam Curing Equipment Deployment | Instant processing reduces thermal stress on heat-sensitive PET-TPU laminate substrates for foldable devices. |
| Indian Automotive OEM Direct Technical Engagement | First-mover positioning in underpenetrated paint protection film specification at domestic assembly plants. |
Study Parameters
Operator-level perspectives from hard-coat application technicians, precision coating line managers, automotive OEM specification engineers, and electronics procurement leads at Samsung and LG anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation against customs trade data, Korean petrochemical industry association reports, ECHA SVHC candidate list disclosures, and SEC filings from diversified chemical conglomerates. Bottom-up demand modeling triangulated against top-down market sizing across polymer film, adhesive film, laminated film, and coated film product categories.
Scenario-bracketing framed volume and value outputs across the analysis window, with segmentation dimensions spanning product type, application vertical, end-user procurement sophistication, and distribution channel structure. CAGRs derived from elasticity-adjusted demand curves incorporating automotive OEM specification tightening rates and foldable electronics manufacturing capacity expansion. Industry-specific inputs included silica nanoparticle feedstock cost trajectories and JIS K5600 certification timeline compression trends.
Macroeconomic conditions sit as an overlay; deviation in semiconductor capital expenditure cycles and East Asian logistics cost indices would shift the trajectory for optical-grade film demand. Forecasts reflect documented assumptions regarding REACH enforcement intensity and GB standard alignment requirements. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Spices, Dry Mixes and Extracts Packaging Market
Packaging Materials
PCR Thermoforms Market
Packaging Materials
VCI Films Market
Packaging Materials
Bottle Sealing Wax Market
Packaging Materials
Flow Wraps Market
Packaging Materials
Bakeable Trays Market
Packaging Materials
Disposable Egg Trays Market
Packaging Materials
Skin Packaging Market
Packaging Materials
Brightness Enhancement Films Market
Packaging Materials
Cast Polypropylene (CPP) Films Market
Packaging Materials
Sanitizer Packaging Market
Packaging Materials
Packaging Straps and Buckles Market
Packaging Materials
Cold Seal Films Market
Packaging Materials
Primary Packaging Market
Packaging Materials
Twist Tie Market
Packaging Materials
PET Packaging Market