
 China Packaging Market | 2026-2036
China Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
China Packaging Market Insights
China's dual carbon goals are pivoting converter investment toward lightweight fiber substrates and recyclable mono-material structures. Nine Dragons Paper leverages its integrated pulp-to-box network across Guangdong and Jiangsu to lock in recycled fiber supply. YUTO Packaging Technology anchors high-volume folding carton production for consumer electronics clients. Tetra Pak (China) navigates aseptic liquid packaging standards while extending its carton collection infrastructure into lower-tier cities.
Packaging in China encompasses protective, containment, and informational systems engineered from paper, plastic, glass, or metal substrates with specified barrier properties, tensile strength, and seal integrity measured in MVTR and OTR parameters. Its primary purpose is preserving product quality through distribution while enabling regulatory traceability and shelf communication. Flexible packaging leads volume due to its material efficiency in snack and instant noodle applications, while rigid formats sustain premium positioning in cosmetics and spirits. Corrugated boxes capture the fastest expansion as e-commerce fulfillment demands crush-resistant, right-sized shipping configurations.
SAMR enforces GB standards for food contact materials and labeling accuracy, while MEE administers extended producer responsibility rules and plastic restriction timelines that reshape material selection across converters. MIIT's green manufacturing certification program creates market access differentiation for facilities hitting energy and water intensity benchmarks. Stakeholders must monitor how provincial enforcement variance between Zhejiang and Guangdong affects compliance cost structures and supplier qualification timelines.
Market Dynamics
E-commerce fulfillment networks are compressing order cycles and forcing corrugated converters to deploy automated right-sizing systems across Yangtze River Delta plants.
Growth Catalysts
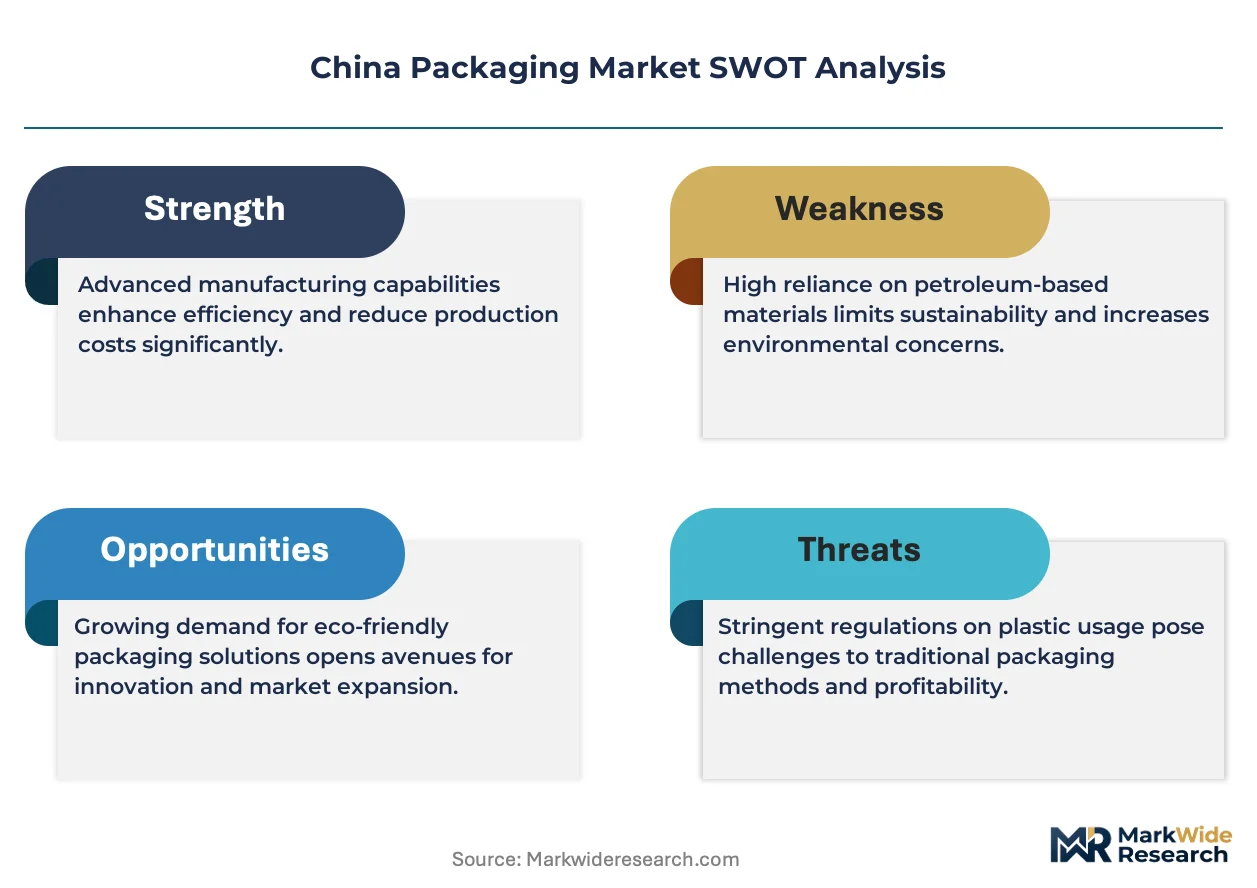
- Dual carbon mandates:MEE's plastic restriction timelines are accelerating fiber substitution in food contact applications. Converters retool lines for recyclable mono-material structures.
- Cross-border e-commerce:Alibaba and JD.com fulfillment centers in Jiangsu province demand crush-resistant shipping configurations for electronics exports.
- Barrier coating advances:Water-based coatings are displacing PE laminates in folding cartons for instant noodle brands seeking recyclability.
Market Restraints
- Recycled fiber cost volatility:OCC import bans since 2018 have concentrated domestic supply control with Nine Dragons and Lee & Man, squeezing mid-tier converter margins.
- Aseptic liquid packaging technical lock-in:Tetra Pak's proprietary filling equipment creates high switching costs for dairy processors.
- Provincial enforcement variance:Zhejiang's stricter MEE inspections versus Guangdong's phased compliance timelines fragment qualification costs.
Strategic Opportunities
- Lower-tier city collection infrastructure:SAMR's extended producer responsibility rules create first-mover advantage for carton collection networks in Henan and Sichuan.
- Smart packaging convergence:NFC-enabled folding cartons for spirits authentication merge physical substrates with digital traceability.
- MIIT green manufacturing certification:Facilities hitting water intensity benchmarks in Jiangsu unlock preferential supplier status to multinational FMCG brands.
Industry Challenges
- Skilled automation technician scarcity:Corrugated plants deploying Bobst and BHS lines face 18-month recruitment cycles for mechatronics specialists in the Pearl River Delta.
- GB standard compliance timeline compression:SAMR's accelerated food contact material testing protocols force reformulation cycles that collide with seasonal packaging contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Packaging Market |
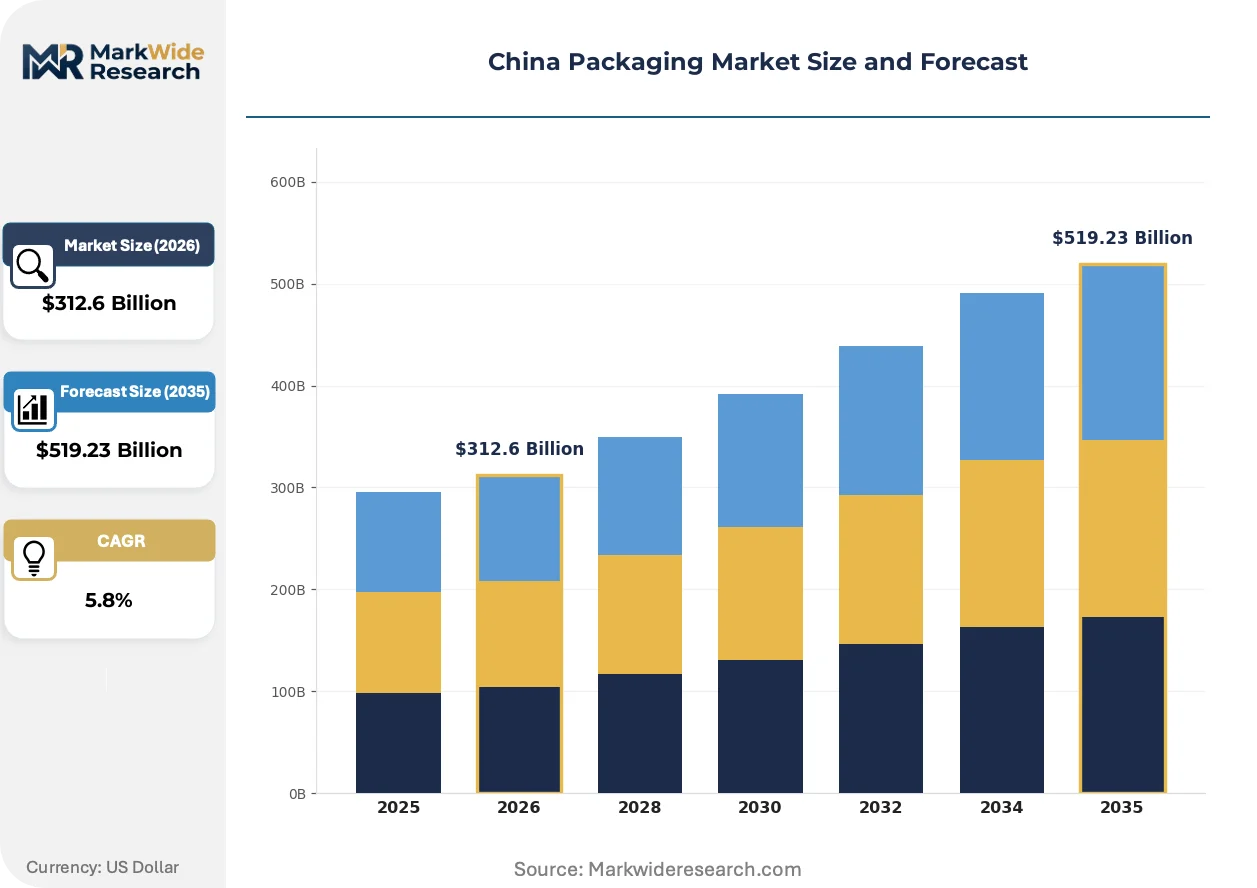
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $519.23 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Packaging, Rigid Packaging, Corrugated Boxes, Tags Material: Plastic, Paper, Glass, Metal End User: Food & Beverages, Cosmetics, Pharmaceuticals, Electronics Packaging Type: Cartons, Pouches, Bottles, Labels |
| Companies Covered | Nine Dragons Paper (Holdings) Ltd., Lee and Man Paper Manufacturing Ltd., YUTO Packaging Technology Co., Ltd., Hexing Packaging Co., Ltd., Shanying International Holdings Co., Ltd., Greatview Aseptic Packaging Co., Ltd., Shanghai Zijiang Enterprise Group Co., Ltd., Amcor Plc, Tetra Pak (China) Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Packaging Market Trends and Innovations
Digital print integration and substrate lightweighting are converging to collapse minimum order quantities and compress design-to-delivery cycles for brand owners.
Digital flexo with in-line spectrophotometry is decentralizing short-run color consistency from centralized gravure houses to regional corrugated plants. Electronics brands in Shenzhen now approve packaging artwork in 48-hour cycles rather than two-week gravure plate schedules. This is decentralizing pre-press capacity from Dongguan printing clusters to satellite facilities in Chengdu and Xi'an.
MEE's extended producer responsibility implementation rules are forcing liquid packaging converters to fund municipal carton collection infrastructure. Dairy processors must now contract separately for collection logistics in tier-3 cities where reverse logistics networks remain undeveloped. Multinational beverage brands are responding by consolidating supplier lists to converters with captive recycling partnerships.
Brand owners in Shanghai and Hangzhou are unbundling packaging specification from long-term converter contracts, shifting to project-based competitive bidding for seasonal campaigns. This procurement fragmentation favors mid-tier folding carton specialists with digital proofing capabilities over incumbent gravure-dependent suppliers. Cosmetics brands exhibit the most aggressive unbundling, compressing supplier relationships to single-SKU trial periods before volume awards.
China Packaging Market Segmentation
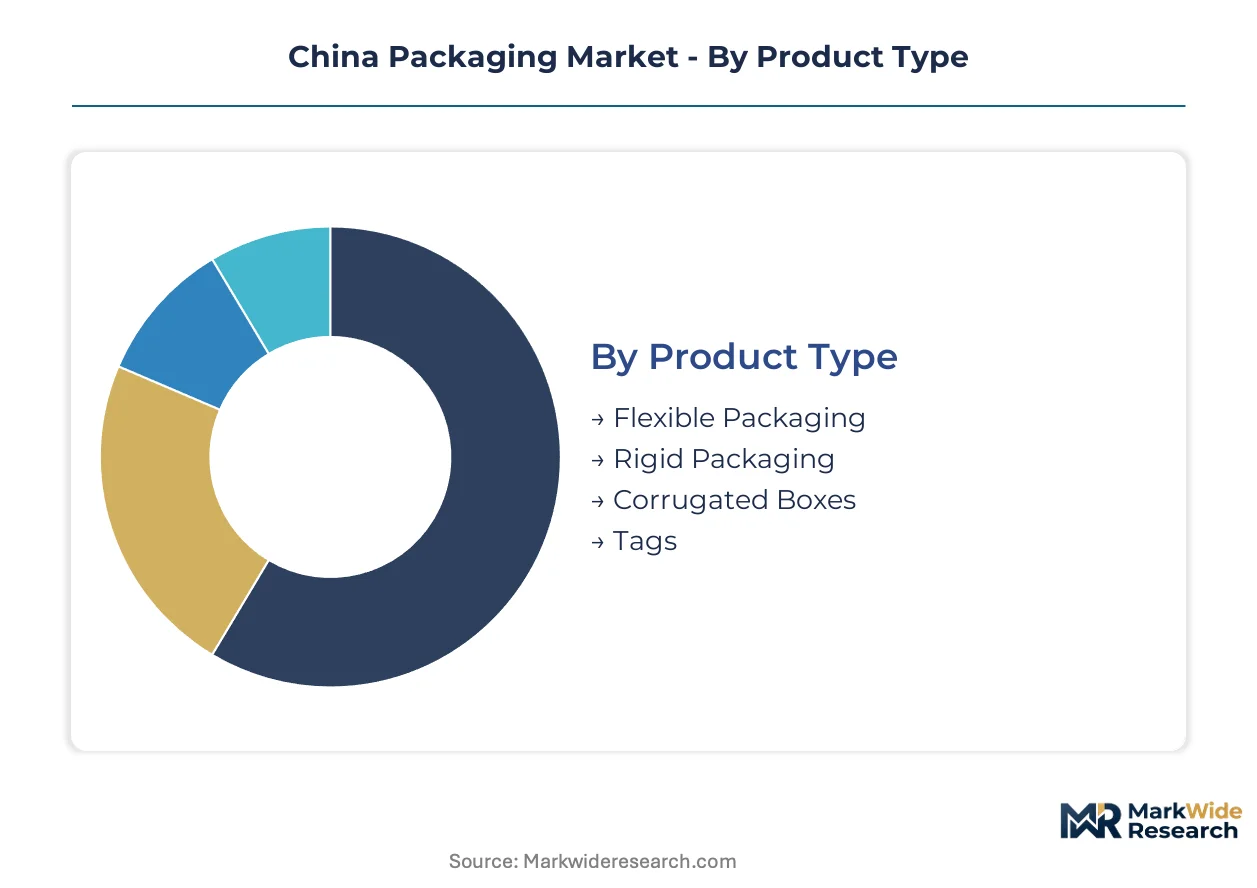
Packaging buyers in China differentiate procurement strategies by product protection requirements, regulatory compliance burdens, and fulfillment velocity needs. E-commerce logistics and dual carbon mandates fragment demand across substrate types and structural formats.
Product Type:
Cost tiers separate high-volume commodity converters from specialty solution providers serving premium positioning needs.
- Flexible Packaging:Multi-layer films and pouches engineered with specified MVTR and OTR barrier properties for shelf-stable food applications. Instant noodle brands in the Yangtze River Delta drive volume for metallized BOPP and cast PP structures as water-based coatings displace PE laminates for recyclability compliance.
- Corrugated Boxes:Fluted fiberboard configurations ranging from single-wall B-flute to triple-wall heavy-duty for electronics export protection. JD.com and Alibaba fulfillment centers in Jiangsu province demand automated right-sizing and crush-resistant specifications for cross-border e-commerce.
- Rigid Packaging:Injection-molded and thermoformed containers for cosmetics and spirits premium positioning.
- Tags:Apparel and logistics labeling with variable data print compatibility.
Volume sits with flexible formats; growth tilts toward corrugated as e-commerce fulfillment accelerates.
Material:
Application requirements dictate substrate selection between barrier performance, mechanical strength, and end-of-life recovery pathways.
- Paper:Recycled fiber-based substrates from OCC and kraft pulp sources, spanning linerboard, corrugating medium, and folding carton grades. Nine Dragons and Lee & Man control domestic supply chains following import bans, concentrating cost volatility exposure with mid-tier converters.
- Plastic:PE, PP, PET, and multilayer barrier films for moisture-sensitive applications. MEE plastic restriction timelines force mono-material redesigns in food contact applications to meet recyclability mandates.
- Glass:Borosilicate and soda-lime containers for spirits and pharmaceutical stability requirements.
- Metal:Tinplate and aluminum for aerosol and canned food preservation.
Paper dominates tonnage; plastic faces substitution pressure from fiber alternatives.
End User:
Customer type determines specification complexity, certification requirements, and supplier qualification timelines.
- Food & Beverages:Aseptic liquid packaging, snack flexible films, and beverage cartons requiring SAMR GB standard compliance for food contact materials. Dairy processors navigate Tetra Pak equipment lock-in while funding municipal carton collection infrastructure under extended producer responsibility rules.
- Electronics:ESD-protective corrugated and molded pulp for semiconductor and consumer device shipment. Shenzhen and Dongguan brands compress artwork approval cycles through digital flexo adoption.
- Cosmetics:Premium folding cartons and rigid boxes with authentication features and shelf differentiation.
- Pharmaceuticals:Blister packs and barrier bottles under NMPA serialization and stability requirements.
Food and beverage anchors volume; electronics exhibits steepest expansion trajectory from cross-border fulfillment demand.
Packaging Type:
Structural format selection balances protection function, shelf communication surface, and supply chain handling efficiency.
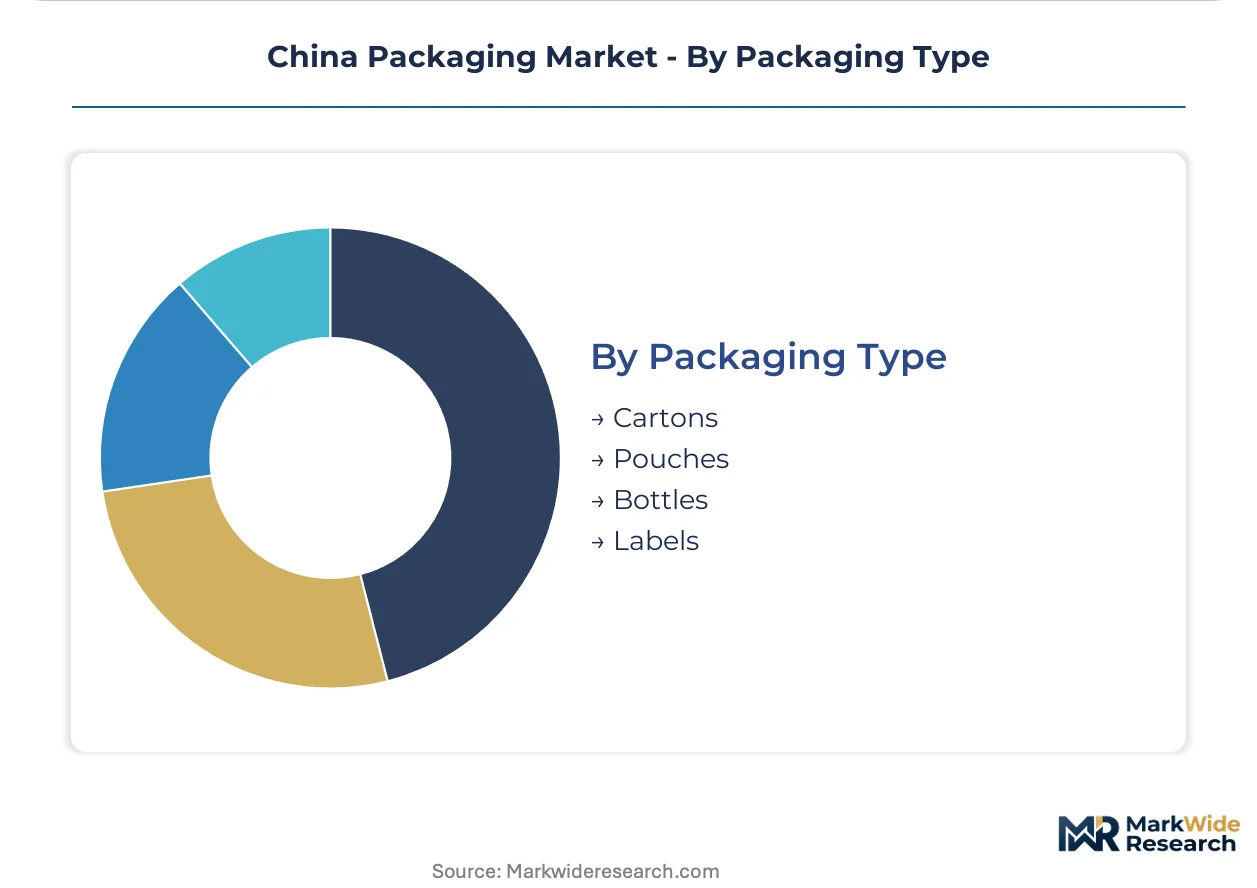
- Cartons:Folding carton and corrugated case formats for retail-ready and shipping applications. YUTO Packaging Technology anchors high-volume production for consumer electronics clients in Guangdong while digital print integration collapses minimum order quantities for seasonal campaigns.
- Pouches:Stand-up and flat pouch configurations for snack and personal care products.
- Bottles:Blow-molded and injection-stretch containers for liquid product containment.
- Labels:Pressure-sensitive and shrink-sleeve formats for brand communication and regulatory disclosure.
Cartons capture the largest addressable base; pouch formats gain share in convenience-oriented segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta manufacturing corridor around Shanghai anchors China's packaging demand concentration, with Jiangsu province hosting JD.com and Alibaba fulfillment centers that drive corrugated volume. Guangdong's Pearl River Delta maintains parallel density in electronics export packaging. Provincial enforcement variance between Zhejiang and Guangdong reshapes compliance cost structures across converters.
Guangdong Province
Electronics brands in Shenzhen compress artwork approval cycles through digital flexo adoption, collapsing traditional two-week gravure schedules into 48-hour turnarounds. MEE's extended producer responsibility rules force liquid packaging converters to fund municipal carton collection infrastructure in tier-3 cities. Dongguan printing clusters face decentralization pressure as pre-press capacity migrates to satellite facilities in Chengdu and Xi'an.
Jiangsu Province
Cross-border e-commerce fulfillment networks demand crush-resistant shipping configurations for electronics exports through Alibaba and JD.com centers. MIIT's green manufacturing certification program creates supplier qualification differentiation for facilities hitting water intensity benchmarks. Nanjing and Suzhou host automated right-sizing system deployments across corrugated plants serving Yangtze River Delta manufacturing.
Zhejiang Province
Stricter MEE inspections versus Guangdong's phased compliance timelines fragment qualification costs for mid-tier converters. Hangzhou cosmetics brands exhibit aggressive procurement unbundling, compressing supplier relationships to single-SKU trial periods before volume awards. Ningbo and Wenzhou folding carton specialists capture seasonal campaign work through digital proofing capabilities.
Sichuan-Chongqing
Lower-tier city collection infrastructure creates first-mover advantage for carton collection networks under SAMR's extended producer responsibility rules. Chengdu satellite facilities absorb pre-press capacity decentralizing from Dongguan clusters. Chongqing's western logistics hub position supports e-commerce fulfillment penetration into inland provinces with shorter delivery radius requirements.
Shandong Peninsula
Pulp-to-box integrated networks concentrate recycled fiber supply control following OCC import bans since 2018. Qingdao and Yantai converters face margin pressure from domestic supply concentration with Nine Dragons and Lee & Man. Food contact material applications drive barrier coating advances as water-based formulations displace PE laminates for recyclability compliance.
China Packaging Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification and captive fiber access dimensions. The vendor base stratifies between integrated pulp-to-box operators, high-volume folding carton specialists, and multinational technology licensors. Three archetypes dominate: fiber-integrated conglomerates controlling recycled supply chains, digital-enabled mid-tier converters capturing seasonal campaign work, and proprietary equipment licensors locking in dairy processors. Competitive moves concentrate on backward integration into pulp assets and geographic consolidation of collection infrastructure.
Within the fiber-integrated tier, Nine Dragons Paper (Holdings) Ltd. and Lee and Man Paper Manufacturing Ltd. occupy positions as recycled fiber gatekeepers following import ban consolidation. YUTO Packaging Technology Co., Ltd. exemplifies the high-volume folding carton archetype serving consumer electronics clients. Tetra Pak (China) Ltd. represents the proprietary equipment licensor model creating switching cost barriers for aseptic liquid packaging applications.
| Leading Market Players |
|---|
| Nine Dragons Paper (Holdings) Ltd. |
| Lee and Man Paper Manufacturing Ltd. |
| YUTO Packaging Technology Co., Ltd. |
| Hexing Packaging Co., Ltd. |
| Shanying International Holdings Co., Ltd. |
| Greatview Aseptic Packaging Co., Ltd. |
| Shanghai Zijiang Enterprise Group Co., Ltd. |
| Amcor Plc |
| Tetra Pak (China) Ltd. |
| Others |
Pricing and Supply Chain Analysis
OCC domestic price indices cascade through China's packaging supply chain, compressing margins for mid-tier converters while concentrating pricing power with Nine Dragons and Lee & Man's integrated pulp-to-box networks. This fiber cost volatility stratifies buyers into three tiers: multinational FMCG brands absorbing premium for MIIT-certified green manufacturing, regional electronics exporters negotiating volume contracts, and price-sensitive commodity buyers facing 18-month qualification cycles.
Pricing Analysis
Throughput-based pricing anchors corrugated contracts to automated line uptime guarantees, with JD.com and Alibaba fulfillment centers paying premiums for crush-resistant specifications. Price differentiation separates MIIT green-certified Jiangsu facilities from uncertified Shandong competitors, while cosmetics brands in Hangzhou drive project-based bidding fragmentation. Cost compression in folding cartons intensifies as digital flexo adoption collapses gravure plate economics, squeezing legacy Dongguan suppliers.
Supply Chain Analysis
Dual-sourcing mandates from electronics brands in Shenzhen force corrugated buyers to qualify parallel suppliers across Guangdong and Jiangsu provinces. Raw material flows draw from domestic OCC streams, water-based coating formulations, and captive pulp networks. Single-source vulnerability concentrates in Tetra Pak's aseptic filling equipment lock-in for dairy processors. Distribution runs through Yangtze River Delta fulfillment clusters and Pearl River Delta export corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's packaging market functions as a consolidation play where MEE's extended producer responsibility rules and OCC supply concentration force weaker converters into distressed sales or contract manufacturing roles.
For Market Incumbents: To counter digital-enabled mid-tier competitors capturing seasonal cosmetics work, Nine Dragons and Lee & Man should deepen backward integration into captive pulp assets while deploying automated right-sizing systems across Yangtze River Delta plants. MIIT green manufacturing certification investment unlocks preferential supplier status to multinational FMCG brands. For New Entrants and Emerging Players: Launch via digital flexo-enabled satellite facilities in Chengdu and Xi'an, targeting pre-press capacity decentralizing from Dongguan clusters. Henan and Sichuan lower-tier city carton collection infrastructure presents the most penetrable white space under SAMR's extended producer responsibility implementation. For Investors and Strategic Acquirers: Distressed-cycle entries favor fiber-integrated mid-caps in Jiangsu with MIIT certification and Alibaba supply relationships, as OCC import ban legacy effects persist. The signal to watch is provincial MEE enforcement variance tightening in Zhejiang versus Guangdong, which would accelerate qualification cost fragmentation and supplier attrition.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Pulp Assets | Nine Dragons locks in fiber supply control following OCC import bans since 2018. |
| Automated Right-Sizing System Deployment | Corrugated plants serving JD.com centers in Jiangsu compress fulfillment cycle times. |
| MIIT Green Manufacturing Certification | Facilities hitting water intensity benchmarks unlock multinational FMCG supplier status. |
| Digital Flexo Pre-Press Capacity Expansion | Satellite facilities in Chengdu absorb artwork approval cycles from Dongguan clusters. |
| Lower-Tier City Collection Infrastructure Buildout | Converters fund municipal carton networks under SAMR extended producer responsibility rules. |
Research Methodology
China customs records, MIIT facility certification databases, and SAMR regulatory filings formed the secondary backbone, cross-referenced with primary interviews across converter operations managers, electronics brand procurement leads, dairy processor packaging directors, and corrugated plant automation engineers. Bottom-up and top-down triangulation validated volume estimates against disclosed capacity expansions and fulfillment center footprint data.
Bottom-up modeling anchored projections to individual facility throughput, substrate grade mix, and end-user contract structures, while top-down cross-checks applied macroeconomic drivers across the projection horizon. Segmentation dimensions included product type, material substrate, end-user industry, and provincial regulatory cluster. CAGRs derived from disclosed capacity utilization trends and e-commerce fulfillment velocity benchmarks.
Provincial MEE enforcement variance, recycled fiber price volatility, and cross-border e-commerce policy shifts are the dominant revision risks. Deviation in dual carbon goal implementation timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
North America Single-Use Packaging Market
Packaging Materials
United States Single Use Packaging Market
Packaging Materials
Honeycomb Packaging Market
Packaging Materials
PET Strap Market
Packaging Materials
Vacuum Thermoformed Packaging Market
Packaging Materials
Tube and Stick Packaging Market
Packaging Materials
Cold Form Foil Market
Packaging Materials
Global Hot Stamping Foils Market
Packaging Materials
Fiber Lids Market
Packaging Materials
Plastic Strapping Materials Market
Packaging Materials
Europe Airless Packaging Market
Packaging Materials
Thermoformed Skin Packaging Market
Packaging Materials
Packaging Materials Market
Packaging Materials
Spices, Dry Mixes and Extracts Packaging Market
Packaging Materials
Disposable Icepacks Market
Packaging Materials
Cash Management Supplies Packaging Market