
 Water Soluble Pods Packaging Market | 2026-2036
Water Soluble Pods Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Water Soluble Pods Packaging Market Outlook
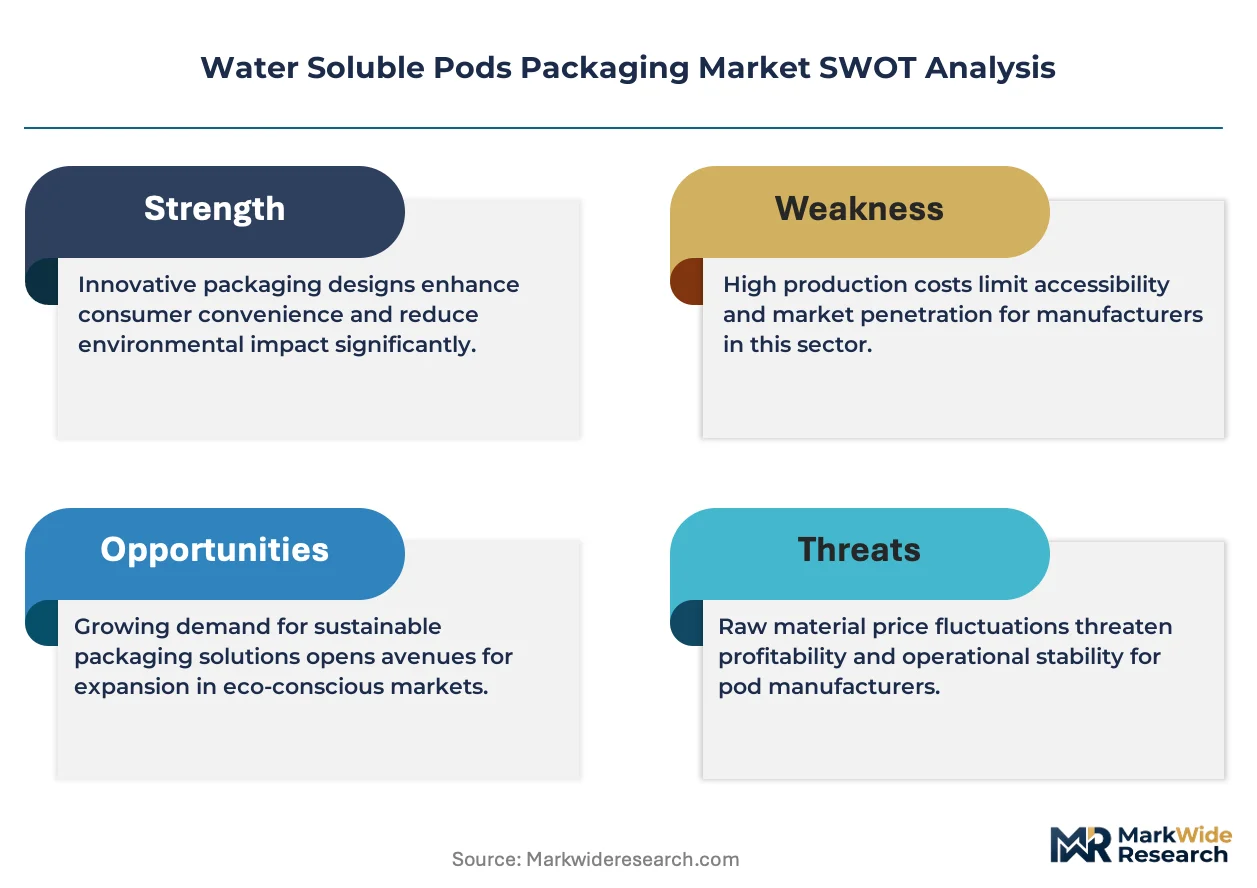
Pharmaceutical unit-dose packaging is recalibrating demand profiles across the value chain as hospitals and long-term care facilities prioritize contamination control and dosing accuracy. Mondi Group leverages its European flexible packaging infrastructure to supply pharmaceutical-grade pod substrates with validated dissolution profiles. KURARAY Co., Ltd. anchors the supply of EVOH and PVOH resin grades that govern film barrier performance in high-humidity climates. Mitsubishi Chemical Corporation differentiates through proprietary copolymer architectures that extend shelf stability for oxygen-sensitive agricultural actives.
Water soluble pods packaging comprises single-dose enclosures formed from polyvinyl alcohol (PVA) or starch-derived films engineered to dissolve completely in aqueous environments within 30–120 seconds at specified temperature thresholds, eliminating manual dosing and secondary container waste. The primary industrial purpose centers on delivering concentrated actives—surfactants, nutrients, or APIs—in pre-measured, hermetically sealed formats that reduce spillage risk and consumer exposure. Single-use Pods dominate current volume as laundry and dishwasher detergent brands complete format transitions, while Biodegradable Pods represent the fastest-expanding material-design category as starch-based and cellulose alternatives displace conventional PVA in jurisdictions with stringent microplastic screening. Concentrated Pods concentrate margin pools in agricultural and pharmaceutical applications where active ingredient stability commands premium pricing.
The EPA regulates pod packaging under the Federal Insecticide, Fungicide, and Rodenticide Act when used for agricultural chemicals, requiring child-resistant features and dissolution validation. REACH and the EU Packaging and Packaging Waste Regulation impose substance restrictions and extended producer responsibility obligations that favor biodegradable film alternatives in European markets. India's BIS certification mandates and the PLI scheme for advanced packaging materials are accelerating domestic film extrusion capacity. Stakeholders must monitor evolving state-level microplastic definitions in the US and EU, as these classifications will determine whether PVA-based pods retain market access or trigger material substitution cycles.
Market Dynamics
Format conversion from conventional bottles to pre-dosed pods is compressing supply chains and concentrating purchasing power among detergent manufacturers who now specify film barrier performance directly with resin suppliers.
Growth Catalysts
- EU Single-Use Plastics Directive:Binding reduction targets for conventional plastic packaging are accelerating brand transitions to water-soluble formats in home care categories.
- Pre-dosed agricultural actives:Farmers in water-stressed regions are adopting pod-based crop protection to eliminate dosing errors and reduce chemical runoff.
- North Rhine-Westphalia industrial clustering:Proximity between detergent formulators and flexible packaging converters in Germany is shortening development cycles for new pod specifications.
Market Restraints
- EVOH resin supply concentration:KURARAY Co., Ltd. and limited Asian suppliers control high-barrier grades, creating vulnerability for humidity-sensitive formulations.
- Microplastic classification uncertainty:Pending state-level definitions in California and EU member states may reclassify PVA as a synthetic polymer, triggering forced material substitution.
- Starch film performance gaps:Current biodegradable alternatives exhibit slower dissolution kinetics and inferior mechanical strength versus PVA in cold-water applications.
Strategic Opportunities
- Pharmaceutical unit-dose expansion:Long-term care facilities in Germany and Japan are specifying validated dissolution profiles for contamination-critical API delivery.
- India PLI scheme for advanced packaging:Domestic film extrusion incentives are attracting substrate producers to serve South Asian agricultural and detergent markets.
- Direct-to-subscription channels:Concentrated pod refills via automated replenishment platforms are bypassing traditional retail shelf-space constraints in North American home care.
Industry Challenges
- Pharmaceutical-grade validation timelines:FDA and EMA dissolution profile certifications require 18-24 month stability studies, delaying product launches.
- Multi-layer film coextrusion expertise:Scarce process engineers capable of tuning PVOH-EVOH-starch laminates for specific temperature-triggered release.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water Soluble Pods Packaging Market |
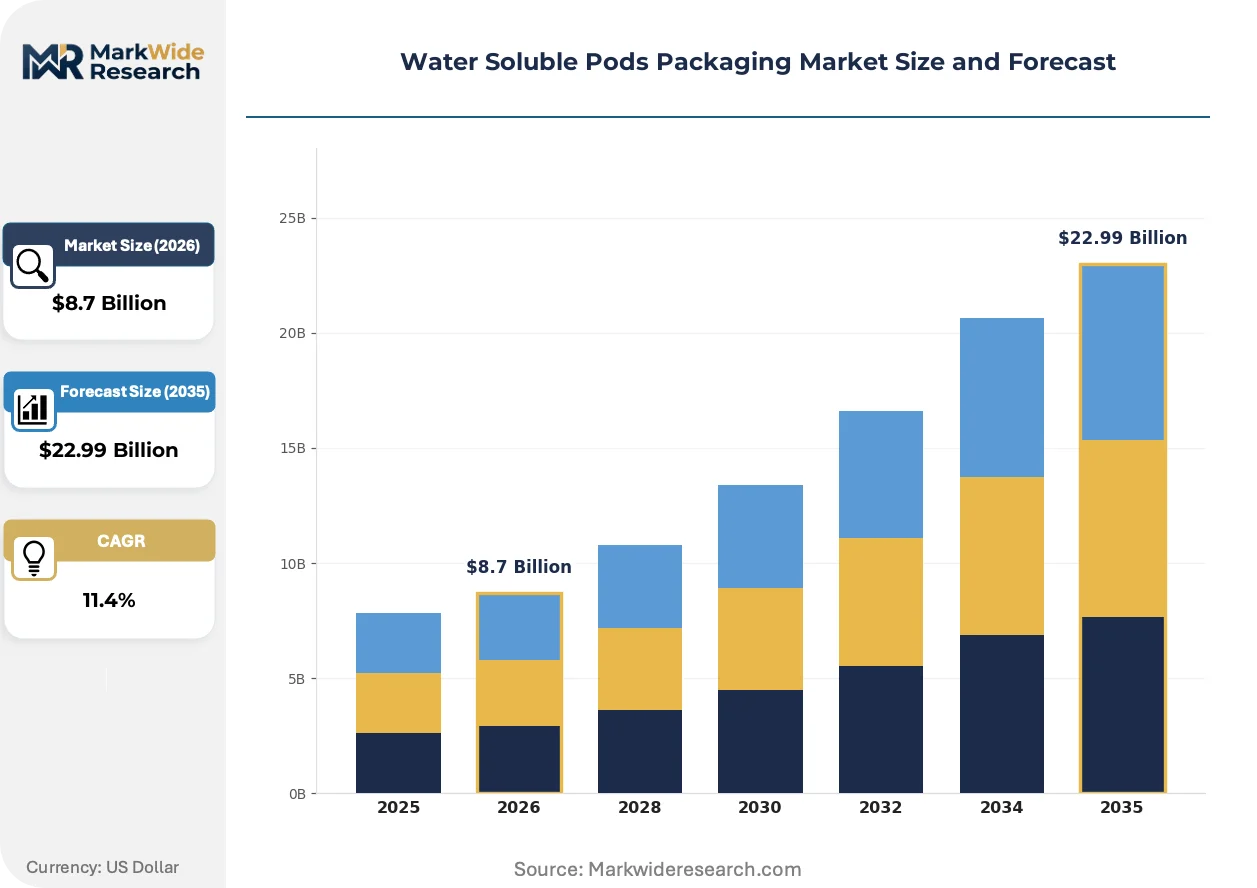
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-use Pods, Multi-pack Pods, Concentrated Pods, Biodegradable Pods Material: PVA, Starch-based, Gelatin, Cellulose End User: Cleansing Products, Food & Beverage, Agriculture, Pharmaceuticals Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Mondi Group, KURARAY Co., Ltd., Mitsubishi Chemical Corporation, Cortec Corporation, Aquapak Polymers Ltd., SEKISUI CHEMICAL CO., LTD., MonoSol, LLC, Constantia Flexibles, Aicello Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water Soluble Pods Packaging Market Strategic Shifts
Active material science development is bifurcating the market between performance-optimized PVA formulations and next-generation bio-based alternatives, with regulatory classification decisions determining which pathway captures investment.
Modular pod architectures with segmented compartments are modularizing delivery formats for multi-phase actives. Agricultural chemical manufacturers in Brazil and Australia are piloting designs that separate incompatible precursors until field dilution triggers reaction. This approach is modularizing product development cycles by allowing formulators to swap active ingredients without redesigning outer barrier films.
REACH substance restriction expansions under the EU Packaging and Packaging Waste Regulation are forcing film producers to document polymer biodegradation kinetics in marine environments. Convertors serving European detergent brands are accelerating starch-PVOH blend validation to pre-empt compliance thresholds. Agricultural pod applications face additional scrutiny as EFSA reviews soil accumulation data for residual film fragments.
Hospital procurement consortia are consolidating supplier lists around vendors with validated pharmaceutical-grade cleanroom extrusion capabilities. Group purchasing organizations in the United States are awarding multi-year contracts contingent on demonstrated dissolution reproducibility across temperature ranges. This concentration is squeezing regional flexible packaging converters who lack in-house analytical validation infrastructure.
Water Soluble Pods Packaging Market Segmentation
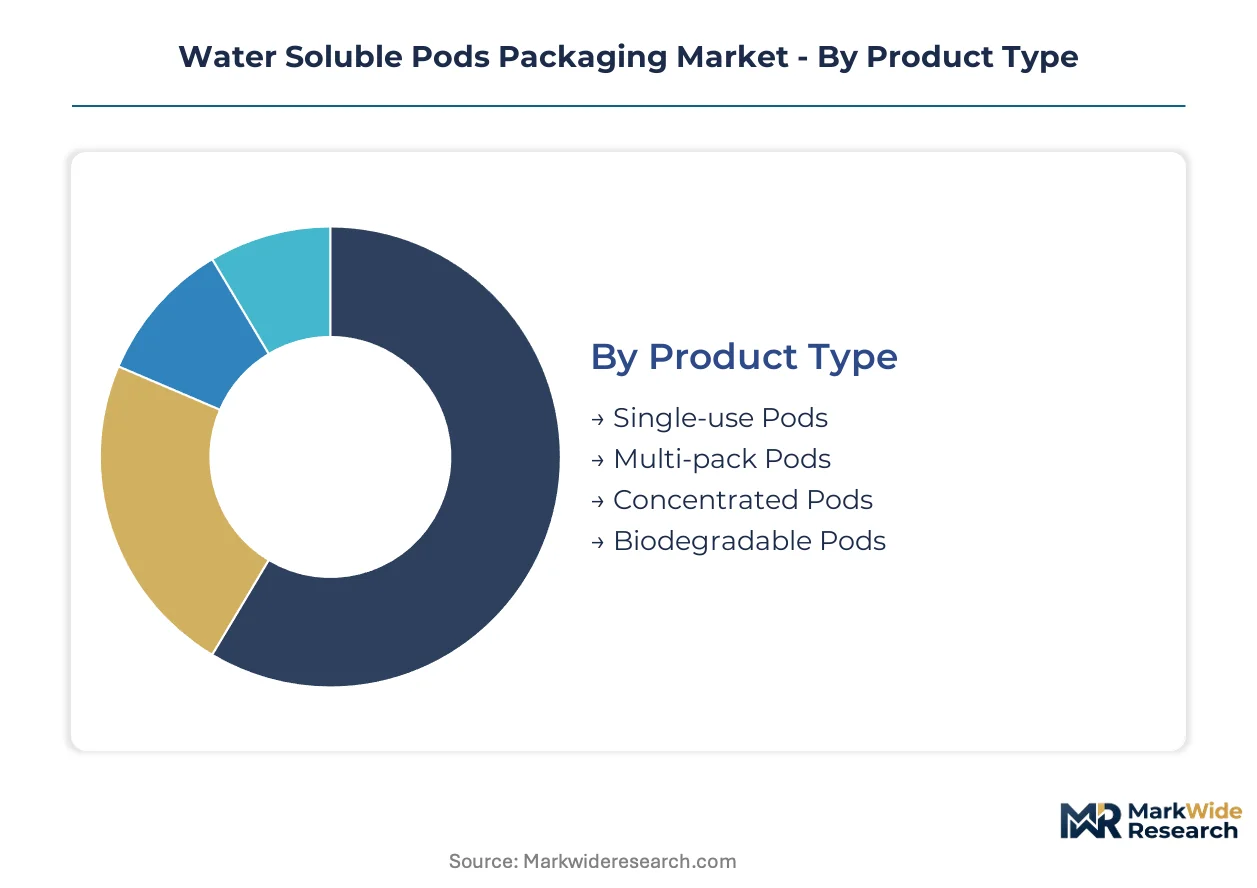
Segmentation in water soluble pods packaging reveals how technical specifications, material choices, and channel strategies concentrate margin pools differently across end-use applications. Manufacturers optimize film formulations and barrier architectures against dissolution kinetics, regulatory thresholds, and dosing precision requirements that vary sharply by customer segment.
Product Type:
Product architecture governs unit economics and supply chain configuration, with format choices determining whether converters pursue high-volume detergent contracts or specialized pharmaceutical validations.
- Single-use Pods:Pre-measured enclosures engineered for one-dose dispensing dominate home care applications where detergent brands have completed format transitions from conventional bottles. Laundry and dishwasher segments in Germany and California drive procurement volumes as brands respond to single-use plastics directives.
- Biodegradable Pods:Starch-derived and cellulose-based alternatives displace conventional PVA in jurisdictions with stringent microplastic screening. European markets under REACH substance restrictions and pending state-level definitions in California accelerate validation timelines for film producers.
- Multi-pack Pods:Bundled configurations for subscription replenishment channels reduce per-unit shipping costs and support direct-to-consumer models in North American home care.
- Concentrated Pods:High-active-load formats command premium pricing in agricultural and pharmaceutical applications where ingredient stability requires enhanced barrier performance.
Single-use Pods lead on scale; Biodegradable Pods lead on momentum.
Material:
Material selection determines dissolution profiles, mechanical integrity, and regulatory access across humidity zones and temperature thresholds.
- PVA:Polyvinyl alcohol films engineered for 30–120 second dissolution at specified temperatures provide the baseline performance standard for detergent applications. KURARAY Co., Ltd. and Mitsubishi Chemical Corporation anchor resin supply for high-barrier grades serving humidity-sensitive formulations.
- Starch-based:Derived from renewable feedstocks, these alternatives exhibit slower dissolution kinetics in cold-water applications but satisfy biodegradation mandates under EU Packaging and Packaging Waste Regulation. Convertors are accelerating starch-PVOH blend validation to pre-empt compliance thresholds.
- Cellulose:Plant-derived films offer tunable mechanical properties for pharmaceutical unit-dose applications requiring validated dissolution reproducibility.
- Gelatin:Traditional biopolymer retains niche use in pharmaceutical capsules and specialized agricultural coatings where oxygen barrier requirements are moderate.
PVA dominates installed capacity; Starch-based materials are climbing the fastest.
End User:
End-use specifications drive divergent validation requirements, from EPA FIFRA compliance for agricultural actives to FDA dissolution certifications for pharmaceutical delivery.
- Cleansing Products:Laundry and dishwasher detergent segments concentrate volume demand as brands convert bottle formats to pre-dosed pods. EU Single-Use Plastics Directive and California state-level packaging waste rules tighten compliance thresholds for conventional plastic alternatives.
- Pharmaceuticals:Unit-dose packaging for APIs requires 18–24 month stability studies for FDA and EMA dissolution profile certifications. Hospital procurement consortia in Germany and Japan are consolidating supplier lists around vendors with validated cleanroom extrusion capabilities.
- Agriculture:Pre-dosed crop protection pods eliminate dosing errors and reduce chemical runoff in water-stressed regions. EFSA reviews soil accumulation data for residual film fragments, adding scrutiny to material selection.
- Food & Beverage:Flavor and nutrient delivery applications face FSSAI mandates in India and analogous food-contact regulations elsewhere, limiting current penetration relative to industrial segments.
Cleansing Products leads on scale; Pharmaceuticals leads on momentum.
Distribution Channel:
Channel configuration determines working capital intensity and customer acquisition economics, with direct models bypassing traditional retail shelf-space constraints.
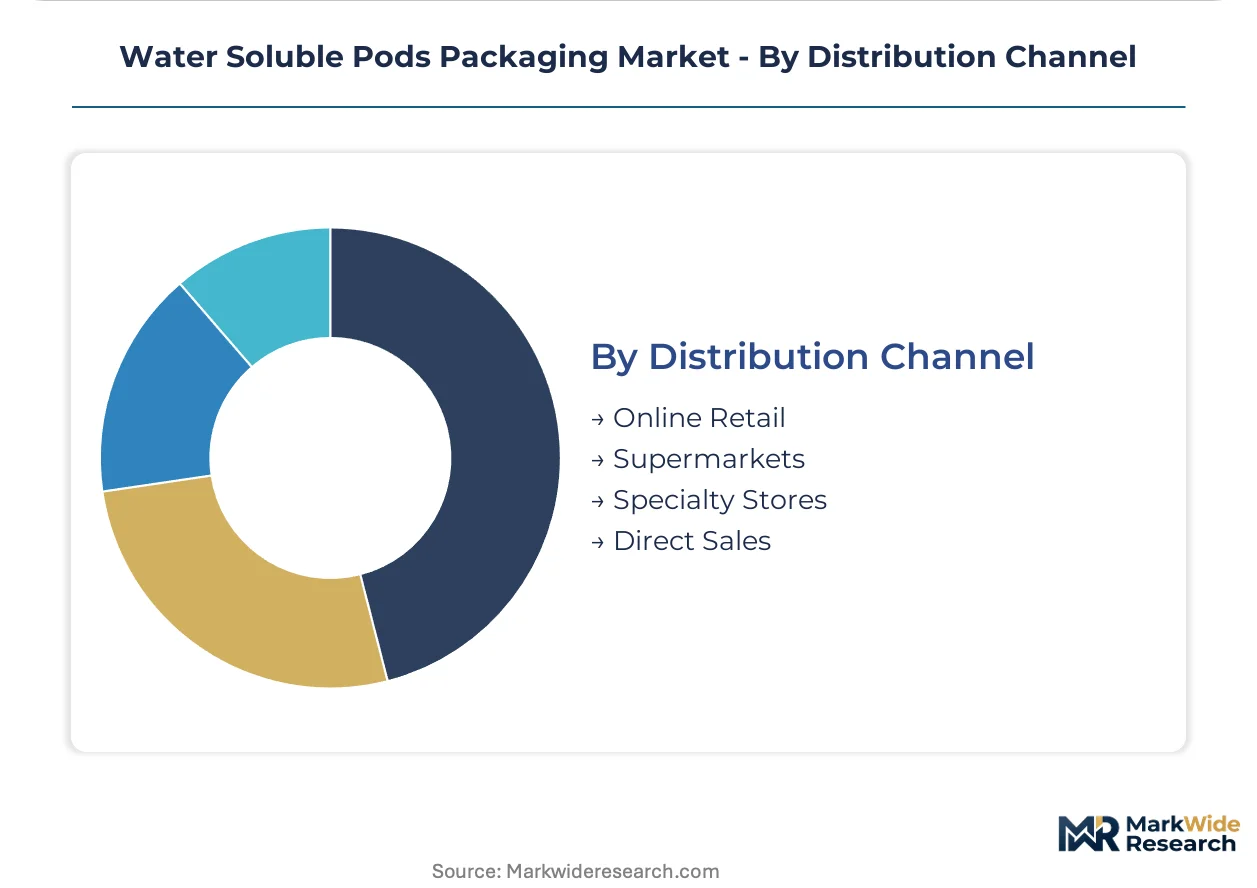
- Online Retail:Automated replenishment platforms for concentrated pod refills concentrate margin in North American home care, shortening reorder cycles and capturing subscription revenue.
- Supermarkets:Mass retail retains volume dominance for detergent pods in Europe and North America, though shelf-space competition pressures brand marketing spend.
- Direct Sales:Agricultural chemical manufacturers in Brazil and Australia pilot modular pod architectures through field representative networks, enabling technical consultation on multi-phase active delivery.
- Specialty Stores:Premium and eco-positioned pod formats reach sustainability-focused consumers in urban centers, though volumes remain fractional against mainstream channels.
Supermarkets leads on scale; Online Retail leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production footprints as manufacturers relocate extrusion capacity to jurisdictions with favorable biodegradation certification timelines and polymer classification regimes.
Germany
Detergent formulators in North Rhine-Westphalia drive procurement volumes for single-use pod substrates under REACH substance restrictions. The EU Packaging and Packaging Waste Regulation imposes extended producer responsibility obligations that favor domestic flexible packaging converters. Industrial clustering around Düsseldorf and Cologne shortens development cycles for new film specifications.
United States
Home care brands convert bottle formats to pre-dosed pods as California tightens state-level packaging waste rules. The EPA regulates agricultural chemical pods under FIFRA, requiring child-resistant features and dissolution validation. Midwest flexible packaging corridors around Chicago and Minneapolis-St. Paul concentrate contract manufacturing for humidity-sensitive formulations.
India
Agricultural pod demand expands in water-stressed regions of Maharashtra and Gujarat where farmers seek dosing precision. BIS certification mandates and the PLI scheme for advanced packaging materials accelerate domestic film extrusion capacity. Chemical formulators in Mumbai-Pune industrial belts pilot starch-PVOH blends for crop protection delivery.
Japan
Hospital procurement consortia specify validated dissolution profiles for pharmaceutical unit-dose applications. METI guidelines on sustainable materials influence resin selection for oxygen-sensitive agricultural actives. Kansai region converters around Osaka supply cleanroom-extruded substrates to long-term care facilities.
Brazil
Agricultural chemical manufacturers pilot modular pod architectures with segmented compartments for incompatible precursors. ANVISA reviews food-contact applications for flavor delivery formats. São Paulo state field representative networks enable technical consultation on multi-phase active delivery systems.
Water Soluble Pods Packaging Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with detergent applications concentrating volume among large flexible packaging converters while pharmaceutical and agricultural niches sustain smaller validated-substrate producers. The vendor base organizes into three tiers: resin suppliers controlling barrier polymer chemistry, film extruders with coextrusion expertise, and brand-owning formulators specifying dissolution performance. Consolidation pressures mount as hospital procurement consortia and detergent manufacturers reduce supplier lists. Dominant competitive moves include backward integration into resin compounding and geographic expansion to capture PLI scheme incentives in South Asia.
Within the resin-supplier tier, KURARAY Co., Ltd. and Mitsubishi Chemical Corporation anchor high-barrier polymer supply for humidity-sensitive formulations. Among European flexible packaging specialists, Mondi Group occupies a position serving pharmaceutical-grade applications with validated cleanroom capabilities. These three exemplify how technical specialization in dissolution profile engineering creates defensive positioning against commodity film competitors.
| Leading Market Players |
|---|
| Mondi Group |
| KURARAY Co., Ltd. |
| Mitsubishi Chemical Corporation |
| Cortec Corporation |
| Aquapak Polymers Ltd. |
| SEKISUI CHEMICAL CO., LTD. |
| MonoSol, LLC |
| Constantia Flexibles |
| Aicello Corporation |
| Others |
Value Chain & Pricing Dynamics
Backward integration into resin compounding anchors supply security and pricing leverage for flexible packaging converters serving detergent and pharmaceutical pod markets. KURARAY Co., Ltd. and Mitsubishi Chemical Corporation control high-barrier EVOH and PVOH grades, forcing converters to negotiate long-term offtake terms or invest in captive polymer blending capacity to defend margin pools.
Pricing Analysis
Retailer markup compression in European supermarkets is intensifying cost pass-through demands on film converters. Three-tier pricing structure across pharmaceutical-grade, food-contact, and industrial detergent tiers reflects certification burden and dissolution validation timelines. Pricing pressure stems from starch-PVOH blend development costs as brands pre-empt microplastic reclassification. Agricultural chemical manufacturers exhibit highest price sensitivity due to commodity crop margin constraints; pharmaceutical unit-dose buyers prioritize dissolution reproducibility over unit cost.
Supply Chain Analysis
Dual-sourcing mandates from hospital procurement consortia and detergent manufacturers require film extruders to qualify secondary resin suppliers for PVOH and starch feedstocks. Supply concentrates in Germany, Japan, and India, with North Rhine-Westphalia clustering around detergent formulators and Mumbai-Pune belts serving agricultural markets. Raw material dependencies center on ethylene vinyl alcohol copolymers, polyvinyl alcohol resins, and modified starch derivatives. Single-source vulnerability persists for pharmaceutical-grade cleanroom extrusion capacity. Distribution runs through direct-to-subscription platforms and mass retail channels with diverging working capital intensity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Water soluble pods packaging functions as a stable compounder anchored by regulatory displacement of conventional plastics across home care and agricultural applications. Format conversion tailwinds from EU and California packaging waste rules sustain volume expansion without cyclical volatility.
For Market Incumbents: Anticipate forced material substitution cycles as California and EU member states finalize PVA microplastic classifications. Defend position by accelerating starch-PVOH blend validation ahead of compliance thresholds and securing pharmaceutical-grade cleanroom certifications to capture hospital procurement consolidation. Capacity addition in India under PLI scheme incentives captures South Asian agricultural demand growth. For New Entrants and Emerging Players: REACH substance restriction expansions in Europe open a window for biodegradable film specialists with validated marine biodegradation kinetics. Target agricultural pod applications in water-stressed regions of Maharashtra and Gujarat where dosing precision commands premium positioning. Pursue direct-to-subscription channel partnerships with North American home care brands to bypass retail shelf-space barriers. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap flexible packaging converters because hospital GPO supplier list consolidation is concentrating purchasing power around validated-substrate producers. Long-term viability rests on exposure to pharmaceutical unit-dose and agricultural active delivery where dissolution profile engineering creates defensive moats. Monitor EFSA soil accumulation review outcomes as inflection indicator for agricultural pod material acceptance.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive PVOH blending capacity insulates converters from KURARAY supply concentration. |
| Pharmaceutical-Grade Cleanroom Certification | FDA dissolution validation opens hospital procurement consortia in Germany and Japan. |
| Starch-PVOH Blend Validation | Pre-emptive REACH compliance secures EU market access against microplastic reclassification. |
| Direct-to-Subscription Channel Launch | Automated replenishment platforms capture recurring revenue in North American home care. |
| India PLI Scheme Capacity Buildout | Domestic film extrusion serves Maharashtra agricultural and South Asian detergent demand. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary interviews engaged resin supplier technical directors, flexible packaging converter plant managers, detergent brand procurement leads, pharmaceutical GPO contracts managers, and agricultural chemical formulators. Secondary validation drew from REACH substance restriction filings, EPA FIFRA registration databases, EU Packaging and Packaging Waste Regulation impact assessments, and BIS certification records. Bottom-up pod volume estimates triangulated against top-down market sizing from trade flow analysis.
Historical reference periods anchored the forecast window to pre-COVID baseline demand and post-regulatory implementation trajectories. Segmentation modeling spanned product architecture, material chemistry, end-use application, and distribution channel across the projection horizon. CAGRs derived from regression analysis of format conversion rates and regulatory compliance timelines. Industry-specific inputs included dissolution kinetic validation timelines and extended producer responsibility fee structures.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt microplastic reclassification or EFSA soil accumulation adverse findings. Deviation in California state-level PVA polymer classification would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Mylar Market
Packaging Materials
Construction Films Market
Packaging Materials
Strip Pack Market
Packaging Materials
Global Thin Wall Packaging Market
Packaging Materials
Thailand Packaging Market
Packaging Materials
Tubes and Cores Market
Packaging Materials
Single-Use Packaging Market
Packaging Materials
Honeycomb Packaging Market
Packaging Materials
Trifold Packaging Market
Packaging Materials
Brightness Enhancement Films Market
Packaging Materials
Microwave Packaging Market
Packaging Materials
Germany Packaging Market
Packaging Materials
Greaseproof Sheets Market
Packaging Materials
Global Anti-Static Films Market
Packaging Materials
Plastic Strapping Materials Market
Packaging Materials
Disposable Egg Trays Market