
 Hygiene Packaging Market | 2026-2036
Hygiene Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Hygiene Packaging Market Intelligence
Multi-source procurement for hygiene-grade substrates is realigning how converters secure resin and fiber supply. Amcor Plc leverages its global film extrusion network to lock in polymer access across multiple continents. Kimberly-Clark Corporation anchors North American demand through captive tissue and nonwoven integration. Essity Aktiebolag competes on sustainability credentials with its expanding line of renewable packaging formats.
Hygiene packaging denotes engineered enclosures designed to preserve sterility, moisture control, and user safety for personal care and sanitary products, typically incorporating multi-layer coextruded films or coated papers with specified bacterial barrier performance per ISO 11607 guidelines. Its primary commercial purpose centers on preventing contamination during distribution while enabling single-hand dispensing in clinical and consumer settings. Wrapped products and pouches command the largest share of unit volume due to their compatibility with high-speed flow-wrap lines, while biodegradable materials represent the fastest-expanding material class as brand owners face ESG compliance deadlines. Plastic still dominates absolute tonnage but faces margin compression from regulatory fees and recycled content mandates.
The FDA enforces biocompatibility and sterility assurance levels for healthcare-bound packaging under 21 CFR requirements, while ECHA's REACH restrictions on phthalates and PFAS chemicals force European converters to reformulate sealant layers. ISO 13485 quality management standards further shape supplier qualification timelines for medical hygiene applications. Stakeholders must monitor evolving state-level extended producer responsibility laws and decide whether to invest in regional recycling infrastructure or pivot toward mono-material designs that simplify end-of-stream sorting.
Market Dynamics
EU Green Deal mandates on single-use plastics are forcing converters to reengineer multi-layer barrier films, compressing margins while opening substrate substitution pathways.
Growth Catalysts
- REACH phthalate restrictions:ECHA's tightening chemical limits accelerate reformulation toward bio-based sealants, creating first-mover advantages for compliant converters in Germany and the Netherlands.
- Healthcare infection control:Sterility assurance protocols in surgical and wound-care settings pull demand for ISO 11607-certified pouches with validated bacterial barrier performance.
- Fiber substrate migration:Coated papers and molded fiber formats gain traction as brand owners pre-position for extended producer responsibility compliance deadlines.
Market Restraints
- Resin supply concentration:Polypropylene and polyethylene feedstock dependence on Gulf Coast petrochemical clusters exposes converters to hurricane-disruption risk and freight cost volatility.
- Multi-layer incompatibility:Current mechanical recycling infrastructure cannot sort coextruded films with incompatible polymer layers, limiting circular economy claims.
- PFAS barrier alternatives:Fluorochemical-free grease and moisture barriers remain cost-prohibitive at scale, constraining food-contact hygiene packaging expansion.
Strategic Opportunities
- Mono-material designs:Single-polymer structures compatible with existing polyethylene film recycling streams unlock access to retailer sustainability scorecards and preferential shelf placement.
- Home care concentrates:Refill pouch formats for surface disinfectants and personal cleansers reduce shipping volumes while requiring specialized oxygen and moisture barrier engineering.
- Digital watermarking integration:Invisible markers enabling automated sortation at materials recovery facilities create differentiation for converters serving EPR-regulated markets.
Industry Challenges
- ISO 13485 certification timelines:Medical-grade quality management system audits require 12-18 month implementation cycles, delaying supplier qualification for healthcare contracts.
- Barrier-film technical talent:Shortage of polymer scientists with coextrusion die design expertise constrains R&D throughput at mid-size converters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hygiene Packaging Market |
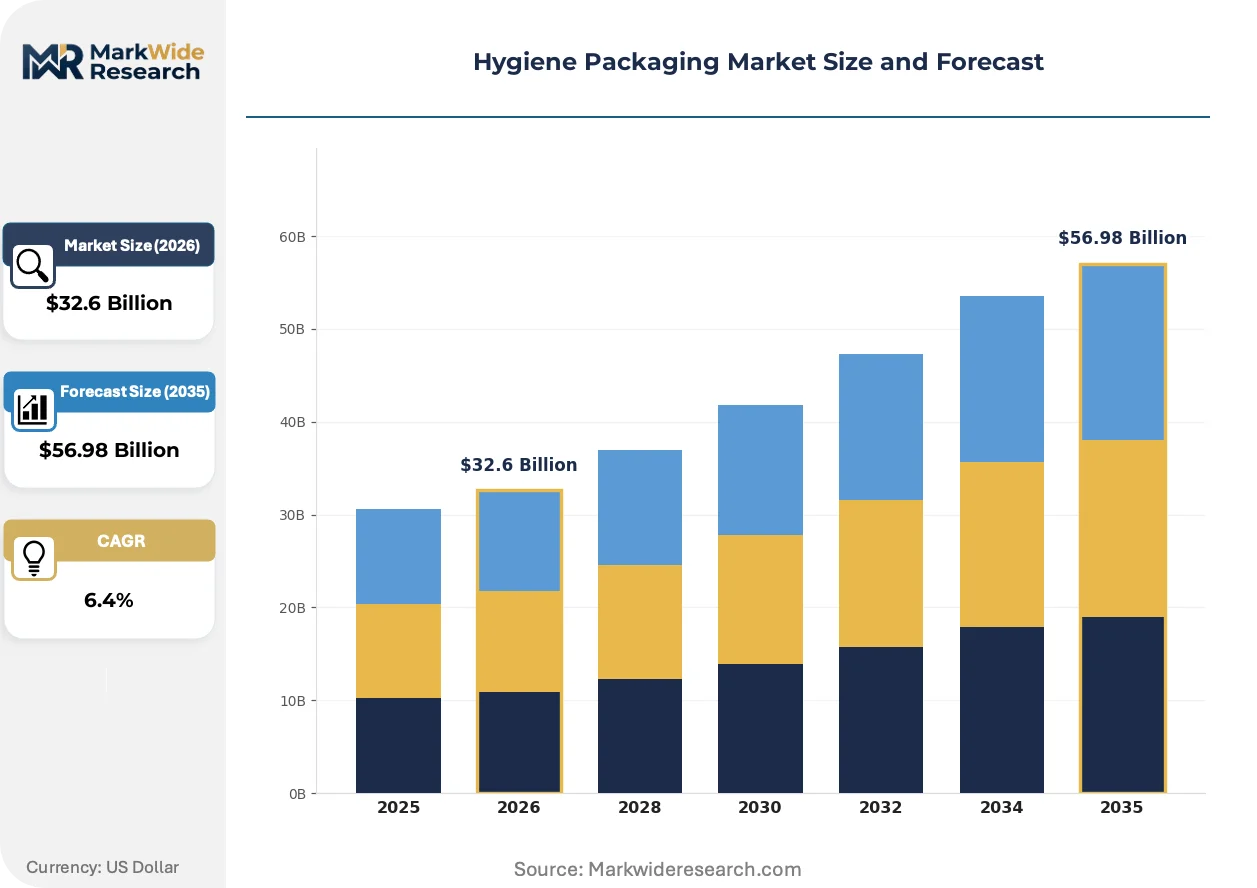
| Market Size in 2026 | $32.6 Billion |
| Market Size in 2035 | $56.98 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wrapped Products, Dispensers, Bags, Containers Material: Plastic, Paper, Aluminum, Biodegradable End User: Healthcare, Retail, Food & Beverage, Hospitality Packaging Type: Shrink Film, Blister Packs, Cartons, Pouches |
| Companies Covered | Amcor Plc, Berry Global, Kimberly-Clark Corporation, WestRock, Essity Aktiebolag, Georgia-Pacific LLC, Mondi Group, Kruger Products, Procter & Gamble Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hygiene Packaging Market Strategic Shifts & Innovations
Active and intelligent packaging functionalities are migrating from premium pharmaceuticals into mass-market hygiene products, driven by consumer safety expectations and supply chain transparency mandates.
Water-based barrier coatings derived from polysaccharides and plant proteins are overtaking conventional polyethylene extrusion layers in diaper and feminine hygiene wrap applications. Procter & Gamble and Essity have accelerated qualification timelines for these substrates in European manufacturing lines. The shift is overtaking legacy film-laminate structures by enabling home-compostable claims without sacrificing moisture vapor transmission rates.
EU Green Deal packaging and packaging waste regulations now mandate recycled content minimums and design-for-recycling criteria across all single-use formats. Converters must submit technical documentation proving compatibility with mainstream recycling processes by 2030. Medical hygiene pouches face the steepest compliance curve due to sterility validation requirements that complicate material substitutions.
Hospital procurement departments now require Environmental Product Declarations and carbon footprint disclosures as mandatory bid evaluation criteria, displacing pure cost-per-unit purchasing. Group purchasing organizations in Germany and France have integrated lifecycle assessment scoring into tender templates. This behavioral pivot pressures converters to invest in third-party verified sustainability data infrastructure or risk exclusion from multi-year supply agreements.
Hygiene Packaging Market Segmentation
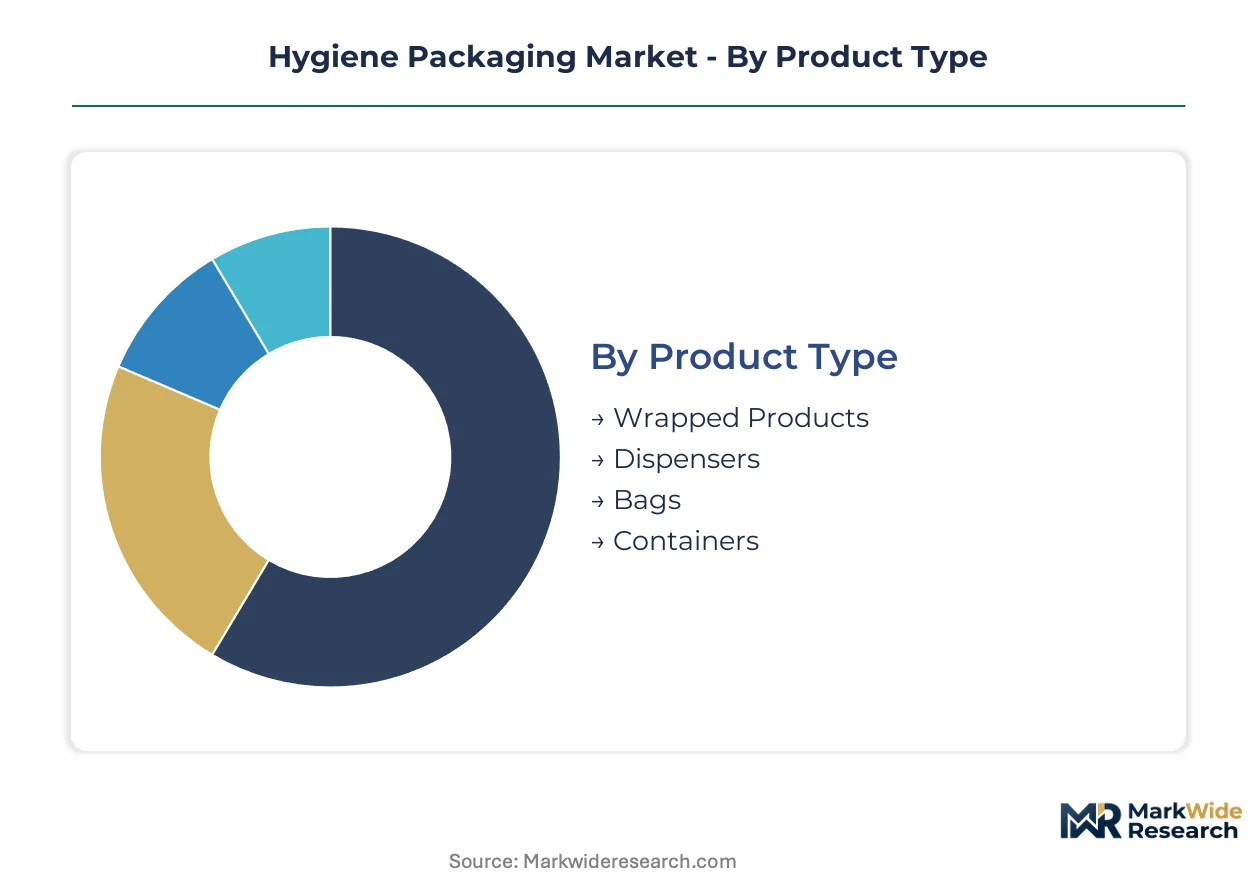
Hygiene packaging segmentation reveals how substrate choices and format engineering align with diverging sterility requirements across end-use environments. Supply concentration in film extrusion and fiber coating capacities shapes which segments converters prioritize for capacity expansion.
Product Type:
Wrapped products concentrate supply among high-speed flow-wrap converters serving consumer hygiene brands, while dispenser formats demand precision molding partnerships with limited qualified suppliers.
- Wrapped Products:Multi-layer coextruded films or coated papers configured for single-hand dispensing in high-throughput manufacturing lines. Hospital procurement in Germany and the Netherlands favors these formats for surgical drape and gown packaging due to validated bacterial barrier performance under ISO 11607.
- Dispensers:Rigid or semi-rigid enclosures integrating mechanical dispensing mechanisms, typically injection-molded from polypropylene with living-hinge designs. Supply concentrates among North American and German converters with captive tooling capabilities, as healthcare facilities mandate tamper-evident activation features.
- Bags:Gusseted or flat configurations for bulk hygiene product containment, ranging from polyethylene retail carry bags to sterilizable Tyvek-lined medical pouches.
- Containers:Rigid tubs and canisters for wet wipes and pre-moistened towelettes, requiring oxygen and moisture barrier engineering.
Today's leader: Wrapped Products. Tomorrow's challenger: Dispensers.
Material:
Cost tier stratification separates commodity resin converters from specialty substrate suppliers investing in bio-based barrier certification.
- Plastic:Polyethylene and polypropylene films dominating absolute tonnage through multi-layer coextrusion, though facing margin compression from EU plastic fees and recycled content mandates. Gulf Coast petrochemical clusters supply the bulk of feedstock, exposing converters to hurricane-disruption risk.
- Biodegradable:Polysaccharide and plant-protein coatings gaining fastest share expansion as Procter & Gamble and Essity accelerate qualification timelines for home-compostable diaper and feminine hygiene wraps in European manufacturing lines.
- Paper:Coated kraft and grease-resistant grades for secondary packaging and retail-ready displays, reformulating to eliminate PFAS barriers under ECHA restrictions.
- Aluminum:Foil laminates for absolute moisture and light barrier requirements in pharmaceutical-adjacent hygiene applications.
Plastic retains volume dominance. Biodegradable climbs the fastest.
End User:
Application severity dictates barrier specification tiers, with healthcare demanding validated sterility assurance and retail prioritizing shelf impact and cost efficiency.
- Healthcare:Surgical and wound-care settings requiring ISO 11607-certified pouches with documented bacterial barrier performance, plus ISO 13485 quality management system compliance for supplier qualification.
- Retail:Mass-market personal care and sanitary products where flow-wrap speed and printability drive substrate selection, with ESG scorecards now mandatory for shelf placement at major European retailers.
- Food & Beverage:Hygiene-adjacent packaging for surface disinfectants and food-contact sanitizers, constrained by fluorochemical-free barrier cost premiums.
- Hospitality:Amenities and institutional supplies where procurement prioritizes unit cost over barrier sophistication.
Healthcare commands specification premiums. Retail drives volume scale.
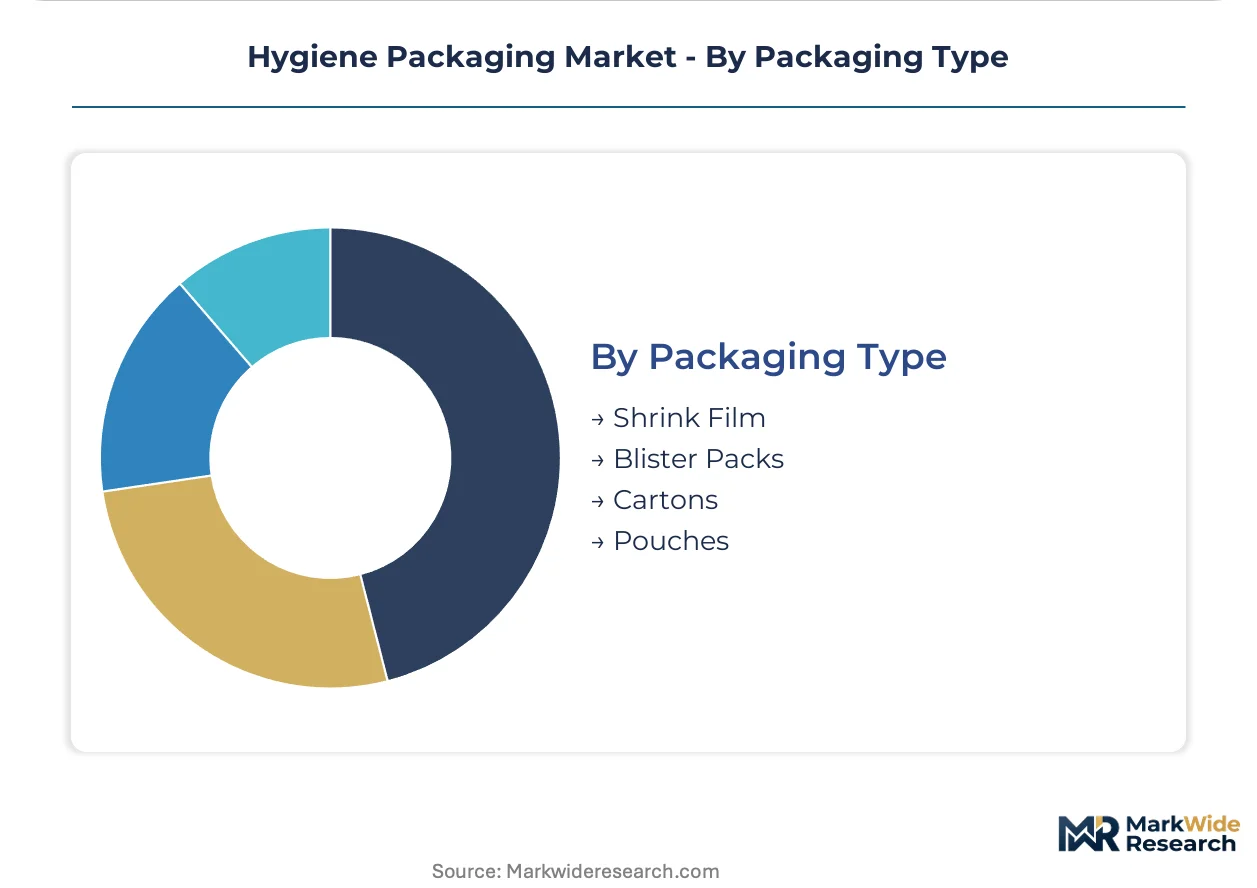
Packaging Type:
Customer type segmentation separates brand owners seeking mono-material recyclability from healthcare purchasers requiring maximum barrier certainty.
- Pouches:Flexible formats with the largest unit volume share, compatible with form-fill-seal automation and increasingly engineered for polyethylene film recycling stream compatibility to meet retailer sustainability scorecards.
- Blister Packs:Thermoformed cavities with lidding foil for unit-dose hygiene products, common in travel-size and sampling applications.
- Shrink Film:Polyolefin bundles for multi-unit retail consolidation, facing substitution pressure from fiber-based collation wraps under EU Green Deal mandates.
- Cartons:Paperboard secondary packaging for premium positioning and retail-ready shelf display, integrating digital watermarking for automated sortation at materials recovery facilities.
Pouches dominate throughput. Cartons gain from EPR compliance positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping converter location decisions as the cost-of-compliance gap between jurisdictions widens. Producers are migrating toward jurisdictions with clearer extended producer responsibility frameworks and established fiber-coating industrial bases.
Germany
Healthcare procurement clusters in North Rhine-Westphalia and Baden-Württemberg drive specification-grade pouch demand from surgical supply manufacturers. ECHA's REACH phthalate restrictions force sealant-layer reformulation, creating first-mover advantages for compliant converters. The Düsseldorf-Cologne corridor concentrates advanced barrier film extrusion capacity serving hospital group purchasing organizations.
United States
FDA 21 CFR biocompatibility requirements for healthcare-bound packaging sustain demand for ISO 13485-certified suppliers across the Midwest and Southeast tissue manufacturing belts. Gulf Coast petrochemical clusters supply polyethylene and polypropylene feedstock, exposing converters to hurricane-disruption risk. Wisconsin and North Carolina host captive tissue-to-packaging integration operations for major consumer hygiene brands.
China
Dual carbon goals and provincial plastic restriction mandates in Zhejiang and Guangdong accelerate substrate substitution toward coated paper formats. The Yangtze River Delta concentrates flow-wrap converter capacity serving domestic diaper and feminine hygiene manufacturers. NMPA medical device packaging regulations are tightening sterility validation requirements for export-oriented producers.
Netherlands
Rotterdam-Antwerp petrochemical logistics hubs enable just-in-time resin access for multi-layer film converters serving Benelux retail markets. EU Green Deal packaging waste regulations mandate recycled content minimums that outpace mechanical recycling infrastructure availability. Eindhoven's materials science cluster supports water-based barrier coating development for home-compostable hygiene wraps.
India
BIS packaging standards for sanitary products are converging with global ISO 11607 guidelines, opening import substitution opportunities for domestic converters. Maharashtra and Gujarat host expanding blown film extrusion capacity targeting Middle East export markets. FSSAI food-contact regulations create compliance complexity for surface disinfectant packaging producers.
Hygiene Packaging Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue fiber-based substrate certification and mono-material recyclability positioning. The market structure reflects moderate consolidation with distinct capability tiers separating global film extruders from regional paperboard converters. Three archetypes dominate: integrated hygiene brand owners with captive packaging operations, independent converters with multi-continent extrusion networks, and specialty substrate innovators focused on bio-based barrier qualification. Capacity expansion and strategic partnerships represent the dominant competitive moves as converters secure resin access and recycling stream compatibility.
Within the integrated brand-owner tier, Kimberly-Clark Corporation and Essity Aktiebolag anchor North American and European demand respectively through captive tissue and nonwoven integration. Amcor Plc exemplifies the independent converter archetype with global film extrusion network positioning. These three entities represent divergent strategic postures: vertical control over upstream fiber supply versus multi-source polymer procurement across continental production nodes.
| Leading Market Players |
|---|
| Amcor Plc |
| Berry Global |
| Kimberly-Clark Corporation |
| WestRock |
| Essity Aktiebolag |
| Georgia-Pacific LLC |
| Mondi Group |
| Kruger Products |
| Procter & Gamble Company |
| Others |
Cost & Logistics Intelligence
Water-based barrier coating adoption in European diaper and feminine hygiene manufacturing simultaneously compresses per-unit material costs and redraws supplier maps toward fiber-coating specialists in Germany and the Netherlands. This substrate transition weakens traditional multi-layer film extruders while elevating converters with polysaccharide formulation expertise.
Pricing Analysis
Distributor margins on hygiene-grade substrates typically absorb 12-18 points before retail markup, though direct-to-OEM contracts for healthcare pouches bypass this layer entirely. Three-tier pricing structure across premium, standard, and economy levels separates ISO 13485-certified medical pouches from retail flow-wrap films and commodity carry bags. Price differentiation rests on sterility validation documentation and ECHA REACH compliance certification. Cost compression in standard-tier retail films is intensifying because EU plastic fees and recycled content mandates squeeze converter margins. Hospital procurement departments show least price sensitivity due to infection control liability exposure, while hospitality amenity buyers drive hardest bargain negotiations.
Supply Chain Analysis
Polymer scientist shortages in Wisconsin and North Carolina constrain coextrusion die design throughput at mid-size converters serving Midwest tissue manufacturing belts. Geographic supply concentration centers on Germany, the United States, and China for film extrusion and fiber coating capacity. Raw material dependencies draw from Gulf Coast polypropylene and polyethylene clusters, Yangtze River Delta resin processing, and Rotterdam-Antwerp petrochemical logistics hubs. Single-source vulnerability to hurricane disruption along the Gulf Coast exposes converters to feedstock interruption. Distribution runs through converter-direct relationships with Kimberly-Clark and Essity captive operations, supplemented by independent film suppliers serving regional hygiene brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hygiene packaging market functions as a geographic-arbitrage play where ECHA REACH compliance costs in Germany run substantially higher than BIS standardization expenses in India, creating margin expansion opportunities for export-oriented South Asian converters.
For Market Incumbents: Deepen backward integration into polysaccharide coating supply by acquiring fiber-treatment specialists in the Eindhoven materials cluster before Essity and Procter & Gamble lock in exclusive capacity. Add ISO 11607 validation laboratory capacity in North Rhine-Westphalia to defend against emerging mono-material recyclability specialists capturing hospital procurement scorecards. For New Entrants and Emerging Players: Mid-tier Indian sanitary product manufacturers seeking import substitution offer the most penetrable buyer archetype as BIS standards converge with ISO 11607. Target Maharashtra and Gujarat blown film extruders with technical partnership proposals rather than capital-intensive greenfield builds. Lead go-to-market through FSSAI food-contact compliance consulting to surface disinfectant packaging producers facing dual regulatory complexity. For Investors and Strategic Acquirers: Valuations sit cheapest among regional paperboard converters with water-based barrier coating pilot lines but lacking EPR compliance data infrastructure. Five-to-ten-year viability hinges on successful navigation of EU Green Deal design-for-recycling documentation requirements. Watch for hospital group purchasing organization tender template changes integrating lifecycle assessment scoring as inflection signal for sustainability data infrastructure acquisition timing.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Design Transition | Polyethylene stream compatibility unlocks retailer sustainability scorecards and preferential shelf placement at major European chains. |
| Water-Based Barrier Coating Scale-Up | Polysaccharide and plant-protein formulations enable home-compostable claims without sacrificing moisture vapor transmission rates. |
| ISO 13485 Certification Investment | Medical-grade quality management system compliance reduces 12-18 month supplier qualification delays for surgical pouch contracts. |
| Digital Watermarking Integration | Invisible markers enable automated sortation at materials recovery facilities serving EPR-regulated Benelux markets. |
| Home Care Concentrate Pouch Development | Refill formats for surface disinfectants reduce shipping volumes while requiring specialized oxygen and moisture barrier engineering. |
Research Approach
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core of this study. Primary interviews with extrusion plant managers, hygiene brand procurement leads, hospital GPO contracts managers, and fiber-coating R&D directors were cross-validated against secondary sources including ECHA REACH substance restriction updates, FDA 21 CFR biocompatibility guidance documents, EU Green Deal packaging waste regulation technical annexes, and SEC filings from listed packaging converters. Customs data on polyethylene and polypropylene resin trade flows provided additional triangulation points.
Historical trendline analysis of substrate substitution patterns and barrier film qualification timelines informed projection frameworks across the analysis window. Segmentation dimensions modeled include product type, material class, end-user severity tier, and geographic regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves incorporating healthcare infection control protocol tightening and EPR compliance deadline proximity. Forecast inputs specifically weighted EU plastic fee implementation schedules and NMPA medical device packaging regulation evolution in China.
Underlying measurement precision varies by segment; healthcare pouch volumes carry tighter precision than hospitality amenity estimates due to consolidated procurement data availability. Forecasts reflect assumptions about mechanical recycling infrastructure buildout rates and fluorochemical-free barrier cost convergence timelines. Material deviation in ECHA PFAS restriction finalization or Gulf Coast hurricane frequency warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Germany Packaging Market
Packaging Materials
Reel in Box Market
Packaging Materials
Fiber Lids Market
Packaging Materials
China Packaging Market
Packaging Materials
Metallized Rollstock Film Market
Packaging Materials
Insulated Thermal Box Liners Market
Packaging Materials
Trifold Packaging Market
Packaging Materials
Child Resistant Zipper Market
Packaging Materials
VCI Packaging Market
Packaging Materials
Tertiary Packaging Market
Packaging Materials
Asia-Pacific Airless Packaging Market
Packaging Materials
Single-Use Packaging Market
Packaging Materials
Graphene Infused Packaging Market
Packaging Materials
Cohesive Packaging Market
Packaging Materials
Packaging Straps and Buckles Market
Packaging Materials
Transit Packaging Market