
 Packaging Supplies Market | 2026-2036
Packaging Supplies Market Size, Share, and Industry Trends Forecast 2026-2036
Packaging Supplies Market Analytics
The EU Packaging and Packaging Waste Regulation is shifting procurement criteria across European supply chains, compelling converters to certify recyclability and reduce virgin material intensity. Amcor leverages its global film and fiber network to pre-empt compliance requirements in multiple jurisdictions. Smurfit Kappa anchors European corrugated supply through integrated pulp-to-box operations spanning recycled feedstock and on-demand converting.
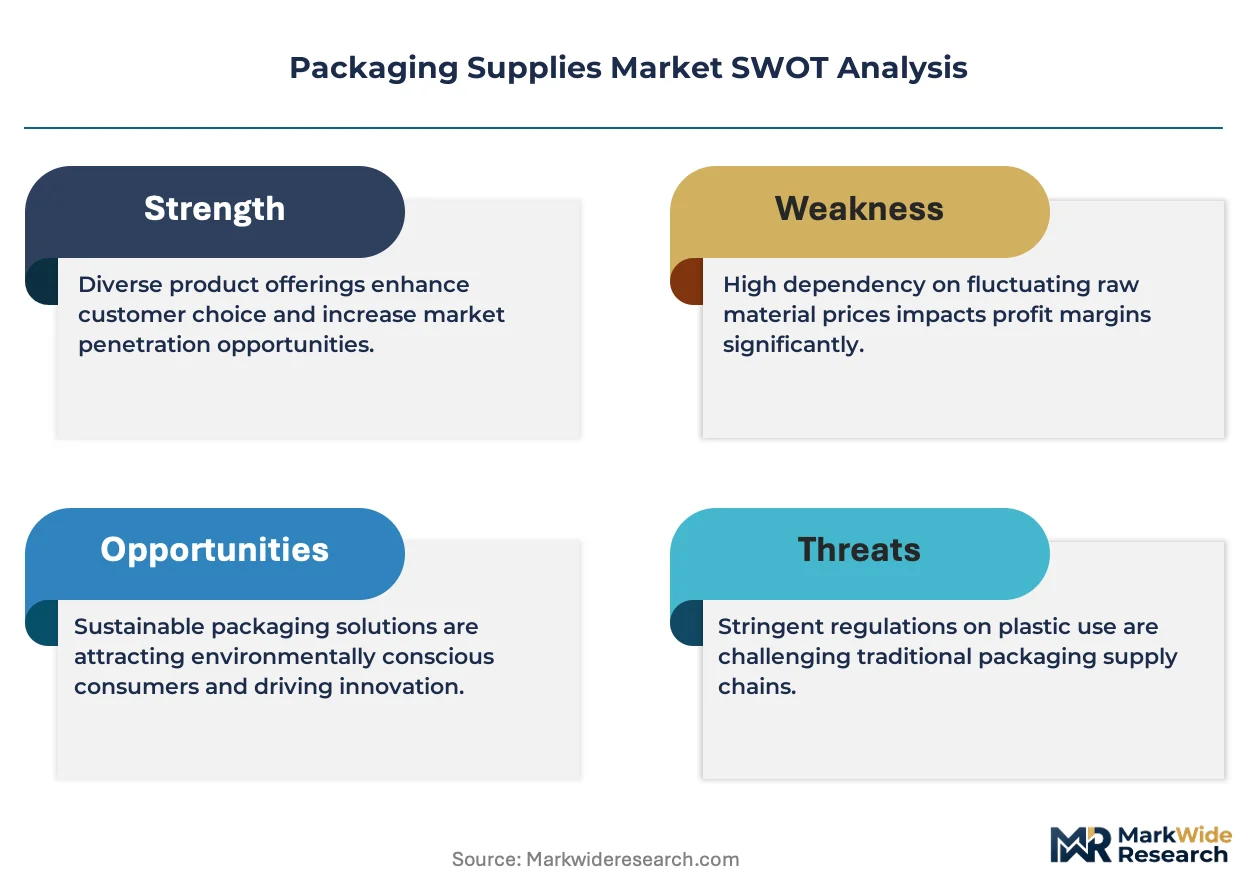
Packaging supplies encompass containers, protective materials, and unit-load platforms engineered to contain, preserve, transport, and display goods through supply chain touchpoints; specifications span burst strength, moisture vapor transmission rates, and drop-test resilience depending on end-use fragility and shelf-life requirements. The primary purpose is to reduce product damage, extend shelf stability, and enable efficient handling across automated and manual logistics systems. Rigid packaging and flexible formats each occupy distinct margin pools, with rigid formats sustaining premium positioning in pharmaceuticals and beverages while flexible wraps capture volume growth in snack foods and e-commerce void fill. Sustainable packaging types are attracting capital as brand owners face Scope 3 disclosure pressures and retailers impose private-label sustainability scorecards.
FDA food-contact regulations, EPA hazardous substance labeling requirements, and ISO 18601 packaging and environment standards collectively govern material selection, migration limits, and end-of-life claims across the United States market. These frameworks raise compliance costs for imported substrates while creating preferential access for domestic converters with certified testing laboratories and documented chain-of-custody systems. Stakeholders must monitor evolving extended producer responsibility legislation at state level and assess whether their material portfolios align with pending recyclability mandates before procurement cycles lock in multi-year supply agreements.
Market Dynamics
E-commerce fulfillment networks are compressing order-to-delivery windows, forcing corrugated and flexible packaging converters to synchronize production with real-time inventory signals rather than forecast-driven batch runs.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Tightening recyclability targets and material recovery mandates are pulling converters toward certified circular feedstock systems and documented chain-of-custody protocols.
- China domestic consumer brand expansion:Direct-to-consumer distribution scaling by homegrown retailers is upgrading protective packaging specifications for electronics, cosmetics, and fresh food verticals.
- Automated void-fill systems:On-demand air cushion and paper-based dunnage technologies are displacing pre-formed polystyrene loose fill in high-velocity fulfillment centers.
Market Restraints
- Recycled pulp cost volatility:Old corrugated containerboard supply fluctuations in North American and European collection networks are compressing margin stability for integrated box producers.
- OCC export restrictions:China's National Sword policy and subsequent waste import bans have stranded feedstock flows, forcing Southeast Asian converters to absorb redirected volume at price discounts.
- Multi-layer film recyclability limitations:Current mechanical recycling infrastructure cannot separate laminated barrier films, constraining brand owner compliance with extended producer responsibility frameworks.
Strategic Opportunities
- India organized retail penetration:Modern trade expansion in tier-2 and tier-3 cities is creating first-mover advantage for corrugated converters with BIS-certified food-contact board capacity.
- Reusable transport packaging:Pooled pallet and collapsible container systems are capturing share in automotive and beverage closed-loop supply chains.
- Digital watermarking integration:Invisible marker technologies combined with AI-powered sortation are enabling high-purity post-consumer resin streams for food-grade applications.
Industry Challenges
- Food-contact migration testing backlog:FDA and EFSA notification queues are extending certification timelines for novel bio-based barrier coatings, delaying commercial launches.
- Legacy ERP-to-MES integration:Converters with decades-old production scheduling systems face data architecture friction when connecting to customer demand-signal platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Packaging Supplies Market |
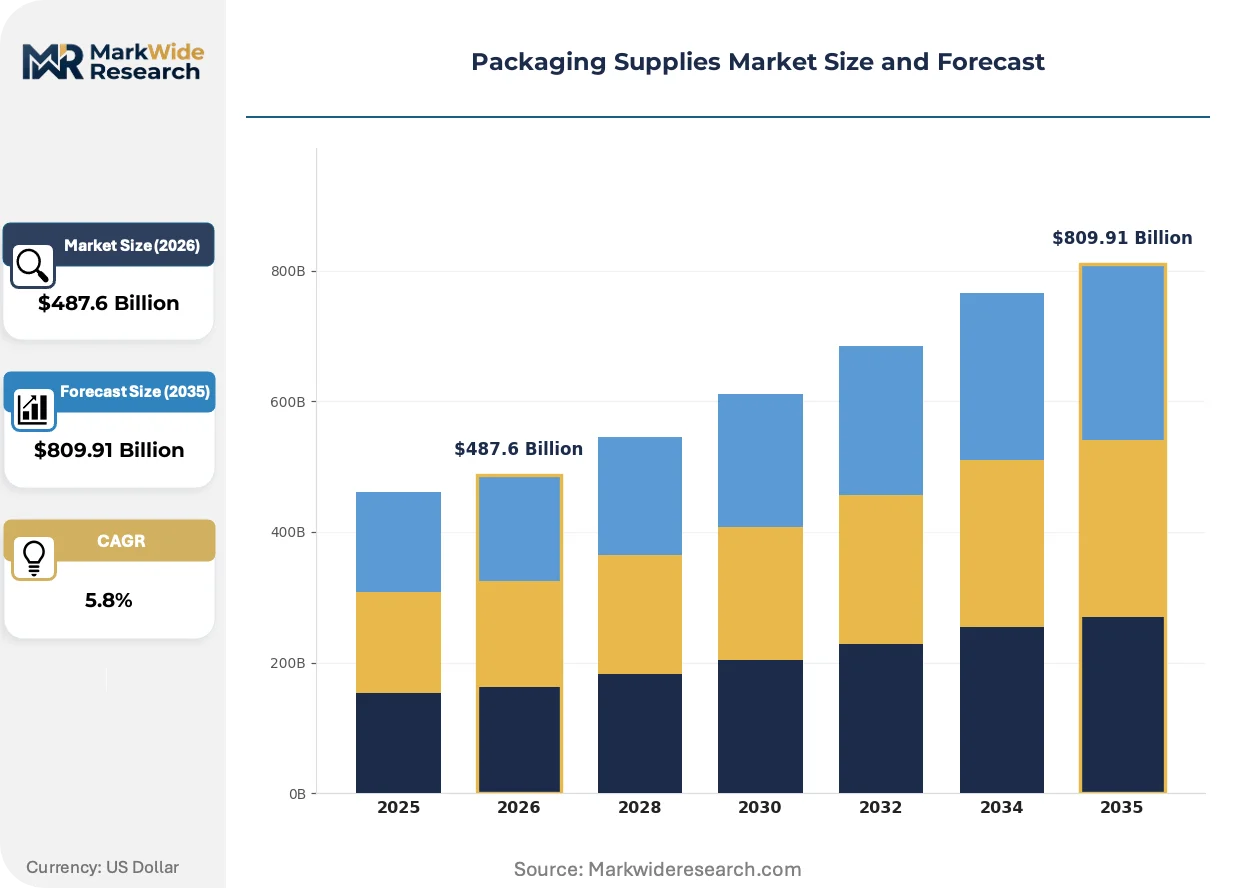
| Market Size in 2026 | $487.6 Billion |
| Market Size in 2035 | $809.91 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Boxes, Bags, Pallets, Wraps Material: Cardboard, Plastic, Foam, Paper End User: Food & Beverage, Electronics, Pharmaceuticals, Cosmetics Packaging Type: Flexible, Rigid, Composite, Sustainable |
| Companies Covered | Amcor, International Paper, WestRock, Ball Corporation, Crown Holdings, Berry Global, Smurfit Kappa, DS Smith, Mondi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Packaging Supplies Market Evolving Landscape
Material science advances and regulatory disclosure requirements are converging to redefine performance specifications and supplier qualification protocols across protective and primary packaging categories.
Mono-material barrier films engineered with advanced polyethylene and polypropylene coextrusion are rewriting compatibility with existing flexible packaging recycling streams. Food and personal care brand owners in Germany and the Netherlands are accelerating specification shifts ahead of 2025 EPR reporting deadlines. The structural consequence is compression of multi-layer laminate market share in shelf-stable snack and confectionery segments.
REACH restrictions on per- and polyfluoroalkyl substances are eliminating grease-resistant fluorochemical treatments from molded fiber foodservice applications. European pulp-molded packaging converters are pivoting toward plant-based wax and clay barrier alternatives. Quick-service restaurant chains with pan-European supply contracts are most affected, requalifying chicken and sandwich container specifications under accelerated timelines.
Direct-to-consumer brand owners are consolidating supplier panels and demanding unit-level traceability from substrate origin through final delivery. Subscription box and specialty food verticals are displacing spot-market purchasing with multi-year partnership agreements. This concentration is most visible in California and New York metro fulfillment corridors, where packaging spend is consolidating among converters with integrated design-to-delivery platforms.
Packaging Supplies Market Segmentation
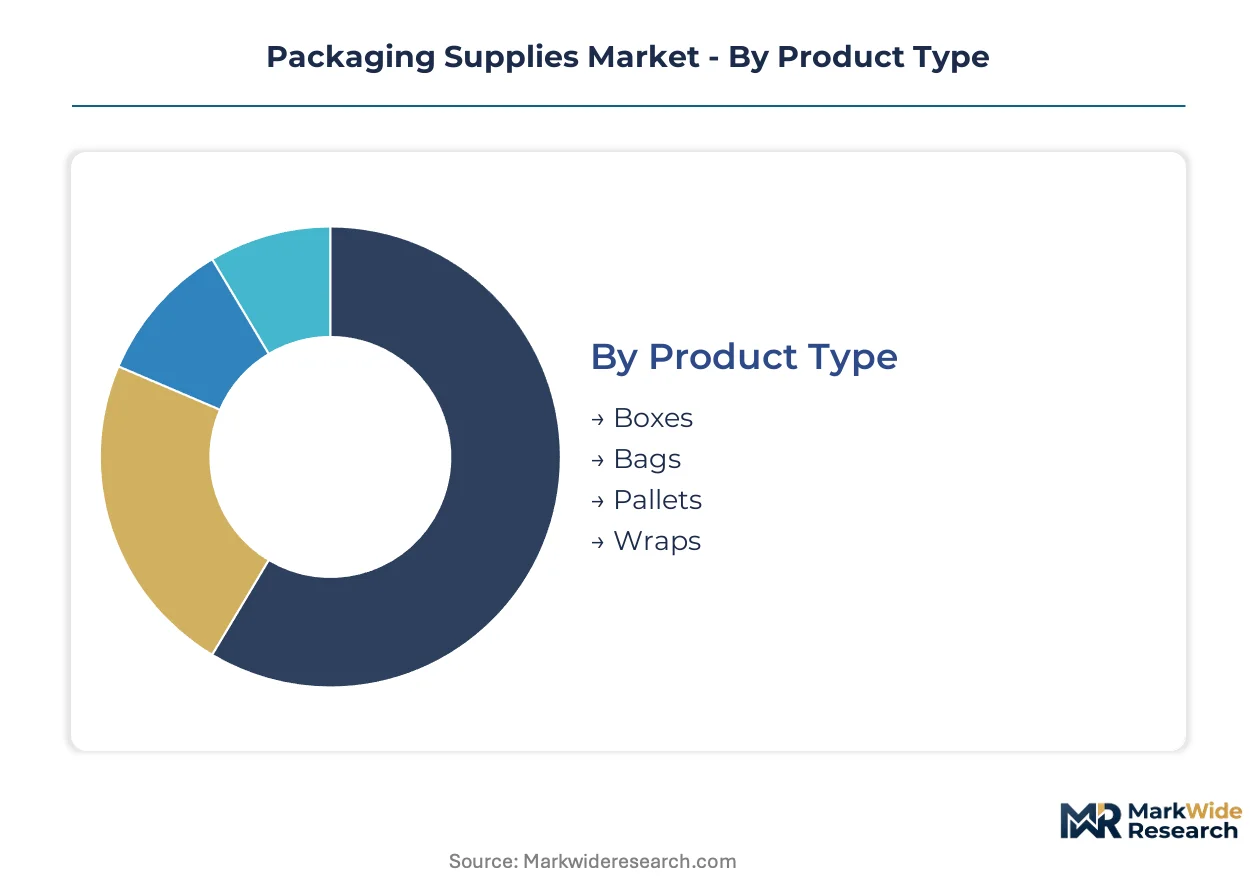
Segmentation in packaging supplies reveals divergent capital requirements and margin profiles across substrate technologies. Procurement teams use these categories to align supplier qualification with end-use compliance burdens and volume scale.
Product Type:
Boxes demand the heaviest upfront investment in corrugators and converting lines, while pallet pooling systems require fleet management infrastructure.
- Boxes:Corrugated fiberboard containers engineered to burst strength and edge crush specifications. E-commerce fulfillment networks in China and Germany are pulling demand toward double-wall and triple-wall configurations for electronics and appliance verticals. Box production absorbs the bulk of installed capacity; wraps are expanding most quickly.
- Bags:Flexible film or paper enclosures with heat-seal or adhesive closure systems. Snack food and fresh produce distribution in California and Maharashtra is concentrating demand for high-barrier laminated pouches with modified atmosphere properties.
- Pallets:Unit-load platforms in wood, plastic, or composite materials enabling forklift and automated guided vehicle handling. Automotive assembly plants in Bavaria and Tennessee are standardizing on pooled plastic pallet programs to reduce single-use wood consumption.
- Wraps:Stretch film, shrink film, and paper-based protective coverings securing palletized loads. Cold-chain logistics operators in the Netherlands and Florida are specifying vented stretch films for produce shipments requiring condensation management.
Converters with box-dominant portfolios face corrugated medium cost volatility; bag specialists capture premium pricing in barrier film niches.
Material:
Material selection governs recyclability certification pathways and food-contact compliance scope across regulatory jurisdictions.
- Cardboard:Recycled and virgin kraft linerboard combined with corrugated medium. European converters are certifying circular feedstock chains ahead of EU Packaging and Packaging Waste Regulation mandates.
- Plastic:Polyethylene, polypropylene, and PET resins in rigid and flexible formats. Mono-material barrier films are displacing multi-layer laminates in German and Dutch snack food packaging specifications.
- Foam:Expanded polystyrene and polyurethane cushioning for shock-sensitive goods. Electronics fulfillment centers in Shenzhen and Austin are piloting molded pulp alternatives under brand owner Scope 3 reduction programs.
- Paper:Kraft paper, tissue, and molded fiber for void fill and primary containment. Quick-service restaurant chains across France and Belgium are requalifying foodservice containers as REACH restrictions eliminate fluorochemical grease barriers.
Plastic commands the widest specification range; paper is climbing fastest on sustainability-driven substitution.
End User:
End-use verticals impose distinct migration limits, sterilization requirements, and shelf-life extension demands on substrate selection.
- Food & Beverage:Primary and secondary packaging with oxygen, moisture, and light barrier properties. Fresh food direct-to-consumer distribution in Shanghai and São Paulo is upgrading protective specifications for temperature-sensitive delivery windows.
- Electronics:Anti-static and moisture-vapor-transmission-controlled enclosures for semiconductors and consumer devices. Domestic brand expansion in China is driving demand for precision-fit corrugated with ESD foam inserts.
- Pharmaceuticals:Child-resistant, tamper-evident, and serialization-compliant containers. FDA and EFSA notification queues are extending certification timelines for novel bio-based barrier coatings in this segment.
- Cosmetics:Premium rigid formats with decoration and dispensing functionality. Direct-to-consumer subscription models in New York and London are consolidating supplier panels around unit-level traceability platforms.
Food and beverage consumes the highest substrate tonnage; cosmetics is gaining share fastest on premiumization and e-commerce penetration.
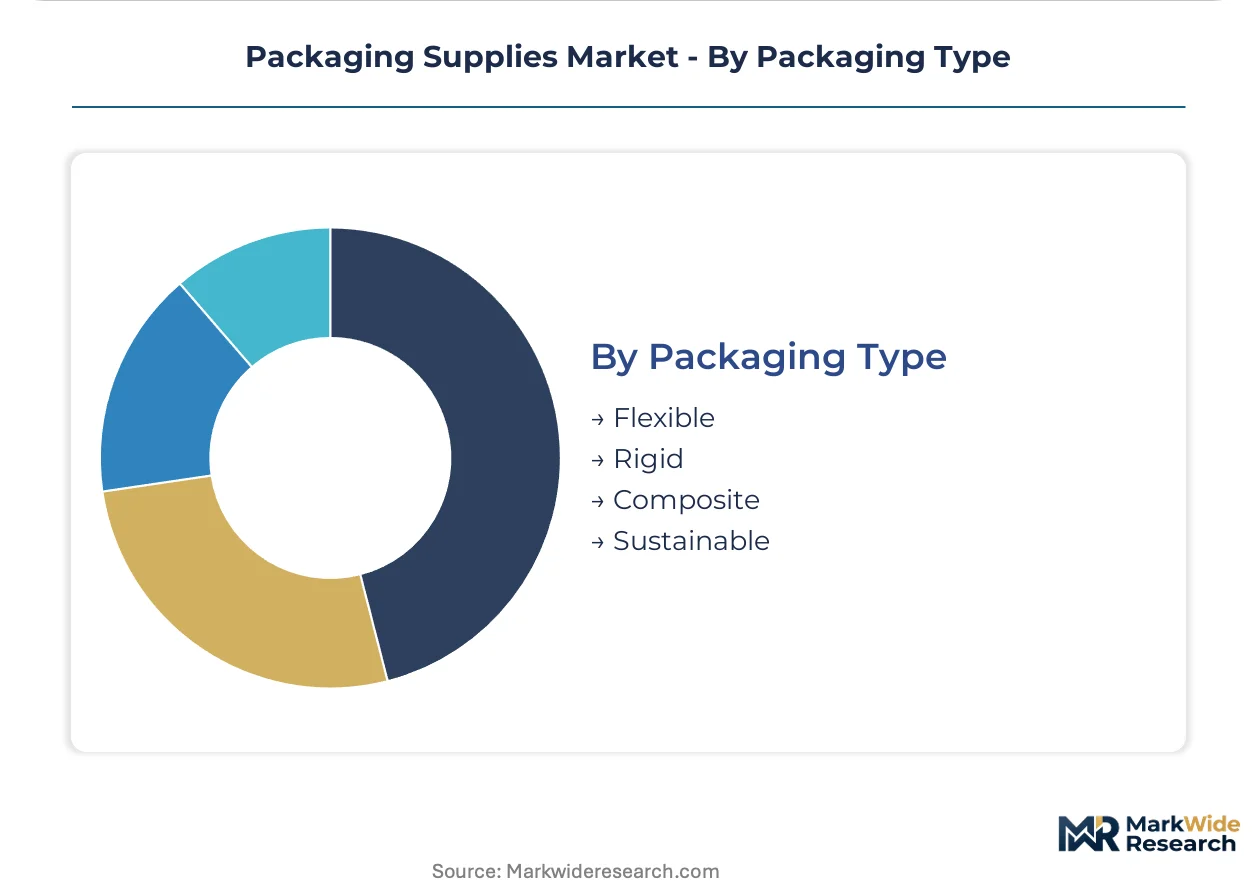
Packaging Type:
Structural format determines compatibility with existing recycling infrastructure and extended producer responsibility reporting obligations.
- Flexible:Films, pouches, and bags conforming to product geometry with minimal material weight. Mono-material polyethylene developments are rewriting compatibility with European flexible packaging recycling streams ahead of EPR deadlines.
- Rigid:Bottles, jars, and containers maintaining dimensional stability under stacking loads. Pharmaceutical and beverage applications in Switzerland and Ontario sustain premium positioning through high-barrier multilayer structures.
- Composite:Multi-material combinations such as aseptic cartons and blister packs. Current mechanical recycling infrastructure cannot separate laminated barrier films, constraining compliance with emerging EPR frameworks.
- Sustainable:Bio-based, recyclable, or reusable formats certified to ISO 18601 and comparable standards. Retailer private-label sustainability scorecards in California and the EU are accelerating capital allocation toward verified circular feedstock systems.
Flexible formats dominate shipment volume; sustainable packaging is expanding most quickly on regulatory and disclosure pressures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai's Yangtze River Delta corridor concentrates the highest packaging procurement velocity as domestic consumer brands scale direct-to-consumer distribution networks.
China
Electronics and cosmetics verticals in Shenzhen and Chengdu are upgrading protective specifications for precision-fit corrugated with anti-static inserts. SAMR's tightening food-contact material standards are accelerating converter certification investments. The Pearl River Delta hosts the densest cluster of integrated pulp-to-box operations serving cross-border e-commerce fulfillment.
Germany
Automotive assembly plants in Bavaria and Baden-Württemberg are standardizing on pooled reusable plastic pallet systems to reduce single-use wood consumption. ECHA's REACH restrictions on per- and polyfluoroalkyl substances are eliminating fluorochemical grease barriers from molded fiber foodservice applications. The Rhine-Ruhr industrial corridor anchors European flexible film converting capacity ahead of EPR reporting deadlines.
United States
Cold-chain logistics operators in Florida and California are specifying vented stretch films for produce shipments requiring condensation management. FDA food-contact migration testing backlogs are extending certification timelines for novel bio-based barrier coatings. The Austin-San Antonio corridor hosts pilot programs for molded pulp alternatives displacing expanded polystyrene in electronics fulfillment.
India
Modern trade expansion in Maharashtra and Karnataka's tier-2 and tier-3 cities is creating first-mover advantage for corrugated converters with BIS-certified food-contact board capacity. FSSAI's tightening packaging material safety standards are raising compliance barriers for imported substrates. The Delhi-NCR cluster concentrates demand for high-barrier laminated pouches in fresh produce distribution.
Netherlands
Snack food brand owners in Randstad are accelerating specification shifts toward mono-material polyethylene films ahead of 2025 EPR reporting deadlines. The EU Packaging and Packaging Waste Regulation's material recovery targets are pulling converters toward certified circular feedstock systems. Rotterdam's port infrastructure handles redirected OCC flows from Southeast Asian collection networks.
Packaging Supplies Market Competitive Landscape
Premium-margin players sit above commodity-margin players across barrier film specialization and integrated pulp-to-box operations. The vendor base organizes into three tiers: multinational converters with cross-continental film and fiber networks, regional corrugated specialists with captive recycled feedstock, and niche flexible packaging engineers serving pharmaceutical and food-contact verticals. Dominant competitive moves include backward integration into recycled pulp supply and geographic expansion through asset-light partnership models.
Within the multinational converter tier, Amcor and Berry Global exemplify global film and fiber platform strategies. Smurfit Kappa occupies a position as a European-anchored integrated corrugated specialist. These three represent distinct archetypes: film-dominant global footprint, diversified rigid and flexible portfolio, and recycled-feedstock-integrated box production respectively.
| Leading Market Players |
|---|
| Amcor |
| International Paper |
| WestRock |
| Ball Corporation |
| Crown Holdings |
| Berry Global |
| Smurfit Kappa |
| DS Smith |
| Mondi |
| Others |
Value Network & Pricing Analysis
Old corrugated containerboard feedstock costs cascade through converter pricing tiers, with integrated pulp-to-box operators in Germany and China commanding premium positioning over spot-market dependent competitors in Southeast Asia. Recycled pulp volatility compresses margin stability for non-integrated producers while EPR compliance investments separate certified circular feedstock suppliers from commodity-grade competitors.
Pricing Analysis
Throughput-linked contract structures anchor value-based pricing for high-velocity e-commerce fulfillment networks. Three-tier pricing structure across premium, standard, and economy levels separates certified food-contact board with full chain-of-custody documentation from generic recycled grades. Cost compression in standard-tier corrugated is intensifying because OCC export restrictions have stranded feedstock flows. Private-label retailers with sustainability scorecards exhibit lowest price sensitivity; spot-market buyers in fragmented converting regions face highest pressure.
Supply Chain Analysis
Direct-to-brand channels handle hyperscale demand from consolidated subscription box and specialty food verticals in California and New York metro corridors. Manufacturing concentration centers on China, Germany, and the United States for integrated corrugators and flexible film extrusion. Feedstock draws from North American and European OCC collection networks, virgin kraft pulp from Nordic and Canadian mills, and polyethylene resin from Gulf Coast petrochemical complexes. Single-source vulnerability in recycled pulp supply creates exposure when collection network disruptions occur. Distribution runs through converter-direct relationships with fulfillment network operators, bypassing traditional distribution intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The packaging supplies sector sits in a material-transition phase as mono-material barrier films displace multi-layer laminates ahead of EPR reporting deadlines. This substrate shift rewards converters with advanced coextrusion capabilities and certified recyclability documentation.
For Market Incumbents: To counter margin erosion from recycled pulp cost volatility, secure captive OCC supply through backward integration into collection network partnerships or long-term offtake agreements with municipal waste operators. Accelerate certification investments for EU Packaging and Packaging Waste Regulation compliance to maintain access to European brand owner panels.
For New Entrants and Emerging Players: E-commerce fulfillment platform partnerships offer the lowest customer acquisition cost route into the packaging supplies value chain. Target tier-2 and tier-3 Indian cities where modern trade expansion outpaces local corrugated converter capacity. Lead with BIS-certified food-contact board and rapid design-to-delivery turnaround as the primary go-to-market angle.
For Investors and Strategic Acquirers: Accelerated specification shifts toward mono-material films in German and Dutch snack food packaging is the leading indicator that barrier film technology transitions are reaching inflection. Five-to-ten year viability favors converters with integrated design platforms and documented circular feedstock chains. Monitor FDA food-contact migration testing queue lengths as a signal of novel bio-based coating commercialization timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Feedstock | Captive OCC supply insulates margin stability from collection network volatility in North America. |
| Mono-Material Barrier Film Scale-Up | Advanced polyethylene coextrusion aligns with German EPR deadlines and Dutch retailer sustainability scorecards. |
| Digital Watermarking Technology Deployment | Invisible marker integration enables AI-powered sortation for food-grade post-consumer resin streams. |
| Reusable Transport Packaging Pooled Systems | Plastic pallet programs capture automotive and beverage closed-loop supply chains in Bavaria and Tennessee. |
| Design-to-Delivery Platform Integration | Real-time demand-signal connectivity locks in multi-year partnerships with direct-to-consumer brand owners. |
Research Methodology
Independent corroboration across converter operations executives, brand owner packaging procurement directors, and recycling infrastructure operators underwrites the qualitative findings in this study. Primary fieldwork combined structured interviews with corrugated plant managers, flexible film technical R&D directors, and e-commerce fulfillment network supply chain leads. Secondary validation drew from customs and trade flow databases, SEC filings of publicly traded packaging companies, and EU regulatory notification databases. Bottom-up volume modeling and top-down macroeconomic triangulation anchored segment-level outputs.
Comparable-period anchoring linked the projection horizon to historical demand cycles in e-commerce fulfillment and food distribution verticals. The analytical framework modeled segmentation across product type, material substrate, end-use vertical, and packaging format structural categories. CAGRs were derived from trend extrapolation adjusted for regulatory inflection points and technology substitution curves. Forecast inputs included OCC collection network capacity trajectories, mono-material film adoption rates in European snack food specifications, and reusable transport packaging penetration in automotive assembly supply chains.
The model holds under stable regulatory enforcement timelines and intact cross-border feedstock flows; deviation in tariff regimes or sudden EPR mandate acceleration would shift volume trajectories. Forecasts reflect base-case assumptions regarding technology adoption curves and brand owner procurement consolidation patterns. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Global Anti-Static Films Market
Packaging Materials
PET Material Packaging Market
Packaging Materials
Battery Packaging Material Market
Packaging Materials
Refrigerator Door Seal Gaskets Market
Packaging Materials
Europe Single-Use Packaging Market
Packaging Materials
Desiccant Market
Packaging Materials
Production Page Volume Market
Packaging Materials
Global Strapping Market
Packaging Materials
Packaging Inserts Market
Packaging Materials
Cushion Case Liner Market
Packaging Materials
Polycoated Cup Stock Market
Packaging Materials
Mylar Market
Packaging Materials
3D Printed Packaging Market
Packaging Materials
Tube and Stick Packaging Market
Packaging Materials
Anti-Scratch Film Market
Packaging Materials
Foam Trays Market