
 Cohesive Packaging Market | 2026-2036
Cohesive Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Cohesive Packaging Market Outlook
Aftermarket service revenue for packaging equipment maintenance and film replenishment contracts is rewriting how suppliers capture lifetime value from cohesive packaging deployments. 3M leverages its adhesive science portfolio to dominate high-performance tape segments where technical specifications determine procurement decisions. Sealed Air anchors North American food logistics through automated wrapping systems integrated with temperature-sensitive films. Mondi competes in European kraft paper-based protective wraps, capitalizing on fiber-based alternatives to conventional plastic films.
Cohesive packaging refers to self-adhering materials that bond to themselves without additional heat, solvents, or mechanical fasteners, typically manufactured through blown film extrusion of polyethylene blends with proprietary tackifier additives to achieve controlled cling force measured in grams per inch width. The primary commercial purpose centers on unitizing pallet loads, bundling irregular products, and protecting surfaces during transit without leaving adhesive residue on wrapped items. Stretch films lead product type volumes due to their dominance in palletizing applications across food and consumer goods distribution networks, while adhesive tapes command premium positioning in electronics protection where clean removal properties justify higher unit economics. Shrink films represent the fastest-growing material format as pharmaceutical cold-chain requirements drive demand for tamper-evident, temperature-stable bundling solutions.
The EPA regulates volatile organic compound emissions from adhesive tape manufacturing facilities, pushing producers toward water-based and hot-melt coating technologies that reduce solvent discharge. REACH compliance in Europe mandates disclosure of Substances of Very High Concern in PVC-containing films, redirecting formulation investments toward polyethylene and polypropylene alternatives. ISO 9001 quality management certification shapes supplier qualification protocols for pharmaceutical and electronics end users who require documented traceability across material batches. Stakeholders must monitor evolving extended producer responsibility frameworks that will increasingly assign end-of-life collection costs to original packaging material suppliers rather than downstream users.
Market Dynamics
E-commerce fulfillment velocity is compressing packaging cycle times and forcing adhesive formulation trade-offs between immediate tack strength and clean release properties. The tension between automation compatibility and material sustainability is restructuring supplier qualification protocols across fulfillment networks.
Growth Catalysts
- REACH SVHC disclosure mandates:European chemical transparency requirements are redirecting formulation investments toward polyethylene alternatives, accelerating solvent-free adhesive adoption in protective film manufacturing.
- Pharmaceutical cold-chain expansion:Temperature-stable bundling demand from biologics distribution is driving tamper-evident shrink film deployment across vaccine and injectable supply chains.
- Germany's industrial packaging corridor:Concentrated automotive and machinery export activity is sustaining premium demand for high-cling stretch films with residue-free removal properties.
Market Restraints
- Petrochemical feedstock volatility:Polyethylene resin price swings compress margin stability for blown film extruders operating on quarterly supply contracts.
- Adhesive additive supply concentration:Proprietary tackifier chemistry remains controlled by a narrow supplier base, creating formulation lock-in and switching costs.
- Mechanical fastener substitution:Reusable pallet collars and strap-based unitizing systems compete for pallet stabilization spend in closed-loop logistics networks.
Strategic Opportunities
- Fiber-based protective wraps:Kraft paper cohesive formulations are capturing share from conventional plastic films in European electronics and luxury goods fulfillment.
- Extended producer responsibility frameworks:Emerging regulations assigning end-of-life collection costs to original material suppliers favor recyclable mono-material designs over multi-layer laminates.
- Automated wrapping system integration:Convergence of machine vision and tension-controlled film application is enabling adaptive bundling for irregular product geometries.
Industry Challenges
- Blown film extrusion technician scarcity:Specialized knowledge of die gap control and bubble stability is concentrating among aging workforces in mature manufacturing regions.
- ISO 9001 batch traceability complexity:Pharmaceutical and electronics end users demand documented material genealogy, requiring ERP system upgrades for mid-tier film converters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cohesive Packaging Market |
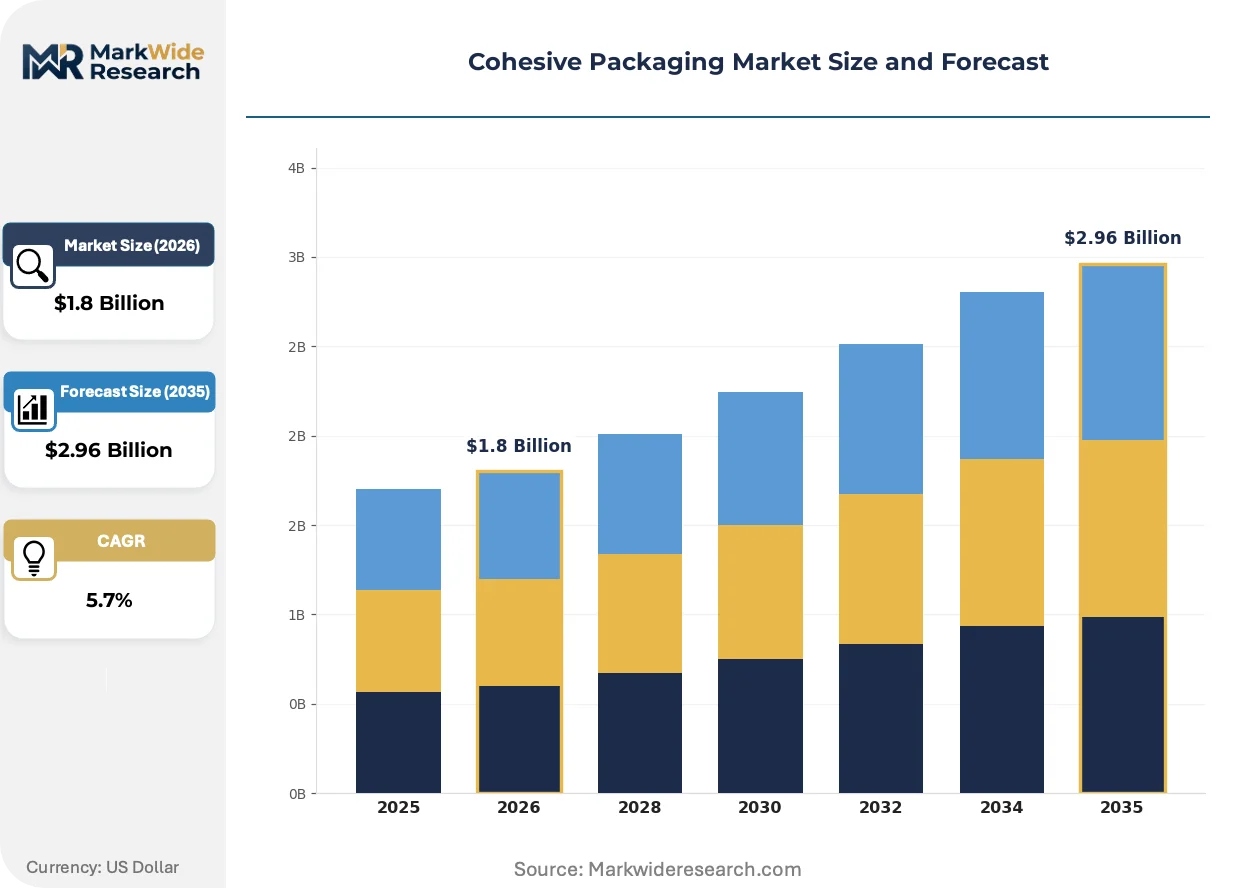
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stretch Films, Shrink Films, Adhesive Tapes, Protective Wraps End Use Industry: Food, Pharmaceuticals, Electronics, Consumer Goods Material: Polyethylene, Polypropylene, PVC, Paper Application: Palletizing, Bundling, Unitizing, Protection |
| Companies Covered | 3M, Berry Global, Sealed Air, Uflex, Sonoco, Mondi, Henkel, Avery Dennison, Amcor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cohesive Packaging Market Strategic Shifts
Material science advances are dissolving the boundary between protective and active packaging functions. Cohesive formulations now integrate sensing and barrier properties without sacrificing the self-adhering convenience that defines the category.
Biopolymer cohesive films derived from agricultural waste streams are hybridizing performance characteristics once exclusive to petroleum-based polyethylene. Food logistics operators in Nordic markets are piloting these materials for temperature-controlled produce distribution. The technology is hybridizing cost structures and forcing incumbent suppliers to reposition virgin resin offerings around consistency and scale rather than performance superiority.
Europe's F-Gas Regulation is accelerating solvent-free adhesive coating adoption by restricting fluorinated greenhouse gas use in film manufacturing processes. Industrial consequence includes capital redeployment toward hot-melt and water-based coating lines. Pharmaceutical cold-chain packaging faces the steepest compliance timeline, driving qualification of alternative formulations ahead of enforcement deadlines.
Buyer consolidation among third-party logistics providers is compressing supplier rosters and elevating technical service capabilities as a procurement criterion. Regional fulfillment networks in the Benelux are unbundling film supply from equipment maintenance contracts, forcing material suppliers to compete on per-unit economics rather than captive system lock-in. This pattern is most visible in grocery e-commerce, where seasonal volume spikes demand flexible sourcing arrangements.
Cohesive Packaging Market Segmentation
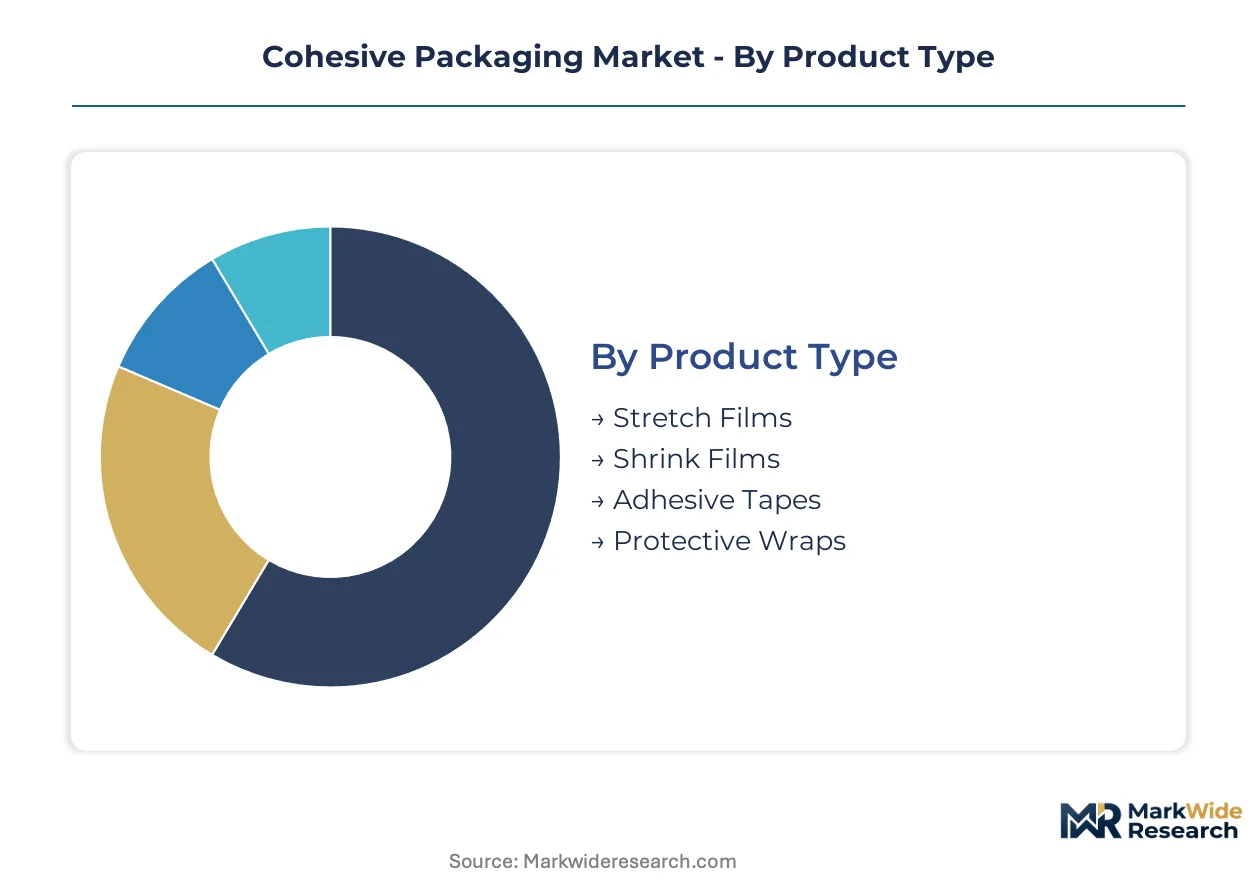
Cohesive packaging purchasing patterns diverge sharply across material formats and end-use specifications. Equipment-integrated replenishment contracts create divergent lifetime value profiles that reshape how suppliers prioritize segment development investments.
Product Type:
Aftermarket service intensity varies dramatically across product formats, with automated wrapping system dependencies creating captive revenue streams for stretch film suppliers while adhesive tapes operate on more transactional procurement cycles.
- Stretch Films:Blown polyethylene extrusions with tackifier additives achieve cling forces of 100-300 grams per inch width. Germany's automotive export corridor sustains premium demand for high-cling formulations that eliminate adhesive residue on painted surfaces.
- Adhesive Tapes:Pressure-sensitive acrylic or rubber-based coatings on oriented polypropylene or PVC backings deliver clean removal properties. Electronics manufacturers in Japan and South Korea specify low-outgassing formulations for semiconductor wafer protection during intra-facility transport.
- Shrink Films:Biaxially oriented polyolefin formulations provide tamper-evident seals with 40-70% shrink ratios upon heat application. Pharmaceutical cold-chain operators favor these for temperature-stable bundling of biologics.
- Protective Wraps:Self-adhering kraft paper or foam laminates cushion irregular geometries without mechanical fasteners. European luxury goods fulfillment networks are substituting these for conventional plastic films under extended producer responsibility pressures.
Stretch Films holds the largest share; momentum sits with Shrink Films.
End Use Industry:
Regulatory compliance burden and batch traceability requirements segment supplier qualification protocols, with pharmaceutical and electronics end users demanding ISO 9001 certification that mid-tier converters struggle to maintain.
- Food:Temperature-sensitive films with oxygen barrier properties preserve produce freshness through modified atmosphere packaging. Nordic retail chains pilot biopolymer cohesive wraps for short-loop distribution.
- Pharmaceuticals:Tamper-evident shrink films with serialization compatibility address EMA serialization mandates for secondary packaging. Cold-chain biologics distribution drives demand for formulations stable across -80°C to +25°C ranges.
- Electronics:Clean-removal adhesive tapes with anti-static properties protect sensitive components during assembly and transit. South Korean display panel manufacturers specify ultra-low adhesion variation for automated application.
- Consumer Goods:Cost-optimized stretch films dominate palletizing for non-durable household products. E-commerce fulfillment velocity compresses packaging cycle times and forces rapid equipment changeover capabilities.
Food commands the greatest volume base; Pharmaceuticals exhibits the steepest expansion trajectory.
Material:
REACH SVHC disclosure mandates and F-Gas Regulation compliance are redirecting formulation investments away from PVC and solvent-borne coatings toward polyethylene and water-based alternatives.
- Polyethylene:Linear low-density and metallocene grades dominate blown film extrusion for stretch and shrink applications. Virgin resin price volatility compresses margin stability for converters on quarterly supply contracts.
- Polypropylene:Biaxially oriented films provide stiffness and clarity for label and tape backings. Tackifier compatibility challenges limit cohesive formulation options versus polyethylene.
- PVC:Plasticized formulations offer cost advantages in adhesive tape backings but face regulatory headwinds from REACH Substances of Very High Concern listings. European converters are accelerating phase-out timelines.
- Paper:Kraft-based cohesive wraps with water-activated or self-adhering coatings capture share in fiber-focused European markets. Mondi and comparable suppliers scale production for electronics and luxury goods protection.
Polyethylene maintains dominant position; Paper is climbing the fastest.
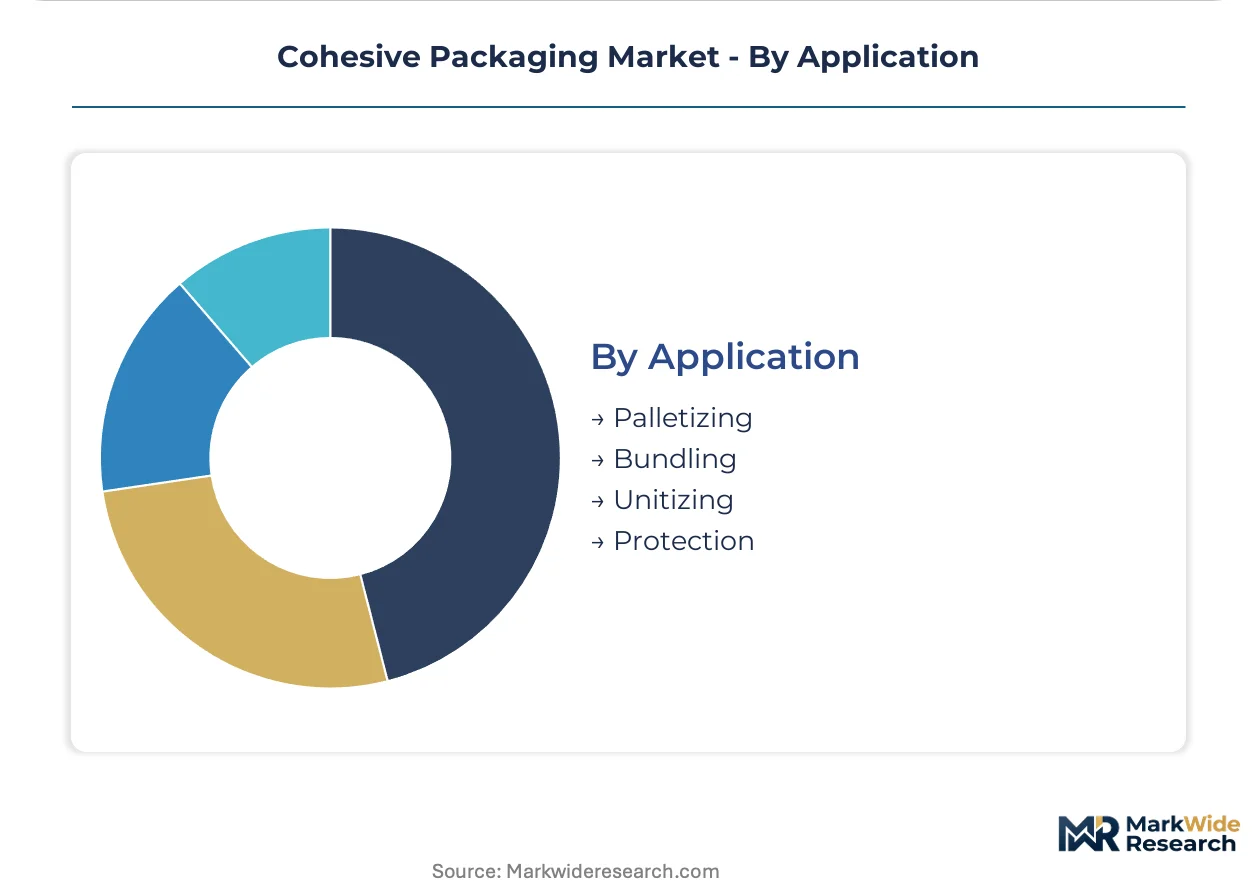
Application:
Automation compatibility requirements segment equipment-integrated versus standalone material demand, with palletizing applications driving high-volume stretch film consumption and protection applications commanding premium unit economics.
- Palletizing:Machine-grade stretch films with consistent elongation properties feed automated wrapping systems. Third-party logistics consolidation in the Benelux unbundles film supply from equipment contracts.
- Bundling:Hand-grade films and tapes unitize irregular product combinations for mixed-load shipments. Seasonal volume spikes in grocery e-commerce demand flexible sourcing arrangements.
- Unitizing:Shrink film tunnels and stretch hood systems secure pallet loads for long-haul distribution. Pharmaceutical serialization requirements elevate tamper-evidence specifications.
- Protection:Surface-contact films and wraps prevent abrasion during transit and handling. Electronics and automotive sectors specify residue-free removal for painted or coated surfaces.
Palletizing captures the greatest volume; Protection delivers the strongest margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography: Europe prioritizes fiber-based protective wraps under extended producer responsibility frameworks, while Asia-Pacific scales blown film extrusion for e-commerce palletizing, and North America concentrates investment in automated wrapping system integration.
Germany
Automotive export logistics sustain premium demand for high-cling stretch films with residue-free removal on painted surfaces. The F-Gas Regulation accelerates solvent-free adhesive coating adoption across the industrial packaging corridor. Stuttgart and Munich anchor machinery and automotive clusters where technical specifications determine procurement protocols.
United States
E-commerce fulfillment velocity drives automated wrapping system deployment with machine-grade stretch films feeding high-throughput distribution centers. EPA volatile organic compound regulations push producers toward water-based and hot-melt coating technologies. The Chicago-Milwaukee industrial corridor concentrates blown film extrusion capacity serving Midwest manufacturing and logistics networks.
China
Consumer goods manufacturing and cross-border e-commerce expansion sustain massive stretch film consumption for palletizing and unitizing applications. GB standards and dual carbon goals redirect investments toward recyclable mono-material designs. The Yangtze River Delta clusters film converters around Shanghai-Ningbo port logistics serving export manufacturing.
Japan
Electronics manufacturing demands clean-removal adhesive tapes with anti-static properties for semiconductor and display panel protection. METI industrial standards shape supplier qualification for precision component logistics. The Kansai region around Osaka concentrates specialty tape formulation for intra-facility transport applications.
India
Pharmaceutical cold-chain expansion drives temperature-stable shrink film demand for biologics distribution across vaccine and injectable supply chains. CDSCO serialization mandates elevate tamper-evidence specifications for secondary packaging. Maharashtra's Mumbai-Pune corridor anchors pharmaceutical manufacturing clusters adopting qualified cohesive packaging systems.
Cohesive Packaging Market Competitive Environment
Capability concentration sits with one tier; scale advantage sits with another. The market structures around adhesive science specialists commanding premium electronics and pharmaceutical segments, diversified materials conglomerates anchoring high-volume food and consumer goods logistics, and regional film converters competing on per-unit economics. Three archetypes dominate: technology-led formulation houses, integrated packaging systems providers, and commodity-scale extrusion operators. Competitive moves center on equipment-integrated service contracts and backward integration into resin and tackifier supply.
Within the technology-led tier, 3M and Avery Dennison occupy positions defined by adhesive science depth and specification-driven procurement relationships. Sealed Air exemplifies the integrated systems archetype, anchoring automated wrapping solutions alongside material supply. Mondi represents the fiber-based alternative vector, scaling kraft paper cohesive formulations for European markets prioritizing extended producer responsibility compliance.
| Leading Market Players |
|---|
| 3M |
| Berry Global |
| Sealed Air |
| Uflex |
| Sonoco |
| Mondi |
| Henkel |
| Avery Dennison |
| Amcor |
| Others |
Value Chain & Pricing Dynamics
The Chicago-Milwaukee industrial corridor concentrates blown film extrusion capacity serving Midwest manufacturing and logistics networks, with quarterly resin supply contracts creating pricing volatility that downstream converters pass through as surcharges on machine-grade stretch film deliveries.
Pricing Analysis
Long-term offtake agreements dominate procurement between major e-commerce fulfillment operators and stretch film suppliers, though spot purchasing persists for seasonal volume spikes in grocery logistics. Price differentiation rests on ISO 9001 certification tier and volume scale commitments, with pharmaceutical-grade formulations commanding substantial premiums over consumer goods specifications. Cost compression in standard-grade polyethylene films is intensifying because of petrochemical feedstock volatility and third-party logistics buyer consolidation. Consumer goods distributors exhibit the highest price sensitivity, while electronics and pharmaceutical end users prioritize technical specification compliance over per-unit economics.
Supply Chain Analysis
Export-control regimes on metallocene catalyst technology limit proprietary resin formulations flowing from select Gulf Coast petrochemical complexes to European converters, constraining high-cling film production capacity abroad. Supply concentrates in the United States, Germany, and China, with blown film extrusion drawing from linear low-density polyethylene, proprietary tackifier additives, and metallocene-grade resins. Single-source vulnerability around specialized adhesive chemistry creates formulation lock-in for incumbent suppliers. Distribution runs through third-party logistics provider networks that increasingly unbundle film supply from equipment maintenance contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aftermarket service revenue from packaging equipment maintenance and film replenishment contracts is expanding faster than virgin material sales, repositioning cohesive packaging as a recurring-revenue service business rather than a commodity supply relationship.
For Market Incumbents: Entrench position through backward integration into tackifier additive supply and captive resin production capacity in the US Gulf Coast petrochemical corridor. Defend against fiber-based protective wrap substitution in European markets by accelerating solvent-free adhesive qualification ahead of F-Gas Regulation enforcement deadlines. Prioritize ISO 9001 batch traceability system investments to maintain pharmaceutical and electronics supplier qualification status. For New Entrants and Emerging Players: Establish a beachhead in kraft paper-based protective wraps for European electronics and luxury goods fulfillment networks where extended producer responsibility frameworks are displacing conventional plastic films. Target India's pharmaceutical cold-chain expansion with temperature-stable shrink film formulations qualified for CDSCO serialization mandates. Lead with automated wrapping system integration partnerships rather than standalone material supply to bypass incumbent equipment lock-in. For Investors and Strategic Acquirers: Long-term, this sits as a service-attach play because equipment-integrated replenishment contracts generate recurring revenue streams with lower customer churn than transactional film sales. Acquisition targets should emphasize mid-tier converters with installed automated wrapping system bases and underdeveloped aftermarket service capabilities. Watch for inflection when third-party logistics provider consolidation accelerates unbundling of film supply from maintenance contracts, forcing material suppliers to compete on pure per-unit economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tackifier Supply | Proprietary adhesive chemistry control reduces formulation lock-in risk from narrow supplier base concentration. |
| Solvent-Free Coating Line Conversion | F-Gas Regulation compliance in Europe mandates capital redeployment ahead of pharmaceutical cold-chain deadlines. |
| Automated Wrapping System Integration | Machine vision and tension-controlled application enables adaptive bundling for irregular e-commerce product geometries. |
| Fiber-Based Protective Wrap Scale-Up | Kraft paper cohesive formulations capture share from plastic films under extended producer responsibility pressures. |
| ISO 9001 Batch Traceability Investment | Pharmaceutical and electronics end users require documented material genealogy for supplier qualification protocols. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across the primary research phase, including blown film extrusion plant managers, third-party logistics procurement leads, pharmaceutical packaging engineers, e-commerce fulfillment operations directors, and aftermarket service heads at equipment manufacturers. Secondary validation drew from EPA volatile organic compound emission filings, ECHA REACH SVHC disclosure databases, customs and trade flow data for polyethylene resin and finished film products, and SEC 10-K disclosures from diversified packaging materials conglomerates. Bottom-up volume estimates triangulated against top-down market sizing derived from end-use industry consumption patterns.
Calibration against historical price realizations and capacity utilization rates anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include material format, end-use industry, application method, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand projections and supply-side capacity expansion schedules. Forecast inputs incorporated petrochemical feedstock price volatility assumptions and evolving extended producer responsibility framework implementation timelines.
Sensitivities concentrate around REACH SVHC list expansions, F-Gas Regulation enforcement acceleration, and abrupt shifts in e-commerce fulfillment velocity. Forecasts reflect documented assumptions on resin price trajectories and adhesive additive supply availability. Material shifts in European regulatory stringency or biopolymer cohesive film performance breakthroughs would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Card Films Market
Packaging Materials
Disposable Egg Trays Market
Packaging Materials
Packaging Straps and Buckles Market
Packaging Materials
Cast Polypropylene (CPP) Films Market
Packaging Materials
France Packaging Market
Packaging Materials
Direct Thermal Printing Films Market
Packaging Materials
Honeycomb Packaging Market
Packaging Materials
Expanded Polystyrene for Packaging Market
Packaging Materials
Neoprene Coffee Sleeves Market
Packaging Materials
Bulb Packaging Market
Packaging Materials
Spices, Dry Mixes and Extracts Packaging Market
Packaging Materials
Trifold Packaging Market
Packaging Materials
Child Resistant Re-Closable Edible Bags Market
Packaging Materials
Europe Consumer Packaging Market
Packaging Materials
Disposable Icepacks Market
Packaging Materials
Paint Packaging Market