
 Punnet Packaging Market | 2026-2036
Punnet Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Punnet Packaging Market Analysis
ISO 22000 certification is bifurcating the competitive landscape into food-grade qualified suppliers and generalist converters. Groupe Guillin SA leverages its thermoforming scale across European berry supply chains. Smurfit Kappa Group Plc anchors its position through integrated paper-based punnet production. Berry Global differentiates via multi-material capabilities spanning PET and biodegradable substrates.
Punnet packaging denotes tray-style containers, typically 150-500 grams in capacity, engineered from thermoformed PET, molded pulp, or extruded polypropylene to protect soft fruits and vegetables through distribution. The structure features ventilation apertures and nesting geometry to optimize cold-chain airflow and pallet density. Plastic punnets retain dominant volume share but face margin compression from regulatory recycling fees. Biodegradable alternatives represent the fastest-expanding material category as retailers enforce Scope 3 emissions targets. Application demand concentrates in berries, where bruise sensitivity and premium pricing justify specialized packaging investment.
FDA food contact regulations govern US market entry for polymer-based punnets, while EFSA and the EU Packaging and Packaging Waste Regulation dictate recycled content thresholds and extended producer responsibility schemes across Europe. Compliance with these frameworks shapes material selection, supplier qualification timelines, and capital allocation toward recycling infrastructure. Stakeholders must monitor evolving extended producer responsibility fee structures to anticipate margin redistribution across the value chain.
Market Dynamics
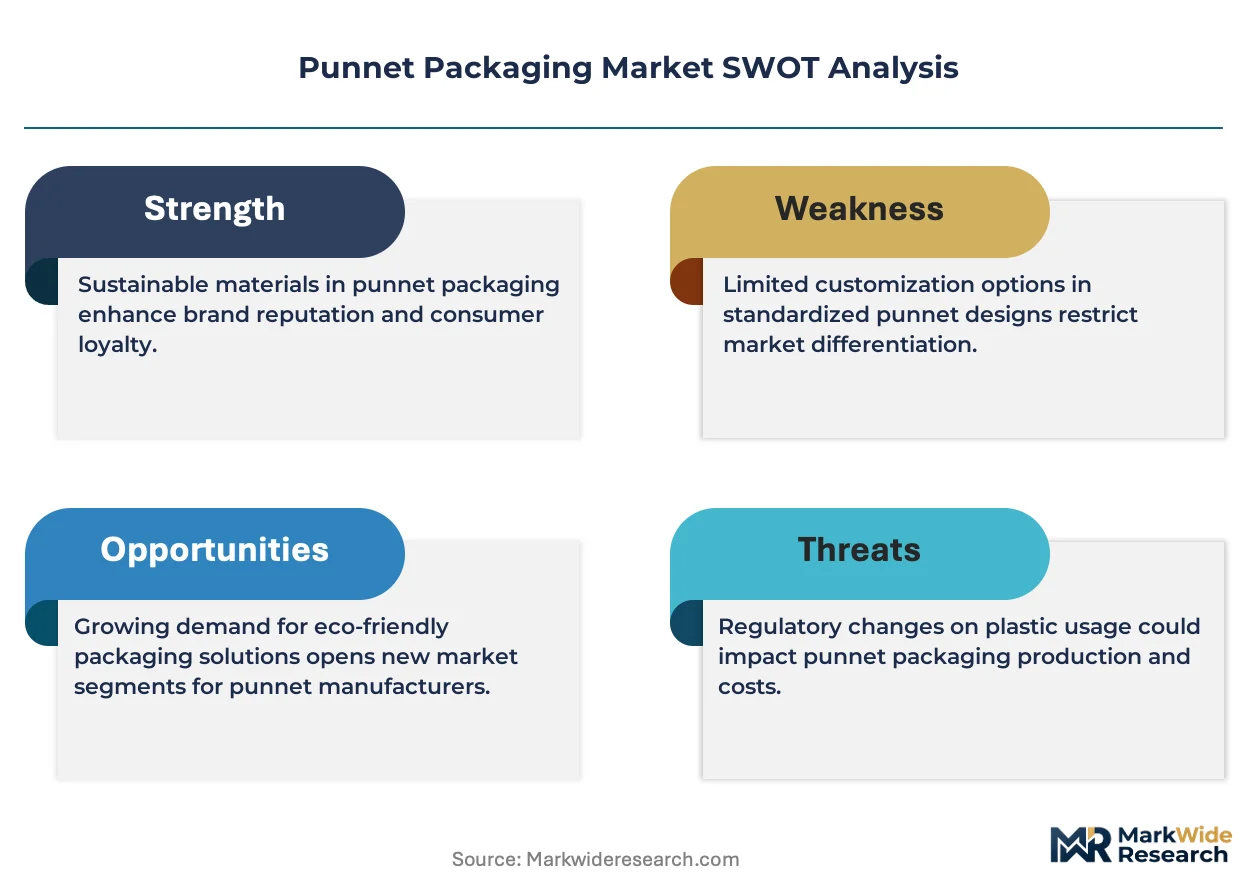
The EU Packaging and Packaging Waste Regulation is compressing margins across plastic-intensive formats while redirecting capital toward biodegradable substrate lines and mechanical recycling infrastructure. This regulatory pressure is the dominant structural force reshaping supplier positioning and buyer procurement criteria.
Growth Catalysts
- Supermarket Private-Label Expansion:Centralized produce sourcing by European retail chains is standardizing punnet specifications and consolidating supplier relationships.
- EU Recycled Content Mandates:The Packaging and Packaging Waste Regulation is forcing adoption of post-consumer PET and driving investment in closed-loop collection systems.
- Berry Cultivation Intensification:Protected agriculture expansion in Morocco and Spain is generating concentrated demand for high-throughput automated packing lines.
Market Restraints
- Recycled PET Feedstock Volatility:Collection rate shortfalls and bale quality inconsistency are inflating rPET premiums above virgin polymer benchmarks.
- Thermoforming Equipment Concentration:German and Italian machinery suppliers control critical forming line capacity, creating procurement bottlenecks for new entrants.
- Biodegradable Performance Gap:Molded pulp and PLA alternatives exhibit moisture sensitivity and stacking strength limitations in extended cold-chain distribution.
Strategic Opportunities
- Central and Eastern European Underpenetration:Polish and Romanian retail modernization is creating first-mover advantages for standardized punnet suppliers.
- Ready-to-Eat Vegetable Segments:Pre-cut salad and snack vegetable lines are adopting modified-atmosphere punnets with premium pricing tolerance.
- Digital Printing Integration:Inline decoration technology is enabling batch-specific branding and traceability coding without label application steps.
Industry Challenges
- ISO 22000 Certification Backlogs:Third-party audit capacity constraints are extending supplier qualification timelines for retail chain approval.
- Legacy Line Retrofit Complexity:Existing thermoforming assets require substantial modification to process biodegradable substrates at commercial throughput rates.
- Extended Producer Responsibility Fee Uncertainty:Evolving national implementations of the EU Packaging and Packaging Waste Regulation are complicating multi-market pricing strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Punnet Packaging Market |
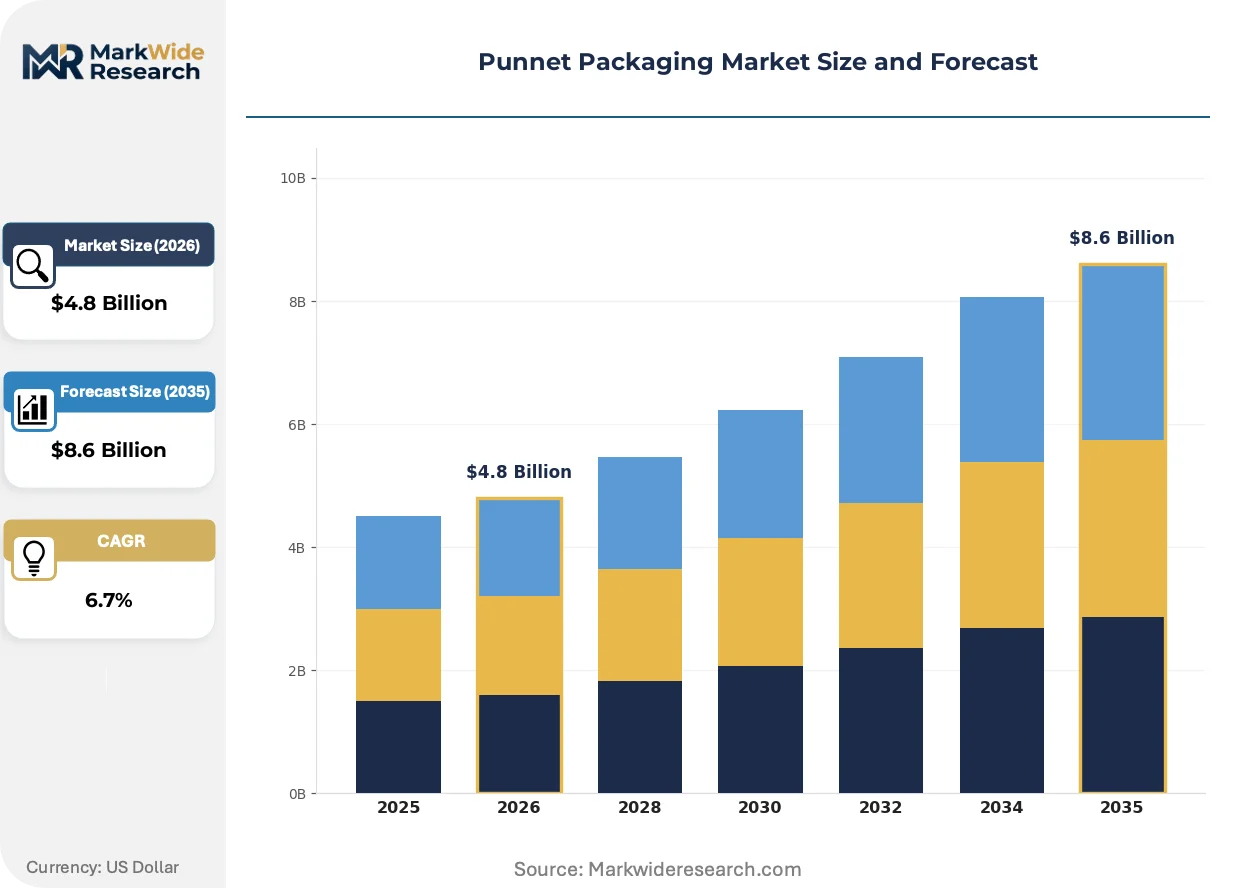
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Plastic, Cardboard, Biodegradable, PET Application: Fruits, Vegetables, Berries, Confectionery Size: Small, Medium, Large, Custom End User: Retailers, Distributors, Food Processors, Wholesalers |
| Companies Covered | Groupe Guillin SA, Infia S.r.l., Smurfit Kappa Group Plc, Amcor, Berry Global, Coveris Holdings SA, Paccor Netherlands BV, Sonoco Products Company, LC Packaging International BV, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Punnet Packaging Market Emerging Trajectories
Active packaging integration and substrate diversification are compressing the technology frontier for soft-fruit protection. Suppliers are racing to embed sensors and barrier layers while navigating regulatory tightening on single-use plastics.
Ultra-thin barrier coating technology is miniaturizing oxygen and moisture protection into nanometer-scale deposited layers on conventional substrates. Berry packers in the Netherlands and Belgium are piloting these coatings to extend raspberry shelf life without full laminate structures. This is miniaturizing the functional distinction between commodity PET and high-performance multilayer films, eroding premium pricing for conventional barrier solutions.
The EU Packaging and Packaging Waste Regulation is mandating minimum recycled content thresholds and extended producer responsibility fee structures across member states. Thermoformers are reconfiguring extrusion lines to process higher rPET loadings while maintaining optical clarity for retail display. Small-format berry punnets face the steepest compliance cost escalation due to their high surface-area-to-volume ratio and limited alternative substrate viability.
Retail procurement consolidation is compressing supplier rosters and lengthening contract durations. German and French supermarket chains are consolidating volume commitments with qualified food-grade converters capable of pan-European fulfillment. This concentration is most visible in the strawberry segment, where three retail groups now control over half of northwest European punnet procurement decisions.
Punnet Packaging Market Segmentation
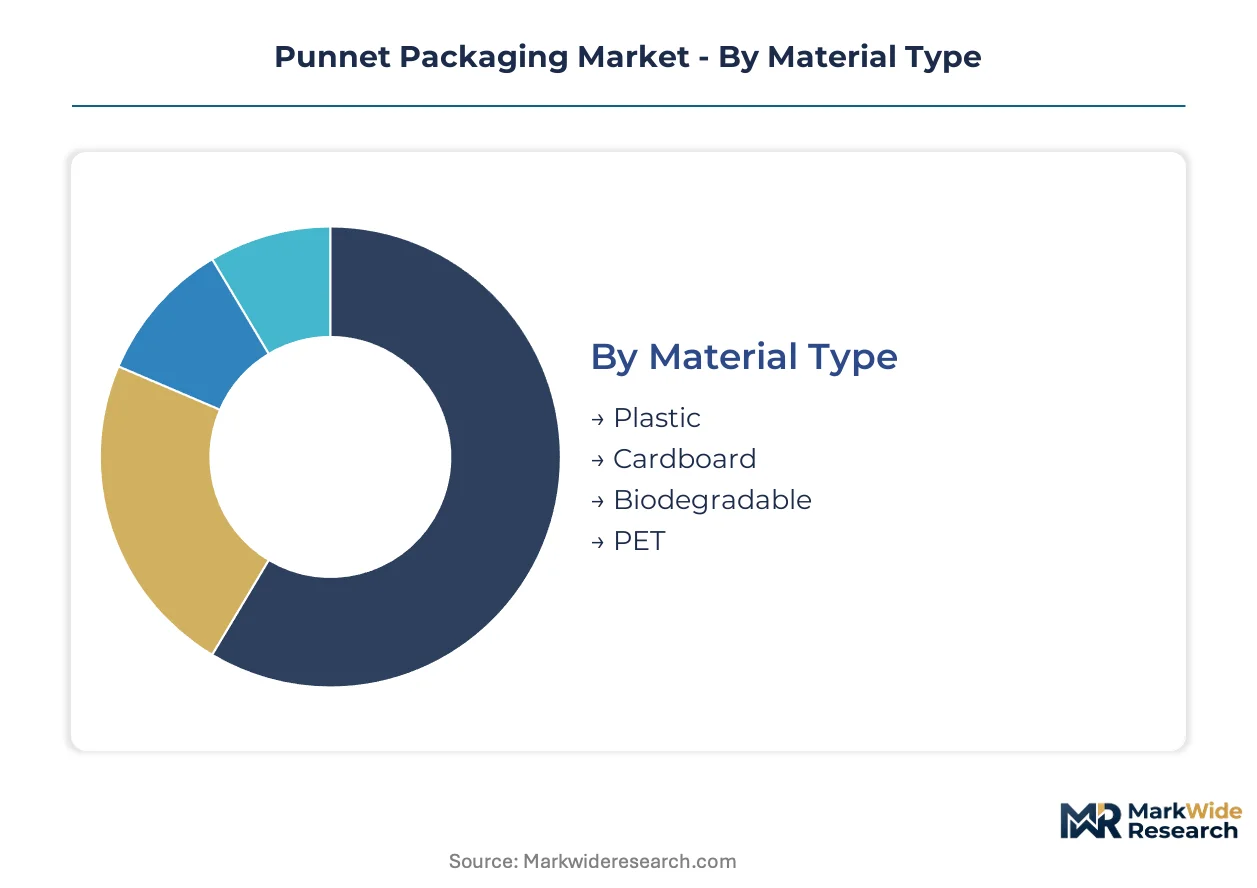
Punnet packaging segmentation reveals where regulatory pressure and substrate innovation intersect most acutely. Material substitution dynamics and application-specific performance requirements determine supplier positioning and capital allocation priorities across each dimension.
Material Type:
Plastic formats face the most intense substitution pressure from biodegradable alternatives as EFSA thresholds on recycled content tighten procurement specifications.
- Plastic:Thermoformed polypropylene and polystyrene structures dominate existing installed base. German retail chains are phasing out virgin plastic punnets for berry lines, compressing volume share despite cost advantages.
- PET:Post-consumer recycled PET loadings are climbing to meet EU Packaging and Packaging Waste Regulation mandates. Dutch packers are retrofitting extrusion lines to process higher rPET ratios while preserving optical clarity for retail display.
- Biodegradable:Molded pulp and PLA substrates are gaining shelf space in French and Belgian supermarket private-label programs. Moisture sensitivity in extended cold-chain distribution limits penetration beyond short-radius supply loops.
- Cardboard:Paper-based formats anchor Smurfit Kappa's integrated production network. Barrier coating limitations restrict adoption to dry-skin vegetables and bakery applications rather than high-moisture berries.
Plastic retains volume leadership; biodegradable holds the steepest expansion curve.
Application:
Margin structures diverge sharply between bruise-sensitive premium categories and commodity produce handling.
- Berries:Raspberry and strawberry punnets command specialized ventilation geometry and modified-atmosphere compatibility. Moroccan and Spanish protected agriculture expansion is concentrating demand for automated high-throughput packing lines.
- Fruits:Stone fruit and apple punnets prioritize nesting density for pallet optimization. Central European distribution networks favor standardized 400-500 gram formats.
- Vegetables:Pre-cut salad lines are adopting premium punnets with traceability coding. Ready-to-eat vegetable segments show strongest pricing tolerance for active packaging integration.
- Confectionery:Chocolate and sugar confectionery punnets emphasize retail visibility through clarity and printability. Seasonal demand spikes complicate capacity planning for converters.
Berries dominate revenue concentration; ready-to-eat vegetables are climbing the fastest.
Size:
Retail format standardization is compressing custom specification tolerance across European procurement.
- Small:150-250 gram capacities target single-serve and premium positioning. High surface-area-to-volume ratios amplify regulatory compliance cost burdens.
- Medium:300-400 gram formats anchor mainstream retail listings. German supermarket chains are consolidating specifications around 375 gram berry punnets.
- Large:500+ gram family packs concentrate in UK and Nordic markets. Pallet density optimization drives geometry standardization.
- Custom:Bespoke dimensions serve specialty retail and export packaging. Audit backlogs for ISO 22000 certification extend qualification timelines.
Medium formats anchor procurement volume; small sizes face steepest unit cost escalation.
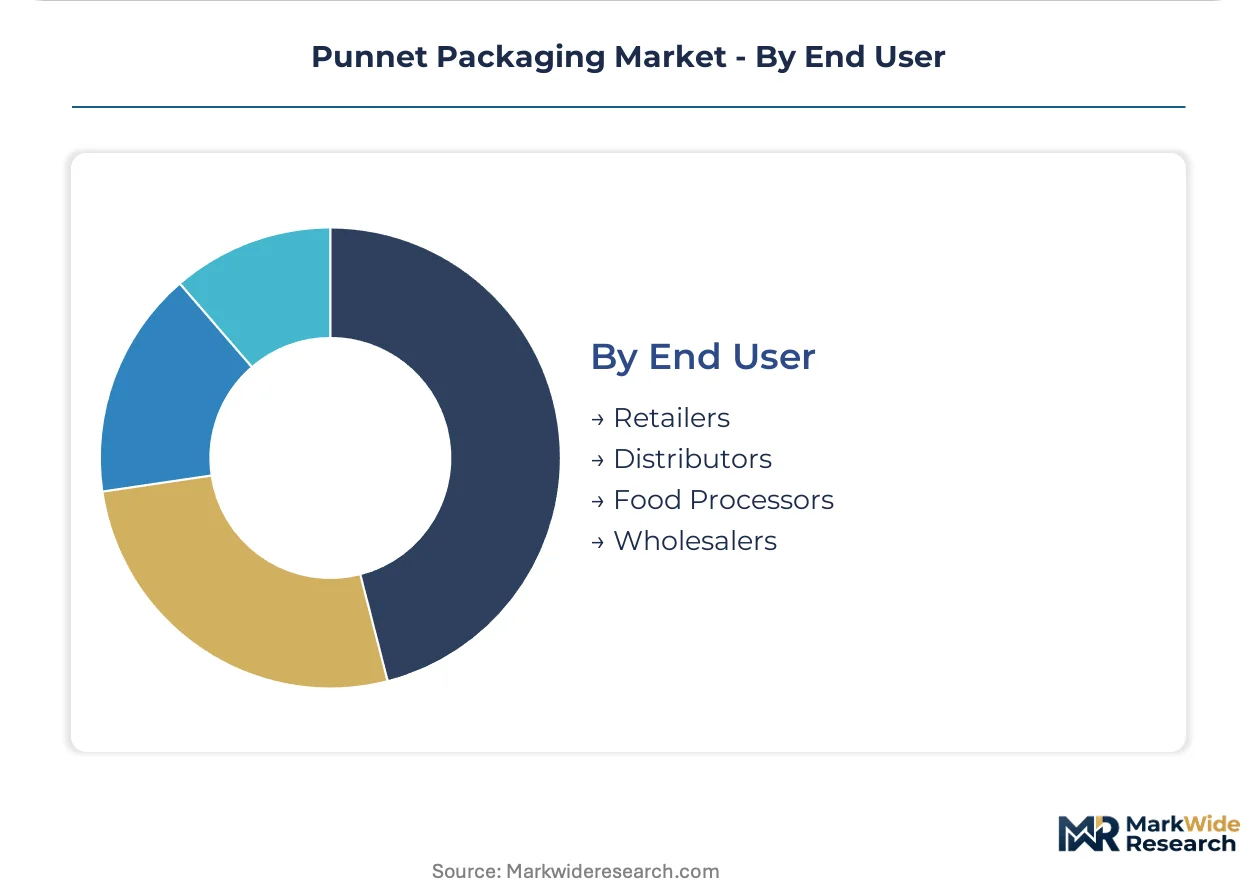
End User:
Channel concentration is restructuring supplier relationship dynamics toward pan-European fulfillment requirements.
- Retailers:German and French supermarket chains are consolidating volume commitments with qualified food-grade converters. Private-label expansion is standardizing specifications across northwest European markets.
- Food Processors:Pre-cut salad and snack vegetable packers demand modified-atmosphere compatibility. Inline digital printing integration enables batch-specific branding without label steps.
- Distributors:Wholesale consolidation favors suppliers with multi-country logistics networks. Polish and Romanian retail modernization is creating first-mover positioning opportunities.
- Wholesalers:Traditional produce wholesale channels retain price-sensitive procurement. Generic specifications limit premium substrate adoption.
Retailers command procurement concentration; food processors are expanding specification sophistication fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Packaging and Packaging Waste Regulation is redirecting investment flows across European punnet markets. National implementations vary in fee structures and recycled content timelines. Industrial clusters concentrate where berry cultivation and retail consolidation intersect.
Germany
Centralized produce distribution networks favor high-throughput automated packing lines serving Aldi and Lidl private-label programs. The EFSA and national packaging ordinances enforce strict recycled content verification for single-use plastics. The Lower Saxony cluster around Oldenburg hosts thermoforming operations supplying northwest European berry chains.
Spain
Protected agriculture expansion in Huelva and Almería generates concentrated demand for export-grade punnets bound for northern Europe. The national extended producer responsibility scheme imposes escalating fees on virgin plastic formats. Valencia-based converters are retrofitting lines to process higher post-consumer PET loadings for supermarket compliance.
Netherlands
Rotterdam distribution hubs anchor pan-European logistics for berry re-export to German and French retail chains. The Dutch Packaging Covenant mandates rapid recycled content scaling ahead of EU baseline requirements. Westland greenhouse clusters drive specialized demand for modified-atmosphere punnets in tomato and pepper segments.
Poland
Retail modernization in Warsaw and Kraków is creating first-mover positioning for standardized punnet suppliers entering former wholesale-dominated channels. The national waste management framework is aligning with EU Packaging and Packaging Waste Regulation implementation timelines. Silesian converters are expanding thermoforming capacity to serve emerging Central European supermarket chains.
France
Carrefour and Intermarché private-label expansion is consolidating procurement around qualified food-grade converters with pan-European fulfillment capability. The AGEC law and national anti-waste roadmap accelerate biodegradable substrate adoption ahead of EU mandates. The Brittany berry processing cluster demands specialized ventilation geometries for soft-fruit export packaging.
Punnet Packaging Market Vendor Landscape
Player mix skews toward integrated packaging conglomerates with multi-material capabilities and regional thermoforming specialists with food-grade certifications. The supplier base concentrates around three strategic archetypes: pan-European scale players with recycling infrastructure, national specialists with retail chain relationships, and substrate-focused innovators in biodegradable formats. Dominant competitive moves include vertical integration into rPET collection systems and strategic partnerships with berry packers for co-developed specifications.
Within the scale-driven tier, Groupe Guillin SA and Smurfit Kappa Group Plc exemplify divergent material strategies—thermoforming concentration versus paper-based integration. Berry Global occupies a position spanning polymer and biodegradable substrate lines. These three anchors represent how European punnet supply is restructuring around regulatory compliance capabilities and retail chain consolidation.
| Leading Market Players |
|---|
| Groupe Guillin SA |
| Infia S.r.l. |
| Smurfit Kappa Group Plc |
| Amcor |
| Berry Global |
| Coveris Holdings SA |
| Paccor Netherlands BV |
| Sonoco Products Company |
| LC Packaging International BV |
| Others |
Supply Flow & Price Mechanics
Sixty-to-ninety-day thermoforming equipment lead times concentrate procurement leverage with German and Italian machinery suppliers, amplifying pricing power for qualified converters while squeezing margin buffers for new entrants lacking established supplier relationships.
Pricing Analysis
Certification level creates the primary spread between food-grade qualified suppliers and generalist converters. Three-tier pricing structure across premium, standard, and economy levels tracks ISO 22000 audit status, rPET loading ratios, and pan-European fulfillment capability. Cost compression in virgin plastic punnets is intensifying because EPR fee escalations compress margins faster than substrate substitution. Traditional wholesale channels exhibit highest price sensitivity; supermarket private-label programs show tolerance for premium positioning when paired with traceability guarantees.
Supply Chain Analysis
Just-in-time raw material sourcing dominates berry packer procurement, though strategic stockpiling of post-consumer PET bales is emerging among Dutch and Spanish converters facing collection rate volatility. Feedstock supply concentrates in Germany, Spain, and the Netherlands, where mechanical recycling infrastructure and protected agriculture clusters intersect. The chain draws from virgin polymer resins, post-consumer flake, and molded pulp fibers as primary inputs. Single-source vulnerability sits with thermoforming equipment suppliers controlling critical line capacity. Distribution runs through Rotterdam and Hamburg hub-and-spoke networks serving pan-European retail consolidation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ISO 22000 audit capacity constraints and rPET optical clarity processing know-how constitute binding bottlenecks that determine which suppliers capture supermarket private-label volume commitments.
For Market Incumbents: Compound food-grade certification moats by accelerating backward integration into closed-loop rPET collection systems before EPR fee structures mature. Retrofit legacy thermoforming assets for biodegradable substrate compatibility to defend position against molded pulp substitution in French and Belgian retail chains. Prioritize capacity addition in Poland and Romania to anchor emerging Central European supermarket modernization. For New Entrants and Emerging Players: Digital printing integration for batch-specific traceability coding represents a service-layer gap where incumbents under-serve mid-size berry packers lacking inline decoration capability. Target Polish retail modernization as the most penetrable geography, where standardized punnet specifications are displacing wholesale-dominated procurement. Pursue co-development partnerships with Moroccan protected agriculture expansion projects as the go-to-market angle. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified packaging conglomerates with underperforming thermoforming divisions lacking food-grade certification depth. Long-term viability hinges on regulatory compliance infrastructure rather than commodity scale, favoring qualified converters with pan-European retailer relationships over volume-driven generalists. Watch rPET bale premium spreads relative to virgin polymer as the inflection indicator for margin redistribution across substrate lines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into rPET Collection | Captures margin from volatile post-consumer feedstock markets while satisfying EFSA recycled content mandates. |
| Biodegradable Substrate Line Retrofit | Positions converters for AGEC law acceleration and French supermarket private-label biodegradable commitments. |
| Digital Printing Capability Addition | Enables batch-specific branding for berry packers without label application bottlenecks. |
| Central European Capacity Expansion | Anchors first-mover positioning in Polish and Romanian retail modernization trajectories. |
| Co-Development Partnership with Berry Packers | Locks in specification influence for modified-atmosphere and ventilation geometry innovation. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with supermarket category buyers, berry packer operations directors, thermoforming plant managers, and EPR scheme administrators. Secondary validation drew from EU Packaging and Packaging Waste Regulation implementation documents, EFSA food contact guidance, national packaging ordinances, and customs trade data for polymer resin and recycled flake flows. Bottom-up volume modeling triangulated against top-down retail procurement concentration estimates.
Across the analysis window, the forecasting framework modeled punnet demand through material type, application segment, size format, and end-user channel dimensions. CAGRs were derived from regression analysis of historical supermarket private-label expansion rates and protected agriculture acreage growth. Industry-specific inputs included rPET loading ratio compliance trajectories and thermoforming line capacity utilization surveys.
Material uncertainties — EPR fee structure finalization, rPET collection rate volatility, and biodegradable substrate performance validation — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory implementation timelines and substrate substitution elasticities. Revision becomes warranted when rPET bale premiums exceed virgin polymer benchmarks by sustained margins that accelerate substrate switching.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Card Films Market
Packaging Materials
US Packaging Market
Packaging Materials
Sealed Wax Packaging Market
Packaging Materials
Europe Airless Packaging Market
Packaging Materials
Release Film for OCA Market
Packaging Materials
Tube Packaging Market
Packaging Materials
Tube and Stick Packaging Market
Packaging Materials
North America Stick Packaging Market
Packaging Materials
Aerosol Packaging Market
Packaging Materials
Production Page Volume Market
Packaging Materials
Graphene Infused Packaging Market
Packaging Materials
Composite Packaging Market
Packaging Materials
Twist Tie Market
Packaging Materials
GCC Disposables (Single-Use) Packaging Market
Packaging Materials
Disposable Egg Trays Market
Packaging Materials
Lidding Foil Market