
 Li Metal Battery Market | 2026-2036
Li Metal Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Li Metal Battery Market Foresight
Solid-state electrolyte integration is rewriting the manufacturing architecture for next-generation energy storage. QuantumScape Corporation leverages ceramic separator technology to sustain high-throughput production targets. Solid Power anchors its position through sulfide-based solid electrolyte manufacturing at scale. SES AI Corporation differentiates via hybrid liquid-solid cell designs that navigate existing lithium-ion infrastructure constraints.
Li metal batteries employ metallic lithium as the anode material, achieving specific energy densities exceeding conventional graphite-anode systems through elimination of host material mass and reduction in cell weight. The chemistry serves applications demanding maximum gravimetric energy, including electric aviation and extended-range electric vehicles. Secondary batteries capture the dominant commercialization pathway as manufacturers prioritize rechargeable architectures over primary cell formats. Solid-state batteries command premium positioning due to enhanced safety profiles and compatibility with lithium metal anodes, though thin film batteries occupy niche roles in microelectronics where form factor constraints override energy density requirements.
The US Department of Energy and NHTSA coordinate on battery safety testing protocols that shape cell qualification timelines for automotive suppliers. EPA hazardous material classifications and OSHA workplace exposure limits govern manufacturing facility design and operational permitting for lithium handling. China's MIIT issues GB standards for new energy vehicle power batteries that mandate thermal runaway propagation resistance, directly influencing solid-state development priorities. Stakeholders must monitor regulatory convergence between safety certification regimes and performance benchmarks as commercial deployment accelerates beyond pilot volumes.
Market Dynamics
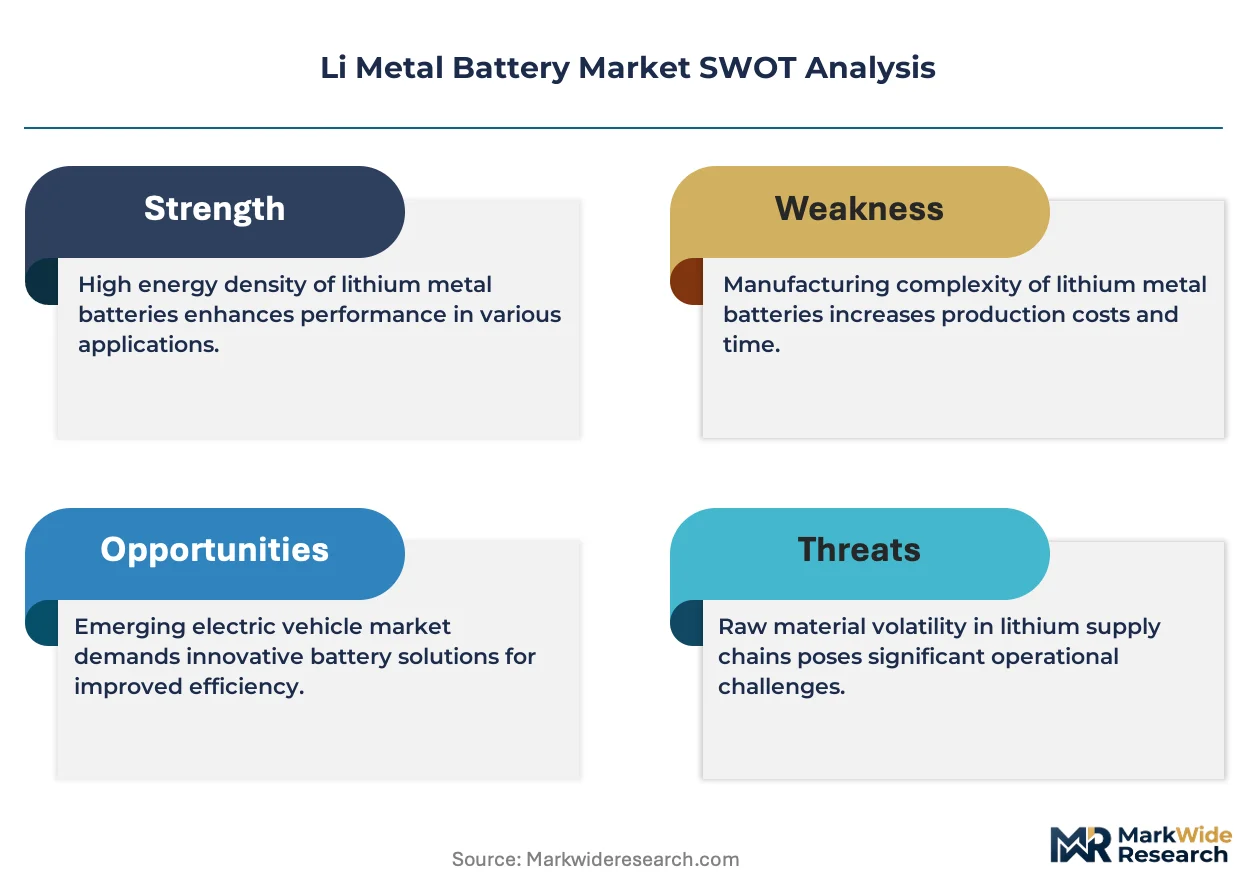
Solid-state electrolyte maturation is collapsing the historical trade-off between energy density and cycle stability, forcing incumbent lithium-ion supply chains to retool for metallic lithium handling and ceramic separator integration.
Growth Catalysts
- GB Standards Mandate:China's MIIT thermal runaway propagation requirements for new energy vehicle power batteries accelerate solid-state lithium metal adoption by disqualifying conventional liquid-electrolyte architectures from premium vehicle segments.
- Electric Aviation:Regional air mobility developers specify lithium metal cells for airframe-integrated battery packs where gravimetric energy density directly determines payload-range economics.
- Sulfide Electrolyte Processing:Advances in argon-atmosphere manufacturing reduce solid-state cell production costs, narrowing the gap with liquid-electrolyte lithium-ion on a per-kWh basis.
Market Restraints
- Lithium Metal Supply Concentration:Primary lithium metal production concentrates in Chinese and South American chemical processing facilities, exposing cell manufacturers to geopolitical supply disruption and input cost volatility.
- Dendrite Suppression Complexity:Ceramic and polymer-ceramic composite separators require sub-micron thickness control to prevent lithium filament penetration, constraining manufacturing yield rates.
- OSHA Workplace Exposure Limits:US facilities face stringent lithium handling protocols that extend facility commissioning timelines and elevate capital requirements for domestic manufacturing.
Strategic Opportunities
- US IRA Manufacturing Credits:Domestic content provisions in the Inflation Reduction Act create capital-access advantages for solid-state lithium metal production facilities sited in battery belt states.
- Marine Electrification:Ferry operators and coastal shipping lines specify lithium metal packs for vessel propulsion where weight reduction translates to route efficiency gains unavailable with conventional chemistries.
- Hybrid Liquid-Solid Designs:Intermediate architectures leveraging localized solid electrolyte barriers enable lithium metal anode deployment within existing cell manufacturing infrastructure.
Industry Challenges
- Solid-State Technician Scarcity:Ceramic processing and dry-room manufacturing expertise resides primarily in semiconductor and specialty materials sectors, requiring cross-industry talent recruitment.
- Automotive Qualification Timelines:NHTSA safety testing protocols for novel cell chemistries impose multi-year validation cycles before volume procurement contracts activate.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Li Metal Battery Market |
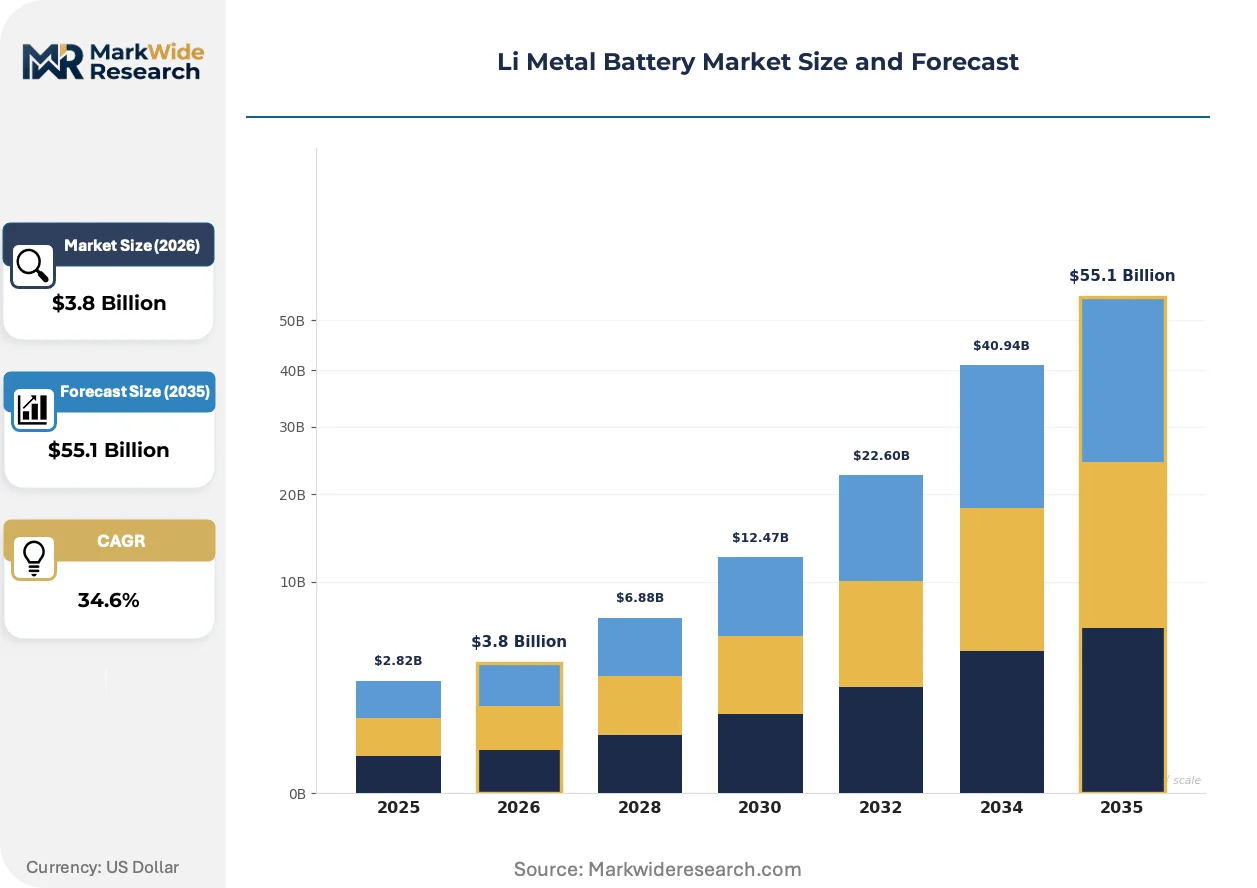
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $55.1 Billion |
| CAGR (2026 – 2036) | 34.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Primary Batteries, Secondary Batteries, Solid-State Batteries, Thin Film Batteries End User: Consumer Electronics, Electric Vehicles, Energy Storage Systems, Aerospace Application: Portable Devices, Grid Storage, Automotive Power, Space Applications Technology: Lithium-Sulfur, Lithium-Ion, Lithium Polymer, Metal-Air |
| Companies Covered | QuantumScape Corporation, Solid Power, SES AI Corporation, Li-Metal Corp, PolyPlus, Sepion Technologies, Blue Solutions, Sion Power, Albemarle Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Li Metal Battery Market Shifts & Advancements
Manufacturing process innovation is compressing the cost curve for ceramic separator production while regulatory pressure on thermal safety accelerates chemistry transitions previously deemed uneconomical.
Thin-film ceramic deposition is collapsing the cost structure for solid-state separator manufacturing. Battery developers in South Korea and Japan adopt atomic layer deposition and chemical vapor deposition techniques borrowed from semiconductor fabrication. This process convergence enables sub-10-micron separator layers that previously required expensive sintering operations.
REACH substance restrictions on fluorinated electrolyte additives in the European Union are redirecting formulation R&D toward sulfide and oxide-based solid electrolyte systems. Cell manufacturers serving German and French automotive OEMs now prioritize halogen-free electrolyte architectures to preempt regulatory compliance costs. The shift compresses development timelines for all-solid-state designs that bypass liquid electrolyte entirely.
Cell procurement by electric vehicle platforms is consolidating around long-term offtake agreements with volume floors and price collars. Tier-one automakers in China and the United States bypass spot-market purchasing, instead securing dedicated production lines from cell suppliers. This contractual shift concentrates volume risk with manufacturers while guaranteeing supply security for vehicle launch programs.
Li Metal Battery Market Segmentation
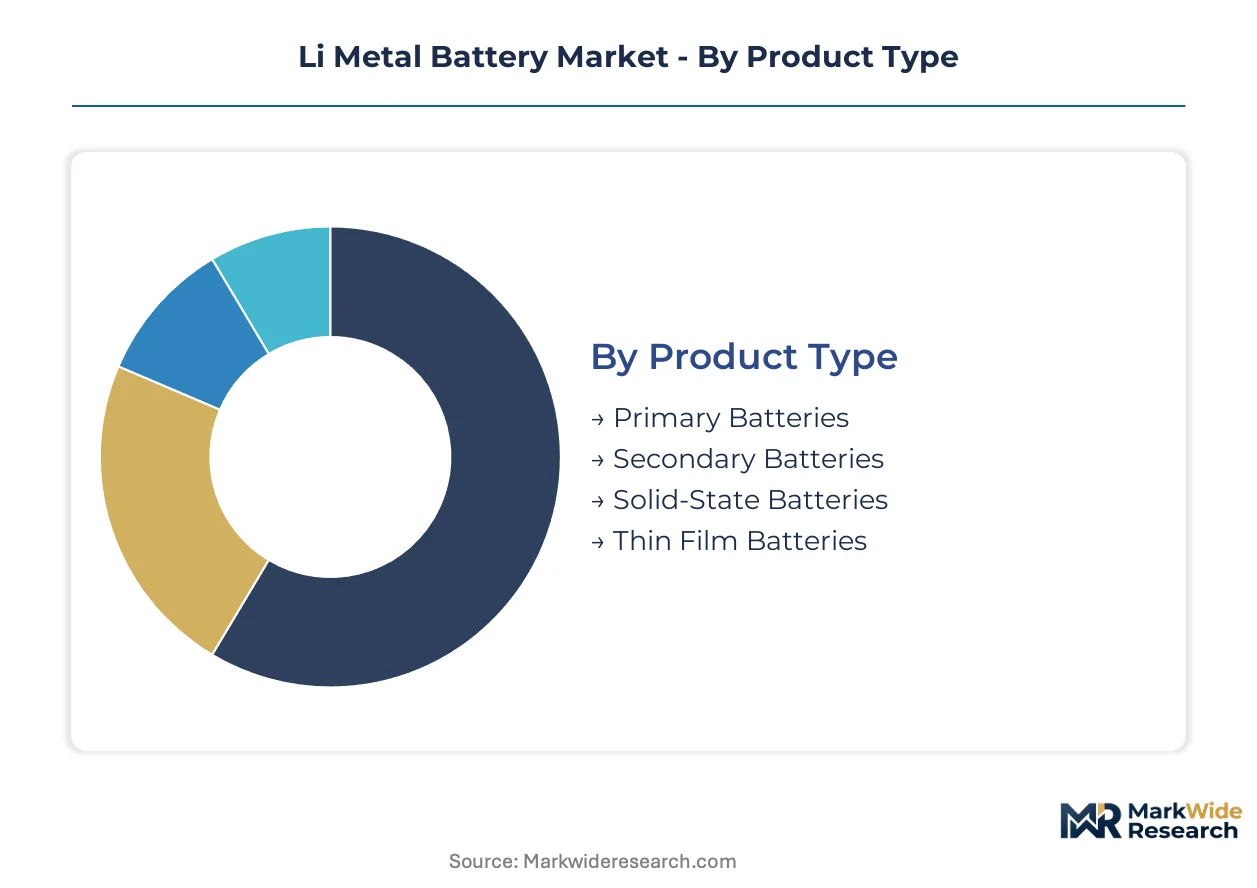
Li metal battery segmentation reveals how chemistry choices and end-use requirements fragment manufacturing priorities. Product architecture, customer application, and technology platform each impose distinct qualification timelines and performance specifications.
Product Type:
Application maturity and rechargeability requirements split the product landscape into four distinct manufacturing pathways.
- Primary Batteries:Single-use lithium metal cells deliver maximum specific energy through irreversible electrochemical conversion. Demand concentrates in military and aerospace applications where replacement access is restricted and cycle life is irrelevant.
- Secondary Batteries:Rechargeable architectures dominate commercial roadmaps as electric vehicle OEMs prioritize total cost of ownership over initial cell price. Chinese and South Korean cell producers anchor volume manufacturing for automotive qualification programs.
- Solid-State Batteries:Ceramic electrolyte integration enables lithium metal anode deployment with suppressed dendrite formation. Japanese and US developers lead pilot production for premium electric vehicle segments.
- Thin Film Batteries:Micro-scale deposition processes serve microelectronics and medical implant applications where form factor constraints override energy density optimization.
Secondary batteries command the established base. The steepest expansion runs through solid-state architectures.
End User:
Customer procurement scale and qualification rigor create tiered supply relationships across four demand centers.
- Electric Vehicles:Automotive OEMs impose multi-year validation cycles and thermal runaway propagation requirements per China's GB standards. Cell suppliers dedicate production lines to secure long-term offtake agreements with volume floors.
- Aerospace:Regional air mobility developers specify gravimetric energy density above all other metrics for airframe-integrated battery packs. US and European aviation regulators coordinate on novel chemistry certification protocols.
- Consumer Electronics:Smartphone and wearable manufacturers prioritize volumetric energy density and fast-charge compatibility over absolute cycle life.
- Energy Storage Systems:Grid-scale operators evaluate lithium metal against sodium-ion and flow battery alternatives for stationary applications where weight is irrelevant.
Electric vehicles anchor current procurement volume. Aerospace applications are climbing the fastest as certification pathways mature.
Application:
Operating environment severity and duty cycle intensity differentiate four deployment contexts.
- Automotive Power:Traction battery packs face vibration, thermal cycling, and crash safety requirements that exceed consumer electronics specifications by an order of magnitude. NHTSA protocols govern US market entry timelines.
- Space Applications:Satellite and launch vehicle systems demand radiation tolerance and vacuum compatibility that eliminate conventional liquid electrolyte options. NASA and ESA qualification programs drive cell design priorities.
- Portable Devices:Handheld electronics emphasize manufacturing cost minimization and supply chain flexibility over extreme performance margins.
- Grid Storage:Utility-scale installations prioritize calendar life degradation rates and fire suppression integration for containerized deployments.
Automotive power holds the dominant share. Space applications are gaining share fastest as launch cadence accelerates.
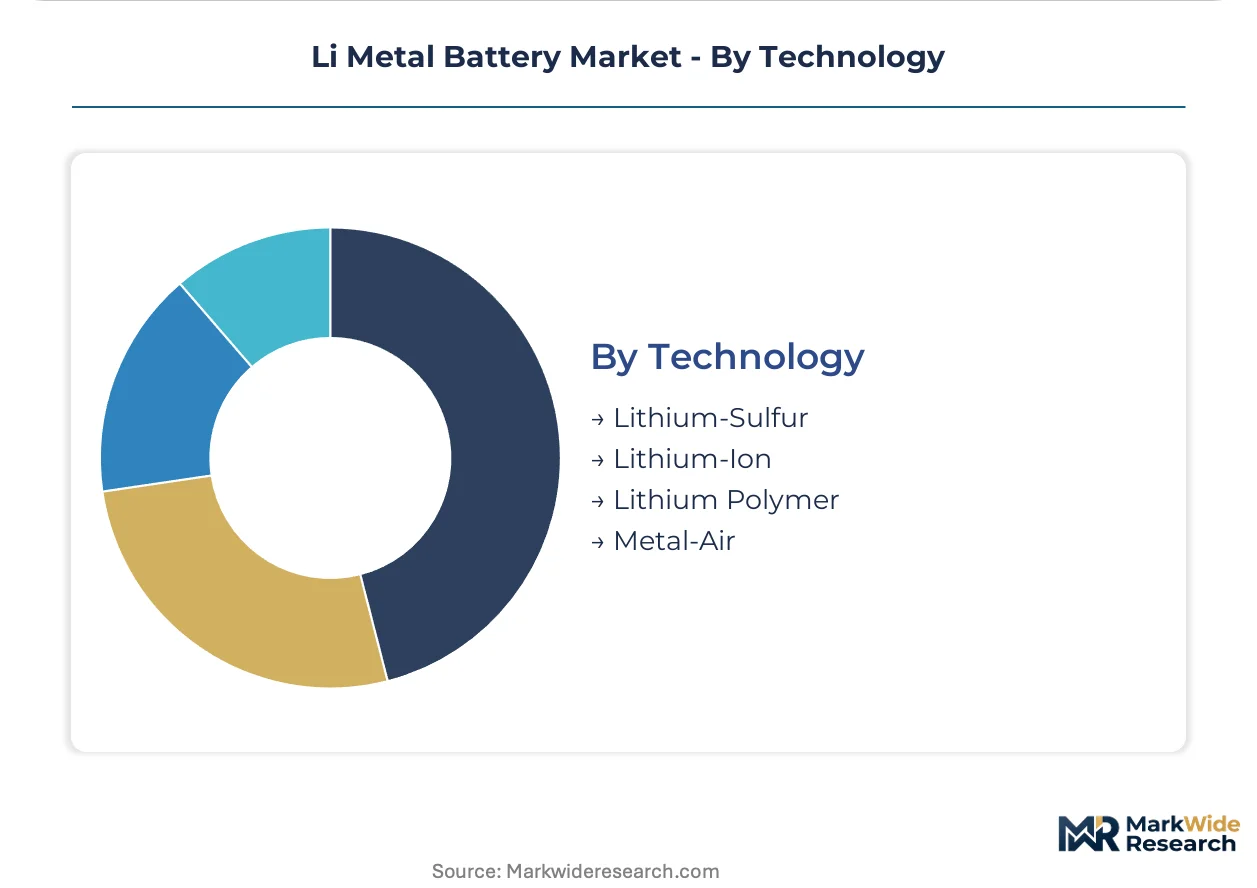
Technology:
Cathode and electrolyte chemistry combinations determine energy density ceilings and manufacturing process compatibility.
- Lithium-Sulfur:Elemental sulfur cathodes paired with lithium metal anodes achieve theoretical specific energy exceeding conventional intercalation chemistries. British and German developers advance cell designs for electric aviation applications.
- Lithium-Ion:Graphite anode replacement with lithium metal while retaining liquid electrolyte enables incremental density gains within existing manufacturing infrastructure.
- Lithium Polymer:Gel electrolyte formulations provide intermediate safety profiles for consumer electronics where mechanical abuse tolerance matters.
- Metal-Air:Ambient oxygen cathodes promise extreme gravimetric performance but face cycle stability challenges that restrict deployment to primary cell formats.
Lithium-ion derivatives retain the installed base. Lithium-sulfur systems show the steepest expansion trajectory as sulfur processing scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China exports lithium metal cells to German automotive OEMs and US aviation developers, establishing the dominant trade corridor for next-generation energy storage systems.
United States
Electric aviation developers in California and Washington State specify lithium metal packs for regional air mobility prototypes. NHTSA safety testing protocols govern multi-year qualification cycles for automotive suppliers. The battery belt cluster spanning Michigan, Ohio, and Georgia hosts IRA-funded solid-state manufacturing facilities.
China
Domestic automakers coordinate with cell producers on pack integration for extended-range electric vehicles. MIIT GB standards mandate thermal runaway propagation resistance that accelerates solid-state chemistry transitions. The Yangtze River Delta concentration around Shanghai and Suzhou anchors pilot production lines for ceramic separator manufacturing.
Germany
Premium automotive OEMs in Stuttgart and Munich procure lithium metal cells for flagship electric vehicle platforms. ECHA REACH substance restrictions on fluorinated electrolyte additives redirect formulation R&D toward sulfide-based systems. The Baden-Württemberg industrial corridor concentrates dry-room manufacturing expertise borrowed from semiconductor fabrication.
Japan
Consumer electronics manufacturers in Tokyo and Osaka evaluate thin-film lithium metal for next-generation wearable devices. METI funding programs support solid-state electrolyte research through national laboratory partnerships. The Nagoya automotive cluster integrates pilot cell production into existing Toyota and Honda supply chains.
South Korea
Battery developers in Seoul and Ulsan adopt atomic layer deposition techniques for sub-10-micron ceramic separators. MFDS chemical handling regulations shape facility design for lithium metal processing operations. The Gyeonggi-Seoul concentration hosts joint ventures between domestic cell producers and US solid-state technology licensors.
Li Metal Battery Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic tiers defined by electrolyte technology maturity and manufacturing scale. Ceramic separator specialists, sulfide electrolyte processors, and hybrid liquid-solid designers each occupy distinct competitive positions. Dominant moves include long-term offtake agreements with automotive OEMs and argon-atmosphere manufacturing facility expansion.
Within the solid-state technology tier, QuantumScape Corporation and Solid Power exemplify divergent approaches to ceramic and sulfide electrolyte commercialization. SES AI Corporation occupies a position bridging liquid and solid architectures. Albemarle Corporation anchors the upstream materials vector through lithium metal supply concentration. Each represents a strategic archetype rather than a definitive market position.
| Leading Market Players |
|---|
| QuantumScape Corporation |
| Solid Power |
| SES AI Corporation |
| Li-Metal Corp |
| PolyPlus |
| Sepion Technologies |
| Blue Solutions |
| Sion Power |
| Albemarle Corporation |
| Others |
Supply & Pricing Matrix
The Shanghai-Hamburg maritime corridor carries lithium metal precursor shipments whose freight cost volatility directly amplifies price spreads between Chinese cell producers and German automotive OEMs, compressing margins for mid-tier suppliers while premium solid-state manufacturers pass through logistics premiums via long-term offtake structures.
Pricing Analysis
The technology-generation pricing gap separating liquid-electrolyte lithium-ion, hybrid liquid-solid architectures, and all-solid-state designs widens as ceramic separator yields improve. Contract-based long-term offtake agreements dominate automotive procurement, with price differentiation driven by GB standard certification tier and volume scale commitments. Cost compression in hybrid architectures intensifies as SES AI and similar developers achieve manufacturing compatibility with existing infrastructure. Grid-scale energy storage buyers exhibit highest price sensitivity, while electric aviation developers accept premium positioning for gravimetric performance.
Supply Chain Analysis
Upstream feedstock concentration in Chilean lithium brine operations, Chinese chemical conversion facilities, and Australian spodumene mines creates layered dependency for cell manufacturers. Ceramic separator production draws from semiconductor-grade alumina and sulfide electrolyte precursors requiring argon-atmosphere handling. Single-source vulnerability in lithium metal refining exposes supply chains to MIIT export protocol shifts. Distribution runs through dedicated automotive logistics networks with thermal-controlled warehousing for active material shipments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Battery lifecycle management services including second-life pack refurbishment and materials recovery are expanding faster than hardware sales, creating recurring revenue pools that offset cell price erosion.
For Market Incumbents: Pre-empt sulfide electrolyte processing scale advantages by securing argon-atmosphere manufacturing capacity in battery belt states before IRA domestic content windows narrow. Ceramic separator yield improvements represent the critical lever against dendrite suppression complexity threatening automotive qualification timelines. Backward integration into lithium metal refining mitigates Chinese supply concentration risk.
For New Entrants and Emerging Players: Build out marine electrification and regional air mobility segments where qualification pathways remain open and incumbent offtake agreements have not yet consolidated. Electric ferry operators in Nordic coastal routes present the most penetrable white-space target. Go-to-market positioning should emphasize gravimetric energy density guarantees with route-specific performance contracts.
For Investors and Strategic Acquirers: Ceramic processing specialists with semiconductor fabrication heritage command scarcity premiums as solid-state manufacturing talent migrates from silicon to energy storage. Long-term viability hinges on five-to-ten-year automotive qualification completion rates rather than pilot production milestones. Cell-level thermal runaway test results from NHTSA protocols serve as the critical inflection signal for volume contract activation.
| Strategic Initiative | Industry Significance |
|---|---|
| Argon-Atmosphere Manufacturing Scale-Up | Sulfide electrolyte production cost parity with liquid-electrolyte systems accelerates solid-state adoption timelines. |
| Automotive Long-Term Offtake Agreement | Volume floors with price collars transfer demand risk to cell manufacturers while securing OEM supply chains. |
| Ceramic Separator Yield Improvement Program | Sub-10-micron deposition techniques borrowed from semiconductor ALD/CVD processes collapse separator cost structures. |
| Hybrid Liquid-Solid Architecture Deployment | Existing lithium-ion infrastructure compatibility enables lithium metal anode introduction without greenfield facility investment. |
| Lithium Metal Refining Backward Integration | Captive supply of battery-grade lithium metal reduces exposure to Chinese and South American chemical processing concentration. |
Research Methodology
A spread of perspectives from solid-state cell engineering directors, automotive Tier 1 procurement managers, ceramic separator manufacturing specialists, and lithium metal refining operators converged on the working assumptions governing chemistry transition timelines. Primary interview findings were cross-validated against MIIT GB standard documentation, NHTSA safety testing protocols, EPA hazardous material classifications, and SEC filings from publicly traded battery developers. Bottom-up cell production estimates and top-down automotive demand projections were triangulated to anchor volume forecasts.
Demand-supply-balance modeling across the projection horizon incorporated product type segmentation by rechargeability architecture, end user differentiation between automotive and aviation qualification rigor, application severity tiers from portable electronics to space systems, and technology platform distinctions among lithium-sulfur, solid-state, and hybrid designs. CAGRs were derived from installed base replacement dynamics and greenfield adoption curves rather than linear extrapolation. Forecast inputs included ceramic separator yield improvement trajectories and IRA domestic content credit eligibility thresholds.
Sensitivities concentrate around NHTSA qualification timeline extensions, MIIT export restriction implementations, and lithium metal spot price volatility. Forecasts reflect documented assumptions regarding sulfide electrolyte manufacturing scale-up rates and automotive OEM platform launch schedules. Cross-checking against IEA battery technology roadmaps and national laboratory solid-state research milestones is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Radial Lithium-Ion Capacitor Market
Lithium-ion Battery
Japan Lithium-Ion Battery Market
Lithium-ion Battery
Portable Lithium Battery Energy Storage Products Market
Lithium-ion Battery
Li-Sulfur Battery Market
Lithium-ion Battery
Lithium Polymer Battery Market
Lithium-ion Battery
Sodium Battery Electrolyte Market
Lithium-ion Battery
Nanotechnology Enabled Battery Market
Lithium-ion Battery
North America Lithium-Ion Battery Separator Market
Lithium-ion Battery
Global Lithium Mining Market
Lithium-ion Battery
Graphite Anode for LIB Market
Lithium-ion Battery
South America Electric Vehicle Battery Materials Market
Lithium-ion Battery
Lithium Battery Grade Lithium Carbonate Market
Lithium-ion Battery
Lithium-Ion Battery Materials Market
Lithium-ion Battery
Lithium Hydroxide Market
Lithium-ion Battery
Lithium Silicon Battery Market
Lithium-ion Battery
Li Air Battery Market