
 Automotive Lithium-Sulfur Battery Market | 2026-2036
Automotive Lithium-Sulfur Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Lithium-Sulfur Battery Market Outlook
Electric bus procurement is realigning the demand profile for automotive lithium-sulfur systems as municipal fleets seek weight reductions and extended range. Sion Power Corporation leverages its solid-state electrolyte architecture to anchor long-cycle-life designs for commercial vehicle integration. LG Energy Solutions Ltd. competes through extensive manufacturing scale across Asian and European production nodes. Zeta Energy LLC differentiates via metallic lithium anode innovations that address dendrite suppression in high-load applications.
Automotive lithium-sulfur batteries employ elemental sulfur cathodes paired with lithium metal anodes, achieving theoretical energy densities exceeding 500 Wh/kg through the lithium-sulfur redox chemistry that converts sulfur to lithium polysulfides during discharge. These systems primarily serve electric vehicle platforms where gravimetric energy density directly determines range capability and payload efficiency. Pouch cells currently dominate prototype deployments due to flexible form factors that maximize volumetric packing efficiency in constrained underfloor battery envelopes. Cylindrical cells are gaining traction among tier-1 suppliers seeking compatibility with existing high-speed winding equipment and thermal management architectures. The deployment segment spanning battery electric vehicles concentrates the largest near-term margin pools as OEMs prioritize pure-electric architectures over hybrid configurations.
The EPA tailpipe emission standards and the EU Battery Regulation's recycled-content mandates are tightening qualification criteria for cell suppliers seeking access to North American and European vehicle platforms. China's MIIT new-energy-vehicle subsidy framework and GB standards for battery safety testing further shape product development roadmaps and cross-border certification costs. Stakeholders must monitor how evolving carbon-border adjustment mechanisms interact with cell manufacturing location decisions and raw-material sourcing strategies.
Market Dynamics
The EU Battery Regulation's carbon-footprint thresholds are compressing qualification timelines for cell suppliers, forcing rapid electrolyte chemistry pivots and manufacturing location decisions before the 2027 enforcement window.
Growth Catalysts
- Electric bus fleet procurement:Municipal operators in South Korea are specifying lithium-sulfur cells for weight-sensitive routes requiring extended range.
- REACH-compliant material pathways:European cathode suppliers are certifying sulfur feedstocks under ECHA substance evaluation frameworks to secure OEM qualification.
- Solid-state electrolyte maturation:Polymer-ceramic hybrid architectures are suppressing polysulfide shuttle effects in pouch cell prototypes.
Market Restraints
- Metallic lithium supply concentration:Primary lithium metal production clusters in Argentina and Chile create geopolitical exposure for anode material sourcing.
- Cycle life degradation:Volume expansion of sulfur cathodes during lithiation-delithiation cycling limits commercial vehicle warranty terms.
- Fluoroethylene carbonate cost volatility:Electrolyte solvent price swings compress cell margin structures during scale-up phases.
Strategic Opportunities
- India's PLI scheme for advanced chemistry cells:Domestic manufacturing incentives are attracting sulfur cathode process technology transfers.
- Aviation auxiliary power units:Regional jet manufacturers are evaluating lithium-sulfur packs for emergency power systems where gravimetric density outweighs cycle requirements.
- Recycled-content mandates:The EU Battery Regulation's 2031 recovery targets for lithium and sulfur are stimulating closed-loop refining infrastructure.
Industry Challenges
- Dry electrode coating expertise:Solvent-free cathode manufacturing requires rare combinations of polymer science and roll-to-roll process engineering.
- UN 38.3 certification timelines:Lithium metal anode transport testing protocols extend product launch schedules by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Lithium-Sulfur Battery Market |
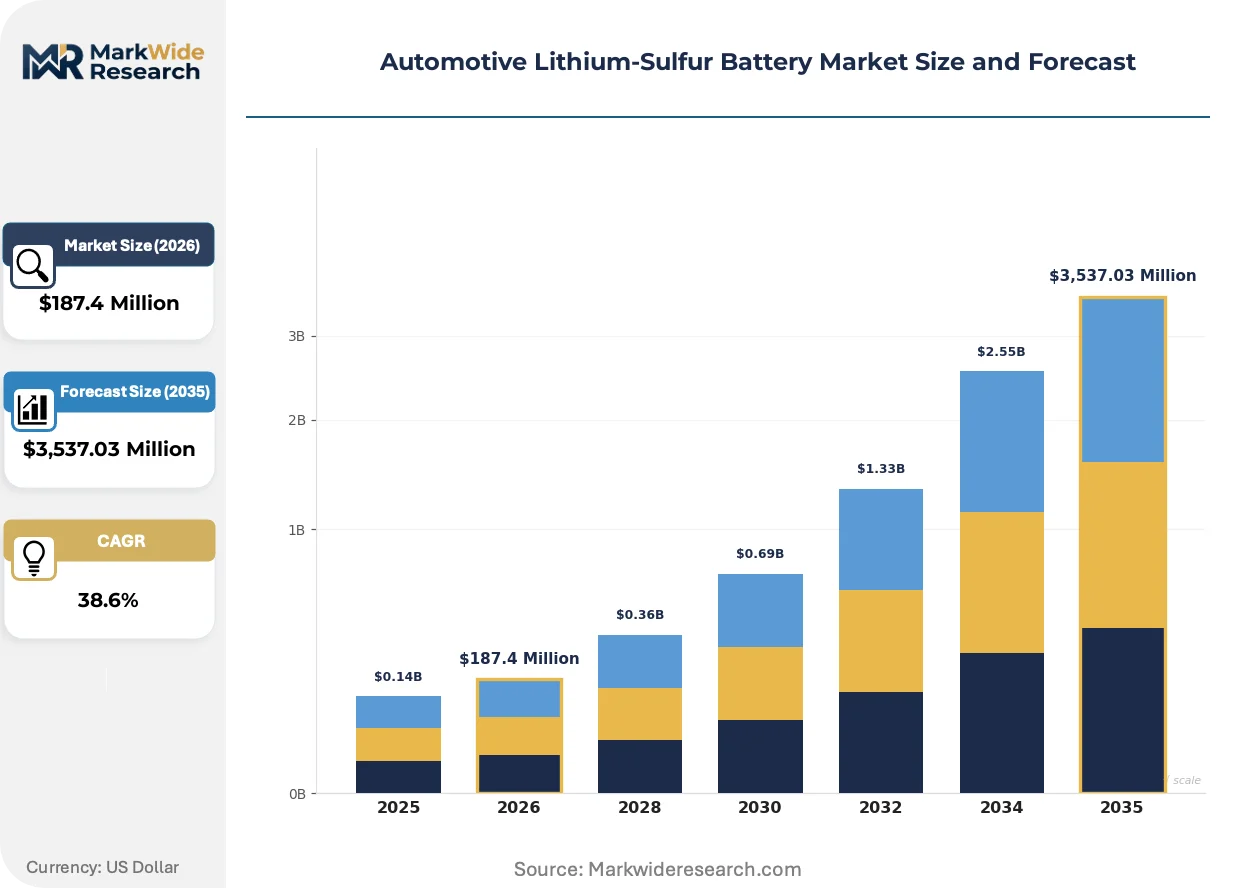
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $3,537.03 Million |
| CAGR (2026 – 2036) | 38.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pouch Cells, Cylindrical Cells, Prismatic Cells, Customized Packs Deployment: Battery Electric Vehicles, Hybrid Electric Vehicles, Plug-in Hybrid Electric Vehicles, Others Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Electric Buses Industry Vertical: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers |
| Companies Covered | Sion Power Corporation, PolyPlus Battery Company, NexTech Batteries Inc., Li-S Energy Limited, GS Yuasa Corporation, LG Energy Solutions Ltd., Zeta Energy LLC, Lyten, Inc., Giner, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Lithium-Sulfur Battery Market Strategic Shifts
Electrolyte formulation is undergoing rapid iteration as polysulfide containment chemistries mature, while manufacturing equipment adapts to handle sulfur's low electrical conductivity without solvent-heavy processing.
Sulfurized polyacrylonitrile cathode materials are expanding into electric bus platforms where energy density requirements exceed lithium iron phosphate capabilities. Tier-1 cell producers in Germany are validating these cathodes under accelerated cycle protocols. The technology is expanding into commercial vehicle segments previously reserved for nickel-cobalt chemistries.
EPA tailpipe emission standards are tightening fleet-average CO2 obligations for light-duty manufacturers, creating compliance pressure that favors high-energy-density cell chemistries. The industrial consequence is accelerated R&D allocation toward lithium-sulfur systems capable of extending electric range without pack weight penalties. Battery electric vehicle platforms in California and the Northeast corridor are responding with pilot procurement programs for next-generation cells.
Fleet procurement departments are consolidating supplier relationships around vertically integrated cell producers capable of certifying carbon intensity across raw material extraction. Direct OEM-cell maker contracting is displacing traditional tier-2 module assembly relationships in heavy-duty applications. This concentration is most visible in German commercial vehicle manufacturing, where municipal transit authorities now require supply chain transparency documentation.
Automotive Lithium-Sulfur Battery Market Segmentation
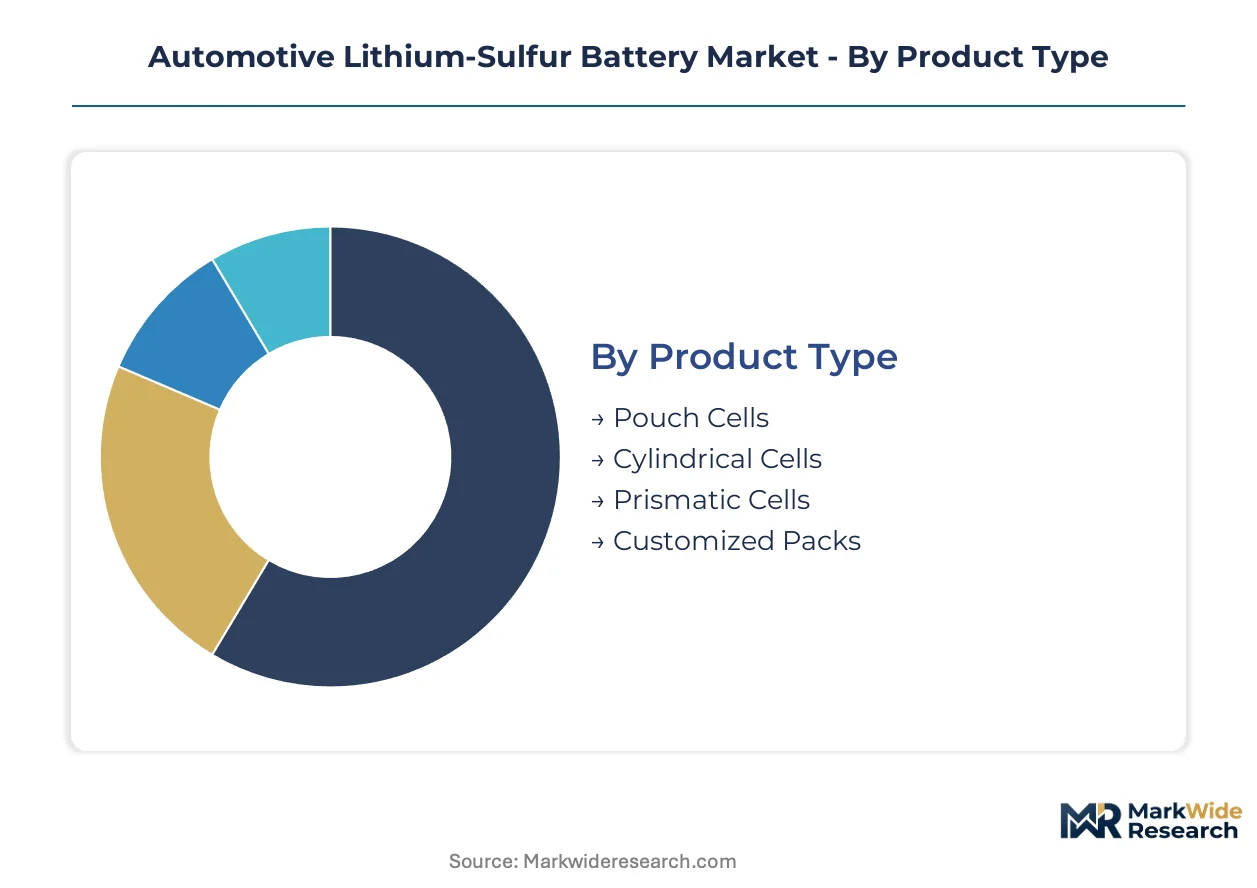
Segmentation reveals how lithium-sulfur chemistry migrates across vehicle architectures and supply chain tiers. Cell form factor and deployment type determine thermal management complexity and manufacturing scale requirements.
Product Type:
Volume concentration favors pouch configurations for their packing efficiency, while cylindrical formats command premium positioning through equipment compatibility.
- Pouch Cells:Flexible polymer-aluminum laminate enclosures maximize volumetric energy density in constrained underfloor battery envelopes. German automotive OEMs are concentrating procurement for high-energy-density platforms where gravimetric efficiency determines range capability.
- Cylindrical Cells:Rolled electrode architectures leverage existing high-speed winding equipment and established thermal management architectures. Tier-1 suppliers in South Korea are validating these formats for compatibility with automated assembly lines originally deployed for nickel-cobalt chemistries.
- Prismatic Cells:Rigid aluminum housings suit modular pack architectures with standardized cell-to-pack integration.
- Customized Packs:Application-specific enclosures address non-standard vehicle envelopes in commercial and specialty segments.
Mature deployment sits with pouch cells. Newer deployment is concentrated in cylindrical formats.
Deployment:
Application maturity separates pure-electric architectures from transitional hybrid configurations.
- Battery Electric Vehicles:Dedicated BEV platforms concentrate the largest near-term margin pools as OEMs prioritize pure-electric architectures over hybrid configurations. EPA tailpipe emission standards are tightening fleet-average obligations for light-duty manufacturers, accelerating R&D allocation toward lithium-sulfur systems capable of extending electric range without pack weight penalties.
- Hybrid Electric Vehicles:Smaller battery capacities in HEVs limit the gravimetric advantage of lithium-sulfur chemistry.
- Plug-in Hybrid Electric Vehicles:Dual-powertrain complexity reduces the relative value of energy density gains.
- Others:Emerging categories include range-extended electric vehicles and fuel-cell hybrid configurations.
Established qualification pathways serve battery electric vehicles. Emerging validation efforts target plug-in hybrid architectures.
Application:
Payload sensitivity creates divergent demand profiles across vehicle mass classes.
- Passenger Vehicles:Light-duty platforms prioritize range extension and cabin space preservation.
- Commercial Vehicles:Freight operators seek weight reductions to maximize cargo capacity within axle load limits.
- Two-Wheelers:Compact powertrains in urban mobility segments value energy density for range-to-weight ratios.
- Electric Buses:Municipal fleet procurement in South Korea is specifying lithium-sulfur cells for weight-sensitive routes requiring extended range and reduced curb weight to accommodate passenger loads.
Volume deployment concentrates in passenger vehicles. Steepest expansion trajectory appears in electric bus procurement.
Industry Vertical:
Supply chain position determines margin capture and qualification burden.
- OEMs:Vehicle manufacturers are consolidating supplier relationships around vertically integrated cell producers capable of certifying carbon intensity across raw material extraction. Direct OEM-cell maker contracting is displacing traditional tier-2 module assembly relationships in heavy-duty applications.
- Aftermarket Providers:Replacement and retrofit services address legacy fleet conversions.
- Tier-1 Suppliers:System integrators manage pack assembly and battery management system integration.
- Vehicle Assemblers:Contract manufacturers without captive cell supply rely on external qualification pathways.
Margin concentration favors OEMs. Aftermarket channels represent emerging volume opportunity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free Trade Zones in South Korea's Incheon and Busan regions are concentrating cell qualification activities for municipal electric bus procurement, while China's MIIT subsidy framework anchors manufacturing scale decisions for automotive lithium-sulfur systems.
South Korea
Municipal transit authorities in Seoul and Busan are specifying lithium-sulfur cells for weight-sensitive electric bus routes requiring extended range. The Ministry of Trade, Industry and Energy (MOTIE) administers production-linked incentives for advanced chemistry cell manufacturing. The Busan-Ulsan industrial corridor hosts prototype validation facilities where tier-1 suppliers test pouch cell configurations for commercial vehicle integration.
Germany
Automotive OEMs in Stuttgart and Munich are concentrating procurement for high-energy-density pouch configurations in premium electric vehicle platforms. The EU Battery Regulation's carbon-footprint thresholds are compressing qualification timelines for cell suppliers before the 2027 enforcement window. The Baden-Württemberg battery cluster is validating sulfurized polyacrylonitrile cathodes under accelerated cycle protocols for commercial vehicle segments.
China
Domestic OEMs are responding to MIIT's new-energy-vehicle subsidy framework and GB standards for battery safety testing. The Yangtze River Delta region, spanning Shanghai and Jiangsu province, concentrates pilot production lines for lithium metal anode processing. Shenzhen-based equipment vendors are adapting high-speed winding machinery for cylindrical lithium-sulfur cell formats.
United States
EPA tailpipe emission standards are tightening fleet-average CO2 obligations for light-duty manufacturers in California and the Northeast corridor. The Inflation Reduction Act's domestic content provisions are reshaping cell manufacturing location decisions for North American vehicle platforms. Arizona and Nevada are attracting pilot facilities for solid-state electrolyte architecture development.
India
The Production Linked Incentive (PLI) scheme for advanced chemistry cells is attracting sulfur cathode process technology transfers to domestic manufacturing. Gujarat and Tamil Nadu are establishing special economic zones for cell component fabrication. The Delhi-NCR transit authority is evaluating lithium-sulfur packs for electric bus fleet expansion under the Faster Adoption and Manufacturing of Electric Vehicles (FAME) program.
Automotive Lithium-Sulfur Battery Market Competitive Environment
Top-tier vendors anchor the qualification-intensive OEM supply tier, while mid-scale specialists occupy process technology niches. The competitive structure fragments across solid-state electrolyte developers, metallic lithium anode innovators, and pouch cell integrators. Three archetypes dominate: vertically integrated chemical conglomerates, venture-backed solid-state specialists, and contract research organizations with pilot manufacturing capabilities. Capacity expansion and strategic partnerships constitute the dominant competitive moves as suppliers position for 2027 regulatory enforcement windows.
Within the solid-state electrolyte tier, Sion Power Corporation and Lyten, Inc. exemplify venture-backed specialists pursuing polymer-ceramic hybrid architectures for long-cycle-life designs. LG Energy Solutions Ltd. represents the integrated conglomerate archetype with extensive manufacturing scale across Asian and European production nodes. Zeta Energy LLC occupies a position among metallic lithium anode innovators addressing dendrite suppression in high-load applications. These three anchors illustrate how competitive positioning stratifies across technology specialization vectors rather than geographic concentration alone.
| Leading Market Players |
|---|
| Sion Power Corporation |
| PolyPlus Battery Company |
| NexTech Batteries Inc. |
| Li-S Energy Limited |
| GS Yuasa Corporation |
| LG Energy Solutions Ltd. |
| Zeta Energy LLC |
| Lyten, Inc. |
| Giner, Inc. |
| Others |
Value Chain & Pricing Dynamics
Electrolyte formulation chemists clustered in Germany's Baden-Württemberg battery corridor command wage premiums that compress margin structures for mid-tier cell producers, widening spreads between premium solid-state configurations and commodity pouch formats sourced from Asian manufacturing nodes.
Pricing Analysis
Short lead-time premiums dominate contract negotiations as OEMs accelerate qualification timelines ahead of EU Battery Regulation enforcement. Pricing stratifies across premium solid-state architectures, standard polymer-ceramic hybrids, and economy liquid-electrolyte prototypes differentiated by cycle-life certification. Cost compression in liquid-electrolyte tiers intensifies because fluoroethylene carbonate solvent volatility feeds raw material uncertainty. Municipal fleet operators exhibit highest price sensitivity due to public procurement constraints, while German premium OEMs absorb premiums for carbon-footprint documentation.
Supply Chain Analysis
Regional distribution centers in South Korea's Busan-Ulsan corridor and China's Yangtze River Delta manage hub-and-spoke patterns for lithium metal anode feedstocks. Primary supply draws from Argentina and Chile for metallic lithium, Germany and South Korea for separator membranes, and China for sulfur cathode precursors. Single-source vulnerability concentrates in lithium metal refining capacity. Distribution runs through tier-1 cell integrators with captive module assembly, displacing traditional tier-2 relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Battery Regulation's carbon-footprint thresholds erect a cost-of-compliance moat that advantages incumbent cell producers with established supply chain transparency documentation, while marginalizing speculative entrants lacking qualified manufacturing footprints.
For Market Incumbents: Lock in long-term offtake agreements with municipal electric bus operators before 2027 qualification windows close. Secure backward integration into sulfur cathode refining through partnerships with European REACH-compliant feedstock suppliers. Solid-state electrolyte patent portfolios represent the critical defensive lever against venture-backed specialists threatening cycle-life performance claims. For New Entrants and Emerging Players: Launch via direct OEM contracting models targeting India's PLI scheme manufacturing incentives for advanced chemistry cells. India's Gujarat and Tamil Nadu special economic zones offer the most penetrable geography given nascent domestic competition and favorable duty structures. Position around metallic lithium anode innovations with dendrite suppression claims validated under accelerated UN 38.3 protocols. For Investors and Strategic Acquirers: Re-rating potential sits with solid-state electrolyte specialists given polymer-ceramic hybrid maturation as the catalyst for commercial vehicle warranty terms. Long-term viability favors venture-backed developers with pilot manufacturing capabilities rather than pure research-stage entities. Watch for tier-1 supplier procurement commitments to Sion Power Corporation or comparable anchors as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Solid-State Electrolyte Scale-Up | Polymer-ceramic hybrid architectures suppress polysulfide shuttle effects for commercial vehicle integration. |
| REACH-Compliant Sulfur Sourcing | ECHA substance evaluation frameworks secure OEM qualification pathways under EU Battery Regulation thresholds. |
| Lithium Metal Anode Processing | Argentina and Chile feedstock control addresses geopolitical exposure in high-load automotive applications. |
| Dry Electrode Coating Investment | Solvent-free cathode manufacturing reduces electrolyte solvent cost volatility compression on margins. |
| Electric Bus Fleet Partnerships | Seoul and Busan municipal procurement anchors volume commitments for weight-sensitive route specifications. |
Study Parameters
SEC filings, ECHA substance registration databases, and MIIT new-energy-vehicle subsidy disclosures formed the secondary backbone, supplemented by customs records tracking lithium metal trade flows. Primary interviews with OEM platform engineers, tier-1 supplier procurement leads, solid-state electrolyte R&D directors, and municipal fleet procurement officers validated demand assumptions. Bottom-up cell production capacity estimates triangulated against top-down vehicle platform electrification targets across the analysis window.
Historical trendline analysis of lithium-sulfur prototype deployments informed penetration rate assumptions across battery electric vehicle, plug-in hybrid, and electric bus segments. The analytical framework modeled vehicle class, propulsion architecture, cell form factor, and regional regulatory cluster dimensions throughout the forecast period. CAGRs derived from segment-level volume builds incorporating EPA tailpipe standard compliance timelines and EU Battery Regulation enforcement phases.
Electrolyte chemistry pivots, carbon-border adjustment mechanism implementations, and lithium metal supply disruptions are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding solid-state maturation timelines and regulatory enforcement consistency. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Lithium Cobalt Oxide Market
Lithium-ion Battery
Lithium-Ion Stationary Battery Storage Market
Lithium-ion Battery
Global Pin Type Lithium-Based Battery Market
Lithium-ion Battery
Lithium-Ion (Li-Ion) Batteries Market
Lithium-ion Battery
Canada Electric Vehicle Battery Anode Market
Lithium-ion Battery
Graphene Battery Technology Market
Lithium-ion Battery
Lithium Cobalt Oxide Battery (LCO) Market
Lithium-ion Battery
Salt Lake Battery Grade Lithium Carbonate Market
Lithium-ion Battery
Liquid Lithium Ion Battery Market
Lithium-ion Battery
Asia Pacific Electric Vehicle Battery Materials Market
Lithium-ion Battery
Lithium Polymer Battery Market
Lithium-ion Battery
Lithium Manganate Battery Market
Lithium-ion Battery
Italy Electric Vehicle Battery Materials Market
Lithium-ion Battery
Consumer Lithium-Ion Battery Market
Lithium-ion Battery
France Lithium-Ion Battery for Electric Vehicle Market
Lithium-ion Battery
Europe Electric Vehicle Battery Anode Market