
 Lithium-Ion Battery Materials Market | 2026-2036
Lithium-Ion Battery Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Lithium-Ion Battery Materials Market Outlook
The split between premium battery grade cathode powders and commodity industrial grade intermediates is realigning procurement strategies across the value chain. Umicore leverages its European precursor network to sustain high-purity cobalt and nickel sulfate output for European automakers. Posco Future M anchors South Korean cathode production through integrated refining partnerships, while Sumitomo Chemical differentiates via advanced electrolyte formulations for high-voltage cells.
Lithium-ion battery materials encompass the active and passive chemical constituents—cathode compounds such as NMC and LFP with specific energy densities exceeding 250 Wh/kg, graphite and silicon-composite anodes, lithium salt electrolytes, and microporous polyolefin separators—that enable reversible electrochemical energy storage in rechargeable cells. Cathode materials command the largest value share given nickel and cobalt feedstock intensity, while anode materials compete on silicon doping ratios that boost capacity beyond conventional graphite limits. Battery grade specifications dominate procurement as electric vehicle applications enforce tight particle size distributions and impurity thresholds.
China's SAMR enforces GB standards on cell safety and material traceability, while the EU Battery Regulation mandates recycled content quotas and carbon footprint declarations that reshape supplier qualification. The US IRA domestic content rules redirect cathode precursor sourcing toward North American refining partnerships. Stakeholders must monitor how regulatory divergence in chemical purity standards and origin requirements affects tolling arrangements and long-term offtake contracts.
Market Dynamics
The battery materials sector is restructuring around cathode chemistry transitions, with high-nickel formulations displacing legacy cobalt-heavy compositions as automakers pursue energy density targets above 300 Wh/kg.
Growth Catalysts
- EU Battery Regulation recycled content mandates:The regulation's 2030 recycled lithium and cobalt quotas are forcing closed-loop partnerships between automakers and hydrometallurgical refiners.
- Silicon-anode doping ratios:Silicon-composite anodes with 10-15% silicon content are expanding cell capacity beyond graphite limits, pulling demand for advanced binder chemistries and electrolyte additives.
- Jiangsu-Fujian supply corridor:Integrated precursor-to-cell production clusters in these provinces are compressing logistics costs and qualification timelines for cathode active materials.
Market Restraints
- Class 1 nickel supply concentration:Battery-grade nickel sulfate production concentrates in Indonesian HPAL operations and Russian Norilsk feedstock, creating single-source vulnerability for European cathode makers.
- Lithium carbonate price volatility:Spot market swings in Qinghai and Salar de Atacama production zones are compressing margin predictability for mid-tier cathode producers without offtake hedges.
- Water-intensive refining:Nickel laterite processing via HPAL requires 40-60 cubic meters per ton of contained nickel, exposing operations to water stress in Sulawesi and Halmahera basins.
Strategic Opportunities
- US IRA domestic content bonus credits:The $35/kWh cell production credit and $10/kWh module credit are redirecting cathode precursor investments toward North American refining joint ventures.
- Stationary storage LFP pivot:Grid-scale battery deployments are accelerating demand for lithium iron phosphate cathodes, opening capacity absorption for producers sidelined from premium EV chemistry tiers.
- Direct recycling hydrometallurgy:Black mass processing technologies that preserve cathode crystal structure are enabling lower-carbon material recovery compared to conventional pyrometallurgical routes.
Industry Challenges
- Qualified materials engineer scarcity:The talent pool for solid-state electrolyte development and high-nickel cathode doping optimization remains concentrated at a handful of national laboratories and tier-one cell producers.
- GB standard certification timelines:China's SAMR enforcement of updated cell safety and traceability protocols is extending qualification cycles for imported cathode materials by 8-14 months.
- IP fragmentation across solid-state patents:Oxide, sulfide, and polymer electrolyte approaches are locked behind competing university and corporate patent thickets, complicating licensing strategies for commercial scale-up.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lithium-Ion Battery Materials Market |
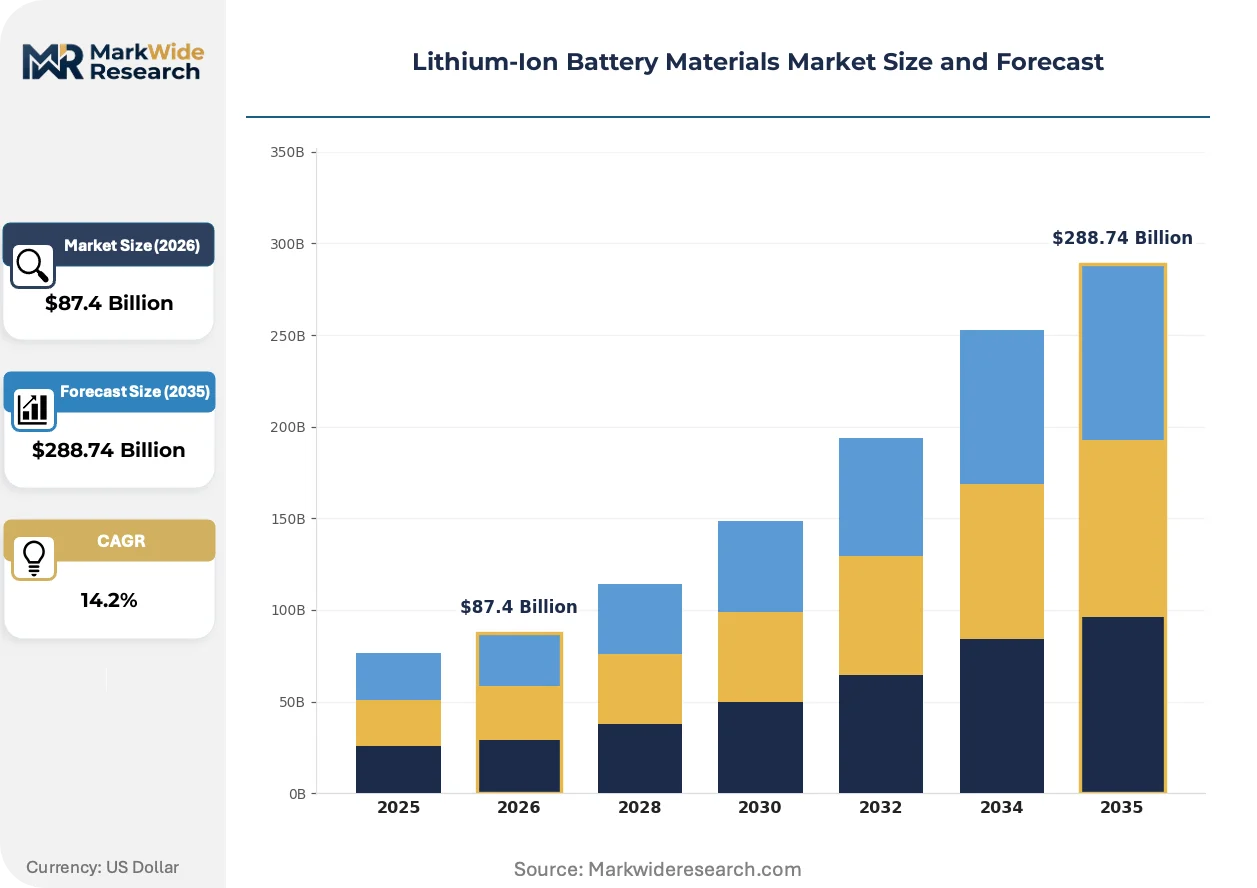
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $288.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cathode Materials, Anode Materials, Electrolytes, Separators Grade: Industrial Grade, Electronic Grade, Battery Grade, Pharmaceutical Grade Application: Electric Vehicles, Consumer Electronics, Energy Storage Systems, Power Tools Delivery Mode: Direct Shipping, Distribution Centers, Online Retail, Bulk Delivery |
| Companies Covered | Samsung SDI, Umicore, Contemporary Amperex Technology Co., Limited (CATL), Posco Future M, Sumitomo Chemical, BYD Company Ltd., Panasonic Holdings Corporation, Alberta Innovates, LG Chem, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lithium-Ion Battery Materials Market Strategic Shifts
Materials innovation is compressing the traditional cathode-anode-separator value chain, with new synthesis methods and regulatory traceability requirements forcing simultaneous adaptation across multiple process steps.
Single-crystal NMC cathode production is decentralizing the conventional polycrystalline supply base. Cell manufacturers in South Korea and Japan are adopting these structures for their superior mechanical stability under high-voltage cycling. The shift is compressing demand for conventional co-precipitated powders and elevating tolling fees for specialty crystallization equipment.
REACH substance-of-very-high-concern listings for nickel compounds are tightening occupational exposure protocols across European precursor facilities. The ECHA regulatory pressure is accelerating automation investments in powder handling and packaging operations. Cathode producers with legacy open-air processing lines in Poland and Finland face capital-intensive retrofit timelines to maintain market access.
Automaker direct contracting with cathode plants is displacing traditional trading house intermediaries in spot lithium and cobalt markets. Tier-one EV manufacturers in Germany and Sweden are establishing multi-year offtake agreements with named production lines rather than commodity pools. This concentration of buying power is most visible in binding supply agreements for high-nickel NMC 811 and NCA chemistries.
Lithium-Ion Battery Materials Market Segmentation
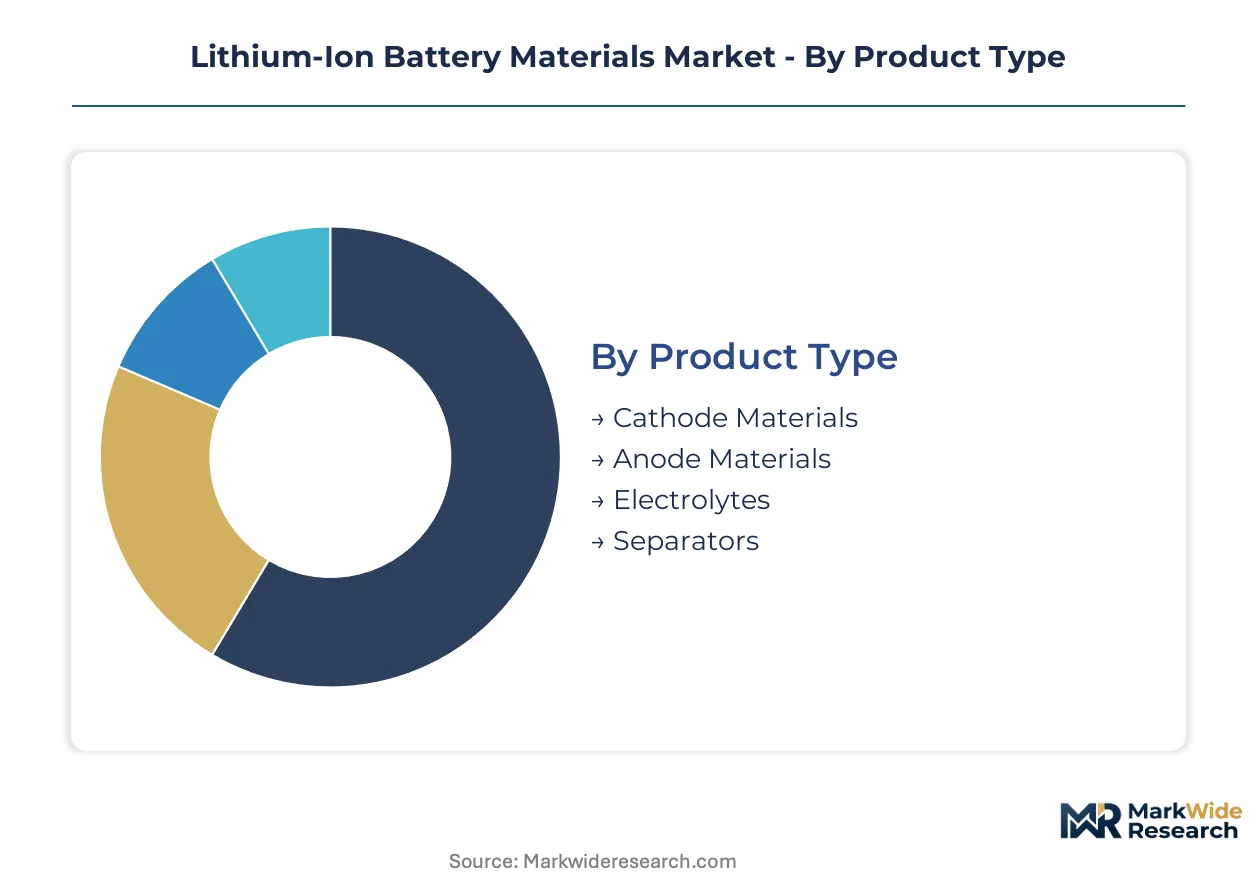
Segmentation in battery materials reveals how cathode chemistry choices cascade through grade specifications and delivery logistics. Procurement strategies diverge sharply between automakers demanding battery-grade traceability and industrial buyers tolerating wider purity bands.
Product Type:
Cathode materials operate as standalone high-value inputs requiring precise precursor integration, while electrolytes and separators embed as functional layers within cell architecture.
- Cathode Materials:NMC and LFP compounds dominate formulations, with nickel-cobalt-manganese ratios shifting toward high-nickel variants for energy density above 250 Wh/kg. Demand clusters in Jiangsu and Fujian provinces where CATL and BYD anchor integrated precursor-to-cell corridors, compressing logistics costs and qualification timelines under China's GB standards.
- Anode Materials:Graphite remains the baseline, though silicon-composite formulations with 10-15% silicon content are expanding capacity beyond conventional limits. South Korean and Japanese cell manufacturers are pulling these advanced anodes for high-voltage cycling applications, elevating tolling fees for specialty binder chemistries.
- Electrolytes:Lithium salt solutions enable ionic transport between electrodes, with high-voltage additives commanding premium formulations from Sumitomo Chemical and Ube Industries.
- Separators:Microporous polyolefin membranes provide physical isolation while permitting ion passage, with ceramic-coated variants gaining traction for thermal stability in automotive packs.
Cathode materials lead volumes today; anode materials are gaining share fastest as silicon doping ratios climb.
Grade:
Grade stratification reflects end-use tolerance for impurities, with battery-grade specifications enforcing tight particle size distributions that industrial grades cannot satisfy.
- Industrial Grade:Intermediate precursors and commodity chemicals with wider impurity bands serve non-automotive applications where electrochemical performance tolerances relax.
- Electronic Grade:Purified inputs meet semiconductor and capacitor manufacturing standards, with trace metal specifications stricter than industrial but looser than battery-grade thresholds.
- Battery Grade:Cathode active materials and electrolyte salts comply with automaker particle size and impurity protocols, with China's SAMR and the EU Battery Regulation tightening traceability mandates that extend qualification cycles for imported materials.
- Pharmaceutical Grade:Ultra-high purity lithium compounds serve medical device batteries and pharmaceutical synthesis, with production volumes dwarfed by industrial and battery-grade tiers.
Battery grade dominates revenue concentration; electronic grade is expanding most quickly as solid-state development pulls specialized precursor demand.
Application:
Application segmentation tracks how energy density requirements and duty cycle intensity reshape chemistry selection across mobility and stationary use cases.
- Electric Vehicles:High-nickel NMC 811 and NCA chemistries pursue energy density targets above 300 Wh/kg, with German and Swedish automakers establishing multi-year offtake agreements with named cathode production lines rather than commodity pools.
- Consumer Electronics:Cobalt-heavy LCO cathodes persist in smartphones and laptops where compact form factors prioritize energy density over material cost, though NMC blends are displacing legacy formulations in tablets and wearables.
- Energy Storage Systems:Grid-scale deployments are accelerating demand for lithium iron phosphate cathodes, opening capacity absorption for producers sidelined from premium EV chemistry tiers.
- Power Tools:Cylindrical cell formats with nickel-manganese-cobalt blends balance discharge rate capability with thermal management in cordless equipment.
Electric vehicles anchor volume today; energy storage systems are climbing the fastest as LFP pivot accelerates.
Delivery Mode:
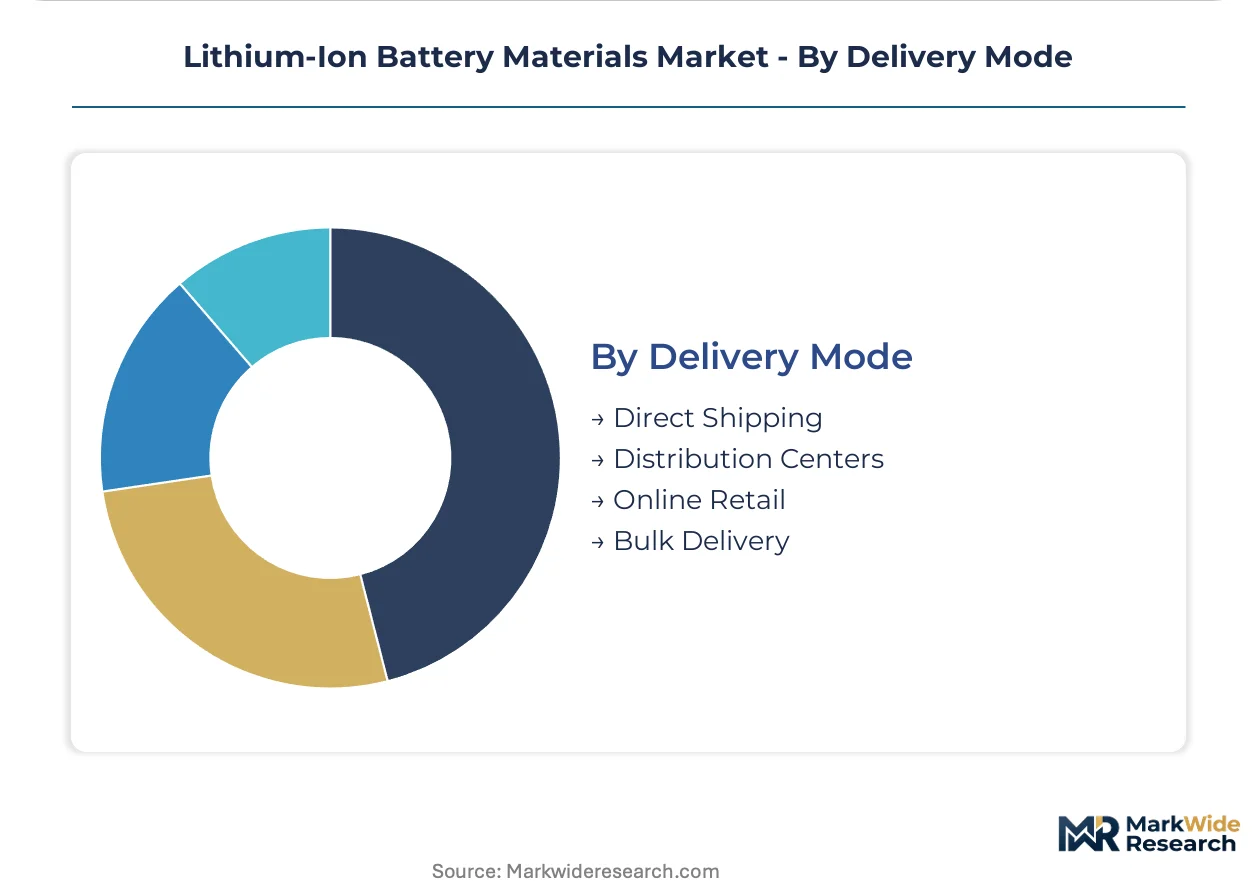
Delivery configuration reflects customer scale and inventory velocity, with bulk arrangements dominating cathode precursor flows and parcel logistics serving fragmented anode and electrolyte demand.
- Direct Shipping:Automakers and tier-one cell producers receive cathode active materials via dedicated logistics to named production lines, with binding contracts specifying lot traceability under EU Battery Regulation carbon footprint declarations.
- Distribution Centers:Regional warehousing in Rotterdam and Singapore buffers supply for European and Southeast Asian cell plants, compressing lead times for qualified materials.
- Online Retail:Specialty electrolyte additives and separator samples move through digital channels for R&D procurement and small-batch cell prototyping.
- Bulk Delivery:Graphite anodes and lithium carbonate ship via containerized bulk to precursor synthesis facilities in China and South Korea.
Direct shipping leads volumes today; distribution centers are gaining share fastest as regional qualification hubs multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Materials engineers and electrochemists concentrate in China's Jiangsu-Fujian corridor, South Korea's Gyeonggi battery belt, and Germany's Rhine-Ruhr chemical complex, anchoring regional production capabilities.
China
CATL and BYD drive cathode precursor demand through integrated Jiangsu-Fujian supply chains. SAMR enforces updated GB standards on cell safety and material traceability. Xiamen and Ningde host the densest concentration of qualified precursor synthesis facilities serving domestic automakers.
South Korea
Posco Future M and LG Chem anchor high-nickel cathode production for European EV exports. The national industrial regulator coordinates with MFDS on battery-grade chemical specifications. Gyeonggi Province clusters precursor refining with Pohang steelworks supplying nickel sulfate feedstock.
Japan
Panasonic and Sumitomo Chemical pull advanced electrolyte formulations for high-voltage silicon-anode cells. METI coordinates national battery supply chain resilience initiatives. Osaka-Kobe chemical complexes concentrate specialty additive production for next-generation cell architectures.
Germany
BMW and Volkswagen establish multi-year cathode offtake agreements with named production lines. ECHA REACH substance-of-very-high-concern listings tighten nickel compound handling protocols. North Rhine-Westphalia's Leverkusen and Dormagen sites retrofit powder handling automation for regulatory compliance.
United States
IRA domestic content bonus credits redirect precursor investments toward North American refining joint ventures. EPA and NHTSA coordinate on battery material lifecycle standards. Michigan and Tennessee anchor emerging cathode qualification hubs serving Detroit automakers.
Lithium-Ion Battery Materials Market Competitive Environment
Top-tier vendors anchor integrated precursor-to-cell supply chains, while mid-tier specialists occupy tolling and formulation niches. The market structure concentrates cathode active material production among Asian integrated chemical-electronics conglomerates and European automotive supply specialists. Three archetypes dominate: integrated battery manufacturers with captive material production, independent cathode specialists serving multiple cell customers, and diversified chemical companies pivoting from industrial to battery-grade specifications. Competitive moves center on backward integration into nickel and lithium refining, plus regional qualification hub establishment under divergent regulatory regimes.
Within the integrated manufacturer tier, Contemporary Amperex Technology Co., Limited and BYD Company Ltd. exemplify the captive supply archetype through in-house precursor synthesis. Umicore occupies a position bridging European automotive qualification requirements with hydrometallurgical refining partnerships. Samsung SDI represents the diversified electronics-chemical conglomerate model, spanning cell assembly and materials development. These three anchors demonstrate how geographic regulatory alignment—China's GB standards, EU Battery Regulation, South Korea's MFDS coordination—shapes competitive positioning without requiring identical structural approaches.
| Leading Market Players |
|---|
| Samsung SDI |
| Umicore |
| Contemporary Amperex Technology Co., Limited (CATL) |
| Posco Future M |
| Sumitomo Chemical |
| BYD Company Ltd. |
| Panasonic Holdings Corporation |
| Alberta Innovates |
| LG Chem |
| Others |
Value Chain & Pricing Dynamics
Automaker direct contracting for high-nickel NMC 811 and NCA cathodes is compressing spot market liquidity and forcing suppliers toward long-term offtake structures with fixed-volume, variable-price mechanisms indexed to London Metal Exchange nickel and Qinghai lithium carbonate benchmarks.
Pricing Analysis
Contract-based long-term offtake agreements dominate cathode active material transactions, with pricing stratifying across battery-grade, electronic-grade, and industrial-grade purity tiers. Price differentiation hinges on particle size distribution compliance under China's GB standards and EU Battery Regulation carbon footprint declarations. Pricing pressure stems from lithium carbonate spot volatility in Salar de Atacama and Qinghai production zones. Mid-tier cathode producers without hedged offtake arrangements exhibit highest price sensitivity; integrated manufacturers with captive precursor synthesis maintain lowest sensitivity.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale automaker demand for qualified cathode materials, with distribution running through regional qualification hubs in Rotterdam and Singapore. Supply concentrates in China, South Korea, and Japan where CATL, Posco Future M, and Panasonic anchor integrated precursor-to-cell corridors. Raw material dependencies center on Indonesian HPAL nickel sulfate, Chilean lithium carbonate, and synthetic graphite from China's Heilongjiang province. Single-source vulnerability in Class 1 nickel sulfate from Indonesian HPAL operations and Russian Norilsk feedstock constitutes the primary structural risk.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where US IRA domestic content credits and EU Battery Regulation recycled content mandates create divergent cost structures that reward North American and European refining investments over Asian commodity exports.
For Market Incumbents: Hedge against lithium carbonate price volatility through backward integration into Australian and Chilean spodumene and brine assets. Secure qualified materials engineering talent pools concentrated at South Korean national laboratories and Japanese tier-one cell producers. Automaker consolidation of buying power through direct cathode plant contracting threatens trading house margins; defend via exclusive tolling arrangements with named production lines. For New Entrants and Emerging Players: Enter via stationary storage LFP cathode production where grid-scale deployments absorb capacity outside premium EV chemistry tiers. Target North American refining joint ventures qualifying for IRA domestic content bonus credits. White-space exists in direct recycling hydrometallurgy preserving cathode crystal structure; establish partnerships with European automakers facing EU Battery Regulation recycled content quotas. For Investors and Strategic Acquirers: Asymmetric upside sits with hydrometallurgical refiners enabling closed-loop partnerships under EU Battery Regulation recycled lithium and cobalt mandates. Long-term viability favors specialists with proven qualification timelines under China's SAMR GB standards and ECHA REACH nickel compound protocols. Monitor silicon-anode doping ratio adoption by South Korean and Japanese cell manufacturers as inflection indicator for advanced binder chemistry demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lithium Refining | Australian spodumene and Chilean brine assets anchor IRA-compliant supply chains for US cathode producers. |
| Long-term Cathode Offtake Agreement | German and Swedish automakers bind named production lines to secure battery-grade material traceability under EU Battery Regulation. |
| Joint Venture for North American Precursor Production | Michigan and Tennessee qualification hubs leverage IRA credits to redirect cathode supply from Jiangsu-Fujian corridors. |
| Green Manufacturing Transition | HPAL water stress in Sulawesi and Halmahera basins drives automation investment and closed-loop recycling adoption. |
| Technology Licensing for Solid-State Electrolyte | Oxide, sulfide, and polymer patent thickets from Japanese chemical conglomerates complicate commercial scale-up licensing strategies. |
Study Parameters
Coverage spans China, South Korea, Japan, Germany, and the United States, with primary inputs from each market. Primary research combined interviews with cathode plant managers, automaker procurement leads, hydrometallurgical refinery operators, and battery-grade chemical distribution channel partners. Secondary validation drew from customs and trade data, SEC 10-K filings, SAMR GB standard documentation, ECHA REACH substance registrations, and IEA critical mineral supply chain reports. Bottom-up cathode active material volume estimates triangulated against top-down electric vehicle production forecasts.
Granularity-level modeling deployed cathode chemistry splits, grade specifications, application segments across electric vehicles and energy storage systems, and delivery mode configurations. CAGRs derived from weighted average of regional production growth trajectories and chemistry-specific adoption curves across the analysis window. Industry-specific forecast inputs incorporated silicon-anode doping ratio penetration curves and EU Battery Regulation recycled content quota compliance timelines.
Inputs from SAMR certification databases and ECHA REACH filings were available through the study window; gaps in real-time HPAL nickel sulfate production data from Indonesian operations introduce uncertainty bands around Class 1 nickel supply assumptions. Forecasts reflect base-case assumptions regarding GB standard enforcement timelines and IRA domestic content rule finalization. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Lithium Battery in Myanmar Market
Lithium-ion Battery
South America Electric Vehicle Battery Electrolyte Market
Lithium-ion Battery
North America Lithium-Ion Battery Separator Market
Lithium-ion Battery
Marine Lithium-Ion Battery Market
Lithium-ion Battery
North America Lithium-Ion Battery Market
Lithium-ion Battery
Lithium-Ion Forklift Battery Market
Lithium-ion Battery
Global Nanowire Battery Market
Lithium-ion Battery
Tanktwo String Cell Battery Market
Lithium-ion Battery
Lithium Iodide Market
Lithium-ion Battery
Lithium Nickel Manganese Cobalt Oxide Battery Market
Lithium-ion Battery
Automotive Lithium Ion Battery Market
Lithium-ion Battery
Lithium Battery Cells for Passenger Car Market
Lithium-ion Battery
Global Lithium-Ion Battery Energy Storage System Market
Lithium-ion Battery
Pouch Lithium-Ion Batteries Market
Lithium-ion Battery
Europe Solid State Battery Market
Lithium-ion Battery
Germany Electric Vehicle Battery Materials Market