
 Nanotechnology Enabled Battery Market | 2026-2036
Nanotechnology Enabled Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Nanotechnology Enabled Battery Market Insights
Multi-source cathode material procurement is recalibrating supply chain risk profiles across the Nanotechnology Enabled Battery industry. Samsung SDI leverages in-house solid-state electrolyte development to reduce external dependency. LG Energy Solution anchors high-nickel cathode production through captive precursor plants in South Korea. Amprius Technologies specializes in silicon-nanowire anodes for aviation and defense applications.
Nanotechnology enabled batteries integrate engineered nanomaterials such as silicon nanowires, graphene composites, and solid-state ceramic electrolytes to achieve energy densities exceeding conventional lithium-ion architectures by 40-70%. These systems primarily serve electric mobility and grid-scale storage where weight reduction and cycle stability determine commercial viability. Solid state batteries occupy the premium tier due to manufacturing complexity and safety certification requirements, while lithium-ion variants sustain volume leadership through established gigafactory infrastructure. Electric vehicles command the dominant application share, though medical devices represent a concentrated margin pool where miniaturization justifies unit cost premiums.
The US Department of Transportation through NHTSA enforces battery thermal runaway standards that shape pack architecture and material selection for automotive suppliers. China's SAMR and GB standards mandate cell-level traceability, forcing manufacturers to restructure quality systems for market access. South Korea's METI-aligned industrial policy directs subsidy allocation toward domestic cathode-anode integration. Stakeholders must monitor regulatory divergence between jurisdictions as compliance costs fragment competitive positioning across export markets.
Market Dynamics
Solid-state electrolyte manufacturing complexity is compressing commercialization timelines and forcing cathode-anode integration decisions across the Nanotechnology Enabled Battery industry.
Growth Catalysts
- Aviation electrification mandates:Regional jet and eVTOL airframe builders are qualifying silicon-nanowire cells for weight-critical propulsion systems, bypassing conventional lithium-ion energy density ceilings.
- South Korea's METI-aligned industrial policy:Subsidy allocation now prioritizes domestic precursor integration, accelerating captive cathode production around Ulsan and Gumi industrial clusters.
- EU F-Gas Regulation phase-down:Fluorinated electrolyte restrictions are accelerating solid-state ceramic electrolyte pilot lines as manufacturers retool for compliance.
Market Restraints
- Silicon feedstock price volatility:Metallurgical-grade silicon spot markets swing with photovoltaic demand cycles, squeezing anode material margins.
- South Korean cathode precursor concentration:Three domestic suppliers control high-nickel precursor output, creating single-source vulnerability for European cell builders.
- Dry electrode coating technical immaturity:Solvent-free manufacturing remains below commercial yield thresholds, constraining solid-state cost reduction.
Strategic Opportunities
- India PLI scheme for advanced chemistry cells:Production-linked incentives for gigafactory investment are opening access to price-sensitive two-wheeler and three-wheeler electrification.
- Medical implant miniaturization:Neurostimulation and continuous glucose monitoring devices require sub-gram power sources where silicon-anode energy density commands 40-60% unit premiums.
- Solid-state and silicon-anode convergence:Hybrid architectures combining ceramic electrolytes with nanowire anodes are unlocking aviation certification pathways unavailable to either technology alone.
Industry Challenges
- Cell-level traceability system implementation:China's SAMR and GB standards mandate lot-level tracking from precursor to pack, forcing quality system overhauls for market access.
- Multiphysics simulation talent scarcity:Solid-state ionic conductivity modeling requires electrochemistry and materials science cross-training unavailable in conventional battery engineering pipelines.
- Thermal runaway certification timeline compression:US NHTSA testing protocols now require 30-minute propagation resistance, extending validation cycles for new chemistries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nanotechnology Enabled Battery Market |
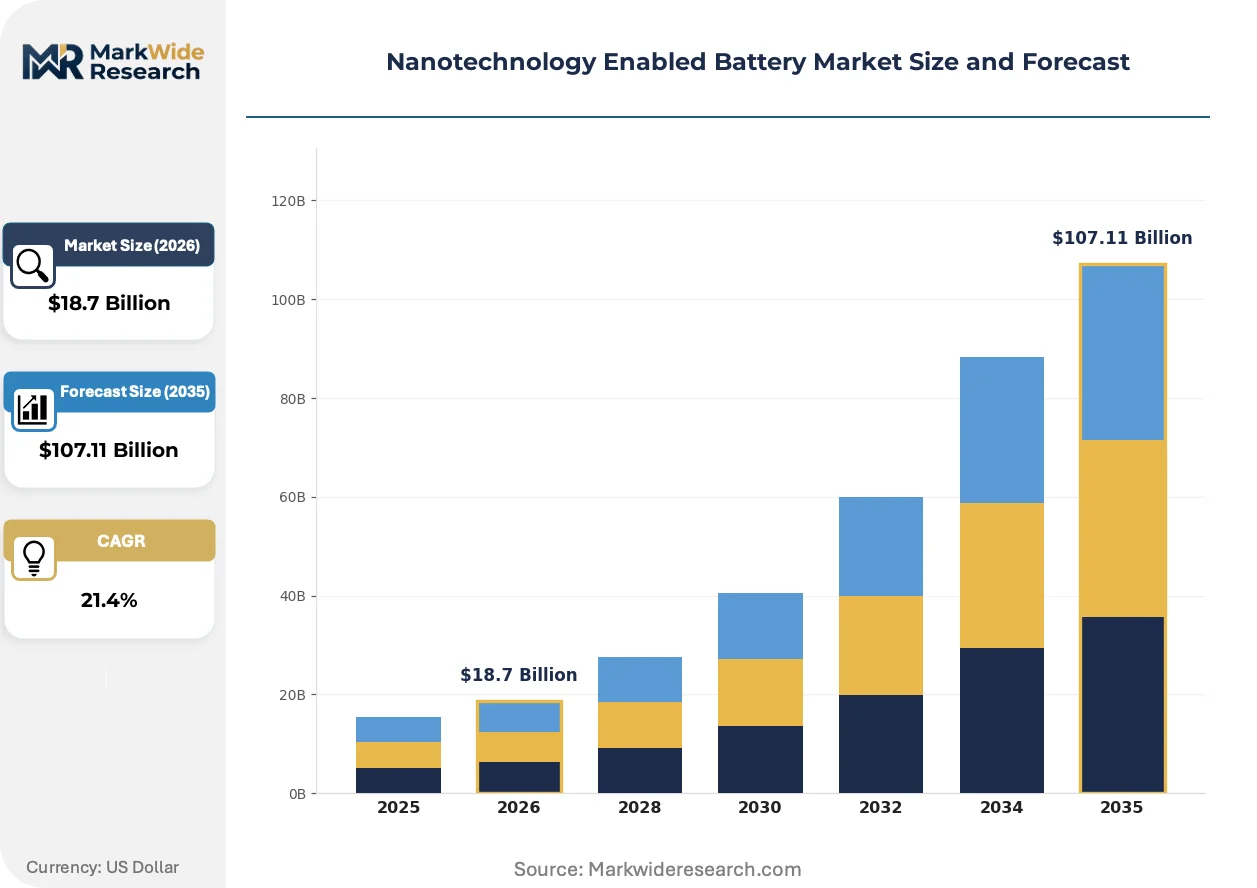
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $107.11 Billion |
| CAGR (2026 – 2036) | 21.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-ion Batteries, Solid State Batteries, Nano-Composite Batteries, Lithium Polymer Batteries End User: Automotive, Consumer Electronics, Renewable Energy, Industrial Applications Technology: Electrochemical, Nano-Coating, 3D Printing, Hybrid Technology Application: Electric Vehicles, Portable Devices, Grid Storage, Medical Devices |
| Companies Covered | Samsung SDI, LG Energy Solution, Panasonic Corporation, Amprius Technologies, QuantumScape, Sila Nanotechnologies, Enevate Corporation, Nanotech Energy, Nexeon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nanotechnology Enabled Battery Market Trends and Innovations
Solid-state manufacturing scale-up and silicon-anode integration are converging to redefine performance benchmarks and supplier qualification criteria across electric mobility applications.
Silicon-nanowire anode technology is electrifying aviation battery procurement. eVTOL developers including Joby Aviation and Archer Aviation are locking multi-year supply agreements for 400 Wh/kg cell formats. This chemistry is displacing graphite-dominated supplier lists and compressing qualification timelines from 48 months to 24 months for airframe integration.
China's NMPA battery safety certification framework now mandates nail penetration and overcharge abuse testing at cell level. Domestic manufacturers must restructure testing protocols and documentation systems. Korean and Japanese exporters face parallel compliance burdens, with Samsung SDI and LG Energy Solution establishing dedicated Shanghai certification teams.
Buyer concentration among electric vehicle OEMs is consolidating cell procurement around performance-tier contracts rather than commodity spot purchasing. Long-term offtake agreements now specify energy density floors and cycle life guarantees. This shift is most visible in South Korea, where Hyundai Motor Group and Kia Corporation anchor demand through equity-linked supplier partnerships.
Nanotechnology Enabled Battery Market Segmentation
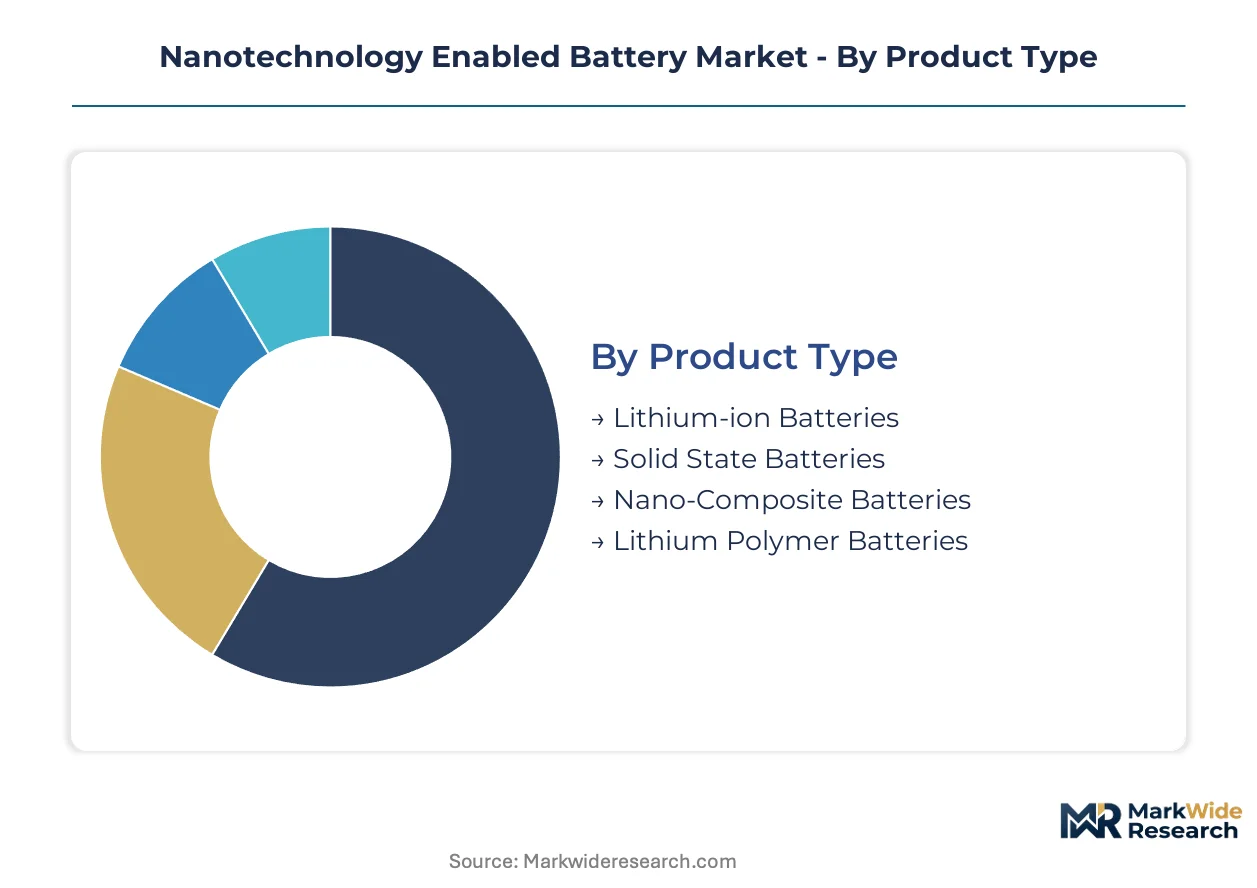
Nanotechnology enabled battery procurement splits across four intersecting dimensions. Product chemistry determines energy density ceilings and safety certification pathways. End-use concentration in electric mobility and grid storage shapes volume allocation and margin structures.
Product Type:
Buyers segment procurement by energy density requirements and thermal stability thresholds, with aviation and automotive OEMs imposing divergent qualification timelines.
- Lithium-ion Batteries:Graphite-anode architectures with liquid electrolyte systems dominate installed manufacturing capacity. Samsung SDI and LG Energy Solution anchor volume production in South Korea's Ulsan-Gumi corridor, serving Hyundai Motor Group and Kia Corporation through equity-linked supply partnerships. Volume sits with lithium-ion; growth tilts toward solid-state.
- Solid State Batteries:Ceramic electrolyte systems eliminate flammable organic solvents, enabling aviation certification pathways unavailable to liquid-electrolyte alternatives. Amprius Technologies and QuantumScape are scaling pilot lines for eVTOL and regional jet applications where 400 Wh/kg energy density floors are mandatory. Manufacturing complexity extends commercialization timelines.
- Nano-Composite Batteries:Silicon-graphene hybrid anodes integrate engineered nanomaterials for defense and medical implant applications. Sub-gram formats command unit premiums in neurostimulation devices.
- Lithium Polymer Batteries:Flexible pouch configurations serve portable electronics and drone systems where form factor adaptability outweighs cycle life requirements.
Procurement volume concentrates in lithium-ion; solid-state claims the steepest expansion trajectory as aviation electrification mandates accelerate.
End User:
Application-specific certification requirements fragment supplier qualification, with automotive thermal runaway standards diverging sharply from medical device biocompatibility protocols.
- Automotive:Electric vehicle OEMs impose 30-minute propagation resistance under US NHTSA protocols, forcing pack architecture redesigns. China's SAMR mandates cell-level traceability from precursor to pack, restructuring quality systems for market access.
- Consumer Electronics:Smartphone and laptop manufacturers prioritize cycle stability and fast-charge capability over absolute energy density, sustaining graphite-anode procurement.
- Renewable Energy:Grid-scale storage operators require 6,000+ cycle life guarantees, favoring lithium iron phosphate chemistries with nanostructured cathodes for rate capability enhancement.
- Industrial Applications:Forklift and warehouse robotics demand rapid opportunity charging, driving nano-coated electrode adoption for reduced lithium plating.
Automotive commands procurement volume; medical applications embedded within portable devices deliver concentrated margins.
Technology:
Manufacturing process selection determines capital intensity and yield rates, with dry electrode coating remaining below commercial thresholds for solid-state cost reduction.
- Electrochemical:Conventional slurry coating and calendering dominates lithium-ion production, leveraging established gigafactory infrastructure.
- Nano-Coating:Atomic layer deposition of ceramic interfaces suppresses dendrite formation in silicon-anode systems, extending cycle life for aviation applications.
- 3D Printing:Additive manufacturing of solid-state electrolyte architectures enables custom cell geometries for medical implants and micro-drones.
- Hybrid Technology:Combined electrochemical-nano-coating processes are piloting at Samsung SDI for next-generation solid-state integration.
Electrochemical processes retain volume leadership; nano-coating gains share fastest as silicon-anode adoption accelerates.
Application:
Weight-critical propulsion systems and miniaturized medical devices create dual premium tiers, with electric vehicles anchoring aggregate demand.
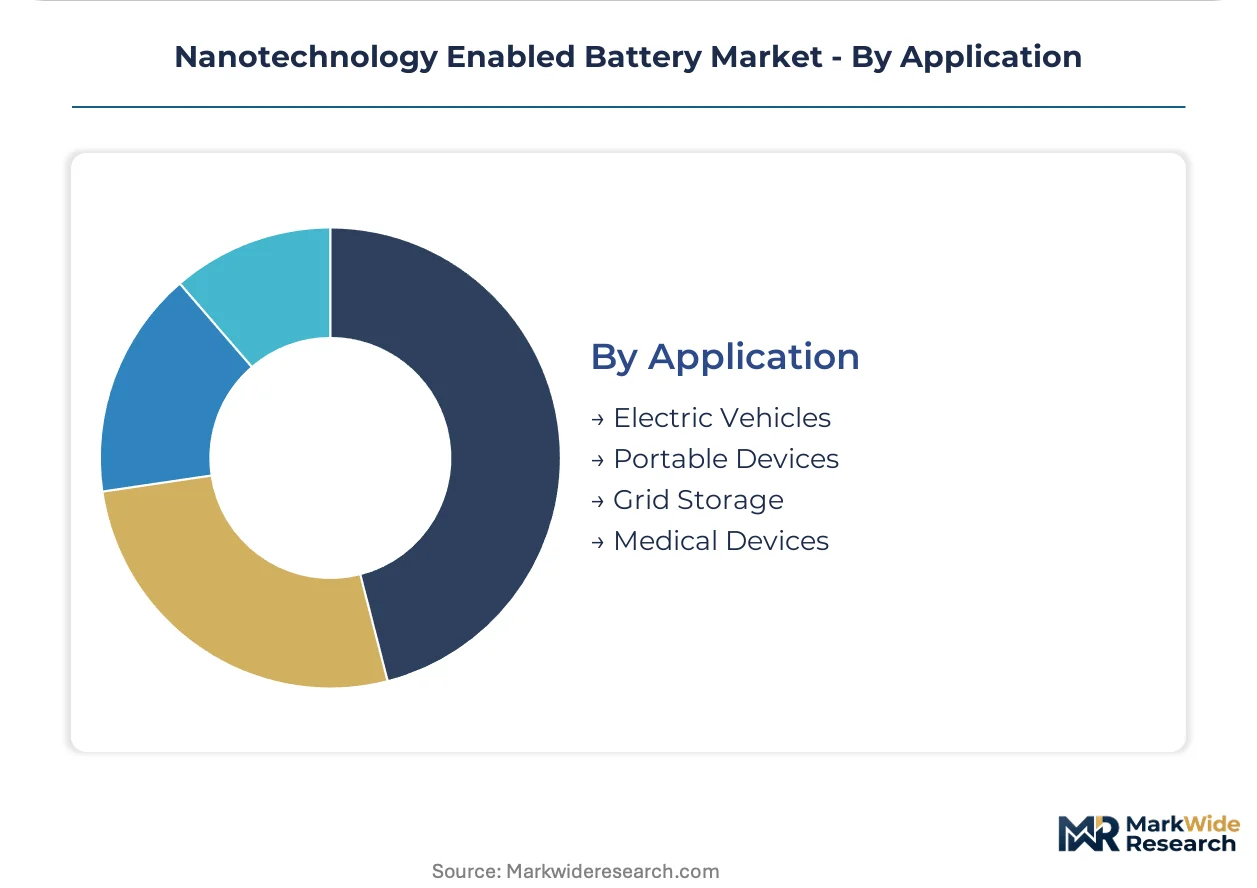
- Electric Vehicles:Hyundai Motor Group and Kia Corporation in South Korea consolidate procurement around performance-tier contracts specifying energy density floors and cycle life guarantees, displacing commodity spot purchasing.
- Portable Devices:Smartphone OEMs require sub-5mm cell thickness, sustaining lithium polymer demand despite energy density limitations.
- Grid Storage:Utility-scale deployments in China and the US prioritize capital cost reduction over gravimetric energy density, favoring established lithium-ion formats.
- Medical Devices:Continuous glucose monitors and neurostimulators require sub-gram power sources where silicon-anode energy density justifies 40-60% unit premiums.
Electric vehicles dominate procurement volume; medical devices represent the most concentrated margin pool.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electric vehicle procurement concentrates in South Korea and China, where integrated gigafactories and state-backed industrial policy reshape supplier geography. Battery cell demand anchors regional investment flows.
China
Domestic EV manufacturers scale silicon-anode procurement for premium vehicle lines. SAMR and GB standards mandate cell-level traceability from precursor to pack, forcing quality system restructuring. The Yangtze River Delta hosts concentrated cathode precursor capacity serving CATL and BYD gigafactories.
South Korea
Hyundai Motor Group and Kia Corporation anchor demand through equity-linked supplier partnerships specifying energy density floors. METI-aligned industrial policy directs subsidy allocation toward domestic cathode-anode integration. The Ulsan-Gumi corridor houses Samsung SDI and LG Energy Solution integrated production complexes.
United States
eVTOL developers including Joby Aviation and Archer Aviation qualify silicon-nanowire cells for weight-critical propulsion systems. NHTSA enforces 30-minute thermal runaway propagation resistance, extending validation cycles. California hosts concentrated aviation battery R&D and pilot manufacturing.
Germany
Automotive OEMs impose divergent qualification timelines from aviation and medical device standards. The EU F-Gas Regulation accelerates solid-state ceramic electrolyte pilot lines as manufacturers retool fluorinated electrolyte processes. Bavaria anchors cell testing and certification infrastructure.
Japan
Industrial policy under METI prioritizes solid-state electrolyte development for next-generation mobility. Domestic manufacturers face compressed commercialization timelines from manufacturing complexity. The Kansai region maintains concentrated materials science research institutions feeding pilot production.
Nanotechnology Enabled Battery Market Competitive Landscape
Capacity expansion dominates the current landscape as manufacturers scale pilot lines toward commercial thresholds. The vendor base separates into three tiers: integrated conglomerates with captive precursor supply, pure-play solid-state specialists, and silicon-anode technology licensors. Strategic archetypes include backward-integrated material producers, aviation-certification-focused developers, and medical implant miniaturization specialists. Competitive moves concentrate on M&A for electrolyte intellectual property and strategic partnerships for aviation qualification pathways.
Among South Korea-based integrated producers, Samsung SDI and LG Energy Solution exemplify the conglomerate tier with captive cathode-anode production. Amprius Technologies occupies a specialist position representing silicon-nanowire anode developers targeting aviation and defense applications. These three anchors illustrate divergent strategic postures: backward integration versus technology licensing versus vertical application focus.
| Leading Market Players |
|---|
| Samsung SDI |
| LG Energy Solution |
| Panasonic Corporation |
| Amprius Technologies |
| QuantumScape |
| Sila Nanotechnologies |
| Enevate Corporation |
| Nanotech Energy |
| Nexeon |
| Others |
Pricing and Supply Chain Analysis
Multiphysics simulation talent concentration in South Korea's Ulsan-Gumi corridor feeds labor-cost differentials that widen pricing-tier spreads between solid-state aviation cells and commodity lithium-ion packs.
Pricing Analysis
Extended warranty and cycle-life guarantee bundling separates premium aviation-grade silicon-nanowire cells from unbundled automotive commodity contracts. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation under US NHTSA and China NMPA protocols. Cost compression in standard-tier lithium-ion is intensifying because dry electrode coating yields remain below commercial thresholds. Automotive OEMs anchored by Hyundai Motor Group exhibit highest price sensitivity, while medical implant manufacturers accept 40-60% unit premiums for sub-gram formats.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Hyundai Motor Group and Kia Corporation, bypassing distributor markups for equity-linked supply partnerships. Geographic supply concentration centers on South Korea, China, and Japan, with the Ulsan-Gumi corridor hosting Samsung SDI and LG Energy Solution integrated complexes. Raw material dependencies draw from metallurgical-grade silicon feedstock, high-nickel cathode precursors, and ceramic electrolyte powders. Single-source vulnerability in South Korean cathode precursor output creates structural risk for European cell builders. Distribution runs through long-term offtake agreements specifying energy density floors rather than spot market procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where cathode-anode precursor control determines margin capture against silicon feedstock volatility.
For Market Incumbents: Deploy captive precursor plant expansion to secure high-nickel cathode supply against Korean supplier concentration risk. Solid-state electrolyte manufacturing complexity threatens margin erosion for liquid-electrolyte incumbents. Accelerate in-house nano-coating capability for silicon-anode cycle life extension. Lock aviation certification pathways through dedicated Shanghai NMPA compliance teams.
For New Entrants and Emerging Players: The 40-60% premium gap between medical implant silicon-anode cells and automotive graphite-anode commodities exposes white-space opportunity. India's PLI scheme for advanced chemistry cells offers penetrable entry for two-wheeler and three-wheeler electrification. Target neurostimulation and continuous glucose monitoring device OEMs with sub-gram format specialization. Pursue technology licensing rather than capital-intensive gigafactory buildout.
For Investors and Strategic Acquirers: Re-rating potential sits with solid-state electrolyte IP holders given EU F-Gas Regulation phase-down accelerating ceramic electrolyte pilot line investment. Long-term viability favors backward-integrated specialists with captive precursor supply and aviation certification progress. Monitor eVTOL airframe builder supply agreement announcements as inflection indicator for silicon-nanowire commercialization timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Cathode Precursor Backward Integration | Samsung SDI and LG Energy Solution reduce external dependency through captive Ulsan-Gumi plants. |
| Solid-State Electrolyte Pilot Scale-Up | QuantumScape and Amprius Technologies advance aviation certification pathways under NHTSA protocols. |
| Silicon-Nanowire Supply Agreement Lock | Joby Aviation and Archer Aviation secure multi-year offtake for 400 Wh/kg cell formats. |
| NMPA Certification Team Establishment | Korean and Japanese exporters restructure quality systems for China's SAMR traceability mandates. |
| Dry Electrode Coating Yield Improvement | Solvent-free manufacturing advances toward commercial thresholds for solid-state cost reduction. |
Research Methodology
Independent corroboration across cell engineering directors, aviation procurement leads, and medical device power system architects underwrites the qualitative findings. Primary interviews with solid-state R&D heads, cathode precursor plant managers, and eVTOL battery qualification officers combined with secondary validation from SEC filings, NHTSA thermal runaway test protocols, and China SAMR GB standard documentation. Bottom-up cell shipment modeling and top-down gigafactory capacity aggregation provided cross-check triangulation.
Comparable historical performance across lithium-ion commercialization cycles anchored the projection horizon to established technology diffusion patterns. The analytical framework segmented by product chemistry, end-use application, manufacturing technology, and regional regulatory cluster throughout the forecast period. CAGRs were derived from installed capacity ramp rates and aviation certification timeline compression. Forecast inputs incorporated silicon feedstock price volatility cycles and EU F-Gas Regulation compliance cost assumptions.
Inputs from NHTSA test protocol disclosures and China NMPA certification databases were available through the study window; gaps in solid-state manufacturing yield data introduce uncertainty bands around commercialization timeline assumptions. Forecasts reflect documented assumptions regarding dry electrode coating technical maturity and aviation qualification pathway acceleration. Practitioners should monitor eVTOL airframe builder supply agreement velocity and EU ceramic electrolyte pilot line announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Li-Ion Portable Battery Market
Lithium-ion Battery
Graphite Anode for LIB Market
Lithium-ion Battery
Lithium Sulfur Dioxide Battery Market
Lithium-ion Battery
Lithium-Ion Battery Packs Market
Lithium-ion Battery
Europe Solid State Battery Market
Lithium-ion Battery
United Kingdom Lithium-Ion Battery for Electric Vehicle Market
Lithium-ion Battery
Global Next Generation Batteries Market
Lithium-ion Battery
Next Generation Advanced Battery Market
Lithium-ion Battery
Lithium-Ion Battery Rechargeable Hearing Aids Market
Lithium-ion Battery
North America Lithium-Ion Battery for Electric Vehicle Market
Lithium-ion Battery
Nanobolt Lithium Tungsten Batteries Market
Lithium-ion Battery
Bangladesh Lithium-Ion Battery Market
Lithium-ion Battery
Lithium Ion Secondary Battery Sales Market
Lithium-ion Battery
Lithium Battery in Myanmar Market
Lithium-ion Battery
Germany Electric Vehicle Battery Materials Market
Lithium-ion Battery
Lithium Battery for Passenger Car Market