
 Lithium Hydroxide Market | 2026-2036
Lithium Hydroxide Market Size, Share, and Industry Trends Forecast 2026-2036
Lithium Hydroxide Market Intelligence
The displacement of lithium carbonate in high-nickel cathode formulations for electric vehicle batteries is hardening the requirement for battery-grade lithium hydroxide. Albemarle Corporation leverages its global production footprint to supply key automotive original equipment manufacturers. Jiangxi Ganfeng Lithium specializes in advanced processing technologies to meet stringent purity demands. Meanwhile, Sociedad Química y Minera de Chile (SQM) competes by converting its vast brine resources into high-purity hydroxide products for the battery supply chain.
Lithium hydroxide is an inorganic compound, LiOH, produced either through the conversion of lithium carbonate or directly from spodumene ore via a roasting process. Its primary industrial purpose is to serve as a precursor for cathode active materials in lithium-ion batteries, where purity levels are critical for performance and safety. Battery Grade material commands a significant price premium and constitutes the largest share of the market, driven by the automotive end-user segment. Industrial Grade and Technical Grade products find application in lubricating greases and matrix materials, representing more mature and stable demand.
Producers must navigate a complex web of regulations, including China's GB standards for battery materials, Europe's REACH chemical registration requirements, and US EPA rules governing mineral processing. These standards directly influence product specifications, market access, and the environmental credentials required by downstream customers. Securing long-term, ethically sourced, and specification-compliant supply remains the central strategic challenge for all participants in the value chain.
Market Dynamics
The fundamental dynamic shaping the lithium hydroxide market is the technological pivot within the electric vehicle battery sector. A decisive shift toward high-nickel cathode chemistries, designed for longer range and faster charging, makes high-purity lithium hydroxide an essential, non-substitutable input.
Growth Catalysts
- Policy Mandates for Localization:The US Inflation Reduction Act (IRA) and the EU Green Deal incentivize the development of regional battery supply chains, directly stimulating investment in new lithium hydroxide conversion capacity within North America and Europe to serve local gigafactories.
- Advanced Cathode Technology:The commercialization of high-nickel cathode formulations like NCM 811 (nickel-manganese-cobalt) and NCA (nickel-cobalt-aluminum) depends on lithium hydroxide's unique properties to ensure thermal stability and long-term performance in EV batteries.
- Gigafactory Expansion:A global build-out of battery manufacturing plants, particularly concentrated in China, Europe, and North America, creates large, consolidated points of demand for battery-grade materials, pulling significant volumes of lithium hydroxide into the automotive supply chain.
Market Restraints
- Feedstock Price Volatility:Producer margins are exposed to extreme price fluctuations for key inputs, particularly spodumene concentrate from hard-rock mining operations. This volatility complicates long-term planning and investment decisions for new conversion facilities.
- Geopolitical Supply Concentration:A substantial majority of the world's lithium chemical conversion and refining capacity is located in China, creating significant supply chain vulnerability and geopolitical risk for automakers and battery manufacturers in other regions.
- Complex Production Processes:Converting spodumene ore or lithium brine into high-purity battery-grade hydroxide is technically challenging and energy-intensive, which limits the speed at which new supply can be brought online to meet rapid demand escalations.
Strategic Opportunities
- Next-Generation Battery Chemistries:The development of solid-state batteries presents a long-term opportunity, as many designs utilize lithium metal anodes, which are often produced from lithium hydroxide as a precursor, potentially opening a new high-value market segment.
- Direct Lithium Extraction (DLE):Innovations in DLE technologies offer a pathway to produce lithium hydroxide from brines with a smaller environmental footprint and potentially lower cost compared to conventional evaporation ponds, creating an opening for new, more sustainable projects.
- Emerging Market Penetration:As countries like India and nations in Southeast Asia begin to build out their own electric vehicle and battery manufacturing ecosystems, there is a clear opportunity for early-mover hydroxide suppliers to establish foundational supply agreements.
Industry Challenges
- Multi-Jurisdictional Compliance:Producers face the operational burden of meeting disparate and stringent product specifications simultaneously, including China's GB standards for battery materials and Europe's comprehensive REACH chemical registration and documentation requirements.
- Intensive Capital Requirements:Building new, large-scale lithium hydroxide conversion plants involves significant capital expenditure and multi-year construction timelines, creating a high barrier to entry and delaying supply responses to market signals.
- ESG and Environmental Scrutiny:The high water and energy consumption associated with lithium hydroxide production is facing increased examination from investors, regulators, and downstream customers, demanding greater transparency and improved sustainability metrics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lithium Hydroxide Market |
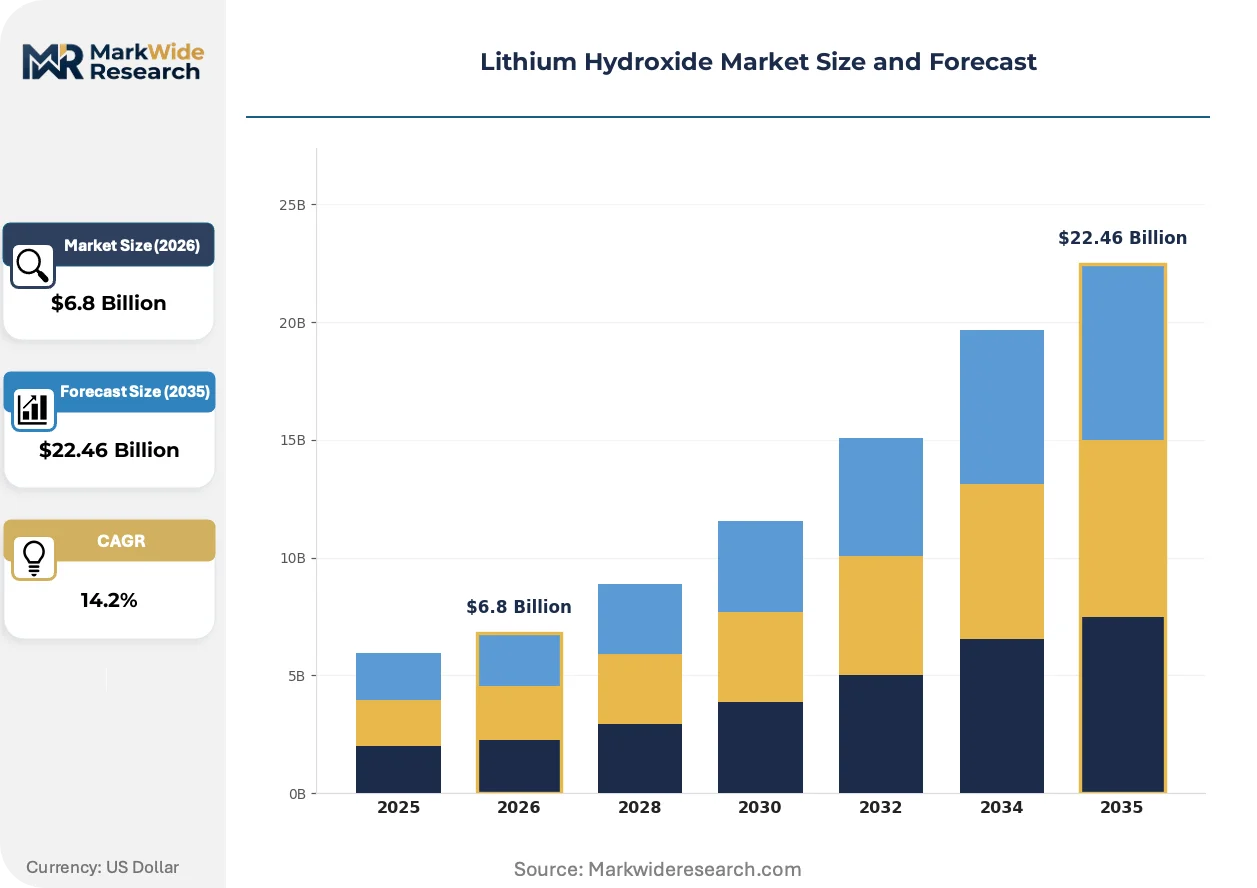
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $22.46 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Battery Grade, Industrial Grade, Technical Grade, Pharmaceutical Grade End User: Automotive, Electronics, Pharmaceuticals, Energy Storage Application: Battery Production, Lubricating Grease, Matrix Materials, Antigravity Applications Packaging Type: Bags, Drums, Bulk Containers, Cylinders |
| Companies Covered | Tianqi Lithium, Yahua Industrial Group, Albemarle Corporation, General Lithium, Sichuan State Lithium Material Ltd., Sociedad Química y Minera de Chile (SQM), FMC Corporation, HAOXIN LIYAN, Jiangxi Ganfeng Lithium, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lithium Hydroxide Market Strategic Shifts & Innovations
The market's trajectory is defined by a push for higher battery energy density and the strategic imperative to build resilient, geographically diversified supply chains. Technology advancements in processing are converging with policy-driven efforts to de-risk sourcing for the automotive industry.
High-purity, low-impurity lithium hydroxide is the critical enabler for advanced cathode materials that improve battery performance. Automotive OEMs and cell manufacturers are rapidly adopting it for high-nickel chemistries to extend electric vehicle range and enhance safety. This preference for hydroxide over carbonate in performance-tier batteries is rewriting the required purity specifications and investment priorities for lithium refiners globally.
European Union regulations, including the Critical Raw Materials Act and the EU Battery Regulation, are establishing strict criteria for recycling content, carbon footprint, and ethical sourcing. These rules compel battery makers and automotive firms to create transparent supply chains with verifiable provenance for materials like lithium hydroxide. The European gigafactory corridor is most affected, now forced to prioritize suppliers compliant with ESG and circularity mandates under frameworks like the CSRD.
Automakers are increasingly moving away from volatile spot market transactions toward direct, long-term offtake agreements with lithium hydroxide producers. This procurement model shift provides producers with the revenue security needed to underwrite and finance capital-intensive new capacity projects. This direct-sourcing strategy is most visible in North America and Europe, where new EV battery plants are actively working to secure multi-year supply lines.
Lithium Hydroxide Market Segmentation
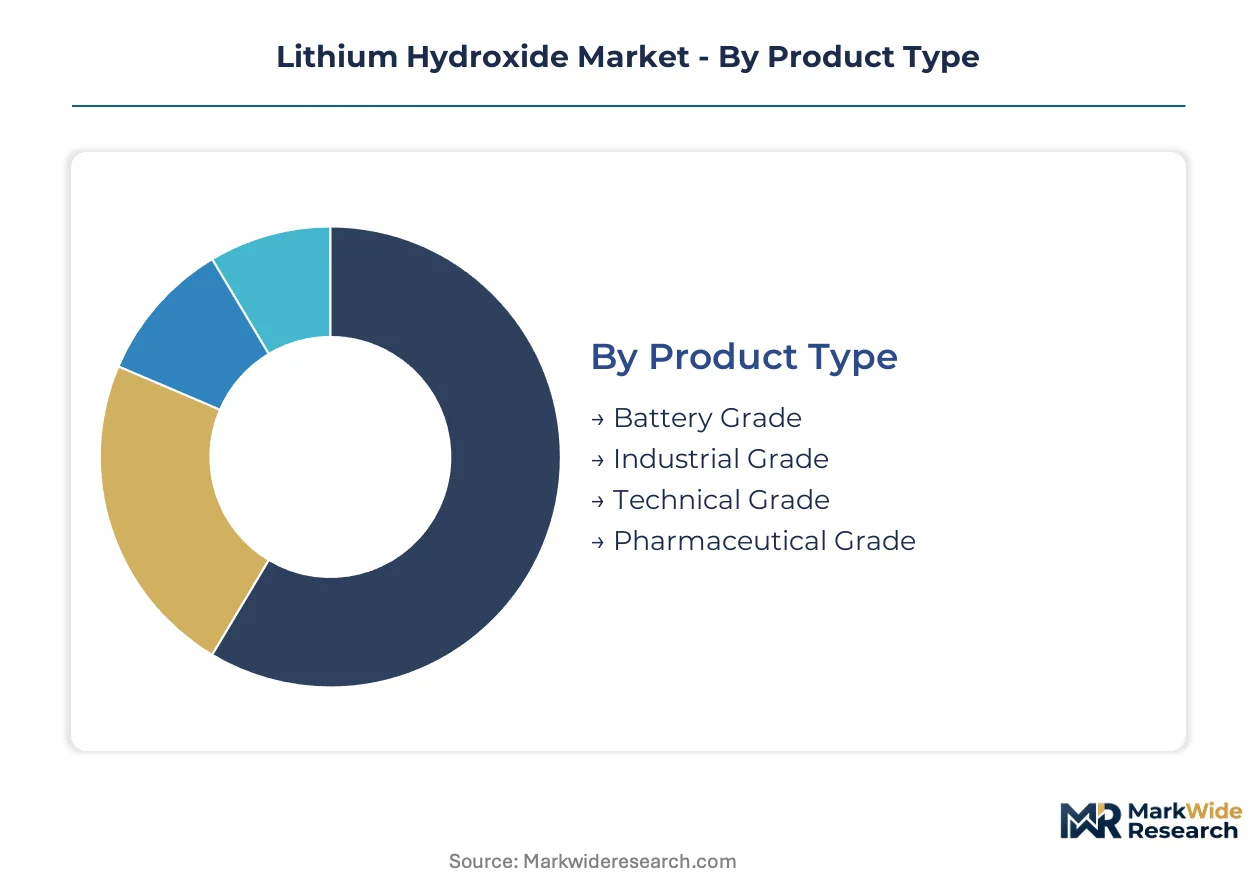
The lithium hydroxide market exhibits distinct characteristics across its various segments, reflecting the diverse purity requirements and end-use applications for this critical chemical. Understanding these segmentations is essential for manufacturers to tailor production processes and for consumers to identify appropriate material specifications. Each category highlights specific demand drivers.
Product Type:
Buyers in the lithium hydroxide market are differentiated by the purity levels and chemical specifications required for their specific end products.
- Battery Grade:This product type features extremely high purity, typically 99.5% LiOH, with minimal impurities like sodium, calcium, and iron. Demand concentrates heavily within China's battery manufacturing hubs, driven by the shift towards high-nickel cathode chemistries for electric vehicles.
- Industrial Grade:This grade serves applications where high purity is less critical, often containing lower concentrations of lithium hydroxide. Demand for industrial-grade material is stable in established sectors like lubricating greases and certain chemical processes.
- Technical Grade:This grade offers a balance between purity and cost, suitable for various chemical reactions and industrial applications that do not require ultra-high specifications.
- Pharmaceutical Grade:This highly specialized grade meets stringent regulatory standards for use in medical and pharmaceutical formulations, requiring meticulous control over trace elements.
Volume sits with Industrial Grade; growth tilts toward Battery Grade.
End User:
End users are primarily distinguished by the specific functional requirements their products place on lithium hydroxide's properties.
- Automotive:The automotive sector utilizes lithium hydroxide primarily for electric vehicle batteries, demanding high-purity material for advanced cathode chemistries like NCM 811. This segment's demand is expanding rapidly in North American and European gigafactory corridors due to policy mandates.
- Energy Storage:Stationary energy storage systems, including grid-scale batteries, rely on lithium hydroxide for their long-duration and high-power battery chemistries. The need for reliable grid infrastructure and renewable energy integration is driving significant investment in this segment globally.
- Electronics:Lithium hydroxide finds application in smaller lithium-ion batteries for consumer electronics, where its performance contributes to device longevity and power output.
- Pharmaceuticals:The pharmaceutical industry uses lithium hydroxide in specific chemical synthesis processes and sometimes as a component in certain medical compounds.
The Automotive sector accounts for the largest share, with Energy Storage expanding most quickly.
Application:
Applications for lithium hydroxide are characterized by their varying volume demands and technological maturity within diverse industrial processes.
- Battery Production:This application involves the direct use of lithium hydroxide as a precursor for cathode active materials in lithium-ion batteries, particularly for high-nickel formulations. The rapid expansion of electric vehicle manufacturing globally is creating unprecedented demand for this specific application.
- Lubricating Grease:Lithium hydroxide is a key component in manufacturing lithium greases, which are widely used for their excellent high-temperature performance and water resistance. This traditional application provides a stable, long-term demand base for industrial-grade material across various industries.
- Matrix Materials:Lithium hydroxide can be incorporated into certain matrix materials, contributing to their structural integrity or chemical properties in specialized composites.
- Antigravity Applications:This niche application area may involve experimental or specialized uses of lithium compounds where their unique chemical properties are leveraged.
Battery Production dominates the application landscape, while Lubricating Grease provides a source of stable demand.
Packaging Type:
Packaging types are determined by logistical considerations, shipment volumes, and the specific handling requirements of different end-user facilities.
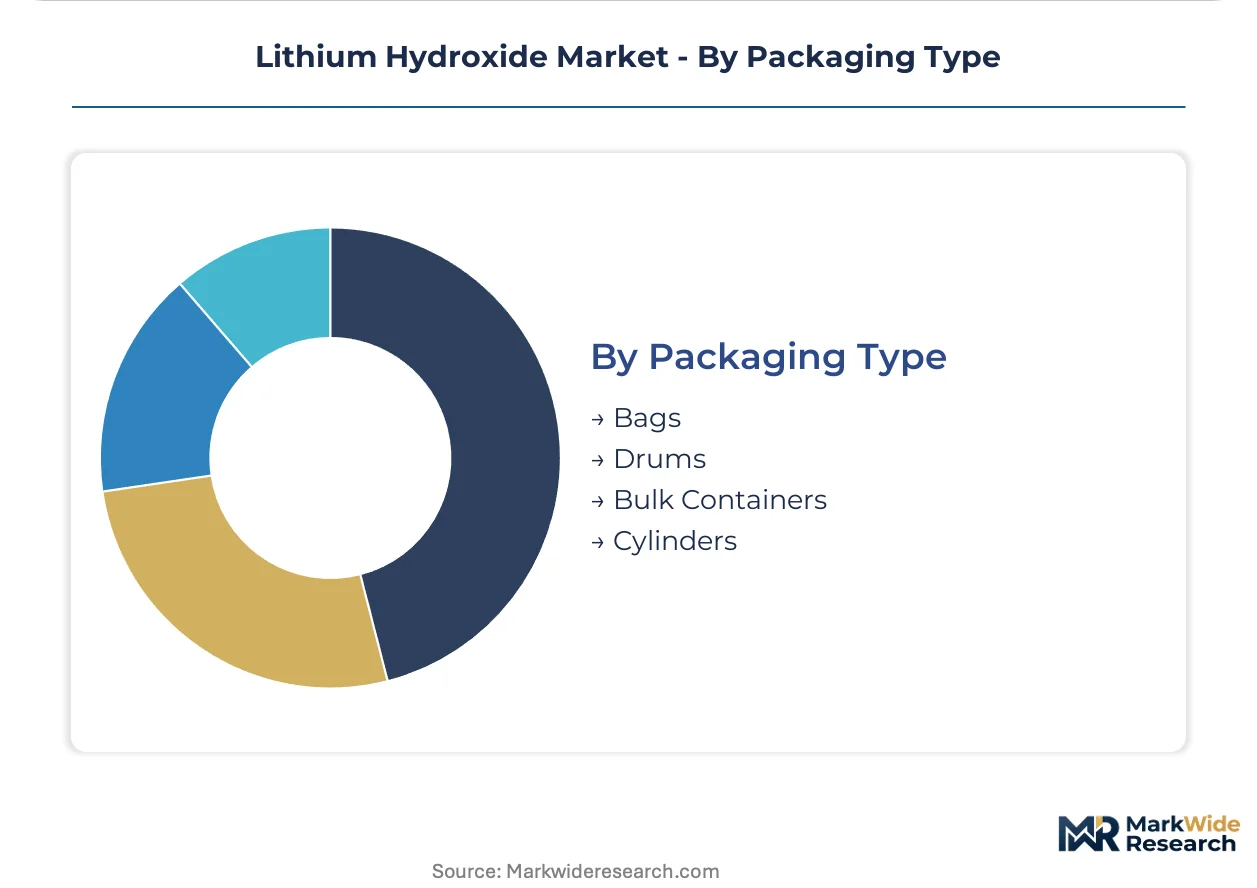
- Bags:Lithium hydroxide is commonly packaged in multi-ply paper or plastic bags, typically holding 20-25 kg, for ease of handling and transport in smaller quantities. This packaging is prevalent for customers requiring moderate volumes or for distribution to diverse, smaller manufacturing sites.
- Bulk Containers:Large volumes of lithium hydroxide are transported in bulk containers such as flexible intermediate bulk containers (FIBCs) or large bins, accommodating several tons of material. This method is favored by large-scale battery manufacturers and chemical plants to optimize freight costs and streamline material input.
- Drums:Steel or plastic drums are used for shipping medium-sized quantities of lithium hydroxide, offering robust protection and ease of stacking for both domestic and international transport.
- Cylinders:While less common for solid lithium hydroxide, cylinders might be used for specific forms or very small, high-purity batches, or for related lithium compounds in gaseous form if applicable.
Bags and Drums are predominantly utilized for smaller shipments, with Bulk Containers increasingly adopted for large-scale industrial customers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for lithium hydroxide concentrates heavily in regions supporting electric vehicle battery manufacturing. China's established battery hubs and emerging gigafactory corridors in North America and Europe drive this consumption. High-purity material is essential for advanced cathode chemistries.
China
China's robust electric vehicle battery production creates substantial demand for battery-grade lithium hydroxide. The nation's GB standards for battery materials dictate stringent purity requirements for cathode precursors. Battery manufacturing hubs in Jiangsu and Guangdong are actively expanding, pulling significant volumes of refined lithium hydroxide.
United States
The United States prioritizes regional supply chain development for electric vehicle components, including lithium hydroxide. The US Inflation Reduction Act (IRA) incentivizes domestic processing and battery manufacturing. New gigafactories in states like Georgia and Michigan are securing long-term supply agreements for local production.
Germany
Germany's automotive industry drives significant lithium hydroxide demand as it transitions toward electric vehicle production. European Union regulations, such as the EU Green Deal and REACH, influence material specifications and sourcing. Battery cell production facilities in Brandenburg and Saxony are focal points for this growing demand.
South Korea
South Korea's leading battery manufacturers require high-purity lithium hydroxide for their advanced cathode chemistries. National industrial policy frameworks support the development of a resilient battery materials supply chain. Battery production facilities in Cheongju and Ulsan are key consumers of refined lithium chemicals.
Australia
Australia, a major source of lithium raw materials, is exploring increased domestic processing capacity for lithium hydroxide. The country's environmental regulations, including the Environmental Protection and Biodiversity Conservation Act, govern mining and processing operations. Lithium mining operations in Western Australia are foundational to global supply chains.
Lithium Hydroxide Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, influencing the market's competitive structure. The lithium hydroxide market exhibits a consolidated structure at the top tier, with several large-scale producers dominating supply. Strategic archetypes include integrated brine-to-hydroxide converters, hard-rock processing specialists, and chemical refiners. Companies primarily pursue capacity expansion and strategic partnerships to secure raw material access and expand geographic reach.
Specialists in large-scale lithium chemical production include Albemarle Corporation, which operates a global production footprint. Jiangxi Ganfeng Lithium, a Chinese-based firm, exemplifies advanced processing technologies for high-purity battery materials. Sociedad Química y Minera de Chile (SQM), a Chilean company, further anchors the market through its extensive brine resources and conversion capabilities. These entities represent diverse approaches to securing raw material inputs and refining them into battery-grade lithium hydroxide for the global supply chain.
| Leading Market Players |
|---|
| Tianqi Lithium |
| Yahua Industrial Group |
| Albemarle Corporation |
| General Lithium |
| Sichuan State Lithium Material Ltd. |
| Sociedad Química y Minera de Chile (SQM) |
| FMC Corporation |
| HAOXIN LIYAN |
| Jiangxi Ganfeng Lithium |
| Others |
Cost & Logistics Intelligence
Automotive OEMs and battery manufacturers increasingly demand stable, long-term lithium hydroxide supply agreements, which influences a shift from volatile spot pricing to contract-based models. This procurement strategy aims to de-risk material sourcing and secure high-purity battery-grade material for gigafactory operations.
Pricing Analysis
Volume for industrial-grade material trades at lower margins, while battery-grade lithium hydroxide commands a significant price premium. Contract-based long-term offtake agreements dominate for battery-grade material, ensuring supply security for automotive OEMs. Price differentiation stems from purity levels, with GB standards and REACH compliance demanding higher specifications, and geographic delivery costs impacting final prices. Pricing softness for industrial grades reflects stable demand and greater competition. Industrial end-users are more price-sensitive, whereas EV battery manufacturers prioritize specification and reliability over marginal cost savings.
Supply Chain Analysis
Lithium hydroxide supply relies heavily on raw material extraction in Australia and Chile, and chemical conversion capacity concentrated in China. Spodumene concentrate from hard-rock mining and lithium brine are critical inputs for production. Geopolitical supply concentration in China presents a significant supply chain vulnerability for North American and European battery manufacturers. Distribution often runs through direct long-term offtake agreements with large-scale battery producers, supplementing traditional chemical distributors for industrial applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The lithium hydroxide market is witnessing a vertical-integration race, as major players pursue upstream raw material control to secure high-purity supply for the burgeoning electric vehicle sector.
For Market Incumbents: Acquire upstream lithium mining assets or explore direct lithium extraction (DLE) technologies to bolster raw material security. Invest in advanced processing R&D to meet evolving high-nickel cathode purity specifications, countering feedstock price volatility. Expand conversion capacity within North America and Europe to mitigate geopolitical supply risks and leverage policy incentives like the US Inflation Reduction Act. Strengthen partnerships with key automotive OEMs to lock in long-term demand.
For New Entrants and Emerging Players: Begin with developing niche processing capabilities for specific high-purity applications beyond mainstream EV batteries, or target industrial-grade segments with less stringent requirements. Focus on regions like India and Southeast Asia, where EV and battery manufacturing ecosystems are nascent, offering foundational supply opportunities. Differentiate through sustainable production methods, such as DLE from brines, to appeal to environmentally conscious downstream customers and secure early market share.
For Investors and Strategic Acquirers: The window for entry favors patient capital seeking long-term value creation in essential battery materials. Target specialty refiners with proven advanced processing technologies or junior miners with economically viable lithium reserves and strong ESG credentials. A key signal to watch is the acceleration of regional policy mandates, such as the EU Green Deal, which will drive localized investment and demand for compliant supply chains.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Increases global supply of battery-grade lithium hydroxide, supporting electric vehicle production targets. |
| Backward Integration | Secures raw material inputs like spodumene, reducing exposure to feedstock price volatility. |
| Green Manufacturing Transition | Addresses environmental scrutiny and meets stringent sustainability requirements from European regulators. |
| Long-term Supply Agreement | Provides revenue security for producers and stable material access for automotive OEMs. |
| Joint Venture | Combines technological expertise or resource access to accelerate new project development in North America. |
Research Approach
Document review covered SEC 10-K filings, trade association reports, and national energy agency reports, complemented by interviews with battery material procurement leads, chemical engineers, automotive OEM supply chain managers, and regulatory compliance officers. This approach combined primary insights with secondary data validation, employing both bottom-up and top-down triangulation to ensure comprehensive market understanding.
The forecast framework utilized historical data cross-referenced with expert panel input across the analysis window. Segmentation dimensions modeled included product type (battery grade, industrial grade), end-user (automotive, energy storage), application (battery production, lubricating grease), and regional adoption patterns. CAGRs were calculated from robust volume and value projections, with key forecast inputs derived from electric vehicle production forecasts and evolving battery chemistry trends.
Underlying measurement precision varies by segment; battery-grade material and automotive end-users carry tighter precision than others due to data availability. Forecasts reflect assumptions regarding geopolitical stability and technological advancements. A small set of named triggers warrants ongoing watch, including raw material supply disruptions and shifts in global EV policy.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
High Temperature Lithium Battery Market
Lithium-ion Battery
Global Lithium Mining Market
Lithium-ion Battery
Automotive 48V Lithium Battery Market
Lithium-ion Battery
Nanobolt Lithium Tungsten Batteries Market
Lithium-ion Battery
Manganese Dioxide Lithium Battery Market
Lithium-ion Battery
Solid State Battery Market
Lithium-ion Battery
Marine Lithium-Ion Battery Market
Lithium-ion Battery
Global Rechargeable Poly Lithium-Ion Batteries Market
Lithium-ion Battery
Portable Lithium Battery Energy Storage Products Market
Lithium-ion Battery
Lithium Battery Pack Market
Lithium-ion Battery
Lithium Ion Secondary Battery Sales Market
Lithium-ion Battery
Lithium-Ion Battery Wet-Process Separator Market
Lithium-ion Battery
Italy Electric Vehicles Battery Anode Market
Lithium-ion Battery
Lithium-Ion (Li-Ion) Batteries Market
Lithium-ion Battery
France Electric Vehicle Lithium-Ion Battery Separator Market
Lithium-ion Battery
Asia-Pacific Solid State Battery Market